
 Water Test Kits Market | 2026-2036
Water Test Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Water Test Kits Market Analysis
The gap between laboratory-grade precision and consumer-grade convenience is repositioning how manufacturers allocate engineering resources. Hach dominates the municipal and industrial compliance tier with instrumentation-heavy portfolios. Hanna Instruments leverages its handheld meter ecosystem to anchor the mid-market segment for field technicians and smaller utilities.
Water test kits are portable analytical systems that detect chemical, biological, or physical contaminants through colorimetric, electrochemical, or spectrophotometric reactions, typically achieving detection limits from parts per million to parts per billion depending on the target analyte and method employed. Their primary purpose is to enable rapid, on-site water quality assessment without requiring full laboratory infrastructure. The technology dimension shows colorimetric strips and dip-tests commanding volume share in household and pool applications, while electrochemical and spectrophotometry methods capture margin pools in industrial compliance and environmental monitoring where regulatory thresholds demand greater accuracy. Drinking water tests and wastewater tests represent the fastest-expanding product type categories as infrastructure replacement cycles and discharge permits tighten simultaneously.
The EPA enforces Safe Drinking Water Act amendments and Lead and Copper Rule provisions that mandate specific testing protocols, directly determining which kit formats qualify for official compliance reporting. ISO 17025 accreditation requirements and WHO drinking water quality guidelines shape product development priorities for manufacturers seeking multi-jurisdictional market access. Stakeholders must track how fragmented municipal procurement standards and emerging contaminant monitoring lists reshape validation requirements for new test chemistries.
Market Dynamics
The EPA's Lead and Copper Rule revisions are forcing municipal utilities to triple compliance testing frequencies, compressing kit replacement cycles and redirecting procurement budgets toward higher-sensitivity electrochemical formats.
Growth Catalysts
- Japan's infrastructure renewal mandates:METI-directed replacement of aging distribution pipes in Tokyo and Osaka metropolitan zones requires continuous chlorine residual and lead monitoring, expanding kit deployment to contractor networks.
- ISO 17025 accreditation expansion:Multi-jurisdictional manufacturers pursuing laboratory-equivalent field testing standards unlock municipal tender eligibility previously restricted to fixed-site laboratories.
- Per- and polyfluoroalkyl substances detection protocols:Emerging contaminant monitoring lists in Germany and several US states are creating demand for specialized immunoassay and LC-MS confirmatory kits.
Market Restraints
- Reagent supply concentration:Specialty enzyme and antibody production for biological contaminant kits concentrates among three European contract manufacturers, exposing buyers to allocation risk during demand surges.
- Cross-reactivity limitations:Colorimetric strip chemistries struggle to distinguish between chemically similar compounds like nitrite and nitrate in high-iron groundwater matrices, limiting deployment in Midwestern US agricultural zones.
- REACH registration costs:Novel test chemistries face €50,000-150,000 substance dossier preparation expenses, delaying European commercialization for mid-tier kit developers.
Strategic Opportunities
- Rural Indian panchayat water schemes:Jal Jeevan Mission deployment of community-level testing stations creates volume demand for Hindi-language instruction kits and SMS-based result reporting systems.
- Smartphone spectrometer integration:Convergence of CMOS imaging sensors with cloud-based calibration algorithms enables laboratory-grade quantification from $20-40 consumer hardware attachments.
- California agricultural discharge permits:Central Valley dairy and nut operations face new nitrate monitoring obligations, opening field technician service contracts for rental-based testing programs.
Industry Challenges
- Electrochemical sensor calibration drift:Field technicians in humid subtropical climates report accelerated reference electrode degradation, requiring unscheduled maintenance visits that erode service contract margins.
- Legacy LIMS integration:Municipal utilities operating 1990s-era laboratory information management systems demand custom data export formats, extending deployment timelines by 4-8 weeks per installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Test Kits Market |
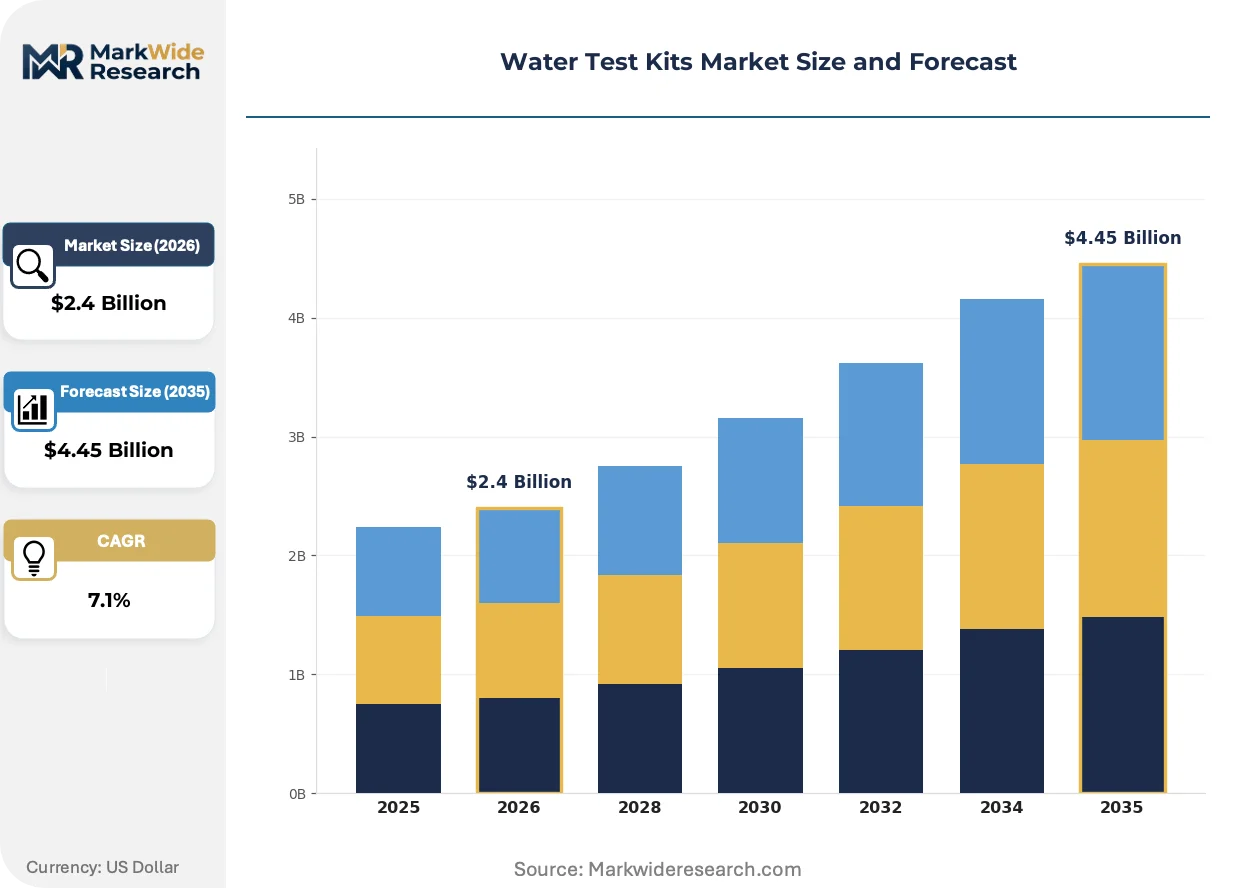
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drinking Water Tests, Pool Tests, Wastewater Tests, Industrial Water Tests Application: Municipal Testing, Home Testing, Industrial Compliance, Environmental Monitoring Technology: Colorimetric, Electrochemical, Ion Chromatography, Spectrophotometry End User: Households, Laboratories, Municipalities, Industries |
| Companies Covered | Palintest, Hanna Instruments, Hach, CHEmetrics, Metrohm AG, LaMotte Company, Camlab Ltd., Aquagenx, Taylor Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Test Kits Market Emerging Trajectories
Portable molecular diagnostics and connected field instrumentation are collapsing the distinction between rapid screening and laboratory confirmation, redistributing analytical workload from centralized facilities to point-of-use deployment.
Microfluidic cartridge systems incorporating pre-stabilized reagents and automated incubation timing are rewriting acceptable accuracy thresholds for non-technical operators. Water districts in Texas and Arizona are deploying these units to wellhead monitoring points previously served by quarterly laboratory pickup. The technology is compressing the viable market for basic colorimetric strips in regulated applications while expanding total addressable volume through operator skill relaxation.
REACH authorization requirements for boron compounds used in pH indicator chemistries are forcing reformulation of established test strip portfolios. German manufacturers are accelerating substitution with natural dye alternatives ahead of 2026 sunset dates. Industrial compliance buyers in the Rhine-Ruhr manufacturing corridor are pre-qualifying reformulated products to avoid supply interruption during transition windows.
Subscription-based kit replenishment programs are displacing traditional spot procurement in North American homeowner segments. Pool service contractors in Florida and Arizona are consolidating chemical testing and kit resupply into monthly flat-rate agreements. The model is most visible in Sun Belt states where year-round pool operation sustains predictable consumption patterns and where distributor networks have invested in route-based logistics infrastructure.
Water Test Kits Market Segmentation
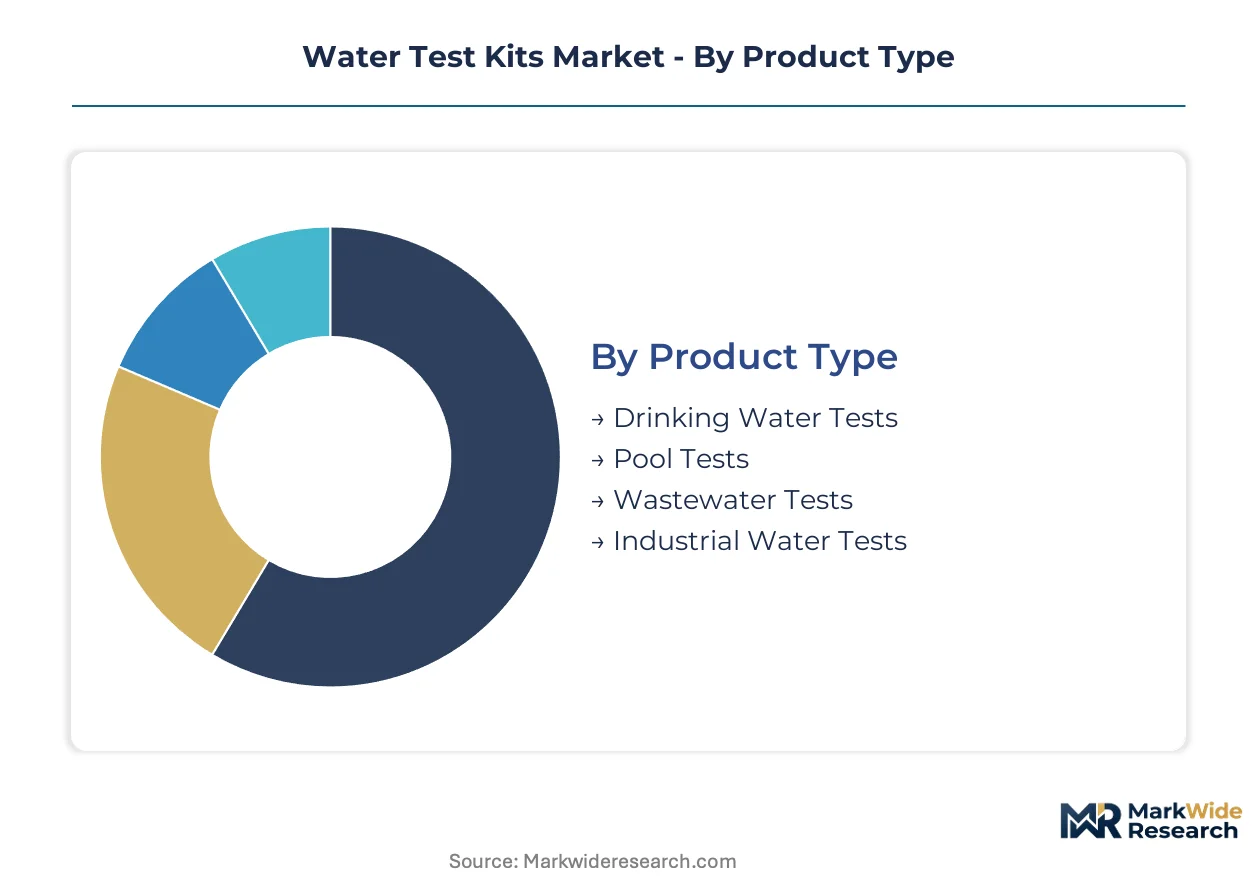
Water test kit manufacturers face divergent certification burdens across segments. EPA compliance protocols for municipal drinking water differ fundamentally from pool maintenance standards or industrial discharge permits. Segment-specific validation requirements dictate R&D allocation and geographic prioritization strategies.
Product Type:
Drinking water and wastewater test kits carry the heaviest regulatory load, requiring EPA, ISO 17025, or WHO equivalency for official reporting. Pool and industrial formats operate under lighter voluntary standards or sector-specific protocols.
- Drinking Water Tests:These kits detect lead, chlorine residual, coliform bacteria, and pH through EPA-approved methods. Municipal utilities in Germany and Japan are expanding procurement of high-sensitivity electrochemical formats to meet tightened Lead and Copper Rule frequencies. Reagent stability and documented detection limits determine tender eligibility.
- Wastewater Tests:Designed for nitrogen, phosphorus, and heavy metals quantification under discharge permit conditions. Industrial facilities in the Rhine-Ruhr corridor pre-qualify products ahead of REACH reformulation deadlines to avoid supply interruption. Regulatory threshold stringency drives margin capture in this segment.
- Pool Tests:Colorimetric strips dominate residential and commercial pool maintenance for chlorine, bromine, and alkalinity monitoring. Florida and Arizona service contractors favor subscription replenishment models integrated with chemical delivery routes.
- Industrial Water Tests:Boiler feedwater and cooling tower chemistry monitoring requires specialized hardness and silica detection. Power plants and semiconductor fabs in East Asian urban clusters demand trace-level accuracy for process control.
Leading the category by volume: Pool Tests. Growing fastest: Wastewater Tests.
Application:
Application segments stratify sharply by customer procurement sophistication and price elasticity. Municipal and industrial buyers negotiate multi-year framework agreements, while home testing operates through retail and e-commerce channels with minimal contract lock-in.
- Municipal Testing:Utilities operate under legally mandated testing schedules with documented chain-of-custody requirements. METI-directed infrastructure renewal in Tokyo and Osaka metropolitan zones is expanding kit deployment to contractor networks beyond traditional utility staff.
- Industrial Compliance:Manufacturing and energy facilities face permit-driven monitoring obligations for effluent discharge and intake water quality. California Central Valley agricultural operations are newly subject to nitrate monitoring under revised discharge permits.
- Home Testing:Residential consumers purchase lead, bacteria, and general chemistry kits through hardware stores and online marketplaces. Subscription-based replenishment is displacing spot procurement in North American Sun Belt states with year-round pool operation.
- Environmental Monitoring:Field researchers and conservation agencies deploy portable kits for surface water and groundwater assessment. Smartphone spectrometer attachments are enabling laboratory-grade quantification from low-cost consumer hardware in remote deployment scenarios.
Capturing the highest margins: Industrial Compliance. Expanding most quickly: Municipal Testing.
Technology:
Technology selection determines both performance ceiling and operator skill requirements. Electrochemical and spectrophotometric methods command premium positioning where regulatory thresholds demand documented accuracy, while colorimetric formats prioritize accessibility and speed.
- Electrochemical:Ion-selective electrodes and amperometric sensors deliver parts-per-billion detection for lead, arsenic, and dissolved oxygen. Humid subtropical climates accelerate reference electrode degradation, eroding service contract margins through unscheduled maintenance.
- Spectrophotometry:Benchtop and portable instruments quantify absorbance at specific wavelengths for multi-parameter analysis. Water districts in Texas and Arizona deploy microfluidic cartridge systems at wellhead monitoring points previously served by quarterly laboratory pickup.
- Colorimetric:Visual or smartphone-read color comparison strips dominate household and pool applications for pH, chlorine, and hardness. REACH authorization requirements for boron compounds are forcing German manufacturers toward natural dye reformulations.
- Ion Chromatography:Laboratory-grade separation and detection of anions and cations at trace concentrations. Environmental monitoring agencies and central laboratories employ these systems for regulatory compliance and research applications.
Commanding volume leadership: Colorimetric. Steepest expansion trajectory: Electrochemical.
End User:
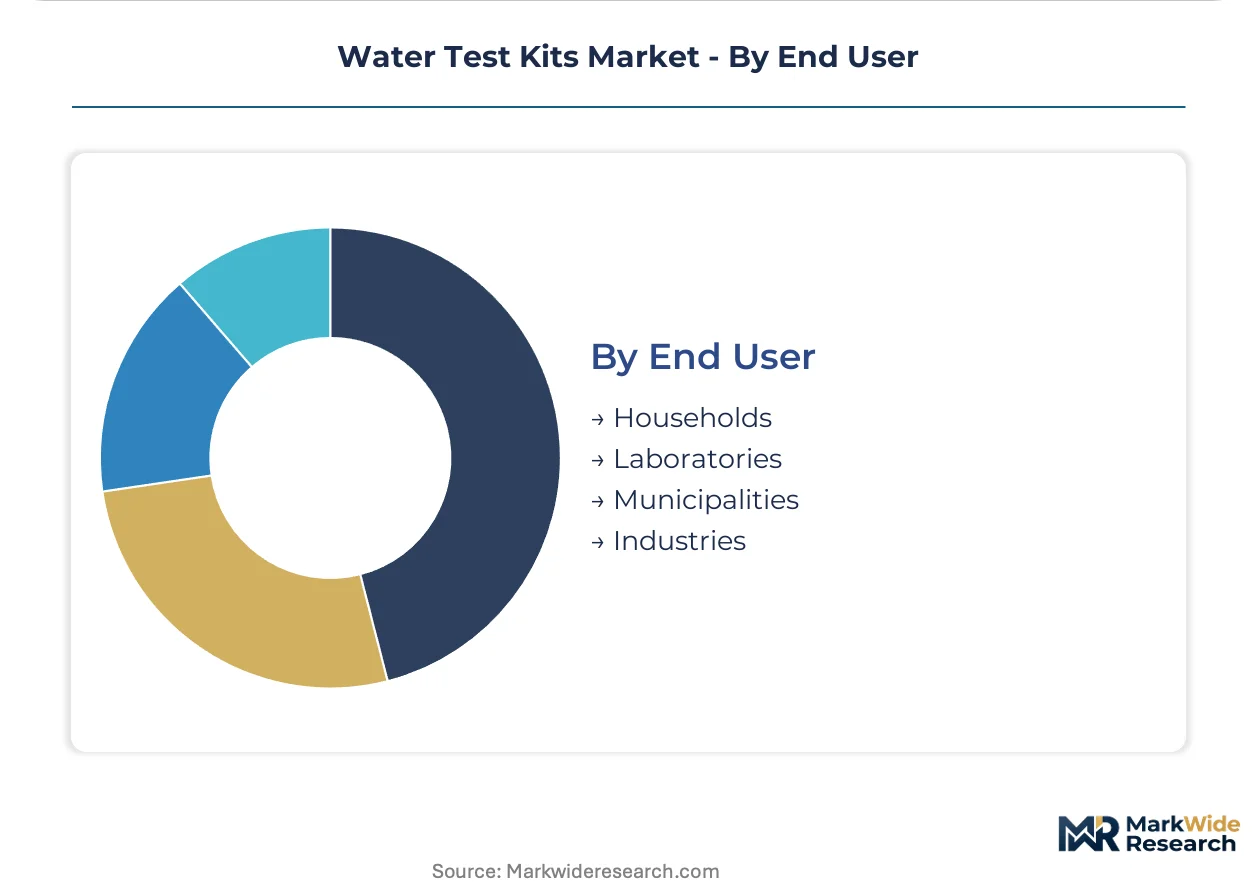
End user categories differ fundamentally in technical capability, purchasing authority, and sensitivity to total cost of ownership versus upfront price. Laboratories and municipalities operate structured procurement processes; households respond to packaging clarity and retail availability.
- Municipalities:Water utilities and treatment plants operate under EPA, WHO, or national equivalent mandates with formal tender processes. Legacy LIMS integration demands consume 4-8 weeks of deployment timeline per installation.
- Industries:Manufacturing, power generation, and food processing facilities require process control and compliance monitoring. Semiconductor fabs and pharmaceutical operations impose the most stringent purity verification protocols.
- Laboratories:Commercial environmental labs and utility central laboratories perform confirmatory analysis and method development. ISO 17025 accreditation expansion unlocks municipal tender eligibility previously restricted to fixed-site facilities.
- Households:Residential consumers test drinking water quality and pool chemistry with minimal technical training. Hindi-language instruction kits and SMS-based result reporting systems are penetrating rural Indian panchayat water schemes.
Generating the largest revenue pool: Municipalities. Gaining share fastest: Households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo and Osaka metropolitan zones anchor kit deployment intensity as METI-directed infrastructure renewal mandates continuous chlorine residual and lead monitoring across contractor networks.
United States
EPA Lead and Copper Rule revisions triple compliance testing frequencies for municipal utilities, compressing kit replacement cycles toward higher-sensitivity electrochemical formats. The Safe Drinking Water Act amendments determine which kit formats qualify for official reporting. Water districts in Texas and Arizona deploy microfluidic cartridge systems at wellhead monitoring points previously served by quarterly laboratory pickup.
Germany
Rhine-Ruhr manufacturing corridor buyers pre-qualify reformulated test strip products ahead of REACH sunset dates for boron compounds. ECHA authorization requirements force natural dye substitution in pH indicator chemistries. Municipalities across the country expand routine water quality screening programs as infrastructure replacement cycles accelerate.
Japan
METI-directed replacement of aging distribution pipes in metropolitan zones requires continuous monitoring, expanding kit deployment beyond traditional utility staff to contractor networks. JIS standards shape product development priorities for domestic manufacturers. Osaka and Tokyo water authorities drive procurement of high-sensitivity formats for tightened compliance frequencies.
India
Jal Jeevan Mission deployment of community-level testing stations creates volume demand for Hindi-language instruction kits and SMS-based result reporting systems. BIS standards influence product specifications for rural panchayat water schemes. Maharashtra and Gujarat industrial clusters generate parallel demand for wastewater discharge monitoring kits.
China
East Asian urban clusters concentrate demand where aging distribution infrastructure requires continuous monitoring. MEE discharge permit tightening drives industrial facility procurement of nitrogen and phosphorus quantification kits. Yangtze River Delta manufacturing zones impose trace-level accuracy requirements for semiconductor fab process control.
Water Test Kits Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification burden and detection precision dimensions. The vendor base stratifies between instrumentation-heavy municipal compliance portfolios and handheld meter ecosystems for field technicians. Three archetypes dominate: electrochemical sensor specialists, colorimetric strip manufacturers, and portable spectrophotometry developers. M&A activity concentrates on technology licensing deals and strategic partnerships for cloud-based calibration algorithms.
Within the electrochemical tier, Hach and Hanna Instruments exemplify divergent positioning strategies. Hach anchors the municipal and industrial compliance segment with instrumentation-heavy portfolios requiring EPA method approval. Hanna Instruments occupies the mid-market field technician segment through handheld meter ecosystem penetration. Palintest represents the portable spectrophotometry archetype, sitting within the laboratory-equivalent field testing standards pursued by ISO 17025-accredited manufacturers.
| Leading Market Players |
|---|
| Palintest |
| Hanna Instruments |
| Hach |
| CHEmetrics |
| Metrohm AG |
| LaMotte Company |
| Camlab Ltd. |
| Aquagenx |
| Taylor Technologies |
| Others |
Supply Flow & Price Mechanics
Captive production of specialty enzymes and antibodies by three European contract manufacturers anchors both supply security and pricing power for biological contaminant kits, while REACH registration costs for novel chemistries erect barriers that protect incumbent margins from mid-tier challengers.
Pricing Analysis
Outcome-based pricing tied to EPA compliance certification tiers separates municipal procurement winners from spot-market suppliers. Three-tier pricing structure across premium electrochemical, standard spectrophotometric, and economy colorimetric levels reflects detection limit documentation and method approval status. Cost compression in the colorimetric tier intensifies as REACH reformulation deadlines force natural dye substitution R&D. Municipal utilities exhibit lowest price sensitivity due to mandate-driven replacement cycles, while rural Indian panchayat schemes demand Hindi-language kits at economy price points.
Supply Chain Analysis
Specialty enzyme and antibody production rests on German, Swiss, and Dutch contract manufacturers, creating single-source vulnerability for biological contaminant kits. Critical inputs span ion-selective electrode membranes, CMOS imaging sensors for smartphone attachments, and pre-stabilized reagent chemistries. Tariff exposure runs through specialty chemical imports from the European Union into East Asian manufacturing clusters. Distribution runs through municipal tender frameworks in Germany and Japan, route-based logistics for North American pool service contractors, and Jal Jeevan Mission procurement channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical sensor formats are displacing colorimetric strips in regulated applications, compressing viable positioning for legacy portfolio-dependent suppliers.
For Market Incumbents: Deploy ISO 17025 accreditation investment to lock municipal tender eligibility ahead of field-testing standard convergence. Backward integration into ion-selective electrode membrane production defends against reference electrode degradation claims in humid subtropical deployments. Channel control through legacy LIMS integration capabilities extends switching costs for 1990s-era utility software environments. For New Entrants and Emerging Players: The mid-market gap between Hach's instrumentation-heavy municipal portfolios and Hanna's handheld meter ecosystem offers white-space for smartphone spectrometer attachments with cloud-based calibration. California Central Valley agricultural discharge permits present the most penetrable regulatory opening, with nitrate monitoring obligations newly imposed on dairy and nut operations. Go-to-market through field technician service contracts for rental-based testing programs bypasses capital-constrained smallholder resistance. For Investors and Strategic Acquirers: Exit pathways concentrate in technology licensing deals for cloud-based calibration algorithms and strategic partnerships for microfluidic cartridge systems. Long-term viability favors electrochemical sensor specialists with EPA method approval moats over colorimetric strip manufacturers facing REACH-driven reformulation costs. Watch for PFAS detection protocol adoptions in German and US state environmental agencies as inflection indicators for immunoassay and LC-MS confirmatory kit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Smartphone Spectrometer Integration | CMOS imaging sensors with cloud calibration enable laboratory-grade quantification from $20-40 consumer hardware attachments. |
| Microfluidic Cartridge Deployment | Texas and Arizona water districts deploy automated incubation systems at wellhead points previously served by quarterly laboratory pickup. |
| REACH Reformulation Pre-Qualification | Rhine-Ruhr manufacturing corridor buyers lock supply continuity ahead of 2026 boron compound sunset dates. |
| Subscription Replenishment Programs | Florida and Arizona pool contractors consolidate chemical testing and kit resupply into monthly flat-rate route-based agreements. |
| ISO 17025 Field Accreditation | Multi-jurisdictional manufacturers unlock municipal tender eligibility previously restricted to fixed-site laboratory facilities. |
Methodological Framework
EPA enforcement databases, ISO accreditation registries, and municipal procurement records formed the secondary backbone, cross-referenced with primary interviews of water utility compliance officers, field technician service contractors, and reagent manufacturing plant managers. Bottom-up triangulation against top-down regulatory mandate analysis validated segment-level demand estimates. Customs data on ion-selective electrode membrane trade flows and Jal Jeevan Mission deployment schedules supplied geographic allocation anchors.
Bottom-up modeling built product-type, application, technology, and end-user dimensions across the projection horizon. Electrochemical sensor replacement frequency assumptions incorporated humid subtropical climate degradation factors. CAGRs derived from infrastructure renewal cycle timing in Tokyo and Osaka metropolitan zones, EPA Lead and Copper Rule compliance frequency multipliers, and REACH reformulation cost pass-through elasticity.
Inputs from METI infrastructure directives and EPA rulemaking dockets were available through the study window; gaps in real-time contractor network deployment data introduce uncertainty bands for Japan demand estimates. Forecasts reflect assumptions on smartphone spectrometer adoption curves and PFAS protocol expansion timelines. Regulatory delay in US state environmental agencies and REACH authorization timeline slippage warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
Global Lab Supplies Market
Testing Equipment
Paint Tester Market
Testing Equipment
Process Analytical Technology Market
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
Global Laboratory Analytical Instruments and Consumables Market
Testing Equipment
Sample Preparation Market
Testing Equipment
Laboratory Mixer Market
Testing Equipment
Elemental Analysis Market
Testing Equipment
Global Chromatography Instruments Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Supercritical Fluid Chromatography (SFC) System Market
Testing Equipment
Steel Testing Equipment Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market
Testing Equipment
Lactose Assay Kit Market
Testing Equipment
Chlorine Meter Market