
 FTIR Fuel Analyzer Market | 2026-2036
FTIR Fuel Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
FTIR Fuel Analyzer Market Foresight
Spectroscopy-trained laboratory technicians is reorganizing how quickly FTIR fuel analyzers deploy across downstream oil and gas operations. Thermo Fisher Scientific leverages its analytical instrumentation heritage to anchor premium benchtop configurations for refinery laboratories. Bruker Corporation sustains competitive positioning through specialized R&D intensity in infrared detector architectures. ABB Ltd. dominates process-integrated online analyzer installations with its automation channel control.
An FTIR fuel analyzer employs Fourier transform infrared spectroscopy to measure hydrocarbon composition, sulfur content, and additive concentrations through interferometric detection of mid-infrared absorption spectra, typically spanning the 2.5 to 25 micrometer wavelength range. The instrument's primary purpose is rapid, non-destructive verification of fuel properties against ASTM D7806 and EN 14078 standards for biodiesel content determination. Portable analyzers occupy the fastest-growing product configuration as field inspection teams at pipeline terminals and storage depots demand laboratory-grade accuracy without fixed infrastructure. Benchtop analyzers retain the deepest margin pools where petrochemical manufacturers perform high-throughput quality control on blended gasoline and diesel batches.
EPA sulfur regulations under the Clean Air Act mandate ultra-low sulfur diesel testing that directly shapes analyzer procurement by US refining facilities. The EU F-Gas Regulation and REACH compliance frameworks in Europe compel additive disclosure and refrigerant gas analysis in imported fuel streams. China's NMPA and GB standards enforce progressively stricter fuel quality specifications for domestic refinery output. Stakeholders must monitor how regulatory divergence between these jurisdictions influences instrument calibration requirements and service revenue models.
Market Dynamics
Refinery laboratories are consolidating from offline batch testing toward continuous inline verification systems, compressing deployment cycles and rewiring vendor-customer relationships around real-time data integration rather than discrete instrument sales.
Growth Catalysts
- EPA sulfur mandates:Ultra-low sulfur diesel specifications under the Clean Air Act compel US refiners to upgrade from periodic sampling to continuous compositional monitoring, directly expanding analyzer procurement budgets.
- Pipeline terminal field inspection:Portable FTIR configurations enable laboratory-grade verification at remote storage depots without fixed infrastructure, accelerating adoption among midstream logistics operators.
- EU F-Gas Regulation:Refrigerant gas analysis requirements for imported fuel streams create mandatory testing protocols that European importers must satisfy through certified analyzer deployment.
Market Restraints
- Detector material concentration:MCT (mercury-cadmium-telluride) infrared detector production concentrates among a handful of specialized suppliers, exposing instrument manufacturers to input bottlenecks and price volatility.
- Calibration complexity:Divergent ASTM D7806 and EN 14078 reference standards force vendors to maintain multiple calibration libraries, inflating service costs and complicating cross-border instrument transfers.
- Raman spectroscopy substitution:Alternative optical methods for hydrocarbon fingerprinting are gaining traction in certain refinery applications where water content interference is minimal.
Strategic Opportunities
- India downstream expansion:Reliance Industries and Indian Oil Corporation are modernizing quality control laboratories at Jamnagar and Paradip refinery complexes, creating first-mover positioning for portable analyzer vendors.
- Electrofuel certification:Synthetic e-fuel blending mandates in Germany require novel compositional verification protocols that existing ASTM methods do not fully address.
- Cloud-connected service models:Remote diagnostic platforms paired with FTIR hardware enable predictive maintenance revenue streams that decouple vendor economics from pure instrument sales cycles.
Industry Challenges
- Spectroscopy technician scarcity:Refinery laboratories report difficulty recruiting personnel trained in interferometric data interpretation and mid-infrared spectral analysis, delaying deployment timelines.
- Legacy LIMS integration:Older laboratory information management systems at established refineries lack API architectures compatible with modern analyzer data streams, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FTIR Fuel Analyzer Market |
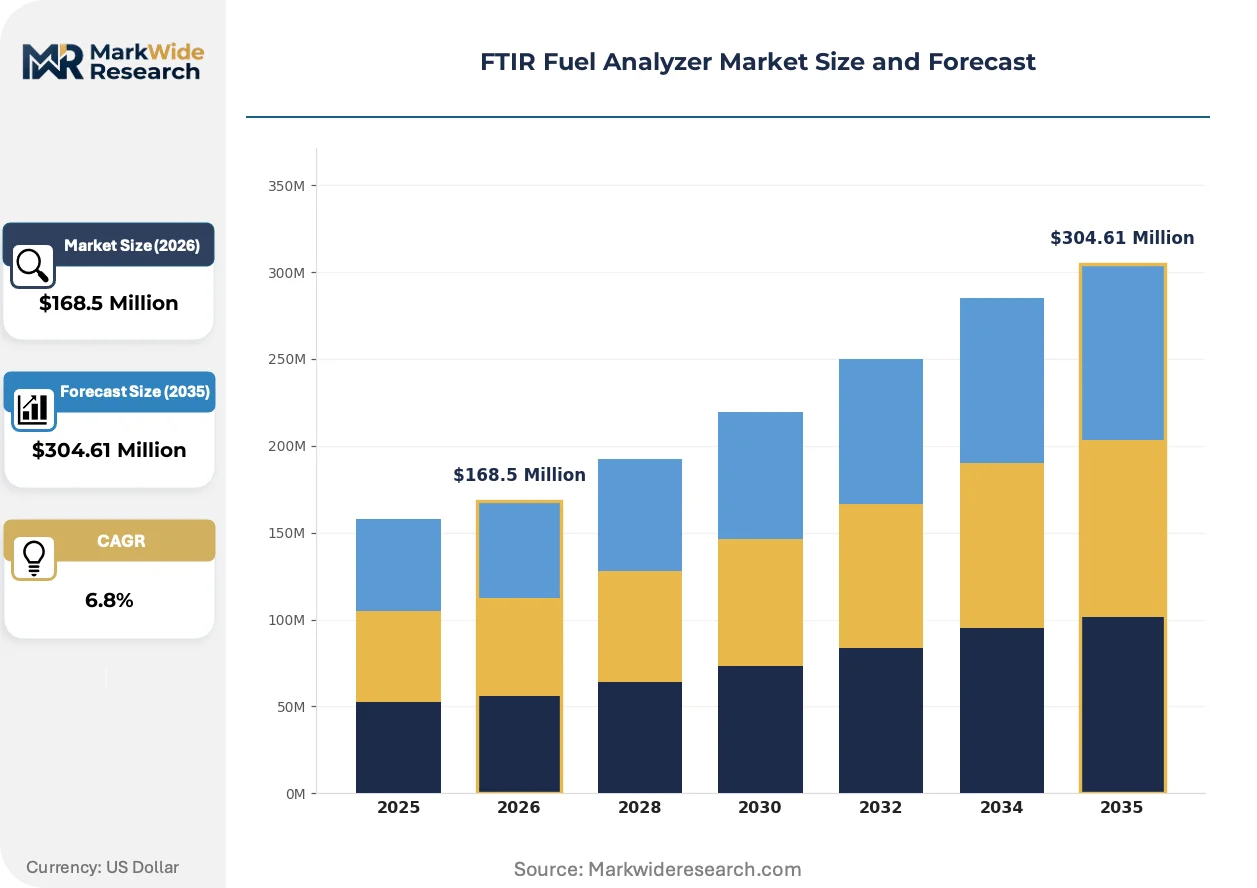
| Market Size in 2026 | $168.5 Million |
| Market Size in 2035 | $304.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzer, Benchtop Analyzer, Handheld Analyzer, Online Analyzer Technology: Fourier Transform Infrared Spectroscopy, Photoacoustic Spectroscopy, Near-Infrared Spectroscopy, Raman Spectroscopy, Ultraviolet-Visible Spectroscopy Application: Quality Control, Contaminant Detection, Additive Analysis, Blend Verification, Regulatory Compliance End User: Fuel Testing Laboratories, Petrochemical Manufacturers, Refining Facilities, Research Institute, Quality Assurance Teams |
| Companies Covered | Thermo Fisher Scientific, Bruker Corporation, ABB Ltd., Siemens AG, MKS Instruments, Inc., Gasmet Technologies Oy, HORIBA Ltd., Yokogawa Electric Corporation, Servomex Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FTIR Fuel Analyzer Market Shifts & Advancements
Portable and process-integrated analyzer configurations are converging with cloud analytics platforms, collapsing the traditional boundary between field inspection and central laboratory verification workflows.
Quantum cascade laser sources are displacing traditional globar infrared emitters in next-generation portable analyzers. Pipeline terminal operators in Texas and Rotterdam are piloting these solid-state configurations for their superior spectral stability in variable ambient conditions. This photonic substitution is compressing calibration drift intervals from weekly to monthly cycles, reducing field service costs.
REACH compliance frameworks in Europe now mandate full additive disclosure in blended fuel imports, compelling refiners to document antioxidant, detergent, and cetane improver concentrations at customs entry points. German and Dutch laboratories are responding by deploying dual-beam FTIR configurations capable of simultaneous hydrocarbon and additive quantification.
Refinery procurement departments are unbundling analyzer hardware from service contracts, negotiating separate agreements for calibration gas supply, software updates, and spectral library access. This disaggregation is most pronounced among integrated oil companies operating across multiple US Gulf Coast facilities, where centralized procurement teams demand line-item transparency previously obscured in bundled pricing.
FTIR Fuel Analyzer Market Segmentation
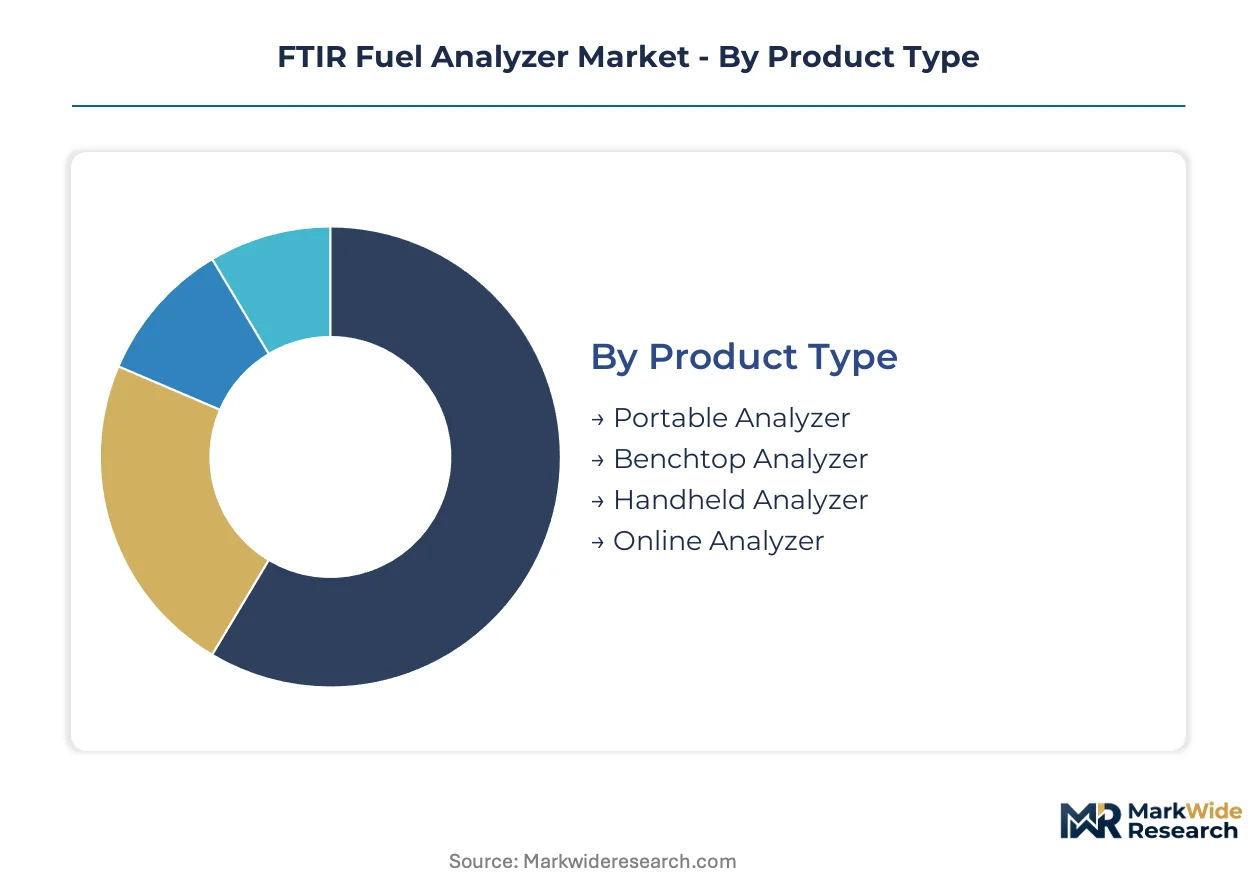
FTIR fuel analyzer procurement patterns diverge sharply across product configurations and end-use environments. Understanding these segment boundaries clarifies where portable units displace fixed infrastructure versus where benchtop precision remains non-negotiable.
Product Type:
Portable configurations face the most acute substitution pressure from Raman and photoacoustic alternatives in field applications where water interference is minimal, while online analyzers defend their installed base through automation integration.
- Portable Analyzer:Battery-powered units with interferometric engines deliver laboratory-grade spectral resolution at pipeline terminals and storage depots. Demand concentrates among midstream logistics operators in the United States and Germany seeking to eliminate fixed laboratory infrastructure at remote facilities.
- Benchtop Analyzer:High-throughput configurations with stabilized optical benches process blended gasoline and diesel batches in centralized refinery laboratories. Petrochemical manufacturers in China and India anchor procurement volumes where batch certification requires documented ASTM D7806 compliance.
- Handheld Analyzer:Single-hand operation units trade spectral range for field portability during rapid spot checks.
- Online Analyzer:Process-integrated systems with automated sampling loops enable continuous inline verification at refining units.
Benchtop analyzers retain volume leadership among centralized laboratories; portable units hold the steepest expansion curve as field inspection mandates proliferate.
Technology:
Cost tier stratification separates premium interferometric platforms from emerging solid-state alternatives, with price-performance ratios determining adoption thresholds across end-use segments.
- Fourier Transform Infrared Spectroscopy:Michelson interferometer architectures with broadband globar or quantum cascade laser sources deliver the reference-grade spectral resolution required for EPA sulfur quantification. Refining facilities in the United States specify FTIR as the primary method for ultra-low sulfur diesel certification under Clean Air Act mandates.
- Photoacoustic Spectroscopy:Laser-induced acoustic detection eliminates sample preparation requirements for opaque or highly viscous fuel matrices. European importers subject to EU F-Gas Regulation refrigerant analysis protocols are piloting these configurations at Rotterdam and Hamburg entry points.
- Near-Infrared Spectroscopy:Shorter-wavelength operation enables faster measurement cycles with reduced optical complexity.
- Raman Spectroscopy:Inelastic light scattering methods compete in applications where water content remains minimal and fluorescence interference is controlled.
- Ultraviolet-Visible Spectroscopy:Electronic transition detection addresses specific additive and dye quantification requirements.
FTIR platforms command the deepest installed base; photoacoustic methods are climbing the fastest as customs laboratories seek reduced sample handling protocols.
Application:
Application maturity varies by regulatory enforcement intensity, with compliance-driven segments commanding premium pricing against discretionary quality control spending.
- Quality Control:Batch release testing of finished gasoline, diesel, and jet fuel specifications against refinery internal standards and customer contractual requirements. Fuel testing laboratories in Germany and China process the highest sample volumes where blend consistency directly impacts supply contract renewals.
- Contaminant Detection:Trace-level identification of water, particulate, and microbial contamination in stored fuel inventories. Pipeline terminal operators in Texas and Louisiana deploy portable units following hurricane-related flooding events that compromise storage integrity.
- Additive Analysis:Quantification of detergent, antioxidant, and cetane improver concentrations in blended products.
- Blend Verification:Confirmation of biodiesel, ethanol, and synthetic component ratios in finished fuels.
- Regulatory Compliance:Documented testing for EPA, EU F-Gas, and GB standard enforcement.
Quality control applications retain volume leadership; contaminant detection holds the steepest expansion curve as climate-related storage risks intensify.
End User:
Customer type determines procurement sophistication, with integrated oil companies negotiating unbundled service contracts against smaller laboratories accepting bundled pricing.
- Refining Facilities:Downstream processing units requiring continuous inline monitoring and batch certification for pipeline injection and product liftings. Reliance Industries at Jamnagar and Indian Oil Corporation at Paradip are modernizing quality control infrastructure with hybrid portable-benchtop deployments.
- Petrochemical Manufacturers:Integrated chemical producers verifying feedstock quality and finished product specifications against customer requirements. BASF and Dow operations in Germany and the United States specify dual-beam configurations for simultaneous hydrocarbon and additive analysis.
- Fuel Testing Laboratories:Independent and captive testing facilities serving regulatory submission and commercial arbitration needs.
- Research Institute:Academic and government laboratories developing next-generation fuel formulations and verification protocols.
- Quality Assurance Teams:Corporate compliance departments overseeing multi-site standardization.
Refining facilities retain volume leadership; petrochemical manufacturers hold the steepest expansion curve as electrofuel blending mandates create novel certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States refiners deploy portable FTIR units at pipeline terminals for field sulfur verification, while German laboratories favor benchtop configurations for additive quantification under REACH mandates. Chinese facilities split demand between inline process analyzers and batch-testing systems as domestic refinery capacity expands.
United States
EPA sulfur mandates under the Clean Air Act drive continuous monitoring upgrades at Gulf Coast refining complexes. Ultra-low sulfur diesel specifications compel facilities from Texas to Louisiana to replace periodic sampling with inline verification systems. Houston-area terminals deploy portable analyzers for rapid field inspection following hurricane-related storage integrity events.
Germany
Electrofuel blending mandates and REACH additive disclosure requirements shape analyzer procurement at petrochemical laboratories. The EU F-Gas Regulation creates mandatory refrigerant gas testing protocols for imported fuel streams. BASF operations in Ludwigshafen and Bayer facilities in Leverkusen specify dual-beam configurations for simultaneous hydrocarbon and additive analysis.
China
NMPA fuel quality specifications and GB standards enforce progressively stricter domestic refinery output testing. State-owned enterprises modernize quality control infrastructure at Sinopec and PetroChina facilities across the Yangtze River Delta and Shandong Peninsula. Independent laboratories in Shanghai and Beijing process high sample volumes for blend certification.
India
Reliance Industries and Indian Oil Corporation expand quality control budgets at Jamnagar and Paradip refinery complexes under BIS fuel standards. The PLI scheme for downstream manufacturing accelerates laboratory infrastructure investment. Gujarat and Maharashtra refining clusters create first-mover positioning for portable analyzer vendors serving field inspection teams.
Netherlands
Rotterdam customs laboratories pilot photoacoustic spectroscopy configurations for reduced sample handling under EU F-Gas import protocols. REACH compliance frameworks mandate full additive documentation at Europe's largest fuel entry point. Dutch importers deploy dual-beam FTIR systems for simultaneous hydrocarbon and refrigerant gas quantification.
FTIR Fuel Analyzer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with analytical instrumentation conglomerates controlling premium benchtop segments while photonics specialists defend niches in detector architectures and process automation. The competitive landscape stratifies across three archetypes: diversified laboratory equipment providers with heritage analytical portfolios, dedicated spectroscopy houses with concentrated R&D intensity, and industrial automation vendors with channel control over inline process installations. Consolidation pressure operates through technology licensing partnerships and service contract unbundling rather than horizontal merger activity.
Among diversified analytical instrumentation providers, Thermo Fisher Scientific and Bruker Corporation exemplify the heritage-driven tier that anchors premium laboratory configurations. Thermo Fisher leverages its analytical instrumentation legacy to occupy positions in refinery laboratory procurement, while Bruker represents concentrated spectroscopy specialization in infrared detector architectures. ABB Ltd. sits within the industrial automation archetype, dominating process-integrated online analyzer installations through its control systems channel relationships with refining facilities.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bruker Corporation |
| ABB Ltd. |
| Siemens AG |
| MKS Instruments, Inc. |
| Gasmet Technologies Oy |
| HORIBA Ltd. |
| Yokogawa Electric Corporation |
| Servomex Group Limited |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for MCT infrared detector procurement concentrate pricing power among a handful of specialized suppliers, forcing instrument manufacturers to absorb input volatility or pass through cost surges to refinery procurement departments with limited alternative sourcing options.
Pricing Analysis
Long-term service contracts dominate analyzer procurement as integrated oil companies unbundle hardware from calibration gas supply and spectral library access. Three-tier pricing structure across premium interferometric platforms, mid-range portable units, and economy-grade handheld configurations separates ASTM-certified laboratory systems from field inspection devices. Cost compression in portable segments is intensifying because Raman spectroscopy alternatives compete on total cost of ownership. Midstream logistics operators exhibit the highest price sensitivity, while petrochemical manufacturers prioritize precision over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for germanium beam splitters and stabilized laser sources manufactured in Germany and Japan. MCT detector fabrication concentrates in the United States and Belgium, while precision optical component machining anchors in Germany and Switzerland. Single-source vulnerability around mercury-cadmium-telluride substrate supply exposes instrument assembly to regulatory restriction risks under REACH substance controls. Distribution runs through authorized distributor networks serving refinery clusters directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable analyzer penetration at pipeline terminals represents an early-cycle expansion story as field inspection mandates proliferate faster than fixed laboratory infrastructure deployment.
For Market Incumbents: Compound service revenue streams through cloud-connected predictive maintenance platforms that decouple economics from instrument sales cycles. Deepen backward integration into infrared detector architectures to defend against MCT supply bottlenecks. Channel control over refinery automation systems at ABB and Siemens installations creates defensive moats against portable specialist entrants.
For New Entrants and Emerging Players: Differentiate on quantum cascade laser source integration for superior spectral stability in variable ambient conditions at Texas and Rotterdam terminals. Target India's Jamnagar and Paradip refinery complexes where Reliance Industries and Indian Oil Corporation modernization programs create first-mover positioning. A calibration-as-a-service go-to-market angle bypasses capital equipment procurement committees.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance tailwind play because EPA sulfur mandates and EU F-Gas Regulation create durable testing demand independent of fuel volume cycles. Acquisition target archetype: photonics specialists with concentrated R&D intensity in solid-state infrared emitters. The signal to watch is electrofuel certification protocol finalization in Germany, which would expand addressable market beyond conventional hydrocarbon testing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Service Platform Launch | Enables predictive maintenance revenue at US Gulf Coast refining facilities. |
| Quantum Cascade Laser Source Integration | Compresses calibration drift intervals from weekly to monthly cycles in field deployments. |
| Backward Integration into Detector Fabrication | Reduces MCT supply vulnerability for instrument manufacturers facing REACH restrictions. |
| India Refinery Laboratory Partnership | Captures PLI scheme downstream investment at Jamnagar and Paradip complexes. |
| Electrofuel Certification Protocol Development | Positions vendors for synthetic fuel blending mandates under German regulatory frameworks. |
Research Methodology
Desk research of customs trade databases, EPA enforcement records, and EU regulatory filings preceded structured interviews with refinery laboratory managers, spectroscopy instrument procurement leads, and infrared detector manufacturing specialists. Primary fieldwork with downstream oil and gas operators combined with secondary validation against ASTM standard documentation and SEC 10-K instrument revenue disclosures. Bottom-up unit shipment estimates triangulated against top-down addressable market calculations across portable, benchtop, and online analyzer configurations.
Variance decomposition across product type, technology platform, application maturity, and end-user procurement sophistication shaped the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by regulatory enforcement intensity in the United States, Germany, and China. Modeled inputs included refinery capacity expansion timelines, sulfur specification phase-in schedules, and cloud service attach rate assumptions for predictive maintenance offerings.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA sulfur mandate enforcement and EU F-Gas Regulation compliance continuity; material deviation in regulatory stringency or electrofuel certification timeline would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Supercritical Fluid Chromatography (SFC) System Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Global Asbestos Testing Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Wood Moisture Tester Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Liquid Chromatography Mass Spectrometry (LCMS) Market
Testing Equipment
Supercritical Fluid Chromatography Market
Testing Equipment
Piping Hydro Testing Market
Testing Equipment
High Performance Liquid Chromatography (HPLC) Market
Testing Equipment
2D Chromatography Market
Testing Equipment
Geochemical Services Market
Testing Equipment
Dynamic Vapor Sorption Analyzer Market
Testing Equipment
China Material Testing Market
Testing Equipment
Chromatography Accessories and Consumables Market
Testing Equipment
Global Host Cell Contaminant Testing Market