
 Sugarcane Packaging Market | 2026-2036
Sugarcane Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Sugarcane Packaging Market Analytics
Buyer concentration across institutional food service is restructuring procurement patterns for plant-based packaging. Sodexo and Aramark-scale operators now specify bagasse compliance in national supply agreements. World Centric leverages its California manufacturing base to anchor West Coast distribution networks. Huhtamäki Oyj competes through European molded-fiber capacity that serves quick-service restaurant chains. Pactiv Evergreen extends its foodservice footprint by integrating bagasse lines alongside legacy plastic operations.
Sugarcane packaging comprises molded fiber articles manufactured from bagasse pulp, the fibrous residue remaining after juice extraction, typically processed at 180-220°C under pressure to form rigid containers with grease-resistant properties. These articles serve as direct substitutes for expanded polystyrene and polypropylene in hot-food and cold-food applications. Food containers dominate volume flows due to quick-service restaurant adoption, while clamshells capture premium positioning through leak-resistant hinge designs. The food grade material segment sustains pricing power through FDA and EFSA compliance requirements that industrial grade alternatives cannot satisfy.
The EU F-Gas Regulation and REACH framework restrict fluorinated additives in food-contact materials, redirecting formulation investment toward PFAS-free oil-resistant coatings. India's BIS certification mandates migration testing for bagasse articles, creating compliance barriers for uncertified imports. The US FDA maintains food-contact notification requirements that shape product development timelines. Stakeholders must monitor evolving state-level extended producer responsibility laws that will redefine collection infrastructure obligations.
Market Dynamics
The EU Single-Use Plastics Directive is compressing demand timelines for petroleum-derived containers while redirecting capital toward bagasse pulping infrastructure. This regulatory compression is restructuring procurement specifications across institutional food service and quick-service restaurant chains.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated additives in food-contact materials are forcing reformulation toward PFAS-free oil-resistant coatings, expanding addressable market for compliant bagasse alternatives.
- Brazilian feedstock concentration:The southeastern industrial corridor integrates sugarcane bagasse residue directly with molded fiber manufacturing, compressing raw material logistics costs.
- Institutional food service procurement:National supply agreements from Sodexo-scale operators now specify bagasse compliance, creating volume anchors for capacity expansion.
Market Restraints
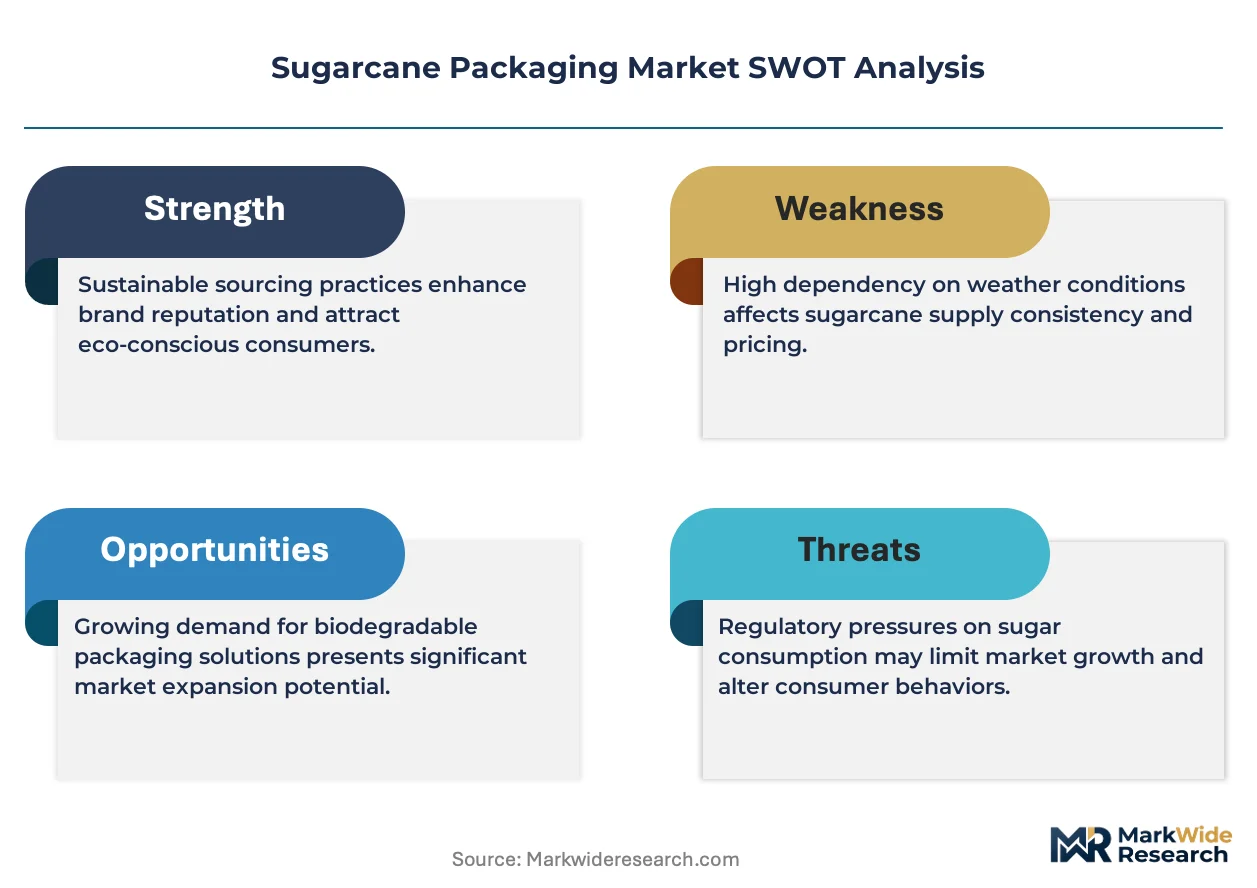
- Bagasse supply seasonality:Sugarcane harvest cycles concentrate feedstock availability, requiring working capital buffers for year-round manufacturing.
- Fluorinated coating dependency:PFAS-free alternatives still exhibit performance gaps in high-temperature oil resistance, limiting hot-food application scope.
- India BIS certification barriers:Mandatory migration testing for bagasse articles creates compliance friction for uncertified imports.
Strategic Opportunities
- US state-level EPR laws:Extended producer responsibility legislation is redefining collection infrastructure obligations, creating first-mover advantages for integrated bagasse recovery systems.
- Cold-chain logistics packaging:Insulated bagasse clamshells for meal-kit delivery remain underpenetrated relative to expanded polystyrene incumbent.
- Digital printing convergence:Integration of water-based inkjet decoration with molded fiber forming enables brand-customized food service containers at short runs.
Industry Challenges
- FDA food-contact notification timelines:Product development cycles extend 12-18 months for novel coating chemistries, compressing competitive response windows.
- Molded fiber tooling capex:Precision thermoforming dies for leak-resistant hinge designs require capital intensity that fragments supplier scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugarcane Packaging Market |
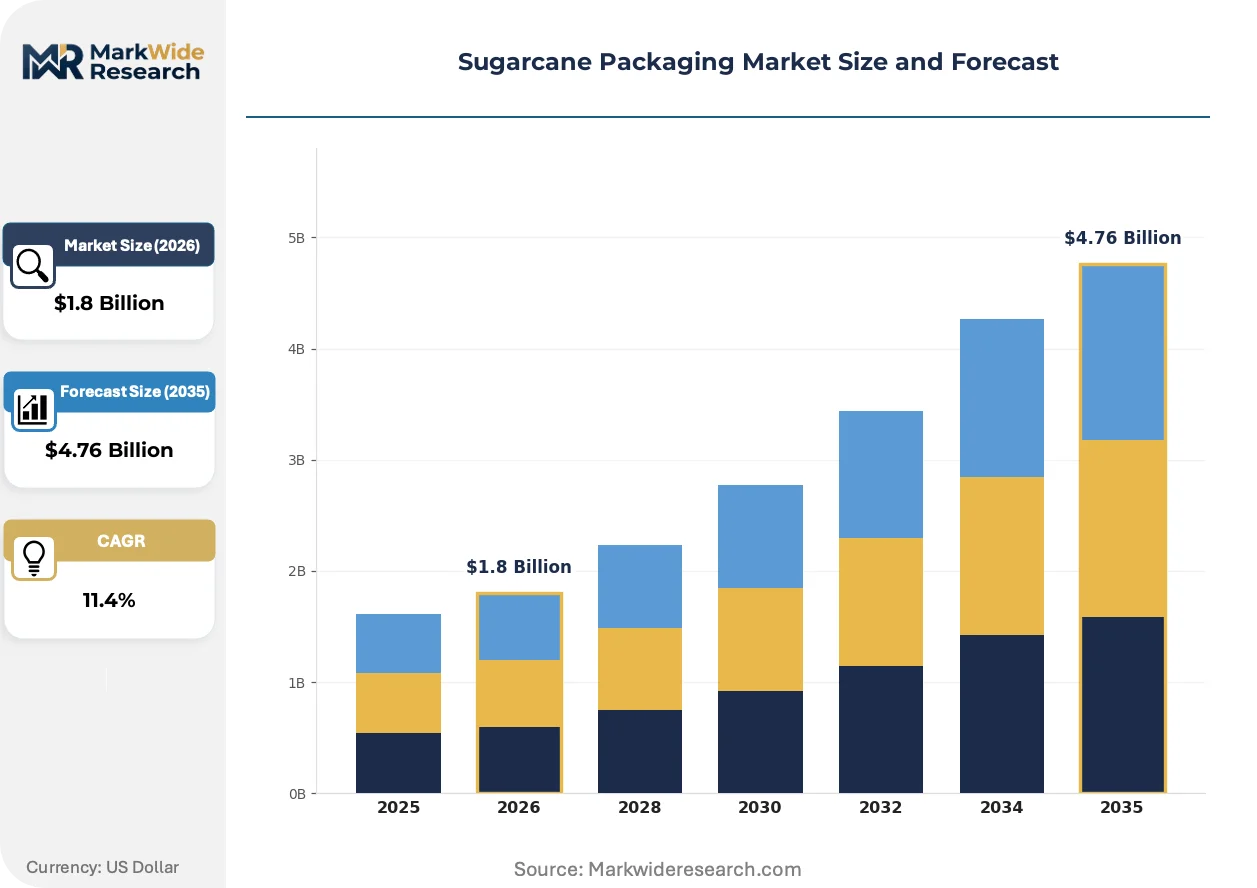
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Bags, Food Containers, Disposable Plates, Clamshells End User: Food Service, Retail, E-Commerce, Agricultural Material Grade: Food Grade, Industrial Grade, Custom Grade, Eco-Friendly Grade Distribution Channel: Online Retail, Wholesale, Direct Sales, Supermarkets |
| Companies Covered | World Centric, BioPak, Eco-Products, Pappco Greenware, Vegware, Ecoriti, Natural Tableware, Pactiv Evergreen, Huhtamäki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugarcane Packaging Market Evolving Landscape
Bagasse pulp processing is absorbing innovation investment as manufacturers seek to match petroleum-based performance without fluorinated additives. The competitive frontier centers on barrier coatings and forming precision.
PFAS-free oil-resistant coating technology is absorbing the bulk of R&D expenditure across molded fiber suppliers. Quick-service restaurant chains in North America are piloting these formulations for hot-food applications despite modest price premiums. The technology is absorbing market share from laminated paperboard alternatives by meeting FDA grease-resistance thresholds without fluorinated chemistry.
REACH framework restrictions on persistent organic pollutants are tightening compliance windows for food-contact materials across European manufacturing. Industrial consequence includes accelerated substitution of legacy fluorinated additives with bio-based barrier systems. Quick-service chains with EU exposure are reformulating specifications fastest, pressuring suppliers to certify alternatives before 2025 enforcement milestones.
Specification consolidation among buyer procurement teams is compressing supplier qualification cycles. National food service contracts now bundle bagasse compliance with carbon accounting requirements, displacing fragmented regional purchasing. This pattern concentrates most visibly in California and New York state institutional purchasing frameworks.
Sugarcane Packaging Market Segmentation
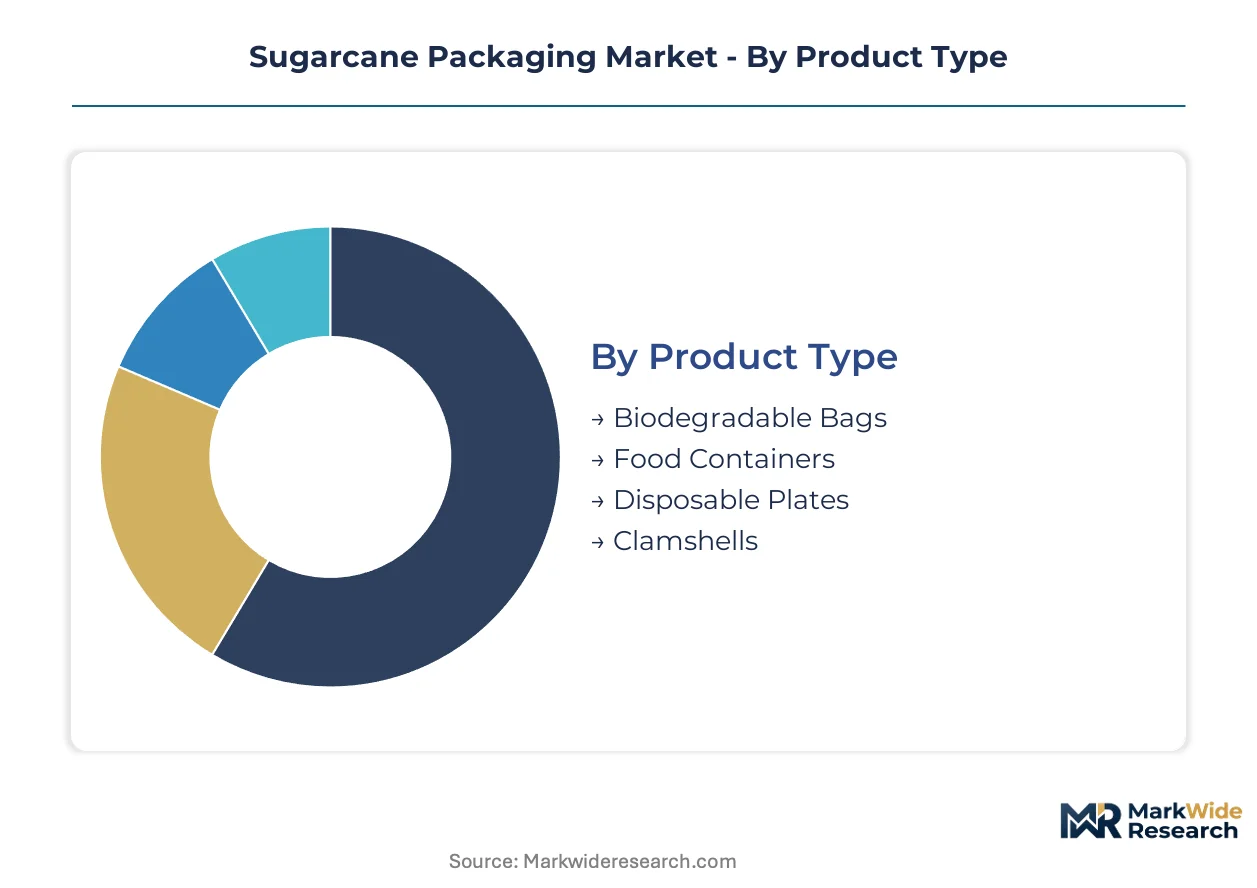
Sugarcane packaging markets fragment across four structural dimensions. Product type and end-user concentration determine volume allocation, while material grade and distribution channel shape margin capture and geographic reach.
Product Type:
Volume concentration tilts toward high-throughput food service applications, while premium positioning attaches to specialized form factors with barrier performance requirements.
- Food Containers:Molded fiber bowls and trays processed at 180-220°C under pressure form the volume backbone. Quick-service restaurant chains across Brazil's southeastern industrial corridor specify these for hot-food applications where grease-resistant properties are mandatory.
- Clamshells:Leak-resistant hinge designs command pricing premiums through precision thermoforming. Meal-kit delivery operators in North America are piloting insulated variants for cold-chain logistics, displacing expanded polystyrene incumbents.
- Biodegradable Bags:Film-grade bagasse pulp formulations serve retail carry-out applications with moderate barrier requirements.
- Disposable Plates:Standard-duty molded fiber rounds dominate institutional catering procurement with basic oil-resistance specifications.
Mature deployment sits with food containers. Newer deployment is concentrated in clamshells.
End User:
Procurement scale separates national contract operators from fragmented regional purchasers, restructuring supplier qualification requirements.
- Food Service:Sodexo and Aramark-scale operators now bundle bagasse compliance with carbon accounting in national supply agreements. These contracts anchor West Coast and Northeast US distribution networks with volume commitments that justify dedicated pulping capacity.
- Retail:Grocery deli counters and prepared-food sections specify bagasse alternatives to meet corporate sustainability targets. EU Single-Use Plastics Directive compliance deadlines are accelerating substitution timelines across French and German retail chains.
- E-Commerce:Direct-to-consumer meal-kit packaging remains underpenetrated relative to food service, with insulated cold-chain applications representing expansion terrain.
- Agricultural:Produce harvesting containers and nursery pots utilize industrial-grade bagasse with lower purity requirements and reduced barrier specifications.
Food service commands procurement consolidation. Retail is gaining share fastest through regulatory compression.
Material Grade:
Certification tier determines addressable market scope, with FDA and EFSA compliance creating enforceable segmentation boundaries.
- Food Grade:FDA food-contact notification and EFSA compliance sustain pricing power through 12-18 month product development timelines that uncertified competitors cannot shortcut. Migration testing protocols under India's BIS certification create additional import barriers that protect compliant suppliers.
- Industrial Grade:Non-food applications absorb lower-cost bagasse pulp with relaxed purity standards, serving agricultural and logistics sectors where barrier performance is secondary to cost position.
- Eco-Friendly Grade:Bio-based certification schemes target sustainability-conscious purchasers willing to accept performance trade-offs in select cold-food applications.
- Custom Grade:Formulation-to-specification contracts serve niche industrial applications with specialized mechanical or aesthetic requirements.
Food grade captures margin concentration. Eco-friendly grade is climbing the fastest through sustainability procurement mandates.
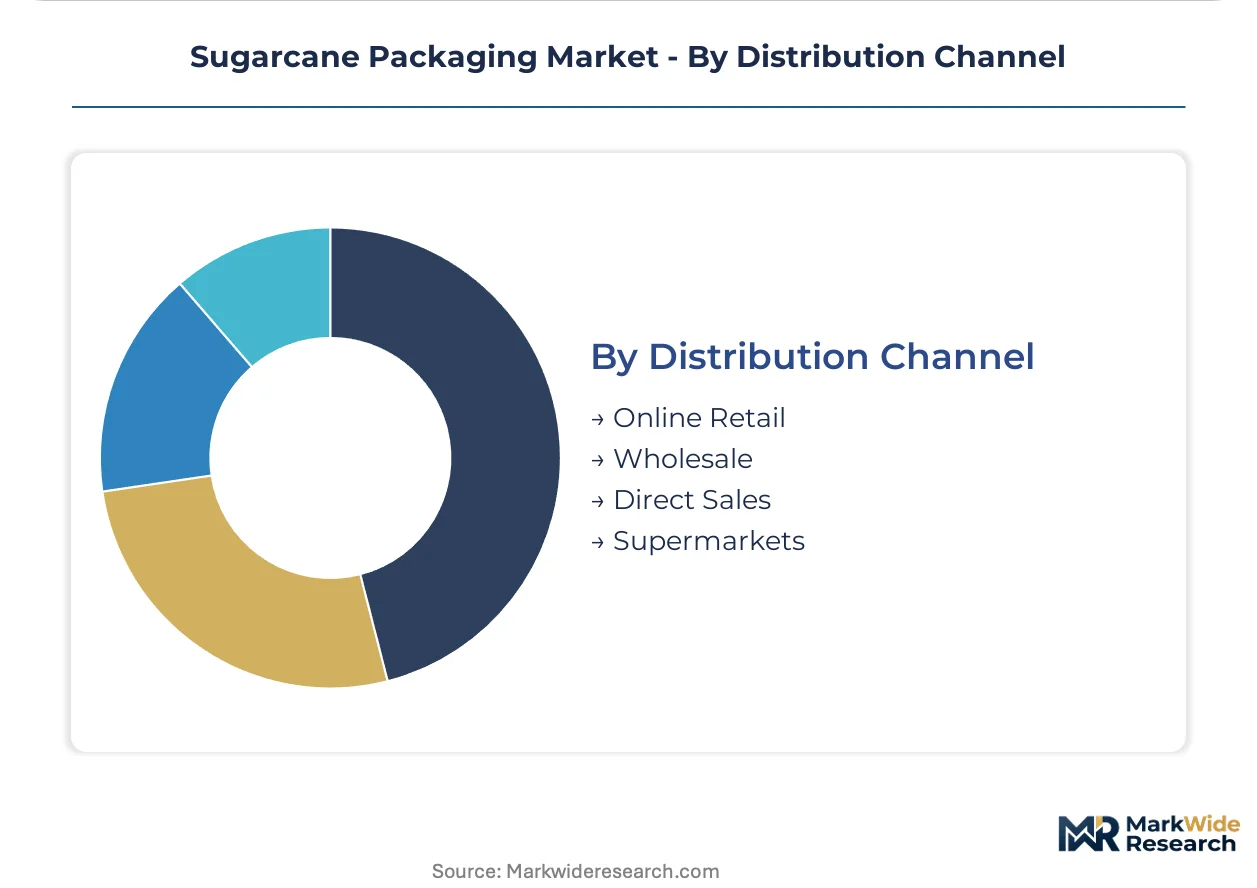
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, with direct relationships dominating institutional volumes.
- Direct Sales:National food service contracts and quick-service restaurant chain specifications route through manufacturer-direct relationships. These channels absorb the full technical support burden for coating certification and compliance documentation.
- Wholesale:Broadline distributors aggregate fragmented regional demand from independent restaurants and smaller retail operators, consolidating logistics across multiple sustainable packaging categories.
- Online Retail:E-commerce platforms serve small-batch purchasers and emerging brands with short-run requirements, though per-unit economics limit penetration in price-sensitive segments.
- Supermarkets:Private-label bagasse lines in European and North American grocery chains are expanding shelf presence for consumer-facing tableware and food storage applications.
Direct sales anchor volume stability. Online retail represents the steepest expansion trajectory for niche and trial-sized procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food service procurement consolidation concentrates demand in three specific national markets where regulatory compression intersects with institutional purchasing scale. Brazil's feedstock proximity, the United States' quick-service restaurant density, and Germany's EU directive implementation create distinct operational environments for bagasse packaging deployment.
Brazil
São Paulo state's sugarcane processing corridor supplies bagasse pulp directly to molded fiber manufacturers, eliminating transoceanic logistics costs. ANVISA's food-contact material regulations align with Mercosur technical standards, streamlining certification for regional suppliers. The southeastern industrial cluster around Piracicaba and Campinas integrates juice extraction facilities with thermoforming operations.
United States
California and New York state institutional purchasing frameworks mandate bagasse compliance in carbon-accounting procurement bundles. FDA food-contact notification requirements shape 12-18 month product development timelines for novel coating chemistries. West Coast distribution networks anchor manufacturing capacity near Los Angeles and San Francisco Bay Area quick-service restaurant concentrations.
Germany
Quick-service chains with EU-wide exposure accelerate PFAS-free specification adoption ahead of 2025 REACH enforcement milestones. The EU F-Gas Regulation redirects formulation investment toward bio-based barrier systems. Industrial packaging capacity concentrates in North Rhine-Westphalia and Bavaria, serving centralized European quick-service distribution.
India
Maharashtra and Uttar Pradesh sugar belt regions generate feedstock for domestic molded fiber production targeting food service and agricultural applications. BIS certification mandates migration testing for bagasse articles, creating compliance friction for uncertified imports. Gujarat's chemical processing infrastructure supplies PFAS-free coating formulations to domestic manufacturers.
United Kingdom
London and Southeast England institutional catering contracts specify bagasse alternatives to meet corporate sustainability disclosure requirements. The UK's post-EU regulatory framework maintains REACH-aligned restrictions on fluorinated additives in food-contact materials. Midlands manufacturing clusters serve national grocery retail private-label bagasse tableware programs.
Sugarcane Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty coating certification and short-run digital customization. The vendor base separates into three maturity tiers: multinational foodservice suppliers with integrated bagasse lines, regional molded fiber specialists, and venture-backed sustainability brands. Strategic differentiation concentrates on PFAS-free barrier performance and national contract qualification. Competitive moves center on backward integration into bagasse pulping capacity and geographic expansion through distributor partnerships.
Within the multinational tier, Huhtamäki Oyj and Pactiv Evergreen exemplify scale-driven positioning through European and North American molded-fiber infrastructure. World Centric occupies a distinct West Coast anchor position serving California's institutional procurement mandates. These three entities represent divergent geographic emphases rather than direct product overlap.
| Leading Market Players |
|---|
| World Centric |
| BioPak |
| Eco-Products |
| Pappco Greenware |
| Vegware |
| Ecoriti |
| Natural Tableware |
| Pactiv Evergreen |
| Huhtamäki Oyj |
| Others |
Value Network & Pricing Analysis
Bagasse pulping technicians concentrated in Brazil's southeastern industrial corridor create labor-cost differentials that widen pricing spreads between FDA-certified food-grade containers and industrial-grade alternatives. These skill premiums compress margins for new entrants while anchoring cost advantages for established operators with captive pulping capacity.
Pricing Analysis
Volume concentrates in standard-duty molded fiber bowls and trays where per-unit economics approach commodity parity, while margins concentrate in leak-resistant clamshells with PFAS-free barrier certification. Price differentiation rests on FDA food-contact notification status and grease-resistance performance tier. Cost compression in the standard container tier is intensifying as Brazilian feedstock integration spreads. Quick-service restaurant chains exhibit lowest price sensitivity due to carbon-accounting procurement mandates, while independent food service operators remain most sensitive.
Supply Chain Analysis
Single-source vulnerability sits with PFAS-free coating formulation suppliers concentrated in Germany and the United States. Raw material dependencies include sugarcane bagasse pulp, bio-based barrier coatings, and thermoforming die steel. Supply chain risk centers on regulatory restriction as REACH and FDA notification timelines extend qualification cycles. Distribution runs through direct manufacturer relationships for national food service contracts, with broadline distributors aggregating fragmented regional demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sugarcane packaging market operates as a cost-of-compliance story where FDA food-contact notification requirements create a 12-18 month barrier-to-entry moat that protects certified incumbents from commodity competition.
For Market Incumbents: Anticipate margin compression in standard containers by accelerating backward integration into bagasse pulping capacity in Brazil's São Paulo corridor. Secure coating formulation partnerships ahead of REACH enforcement milestones to defend against emerging entrants with bio-based barrier technology. For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany opens a window for PFAS-free coating specialists to capture quick-service restaurant reformulation demand. Target insulated cold-chain clamshells for North American meal-kit operators, where expanded polystyrene displacement lags food service adoption. Lead with short-run digital printing capabilities to serve sustainability-branded regional chains. For Investors and Strategic Acquirers: The window for entry favors molded fiber specialists with certified coating pipelines and existing food service contract relationships. Long-term viability hinges on integration with bagasse feedstock sources rather than toll manufacturing dependence. Watch for BIS certification acceleration in India as an inflection signal for Asian market opening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulping | Captive bagasse supply from São Paulo juice extraction facilities eliminates transoceanic logistics exposure. |
| PFAS-Free Coating Certification | FDA notification for novel barrier chemistries locks in quick-service restaurant specification compliance ahead of REACH deadlines. |
| Digital Printing Convergence | Water-based inkjet integration with molded fiber forming enables brand-customized short runs for regional restaurant chains. |
| Cold-Chain Clamshell Development | Insulated bagasse formulations for meal-kit delivery displace expanded polystyrene in underpenetrated logistics applications. |
| Extended Producer Responsibility Systems | Integrated bagasse recovery infrastructure creates first-mover advantage as US state-level EPR laws redefine collection obligations. |
Research Methodology
Multi-period observation of bagasse pulp pricing spreads, coating certification timelines, and food service contract award patterns anchored the trend analysis, supplemented by interviews with molded fiber plant managers, quick-service restaurant procurement directors, regulatory affairs specialists at packaging suppliers, and sustainability officers at institutional food service operators. Secondary validation drew from FDA food-contact notification databases, ECHA REACH substance registrations, Brazilian customs export records, and EU Single-Use Plastics Directive implementation tracking. Bottom-up volume estimates from pulping capacity and top-down demand triangulation from food service procurement data were cross-referenced.
Segment-weighting applied product type, material grade certification tier, and end-user concentration dimensions across the projection horizon. CAGRs were derived from trend extrapolation of regulatory compression effects and procurement specification consolidation. Industry-specific forecast inputs included sugarcane harvest cycle timing, thermoforming tooling lead times, and migration testing queue lengths at BIS and FDA.
The model assumes a particular technology adoption path for PFAS-free barrier coatings; alternative pathways for fluorine-free oil resistance would alter the outlook if performance gaps in high-temperature applications close faster than projected. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Foil Labels Market
Packaging
Europe Confectionery Packaging Market
Packaging
Global Disappearing Packaging Market
Packaging
Transparent Food Packaging Market
Packaging
Plunger Stopper Market
Packaging
Washi Tapes Market
Packaging
Metal Food Cans Market
Packaging
Recycled Plastic Envelope Market
Packaging
Aseptic Formulation Processing Market
Packaging
Die Cut Labels Market
Packaging
Multicomponent Bottle Market
Packaging
ESD Totes Market
Packaging
Plastic Packaging Market
Packaging
Ethical Label Market
Packaging
Global Polyethylene Packaging Market
Packaging
Global Personalized Packaging Market