
 Global Personalized Packaging Market | 2026-2036
Global Personalized Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personalized Packaging Market Intelligence
Multi-source procurement among brand owners is shifting toward integrated design-to-delivery partnerships with specialized converters. Mondi leverages its European paperboard network to offer short-run personalization at scale. Amcor competes through digital printing investments across flexible packaging lines. Smurfit Kappa anchors its position with corrugated customization tools for e-commerce subscription boxes.
Personalized packaging denotes containers, wraps, or enclosures engineered to carry individual consumer identifiers, variable graphics, or bespoke structural formats, typically produced through digital workflows that switch designs without plate changes. Its commercial purpose centers on brand differentiation, consumer retention, and supply-chain traceability through serialized codes. Flexible packaging leads volume in food and beverage applications where portion customization and shelf-life extension converge. Digital printing represents the fastest-expanding technology segment as run lengths compress and versioning proliferates. Paperboard packaging occupies the premium margin pool in cosmetics and personal care, where rigid structural formats command price premiums.
FDA food-contact material regulations, EU REACH chemical compliance for printed substrates, and China's GB standards for packaging recyclability collectively shape product formulation and market access requirements across major supply corridors. These frameworks compel converters to validate ink migration limits, substrate biodegradability claims, and extended producer responsibility documentation before commercial deployment. Stakeholders must monitor evolving extended producer responsibility schemes and digital watermarking standards to anticipate compliance-driven specification changes.
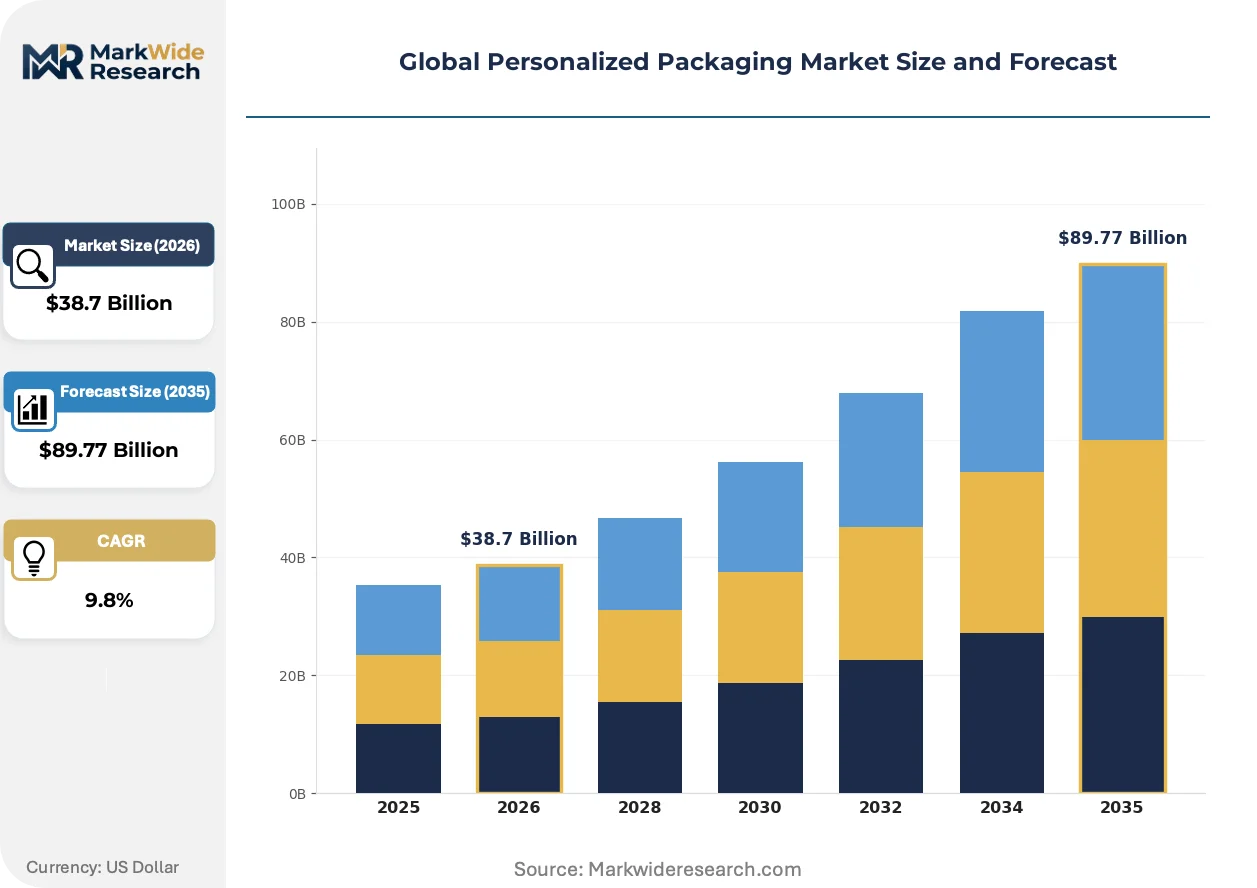
Market Dynamics
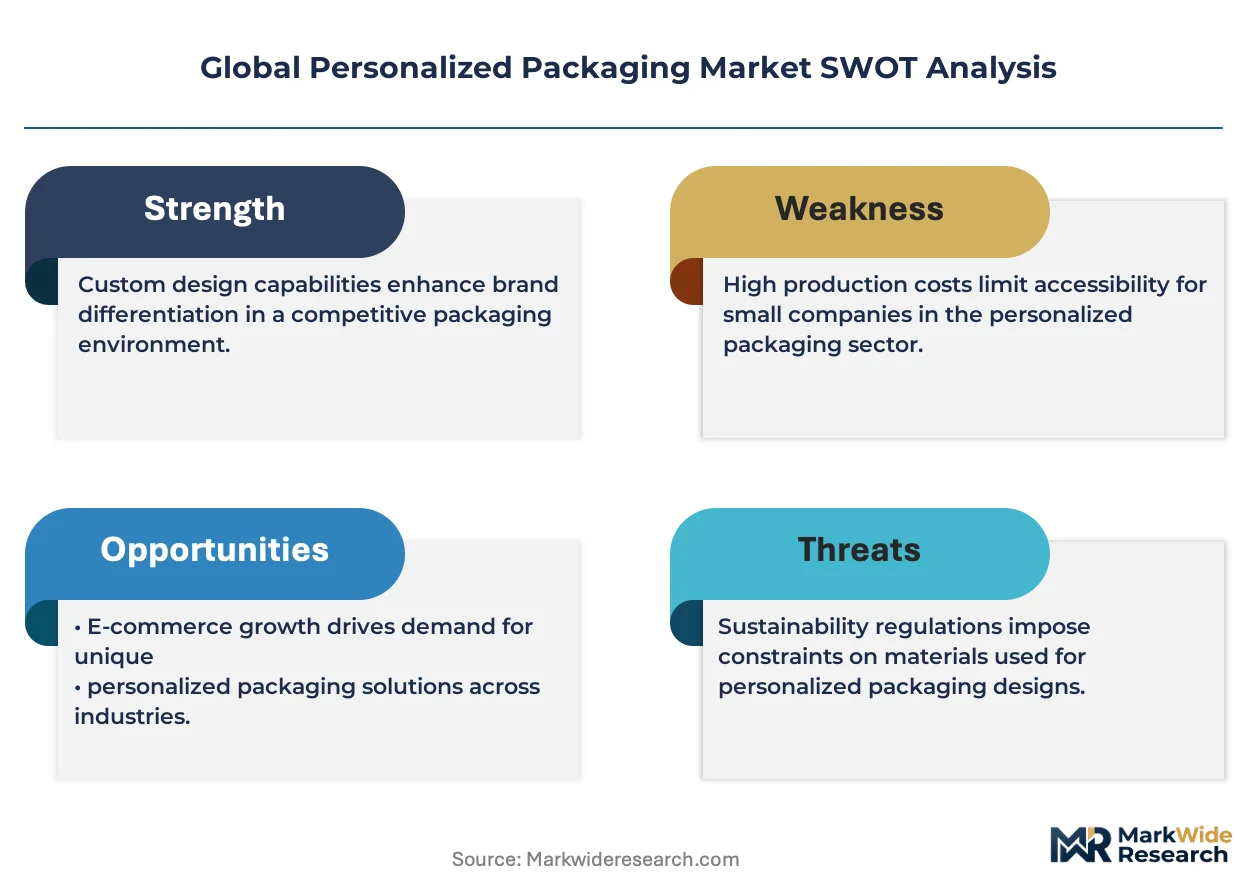
Digital printing workflows are compressing minimum order quantities from thousands to hundreds of units, forcing converters to reconfigure production scheduling and inventory management around batch-of-one economics.
Growth Catalysts
- E-commerce unboxing expectations:Subscription box brands now mandate serialized graphics and personalized inserts as standard fulfillment requirements, pulling investment into short-run digital assets.
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are accelerating demand for traceable, variable-coded packaging that supports circular economy documentation.
- Food portion customization:Flexible packaging converters serving meal-kit and specialty nutrition brands are scaling digital presses to match pack sizes to individual dietary profiles without plate changeover delays.
Market Restraints
- Pigment and substrate cost volatility:Specialty inks formulated for food-contact compliance face input cost swings tied to titanium dioxide and bio-based resin supply chains concentrated in East Asian chemical manufacturing zones.
- Digital press throughput ceilings:Current single-pass inkjet systems hit speed limitations above 150 meters per minute on corrugated board, constraining viability for high-volume beverage case runs.
- REACH chemical compliance friction:EU restrictions on certain photoinitiators in UV-cured inks force reformulation cycles that delay product launches by 8-14 months.
Strategic Opportunities
- India direct-to-consumer expansion:Domestic beauty and ayurvedic brands are piloting regional language personalization on folding cartons, creating first-mover positioning for converters with Hindi, Tamil, and Bengali variable-data capabilities.
- Blockchain-integrated serialization:Convergence of digital printing with distributed ledger verification enables anti-counterfeit packaging for pharmaceuticals and luxury goods without secondary label application.
- Reusable packaging membership models:German loop-delivery startups are contracting for durable, personalized returnable containers that carry consumer identifiers across multiple use cycles.
Industry Challenges
- Prepress workflow reconfiguration:Legacy MIS systems at mid-tier converters lack API connectivity to web-to-print portals, forcing manual job ticket creation that erodes margin on sub-500-unit runs.
- Color consistency certification:Brand owners now require G7 Master qualification for all personalized packaging suppliers, extending onboarding timelines and disqualifying uncertified regional players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personalized Packaging Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $89.77 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Paperboard Packaging, Metallic Packaging, Biodegradable Packaging Application: Food & Beverage, Cosmetics & Personal Care, Pharmaceuticals, Electronics, Consumer Goods End User: Brand Owners, Retailers, E-commerce Platforms, Distributors, Custom Packaging Providers Printing Technology: Digital Printing, Flexographic Printing, Offset Printing, Gravure Printing, Screen Printing |
| Companies Covered | Mondi, Berlin Packaging, Amcor, Packlane, Sonoco, Sealed Air, WestRock, PakFactory, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personalized Packaging Market Strategic Shifts & Innovations
Water-based inkjet formulations are penetrating food-contact applications previously reserved for solvent and UV platforms, rewriting substrate compatibility assumptions across converter R&D priorities.
Single-pass inkjet arrays with aqueous pigment systems are absorbing market share from toner-based electrophotography in folding carton applications. Premium chocolate and cosmetic brands in France and Switzerland are adopting these presses for metallic-effect personalization at run lengths below 300 units. The technology is absorbing margin pressure from brand owners who refuse to pay plate fees for seasonal or limited-edition graphics.
China's GB standards for packaging recyclability are tightening biodegradability documentation requirements for printed films and coatings. Converters exporting to the Chinese market must now submit third-party compostability certifications for all personalized flexible packaging substrates. Food and beverage brands with China-facing supply chains are responding by specifying uncoated paperboard alternatives that simplify compliance verification.
Brand procurement teams are consolidating vendor relationships around converters offering integrated design-to-fulfillment platforms. Mid-market CPG companies in the United States are abandoning transactional spot-buying for personalized packaging in favor of annual contracts with guaranteed capacity and real-time order tracking. This consolidation is most visible in the beauty and personal care vertical, where marketing calendars demand predictable turnaround on 50-200 SKU variations per product launch cycle.
Global Personalized Packaging Market Segmentation
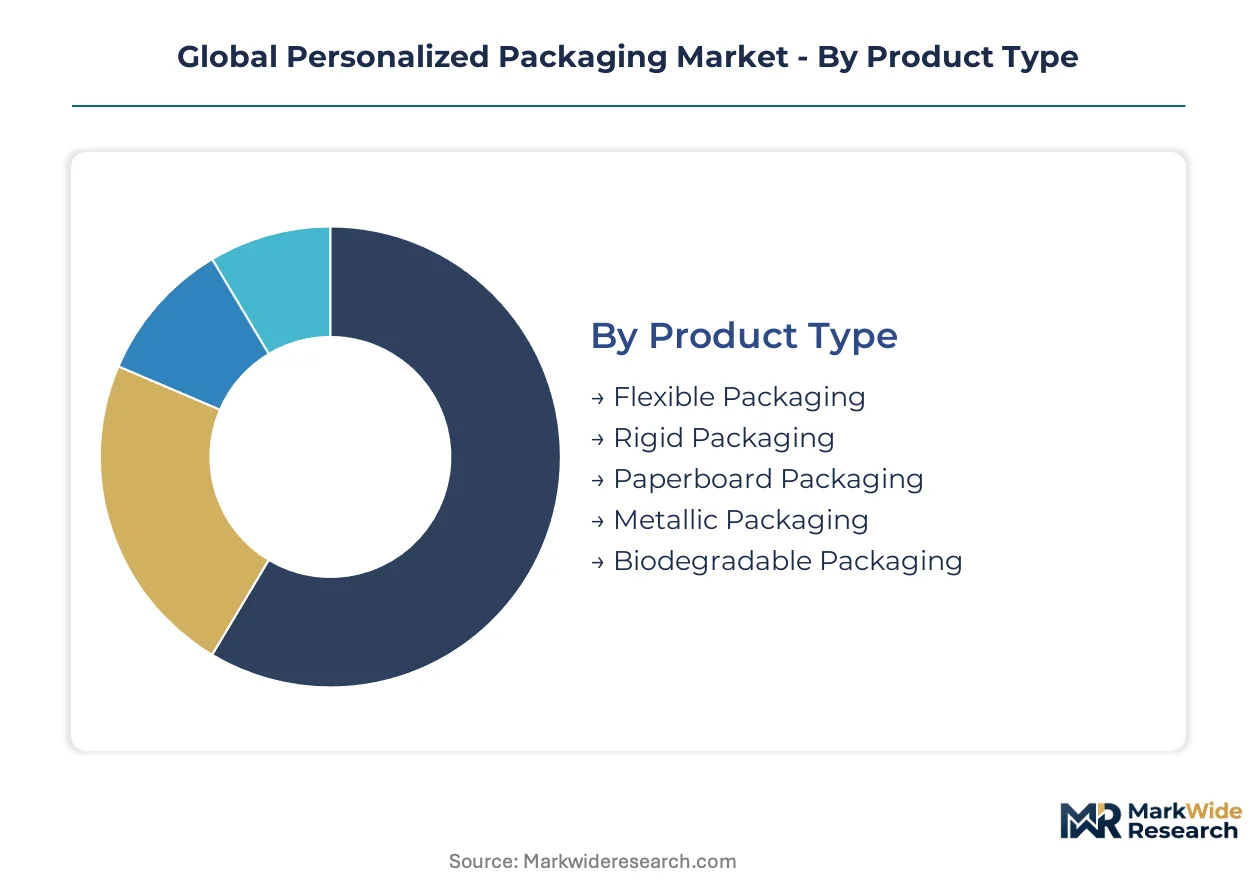
Personalized packaging markets fragment across material, application, and technology dimensions that determine production economics and compliance pathways. Understanding segment boundaries clarifies where digital workflows displace conventional plate-based systems and where regulatory constraints reshape substrate specifications.
Product Type:
Integration depth varies sharply across material categories, with some formats serving as standalone consumer touchpoints while others embed within larger protective systems.
- Flexible Packaging:Polymer-based films and pouches engineered for variable-data printing on form-fill-seal lines. Meal-kit brands in the United States specify digitally printed portion packs that switch graphics without stopping production for plate changes.
- Paperboard Packaging:Rigid cartons and folding boxes carrying premium structural formats. Cosmetic brands in France and Switzerland commission metallic-effect personalization at sub-300-unit runs, absorbing margin pressure from seasonal campaign demands.
- Rigid Packaging:Molded containers and bottles with applied labels or direct-print surfaces. Food-contact compliance requirements from FDA and EFSA constrain ink formulation choices across North American and European supply chains.
- Metallic Packaging:Aluminum and steel substrates with specialized coating systems for variable decoration. Beverage can printers in Germany pilot laser-etched serialization for anti-counterfeit traceability.
- Biodegradable Packaging:Compostable films and molded pulp meeting China's GB standards for recyclability documentation. Export-oriented converters submit third-party certifications to satisfy tightened biodegradability verification.
Flexible packaging leads volumes today; paperboard packaging is gaining share fastest.
Application:
End-use concentration determines margin structures, with premium verticals tolerating higher per-unit personalization costs than mass-market categories.
- Food & Beverage:The largest addressable base spanning fresh produce, processed goods, and beverage applications. Specialty nutrition brands scale digital presses to match pack sizes to individual dietary profiles without plate changeover delays.
- Cosmetics & Personal Care:Premium margin pool where rigid structural formats command price premiums. Marketing calendars in this vertical demand predictable turnaround on 50-200 SKU variations per product launch cycle.
- Pharmaceuticals:Serialization-mandated packaging for track-and-trace compliance. Blockchain-integrated verification enables anti-counterfeit protection without secondary label application.
- Electronics:Protective enclosures with brand-differentiated unboxing experiences. Subscription box brands mandate serialized graphics as standard fulfillment requirements.
- Consumer Goods:Broad category spanning household products and durables with variable regional specifications. Localized consumer engagement drives specification divergence across supply corridors.
Food & Beverage dominates absolute volume; Cosmetics & Personal Care shows the steepest expansion trajectory.
End User:
Procurement sophistication separates transactional spot-buyers from integrated design-to-delivery partners with guaranteed capacity arrangements.
- Brand Owners:CPG and specialty manufacturers specifying packaging as strategic brand asset. Mid-market companies in the United States abandon transactional purchasing for annual contracts with real-time order tracking.
- E-commerce Platforms:Fulfillment networks where unboxing experience drives retention metrics. Subscription box economics pull investment into short-run digital assets across United States, China, and Germany.
- Retailers:Private-label operators requiring rapid versioning for seasonal promotions. Grocery chains specify variable graphics for store-brand product lines.
- Distributors:Intermediary procurement with consolidated volume across multiple brand portfolios. Regional players face disqualification without G7 Master color consistency certification.
- Custom Packaging Providers:Specialized converters offering design-to-fulfillment integration. Vendor consolidation favors partners with API-connected web-to-print portals.
Brand Owners command the largest procurement volumes; E-commerce Platforms are expanding demand most rapidly.
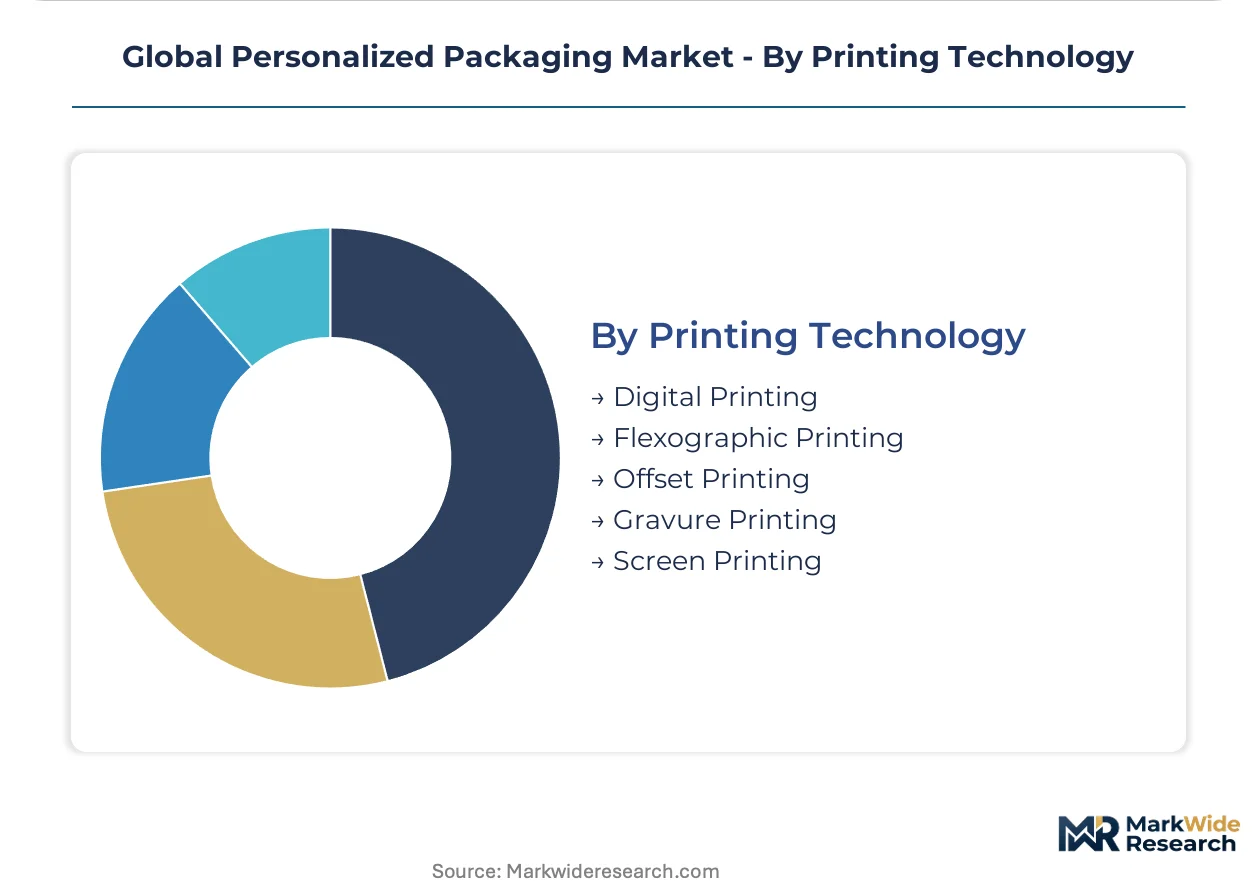
Printing Technology:
Technology selection hinges on run-length economics, with digital workflows compressing minimum order quantities from thousands to hundreds of units.
- Digital Printing:Inkjet and electrophotographic systems enabling batch-of-one production. Single-pass aqueous pigment arrays absorb market share from toner platforms in folding carton applications.
- Flexographic Printing:Rotary relief printing for medium-to-long runs with plate-based graphics. Converters reconfigure production scheduling around hybrid workflows combining flexo bases with digital overprints.
- Offset Printing:Planographic lithography for high-volume, high-fidelity reproduction. Plate fees for seasonal or limited-edition graphics drive brand owners toward digital alternatives.
- Gravure Printing:Intaglio engraving for premium decorative effects at scale. Cylinder costs restrict viability for personalized versioning below mass-market thresholds.
- Screen Printing:Stencil-based deposition for thick ink layers and specialty substrates. UV-cured formulations face REACH compliance friction requiring 8-14 month reformulation cycles.
Offset printing retains volume leadership; digital printing is climbing the fastest as run lengths compress and versioning proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr Valley converter cluster anchors European personalized packaging capacity, with Düsseldorf and Dortmund hosting specialized digital print facilities serving cosmetic and pharmaceutical brand owners.
United States
Subscription box fulfillment networks in New Jersey and Pennsylvania drive demand for serialized unboxing experiences. FDA food-contact material regulations govern ink migration limits for meal-kit portion packs. Chicago-area converters integrate web-to-print portals with e-commerce platform APIs to compress order-to-delivery cycles.
Germany
Loop-delivery startups in Berlin and Hamburg contract for durable returnable containers with consumer identifiers across multiple use cycles. EU REACH chemical compliance restricts photoinitiators in UV-cured inks, forcing reformulation cycles. Bavarian folding carton specialists pilot metallic-effect personalization for premium chocolate brands at sub-300-unit runs.
China
Domestic beauty brands in Shanghai and Guangzhou pilot regional language personalization on folding cartons for direct-to-consumer expansion. GB standards for packaging recyclability tighten biodegradability documentation requirements for printed films. Yangtze River Delta converters submit third-party compostability certifications to satisfy export compliance verification.
India
Ayurvedic and beauty brands in Maharashtra and Karnataka commission Hindi, Tamil, and Bengali variable-data capabilities for regional market penetration. FSSAI food safety standards shape substrate selection for personalized nutrition packaging. Mumbai-based converters scale digital presses to match pack sizes to individual dietary profiles without plate changeover delays.
Switzerland
Premium cosmetic brands in Geneva and Basel adopt single-pass aqueous pigment systems for metallic-effect personalization at seasonal campaign volumes. Swissmedic pharmaceutical serialization mandates accelerate blockchain-integrated verification pilots. Zurich-area converters anchor G7 Master qualification requirements that extend supplier onboarding timelines.
Global Personalized Packaging Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue design-to-fulfillment platform integration. The vendor base compresses around converters with guaranteed capacity arrangements and real-time order tracking capabilities. Three archetypes dominate: integrated paperboard network operators, flexible packaging digital print specialists, and corrugated customization tool providers. Competitive moves concentrate on strategic partnerships with e-commerce fulfillment networks and vertical integration into prepress workflow software.
Within the integrated network tier, Mondi leverages its European paperboard footprint to anchor short-run personalization at scale. Amcor occupies a position among flexible packaging specialists competing through digital printing investments across production lines. Smurfit Kappa exemplifies the corrugated customization archetype with tools targeting e-commerce subscription box economics. These three represent contrasting strategic postures on batch-of-one production economics and compliance documentation integration.
| Leading Market Players |
|---|
| Mondi |
| Berlin Packaging |
| Amcor |
| Packlane |
| Sonoco |
| Sealed Air |
| WestRock |
| PakFactory |
| Smurfit Kappa |
| Others |
Cost & Logistics Intelligence
EU extended producer responsibility mandates gate qualified supply and premium-tier pricing access by requiring converters to submit third-party compostability certifications and serialized traceability documentation before commercial deployment. Brand owners without compliant supplier networks face exclusion from major European retail channels, compressing procurement options and elevating pricing power for certified converters.
Pricing Analysis
Input-cost pass-through from titanium dioxide and bio-based resin volatility shapes contract structures across flexible packaging tiers. Three-tier pricing structure across premium, standard, and economy levels separates G7 Master-qualified converters from uncertified regional players and commodity spot-buyers. Pricing pressure stems from digital press throughput ceilings constraining high-volume beverage case economics. Mid-market CPG companies show highest price sensitivity, while premium cosmetic brands absorb per-unit premiums for sub-300-unit metallic-effect runs.
Supply Chain Analysis
Regional distribution centers in the Ruhr Valley, New Jersey-Pennsylvania corridor, and Yangtze River Delta anchor hub-and-spoke fulfillment patterns for personalized packaging. Supply concentrates in Germany, the United States, and China, with raw material dependencies on East Asian chemical manufacturing zones for specialty inks and European paperboard networks for rigid formats. Single-source vulnerability around titanium dioxide supply chains concentrated in specific chemical manufacturing zones presents structural risk. Distribution runs through integrated design-to-fulfillment platforms with API-connected web-to-print portals replacing transactional spot-buying.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Personalized Packaging Market functions as a stable compounder, with e-commerce unboxing expectations driving steady reinvestment into short-run digital assets across subscription box fulfillment networks.
For Market Incumbents: Anticipate margin compression from water-based inkjet formulations penetrating food-contact applications previously reserved for solvent platforms. Defensive moves center on backward integration into prepress workflow software and captive supply of G7 Master color certification capacity. Threat substitution from blockchain-integrated serialization providers demands counter-investment in distributed ledger verification pilots. For New Entrants and Emerging Players: Begin with regional language personalization capabilities for India's direct-to-consumer beauty and ayurvedic expansion. White-space targets include Hindi, Tamil, and Bengali variable-data folding cartons and durable returnable container contracts with German loop-delivery startups. Go-to-market angle emphasizes API connectivity to e-commerce platform order management systems. For Investors and Strategic Acquirers: Roll-up economics work for specialized converters with G7 Master qualification and guaranteed capacity arrangements because vendor consolidation favors partners with real-time order tracking. Long-term viability spans the mid-term expansion window. Acquisition target archetype: mid-tier converters with European paperboard network access and digital press fleets. Signal to watch: extended producer responsibility scheme expansions accelerating compliance-driven specification changes.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Press Fleet Expansion | Amcor and Mondi deployments absorb share from toner-based electrophotography in folding carton applications. |
| Backward Integration into Prepress Software | Converters eliminate manual job ticket creation eroding margin on sub-500-unit runs through API-connected portals. |
| G7 Master Certification Investment | Brand procurement teams disqualify uncertified regional players from annual contract consideration. |
| Blockchain Serialization Partnership | Swissmedic pharmaceutical mandates accelerate anti-counterfeit packaging without secondary label application. |
| Regional Language Variable-Data Capability | Maharashtra and Karnataka converters capture first-mover positioning for India's direct-to-consumer beauty expansion. |
Research Approach
Bottom-up e-commerce platform modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with brand procurement managers, digital press operators, regulatory compliance officers, and e-commerce fulfillment directors combined with secondary validation from FDA food-contact guidance documents, EU REACH substance restriction updates, Chinese GB standards filings, and customs trade data on specialty ink imports. Triangulation across these sources anchors volume and value estimates.
Input-output matrices mapping digital press throughput, substrate compatibility coefficients, and compliance documentation requirements across material and application segments drive the forecast framework. Segmentation dimensions include packaging format, end-use vertical, printing technology, and regional regulatory cluster. CAGRs derive from run-length compression trajectories and versioning proliferation rates observed across the analysis window. Industry-specific inputs incorporate EU Packaging and Packaging Waste Regulation implementation timelines and water-based inkjet formulation R&D cycles.
Several conditions sit outside the modeled scope, including speculative breakthroughs in single-pass inkjet speed beyond 150 meters per minute on corrugated board and unilateral tariff disruptions affecting East Asian chemical supply chains. Forecasts reflect documented assumptions on e-commerce penetration curves and extended producer responsibility scheme expansions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Packaging
Global Spoil Detection-Based Smart Label Market
Smart Packaging
Smart Packaging Market
Smart Packaging
Smart Medication Packaging Market
Smart Packaging
Smart Tag Packaging Market
Smart Packaging
Smart Retail Packaging Market
Smart Packaging
Smart Food Packaging Market
Smart Packaging
Self Cooling Packaging Market
Smart Packaging
Global Nano Enabled Packaging Market
Smart Packaging
Smart Bottle Market
Smart Packaging
North America Smart Label Market
Smart Packaging
Smart Label Market
Smart Packaging
Digital Packaging Market
Smart Packaging
Intelligent Tamper-Proof Packaging Market