
 Thiamine Market | 2026-2036
Thiamine Market Size, Share, and Industry Trends Forecast 2026-2036
Thiamine Market Intelligence
A capital-intensity divergence between integrated chemical synthesis and specialized fermentation producers is unwinding the market’s traditional cost structure. BASF SE leverages its extensive chemical manufacturing scale for commodity-grade thiamine. In contrast, Koninklijke DSM N.V. differentiates through its focus on high-purity nutritional ingredients and advanced fermentation processes. Meanwhile, Zhejiang Medicine Co. Ltd. anchors its position through large-volume production catering to Asia's feed and pharmaceutical sectors.
Thiamine, or vitamin B1, is an essential water-soluble vitamin crucial for carbohydrate metabolism. It is typically synthesized as thiamine hydrochloride for stability in various formulations. Feed additives represent the largest application by volume, driven by inclusion in animal diets to support growth and health. The nutritional supplements segment, primarily in tablet and capsule forms, commands higher price points and caters to direct consumer health needs.
Regulatory frameworks from the US FDA and Europe's EFSA dictate purity standards for pharmaceutical and food-grade thiamine. In China, GB standards govern its use in feed additives and fortified foods, creating distinct market access requirements. These regulations directly influence production costs and grade-specific supply chains. Consequently, manufacturers must decide whether to focus on high-volume feed applications or invest in the stringent quality systems required for human nutritional products.
Market Dynamics
The divergence between high-volume feed-grade and high-purity human-grade production defines the market’s core tension. This split is driven by disparate regulatory requirements from bodies like the FDA and EFSA and distinct capital investment strategies for synthesis versus fermentation.
Growth Catalysts
- Feed Additive Demand:Inclusion in livestock diets in major agricultural economies like China supports animal health and productivity, creating a large, stable volume base for thiamine.
- Food Fortification Mandates:Policies from regulators such as India's FSSAI compel the addition of thiamine to staple foods, creating guaranteed demand for food-grade ingredients.
- Nutraceutical Growth:An expanding consumer focus on preventative health and wellness, particularly in North America and Europe, fuels demand for thiamine in dietary supplements.
Market Restraints
- Raw Material Volatility:Production costs for chemically synthesized thiamine are directly exposed to price fluctuations in petrochemical-derived precursors, impacting manufacturer margins and price stability.
- Supply Chain Concentration:A heavy concentration of large-scale manufacturing in China creates potential supply disruption risks for global consumers due to geopolitical or domestic policy shifts.
- High Capital Costs:Establishing cGMP-compliant fermentation facilities for high-purity thiamine requires significant capital investment, creating a high barrier to entry for new competitors.
Strategic Opportunities
- Plant-Based Fortification:The expansion of plant-based meat and dairy alternatives presents an opportunity for fortifying these products with thiamine to match the nutritional profile of their animal-based counterparts.
- Specialized Formulations:Developing novel, more stable thiamine derivatives opens applications in targeted therapeutic areas and premium dietary supplements that offer enhanced bioavailability.
- Emerging Economies:Rising nutritional awareness in Southeast Asian and Latin American countries creates new growth frontiers for both fortified foods and consumer health products.
Industry Challenges
- Regulatory Navigation:Manufacturers face complexity in securing and maintaining approvals across different jurisdictions, each with unique standards like the US FDA, Europe's EFSA, and China's GB standards.
- Energy-Intensive Production:Both chemical synthesis and fermentation are energy-intensive processes, exposing producers to volatile energy costs and pressure to adopt more sustainable manufacturing practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thiamine Market |
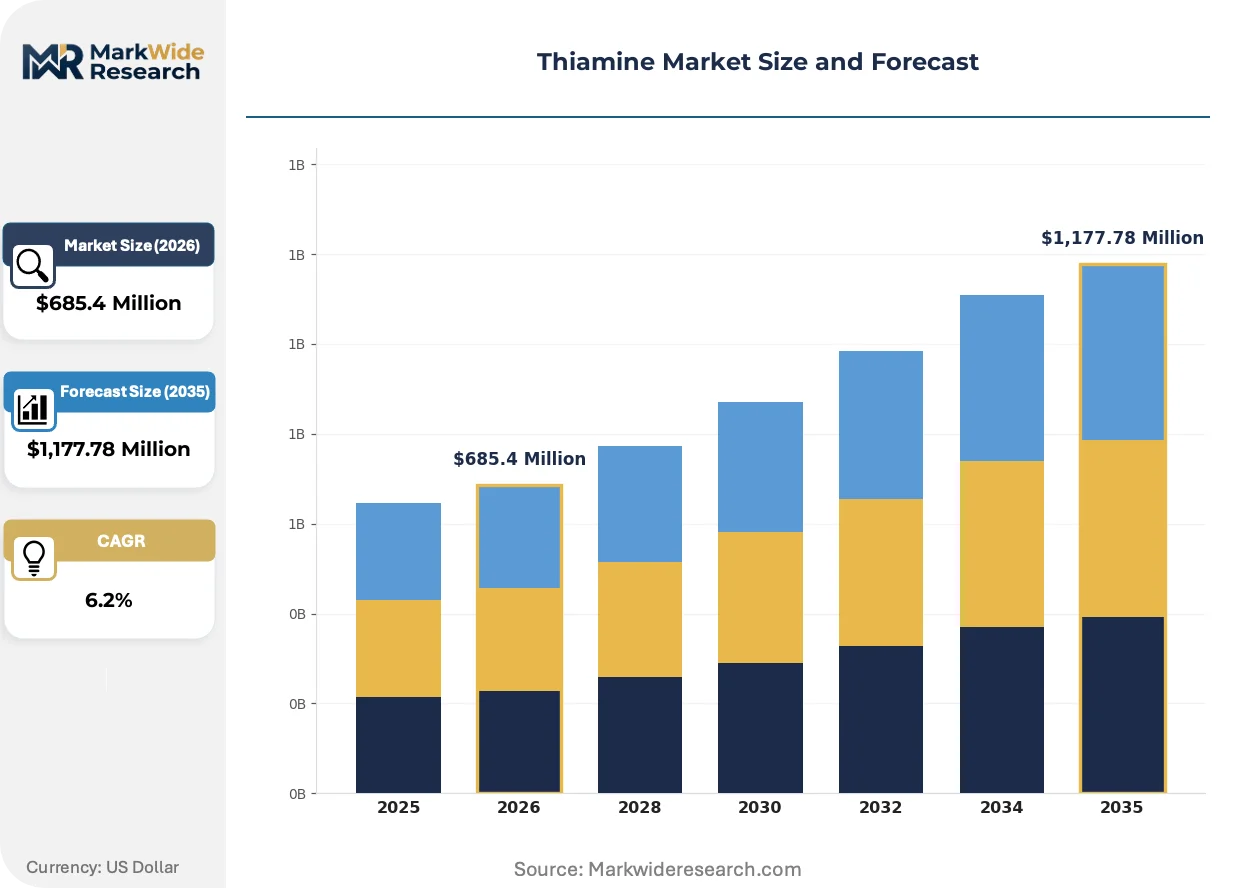
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Tablets, Capsules, Powder, Liquids Application: Nutritional Supplements, Pharmaceuticals, Feed Additives, Food Fortification Distribution Channel: Online Retail, Pharmacy Chains, Supermarkets, Specialty Stores End User: Health Enthusiasts, Patients, Livestock, Nutraceutical Companies |
| Companies Covered | Huazhong Pharmaceutical Co. Ltd., Xinfa Pharmaceutical Co. Ltd., BASF SE, The Nature's Bounty Co. Ltd., Jiangsu Yibang Pharmaceutical, Koninklijke DSM N.V., Jiangxi Tianxin Pharmaceutical Co. Ltd., Nutricost LLC, Zhejiang Medicine Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thiamine Market Strategic Shifts & Innovations
Process optimization and product specialization are simultaneously reshaping the thiamine market. Manufacturers are pursuing greater efficiency in commodity grades while also investing in advanced methods to meet demand for higher-purity, application-specific formulations.
Advanced fermentation technology allows for the direct biological synthesis of high-purity thiamine. Nutraceutical and pharmaceutical companies are rapidly adopting this source for premium products requiring stringent quality control. This bio-based method is displacing traditional chemical synthesis routes for high-value applications where purity and non-GMO certification are critical differentiators.
Food fortification regulations, such as those implemented by India’s FSSAI, are becoming a significant market driver. The policy mandates thiamine’s inclusion in staple goods, creating a predictable, large-scale demand channel independent of consumer choice. The food processing sector is most affected, now embedding fortification into its core production processes to achieve compliance.
Consumer demand for clean-label ingredients is altering procurement patterns in the human nutrition segment. This shift pressures suppliers to provide thiamine with full source transparency and certifications like non-GMO, moving beyond simple price-based competition. This trend is most prominent in the direct-to-consumer supplement markets of North America and Europe.
Thiamine Market Segmentation
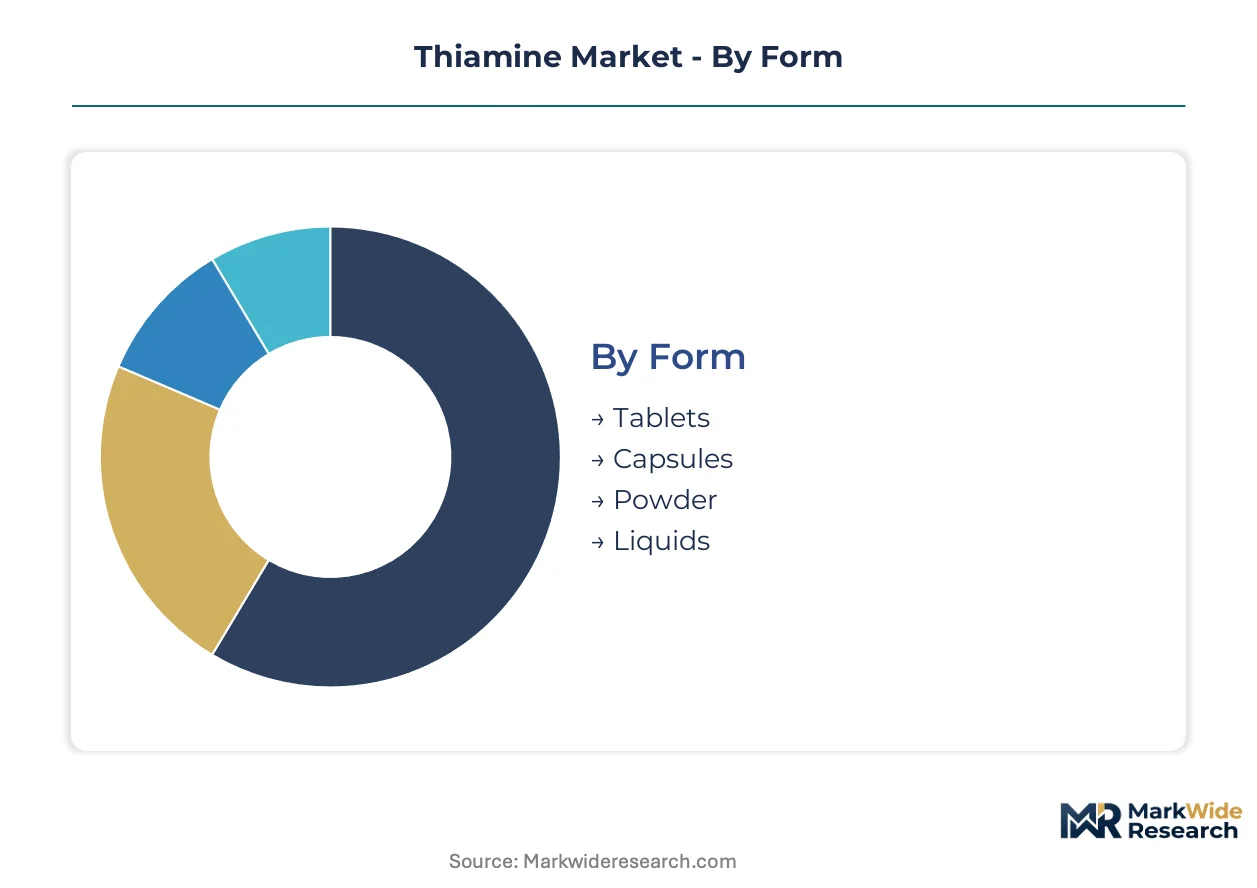
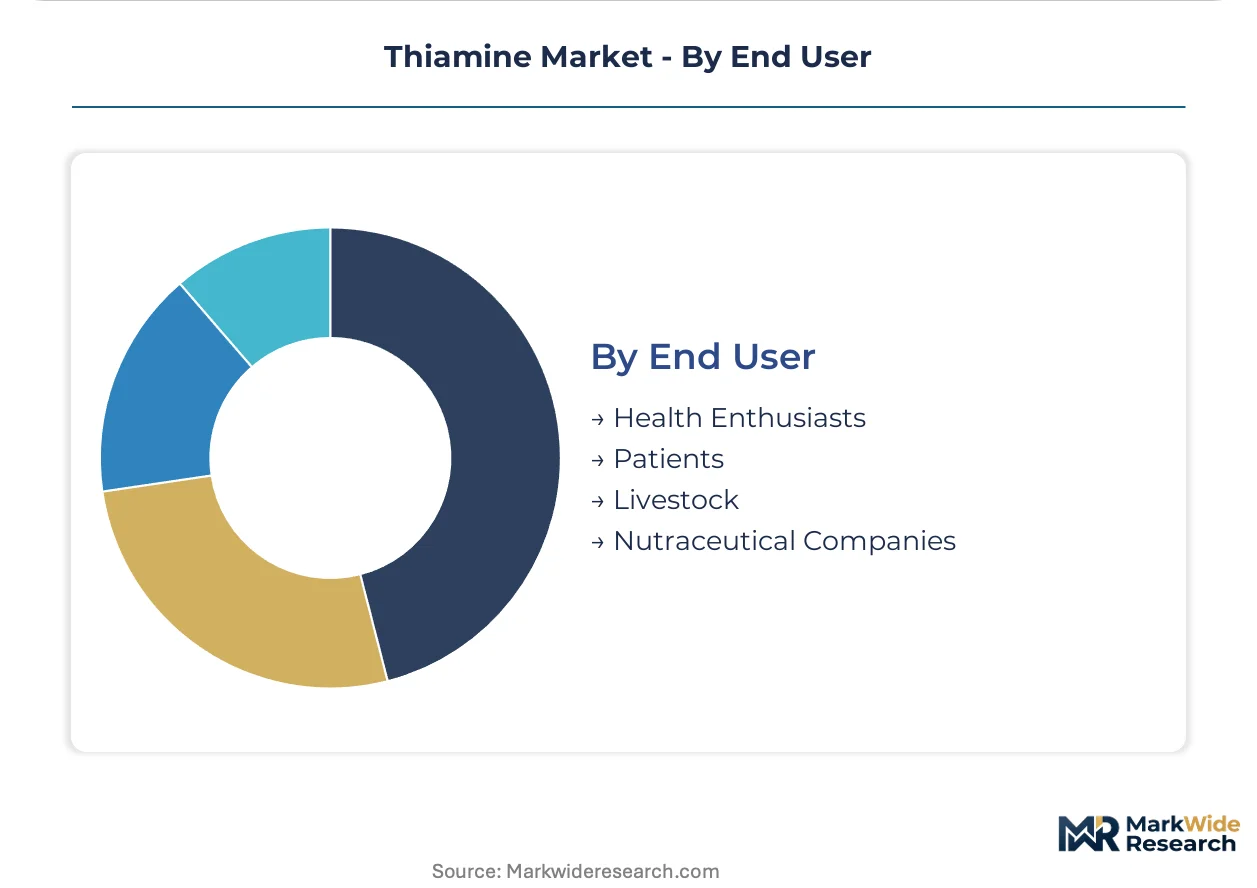
Thiamine market segmentation reveals distinct value propositions and competitive landscapes across various forms, applications, distribution channels, and end-user groups. Understanding these divisions is critical for manufacturers to align production capabilities with specific market demands and regulatory requirements.
Form:
Segments based on thiamine form face varying degrees of substitution pressure, particularly as advanced delivery systems emerge for human consumption. Different forms dictate stability, bioavailability, and ease of incorporation into diverse product matrices.
- Tablets:This solid oral dosage form typically contains thiamine hydrochloride or mononitrate, offering precise dosing and extended shelf life for nutritional supplements and pharmaceutical applications. Demand concentrates in consumer health markets across North America and Europe, driven by convenience and established regulatory approval pathways.
- Powder:Thiamine in powder form is highly versatile, essential for bulk applications in animal feed, food fortification, and compounding pharmacies due to its ease of mixing and cost-effectiveness. The feed additives sector in China and India drives significant volume, where large-scale integration into animal diets is paramount for growth.
- Capsules:Encapsulated thiamine provides a protected form, often preferred for specific dietary supplements targeting improved absorption or containing multiple active ingredients. These formulations cater to consumers seeking cleaner labels and higher purity standards in health-conscious markets.
- Liquids:Liquid thiamine formulations, including oral drops and injectable solutions, are used for rapid absorption or for individuals with swallowing difficulties. These are primarily found in specialized pharmaceutical and medical nutrition segments.
Powder retains volume leadership; Tablets hold the steepest expansion curve.
Application:
The application segments exhibit distinct demand patterns, reflecting varying regulatory oversight and consumer willingness to pay for specific health benefits or animal productivity gains. Each application requires different purity standards and formulation expertise.
- Feed Additives:This segment represents the largest volume consumption of thiamine, integrated into livestock and aquaculture diets to enhance animal growth, health, and productivity. Demand is concentrated in major agricultural economies like China and Brazil, where large-scale animal farming operations depend on consistent nutrient supplementation.
- Nutritional Supplements:Thiamine is a common ingredient in multivitamin formulations and standalone B1 supplements, catering to consumers focused on preventative health and specific dietary needs. This application commands higher price points, particularly in North America and Western European markets, driven by a strong wellness trend.
- Food Fortification:Government mandates, such as those from India's FSSAI, drive consistent demand for thiamine inclusion in staple foods like flour, rice, and cereals to address public health deficiencies. This segment ensures a baseline demand, independent of direct consumer purchasing decisions.
- Pharmaceuticals:Thiamine hydrochloride is used in medical treatments for thiamine deficiency (beriberi) and Wernicke-Korsakoff syndrome, available as oral tablets or injectable solutions. This application adheres to stringent pharmaceutical-grade purity standards and regulatory approvals from bodies like the US FDA.
Volume concentration sits with Feed Additives; Nutritional Supplements exhibit robust margin potential.
Distribution Channel:
Distribution channels for thiamine products reflect the end-user base and the regulatory environment governing product sales. Each channel offers different reach, customer engagement, and logistical requirements for manufacturers.
- Pharmacy Chains:This channel is critical for pharmaceutical-grade thiamine and many dietary supplements, benefiting from professional advice and consumer trust in health-related purchases. Pharmacy networks in Germany and France provide a reliable point of sale for medicinal thiamine.
- Online Retail:E-commerce platforms offer broad geographic reach and competitive pricing for nutritional supplements, attracting health-conscious consumers seeking convenience and product variety. This channel shows strong growth in the United States and the United Kingdom for direct-to-consumer sales.
- Supermarkets:Supermarkets serve as a primary outlet for fortified food products containing thiamine, integrated into daily grocery shopping routines for a mass consumer base. Major retail chains in India and Brazil distribute a significant volume of fortified staples.
- Specialty Stores:Health food stores and specialized nutrition shops cater to niche consumer segments seeking organic, non-GMO, or specific dietary supplements. These stores often provide a curated selection and personalized customer service.
Pharmacy Chains hold established market access; Online Retail is expanding its reach rapidly.
End User:
End-user segmentation highlights the diverse beneficiaries of thiamine, from individual consumers to agricultural industries. Each end-user group has specific requirements regarding product form, purity, and price sensitivity.
- Livestock:This end-user group, primarily poultry, swine, and cattle, consumes thiamine as a feed additive to support metabolic functions, improve feed conversion, and promote overall animal health. Large-scale farming operations in China and the US are major purchasers, prioritizing cost-effectiveness and volume.
- Health Enthusiasts:Individuals actively pursuing wellness and preventative health through dietary supplements represent a significant end-user segment for thiamine. These consumers in Canada and Australia often seek high-purity, certified products for energy metabolism and cognitive support.
- Patients:Individuals diagnosed with thiamine deficiencies or related medical conditions receive pharmaceutical-grade thiamine, often under medical supervision. This segment relies on prescriptions and hospital procurement for treatment.
- Nutraceutical Companies:These companies are B2B purchasers of bulk thiamine for incorporation into their own branded nutritional supplements and functional food products. They demand consistent quality and reliable supply chains from thiamine manufacturers.
Livestock drives overall market volume; Health Enthusiasts represent a premium-focused consumer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thiamine market demand displays varying elasticity across regions, with feed additive applications in agricultural economies exhibiting higher price sensitivity compared to premium nutritional supplements in developed markets. This regional divergence influences production strategies and distribution channels for thiamine manufacturers. Regulatory frameworks further shape regional market dynamics and access.
China
Demand for thiamine in China is primarily driven by its expansive animal nutrition and pharmaceutical industries. GB standards rigorously govern its use in feed additives and fortified foods, creating specific market access requirements. Production gravity centers on chemical manufacturing hubs like Zhejiang province, where large-volume output caters to Asia's sectors.
India
India's thiamine consumption is significantly bolstered by food fortification mandates, particularly FSSAI regulations compelling its inclusion in staple foods. This policy creates a predictable, large-scale demand channel for food-grade thiamine. Major food processing clusters in states like Maharashtra and Uttar Pradesh are embedding fortification into core production.
United States
The United States market for thiamine is largely influenced by consumer demand for nutritional supplements and pharmaceutical applications. US FDA purity standards dictate the quality requirements for both food and drug grades, ensuring product safety and efficacy. Key consumer health markets, particularly in California and New York, drive innovation in high-purity thiamine formulations.
Germany
Germany exhibits robust demand for pharmaceutical-grade thiamine and high-purity nutritional ingredients, reflecting its advanced healthcare sector. Europe's EFSA regulations ensure stringent quality and safety standards for thiamine used in food and supplements across the region. Biotech and pharmaceutical clusters in Bavaria and North Rhine-Westphalia focus on specialized thiamine derivatives.
Brazil
Brazil's thiamine market is heavily dominated by the feed additives sector, supporting its vast livestock and aquaculture industries. ANVISA regulations oversee the quality and safety of feed ingredients and nutritional products within the country. Large-scale farming operations in states like Mato Grosso and Rio Grande do Sul are major purchasers, prioritizing cost-effective thiamine volumes.
Thiamine Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the thiamine market's competitive structure. These large chemical manufacturers leverage extensive scale for commodity-grade production, often serving as foundational suppliers. The market features strategic archetypes including high-volume producers focusing on feed, specialized fermentation companies targeting premium human nutrition, and consumer-focused supplement brands. Capacity expansion and strategic partnerships remain dominant competitive moves, alongside portfolio diversification to capture different purity segments.
Among the established chemical manufacturers, Germany-based BASF SE exemplifies the archetype of a scale-driven producer, focusing on commodity-grade thiamine. Netherlands-headquartered Koninklijke DSM N.V. occupies a position as a specialist in high-purity nutritional ingredients, often utilizing advanced fermentation processes. China-based Zhejiang Medicine Co. Ltd. anchors the high-volume production segment, catering specifically to Asia's expansive feed and pharmaceutical sectors. These companies collectively illustrate the divergent strategies across the thiamine value chain.
| Leading Market Players |
|---|
| Huazhong Pharmaceutical Co. Ltd. |
| Xinfa Pharmaceutical Co. Ltd. |
| BASF SE |
| The Nature's Bounty Co. Ltd. |
| Jiangsu Yibang Pharmaceutical |
| Koninklijke DSM N.V. |
| Jiangxi Tianxin Pharmaceutical Co. Ltd. |
| Nutricost LLC |
| Zhejiang Medicine Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Days-of-inventory for commodity-grade thiamine, heavily influenced by large-scale Chinese production, directly impacts global spot pricing and manufacturer margins. This concentration creates a dynamic where supply-side shifts quickly reverberate through the value chain, affecting buyers from agricultural to pharmaceutical sectors.
Pricing Analysis
Specialized formulation support, often bundled with high-purity thiamine, drives significant lifetime value for producers targeting pharmaceutical and nutraceutical companies. The market employs a hybrid pricing model, combining commodity spot pricing for bulk feed-grade material with contract-based long-term offtake agreements for large agricultural buyers. Price differentiation stems from quality grade, such as pharmaceutical versus feed, and specific certifications like non-GMO status. Pricing softness runs through commodity grades due to high-volume production in China. Livestock companies are highly price-sensitive, while pharmaceutical and premium nutraceutical buyers prioritize consistent purity and regulatory compliance.
Supply Chain Analysis
Strategic stockpiling of thiamine is common among large-scale buyers, mitigating risks from concentrated production and volatile raw material prices. Geographic supply concentration heavily centers on China, with emerging production in India supporting domestic fortification mandates. The industry relies on petrochemical-derived precursors for chemical synthesis and specialized fermentation media for high-purity production. A primary supply chain risk involves potential export restrictions or policy shifts within China, impacting global availability. Distribution runs through direct channels for major feed and pharmaceutical companies, complemented by specialized ingredient distributors for smaller nutraceutical and food fortification clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thiamine market presents a fragmentation opportunity, driven by expanding consumer demand for clean-label ingredients and specialized nutritional supplements. This shift creates distinct niches for producers able to meet stringent quality and transparency requirements.
For Market Incumbents: Secure long-term supply agreements for petrochemical precursors to mitigate raw material volatility impacting chemical synthesis. Invest strategically in advanced fermentation capacity to counter the emerging threat from bio-based alternatives and capture premium human nutrition segments. Deepen vertical integration into specialized thiamine derivatives, leveraging existing scale to offer a broader product portfolio. Pursue rigorous certification investments, like non-GMO verification, to defend market share against specialized entrants.
For New Entrants and Emerging Players: Anchor in high-purity thiamine production via advanced fermentation, targeting the growing nutraceutical and pharmaceutical segments. The most penetrable segment lies within niche dietary supplements demanding rigorous certifications such as non-GMO or organic. Develop specialized formulations for the expanding plant-based food fortification market, aligning with consumer clean-label preferences. A key go-to-market angle involves strategic partnerships with innovative food brands seeking transparent and sustainably sourced ingredients.
For Investors and Strategic Acquirers: Long-term, this sits as a foundational ingredient play because thiamine is an essential nutrient with regulatory-driven demand in food fortification and animal health. Acquisition targets should focus on mid-cap specialists possessing proprietary fermentation technology or robust distribution networks in high-growth emerging economies. These firms offer differentiated value beyond commodity production. A critical signal to watch is an acceleration in M&A activity involving companies with strong clean-label certifications or novel derivative portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Fermentation Capacity | This move addresses rising demand for high-purity, non-GMO thiamine in nutraceuticals and pharmaceuticals. |
| Secure Long-Term Precursor Contracts | Mitigating raw material price volatility strengthens cost stability for chemically synthesized thiamine producers. |
| Invest in Regulatory Compliance Systems | Achieving US FDA and EFSA standards unlocks premium human nutrition and pharmaceutical market access. |
| Develop Specialized Thiamine Derivatives | Creating novel forms enhances bioavailability and opens applications in targeted therapeutic areas. |
| Establish Distribution in Southeast Asia | Tapping into rising nutritional awareness in countries like Vietnam and Indonesia expands consumer reach. |
Research Approach
The analysis maps thiamine's feed additive, food fortification, and pharmaceutical sub-sectors, each validated through extensive primary interviews with industry stakeholders. This included conversations with pharmaceutical R&D directors, feed formulation specialists, and food processing procurement managers. Secondary validation drew from US FDA filings, EFSA scientific opinions, and China's GB standards for feed additives. A rigorous bottom-up and top-down triangulation approach ensured data consistency and accuracy.
All forecast outputs were rigorously validated against external benchmarks, including historical market trends and macroeconomic indicators, to ensure internal consistency. The analytical framework modeled key segmentation dimensions: form, application, distribution channel, end user, and purity grade over the projection horizon. Compound annual growth rates were derived from historical data and projected growth catalysts. Key industry inputs included global livestock population trends and food fortification policy implementation.
Material uncertainties — including unforeseen geopolitical shifts or rapid technological disruptions — sit outside the modeled envelope, representing potential revision triggers. Forecasts reflect assumptions documented through primary and secondary research, acknowledging inherent market complexities. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Functional Polymer Market
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Asia-Pacific Amino Acids Market
Functional Chemicals
Ortho Phthalic Aldehyde Market
Functional Chemicals
Global Sodium Lignosulfonate Market
Functional Chemicals
Threonine Acids Market
Functional Chemicals
Citrulline Malate Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Tartrazine Market
Functional Chemicals
Global Potassium Citrate Market
Functional Chemicals
Acrylamide Monomer Market
Functional Chemicals
Europe Fumaric Acid Market
Functional Chemicals
Transfluthrin Market
Functional Chemicals
Thymolphthalein Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
L-Alanyl-L-Glutamine Market