
 Pump Over Tanks Market | 2026-2036
Pump Over Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Pump Over Tanks Market Analytics
Automated variable-frequency drive pumping is reshaping how wineries and chemical processors manage batch transfers and circulation operations. SPX FLOW leverages its hygienic equipment portfolio to sustain dominance in food-grade tank integration systems. Graco Inc. anchors its position through precision fluid handling technology for industrial coating and chemical applications. IDEX Corporation competes across multiple verticals with specialized pump architectures that navigate stringent material compatibility requirements.
Pump over tanks are sealed cylindrical vessels designed to receive, temporarily store, and redistribute liquids via integrated pumping mechanisms, typically constructed with 304 or 316 stainless steel walls rated for pressures between 15 and 150 psi depending on application. Their primary purpose centers on enabling controlled liquid circulation, transfer, and mixing across fermentation, chemical processing, and wastewater treatment operations. Steel vertical tanks lead the product type landscape due to structural efficiency in footprint-constrained facilities, while polyethylene horizontal configurations represent the fastest-expanding material-form pairing for agricultural and secondary containment applications. Double-wall tank demand concentrates around chemical storage end uses where secondary containment regulations mandate spill prevention redundancy, and mobile tank systems occupy niche but high-margin positions in construction and emergency response sectors.
EPA's Spill Prevention, Control, and Countermeasure rules govern aboveground storage capacity thresholds in the United States, forcing facility upgrades toward double-wall and leak-detection-integrated pump over tank systems. REACH and the EU Industrial Emissions Directive impose material traceability and chemical compatibility documentation burdens across European manufacturing and process industries. Australia's Work Health and Safety regulations, administered through state-level authorities, mandate pressure vessel certification for tank-pump integrated systems in industrial settings. Stakeholders must monitor evolving harmonization between ASME pressure vessel codes and emerging EU carbon border adjustment mechanisms that will reshape material sourcing decisions for tank fabricators serving export markets.
Market Dynamics
Variable-frequency drive integration is restructuring capital deployment patterns across fermentation and chemical processing facilities, compressing payback periods while elevating technical specifications for tank-pump integration. This shift is forcing fabricators to redesign vessel architectures around precision flow control rather than static capacity metrics.
Growth Catalysts
- REACH chemical compatibility mandates:European process industries must document material traceability for all wetted surfaces, accelerating replacement cycles for legacy carbon steel vessels with 316L stainless steel pump over tanks.
- Cap management automation:Wineries in California and Bordeaux are retrofitting fermentation cellars with automated pump-over systems to reduce labor intensity during peak harvest windows.
- Secondary containment retrofit wave:EPA SPCC enforcement actions against aboveground storage facilities are triggering upgrade demand for double-wall configurations with integrated leak detection.
Market Restraints
- Nickel alloy price volatility:316 stainless steel input costs fluctuate with Indonesian ore export policies, compressing fabrication margins and extending quotation validity periods.
- Specialized welder scarcity:ASME Section IX certified pressure vessel welders concentrate in Germany and the United States, creating production bottlenecks for export orders.
- Polyethylene substitution in agriculture:Horizontal polyethylene tanks capture secondary containment applications below 5,000 liters, displacing steel in cost-sensitive vineyard and orchard operations.
Strategic Opportunities
- Australian mining process water:Western Australia and Queensland operations require mobile pump over tank systems for remote site dewatering and slurry transfer, a segment with limited established supply.
- EU carbon border adjustment alignment:Tank fabricators sourcing European steel can position for preferential access as CBAM phases in, creating margin advantage over Asian competitors.
- IoT-enabled predictive maintenance:Integration of vibration and pressure sensors with cloud analytics platforms allows service contract bundling, shifting revenue from equipment to recurring monitoring fees.
Industry Challenges
- ASME U-stamp certification timelines:Third-party inspection backlogs at authorized agencies extend delivery schedules by 8-12 weeks for pressure-rated pump over tank systems.
- Legacy SCADA integration:Brownfield chemical plants require custom protocol bridges to connect modern variable-frequency drives with 1990s-era distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pump Over Tanks Market |
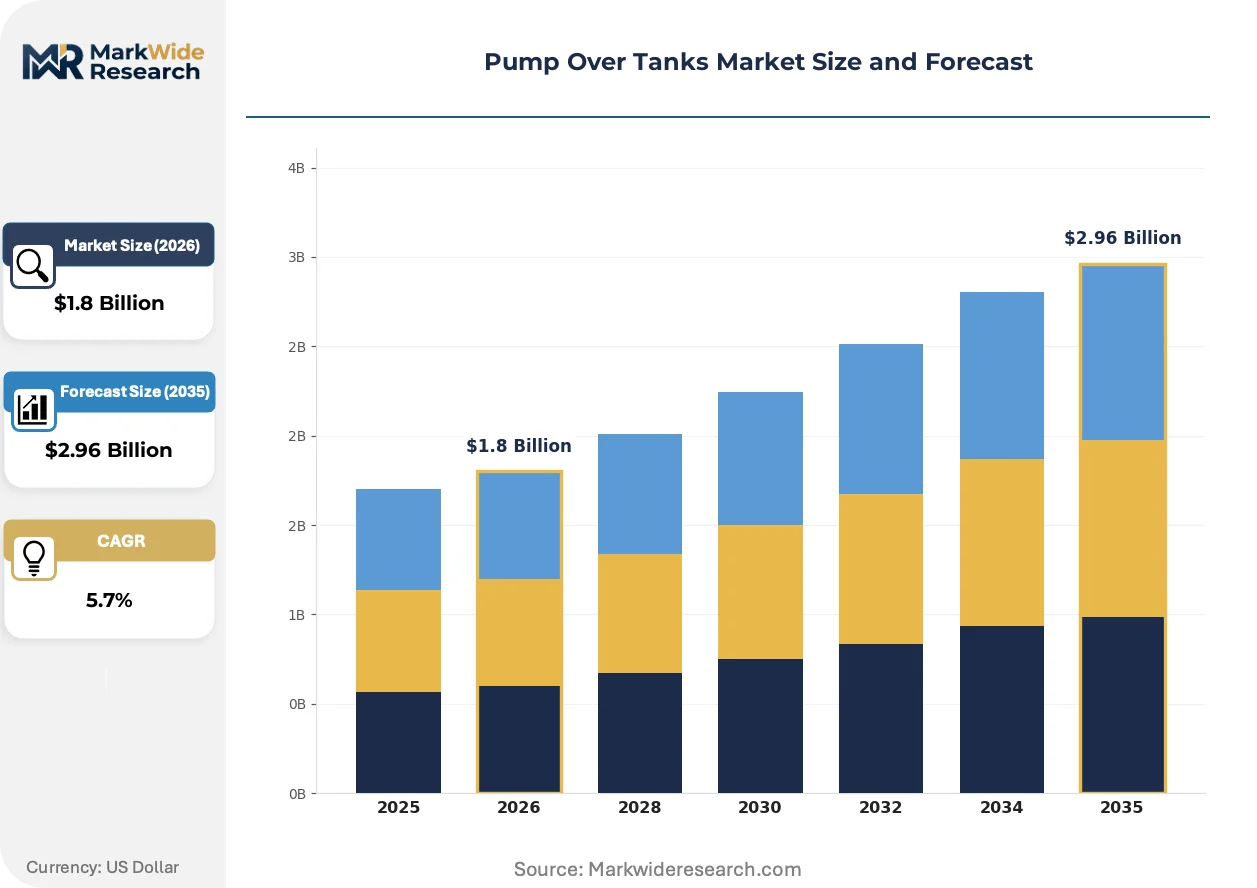
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Tanks, Horizontal Tanks, Double-Wall Tanks, Mobile Tanks Material: Steel, Polyethylene, Fiberglass, Concrete Application: Agriculture, Industrial Processes, Wastewater Management, Chemical Storage End User: Farms, Manufacturing Facilities, Municipalities, Construction Companies |
| Companies Covered | Criveller Group, Prettech Machinery Making, Sheras CO., Ltd., Inoxpa, Pumps&Systems, Pulsair Systems Inc., SPX FLOW, Graco Inc., IDEX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pump Over Tanks Market Evolving Landscape
Digital flow control architectures are displacing manual valve operations across batch processing environments, while regulatory documentation burdens intensify material certification requirements. These forces are compressing supplier qualification timelines and elevating technical service expectations.
Magnetic drive pump technology is migrating from high-purity pharmaceutical applications into corrosive chemical handling segments. Specialty chemical processors in Germany and the Netherlands are adopting sealless configurations to eliminate fugitive emissions. This migration is compressing demand for traditional packed gland pump over tank systems in hazardous fluid categories.
EPA's Spill Prevention, Control and Countermeasure rules now require qualified facility response plans for aggregate aboveground oil storage exceeding 1,320 gallons. Food processing and agricultural operations previously exempt from full SPCC compliance must now install secondary containment with professional engineer certification. Wineries and breweries in California are responding by consolidating storage into fewer, larger double-wall pump over tank installations to reduce plan complexity.
Buyer concentration among multi-site beverage conglomerates is compressing vendor qualification cycles and standardizing specifications across facilities. Procurement teams at major California and Australian wine groups now mandate API 650 compliance even for atmospheric fermentation tanks, previously outside scope. This specification creep is marginalizing regional fabricators lacking third-party certification capabilities, concentrating contract awards among ASME-certified suppliers with established beverage sector references.
Pump Over Tanks Market Segmentation
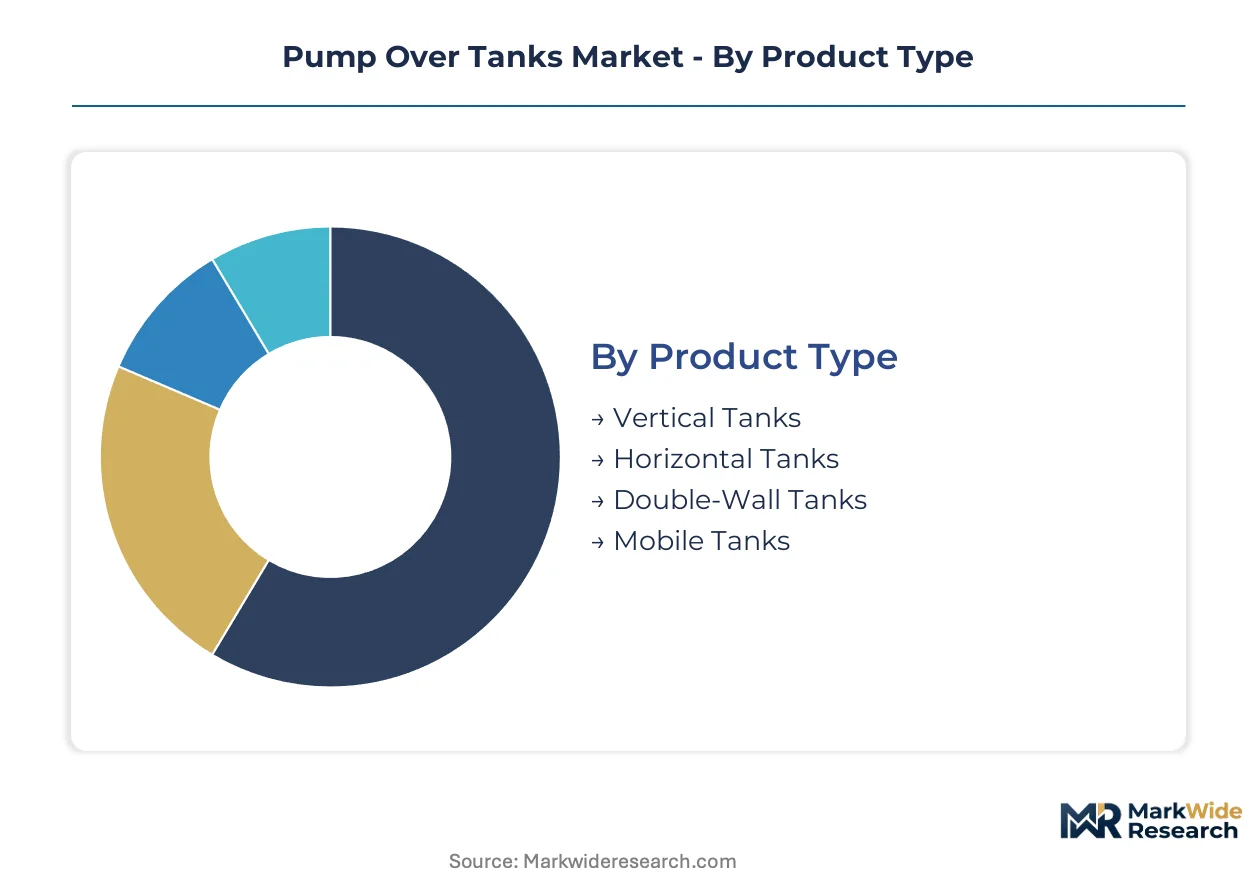
Pump over tank procurement patterns diverge sharply across material specifications, installation orientation, and regulatory exposure. Understanding these segment boundaries clarifies why stainless steel vertical configurations command premium positioning while polyethylene alternatives capture cost-sensitive agricultural volume.
Product Type:
Mature vertical and horizontal formats dominate installed base, while emerging double-wall and mobile configurations respond to tightening containment mandates and remote site logistics.
- Vertical Tanks:Cylindrical vessels with axis-oriented loading maximize floor space efficiency in footprint-constrained fermentation cellars and chemical processing facilities. Demand concentrates in California wineries and German chemical processors where ceiling height permits elevated fill levels and gravity-fed discharge.
- Horizontal Tanks:Low-profile configurations suit below-grade installation and transport trailer mounting for mobile field operations. Australian mining contractors in Western Australia specify horizontal formats for remote dewatering circuits where site access limits vertical clearance.
- Double-Wall Tanks:Integral secondary containment eliminates external bund requirements for EPA SPCC compliance.
- Mobile Tanks:Skid-mounted or trailer-integrated systems serve construction dewatering and emergency response deployment.
Vertical tanks retain volume leadership; mobile tanks hold the steepest expansion curve.
Material:
Cost tiers separate corrosion-resistant alloys from commodity polymers, with specification grade determining end-use access and certification burden.
- Steel:304 and 316 stainless grades deliver pressure-rated integrity for fermentation and chemical processing. REACH documentation requirements in Europe are accelerating 316L substitution for legacy carbon steel in process industries.
- Polyethylene:Rotationally molded HDPE and cross-linked formulations dominate agricultural containment below 5,000 liters. Bordeaux vineyard operators specify polyethylene for secondary containment of fertilizer and adjuvant storage where steel economics fail.
- Fiberglass:Corrosion-resistant FRP serves chemical storage with reduced weight versus steel.
- Concrete:Precast or cast-in-place construction anchors permanent municipal wastewater infrastructure.
Steel commands revenue concentration; polyethylene captures the fastest volume expansion in agricultural substitution.
Application:
Customer type and regulatory intensity shape specification requirements across process, containment, and environmental management functions.
- Agriculture:Vineyard pump-over operations and fertilizer containment drive demand for corrosion-resistant circulation systems. California Central Valley nut processors specify 316 stainless for pesticide handling compliance.
- Industrial Processes:Batch chemical manufacturing and coating operations require material traceability and pressure certification. German specialty chemical producers mandate ASME U-stamp compliance for integrated tank-pump systems.
- Wastewater Management:Municipal and industrial treatment facilities deploy pump over tanks for sludge transfer and equalization.
- Chemical Storage:Aboveground hazardous fluid containment triggers secondary containment and leak detection integration.
Industrial processes generate premium pricing; agriculture delivers the steepest volume trajectory.
End User:
Procurement sophistication and specification authority separate institutional buyers from fragmented owner-operators.
- Farms:Vineyard and orchard operators prioritize harvest-season reliability and cap management automation. Napa Valley wine groups consolidate procurement across multiple cellar sites to standardize on ASME-certified fabricators.
- Manufacturing Facilities:Chemical processors and food manufacturers demand documentation packages for regulatory audit trails. Dutch chemical clusters specify sealless magnetic drive integration to eliminate fugitive emissions exposure.
- Municipalities:Public works departments specify concrete and steel for permanent wastewater infrastructure with 30-year design life.
- Construction Companies:Dewatering and remediation contractors rent or purchase mobile systems for project-specific deployment.
Manufacturing facilities anchor premium demand; construction companies drive mobile segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in pump over tank fabrication favor established steel-producing economies, with German and U.S. fabricators supplying ASME-certified systems to wine regions lacking domestic pressure vessel capacity. Net importers concentrate in premium wine zones where fermentation infrastructure outpaces local metalworking capability.
United States
California's Central Valley and Napa Valley wine clusters drive stainless steel vertical tank procurement for cap management automation. EPA Spill Prevention, Control and Countermeasure rules mandate secondary containment for aboveground storage exceeding 1,320 gallons, forcing cellar consolidation into double-wall configurations. Texas Gulf Coast chemical processors anchor industrial demand for pressure-rated integrated systems.
Germany
Specialty chemical producers in the Rhine-Ruhr and Bavarian chemical clusters specify ASME U-stamp compliance for integrated tank-pump architectures. REACH documentation requirements accelerate 316L stainless substitution for legacy carbon steel vessels. Stuttgart-area fabricators leverage proximity to automotive coating operations to supply precision circulation systems.
Australia
Western Australian mining contractors in the Pilbara and Goldfields regions deploy mobile horizontal pump over tanks for remote dewatering circuits. Queensland coal seam gas operations require slurry transfer systems in footprint-constrained well pads. Work Health and Safety regulations mandate pressure vessel certification for tank-pump integration in industrial settings.
France
Bordeaux vineyard operators retrofit fermentation cellars with automated pump-over systems to compress harvest labor windows. Polyethylene secondary containment vessels capture fertilizer and adjuvant storage below 5,000 liters where steel economics fail. The country's national environmental regulator enforces chemical storage directives tightening tank integrity requirements.
China
Shandong Peninsula and Yangtze River Delta fabricators supply cost-competitive 304 stainless configurations for domestic food processing. Export-oriented producers face margin pressure from EU carbon border adjustment mechanisms phasing in during the forecast window. Local chemical processors increasingly specify magnetic drive pump integration to eliminate fugitive emissions.
Pump Over Tanks Market Competitive Landscape
On the supply side, the industry is bifurcated between ASME-certified specialists serving regulated process industries and regional fabricators competing on agricultural volume. Tiering separates documentation-heavy chemical sector suppliers from vineyard-focused cellar equipment providers. Two strategic archetypes dominate: integrated pump-tank system architects and component-specialist assemblers. Competitive moves concentrate on certification acquisition for market access and IoT-enabled service bundling to shift revenue toward recurring monitoring contracts.
Among the named participants, SPX FLOW and Graco Inc. occupy positions within the integrated systems tier, while IDEX Corporation exemplifies the diversified fluid handling specialist archetype. Prettech Machinery Making represents the Asia-Pacific fabrication base serving cost-sensitive agricultural procurement. Criveller Group and Inoxpa anchor the wine industry vertical with cellar-focused equipment portfolios. Pulsair Systems Inc. and Pumps&Systems sit within the mixing and agitation technology layer, supplying components to tank integrators rather than complete systems. Sheras CO., Ltd. and Prettech Machinery Making reflect the geographic diversification of stainless steel supply chains toward ore-proximate manufacturing zones.
| Leading Market Players |
|---|
| Criveller Group |
| Prettech Machinery Making |
| Sheras CO., Ltd. |
| Inoxpa |
| Pumps&Systems |
| Pulsair Systems Inc. |
| SPX FLOW |
| Graco Inc. |
| IDEX Corporation |
| Others |
Value Network & Pricing Analysis
Nickel alloy price volatility tied to Indonesian ore export policies determines both the spread between 304 and 316L stainless steel tank tiers and the geographic shape of fabrication sourcing. Fabricators in ore-proximate zones capture margin advantage while distant producers absorb quotation validity extensions.
Pricing Analysis
The technology-generation pricing gap separates legacy packed gland pump systems from sealless magnetic drive configurations and emerging IoT-enabled predictive maintenance bundles. Pricing stratifies across ASME U-stamp certified premium tiers, standard 304 stainless configurations, and economy polyethylene alternatives for agricultural containment. Price differentiation hinges on certification grade and geographic delivery cost, with California wine groups consolidating procurement to extract volume leverage. Cost compression in standard steel tiers intensifies because Indonesian nickel policy swings feed directly into 316L input costs. Agricultural vineyard operators exhibit highest price sensitivity, while German chemical processors prioritize material traceability documentation over unit economics.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk as carbon border adjustment mechanisms phase in. Fabrication concentrates in China, Germany, and the United States, with Shandong Peninsula mills feeding cost-competitive 304 stainless and Stuttgart-area specialists serving precision chemical sector demand. Raw material dependencies rest on Indonesian nickel ore, Chinese steel slab, and specialized ASME-certified welding consumables. Single-source vulnerability concentrates in certified pressure vessel welder pools, with ASME Section IX qualified labor clustering in Germany and the United States. Distribution runs through direct OEM relationships for integrated tank-pump systems and regional equipment distributors for replacement agricultural vessels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pump over tanks market sits in early-cycle expansion as cap management automation penetrates harvest-intensive wine regions and EPA spill prevention enforcement triggers retrofit waves. Regulatory documentation burdens and variable-frequency drive integration create durable specification upgrading.
For Market Incumbents: Pre-empt polyethylene substitution in agricultural segments by embedding IoT sensor packages that shift revenue toward recurring monitoring contracts. Acquire ASME U-stamp certification capabilities in Asia-Pacific zones to defend against Chinese fabricators leveraging ore proximity. Magnetic drive technology migration from pharmaceutical into chemical applications represents the priority substitution threat demanding sealless pump integration investment.
For New Entrants and Emerging Players: Western Australian mining contractors in the Pilbara represent the most penetrable entry point, with remote dewatering circuits demanding mobile horizontal configurations where established supply remains thin. Queensland coal seam gas slurry transfer operations offer secondary white-space targeting. A rental-plus-service contract go-to-market angle bypasses capital procurement friction at resource extraction sites.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors ASME-certified specialists with beverage sector reference portfolios. Long-term viability over the coming decade rests on documentation-heavy regulatory compliance capabilities rather than pure fabrication scale. Acquisition targets should demonstrate established EPA SPCC plan engineering relationships and REACH material traceability systems. The signal to watch is buyer concentration among multi-site California and Australian wine groups mandating API 650 compliance for atmospheric tanks.
| Strategic Initiative | Industry Significance |
|---|---|
| ASME U-Stamp Certification Acquisition | Unlocks regulated chemical sector procurement in Germany and Texas Gulf Coast clusters. |
| IoT Sensor Integration for Predictive Maintenance | Enables recurring service revenue bundling with SPX FLOW and Graco Inc. reference architectures. |
| Backward Integration into Nickel Alloy Sourcing | Insulates margin from Indonesian ore policy volatility for 316L stainless production. |
| Joint Venture with Australian Mining Contractors | Establishes mobile tank rental footprint in Pilbara dewatering circuits. |
| REACH Documentation System Implementation | Secures preferential positioning as EU carbon border adjustments reshape material sourcing. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with tank fabricator technical directors, winery cellar managers, chemical plant procurement leads, and aftermarket service heads; and secondary validation through customs trade records, ASME certification agency filings, EPA SPCC enforcement actions, and REACH compliance databases. Bottom-up triangulation across vessel shipment volumes and top-down reconciliation against end-use capital expenditure patterns anchored market sizing. Primary fieldwork concentrated in California wine clusters, German chemical corridors, and Western Australian mining regions.
Forecast inputs considered product type segmentation across vertical, horizontal, double-wall, and mobile configurations; material grade tiers from polyethylene through 316L stainless; and application intensity across fermentation automation, chemical processing, and remote dewatering. CAGRs were derived from regression against regulatory compliance retrofit cycles and variable-frequency drive adoption curves. Industry-specific inputs included nickel alloy price volatility indices and ASME certification backlog durations.
Macroeconomic conditions sit as an overlay; deviation in construction activity, mining capital deployment, or agricultural commodity prices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and welding labor pool expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
United States Positive Displacement Pumps Market
Pumps and Control Devices
Hydrogen Circulation Pump Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Air Compressor Controller Market
Pumps and Control Devices
Vane Pump Market
Pumps and Control Devices
Southeast Asia Industrial Pumps Market
Pumps and Control Devices
Pressure Pumping Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Asia-Pacific Peristaltic Pumps Market
Pumps and Control Devices
Fluid Power Equipment Market
Pumps and Control Devices
Condensate Pump Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
Flow Back Equipment Market
Pumps and Control Devices
Mixed Flow Pump Market
Pumps and Control Devices
Centrifugal Water Pump Market