
 Email Deliverability Tools Market | 2026-2036
Email Deliverability Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Email Deliverability Tools Market Foresight
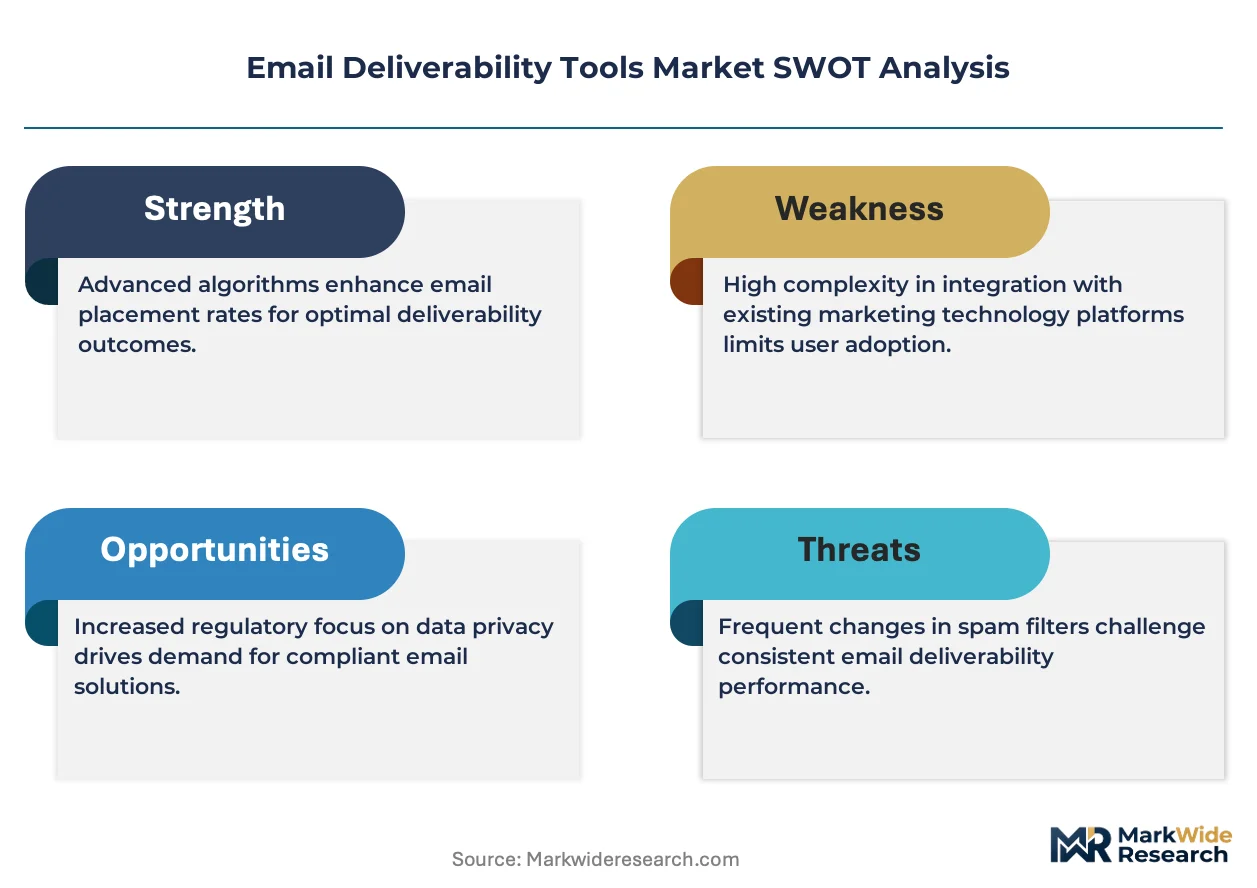
Subscription-based deliverability monitoring is broadening what vendors monetize beyond one-time list cleaning. Everest by Validity anchors the high-end enterprise segment through deep integration with CRM workflows. Folderly competes by specializing in Google Workspace and Microsoft 365 compatibility layers. Warmup Inbox extends its position in the self-serve tier with automated reputation building for cold outreach sequences.
Email deliverability tools encompass software platforms that authenticate sender identity, score content against spam filters, and optimize inbox placement rates through technical protocol enforcement. These systems typically operate across SPF, DKIM, and DMARC authentication layers while monitoring sender reputation scores and blacklist status in real time. Cloud-based deployment captures the largest addressable base due to frictionless onboarding and API-native architecture. List verification solutions command premium pricing because bad data directly erodes sender reputation scores. Domain authentication features are maturing fastest as Google and Yahoo mandate stricter baseline requirements.
The Federal Communications Commission enforces anti-spam statutes that shape US sender liability frameworks, while the EU AI Act and GDPR impose algorithmic transparency and consent documentation burdens on European email programs. California's CCPA amplifies data deletion requirements for any sender processing consumer inboxes tied to state residents. Stakeholders must weigh authentication protocol investments against the operational cost of deliverability failures that now trigger direct revenue loss.
Market Dynamics
Google and Yahoo's 2024 bulk sender authentication mandates are compressing infrastructure upgrade cycles, forcing mid-market senders toward automated DMARC enforcement platforms that previously served only enterprise accounts.
Growth Catalysts
- EU AI Act compliance layers:European senders now require algorithmic transparency documentation for automated email sequences, creating demand for audit-ready deliverability stacks that integrate consent logging with reputation monitoring.
- E-commerce cart recovery monetization:Online retailers measure inbox placement against abandoned-cart revenue recovery, directly tying deliverability tool ROI to transaction volume rather than open rates alone.
- SPF flattening automation:Technical teams at SaaS companies are adopting dynamic DNS management tools that eliminate lookup limit failures during high-volume promotional sends.
Market Restraints
- IPv4 warming cost escalation:Dedicated IP provisioning for new senders requires 4-6 week reputation incubation periods, inflating customer acquisition costs for self-serve platform tiers.
- Blacklist remediation concentration:Three major reputation data aggregators control 80% of filtering decisions, creating single-point-of-failure risk for senders dependent on specific list hygiene vendors.
- TLS certificate management fragmentation:Multi-domain email programs face operational drag from certificate renewal cycles that interrupt authenticated sending across sub-brands.
Strategic Opportunities
- German B2B outreach specialization:The country's strict anti-cold-email enforcement under UWG and GDPR creates premium demand for consent-verified infrastructure that pre-screens business contact permissibility.
- API-native ESP convergence:Headless email service providers are unbundling deliverability monitoring from campaign management, opening white-label integration slots for specialized reputation tools.
- California CCPA deletion orchestration:Automated suppression list synchronization across fragmented martech stacks addresses the 45-day deletion mandate for consumer email data.
Industry Challenges
- DMARC policy escalation expertise gap:Engineering teams lack DNSSEC and aggregate report parsing capabilities needed to progress from p=none to p=reject without service interruption.
- Cross-platform reputation portability:Senders switching between Mailgun, SendGrid, and Amazon SES cannot transfer IP warming history, forcing repeated infrastructure investment.
- BIMI certificate authority bottlenecks:Mark certificate issuance requires VMC validation that currently processes through two approved providers, creating 6-8 week deployment delays for brand logo inbox display.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Email Deliverability Tools Market |
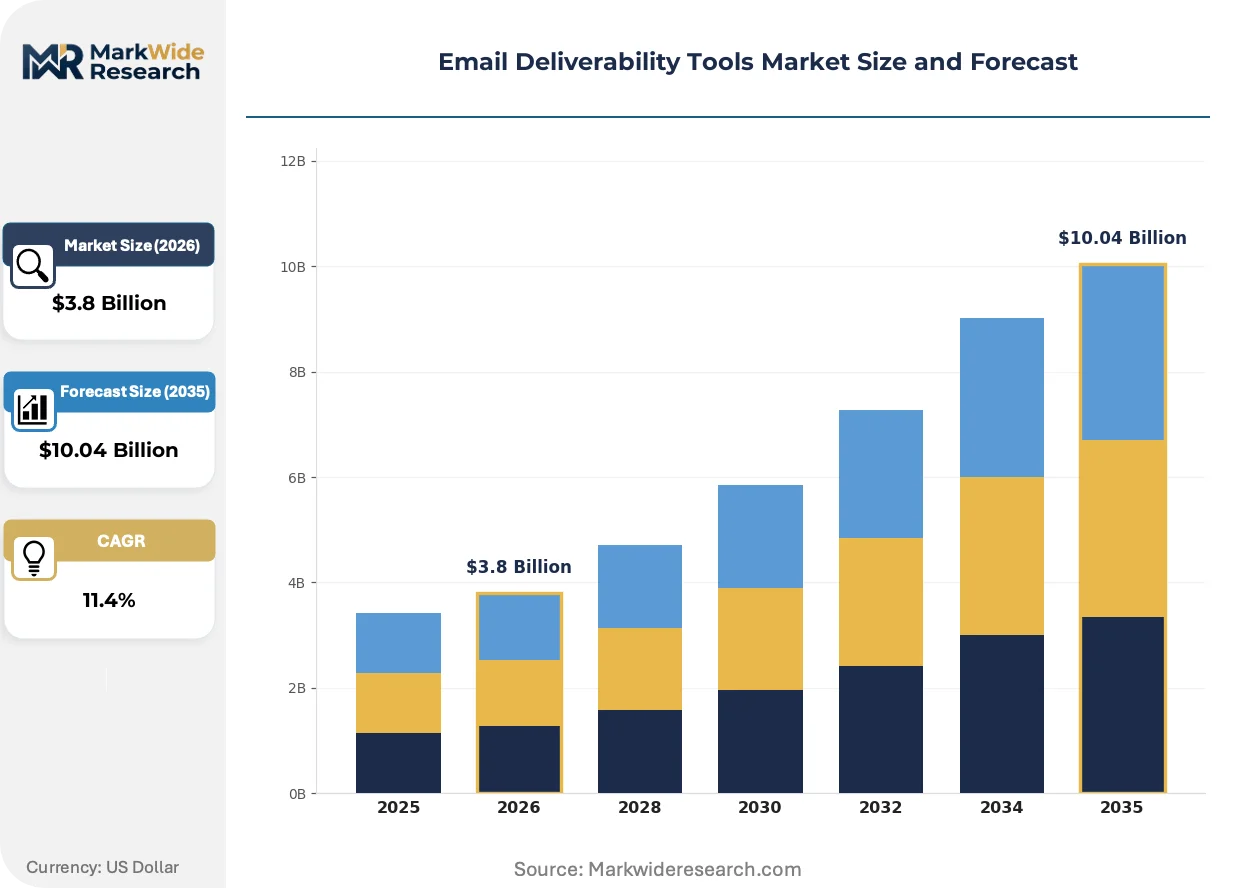
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feature: A/B Testing, Analytics, Domain Authentication, Spam Testing Customer Type: Small Businesses, Enterprises, Marketing Agencies, E-commerce Deployment: Cloud-Based, On-Premise, Hybrid, Multi-Tenant Solution: Email Monitoring, Warm-Up Services, List Verification, Inbox Placement |
| Companies Covered | Amplemarket, Folderly, GlockApps, ZeroBounce, Mailgun Optimize, Everest by Validity, MxToolbox, TrulyInbox, Warmup Inbox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Email Deliverability Tools Market Shifts & Advancements
Distributed ledger verification protocols are emerging as alternatives to centralized reputation databases, while machine learning content scoring compresses the feedback loop between send and filter classification. These shifts are redrawing vendor competitive boundaries.
Blockchain-based sender reputation registries are decentralizing trust establishment away from incumbent blacklist operators. High-volume cold outreach agencies in the US and UK are piloting these systems to bypass traditional warming periods. The architecture is decentralizing IP reputation ownership toward domain-bound cryptographic credentials that travel with the sender across infrastructure providers.
EU AI Act algorithmic transparency requirements are mandating explainable scoring for automated email classification systems. European senders must now document how engagement predictions influence send-time optimization and content personalization. Marketing automation platforms serving Germany and France are retrofitting audit trails that expose model decision trees to regulatory inspection.
Revenue-based pricing models are displacing seat-based subscriptions among mid-market SaaS companies. Deliverability vendors now index fees to recovered cart value or pipeline influenced rather than message volume. This shift concentrates fastest among D2C brands in California and New York where attribution infrastructure already connects email engagement to purchase events.
Email Deliverability Tools Market Segmentation
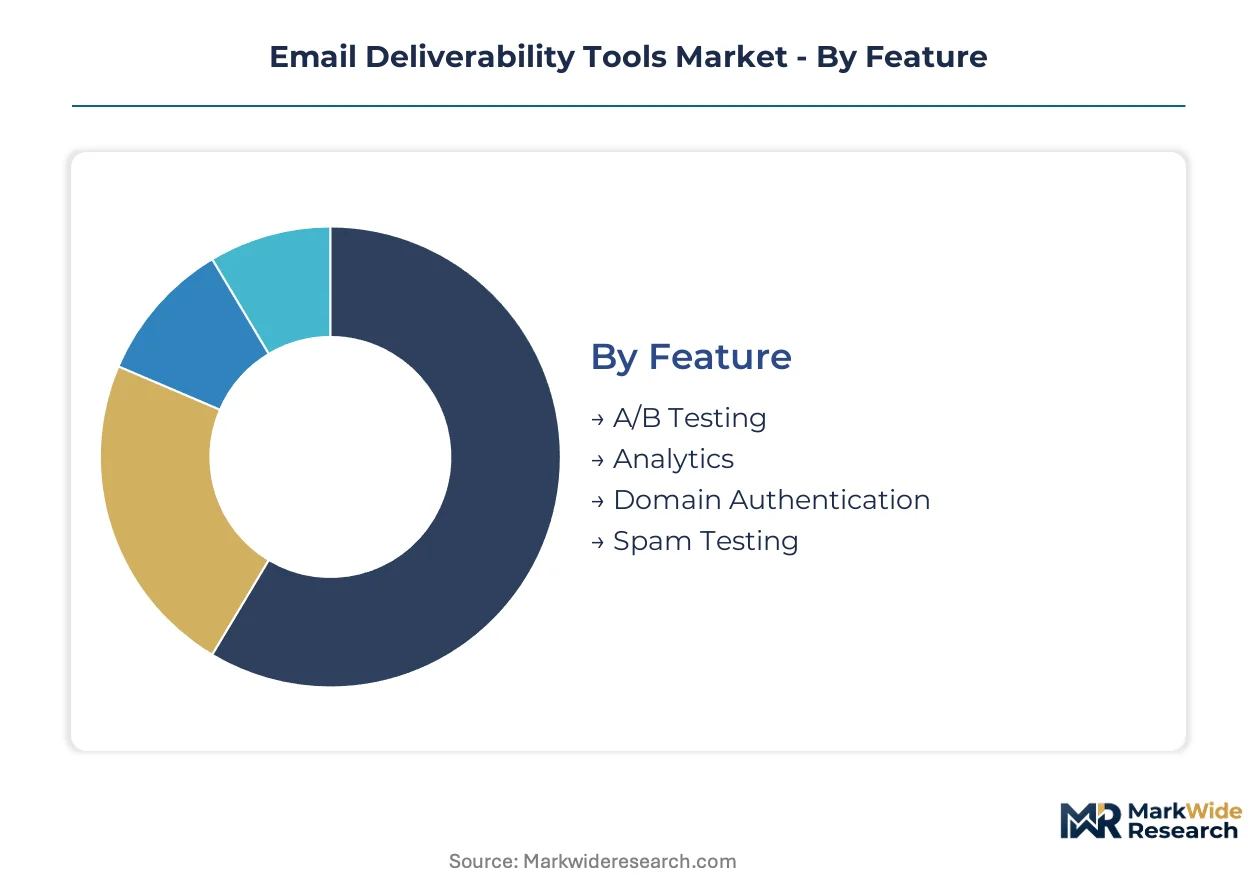
Deliverability tool buyers segment sharply by technical sophistication and infrastructure control requirements. Authentication protocol enforcement demands vary dramatically across self-serve platforms versus enterprise orchestration layers.
Feature:
Technical capability modules define pricing tiers and integration complexity for procurement teams evaluating vendor stacks.
- Domain Authentication:SPF, DKIM, and DMARC protocol enforcement tools anchor enterprise procurement decisions. Financial services firms in Germany and healthcare systems in the US drive concentration here due to regulatory audit requirements.
- Analytics:Real-time reputation scoring dashboards aggregate blacklist status, engagement velocity, and inbox placement rates. E-commerce platforms in California and New York index vendor selection to recovered cart value attribution.
- Spam Testing:Pre-send content scoring against Bayesian filters and image-to-text ratios.
- A/B Testing:Subject line and send-time optimization modules for campaign performance iteration.
Domain Authentication leads on scale; Analytics leads on momentum.
Customer Type:
Organizational scale dictates contract structure, with seat-based pricing giving way to revenue-indexed models among digitally native buyers.
- Enterprises:Multi-brand conglomerates require centralized DMARC policy management across subsidiary domains. German automotive suppliers and US pharmaceutical manufacturers concentrate demand here due to supply chain communication complexity.
- E-commerce:Direct-to-consumer retailers measure tool ROI against abandoned-cart recovery rates. Subscription beauty brands in California and flash-sale platforms in New York represent the steepest expansion trajectory.
- Marketing Agencies:Multi-client reputation monitoring with white-label reporting capabilities.
- Small Businesses:Self-serve onboarding with pre-configured authentication templates.
Enterprises dominate current vendor revenue; E-commerce is climbing the fastest.
Deployment:
Infrastructure location choices reflect data sovereignty requirements and existing cloud architecture investments.
- Cloud-Based:API-native SaaS delivery eliminates provisioning latency and enables automatic protocol updates. Mid-market SaaS companies in the UK and digital publishers in Australia prefer this model for frictionless ESP switching.
- Hybrid:Sensitive authentication keys remain on-premise while reputation monitoring leverages external analytics. German financial institutions and Swiss pharmaceutical companies drive this architecture due to FINMA and BaFin data localization guidance.
- On-Premise:Air-gapped environments for defense contractors and government agencies.
- Multi-Tenant:Shared infrastructure with logical isolation for agency client separation.
Cloud-Based captures volume concentration; Hybrid is gaining share fastest among regulated sectors.
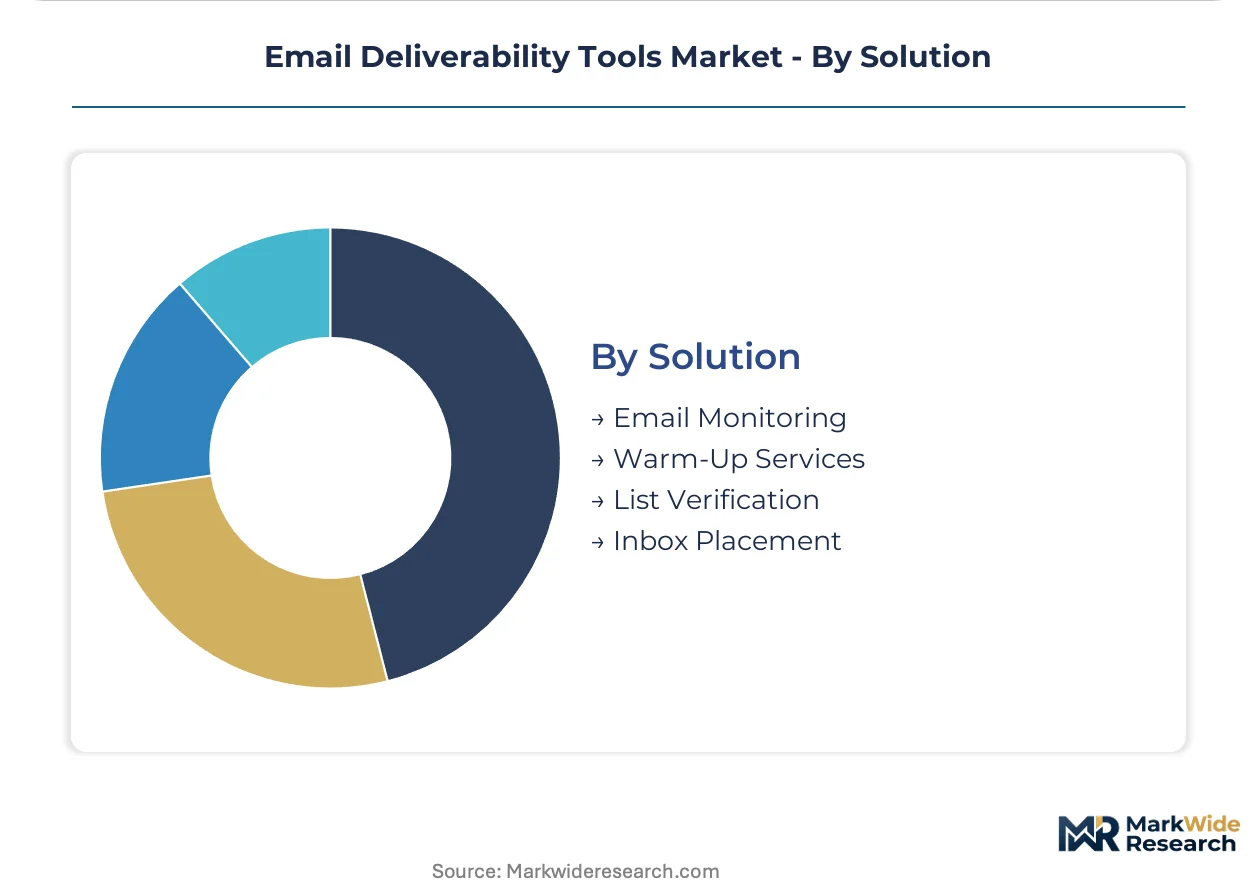
Solution:
Functional modules map to distinct stages of the deliverability lifecycle from list acquisition to inbox placement verification.
- List Verification:Real-time email validation and disposable domain detection protect sender reputation scores. Cold outreach agencies in the US and UK concentrate procurement here to minimize hard bounce rates.
- Inbox Placement:Seed list testing across Gmail, Outlook, and Yahoo folders with provider-specific filtering intelligence. Enterprise B2B software vendors in Germany and France prioritize this capability for sales development representative sequence performance.
- Email Monitoring:Continuous reputation tracking with blacklist alert automation.
- Warm-Up Services:Gradual volume ramping for new dedicated IP addresses.
List Verification leads on scale; Inbox Placement leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compliance cost differentials are pushing deliverability infrastructure investment toward jurisdictions with clearer regulatory frameworks, while senders in high-penalty markets outsource authentication management to specialized vendors.
United States
E-commerce cart recovery platforms and cold outreach agencies drive procurement volume. The FCC enforces anti-spam statutes that shape sender liability frameworks, with California's CCPA amplifying data deletion requirements. San Francisco and New York Metro clusters concentrate D2C brands deploying revenue-indexed deliverability pricing.
Germany
B2B software vendors and automotive suppliers demand consent-verified infrastructure for sales development sequences. The EU AI Act and GDPR impose algorithmic transparency and documentation burdens on European email programs. Berlin and Munich host the steepest concentration of DMARC policy management deployments.
United Kingdom
Mid-market SaaS companies prefer API-native SaaS delivery for frictionless ESP switching. The UK Information Commissioner's Office enforces data protection standards post-Brexit that largely mirror GDPR. London's fintech cluster drives hybrid deployment adoption for sensitive authentication key management.
France
Marketing automation platforms serving enterprise accounts retrofit audit trails for regulatory inspection. The CNIL enforces consent documentation requirements with particular attention to automated email classification systems. Paris-based luxury brands pilot BIMI certificate deployment for brand logo inbox display.
Australia
Digital publishers favor cloud-based deployment for automatic protocol updates across high-volume content distribution. The Australian Communications and Media Authority administers spam regulations with emphasis on unsubscribe mechanism enforcement. Sydney and Melbourne clusters concentrate list verification procurement for cold outreach agencies.
Email Deliverability Tools Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise orchestration layers consolidating around integrated authentication suites while self-serve tiers fragment across point solutions. The vendor base organizes into three strategic archetypes: full-stack enterprise platforms, workspace-native specialists, and automated warming services. Dominant competitive moves include API-native ESP convergence partnerships and white-label integration slot expansion.
Within the enterprise platform tier, Everest by Validity and Mailgun Optimize represent the integrated-authentication archetype, anchoring high-end procurement decisions through deep CRM workflow integration. Folderly occupies a position among workspace-native specialists, while Warmup Inbox exemplifies the automated reputation-building segment for cold outreach sequences.
| Leading Market Players |
|---|
| Amplemarket |
| Folderly |
| GlockApps |
| ZeroBounce |
| Mailgun Optimize |
| Everest by Validity |
| MxToolbox |
| TrulyInbox |
| Warmup Inbox |
| Others |
Supply & Pricing Matrix
Cloud infrastructure spot pricing indices cascade through email deliverability tool cost structures, compressing margins for API-native vendors while amplifying pricing power for authentication protocol specialists with captive data center capacity.
Pricing Analysis
Direct-to-OEM channel discounts of 15-25 points anchor enterprise procurement negotiations, while self-serve tiers retain list-price integrity. Pricing stratifies across premium DMARC orchestration, standard reputation monitoring, and economy list-verification tiers, with certification grade and volume scale as primary differentiation levers. Cost compression in the mid-market tier intensifies because Google and Yahoo authentication mandates commoditized baseline SPF/DKIM features. E-commerce platforms exhibit highest price sensitivity due to revenue-indexed fee structures, whereas German automotive suppliers show lowest sensitivity given regulatory audit requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand, while API marketplaces and ESP integration partnerships serve the long tail. Engineering talent concentrates in the United States, Germany, and India, with reputation data feeds anchored in the United States and Ireland. The supply chain draws from cloud compute instances, TLS certificate authority services, and seed list provider networks. Single-source vulnerability in VMC certificate issuance creates deployment bottlenecks for BIMI logo display. Distribution runs through SaaS marketplaces, direct sales teams, and white-label ESP integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into durable demand, with Google and Yahoo's 2024 bulk sender authentication mandates forcing infrastructure upgrade cycles across mid-market accounts.
For Market Incumbents: Deploy API-native ESP convergence partnerships to lock white-label integration slots before headless email providers consolidate their vendor panels. Incumbents must deepen DMARC policy escalation expertise through targeted hiring in DNSSEC engineering, defending against automated warming services encroaching on enterprise warming contracts. The threat of blockchain-based reputation registries piloted by cold outreach agencies demands proactive pilot participation to influence protocol standards. For New Entrants and Emerging Players: AI-powered content scoring algorithms offer entry leverage against incumbents reliant on legacy Bayesian filter matching. New entrants should target German B2B outreach specialization, where UWG and GDPR consent-verification requirements create premium pricing tolerance underserved by generalized platforms. A compliance-first go-to-market angle emphasizing audit-ready documentation accelerates trust acquisition in this high-penalty jurisdiction. For Investors and Strategic Acquirers: Asymmetric upside sits with workspace-native specialists possessing deep Google Workspace and Microsoft 365 integration layers that resist commoditization. Long-term viability favors vendors with revenue-indexed pricing models aligned to e-commerce cart recovery monetization. The signal to watch is BIMI certificate adoption velocity among Fortune 500 brands, indicating brand investment in inbox display infrastructure that sustains premium tool demand.| Strategic Initiative | Industry Significance |
|---|---|
| DMARC Policy Automation Platform | Compresses enterprise upgrade cycles forced by Google and Yahoo authentication mandates. |
| Revenue-Indexed Pricing Model | Aligns vendor fees to recovered cart value, capturing e-commerce platform expansion. |
| German Compliance Specialization | Addresses UWG and GDPR consent-verification premiums in strict enforcement jurisdiction. |
| API-Native ESP Integration | Secures white-label slots as headless email providers unbundle deliverability monitoring. |
| Blockchain Reputation Registry Pilot | Decentralizes trust establishment away from incumbent blacklist operator concentration. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with email operations directors, deliverability engineers, ESP product managers, and martech procurement officers informed demand-side dynamics. Secondary sources included FCC enforcement records, EU AI Act implementation guidance, SEC filings from public email infrastructure providers, and hyperscaler capex disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from authentication protocol adoption curves.
Rate-of-change decomposition across the analysis window isolates volume drivers from pricing dynamics, with CAGRs derived from regression against historical authentication mandate implementation patterns. Segmentation dimensions modeled include deployment model, customer type, feature module, and regional regulatory cluster. Forecast inputs incorporated e-commerce transaction volume elasticity, DMARC policy adoption velocity, and EU AI Act compliance cost pass-through assumptions.
The model holds under stable regulatory enforcement intensity; deviation in blacklist operator consolidation or certificate authority bottleneck resolution would shift vendor competitive positioning. Forecasts reflect documented assumptions regarding authentication mandate timeline adherence and cloud infrastructure cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Virtual Closet Market
Digital Solutions
Neuromarketing Solutions Market
Digital Solutions
AI In Packaging Design Market
Digital Solutions
Global User Experience (UX) Market
Digital Solutions
Data Converter Market
Digital Solutions
India Loyalty Program Market
Digital Solutions
Labor Management System in Retail Market
Digital Solutions
File Sharing Market
Digital Solutions
Smart Dictation Systems Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Contact Tracing Application Market
Digital Solutions
Global Data Catalog Market
Digital Solutions
Multicarrier Parcel Management Solutions Software Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Enterprise Search Market
Digital Solutions
Game Engines Market