
 Kazakhstan ICT Market | 2026-2036
Kazakhstan ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Kazakhstan ICT Market Insights
Kazakhstan's national digitalization strategy "Digital Kazakhstan" is shifting procurement priorities across public and private sectors. Kazakhtelecom anchors fixed-line and broadband infrastructure across the country's vast territory. Huawei Technologies competes aggressively in 5G equipment and data center buildouts. Cisco Systems leverages its enterprise networking portfolio to serve Kazakhstan's banking and mining verticals.
Information and communications technology encompasses the hardware, software, and services enabling data processing, transmission, and storage across enterprise and consumer environments. Core specifications include server rack densities exceeding 30kW per cabinet in modern Kazakh data centers and fiber-optic backbone links spanning over 120,000 route kilometers nationally. Services currently leads value generation as system integration and managed security contracts expand, while Cloud Computing within the technology dimension is growing fastest as local enterprises abandon legacy on-premises architectures. Hardware retains volume dominance through PC and server refresh cycles across government and educational institutions.
Kazakhstan's Ministry of Digital Development oversees compliance with national cybersecurity standards and data localization mandates requiring sovereign storage of citizen information. The country's technical regulation agency enforces GB-influenced equipment certification for network infrastructure imports, creating compliance barriers for non-aligned vendors. Stakeholders must monitor how evolving data sovereignty rules and cross-border data flow restrictions reshape cloud deployment strategies and vendor selection criteria.
Market Dynamics
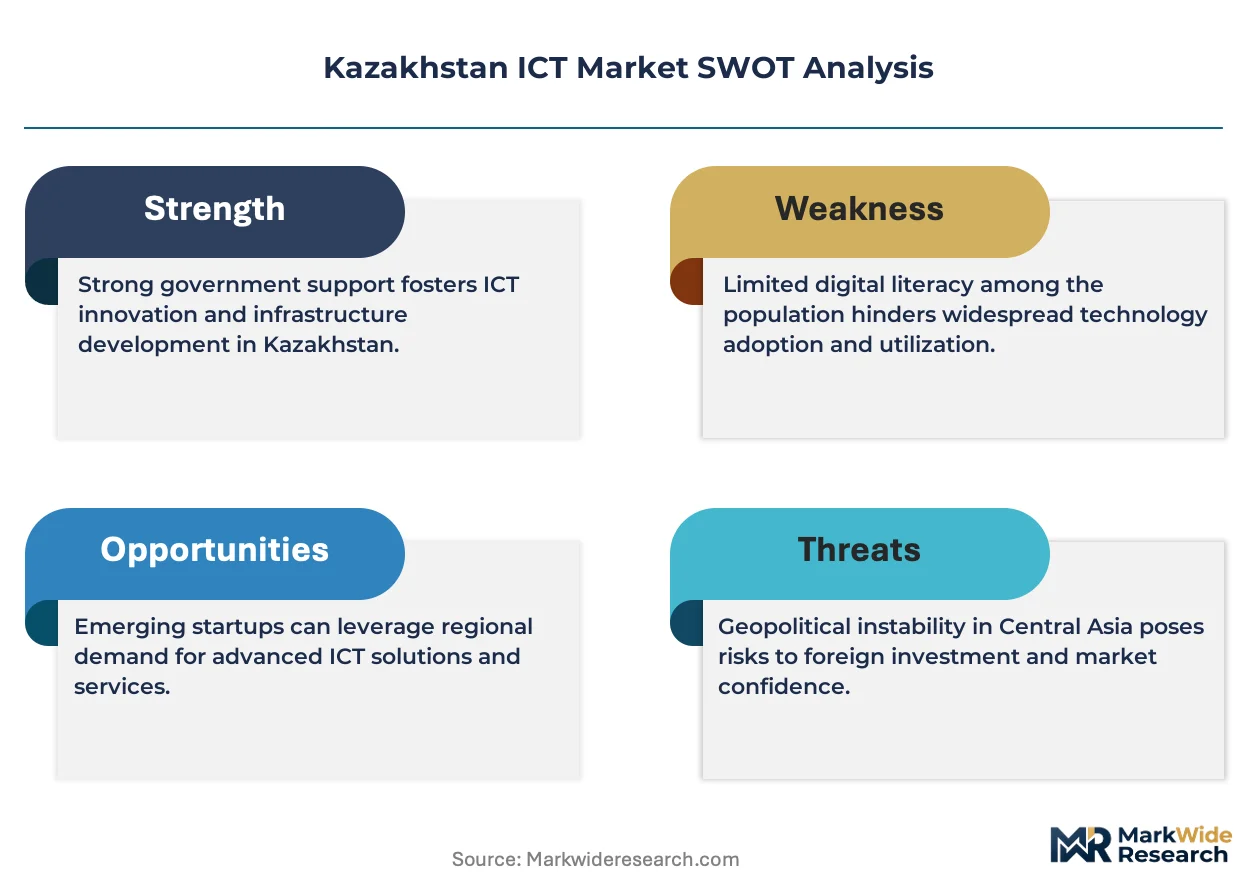
Kazakhstan's ICT sector faces acute pressure from data localization mandates and sovereign cloud requirements that are restructuring procurement patterns and vendor qualification criteria across public and private buyers.
Growth Catalysts
- Digital Kazakhstan framework:Government-mandated digitalization timelines are accelerating enterprise software procurement cycles and IT infrastructure refresh rates across state-owned enterprises.
- Astana International Financial Centre:Concentrated banking and fintech activity in the capital is generating clustered demand for Tier III+ data center capacity and managed security services.
- Fiber backbone densification:Kazakhtelecom's ongoing expansion of fiber-optic routes into secondary cities is enabling cloud service penetration beyond Almaty and Astana.
Market Restraints
- GB-influenced equipment certification:Technical regulation agency import requirements create compliance delays and qualification costs for non-aligned network infrastructure vendors.
- Capital intensity of data center construction:Power and cooling infrastructure requirements for 30kW+ rack densities demand substantial upfront investment, limiting greenfield development to well-capitalized operators.
- Cross-border data flow restrictions:Sovereign storage mandates for citizen information constrain hybrid cloud architectures and complicate disaster recovery strategies for multinational enterprises.
Strategic Opportunities
- Shymkent and Aktobe metro zones:Secondary urban centers remain underpenetrated for enterprise SaaS and managed services relative to Almaty-Astana corridor.
- 5G private network deployment:Mining and oil & gas extraction operations present specialized use cases for industrial IoT and autonomous equipment control.
- Cybersecurity services convergence:Managed detection and response offerings bundled with compliance monitoring address gaps in local enterprise security operations centers.
Industry Challenges
- Cloud architecture skill scarcity:Local system integrators face shortages of certified professionals in multi-cloud orchestration and containerized workload management.
- Legacy system integration friction:Soviet-era industrial control systems in extractive industries resist standard API connectivity and require custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kazakhstan ICT Market |
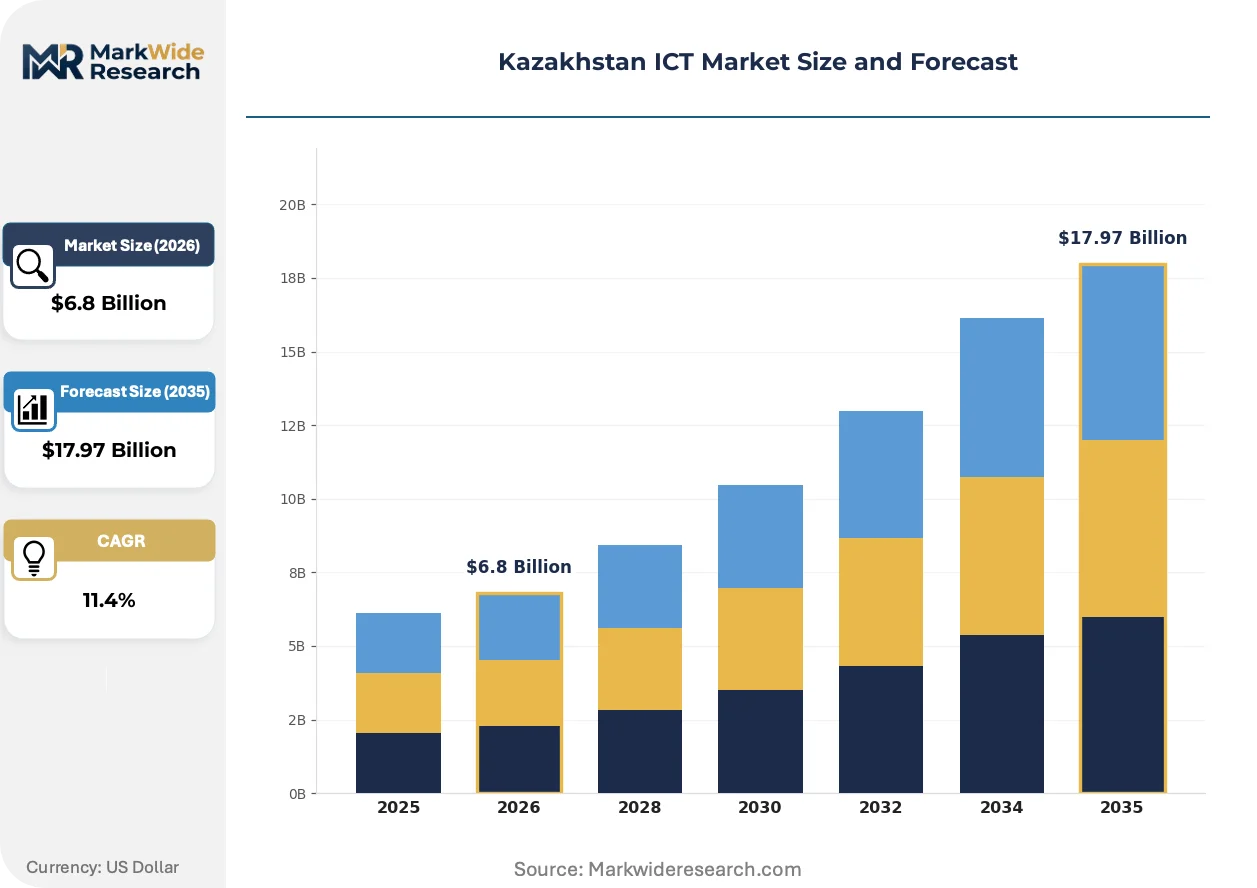
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Networking, Services End User: Government, Enterprises, SMEs, Educational Institutions Technology: Cloud Computing, AI, IoT, Cybersecurity Deployment: On-Premises, Cloud, Hybrid, Managed Services |
| Companies Covered | Cisco Systems, LeverX International Company, Microsoft Corporation, Oracle Corporation, Hewlett Packard Enterprise, Kazakhtelecom, IBM Corporation, Samsung Electronics, Huawei Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kazakhstan ICT Market Trends and Innovations
Edge computing architectures and sovereign cloud deployment models are compressing traditional centralized infrastructure strategies while reshaping vendor competitive positioning in Kazakhstan's enterprise segment.
Artificial intelligence inference workloads are integrating directly into Kazakh data center design specifications. Financial institutions in Astana are deploying GPU-accelerated infrastructure for real-time fraud detection and algorithmic trading. This compression of compute-to-data proximity is integrating latency-sensitive applications previously hosted in regional hubs.
Kazakhstan's Ministry of Digital Development has tightened data localization enforcement through amended cybersecurity compliance protocols. Industrial consequence includes mandatory sovereign storage for biometric and financial transaction data. Banking and telecommunications verticals are responding by establishing in-country cloud regions with domestic operators rather than relying on foreign hyperscale availability zones.
Enterprise buyers are consolidating vendor relationships around integrated platform providers capable of delivering infrastructure, security, and application layers under unified service level agreements. System integrators and value-added resellers are losing standalone infrastructure margins to direct procurement from cloud operators. This concentration is most visible among Kazakhstan's national oil company and mining conglomerates seeking simplified accountability structures.
Kazakhstan ICT Market Segmentation
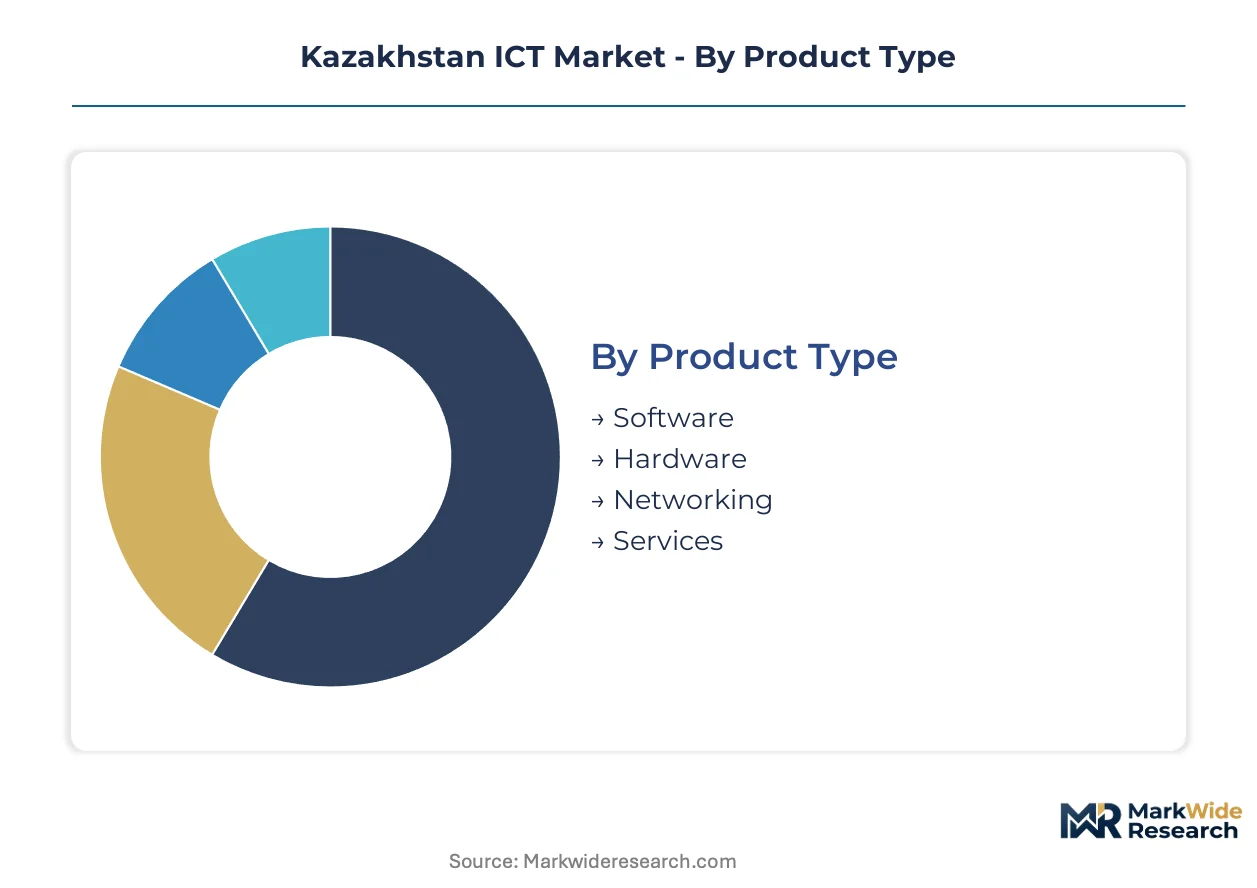
Kazakhstan's ICT procurement patterns diverge sharply across buyer sophistication and infrastructure maturity. State mandates concentrate demand in sovereign-compliant categories while private enterprises pursue cost-optimized hybrid architectures.
Product Type:
Buyer sophistication and procurement authority separate the four product categories, with government tenders favoring bundled infrastructure while enterprises prioritize modular software procurement.
- Software:Enterprise resource planning and customer relationship management suites dominate public sector tenders under Digital Kazakhstan mandates. Astana-based financial institutions drive demand for banking-specific middleware requiring Ministry of Digital Development certification.
- Services:System integration and managed security contracts absorb the largest share of enterprise IT budgets as local skills scarcity forces reliance on external specialists. Tier III+ data center operators bundle professional services with colocation to differentiate against hyperscale competition.
- Hardware:Server and storage refreshes cycle through government and educational institutions on centralized procurement schedules. PC deployments concentrate in urban school districts completing one-to-one device programs.
- Networking:Fiber-optic backbone equipment and 5G radio access units flow through Kazakhtelecom's national expansion program. Enterprise demand for software-defined WAN solutions lags behind infrastructure deployment.
Volume sits with Hardware; growth tilts toward Services.
End User:
Budget scale and compliance stringency create four distinct buyer archetypes, from centralized state procurement to fragmented SME purchasing.
- Government:State-owned enterprises and ministry IT departments operate under mandatory digitalization timelines with sovereign cloud requirements. Procurement flows through centralized tender platforms with domestic content preferences.
- Enterprises:National oil company and mining conglomerates pursue integrated platform consolidation to simplify vendor accountability. These buyers command custom service level agreements unavailable to smaller counterparts.
- Educational Institutions:Universities and technical colleges drive GPU-accelerated infrastructure demand for research computing and AI curriculum development. Device procurement concentrates in Almaty and Astana metropolitan zones.
- SMEs:Small and medium enterprises access cloud productivity suites through distributor channels with minimal customization. This segment exhibits highest price sensitivity and lowest vendor loyalty.
Procurement scale concentrates with Government; commercial flexibility expands fastest among SMEs.
Technology:
Infrastructure maturity and regulatory exposure differentiate adoption trajectories across the four technology domains.
- Cloud Computing:Local operators establish sovereign cloud regions to satisfy data localization mandates for biometric and financial transaction storage. Hybrid architectures face friction from cross-border data flow restrictions.
- Cybersecurity:Managed detection and response services address capability gaps in enterprise security operations centers. Compliance monitoring bundles gain traction as Ministry enforcement tightens.
- AI:GPU-accelerated inference workloads integrate into financial institution data centers for real-time fraud detection. Algorithmic trading infrastructure in Astana International Financial Centre drives specialized hardware procurement.
- IoT:Industrial sensors and autonomous equipment control systems deploy in mining and oil & gas extraction operations. Private 5G networks enable latency-sensitive use cases unavailable through public infrastructure.
Revenue concentration favors Cloud Computing; steepest expansion trajectory belongs to Cybersecurity.
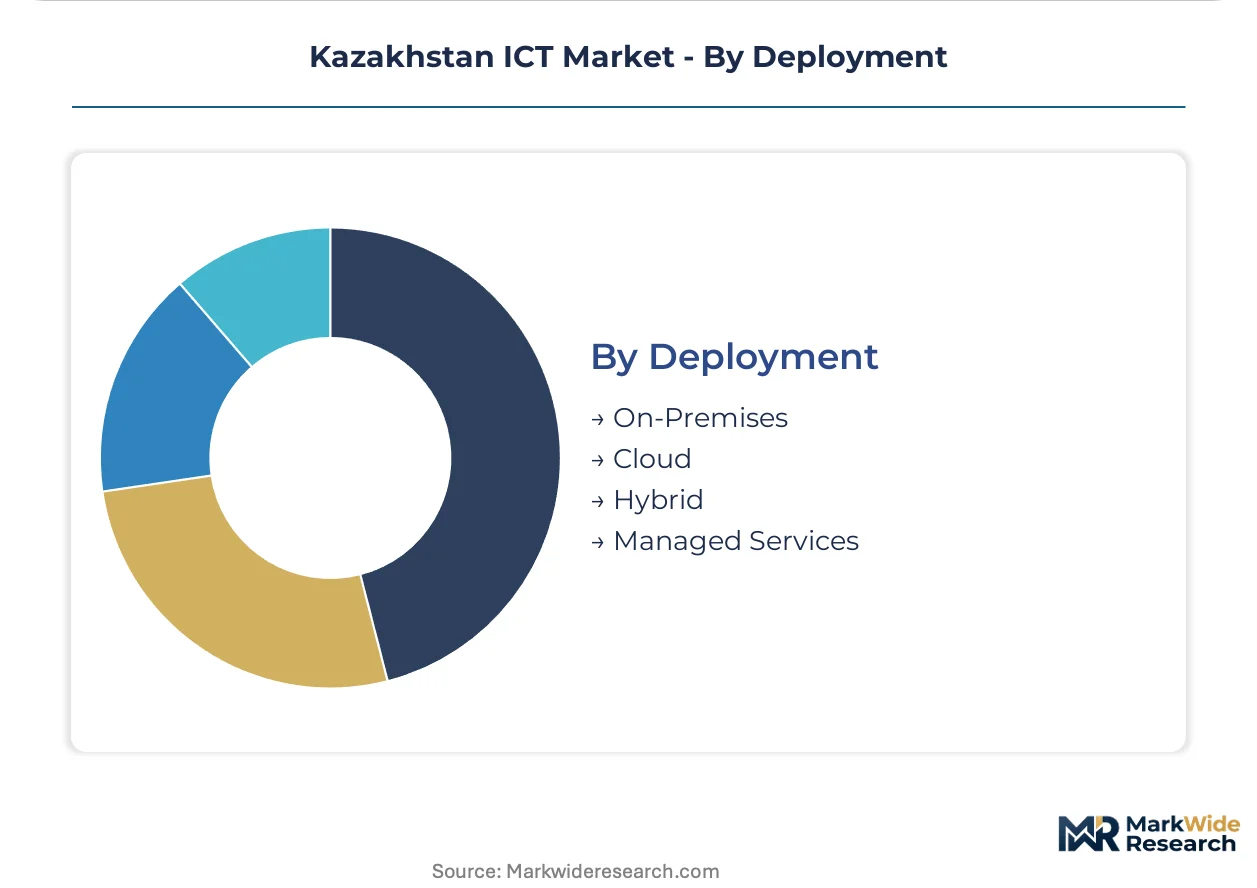
Deployment:
Capital availability and workload sensitivity to latency determine architecture selection across deployment models.
- Managed Services:Outsourced infrastructure operation appeals to enterprises lacking certified professionals in multi-cloud orchestration. Providers absorb talent scarcity risk through service commitments.
- Cloud:Public cloud adoption accelerates as local enterprises abandon legacy on-premises architectures. Sovereign storage requirements push banking and telecommunications verticals toward domestic operator regions.
- Hybrid:Mixed architectures face structural constraints from data sovereignty rules complicating disaster recovery strategies. Multinational enterprises struggle to synchronize global operations with local mandates.
- On-Premises:Legacy data center retention persists in extractive industries with Soviet-era industrial control systems resisting standard API connectivity. Custom middleware development delays cloud migration timelines.
Installed base remains with On-Premises; strategic investment shifts toward Managed Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Astana anchors Kazakhstan's ICT demand concentration through the Astana International Financial Centre, where banking and fintech clusters drive Tier III+ data center procurement. Almaty maintains legacy commercial density, while fiber backbone expansion unlocks secondary metro zones.
Almaty Metropolitan Zone
Enterprise software procurement and educational institution device deployments concentrate in Kazakhstan's commercial capital. The Ministry of Digital Development channels Digital Kazakhstan tenders through centralized platforms with domestic content preferences. GPU-accelerated infrastructure demand at universities and technical colleges drives specialized hardware procurement cycles.
Astana Capital Region
Financial services verticals generate clustered demand for sovereign cloud capacity and managed security services. Data localization mandates from the Ministry of Digital Development require biometric and financial transaction storage within national borders. The Astana International Financial Centre hosts algorithmic trading infrastructure and real-time fraud detection systems.
Shymkent Metro Zone
Secondary urban enterprise demand for SaaS and managed services remains underpenetrated relative to the Almaty-Astana corridor. Kazakhtelecom's fiber-optic backbone densification extends cloud service penetration beyond primary metros. Industrial buyers in this southern hub exhibit growing procurement sophistication for integrated platform solutions.
Aktobe Industrial Corridor
Mining and oil & gas extraction operations present specialized use cases for private 5G networks and industrial IoT deployment. Soviet-era industrial control systems resist standard API connectivity, requiring custom middleware development. Extractive industry conglomerates pursue vendor consolidation to simplify accountability structures.
Atyrau Energy Basin
Oil & gas headquarters operations generate demand for cybersecurity services convergence and compliance monitoring bundles. Cross-border data flow restrictions complicate disaster recovery strategies for multinational energy enterprises. Local system integrators absorb talent scarcity risk through managed infrastructure operation commitments.
Kazakhstan ICT Market Competitive Landscape
The competitive structure tilts toward diversified technology conglomerates with sovereign cloud capabilities. Market concentration reflects procurement authority consolidation among national oil companies, mining conglomerates, and state-owned enterprises. Three archetypes dominate: integrated platform providers bundling infrastructure and security layers; specialized system integrators serving compliance-heavy verticals; and domestic telecom operators leveraging fiber backbone assets. M&A activity concentrates on cybersecurity capability acquisition, while strategic partnerships address multi-cloud orchestration skill gaps.
Among diversified technology conglomerates, Cisco Systems and Microsoft Corporation exemplify integrated platform positioning, while Kazakhtelecom anchors domestic infrastructure control. Huawei Technologies occupies a position bridging equipment supply and data center buildout execution. These players represent contrasting responses to data localization mandates—foreign vendors establishing domestic operator partnerships versus indigenous carriers expanding sovereign cloud regions.
| Leading Market Players |
|---|
| Cisco Systems |
| LeverX International Company |
| Microsoft Corporation |
| Oracle Corporation |
| Hewlett Packard Enterprise |
| Kazakhtelecom |
| IBM Corporation |
| Samsung Electronics |
| Huawei Technologies |
| Others |
Pricing and Supply Chain Analysis
State-owned enterprises and national oil companies concentrate procurement authority in Kazakhstan's ICT sector, anchoring enterprise software and infrastructure contracts to long-term managed service agreements with sovereign compliance requirements.
Pricing Analysis
Value-based pricing tied to system uptime and security incident response anchors enterprise contracts in Kazakhstan's banking and extractive verticals. Tiered pricing separates Tier III+ data center colocation with guaranteed availability from standard cloud hosting, with certification level from the Ministry of Digital Development commanding material premiums. Cost compression in hardware procurement intensifies as Kazakhtelecom's centralized tenders squeeze distributor margins on networking equipment. SMEs exhibit highest price sensitivity, while national conglomerates prioritize vendor accountability over unit cost.
Supply Chain Analysis
Regional distribution centers in Almaty and Astana operate hub-and-spoke patterns for enterprise hardware fulfillment into secondary cities. Supply concentrates in China for server and networking equipment, South Korea for memory and display components, and the United States for specialized cybersecurity appliances. Component dependencies span GPU accelerators for AI inference, fiber-optic transmission gear, and precision cooling systems. Single-source vulnerability around advanced semiconductor fabrication creates exposure. Distribution runs through authorized value-added resellers with Ministry certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kazakhstan's ICT sector operates under supply-constrained conditions where certified cloud infrastructure capacity props pricing power for sovereign-compliant operators.
For Market Incumbents: Acquire cybersecurity specialist capabilities to bundle managed detection and response with existing infrastructure contracts. Defensive consolidation should target system integrators holding Ministry of Digital Development certifications, as emerging domestic cloud operators threaten platform relationships with national oil companies. Capacity addition in Astana's Tier III+ data center zone reinforces geographic moats. For New Entrants and Emerging Players: Value-added resellers in Shymkent and Aktobe represent the most penetrable channel layer for SaaS distribution outside the Almaty-Astana corridor. White-space targets include industrial IoT middleware for mining operations and GPU-accelerated infrastructure for technical colleges. A compliance-first go-to-market angle addressing data localization mandates differentiates against unqualified foreign hyperscalers. For Investors and Strategic Acquirers: The window for entry favors domestic operators with sovereign cloud regions and established Ministry relationships. Long-term viability rests on regulatory alignment rather than technology differentiation. The signal to watch is enforcement intensity around biometric data storage mandates, which would accelerate banking vertical consolidation toward compliant infrastructure providers.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Region Establishment | Domestic operators capture banking and telecommunications verticals requiring Ministry-certified data localization. |
| Cybersecurity Capability Acquisition | Managed detection and response bundling addresses enterprise security operations center gaps in extractive industries. |
| Fiber Backbone Expansion Partnership | Kazakhtelecom's secondary city densification enables cloud service penetration beyond Almaty and Astana metros. |
| GPU Infrastructure Deployment | Financial institutions in Astana International Financial Centre demand real-time fraud detection hardware. |
| Industrial IoT Middleware Development | Mining and oil & gas operations require custom connectivity solutions for Soviet-era control systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for Kazakhstan's ICT market sizing. Primary interviews with CTOs at financial institutions, IT procurement officers in state-owned enterprises, platform engineers at data center operators, and channel partners in Almaty and Astana complemented secondary validation. Ministry of Digital Development cybersecurity compliance protocols, Kazakhtelecom infrastructure disclosures, and enterprise software licensing databases supplied quantitative anchors. Bottom-up segment builds triangulated against top-down macroeconomic indicators.
Data-stream reconciliation across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern produced volume and value estimates. CAGRs derived from trend extrapolation of sovereign cloud investment cycles, fiber densification timelines, and enterprise software refresh rates. Inputs included GPU infrastructure procurement patterns in Astana's financial district and industrial IoT sensor deployment rates in extractive operations.
Caveats apply where Ministry enforcement intensity around data localization or shifts in GB-influenced equipment certification protocols could materially shift the outlook. Forecasts reflect documented assumptions about regulatory continuity and capital commitment to Digital Kazakhstan timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
EHS Software Market
Digital Solutions
Lecture Capture Systems Market
Digital Solutions
Parking Management Systems Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
Restaurant POS Terminals Market
Digital Solutions
Ad Network Software Market
Digital Solutions
Web Performance Market
Digital Solutions
Data Classification Tool Market
Digital Solutions
IT Monitoring Tools Market
Digital Solutions
Real Time Store Monitoring Platform Market
Digital Solutions
Data Analytics in the Smart Home Market
Digital Solutions
Outsourced Digital Workplace Service Market
Digital Solutions
Stylus Pen for Education Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
Docker Monitoring Market
Digital Solutions
UAE Digital Twin Market