
 Molecular Information Systems Market | 2026-2036
Molecular Information Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Information Systems Market Analysis
The divergence between premium sequencing platforms and commodity reagent tiers is hardening as capital equipment vendors tighten performance specifications while bulk consumable producers compete on throughput economics. Thermo Fisher Scientific leverages integrated workflow architectures spanning sample prep through data analysis. Illumina dominates high-throughput next-generation sequencing with proprietary flow cell chemistry. QIAGEN N.V. anchors the sample-to-insight value chain with automated nucleic acid extraction systems.
Molecular information systems encompass hardware, software, and consumable infrastructures that capture, process, and interpret nucleic acid and protein-level data with specified sensitivity thresholds, typically detecting variants at frequencies below one percent. These systems serve pharmaceutical discovery pipelines, clinical diagnostic laboratories, and academic research programs requiring standardized, reproducible molecular characterization. Sequencing platforms command the largest installed base revenue share due to instrument placement stickiness and recurring reagent pull-through. CRISPR-enabled systems represent the fastest-expanding technology segment as gene editing transitions from research tool to therapeutic manufacturing quality control. Academic institutions constitute the most price-sensitive end user category, while pharmaceutical companies generate the highest per-site annual consumable spend.
FDA premarket review pathways for next-generation sequencing-based oncology panels establish analytical validity benchmarks that shape vendor R&D priorities. The NIH's data sharing policies and the EPA's genomic research material transport guidelines collectively determine laboratory operational compliance burdens. Stakeholders must monitor evolving reimbursement decisions for molecular diagnostic tests by the Centers for Medicare & Medicaid Services, as coverage determinations directly influence hospital capital allocation cycles.
Market Dynamics
CRISPR technology integration is compressing qualification timelines for molecular diagnostic platforms while fragmenting vendor specialization across the gene editing workflow.
Growth Catalysts
- NIH Funding Priorities:The National Institutes of Health directs substantial grant capital toward precision medicine infrastructure, compelling academic medical centers to upgrade sequencing capacity.
- FDA Diagnostic Pathway Reforms:Streamlined premarket review for next-generation sequencing-based oncology panels accelerates commercialization timelines for validated assays.
- Pharmaceutical Discovery Pipelines:Drug developers deploy molecular information systems to stratify patient populations, generating recurring consumable demand for variant detection below one percent frequency.
Market Restraints
- Flow Cell Chemistry Concentration:Proprietary reagent architectures from dominant sequencing platform vendors lock laboratories into single-source supply relationships with limited price leverage.
- Capital Equipment Intensity:High-throughput instrument placements require seven-figure upfront investment, constraining adoption among mid-sized diagnostic laboratories.
- EPA Genomic Material Transport:Compliance with environmental agency guidelines for nucleic acid specimen movement adds operational friction to multi-site research collaborations.
Strategic Opportunities
- CRISPR-Therapeutic Manufacturing QC:Gene editing's transition from research tool to commercial therapy creates demand for validated quality control systems in biologics production.
- India's PLI Scheme:Production-linked incentives for medical device manufacturing attract molecular diagnostic component assembly to lower-cost jurisdictions.
- Cloud-Native Data Architecture:Laboratory information management systems migrate to subscription-based platforms, unbundling software from hardware procurement cycles.
Industry Challenges
- Bioinformatics Talent Scarcity:Shortages of computational biologists capable of interpreting variant call format data slow deployment of clinical-grade pipelines.
- Multi-Vendor Integration Complexity:Laboratories struggle to harmonize data outputs across incompatible sample prep, sequencing, and analysis platforms from different suppliers.
- Reimbursement Timeline Uncertainty:Centers for Medicare & Medicaid Services coverage determinations for molecular diagnostic tests lag FDA clearance by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Information Systems Market |
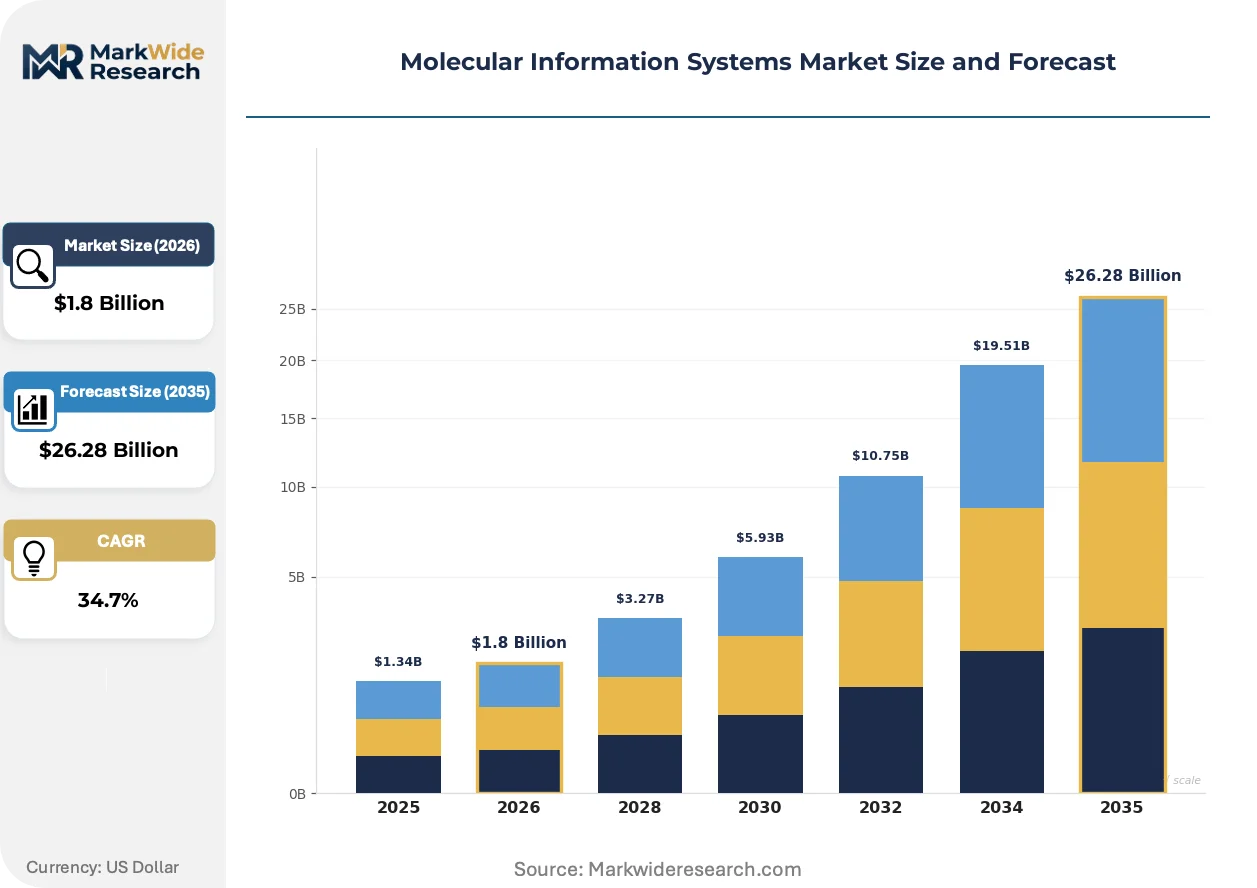
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sequencing Platforms, Microarrays, PCR Instruments, Reagents Technology: Next-Generation Sequencing, Microarray Analysis, Diagnostic Imaging, CRISPR Application: Genomic Research, Drug Discovery, Clinical Diagnostics, Personalized Medicine End User: Academic Institutions, Pharmaceutical Companies, Contract Research Organizations, Hospitals |
| Companies Covered | QIAGEN N.V., Thermo Fisher Scientific Inc., Illumina Inc., Danaher Corporation, F. Hoffmann-La Roche, Agilent Technologies, Abbott Laboratories, Becton Dickinson and Company, Hologic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Information Systems Market Emerging Trajectories
Cloud-native architectures and artificial intelligence-enabled variant interpretation are redistributing value capture from hardware vendors to software layer specialists.
Single-molecule real-time sequencing is absorbing capital allocation from short-read platforms in structural variant detection applications. Clinical cytogenetics laboratories adopt Pacific Biosciences and Oxford Nanopore systems for resolving complex genomic rearrangements. Pharmaceutical toxicology groups deploy these technologies to compress preclinical safety assessment timelines.
The European Union's Medical Device Regulation imposes notified body oversight on software-as-a-medical-device components within molecular information workflows. In vitro diagnostic manufacturers reclassify data analysis modules to meet Class IIa or higher conformity requirements. German and French notified bodies experience backlogs exceeding eighteen months for novel algorithm submissions.
Hospital procurement departments consolidate molecular diagnostic vendor relationships to secure enterprise-wide pricing and unified service contracts. Integrated delivery networks in the United States negotiate multi-year reagent supply agreements spanning pathology, oncology, and infectious disease divisions. This concentration shifts negotiation leverage from individual laboratory directors to centralized supply chain functions.
Molecular Information Systems Market Segmentation
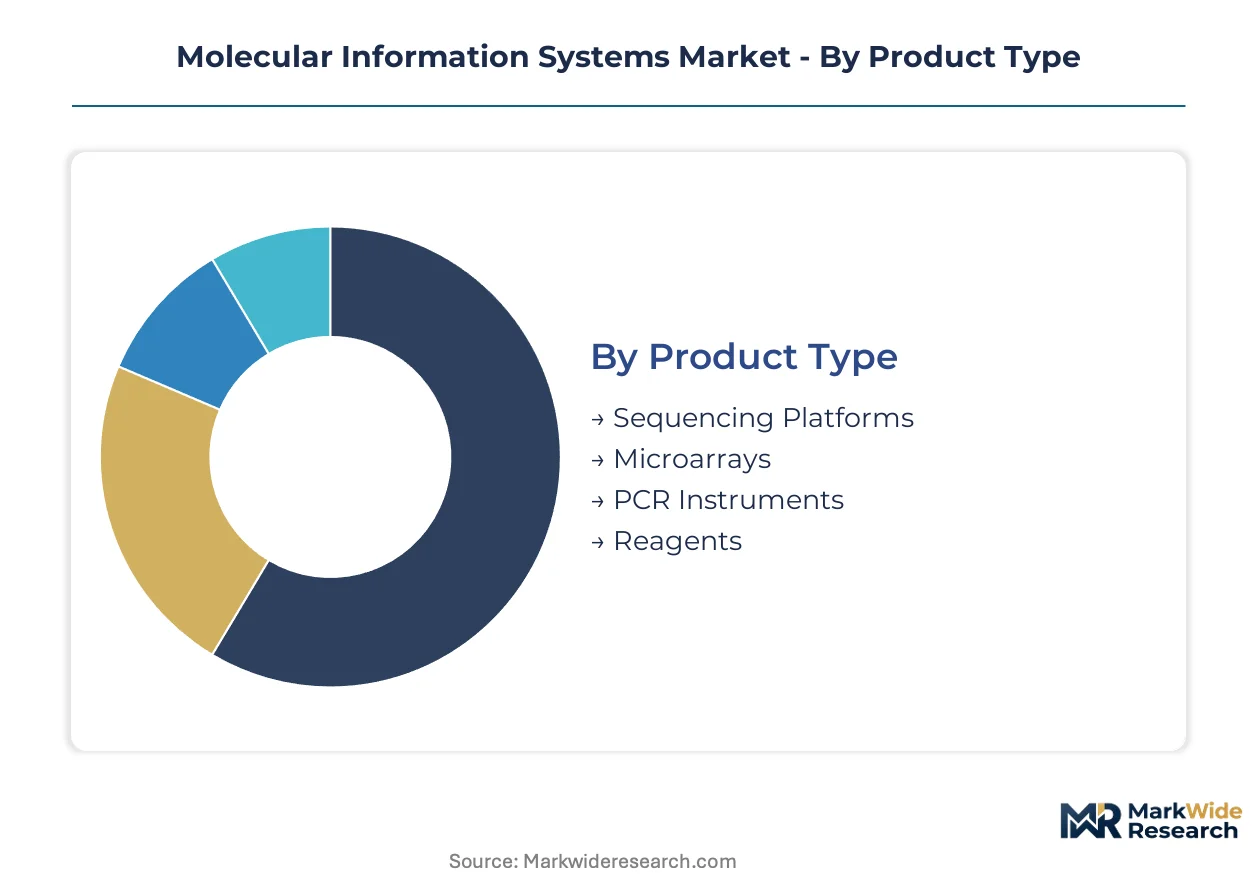
Molecular information systems fragment across four distinct taxonomies that govern procurement patterns and vendor specialization. Product type determines capital intensity and recurring revenue profiles. Technology selection constrains analytical sensitivity and workflow integration options. Application focus shapes regulatory compliance burdens and reimbursement pathways. End user category dictates price elasticity and purchasing centralization.
Product Type:
Volume leaders anchor installed base economics while premium tiers capture margin expansion from performance-critical applications.
- Sequencing Platforms:High-throughput instruments utilizing proprietary flow cell chemistry generate recurring reagent pull-through through instrument placement stickiness. Pharmaceutical toxicology groups and academic medical centers in the United States concentrate demand for platforms detecting variants below one percent frequency, driven by NIH precision medicine infrastructure grants.
- Reagents:Consumable architectures—enzymes, nucleotides, and library preparation kits—constitute the recurring revenue backbone of vendor financial models. Contract research organizations and hospital pathology laboratories generate the highest per-site annual spend, constrained by proprietary lock-in from dominant sequencing platform vendors.
- Microarrays:Solid-state nucleic acid hybridization systems serve targeted genotyping applications with established analytical validity.
- PCR Instruments:Thermal cycling platforms support amplification-dependent detection workflows in clinical diagnostic settings.
Today's leader: Sequencing Platforms. Tomorrow's challenger: Reagents.
Technology:
Maturity gradients separate established analytical methods from emerging modalities reshaping qualification timelines.
- Next-Generation Sequencing:Massively parallel detection of nucleic acid sequences dominates structural variant identification and oncology panel applications. FDA premarket review pathway reforms for NGS-based oncology panels accelerate commercialization timelines, concentrating adoption among United States hospital systems seeking streamlined diagnostic validation.
- CRISPR:Gene editing technology transitions from research tool to therapeutic manufacturing quality control, creating validated system demand in biologics production. Biopharmaceutical manufacturers in the United States and European Union deploy CRISPR-enabled platforms for cell line characterization, climbing the fastest as gene therapies advance toward commercial scale.
- Microarray Analysis:Hybridization-based detection supports high-throughput genotyping with established regulatory precedents.
- Diagnostic Imaging:Spatial molecular visualization integrates with sequencing data for tissue context interpretation.
Established foundation: Next-Generation Sequencing. Emerging disruption: CRISPR.
Application:
Reimbursement visibility and development timeline uncertainty segment addressable market opportunity.
- Clinical Diagnostics:Patient-facing testing workflows require analytical validity demonstration and payer coverage alignment. United States hospital laboratories concentrate investment here, constrained by Centers for Medicare & Medicaid Services coverage determinations lagging FDA clearance by twelve to eighteen months.
- Drug Discovery:Preclinical and clinical trial support applications generate premium consumable demand from variant stratification requirements. Pharmaceutical companies deploy molecular information systems across discovery pipelines, expanding most quickly as precision medicine architectures reshape trial design.
- Genomic Research:Academic and government-funded investigations establish methodological precedents for clinical translation.
- Personalized Medicine:Patient-specific therapeutic selection and monitoring applications integrate multi-omic data layers.
Revenue concentration: Drug Discovery. Regulatory clarity: Clinical Diagnostics.
End User:
Purchasing centralization and price sensitivity gradients determine vendor contract structure and service intensity.
- Pharmaceutical Companies:Integrated drug developers command highest per-site annual consumable expenditure through discovery pipeline deployment and manufacturing quality control requirements. United States and European Union biopharmaceutical operations generate concentrated demand for CRISPR-enabled systems in cell therapy production.
- Academic Institutions:University and medical school laboratories exhibit greatest price sensitivity while establishing methodological standards for clinical adoption. NIH funding priorities in the United States compel sequencing capacity upgrades, though grant-dependent budgets constrain premium platform procurement.
- Hospitals:Clinical diagnostic service lines pursue enterprise-wide vendor consolidation for unified pricing and service contracts.
- Contract Research Organizations:Outsourced service providers aggregate demand across sponsor portfolios with standardized platform requirements.
Margin priority: Pharmaceutical Companies. Volume foundation: Academic Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision medicine infrastructure outpaces France in sequencing platform density per capita, while India's PLI scheme redirects component assembly from higher-cost Asian manufacturing bases.
United States
NIH precision medicine grants and academic medical center consolidation drive sequencing capacity expansion across major metropolitan hospital systems. FDA premarket review pathway reforms for oncology panels compress commercialization timelines for assay developers. The Boston-Cambridge biotech corridor concentrates CRISPR-enabled therapeutic manufacturing quality control system deployment.
Germany
Industrial laboratory automation demand and pharmaceutical toxicology outsourcing sustain premium instrument procurement from global vendors. EMA oversight of software-as-a-medical-device components extends notified body review timelines for algorithm submissions. The Rhine-Main biotech cluster anchors molecular diagnostic reagent manufacturing for European distribution.
China
Domestic NMPA approval acceleration and biologics manufacturing scale-up create demand for validated gene editing quality control systems. National genomic data security regulations constrain cross-border specimen movement for multi-site research collaborations. The Yangtze River Delta biopharmaceutical manufacturing zone concentrates cell therapy production facility investment.
India
Contract research organization capacity expansion and government-funded genomic research programs generate mid-tier instrument demand. PLI scheme incentives for medical device component assembly attract molecular diagnostic supply chain relocation from established Asian manufacturing centers. The Hyderabad-Genome Valley cluster anchors nucleic acid extraction system production for export markets.
United Kingdom
NHS genomic medicine service integration and academic research commercialization programs sustain dual-track demand for clinical and research-grade platforms. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for novel diagnostic algorithms. The Cambridge-London life sciences corridor concentrates early-stage CRISPR therapeutic development and associated analytical system procurement.
Molecular Information Systems Market Vendor Landscape
Top-tier vendors anchor integrated workflow architectures spanning sample preparation through data analysis, while specialized reagent producers compete on bulk consumable economics and regional distribution reach. Mid-tier regional players occupy niche positions in automated nucleic acid extraction and localized service support. Three archetypes dominate: diversified life science conglomerates with cross-platform portfolios, sequencing-focused technology specialists with proprietary chemistry lock-in, and sample-to-insight workflow integrators with automated preparation systems. Competitive dynamics center on strategic partnerships for multi-omics data integration and vertical control over critical reagent supply chains.
Among diversified instrumentation conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify scale-driven platform consolidation across the molecular information value chain. Illumina occupies a position as the archetypal sequencing technology specialist with flow cell chemistry-dependent recurring revenue models. QIAGEN N.V. anchors the sample preparation tier with automated extraction systems that interface with downstream analytical platforms from multiple vendors.
| Leading Market Players |
|---|
| QIAGEN N.V. |
| Thermo Fisher Scientific Inc. |
| Illumina Inc. |
| Danaher Corporation |
| F. Hoffmann-La Roche |
| Agilent Technologies |
| Abbott Laboratories |
| Becton Dickinson and Company |
| Hologic Inc. |
| Others |
Supply Flow & Price Mechanics
Bioinformatics talent concentration in the Boston-Cambridge corridor and Basel region drives labor-cost differentials that widen pricing-tier spreads between premium analytical platforms and economy-grade reagent bundles.
Pricing Analysis
Bundled instrument-service contracts dominate high-throughput sequencing platforms while unbundled reagent procurement prevails in mid-tier PCR and microarray segments. Pricing stratifies across premium, standard, and economy tiers based on analytical sensitivity thresholds and FDA premarket review tier certification. Cost compression in economy-grade consumables is intensifying because contract research organizations consolidate purchase volumes through group purchasing organizations. Academic institutions exhibit greatest price sensitivity due to grant-dependent budgets, while pharmaceutical toxicology groups accept premium pricing for validated variant detection below one percent frequency.
Supply Chain Analysis
Freight cost volatility for temperature-controlled nucleic acid specimen transport constrains multi-site research collaboration economics and shapes regional distribution center placement. Manufacturing concentration centers on the United States for high-throughput sequencing instruments, Germany for automated sample preparation systems, and China for plastic consumables and electronic subcomponents. Critical dependencies include proprietary flow cell chemistry from dominant platform vendors, specialized enzymes from recombinant protein foundries, and rare-earth magnets for magnetic bead separation workflows. Single-source vulnerability for flow cell architectures locks laboratories into limited supplier relationships. Distribution runs through authorized distributor networks for capital equipment and direct-to-laboratory e-commerce portals for recurring consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in molecular information systems rests on cloud-native software unbundling from hardware procurement cycles and CRISPR-therapeutic manufacturing quality control premium tier development.
For Market Incumbents: Deepen proprietary reagent lock-in through expanded compatibility certification programs for third-party sample prep automation. Anchor service contract renewal rates by embedding predictive maintenance algorithms into sequencing platform firmware. CRISPR-enabled system commoditization from emerging bioprocess analytics vendors threatens consumable pull-through economics. Capacity addition in India's PLI-subsidized manufacturing zones reduces cost-to-serve for Asia-Pacific reagent distribution. For New Entrants and Emerging Players: The price-point gap between premium sequencing platforms and economy-grade PCR systems creates entry space for mid-tier long-read sequencing specialists. Academic medical centers in the United Kingdom and India represent the most penetrable end-user category due to NHS and government-funded genomic research program budget cycles. A software-as-a-medical-device regulatory pathway focus accelerates time-to-revenue against hardware-intensive incumbents. For Investors and Strategic Acquirers: Pharmaceutical companies with cell therapy manufacturing pipelines are the most active acquirer in this space, seeking captive quality control system supply. Long-term viability favors vendors with cloud-native data architecture subscription models over hardware-dependent revenue concentration. Acquisition target archetypes include automated nucleic acid extraction specialists with multi-platform compatibility and CRISPR analytics software modules with EMA MDR Class IIa conformity progress. The signal to watch is Centers for Medicare & Medicaid Services coverage determination acceleration for oncology panel reimbursement.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native LIMS Migration | Unbundles software revenue from seven-figure instrument procurement cycles. |
| CRISPR QC System Validation | Captures gene therapy manufacturing compliance spend from FDA-regulated biologics. |
| Multi-Omics Data Integration Partnership | Combines sequencing, proteomics, and imaging outputs for pharmaceutical discovery pipelines. |
| India PLI Manufacturing Footprint | Reduces reagent cost-to-serve through Hyderabad-Genome Valley component assembly. |
| Software-as-a-Medical-Device Certification | Meets EMA MDR Class IIa requirements for algorithm-based variant interpretation. |
Methodological Framework
Multiple input streams — primary interviews with laboratory directors and hospital procurement managers, regulatory filings with FDA and EMA, and GPO contract databases — were reconciled through bottom-up and top-down triangulation. Conversations with sequencing platform operators, biopharmaceutical manufacturing quality control leads, and academic core facility managers informed workflow adoption patterns. Secondary validation drew from ClinicalTrials.gov precision medicine trial registrations, CMS Medicare coverage determination documents, and NIH RePORTER grant award data.
Historical instrument placement and consumable pull-through rates were cross-referenced against panel input from biopharmaceutical capital planning committees and academic medical center budget officers. The analytical framework modeled product type, technology maturity, application reimbursement visibility, and end-user purchasing centralization across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation with macro healthcare R&D expenditure trends and precision medicine infrastructure grant award trajectories.
The model assumes a particular technology adoption path; alternative pathways for single-molecule real-time sequencing displacement of short-read platforms would alter the outlook. Forecasts reflect assumptions regarding FDA premarket review timeline stability and NIH funding priority continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Qatar ICT Market
Digital Solutions
Workspace As a Service Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
AQI App Market
Digital Solutions
Control Room Solutions Market
Digital Solutions
OTA Transmission Platform Market
Digital Solutions
Global Cloud POS Market
Digital Solutions
Tablet Based E-Detailing Market
Digital Solutions
Enterprise Mobility in Energy Sector Market
Digital Solutions
Microservices Architecture Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
US Digital Signage Market
Digital Solutions
Mobile Engagement Market
Digital Solutions
Manufacturing Execution System Market
Digital Solutions
Global Referral Management Market
Digital Solutions
Agriculture Software Market