
 North America Online Dating Services Market | 2026-2036
North America Online Dating Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Online Dating Services Market Analytics
AI engineering talent scarcity is reorganizing how platforms build recommendation engines across the region. Match Group, Inc. leverages its portfolio breadth to sustain engagement across multiple demographics. Bumble Inc. differentiates through women-first messaging architecture that anchors brand loyalty among professionals. Hinge specializes in relationship-oriented positioning that competes directly with swipe-based alternatives.
North America online dating services encompass digital platforms that use proprietary algorithms, user preference matrices, and real-time behavioral signals to facilitate romantic connections between individuals. These systems process profile metadata, swipe patterns, and message sentiment to generate compatibility scores and curated match suggestions. Mobile Apps capture the dominant share of session volume as smartphone-native behavior displaces desktop onboarding flows. Freemium subscription models concentrate the largest user base while Premium Access tiers extract higher lifetime value from commitment-seeking segments. Niche Platforms serving LGBTQ+ and senior demographics represent the fastest-growing addressable pools as underserved populations demand tailored safety features and community verification protocols.
The Federal Trade Commission scrutinizes subscription billing practices and dark pattern design that trap users in recurring payments. State attorneys general in California and Texas enforce biometric privacy statutes that restrict facial recognition training datasets without explicit consent. Canada's Office of the Privacy Commissioner applies PIPEDA principles to cross-border data flows between Toronto-based engineering teams and US server infrastructure. Stakeholders must monitor evolving state patchworks of AI disclosure requirements that could force algorithmic transparency before match recommendations deploy.
Market Dynamics
Algorithmic matching architectures now determine user retention economics as platforms compete on prediction accuracy rather than network size alone. The FTC's scrutiny of subscription billing practices forces engineering teams to rebuild payment flows around explicit consent mechanisms.
Growth Catalysts
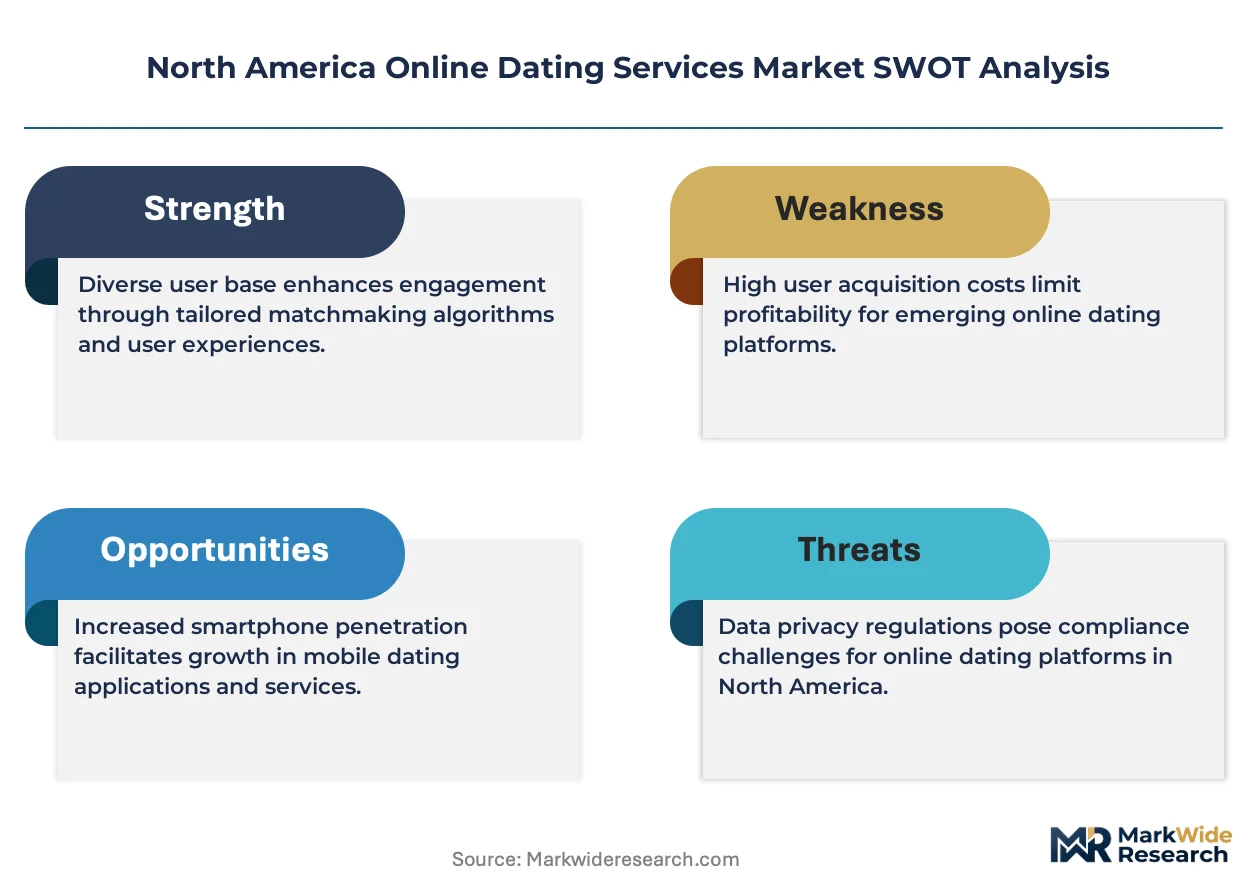
- Biometric Privacy Statutes:California and Texas state attorneys general enforce explicit consent requirements for facial recognition training datasets. Platforms that architect compliant data pipelines gain defensible positioning against enforcement actions.
- Freemium Mobile Onboarding:Smartphone-native behavior patterns concentrate session volume in apps with frictionless registration flows. California and Texas users drive the highest freemium-to-premium conversion rates through localized payment infrastructure.
- Niche Platform Expansion:LGBTQ+ and senior demographics demand tailored safety features and community verification protocols. These underserved populations represent addressable pools with distinct feature requirements and lower competitive density.
Market Restraints
- AI Engineering Talent Scarcity:Recommendation engine development stalls as platforms compete for machine learning specialists. Toronto-based engineering teams face cross-border recruitment friction under PIPEDA data flow restrictions.
- State Patchwork Compliance:California's biometric laws and Texas privacy statutes create fragmented legal obligations. Platforms must maintain parallel consent architectures rather than unified national systems.
- Dark Pattern Liability:The FTC's recurring payment enforcement exposes platforms to refund obligations and reputation damage. Interface designs that obscure cancellation flows trigger specific regulatory penalties.
Strategic Opportunities
- Canadian Federal Privacy Alignment:PIPEDA principles applied to cross-border data flows create first-mover advantages for Toronto-headquartered operations. Platforms that integrate Canadian and US compliance architectures reduce dual-jurisdiction friction.
- Women-First Messaging Architecture:Professionals seeking differentiated control over conversation initiation drive brand loyalty through specific interface designs. This behavioral segment shows higher lifetime value and lower churn than swipe-based alternatives.
- Algorithmic Transparency Mandates:Evolving AI disclosure requirements in multiple states force explanatory interfaces before match recommendations deploy. Early adopters of interpretable matching logic build trust premiums with commitment-seeking users.
Industry Challenges
- Real-Time Behavioral Signal Processing:Engineering teams must process swipe patterns and message sentiment at scale without latency degradation. Infrastructure investments for sub-second compatibility scoring strain capital allocation priorities.
- Legacy Desktop Migration:Platforms maintaining web-based onboarding flows face user abandonment as smartphone-native behavior dominates. Feature parity between mobile and desktop environments consumes development resources with diminishing returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Online Dating Services Market |
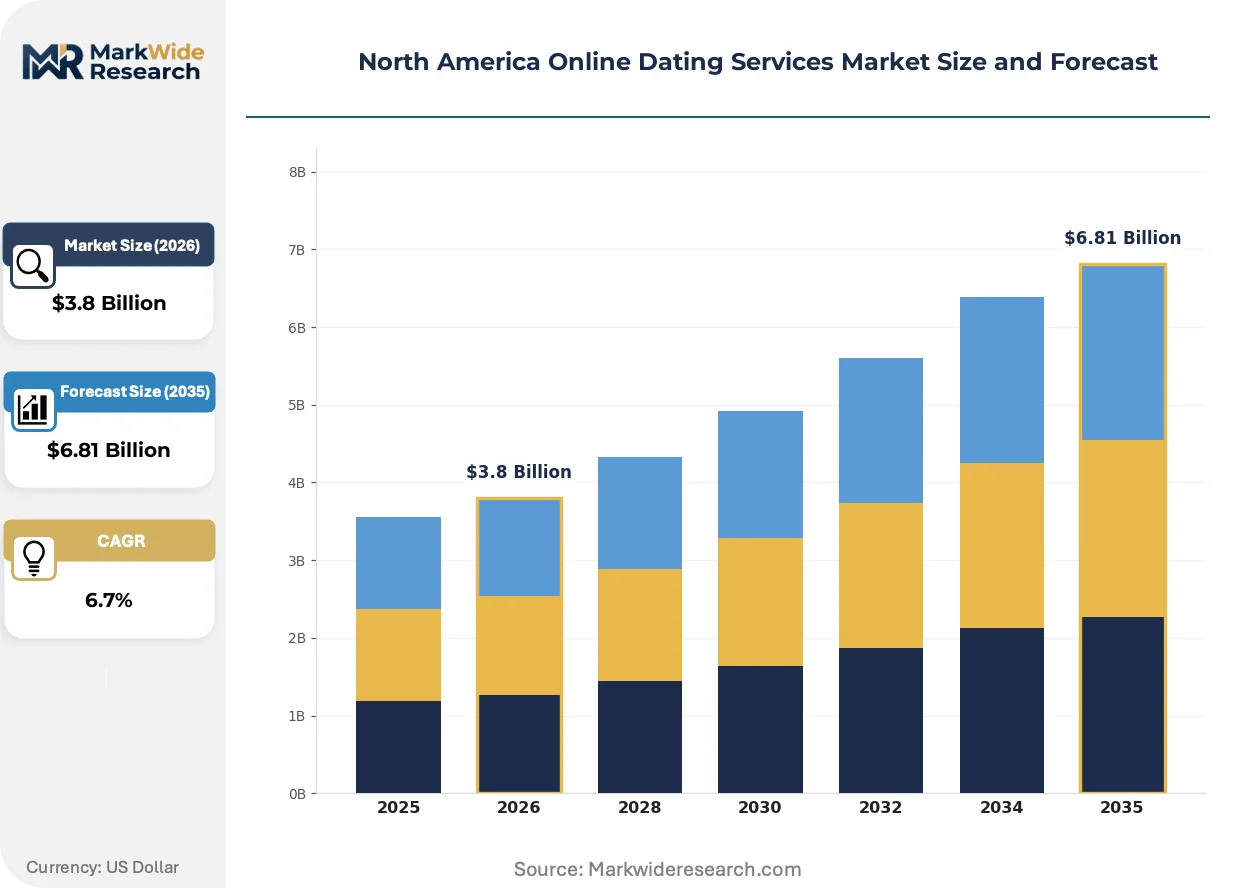
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Apps, Desktop Websites, Matchmaking Services, Niche Platforms Subscription Model: Freemium, Monthly Subscription, One-Time Payment, Premium Access User Demographic: Millennials, Gen Z, Singles, Divorced Individuals Target Audience: LGBTQ+, Professionals, Seniors, Casual Daters |
| Companies Covered | Match Group, Inc., Bumble Inc., eharmony Inc., Zoosk, Inc., Hinge, Plenty of Fish, Grindr LLC, The Meet Group, Inc., Coffee Meets Bagel, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Online Dating Services Market Evolving Landscape
Generative AI is rewriting how platforms construct user profiles and simulate conversation chemistry. Three distinct shifts are compressing competitive timelines across the region.
Large language models are decomposing traditional questionnaire-based profile building. Gen Z users in California and Texas now expect AI-generated icebreakers and dynamic bio suggestions. This capability is decomposing the advantage held by incumbent platforms with legacy static profile architectures.
Canada's Office of the Privacy Commissioner applies PIPEDA principles to cross-border data flows between Toronto engineering teams and US server infrastructure. Platforms must architect explicit consent checkpoints before facial recognition training datasets aggregate. California-based operators face the strictest biometric compliance obligations and have begun segregating Canadian user data in Toronto-region cloud instances.
Commitment-seeking segments now reject swipe-based interfaces in favor of relationship-oriented positioning. Hinge's deliberate design choices attract users who self-identify as seeking long-term partnerships rather than casual connections. This behavioral pivot is most visible among professionals aged 25-34 in Texas metropolitan clusters.
North America Online Dating Services Market Segmentation
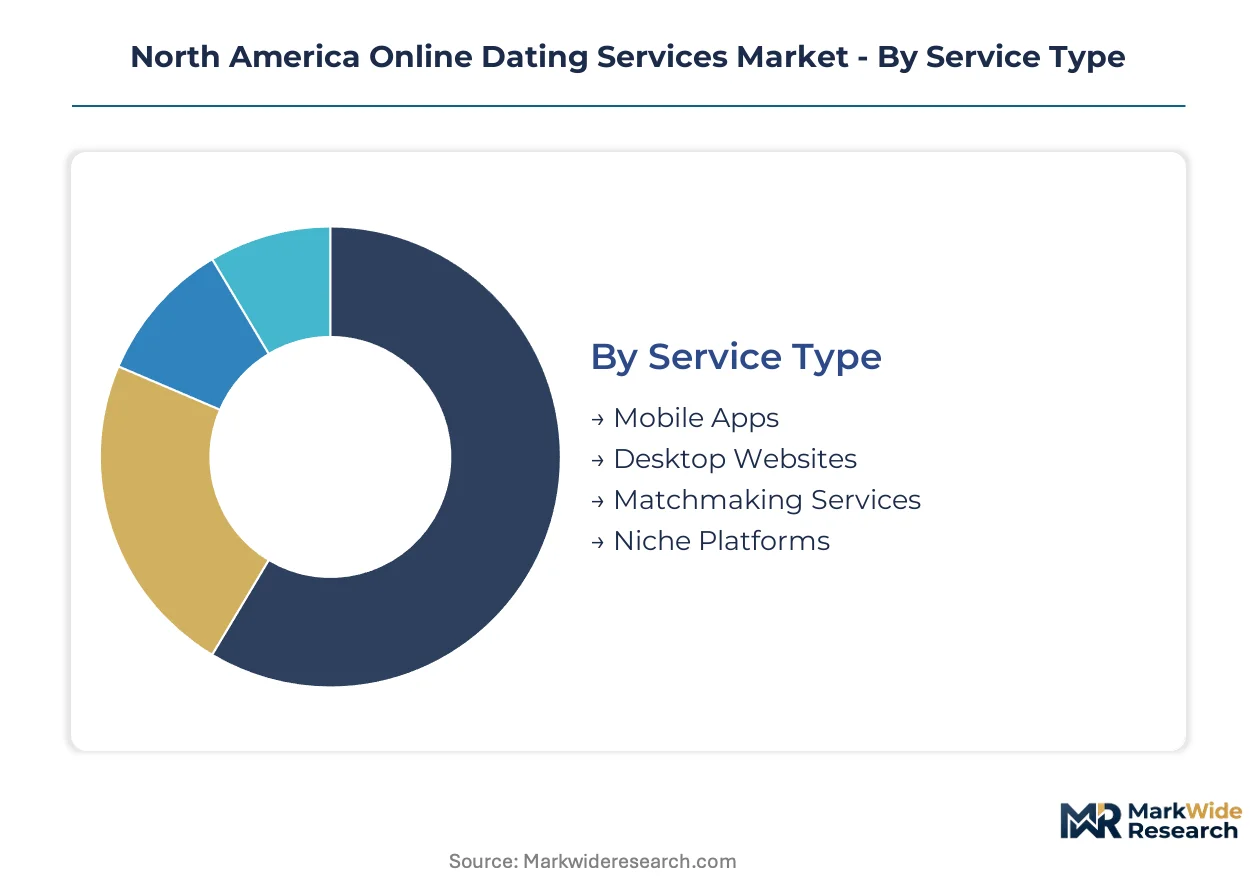
Platform architecture choices determine monetization depth across North America. Subscription model selection and demographic targeting reshape customer lifetime value calculations for operators competing on retention metrics.
Service Type:
Margin pools concentrate in smartphone-native environments where session frequency enables behavioral data accumulation and algorithm refinement.
- Mobile Apps:Native iOS and Android applications process real-time swipe patterns, location signals, and message sentiment through on-device inference engines. California and Texas users generate the highest session density, driving freemium-to-premium conversion through frictionless in-app purchase flows.
- Desktop Websites:Browser-based platforms retain utility for detailed profile construction and extended messaging sessions. Older demographics in Canadian metropolitan areas sustain this channel through preference for larger-screen interaction and reduced notification fatigue.
- Matchmaking Services:Human-curated pairing commands premium pricing through personalized consultation and background verification. Professionals seeking relationship-oriented outcomes absorb higher per-match fees in exchange for reduced screening burden.
- Niche Platforms:Specialized environments serving faith-based, ethnic, or interest-specific communities deploy tailored safety protocols and verification standards. Lower competitive density permits subscription pricing above mass-market alternatives.
Mobile Apps hold installed capacity. Niche Platforms are rotating up the share rankings.
Subscription Model:
Revenue concentration follows the freemium funnel where large user bases subsidize premium extraction from commitment-seeking segments.
- Freemium:Zero-entry-cost onboarding maximizes addressable population capture while gating advanced filters, unlimited swipes, and read receipts behind paywalls. Texas and California operators optimize conversion timing through A/B-tested feature restriction points.
- Monthly Subscription:Recurring billing architectures sustain predictable revenue streams but expose platforms to FTC scrutiny around cancellation flow transparency. Auto-renewal mechanics require explicit consent checkpoints under evolving state biometric and privacy statutes.
- One-Time Payment:Single-transaction models eliminate churn risk while capping per-customer lifetime value. Event-driven purchases—profile boosts, temporary visibility elevation—appeal to episodic users seeking concentrated matching windows.
- Premium Access:Tiered subscription levels bundle priority matching, advanced compatibility analytics, and incognito browsing modes. Professionals demonstrate highest willingness-to-pay for features signaling relationship seriousness.
Freemium holds installed capacity. Premium Access is rotating up the share rankings.
User Demographic:
Behavioral segmentation reveals divergent platform expectations across generational and relationship-status divides.
- Millennials:Users aged 28-43 balance career establishment with partnership formation, sustaining demand for relationship-oriented positioning. This cohort shows highest engagement with video profile features and voice note exchange capabilities.
- Gen Z:Digital-native entrants aged 18-27 expect AI-generated conversation starters and dynamic bio optimization. California and Texas Gen Z users drive adoption of generative profile tools that decompose traditional questionnaire-based onboarding.
- Singles:Never-married individuals represent the largest addressable population, with preferences fragmenting across casual and commitment-seeking intentions. Platform selection correlates with stated relationship goals rather than demographic attributes alone.
- Divorced Individuals:Previously married users prioritize safety verification and transparent intent signaling. Higher average age and established income profiles support premium subscription absorption for features reducing screening friction.
Millennials hold installed capacity. Gen Z is rotating up the share rankings.
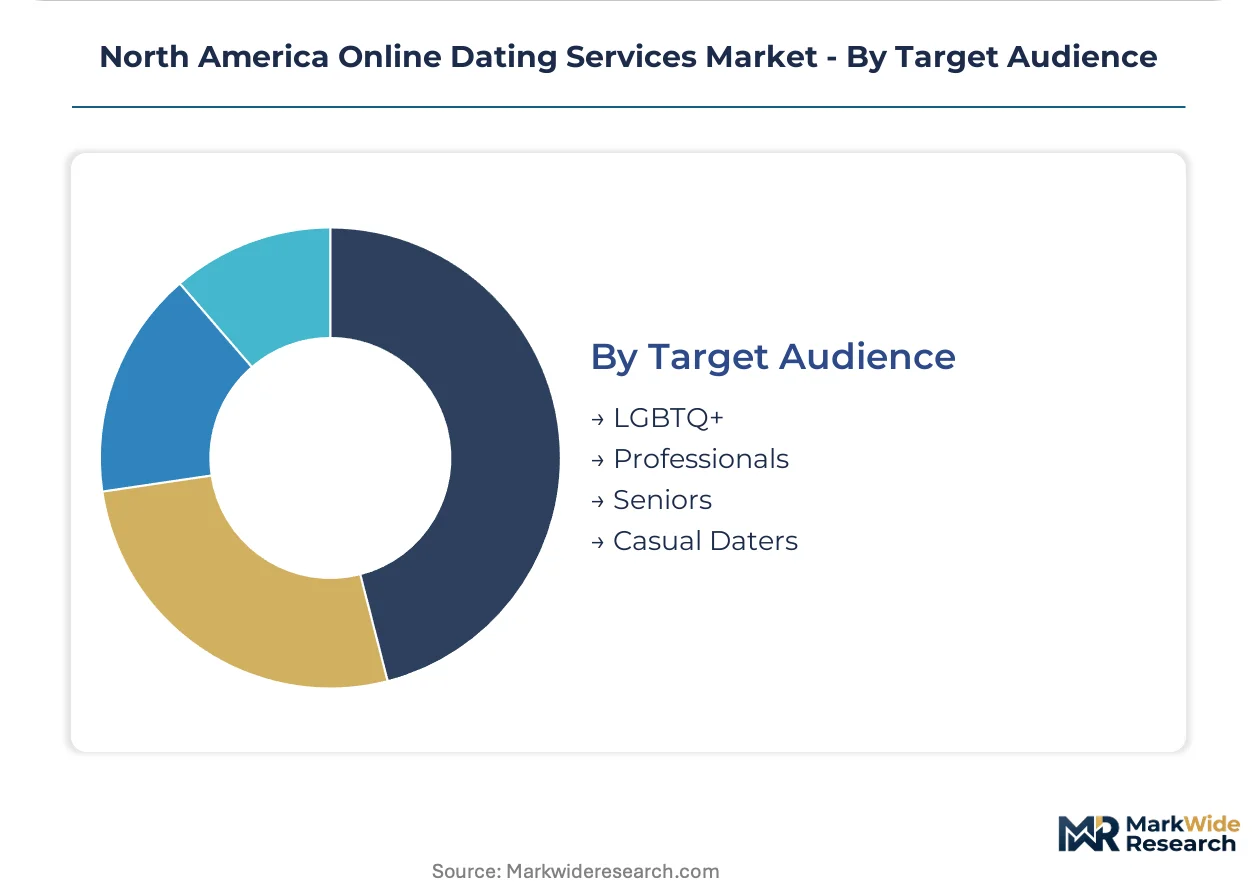
Target Audience:
Specialized safety and community verification requirements create defensible positioning for purpose-built platforms serving historically underserved populations.
- LGBTQ+:Platforms deploy identity-affirming profile options, pronoun display fields, and location-privacy safeguards against outing risks. Toronto-based engineering teams integrate PIPEDA-compliant data architectures with community-specific moderation protocols.
- Professionals:Time-constrained users aged 25-40 absorb premium pricing for efficient matching algorithms and verified credential displays. Texas metropolitan clusters show highest concentration of professionals seeking women-first messaging architectures.
- Seniors:Users over 55 demand simplified interfaces, fraud prevention education, and customer support accessibility. This expanding demographic exhibits lower platform-switching frequency once trust establishes through successful match outcomes.
- Casual Daters:Intent-declared users seeking non-committal connections concentrate in swipe-based mobile environments. Freemium models capture this volume while premium tiers extract limited conversion due to lower relationship investment.
Professionals hold installed capacity. LGBTQ+ is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North America, with United States users driving mobile-first freemium adoption while Canadian operators navigate stricter federal privacy architectures. Mexico's emerging market exhibits distinct platform preferences shaped by payment infrastructure limitations and demographic composition.
United States
California and Texas metropolitan clusters generate the highest session density and freemium-to-premium conversion rates. The FTC enforces explicit consent requirements for subscription billing flows and scrutinizes dark pattern interface designs. San Francisco and Austin engineering hubs concentrate AI talent development for algorithmic matching systems.
Canada
Toronto-based users sustain demand for desktop website platforms alongside mobile adoption, particularly among older demographics. The Office of the Privacy Commissioner applies PIPEDA principles to cross-border data flows between Canadian engineering teams and United States server infrastructure. Montreal and Vancouver operations segregate user data in Toronto-region cloud instances to satisfy federal compliance obligations.
Mexico
Mexico City Metro anchors demand for mobile apps with frictionless registration flows adapted to limited credit card penetration. The national data protection authority enforces consent requirements for biometric data collection under federal privacy law. Guadalajara and Monterrey clusters concentrate platform localization efforts for Spanish-language interface optimization.
North America Online Dating Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with portfolio breadth determining user retention economics across demographic segments. The market exhibits tiered concentration where multi-brand operators leverage shared infrastructure against single-platform specialists competing on feature differentiation. Two strategic archetypes dominate: diversified portfolio companies spanning casual to relationship-oriented positioning, and niche platforms serving identity-specific communities with tailored safety protocols. Competitive moves center on algorithmic transparency investments and biometric compliance architectures that preempt regulatory enforcement.
Within the diversified portfolio tier, Match Group, Inc. and Bumble Inc. occupy positions that exemplify divergent strategic bets on user control architectures. Match Group's multi-brand structure spans swipe-based and relationship-oriented platforms, while Bumble's women-first messaging design anchors brand loyalty among professional demographics. Hinge represents the relationship-oriented specialist archetype, competing directly against casual positioning through deliberate interface choices that attract commitment-seeking users.
| Leading Market Players |
|---|
| Match Group, Inc. |
| Bumble Inc. |
| eharmony Inc. |
| Zoosk, Inc. |
| Hinge |
| Plenty of Fish |
| Grindr LLC |
| The Meet Group, Inc. |
| Coffee Meets Bagel, Inc. |
| Others |
Value Network & Pricing Analysis
Server capacity utilization at hyperscale cloud regions in Virginia and Oregon shapes both infrastructure cost floors and platform pricing power across North America. Scale economics in GPU inference clusters concentrate supply leverage among operators with multi-tenant architectures, compressing per-user algorithmic serving costs while enabling aggressive freemium onboarding.
Pricing Analysis
Subscription billing structures dominate revenue architecture, with auto-renewal contracts capturing predictable cash flows and project-based event purchases serving episodic users. Price differentiation rests on verification tier depth and geographic feature gating, with California users absorbing premium positioning for advanced compatibility analytics. Cost compression in basic matching tiers is intensifying as generative AI tools commoditize profile construction. Casual daters exhibit highest price sensitivity, while commitment-seeking professionals demonstrate lowest elasticity for relationship-oriented positioning.
Supply Chain Analysis
United States and Canada anchor cloud infrastructure deployment, with Toronto-region instances serving PIPEDA-compliant data segregation requirements. Raw material dependencies span NVIDIA GPU allocations, real-time messaging middleware licenses, and biometric processing SDKs. Single-source vulnerability concentrates in facial recognition training dataset pipelines subject to Texas and California consent statutes. Distribution runs through mobile app stores with in-app purchase rails, supplemented by direct web subscription flows for desktop-retained demographics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform fragmentation creates entry niches as generational demand splits between swipe-based casual positioning and relationship-oriented architectures. Incumbents and challengers face divergent imperatives across three stakeholder categories.
For Market Incumbents: Shield core user bases through biometric compliance preemption in Texas and California consent architectures. Consolidate AI engineering talent in Toronto-Vancouver corridors to circumvent PIPEDA cross-border friction. Prioritize interpretable matching logic investments before state disclosure mandates harden. For New Entrants and Emerging Players: Lead with safety-verification protocols in LGBTQ+ and senior demographics where competitive density remains lowest. Target Texas metropolitan professional clusters with women-first messaging differentiation. Deploy Toronto-headquartered operations to capture Canadian federal privacy alignment advantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors niche platforms with defensible community verification standards over mass-market swipe architectures. Five-to-ten year viability hinges on algorithmic transparency trust premiums rather than network scale alone. Watch for FTC enforcement velocity on dark pattern liability as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Compliance Architecture | Preemptive PIPEDA and Texas statute alignment reduces enforcement exposure and accelerates Toronto engineering recruitment. |
| Algorithmic Transparency Interface | Interpretable match explanations build commitment-seeking user trust before state AI disclosure mandates deploy. |
| Niche Platform Acquisition | LGBTQ+ and senior community verification protocols offer lower competitive density with premium pricing absorption. |
| Generative AI Profile Tools | Dynamic bio construction and icebreaker generation decompose legacy questionnaire-based onboarding advantages. |
| Cross-Border Data Segregation | Toronto-region cloud instance deployment satisfies Canadian federal privacy requirements for US-headquartered operators. |
Research Methodology
A spread of perspectives from platform engineering leads, privacy compliance officers, mobile app store partnership managers, and user experience researchers converged on the working assumptions. Primary fieldwork combined structured interviews with Match Group and Bumble product executives, Canadian Office of the Privacy Commissioner policy staff, and Texas Attorney General consumer protection investigators. Secondary validation drew from SEC 10-K filings, FTC enforcement action dockets, PIPEDA compliance guidance, and Sensor Tower mobile analytics. Bottom-up user cohort modeling and top-down addressable population sizing were triangulated against subscription revenue disclosures.
Segmentation dimensions modeled include platform architecture type, subscription model tier, generational demographic cohort, and target audience specialization across the projection horizon. CAGRs were derived from historical conversion rate trajectories and freemium-to-premium upgrade elasticity estimates. Forecast inputs incorporated biometric statute enforcement timelines, GPU inference cost curves, and generative AI capability diffusion rates.
Forecasts assume regulatory continuity in FTC subscription billing scrutiny, California biometric consent enforcement, and PIPEDA cross-border data flow principles; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Document Management System Market
Digital Solutions
Governed Enterprise Architecture Scenario Sandbox Market
Digital Solutions
Community Engagement Software Market
Digital Solutions
Consent Management Market
Digital Solutions
Electronic Document Management System (EDMS) Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Change Management Software Market
Digital Solutions
Physical-Digital Integration Market
Digital Solutions
Digital Experience Technology Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
Global Capacity Management Market
Digital Solutions
Switzerland ICT Market
Digital Solutions
Digital Workplace Market
Digital Solutions
Cloud Electronic Design Automation Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
Digital Shelf Market