
 Heat Treatment Furnace Market | 2026-2036
Heat Treatment Furnace Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Treatment Furnace Market Outlook
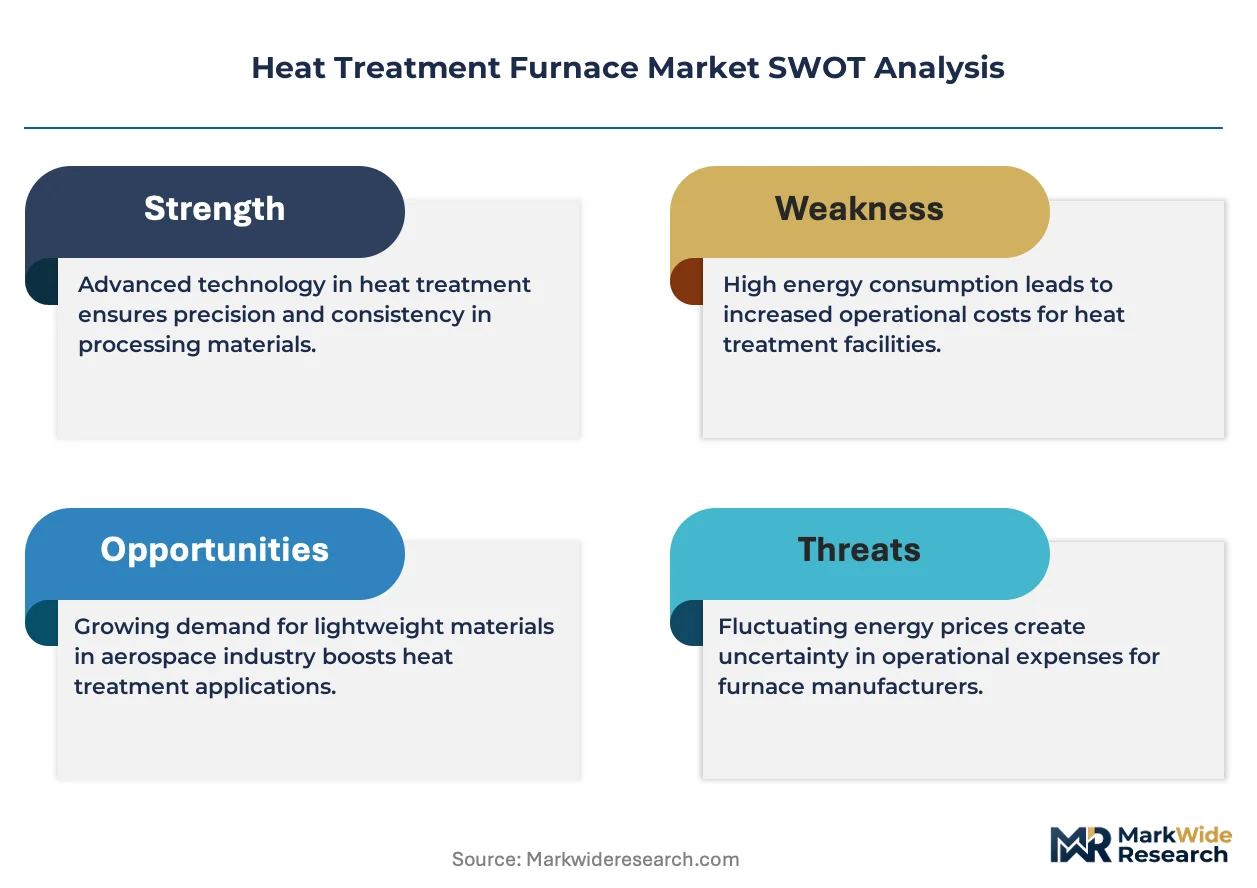
Software-defined thermal profiling and predictive maintenance subscriptions are decoupling equipment sales from pure hardware transactions across the heat treatment furnace landscape. Ipsen USA leverages its North American service infrastructure to anchor long-term aftermarket contracts with automotive heat treaters. Nabertherm GmbH competes through deep specialization in laboratory and production-scale batch furnace architectures. Carbolite Gero Limited sustains premium positioning across European research institutions and aerospace qualification labs.
A heat treatment furnace is a thermally insulated chamber engineered to precisely control temperature, atmosphere, and cooling rates for altering the microstructure of metals and alloys, typically operating from 300°C to over 2,400°C depending on process requirements. Its primary industrial purpose centers on achieving specified mechanical properties—hardness, toughness, wear resistance, or dimensional stability—in finished components across transportation, energy, and tooling sectors. Vacuum furnace systems command the highest margin pools within the product type dimension, driven by stringent atmosphere purity requirements for titanium and nickel superalloy processing. Within end user categories, aerospace qualification protocols are expanding fastest, though metalworking retains the largest installed base of convection and resistance-heated batch systems. Induction heating technology leads operational efficiency metrics for continuous hardening lines serving automotive powertrain manufacturers.
EPA emissions standards and OSHA thermal process safety mandates shape furnace combustion system designs and operator certification requirements across United States installations. REACH compliance and the EU Green Deal's decarbonization benchmarks are accelerating European demand for hydrogen-ready burner retrofits and electric resistance alternatives to gas-fired equipment. Nadcap accreditation requirements from the Performance Review Institute govern aerospace supplier furnace qualifications globally. Stakeholders must monitor evolving carbon border adjustment mechanisms and alloy traceability standards to anticipate which thermal process investments will retain compliance advantage.
Market Dynamics
Software-defined thermal profiling and predictive maintenance subscriptions are decoupling equipment sales from pure hardware transactions, fundamentally restructuring how furnace OEMs capture lifetime value from aerospace and automotive heat treaters.
Growth Catalysts
- EU Green Deal Decarbonization Benchmarks:Hydrogen-ready burner retrofits and electric resistance alternatives gain regulatory tailwinds across German and French installations, accelerating capital deployment in furnace fleet modernization.
- Additive Manufacturing Feedstock Precision:Vacuum furnace demand concentrates in titanium and nickel superalloy processing for powder metallurgy applications, pulling investment toward atmosphere purity systems.
- Nadcap Accreditation Requirements:Aerospace supplier qualification protocols from the Performance Review Institute mandate furnace fleet expansions among North American and European OEMs serving jet engine component programs.
Market Restraints
- High-Purity Refractory Material Costs:Graphite heating elements and molybdenum fixtures face supply concentration from limited specialty metal producers, compressing margins on vacuum furnace configurations.
- Natural Gas Price Volatility:Convection and atmosphere furnace operators in gas-dependent regions absorb input cost swings that erode predictable operating economics for batch heat treaters.
- REACH Compliance Complexity:ECHA substance restrictions on certain quenching oils and salt bath chemistries force formulation changes that delay process qualification timelines.
Strategic Opportunities
- India Industrial Corridor Expansion:PLI scheme incentives for automotive and aerospace component manufacturing create underpenetrated demand for induction hardening lines and batch furnace installations.
- Digital Twin Convergence:Integration of IoT sensor networks with physics-based thermal simulation enables remote process optimization and predictive maintenance service models.
- Carbon Border Adjustment Mechanisms:EU CBAM implementation rewards low-carbon thermal processing investments, favoring electric resistance and hydrogen combustion retrofits in export-oriented heat treaters.
Industry Challenges
- Nadcap Auditor Scarcity:Limited pool of PRI-qualified thermal process auditors extends supplier accreditation timelines, delaying aerospace contract qualification and revenue recognition.
- Legacy Control System Integration:Retrofitting software-defined profiling capabilities onto decades-old furnace architectures requires custom engineering that fragments vendor service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Treatment Furnace Market |
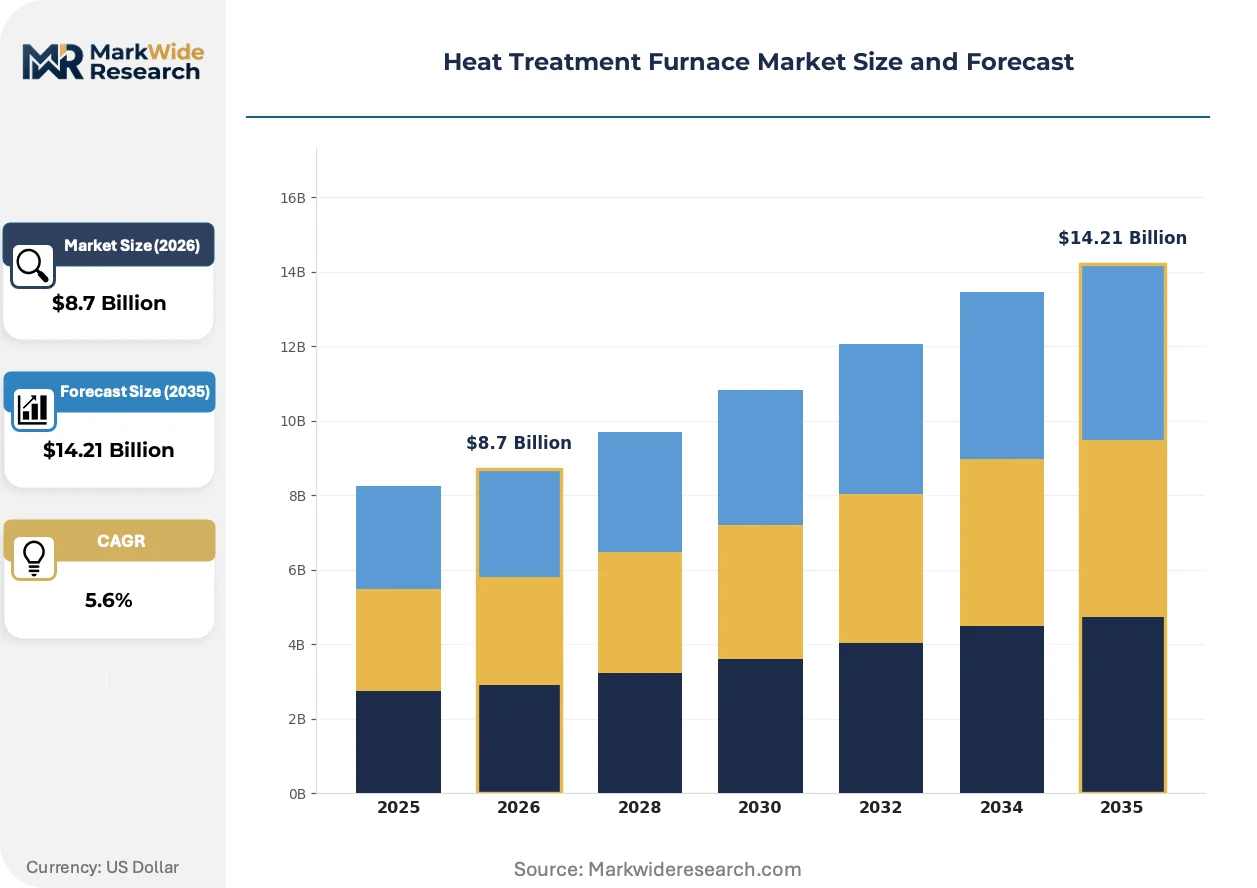
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Furnace, Continuous Furnace, Vacuum Furnace, Induction Furnace End User: Aerospace, Automotive, Manufacturing, Metalworking Technology: Convection Heating, Radiation Heating, Resistance Heating, Induction Heating Application: Hardening, Tempering, Annealing, Stress Relieving |
| Companies Covered | Nabertherm GmbH, Solar Manufacturing, Ipsen USA, MTI Corporation, Sentro Tech Corporation, AFC-Holcroft, Carbolite Gero Limited, Thermo Fisher Scientific, Surface Combustion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Treatment Furnace Market Strategic Shifts
Active thermal process intelligence and connected furnace architectures are compressing the traditional separation between equipment procurement and ongoing process optimization services.
Artificial intelligence-driven thermal profiling is consolidating control over heat treatment variability by embedding machine learning models directly into furnace PLCs. Automotive powertrain manufacturers in Germany and Japan deploy these systems to reduce distortion in gear hardening operations. The technology is consolidating vendor influence over process outcomes, shifting competitive advantage from hardware specifications to algorithmic thermal control expertise.
REACH authorization requirements for chromium-based quenching salts are forcing substitution toward polymer and vegetable-based alternatives across European heat treatment operations. ECHA substance restriction timelines compress reformulation windows for salt bath furnace operators. Nadcap-accredited suppliers in France and Italy face the steepest requalification burdens as they balance compliance against aerospace process stability requirements.
After-sales service unbundling now separates predictive maintenance subscriptions from original equipment purchases, enabling heat treaters to outsource thermal process optimization. Automotive tier-one suppliers in the United States favor this model to reduce in-house metallurgical engineering headcount. The shift is most visible among high-volume continuous furnace operators seeking to convert fixed engineering costs into variable performance-based expenditures.
Heat Treatment Furnace Market Segmentation
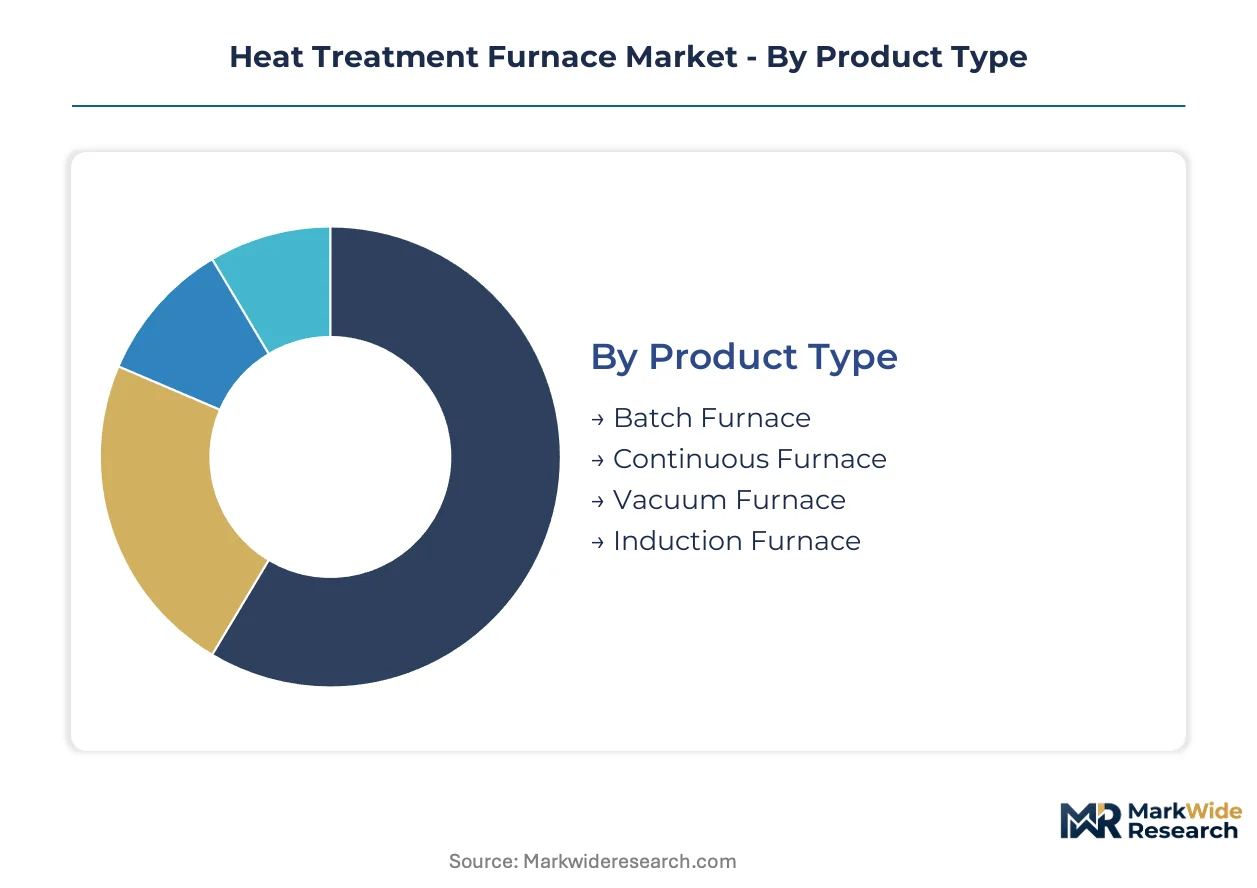
Segmentation in the heat treatment furnace market reflects divergent thermal process requirements across precision-critical industries. Equipment specifications vary dramatically between aerospace qualification protocols and high-volume automotive production lines. Understanding these divisions reveals where capital deployment concentrates and which technology architectures command premium positioning.
Product Type:
The technology axis separates atmosphere-controlled systems from vacuum and electromagnetic alternatives, with margin pools concentrating where atmosphere purity requirements are most stringent.
- Vacuum Furnace:Sealed chamber designs with multi-stage pumping systems achieve pressures below 10^-5 mbar for titanium and nickel superalloy processing. Nadcap-accredited suppliers in Germany, Japan, and the United States deploy these systems for additive manufacturing feedstock production and jet engine component qualification. Atmosphere purity mandates pull investment toward graphite heating element configurations despite refractory material cost pressures.
- Batch Furnace:Insulated chamber systems with programmable thermal cycles accommodate varied load sizes and process recipes across job shop environments. Metalworking operations in France and Italy retain the largest installed base of electrically heated box and pit furnace architectures. Flexibility in handling mixed alloy loads sustains demand despite longer cycle times versus continuous alternatives.
- Continuous Furnace:Conveyor-based systems integrate heating, soaking, and cooling zones for uninterrupted high-volume throughput. Automotive powertrain manufacturers favor pusher and roller hearth designs for gear and shaft hardening lines.
- Induction Furnace:Electromagnetic coil configurations generate rapid, localized heating through eddy current induction for surface hardening applications. Fastener and tooling producers deploy these systems where distortion control is paramount.
Batch furnace architectures lead on installed base scale; vacuum furnace systems lead on momentum as aerospace qualification requirements expand.
End User:
Customer type segmentation tracks capital intensity differences between qualification-driven aerospace programs and cost-optimized automotive volume production.
- Aerospace:OEMs and tier suppliers operate furnace fleets subject to Performance Review Institute audit protocols for jet engine rotating components. Nadcap accreditation mandates in the United States and France drive fleet expansion and control system upgrades. Thermal process data traceability requirements favor vendors offering software-defined profiling capabilities.
- Automotive:Powertrain manufacturers and tier-one suppliers deploy continuous hardening lines for transmission and driveline components. German and Japanese producers prioritize induction systems for distortion-sensitive gear finishing operations. After-sales service unbundling enables conversion of fixed engineering costs to variable performance-based expenditures.
- Metalworking:Job shops and contract heat treaters serve fragmented tooling and component markets with batch furnace flexibility. REACH compliance complexity for quenching chemistries forces reformulation investments across European operations.
- Manufacturing:General industrial producers utilize standard heat treatment cycles for machinery and equipment components. Capital constraints in emerging markets sustain demand for refurbished and retrofitted furnace systems.
Automotive end users lead on equipment volume; aerospace qualification protocols climb the fastest as additive manufacturing feedstock precision requirements intensify.
Technology:
The heating mechanism dimension determines energy efficiency profiles and atmosphere control capabilities across furnace architectures.
- Induction Heating:Electromagnetic energy transfer achieves rapid surface heating with minimal thermal penetration into substrate cores. Automotive gear manufacturers in Germany deploy these systems to reduce distortion in precision hardening operations. Machine learning integration into power supply controls is consolidating vendor influence over process outcomes.
- Resistance Heating:Electric element configurations provide precise temperature control and eliminate combustion emissions for cleanroom-compatible operations. EU Green Deal decarbonization benchmarks accelerate substitution for gas-fired alternatives in French and Dutch installations. Hydrogen-ready burner retrofits compete for capital allocation in mixed-fuel transition strategies.
- Convection Heating:Forced circulation of heated atmosphere ensures temperature uniformity across complex load geometries. Salt bath and fluidized bed variants face REACH authorization pressures for chromium-based chemistries.
- Radiation Heating:Infrared and radiant tube configurations deliver rapid thermal response for continuous processing lines. Ceramic fiber insulation advances reduce heat loss in high-temperature brazing and sintering applications.
Resistance heating leads on regulatory tailwinds; induction heating gains share fastest through distortion control advantages in precision powertrain manufacturing.
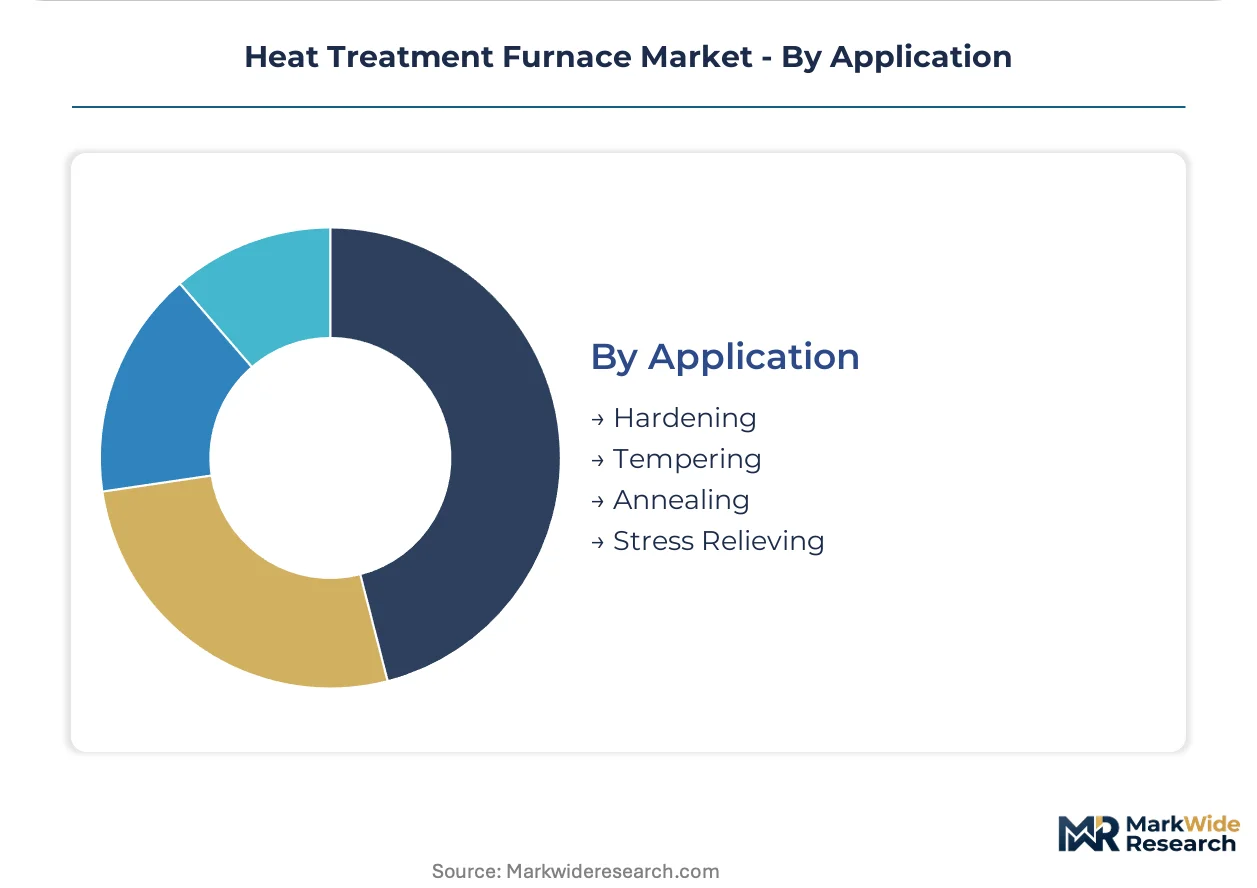
Application:
Process purpose segmentation aligns equipment specifications with metallurgical transformation requirements from surface hardening through microstructure relaxation.
- Hardening:Rapid heating above critical transformation temperatures followed by controlled quenching achieves elevated surface hardness for wear resistance. Automotive transmission gear producers in Japan deploy induction hardening lines with integrated quenching cells for distortion minimization. Process monitoring integration enables real-time adaptive control of heating depth and cooling rate parameters.
- Annealing:Controlled heating and slow cooling cycles soften work-hardened materials and relieve internal stresses from prior forming operations. Aerospace titanium processors in the United States utilize vacuum annealing for contamination-sensitive superalloy feedstocks. Atmosphere purity requirements sustain premium positioning for cold-wall vacuum architectures.
- Tempering:Sub-critical heating after hardening reduces brittleness while retaining sufficient hardness for service conditions. Batch furnace flexibility accommodates varied tempering specifications across job shop environments.
- Stress Relieving:Low-temperature thermal cycles mitigate residual stresses from welding and machining without significant hardness reduction. Heavy equipment manufacturers apply these processes to welded fabrications prior to final machining operations.
Hardening applications lead on equipment utilization intensity; annealing processes expand most quickly through vacuum system deployment for additive manufacturing feedstock qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys vacuum furnace capacity for additive manufacturing feedstock production at triple the intensity of France, while Japan concentrates induction hardening lines for automotive powertrain precision. This divergence shapes capital allocation patterns across major thermal processing markets.
United States
Aerospace OEMs in Ohio and Connecticut expand furnace fleets to satisfy Nadcap accreditation protocols for jet engine rotating components. EPA emissions standards and OSHA thermal process safety mandates shape combustion system designs across Michigan and Texas installations. Cleveland's manufacturing corridor anchors vacuum furnace demand for titanium superalloy processing.
Germany
EU Green Deal decarbonization benchmarks accelerate hydrogen-ready burner retrofits and electric resistance alternatives in Baden-Württemberg and Bavaria. ECHA REACH compliance complexity forces reformulation investments for salt bath chemistries across North Rhine-Westphalia. Stuttgart's automotive cluster deploys AI-driven thermal profiling for gear distortion control.
Japan
Precision metallurgy for powder metallurgy applications concentrates vacuum furnace demand in Nagoya and Osaka industrial zones. METI industrial efficiency standards push machine learning integration into induction power supply controls. Aichi Prefecture's powertrain manufacturers favor continuous hardening lines with adaptive quenching cells.
India
PLI scheme incentives for automotive and aerospace component manufacturing create underpenetrated demand for induction hardening lines in Maharashtra and Tamil Nadu. Central Electricity Authority grid reliability standards influence electric resistance furnace deployment decisions. Pune's industrial corridor attracts batch furnace installations for contract heat treaters.
China
Dual carbon goals and MIIT energy efficiency standards drive furnace fleet modernization in Jiangsu and Guangdong provinces. GB standards for industrial emissions shape combustion system retrofits across the Yangtze River Delta. Shanghai's aerospace suppliers invest in vacuum annealing capacity for contamination-sensitive superalloy feedstocks.
Heat Treatment Furnace Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vacuum furnace configurations concentrating around atmosphere purity specialists while batch furnace demand fragments across regional fabricators. The vendor base organizes into three strategic archetypes: European precision engineering houses, North American aerospace-anchored service integrators, and Asian scale-driven equipment fabricators. Competitive dynamics center on M&A activity consolidating aftermarket service capabilities and geographic expansion into underpenetrated industrial corridors.
Among German precision engineering houses, Nabertherm GmbH and Carbolite Gero Limited exemplify the laboratory-to-production specialization archetype, occupying positions where Nadcap accreditation requirements and research institution relationships sustain premium positioning. Ipsen USA represents the North American service-anchored model, leveraging regional infrastructure for long-term aftermarket contracts. These three entities illustrate how geographic origin and organizational structure correlate with distinct competitive vectors in thermal processing equipment supply.
| Leading Market Players |
|---|
| Nabertherm GmbH |
| Solar Manufacturing |
| Ipsen USA |
| MTI Corporation |
| Sentro Tech Corporation |
| AFC-Holcroft |
| Carbolite Gero Limited |
| Thermo Fisher Scientific |
| Surface Combustion |
| Others |
Value Chain & Pricing Dynamics
Software-defined thermal profiling subscriptions are compressing equipment margins while redistributing value capture toward aftermarket service contracts across aerospace and automotive heat treater accounts. This shift simultaneously elevates graphite heating element and molybdenum fixture costs as vacuum furnace configurations multiply.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for standard batch furnace architectures. Pricing stratifies across Nadcap-accredited vacuum systems, standard industrial batch configurations, and refurbished economy-tier installations. Cost compression in convection-heated equipment is intensifying because natural gas price volatility erodes operating economics for gas-dependent operators. Metalworking job shops exhibit highest price sensitivity; aerospace qualification labs show least sensitivity due to traceability mandates.
Supply Chain Analysis
Dual-sourcing requirements from Nadcap-accredited aerospace suppliers mandate qualified secondary sources for graphite heating elements and molybdenum fixtures. Manufacturing concentrates in Germany, Japan, and the United States for precision vacuum architectures, with China expanding in standard resistance-heated systems. Supply chains draw from limited specialty refractory metal producers for high-purity heating elements. Single-source vulnerability concentrates around isostatic graphite suppliers. Distribution runs through OEM-direct channels for large vacuum systems and regional fabricator networks for batch furnace replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heat treatment furnace market compounds steadily as aerospace qualification protocols and additive manufacturing feedstock precision sustain replacement cycles and fleet expansions.
For Market Incumbents: Anchor aftermarket service contracts through predictive maintenance subscriptions that convert fixed engineering costs to variable performance expenditures. Defend against emerging software-native thermal profiling vendors by deepening captive supply of graphite heating elements and molybdenum fixtures. Prioritize Nadcap auditor training partnerships to compress supplier accreditation timelines and accelerate revenue recognition. For New Entrants and Emerging Players: The price-point gap between European precision vacuum systems and Asian economy batch furnaces creates entry space for mid-tier induction hardening lines with integrated IoT controls. Target India's PLI-subsidized automotive corridors where underpenetrated demand for continuous hardening equipment outpaces qualified local supply. Lead with software-defined thermal profiling as a standalone service to bypass capital-intensive furnace manufacturing. For Investors and Strategic Acquirers: Valuations sit cheapest among regional batch furnace fabricators lacking aftermarket service infrastructure. Long-term viability favors vendors with installed base scale sufficient to support recurring predictive maintenance revenue. Watch Nadcap auditor pool expansion as the signal indicating accelerated aerospace supplier qualification activity and furnace fleet investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refractory Metals | Captive graphite and molybdenum supply secures margin pools on vacuum furnace configurations. |
| Software-Defined Thermal Profiling Launch | AI-driven control systems embed vendor influence directly into aerospace process outcomes. |
| Hydrogen-Ready Burner Retrofit Program | EU Green Deal compliance positions European fabricators for carbon border adjustment advantage. |
| Nadcap Auditor Training Partnership | Performance Review Institute collaboration compresses supplier qualification timelines. |
| India Industrial Corridor Expansion | PLI scheme alignment captures automotive and aerospace component manufacturing demand. |
Study Parameters
Direct dialogue with furnace OEM technical directors, aerospace tier-one supplier procurement heads, automotive powertrain manufacturing engineers, and contract heat treater operations managers grounded qualitative findings. Secondary validation drew from SEC 10-K filings, ECHA REACH substance restriction updates, PRI Nadcap accreditation bulletins, and customs trade data on refractory metal imports. Bottom-up equipment shipment tallies and top-down industrial capital expenditure estimates were triangulated to anchor market sizing.
Segment-level value outputs were generated across product type, end user, heating technology, and application dimensions throughout the forecast period. CAGRs were derived from regression analysis against industrial production indices, aerospace OEM delivery schedules, and additive manufacturing powder metallurgy capacity announcements. Forecast inputs incorporated EU Green Deal implementation timelines, PLI scheme incentive disbursement patterns, and Nadcap auditor pool expansion trajectories.
Caveats apply where ECHA substance restriction accelerations, natural gas price shocks, or Nadcap auditor scarcity could materially shift the outlook. Forecasts reflect documented assumptions on regulatory implementation pace and aerospace production ramp schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Land Surveying Equipment Market
Others
Calcined Petroleum Coke Market
Others
Cat Food Market
Others
Tunnel Lighting Market
Others
Bicycle Panniers Market
Others
Managed Video As a Service Market
Others
Digital Signage Media Player Market
Others
Solar Animal Repellent Market
Others
Dry-Cleaning and Laundry Services Market
Others
Europe Refrigerated Display Cases Market
Others
Global Mobile Video Optimization Market
Others
Global Sports and Fitness Wears Market
Others
Buchner Funnels Market
Others
Rotary Union Market
Others
Super Computer Market
Others
Fresh Durian Market