
 Stock Tanks Market | 2026-2036
Stock Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Stock Tanks Market Analytics
Welder and rotational-molding technician availability is reorganizing production capacity across the stock tanks industry. Behlen Country leverages its Nebraska-based metal fabrication heritage to sustain galvanized steel output for large-scale ranch operations. Norwesco competes through polyethylene tank specialization, dominating the portable and above-ground plastic segments with standardized mold platforms. Centennial Plastics anchors Southwest distribution through regional manufacturing proximity to Texas and Oklahoma agricultural corridors.
Stock tanks are rigid liquid containment vessels, typically fabricated from galvanized steel, rotationally molded polyethylene, or reinforced concrete, designed to provide passive water access for livestock, wildlife, and auxiliary agricultural uses with capacities spanning one hundred to several thousand gallons. Metal tanks withstand hoof impact and UV exposure across decades of outdoor service, while plastic variants offer lighter transport and chemical resistance for treated water applications. Agricultural end users occupy the dominant demand position given cattle and equine herd hydration requirements across rangeland and feedlot operations. The 400-800 gallon capacity band represents the fastest-growing segment as mid-size ranchers standardize around versatile volumes that balance refill frequency with footprint constraints.
The EPA enforces Clean Water Act provisions that affect stock tank placement near navigable waters, while state-level agricultural extension services in Texas and Oklahoma administer voluntary water quality certification programs that influence buyer specifications. USDA conservation cost-share programs periodically subsidize tank installations as part of broader rangeland improvement initiatives, redirecting procurement timing and volume across eligible counties. Stakeholders must monitor drought declaration patterns and federal grazing lease adjustments to anticipate regional replacement cycles and material preference shifts.
Market Dynamics
Welder and rotational-molding technician scarcity is compressing production capacity across the stock tanks industry, forcing manufacturers to reorganize fabrication footprints around available skilled labor pools rather than raw material proximity or transport economics.
Growth Catalysts
- USDA Conservation Cost-Share Programs:Federal rangeland improvement subsidies redirect procurement timing across eligible counties, accelerating tank installations during drought declaration windows.
- Texas Cattle Density:Concentrated livestock operations in the Panhandle and Rolling Plains drive replacement cycles for both galvanized steel and polyethylene containment systems.
- Polyethylene Rotational Molding:Standardized mold platforms enable rapid capacity scaling for portable above-ground tanks serving mid-size ranch operations.
Market Restraints
- Zinc Price Volatility:Galvanized steel fabrication faces input cost pressure from zinc alloy supply fluctuations, squeezing margin on large-diameter metal tanks.
- Nebraska Welder Concentration:Metal fabrication heritage clusters skilled labor in the Midwest, limiting geographic flexibility for steel tank production expansion.
- EPA Stormwater Proximity Rules:Clean Water Act placement restrictions near navigable waters constrain installation options and extend site permitting timelines.
Strategic Opportunities
- Oklahoma Agricultural Corridors:Regional manufacturing proximity gaps in the Southwest create white space for distribution hub establishment serving ranch operations.
- Wildlife Management Applications:State park and conservation district contracts for game water sources represent an emerging application segment beyond traditional livestock use.
- Dual-Material Service Bundles:Convergence of metal and polymer expertise enables single-source containment solutions spanning permanent and portable deployment needs.
Industry Challenges
- Rotational-Molding Technician Pipeline:Specialized polymer fabrication skills require multi-year apprenticeship development, creating hiring bottlenecks during demand surges.
- State Water Quality Certification:Voluntary agricultural extension programs in Texas and Oklahoma impose specification complexity without uniform federal standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stock Tanks Market |
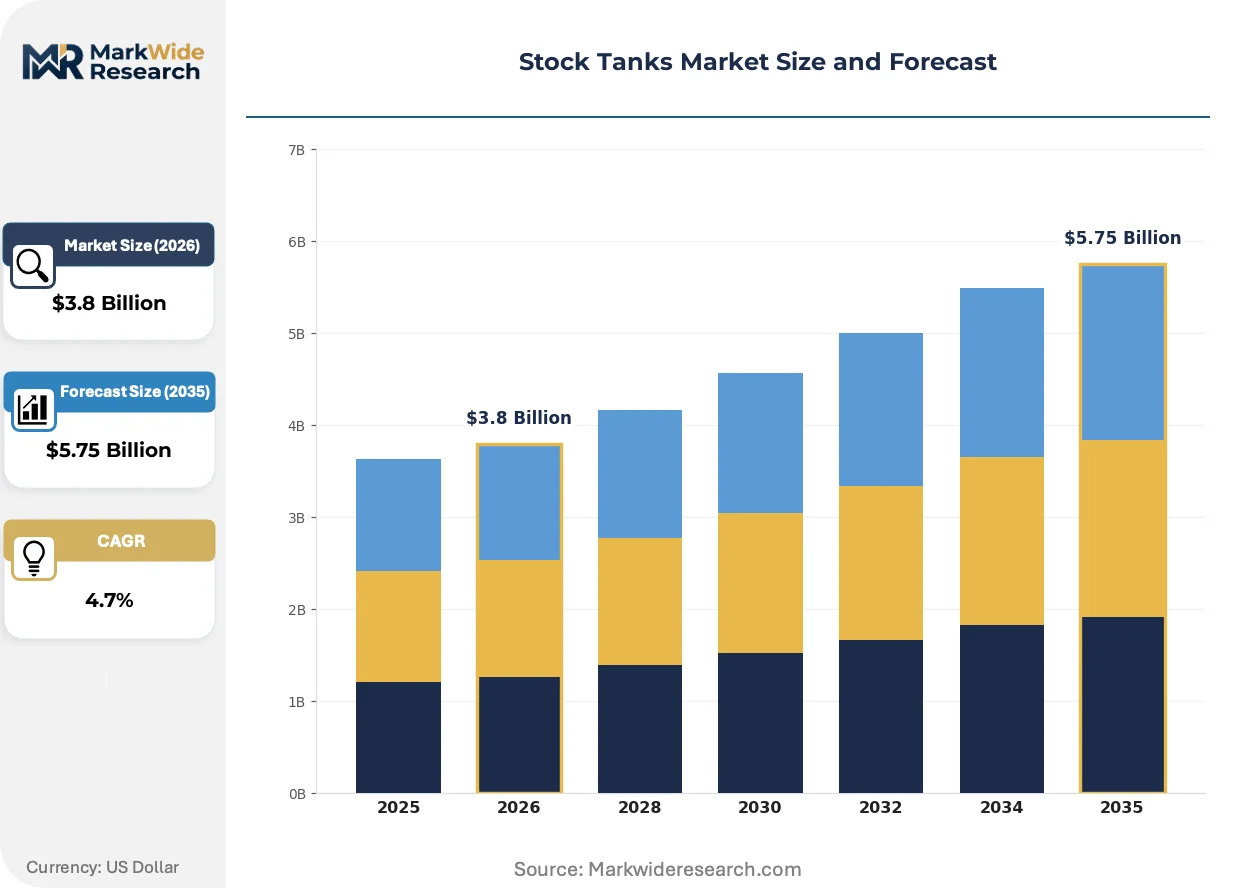
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Tanks, Metal Tanks, Concrete Tanks, Fiberglass Tanks End User: Agricultural, Industrial, Residential, Commercial Capacity: 100-400 Gallons, 400-800 Gallons, 800-1200 Gallons, Above 1200 Gallons Installation: Above Ground, In Ground, Semi-In Ground, Portable |
| Companies Covered | Behlen Country, Tractor Supply Company, Stock Tank Pool Company, Utility Tank Company, Superior Plastic Products, Norwesco, Higgin Botham, Western Steel & Tank, Centennial Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stock Tanks Market Evolving Landscape
Material science advances and regulatory pressure on stormwater containment are compressing traditional fabrication methods while opening modular deployment architectures. Three developments merit particular attention.
UV-stabilized polyethylene formulation is miniaturizing tank wall thicknesses without sacrificing impact resistance. Mid-size ranchers in drought-prone counties are adopting these lighter vessels for rapid relocation between pasture rotations. The technology is miniaturizing transport logistics, reducing freight costs and enabling direct-to-ranch distribution models previously uneconomical for metal alternatives.
EPA revised stormwater management guidelines are mandating corrosion-resistant materials and sealed containment designs for installations near drainage channels. Manufacturers serving the agricultural sector must retool fabrication lines to meet revised specification thresholds. Texas and Oklahoma extension services are accelerating voluntary certification adoption as buyers anticipate federal enforcement expansion.
Direct procurement from regional manufacturing facilities is displacing traditional distributor intermediaries for large-volume ranch orders. Feedlot operators in the Texas Panhandle now negotiate tank specifications directly with fabrication plants, unbundling after-sales service contracts. This channel compression is most visible in the 400-800 gallon capacity band where standardized configurations reduce specification complexity.
Stock Tanks Market Segmentation
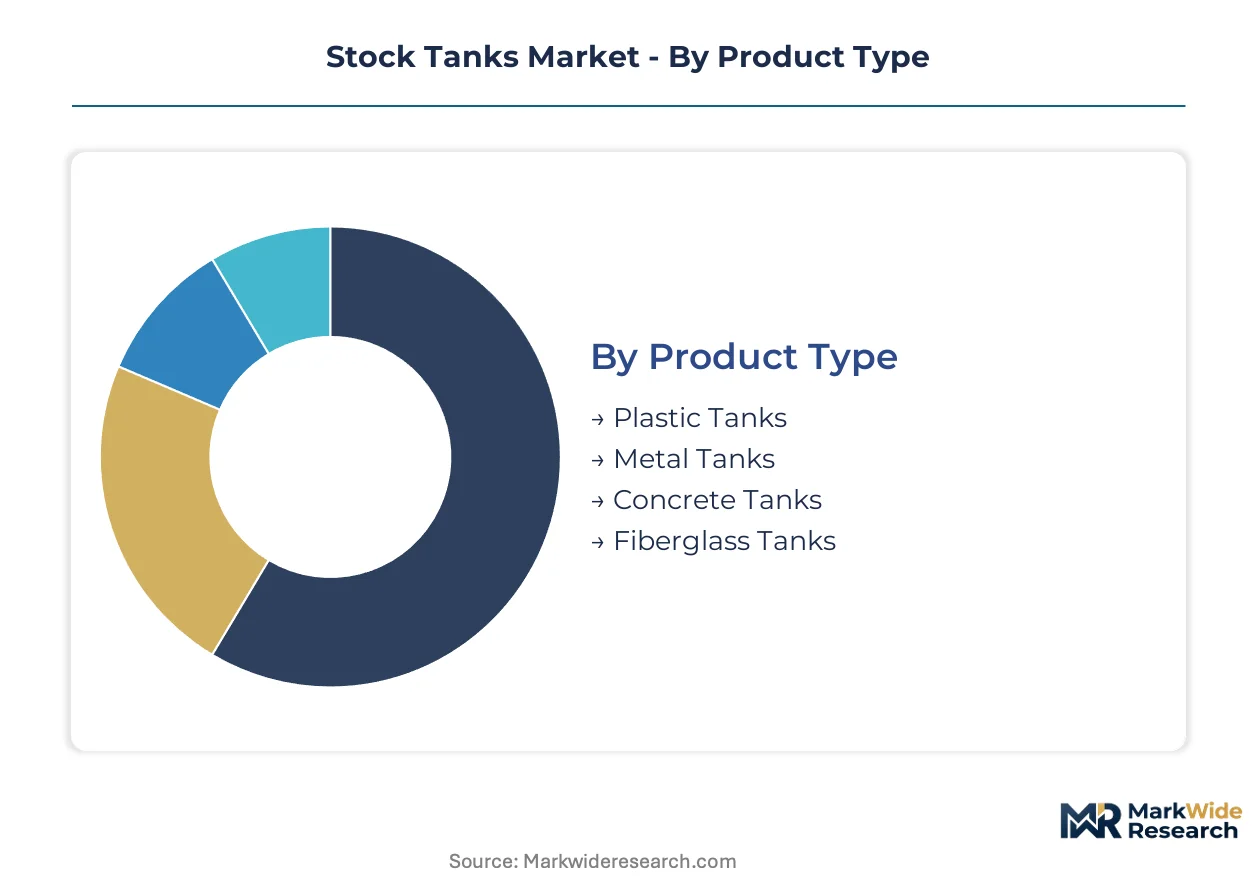
Stock tank procurement patterns diverge sharply across material specifications, end-use applications, and deployment configurations. Ranchers prioritize durability and mobility trade-offs, while industrial buyers emphasize chemical resistance and regulatory compliance. Understanding these segment boundaries clarifies where manufacturers must align fabrication capabilities with buyer specification clusters.
Product Type:
Margin pools concentrate in polyethylene rotational molding, where standardized mold platforms enable rapid capacity scaling without skilled welder dependency.
- Plastic Tanks:UV-stabilized polyethylene formulations miniaturize wall thicknesses without sacrificing impact resistance. Demand concentrates among mid-size ranchers in drought-prone Texas counties adopting rapid pasture rotation strategies, with lighter vessels reducing freight costs and enabling direct-to-ranch distribution.
- Metal Tanks:Galvanized steel fabrication withstands decades of hoof impact and UV exposure across outdoor service. Large-scale ranch operations in Nebraska and the Texas Panhandle specify these for permanent installations, though zinc price volatility squeezes margins on large-diameter configurations.
- Concrete Tanks:Reinforced concrete delivers maximum durability for fixed industrial and agricultural containment. Municipal water districts and feedlot operators specify these for high-capacity permanent installations where relocation is never required.
- Fiberglass Tanks:Corrosion-resistant composite construction serves chemical storage and specialized industrial applications. Wastewater treatment facilities and chemical processing plants specify these where polyethylene chemical resistance proves insufficient.
Metal tanks hold installed capacity across decades of ranch infrastructure. Plastic tanks are rotating up the share rankings as rotational-molding capacity expands and transport economics shift.
End User:
Volume concentration follows cattle density maps, with agricultural procurement cycles tied to USDA conservation program windows and drought declaration timing.
- Agricultural:Cattle and equine herd hydration requirements dominate demand across rangeland and feedlot operations. Texas and Oklahoma ranchers drive replacement cycles for both galvanized steel and polyethylene systems, with procurement timing accelerating during federal cost-share program eligibility periods.
- Industrial:Manufacturing and processing facilities require chemical-resistant containment for process water and treatment applications. EPA stormwater proximity rules constrain installation options near navigable waters, extending site permitting timelines.
- Residential:Rural property owners and hobby farms specify smaller-capacity tanks for limited livestock and landscaping irrigation. Direct procurement from regional manufacturing facilities is displacing traditional distributor intermediaries for these orders.
- Commercial:Equestrian centers, veterinary facilities, and agricultural service businesses require standardized configurations for professional operations. The 400-800 gallon capacity band dominates this segment as standardized specifications reduce procurement complexity.
Agricultural end users anchor procurement volume through federal program cycles. Commercial buyers are climbing the fastest as professional service businesses standardize containment infrastructure.
Capacity:
Mid-size configurations balance refill frequency against footprint constraints, capturing the most dynamic specification activity across ranch operations.
- 100-400 Gallons:Compact vessels serve hobby farms, wildlife water stations, and auxiliary agricultural uses. State park and conservation district contracts for game water sources concentrate demand in this band.
- 400-800 Gallons:Versatile volumes standardize around mid-size rancher requirements, balancing labor efficiency with spatial constraints. This band exhibits the steepest expansion trajectory as Texas Panhandle feedlot operators negotiate direct specifications with fabrication plants.
- 800-1200 Gallons:Large-scale ranch operations and commercial equestrian facilities specify these for reduced refill labor. Nebraska metal fabrication heritage clusters serve this capacity tier with galvanized steel output.
- Above 1200 Gallons:Maximum capacity configurations serve feedlot operations and municipal water districts requiring bulk containment. Reinforced concrete and heavy-gauge steel dominate this tier where permanent installation is assumed.
800-1200 gallon configurations hold installed capacity across established ranch infrastructure. The 400-800 gallon band is gaining share fastest as channel compression and standardized procurement reshape buyer behavior.
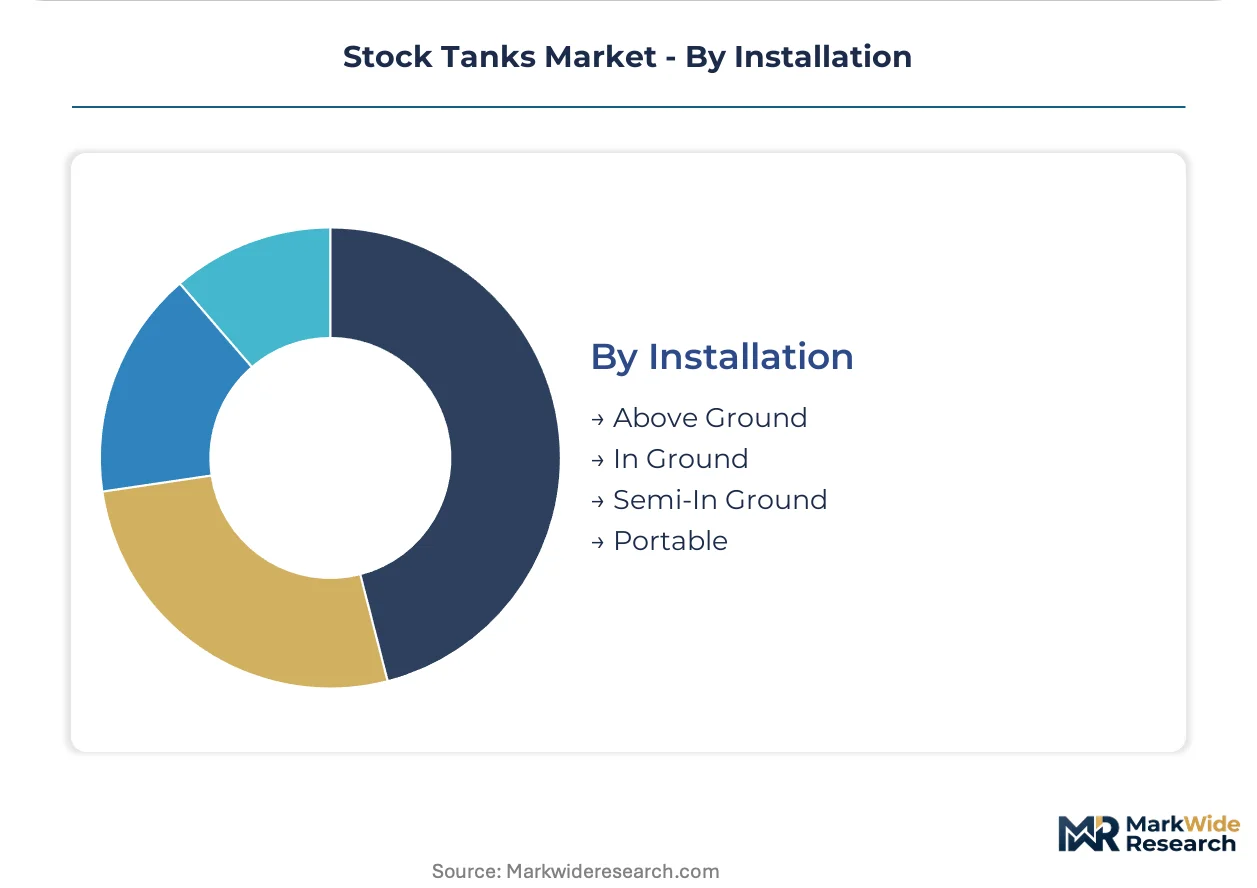
Installation:
Deployment architecture determines material suitability and regulatory exposure, with above-ground portable systems commanding premium positioning for flexibility.
- Above Ground:Elevated placement enables gravity-fed distribution and simplified maintenance access across all material types. Polyethylene variants dominate this category for portable above-ground applications serving pasture rotation strategies.
- In Ground:Buried installation minimizes footprint and freeze protection requirements for permanent agricultural and residential use. Concrete and fiberglass specifications concentrate here where soil contact and structural load-bearing are primary concerns.
- Semi-In Ground:Partial burial reduces excavation costs while maintaining some accessibility for maintenance. This hybrid approach serves commercial equestrian facilities and rural residential properties with aesthetic and practical constraints.
- Portable:Rapid relocation capability enables drought-responsive pasture management and emergency water deployment. Lighter polyethylene formulations and standardized mold platforms are expanding capacity for this segment across Southwest manufacturing proximity.
Above-ground installations hold installed capacity across existing ranch infrastructure. Portable configurations are climbing the fastest as UV-stabilized polyethylene miniaturization reduces transport logistics costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA stormwater management guidelines and USDA conservation cost-share programs anchor demand concentration in the United States, with secondary markets emerging in Canada, Australia, Brazil, and Germany where livestock operations and agricultural extension services drive comparable procurement cycles.
United States
Texas cattle density and Panhandle feedlot operations generate replacement cycles for galvanized steel and polyethylene containment systems. USDA conservation cost-share programs redirect procurement timing across eligible counties during drought declaration windows. Nebraska metal fabrication heritage clusters sustain Behlen Country's galvanized steel output for large-scale ranch operations.
Canada
Prairie province ranchers in Alberta and Saskatchewan specify durable containment for extensive beef operations across cold climate ranges. Environment and Climate Change Canada guidelines influence material specifications for installations near navigable waters. Ontario rotational-molding capacity serves eastern agricultural corridors with standardized polyethylene platforms.
Australia
Queensland and New South Wales cattle stations drive demand for UV-stabilized polyethylene tanks across drought-prone rangeland. The Department of Agriculture, Water and the Environment administers water infrastructure subsidies that accelerate installation timelines during dry periods. Regional manufacturing proximity in Victoria supports distribution to southeastern pastoral zones.
Brazil
Mato Grosso and Goiás ranching operations expand tank deployments to support herd hydration across expanding pasture frontiers. MAPA (Ministry of Agriculture, Livestock and Food Supply) rural credit programs influence procurement timing for agricultural infrastructure investments. São Paulo state rotational-molding capacity supplies standardized vessels to southeastern commercial livestock operations.
Germany
Bavarian and Lower Saxony dairy operations specify corrosion-resistant containment for intensive livestock facilities. REACH regulations and EU environmental standards shape material compliance requirements for agricultural water systems. North Rhine-Westphalia metal fabrication clusters serve central European distribution through established steelworking heritage.
Stock Tanks Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with metal fabrication heritage and rotational-molding capacity defining competitive boundaries. The market structure concentrates around Nebraska-based steelworking tradition and Southwest polyethylene specialization, creating geographic capability clusters that resist rapid replication. Three archetypes dominate: galvanized steel fabricators with ranch-scale heritage, rotational-molding specialists with standardized mold platforms, and regional distributors anchoring proximity to Texas-Oklahoma agricultural corridors. Competitive moves center on direct procurement channel compression and dual-material service bundling that spans permanent and portable deployment needs.
Within the metal fabrication tier, Behlen Country exemplifies integrated steelworking heritage, while Norwesco occupies a position as a polyethylene rotational-molding specialist with standardized platform scale. Centennial Plastics represents regional manufacturing proximity strategy, anchoring Southwest distribution through Oklahoma-Texas corridor positioning. These three companies illustrate how capability scarcity in welder and technician pools constrains competitive entry and reinforces established geographic production clusters.
| Leading Market Players |
|---|
| Behlen Country |
| Tractor Supply Company |
| Stock Tank Pool Company |
| Utility Tank Company |
| Superior Plastic Products |
| Norwesco |
| Higgin Botham |
| Western Steel & Tank |
| Centennial Plastics |
| Others |
Value Network & Pricing Analysis
Polyethylene's displacement of galvanized steel in mid-capacity ranch applications simultaneously shifts production gravity toward Southwest rotational-molding clusters and compresses price premiums previously commanded by Midwest metal fabrication heritage. This substitution dynamic redraws both supply geography and buyer economics across the stock tanks industry.
Pricing Analysis
Texas Panhandle feedlot operators pay freight-adjusted premiums for Nebraska-fabricated galvanized steel tanks, while Oklahoma-proximate polyethylene vessels trade at delivered-cost parity through direct procurement channels. Three-tier pricing structure across premium metal, standard polymer, and economy concrete levels segments buyers by durability requirements and relocation frequency. Price differentiation hinges on zinc alloy input costs and rotational-mold platform standardization, with zinc volatility squeezing margins on large-diameter steel configurations. Mid-size ranchers in drought-prone counties exhibit highest price sensitivity, prioritizing transport economics over decades-long service life.
Supply Chain Analysis
Strategic stockpiling of UV-stabilized polyethylene resin dominates inventory strategy ahead of Texas drought declaration windows, while galvanized steel coil procurement follows just-in-time rhythms tied to Nebraska welder availability. Manufacturing concentrates in the United States, with secondary capacity in Canada and Australia serving comparable agricultural extension programs. Raw material dependencies span zinc alloy feedstock, polyethylene resin grades, and rotational-mold tooling fabrication. Single-source vulnerability clusters around Nebraska-based welder pools for metal tank output. Distribution runs through direct-to-ranch channels for large-volume orders, with regional distributors retaining relevance for smaller commercial and residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stock tanks market sits in early-cycle expansion as USDA conservation cost-share programs accelerate penetration among mid-size ranchers previously reliant on improvised water sources. Federal rangeland improvement subsidies create a durable adoption tailwind across eligible Texas and Oklahoma counties.
For Market Incumbents: Consolidate rotational-molding technician pipelines through apprenticeship partnerships with Oklahoma technical colleges, securing capacity scaling flexibility absent from competitor footprints. Lock in multi-year zinc supply contracts to buffer margin compression from alloy price volatility threatening large-diameter steel tank profitability. Channel control through direct procurement platform investments defends position against distributor disintermediation accelerating in the 400-800 gallon band. For New Entrants and Emerging Players: Anchor in Oklahoma agricultural corridor distribution gaps, where regional manufacturing proximity to Texas Panhandle feedlot operators remains underserved by incumbent Southwest footprints. Target wildlife management applications as the most penetrable expansion segment beyond traditional livestock use, leveraging state park and conservation district contract pipelines. Pursue dual-material service bundling as the go-to-market angle, converging metal and polymer expertise to capture single-source procurement preferences among mid-size ranchers standardizing containment infrastructure. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors rotational-molding specialists with standardized mold platforms and captive technician development pipelines. Long-term viability over the coming decade rests on regulatory alignment with EPA stormwater proximity enforcement expansion and drought-responsive federal program cycles. Acquisition target archetype: regional manufacturers with Southwest distribution proximity and uncommitted polyethylene capacity. The signal to watch is Texas extension service voluntary certification adoption rates as a leading indicator of specification complexity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Pipeline Development | Apprenticeship partnerships with Oklahoma technical colleges secure rotational-molding capacity scaling flexibility absent from competitor footprints. |
| Direct Procurement Platform Investment | Channel compression in the 400-800 gallon band enables feedlot operator relationships previously intermediated by distributors. |
| Dual-Material Service Bundling | Convergence of metal and polymer expertise captures single-source procurement preferences among standardizing mid-size ranchers. |
| Wildlife Management Application Expansion | State park and conservation district contracts for game water sources open penetration beyond traditional livestock demand concentration. |
| Zinc Supply Contract Structuring | Multi-year alloy feedstock commitments buffer margin compression threatening large-diameter galvanized steel tank profitability. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ranch operations managers, feedlot procurement leads, rotational-molding plant supervisors, USDA extension service coordinators, and distributor sales heads. Secondary validation drew from EPA stormwater guidance documents, USDA conservation program enrollment data, Texas and Oklahoma agricultural extension specifications, customs records for polyethylene resin imports, and SEC filings from publicly traded materials suppliers. Bottom-up tank shipment estimates triangulated against top-down agricultural water infrastructure spending patterns.
Across the analysis window, volume and value outputs reflect segmented modeling across material type, end-user category, capacity band, and installation configuration dimensions. CAGRs were derived from historical shipment trajectories adjusted for federal program cycle timing and drought declaration frequency. Industry-specific forecast inputs include rotational-molding technician graduation rates from regional technical colleges and zinc alloy futures curve positioning.
Material uncertainties — drought declaration pattern shifts, EPA enforcement intensity revisions, and rotational-molding technician pipeline disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about federal conservation program continuity and polyethylene resin supply stability. Revision becomes warranted when USDA cost-share eligibility thresholds or EPA stormwater proximity rule enforcement intensity crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
Gardening Tools Market
Agricultural Equipment
Bulk Reception Feeder Market
Agricultural Equipment
Pond Aeration System Market
Agricultural Equipment
Global Fishing Equipments Market
Agricultural Equipment
Solar Insect Trap Market
Agricultural Equipment
Irrigation Syringe Market
Agricultural Equipment
Tree Transplanters Market
Agricultural Equipment
Agriculture Evaporative Cooling Pad Market
Agricultural Equipment
Bean Harvester Market
Agricultural Equipment
Soil Testing Equipment Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Grain Mill Grinder Market
Agricultural Equipment
Floating Covers Market
Agricultural Equipment
Horse Drawn Farming Equipment Market