
 Agriculture Evaporative Cooling Pad Market | 2026-2036
Agriculture Evaporative Cooling Pad Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Evaporative Cooling Pad Market Insights
Large-scale poultry integrators are reorganizing demand away from smallholder dairy installations toward climate-controlled broiler houses. Munters sustains technology leadership through proprietary wet-media engineering and global distribution reach. J&D Manufacturing anchors North American supply with heavy-gauge housing and direct-to-farm channel control. Kuul Evaporative Cooling differentiates on cooling-efficiency ratings and modular replacement-pad programs for retrofit cycles.
Agriculture evaporative cooling pads are engineered wet-media heat exchangers, typically constructed from cross-corrugated cellulose paper impregnated with wet-strength resins and soluble salts, that reduce inlet air temperature through water evaporation while increasing relative humidity for livestock and crop environments. Cellulose pads dominate installed base due to superior saturation efficiency and biodegradable end-of-life handling, though plastic variants are gaining share in high-alkalinity water zones where mineral scaling degrades organic fiber. Permanent installations command the largest revenue pool across dairy and greenhouse segments, while modular systems represent the fastest-growing installation category as rental-service models penetrate seasonal horticulture operators.
USDA ventilation guidelines under the Animal Welfare Act, EPA Clean Water Act discharge permits for pad runoff, and OSHA heat-illness prevention standards collectively shape product specifications and farm compliance spending. California's Cal/OSHA indoor heat standard and the EU F-Gas Regulation restricting synthetic refrigerants are accelerating evaporative cooling substitution in controlled-environment agriculture. Stakeholders must monitor evolving state-level heat-stress thresholds and water-use restrictions that will determine pad-material selection and system sizing decisions.
Market Dynamics
Poultry integrators are consolidating procurement around cellulose-based wet-media systems as USDA biosecurity ventilation mandates tighten and state heat-stress ordinances multiply. This structural pull from large-scale livestock operators is compressing margins for legacy plastic-pad suppliers while elevating specification complexity across the supply base.
Growth Catalysts
- Cal/OSHA Indoor Heat Standard:California's workplace temperature limits force broiler and dairy operators to upgrade ventilation systems, directly expanding specification-grade pad demand in the Central Valley corridor.
- Cellulose Saturation Efficiency:Cross-corrugated paper media with wet-strength resin impregnation delivers superior evaporative performance versus plastic alternatives, driving replacement cycles in high-value greenhouse clusters.
- EU F-Gas Phase-Down:Synthetic refrigerant restrictions under the EU regulation accelerate evaporative cooling substitution in Dutch and Spanish controlled-environment agriculture facilities.
Market Restraints
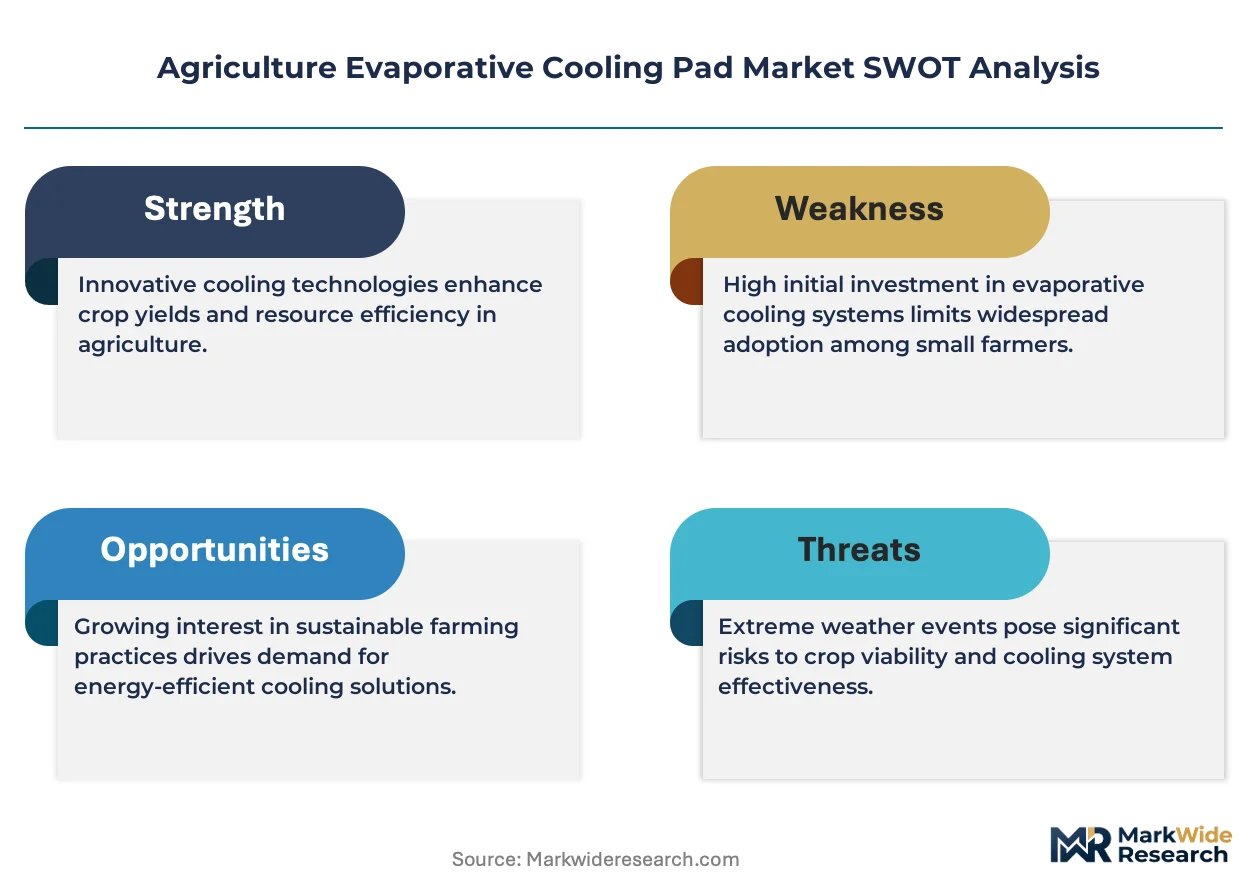
- Pulp Fiber Cost Volatility:Kraft cellulose feedstock prices fluctuate with global paper commodity cycles, compressing pad manufacturer margins during supply tightness.
- Water Chemistry Limitations:High-alkalinity groundwater in parts of the US Southwest and Middle East accelerates mineral scaling on cellulose fibers, forcing premature replacement or plastic-pad substitution.
- Installation Labor Concentration:Skilled HVAC-agriculture crossover technicians cluster in California, the Netherlands, and São Paulo state, creating service bottlenecks for remote farm deployments.
Strategic Opportunities
- Seasonal Horticulture Rental Models:Modular evaporative cooling systems deployed on short-term leases capture margin from Mediterranean and Australian growers with intermittent cooling needs.
- Retrofit Replacement Cycles:First-generation pad installations from the 2010s approach end-of-life simultaneously across California's San Joaquin Valley, creating concentrated demand windows for upgrade-ready suppliers.
- Sensor-Integrated Smart Pads:Convergence of IoT moisture sensors with variable-speed pump controls enables predictive maintenance contracts and recurring revenue streams.
Industry Challenges
- Cross-Disciplinary Installation Expertise:Agricultural evaporative cooling requires technicians fluent in both livestock ventilation biology and mechanical HVAC sizing, a skill combination that training programs have not scaled.
- Runoff Discharge Permitting:EPA Clean Water Act pad effluent regulations vary by watershed, forcing distributors to maintain jurisdiction-specific compliance documentation that delays project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Evaporative Cooling Pad Market |
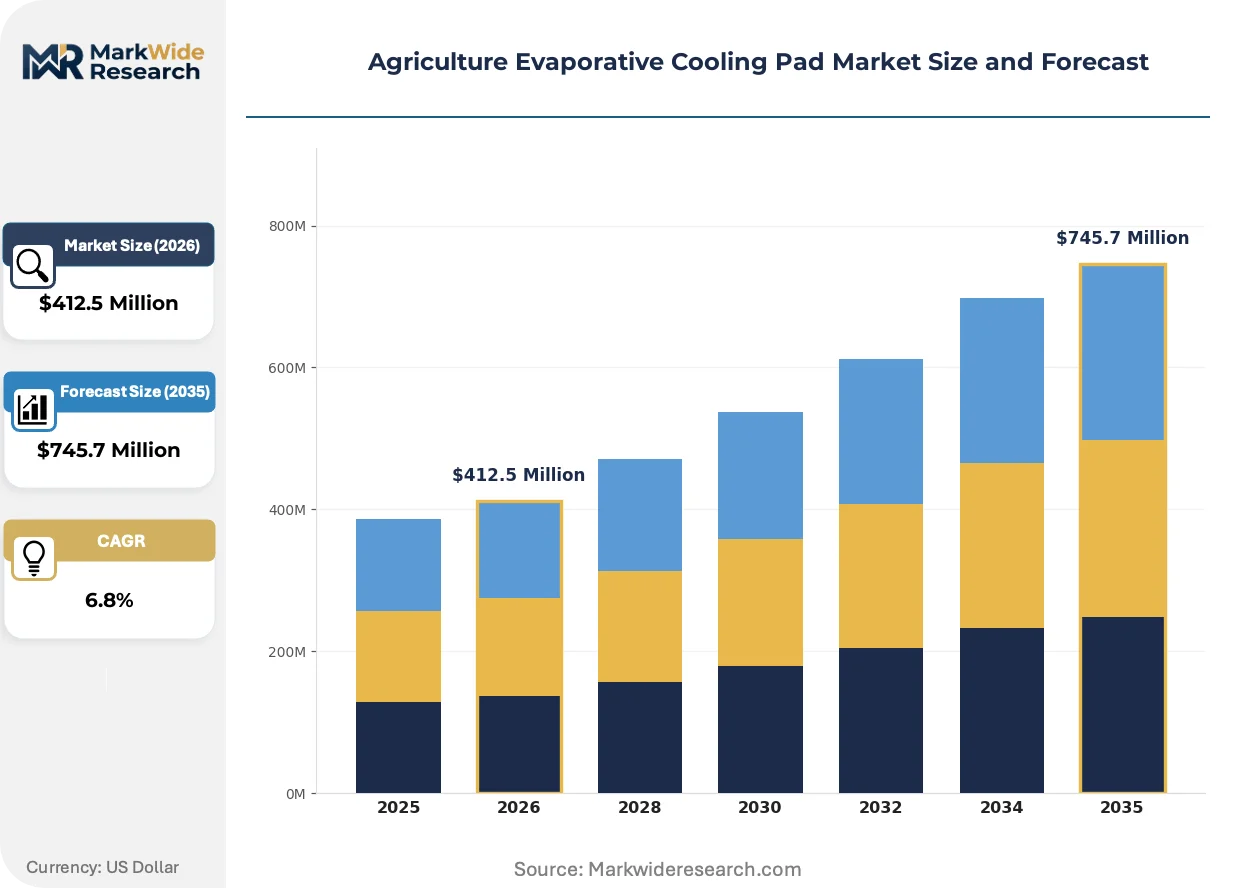
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose, Plastic, Metal, Composite End Use Industry: Dairy Farms, Poultry Farms, Greenhouses, Horticulture Cooling Efficiency: High Efficiency, Medium Efficiency, Low Efficiency, Adjustable Installation Type: Permanent, Temporary, Modular, Customizable |
| Companies Covered | J&D Manufacturing, Plasson Ltd, Munters, Kuul Evaporative Cooling, Idromeccanica Lucchini, Abbi-Aerotech, Portacool Evaporative Coolers, Phoenix Manufacturing, Automated Production Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Evaporative Cooling Pad Market Trends and Innovations
Material science advances and regulatory pressure on synthetic cooling are fragmenting traditional product hierarchies. Three developments are reshaping how wet-media systems are specified, deployed, and monetized across livestock and crop applications.
Biodegradable cellulose formulations with enhanced wet-strength resins are fragmenting the installed base between premium organic media and commodity plastic alternatives. Large-scale poultry integrators in Brazil and the Netherlands are specifying these advanced pads for new construction, while plastic variants retain share only in high-alkalinity water zones where mineral scaling degrades fiber integrity. The technology is fragmenting supplier tiers by separating engineered-media specialists from generic housing manufacturers.
The EU F-Gas Regulation restricting hydrofluorocarbon refrigerants is redirecting capital expenditure toward evaporative cooling in Spanish and Italian greenhouse clusters. Controlled-environment agriculture operators facing synthetic coolant phase-down deadlines are sizing wet-media systems for full cooling loads previously handled by mechanical refrigeration. Dutch Gelderland greenhouse cooperatives are consolidating procurement around pad suppliers with EU-wide service networks to ensure compliance documentation consistency.
Integrator procurement offices are consolidating vendor relationships to reduce specification variance across multi-site broiler operations. Tyson Foods, JBS, and BRF-scale buyers are issuing master service agreements that bundle pad supply, installation, and predictive replacement scheduling. This concentration is most visible in Brazil's São Paulo state, where vertically coordinated poultry chains now represent the dominant demand channel and squeeze regional distributors on price transparency and inventory carrying terms.
Agriculture Evaporative Cooling Pad Market Segmentation
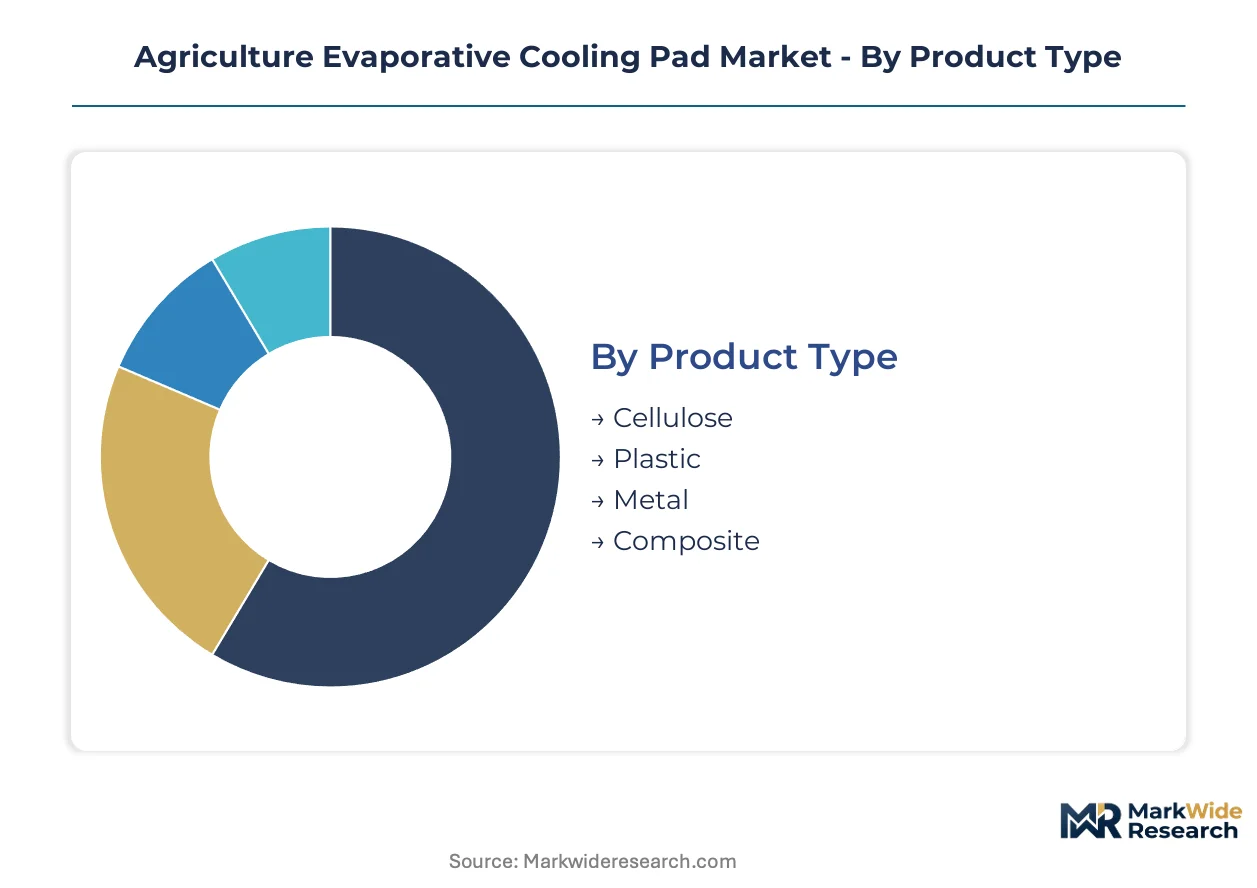
Material composition and installation permanence determine regulatory compliance pathways and capital recovery profiles across livestock and controlled-environment agriculture. Segmentation choices directly impact USDA ventilation mandate adherence, EPA discharge permitting complexity, and operational flexibility under tightening state-level heat-stress ordinances.
Product Type:
USDA biosecurity ventilation guidelines and EPA Clean Water Act runoff permitting create divergent compliance burdens between organic fiber and synthetic media, with wet-strength resin chemistry becoming a specification differentiator.
- Cellulose:Cross-corrugated paper impregnated with wet-strength resins and soluble salts delivers superior saturation efficiency and biodegradable end-of-life handling. Demand concentrates in California's Central Valley dairy operations and the Netherlands' Gelderland greenhouse cluster, where EU F-Gas Regulation restrictions on synthetic refrigerants accelerate wet-media substitution.
- Plastic:Polymer-based corrugated media resists mineral scaling in high-alkalinity groundwater zones across the US Southwest and Middle East, though cellulose saturation efficiency advantages compress margins and limit specification to water chemistry-constrained environments.
- Metal:Aluminum and stainless steel wet-media systems serve high-temperature industrial agriculture applications with pressure-wash sanitization requirements under OSHA heat-illness prevention standards.
- Composite:Hybrid organic-synthetic layered constructions balance saturation performance with scaling resistance for transitional water chemistry zones in Brazil's São Paulo state poultry belt.
Established volume favors cellulose; emerging adoption favors composite.
End Use Industry:
Customer concentration patterns split between vertically integrated livestock operators with master service agreements and fragmented seasonal horticulture renters with intermittent cooling needs.
- Dairy Farms:Permanent installation pads in tunnel-ventilated freestall barns address Cal/OSHA indoor heat standard compliance across California's San Joaquin Valley, with replacement cycles accelerating as first-generation installations from the 2010s approach end-of-life.
- Poultry Farms:Broiler and layer houses dominate procurement consolidation by Tyson Foods, JBS, and BRF-scale integrators bundling pad supply with predictive replacement scheduling under tightened USDA ventilation mandates.
- Greenhouses:Dutch Gelderland cooperatives consolidate procurement around EU-wide service networks to ensure F-Gas Regulation compliance documentation consistency for controlled-environment tomato and pepper production.
- Horticulture:Mediterranean and Australian seasonal growers drive modular rental-model penetration with intermittent cooling requirements and capital constraint profiles distinct from permanent livestock infrastructure.
Procurement concentration favors poultry; rental-service innovation favors horticulture.
Cooling Efficiency:
Performance tiering aligns with value-at-risk calculations in high-value crop segments versus cost minimization imperatives in commodity livestock operations.
- High Efficiency:Cross-corrugated cellulose with optimized flute geometry achieves maximum saturation efficiency for pharmaceutical-grade greenhouse operations and premium seed propagation facilities where temperature variance directly impacts product value.
- Medium Efficiency:Standard wet-media specifications balance capital cost against performance for commercial broiler houses and mid-scale dairy operations with moderate heat-stress exposure.
- Low Efficiency:Basic corrugated constructions serve seasonal applications and backup cooling redundancy where primary mechanical systems handle peak loads.
- Adjustable:Variable-density pad systems with modular sectioning allow seasonal reconfiguration for mixed livestock-crop operations in transitional climate zones.
Specification-grade volume favors high efficiency; retrofit flexibility favors adjustable.
Installation Type:
Capital deployment models fragment between asset-heavy permanent infrastructure and service-based temporary deployments, with skilled technician availability constraining geographic expansion.
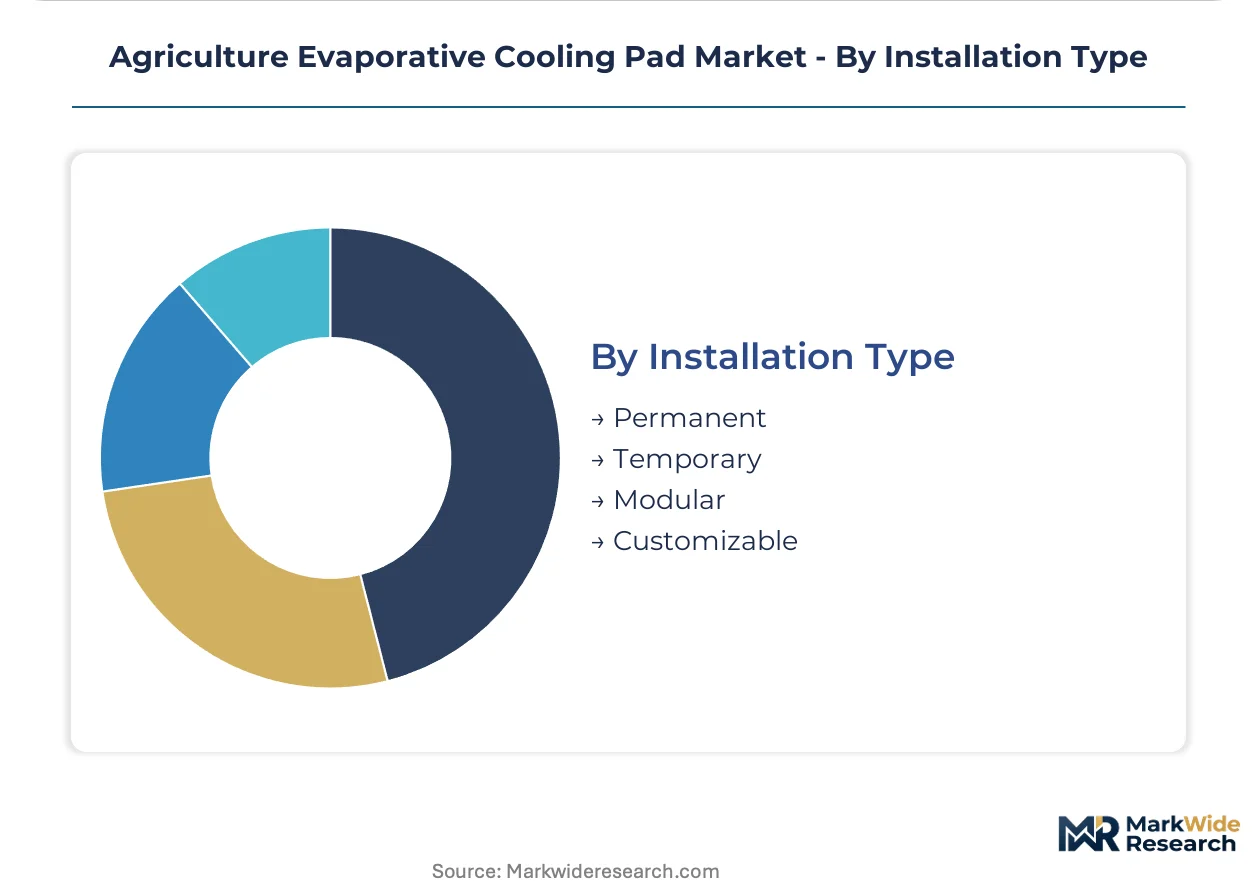
- Permanent:Fixed housing with integrated sump and pump systems commands the largest revenue pool across dairy and greenhouse segments, requiring skilled HVAC-agriculture crossover technicians concentrated in California, the Netherlands, and São Paulo state.
- Temporary:Seasonal rental-service models penetrate Australian and Mediterranean horticulture with short-term lease structures capturing margin from intermittent cooling needs without capital ownership burden.
- Modular:Standardized sectioned pads with quick-connect framing enable rapid deployment and predictive replacement scheduling, climbing the fastest as integrator procurement offices consolidate vendor relationships across multi-site broiler operations.
- Customizable:Engineered-to-order systems address non-standard building geometries and hybrid ventilation configurations in retrofit applications.
Revenue concentration favors permanent; service-model innovation favors modular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale poultry integrators concentrate procurement in four distinct geographies where heat-stress regulations and controlled-environment agriculture clusters overlap. Each market exhibits unique compliance pathways and vendor consolidation patterns.
United States
California's Central Valley dairy operations and broiler houses drive specification-grade cellulose pad demand under Cal/OSHA indoor heat standard enforcement. EPA Clean Water Act discharge permits for pad runoff complicate distributor compliance documentation across watershed jurisdictions. The San Joaquin Valley replacement cycle accelerates as first-generation installations from the 2010s approach end-of-life simultaneously.
Brazil
São Paulo state poultry integrators reorganize procurement around master service agreements bundling pad supply with predictive replacement scheduling. ANVISA biosecurity guidelines intersect with state-level heat-stress ordinances to tighten ventilation mandates. Vertically coordinated broiler chains now represent the dominant demand channel, squeezing regional distributors on price transparency.
Netherlands
Gelderland greenhouse cooperatives consolidate procurement around EU-wide service networks to ensure F-Gas Regulation compliance documentation consistency. The EU phase-down of hydrofluorocarbon refrigerants redirects capital expenditure toward full-load evaporative cooling systems. Dutch controlled-environment tomato and pepper producers size wet-media systems for cooling loads previously handled by mechanical refrigeration.
Australia
Mediterranean climate zone horticulture operators drive modular rental-service model penetration with intermittent cooling requirements. The country's national agricultural safety regulator enforces heat-illness prevention standards that elevate specification complexity. New South Wales and Victoria seasonal growers capture margin through short-term leases without capital ownership burden.
China
Yangtze River Delta greenhouse clusters adopt biodegradable cellulose formulations as MEE environmental standards tighten synthetic coolant oversight. Provincial dual carbon goals accelerate wet-media substitution in controlled-environment vegetable production. Zhejiang and Jiangsu facility operators balance saturation performance against mineral scaling resistance in transitional water chemistry zones.
Agriculture Evaporative Cooling Pad Market Competitive Landscape
Player mix skews toward wet-media engineering specialists with proprietary resin chemistry and global distribution infrastructure. The supply base fragments between premium cellulose formulators and commodity housing fabricators. Three archetypes dominate: engineered-media specialists controlling resin impregnation patents, integrated HVAC-agriculture system providers with direct-to-farm channels, and regional metal-fabrication shops supplying plastic-pad alternatives. Competitive moves concentrate on strategic partnerships with poultry integrators and predictive maintenance service bundling.
Among North American fabricators, J&D Manufacturing anchors heavy-gauge housing production with distribution reach across dairy and poultry segments. Munters occupies a position exemplifying wet-media engineering leadership through proprietary cellulose formulations and global service networks. Kuul Evaporative Cooling represents the cooling-efficiency rating specialist tier, differentiating on modular replacement-pad programs for retrofit cycles. These three collectively illustrate how vendor consolidation around integrator procurement offices is compressing margins for undifferentiated regional suppliers.
| Leading Market Players |
|---|
| J&D Manufacturing |
| Plasson Ltd |
| Munters |
| Kuul Evaporative Cooling |
| Idromeccanica Lucchini |
| Abbi-Aerotech |
| Portacool Evaporative Coolers |
| Phoenix Manufacturing |
| Automated Production Ltd |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements with Tyson Foods, JBS, and BRF-scale integrators lock in cellulose pad supply access while stripping price visibility from regional distributors across Brazil's São Paulo state and California's Central Valley. These master service agreements bundle predictive replacement scheduling with volume commitments, compressing margins for undifferentiated suppliers exposed to spot pulp fiber markets.
Pricing Analysis
Cost-plus contracts with kraft cellulose indexation dominate procurement between pad manufacturers and large-scale poultry integrators. Three-tier pricing structure across specification-grade cellulose, commodity plastic alternatives, and modular rental systems differentiates by saturation efficiency ratings and wet-strength resin chemistry. Pricing pressure stems from pulp fiber cost volatility tied to global paper commodity cycles. Commodity livestock operators exhibit highest price sensitivity, while pharmaceutical-grade greenhouse facilities prioritize performance over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for wet-strength resin imports and cross-corrugated paper machinery. Manufacturing concentrates in the United States, Brazil, and the Netherlands, with feedstock draws from Scandinavian pulp mills and Southeast Asian resin suppliers. Single-source vulnerability sits with specialized wet-media engineering expertise clustered in California, São Paulo state, and Gelderland. Distribution runs through direct-to-farm channels controlled by integrated HVAC-agriculture system providers and regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts with IoT moisture sensors and variable-speed pump controls represent a service-attach opportunity expanding faster than hardware sales as integrators consolidate vendor relationships. Recurring revenue from replacement-pad subscription programs captures margin from retrofit cycles accelerating across first-generation installations.
For Market Incumbents: Consolidate procurement relationships with vertically coordinated poultry chains in Brazil and California by bundling pad supply with installation and compliance documentation services. Deepen backward integration into wet-strength resin formulation to defend against pulp fiber cost volatility. Secure EU-wide service network coverage to capture F-Gas Regulation-driven substitution demand in Dutch and Spanish greenhouse clusters. For New Entrants and Emerging Players: Lead with sensor-integrated smart pad systems targeting seasonal horticulture rental models in Mediterranean climate zones and Australian states with intermittent cooling requirements. Modular deployment programs for retrofit replacement cycles in California's San Joaquin Valley offer the most penetrable entry point. Pursue direct partnerships with greenhouse cooperatives seeking short-term lease structures without capital ownership burden. For Investors and Strategic Acquirers: Engineered-media specialists with proprietary resin impregnation patents and predictive maintenance service capabilities present attractive acquisition targets in a market consolidating around integrator procurement offices. Long-term viability hinges on regulatory enforcement of heat-stress ordinances and synthetic refrigerant phase-downs across multiple jurisdictions. Watch for state-level indoor heat standard adoptions beyond California as the critical inflection signal for specification-grade pad demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captures margin from wet-strength chemistry and insulates against pulp fiber commodity cycles. |
| Predictive Maintenance Service Launch | Converts hardware sales into recurring revenue through IoT-enabled replacement scheduling contracts. |
| EU Service Network Expansion | Ensures F-Gas Regulation compliance documentation consistency for Dutch Gelderland greenhouse cooperatives. |
| Modular Rental Model Penetration | Captures seasonal horticulture demand in Mediterranean and Australian markets without capital barriers. |
| Certification Investment for Cal/OSHA Compliance | Unlocks specification-grade procurement from Central Valley dairy operators under indoor heat standard enforcement. |
Research Methodology
Operator-level perspectives from poultry integrator procurement officers, greenhouse cooperative technical directors, dairy farm maintenance managers, and HVAC-agriculture crossover technicians anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation from USDA ventilation guideline filings, EPA Clean Water Act discharge permit databases, EU F-Gas Regulation compliance documentation, and SEC filings from publicly traded livestock operators. Bottom-up installation data and top-down sector spending estimates were triangulated to construct market sizing.
Sensitivity analysis tested forecast robustness across pulp fiber price scenarios, regulatory enforcement intensity variations, and water chemistry constraint assumptions over the projection horizon. Segmentation dimensions modeled include material composition, installation permanence, cooling efficiency tier, and end-use industry concentration. CAGRs were derived from fitted growth curves calibrated to replacement cycle timing, regulatory mandate phase-in schedules, and integrator procurement consolidation patterns. Industry-specific inputs incorporated heat-stress mortality cost models and synthetic refrigerant substitution elasticity parameters.
Forecasts assume regulatory continuity in USDA biosecurity ventilation mandates, Cal/OSHA indoor heat standard enforcement, and EU F-Gas Regulation phase-down schedules; material policy shifts would require re-modeling. Water-use restriction adoptions and state-level heat-stress threshold modifications represent specific risk factors that could revise demand trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Global Feeding Systems Market
Agricultural Equipment
Stock Tanks Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Global Subsoiler Market
Agricultural Equipment
Intelligent Milking Robot Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Lawn Shredder Market
Agricultural Equipment
Cordless Sprayer Market
Agricultural Equipment
Hay and Forage Rakes Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Plows Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Gardening Equipment Market
Agricultural Equipment
Agriculture Seeder Market