
 Global Fishing Equipments Market | 2026-2036
Global Fishing Equipments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fishing Equipments Market Analysis
Modular rod-and-reel bundling is repositioning buyer choice away from standalone component purchases. Shimano Inc. leverages integrated drivetrain design across saltwater and freshwater portfolios. Pure Fishing, Inc. anchors its market presence through brand portfolio breadth spanning multiple price tiers. Daiwa Corporation dominates precision-machined reel manufacturing with advanced drag system specialization.
Fishing equipments comprise purpose-built tools for fish capture including rods, reels, lines, and terminal tackle, typically constructed from carbon fiber composites, aluminum alloys, or graphite matrices with drag ratings from 5 to 80 pounds depending on target species and environment. The primary commercial purpose spans protein procurement for commercial fleets through leisure engagement for recreational participants. Rods and reels command the largest product-type revenue pool due to replacement cycles tied to blank technology advances. Recreational anglers represent the fastest-growing end-user channel as participation rates climb in developed economies. Saltwater application segments carry premium pricing multiples over freshwater equivalents due to corrosion-resistant material requirements.
EPA guidelines on lead sinker alternatives and EU REACH restrictions on perfluorinated compounds are reshaping bait and line formulation standards across export-oriented manufacturers. Japan's METI fishing gear quality certifications and China's GB standards for carbon fiber tensile ratings create layered compliance thresholds for market access. Stakeholders must monitor evolving material restrictions and certification reciprocity agreements between major producing and consuming jurisdictions.
Market Dynamics
Carbon fiber blank technology and EU REACH compliance on fluorocarbon coatings are redirecting material sourcing across fishing equipment supply chains. Recreational anglers across North America and Europe are upgrading to performance-tier combos, compressing replacement cycles and reshaping manufacturer R&D priorities.
Growth Catalysts
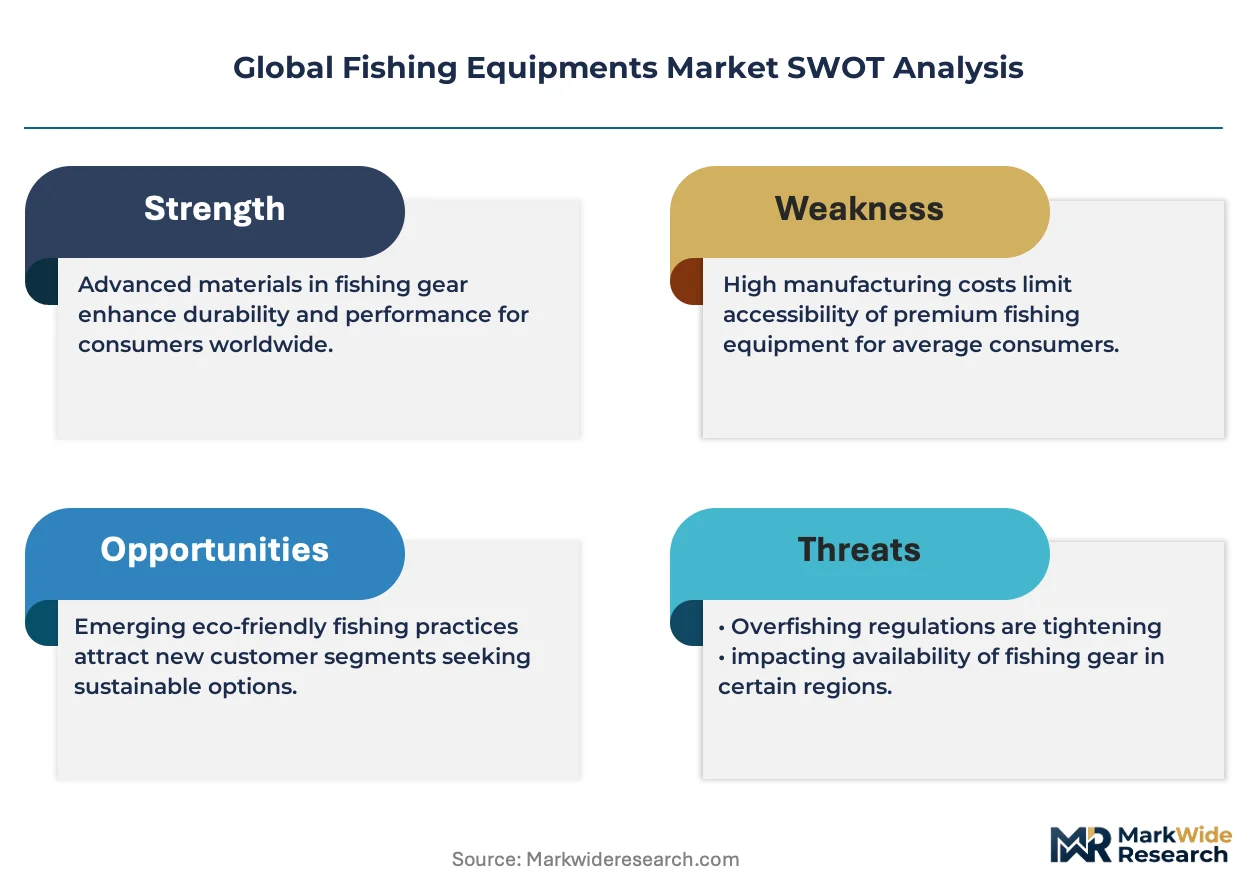
- Recreational participation surge:Marine leisure infrastructure expansion in coastal China, Japan, and the United States is generating sustained equipment refresh demand.
- REACH fluorocarbon mandates:EU restrictions on perfluorinated compounds are accelerating compliant coating formulation adoption among export-oriented manufacturers.
- Carbon fiber tensile certification:China's GB standards for blank ratings are creating quality-tier differentiation that rewards certified producers with premium positioning.
Market Restraints
- Prepreg carbon fiber supply concentration:Toray Industries and Mitsubishi Chemical dominate aerospace-grade fiber allocation, constraining fishing rod blank production capacity.
- Aluminum alloy price volatility:Reel chassis and frame manufacturing faces input cost pressure from LME aluminum futures fluctuation.
- Drag system precision limits:Saltwater big-game applications exceed current cork-carbon hybrid drag washer thermal dissipation thresholds.
Strategic Opportunities
- Underpenetrated Southeast Asia leisure marine:Thailand, Vietnam, and Indonesia coastal tourism development lacks proportional equipment retail infrastructure.
- Modular rod-and-reel bundling:Integrated drivetrain design is displacing standalone component purchases in premium saltwater segments.
- Japan METI quality certification reciprocity:Bilateral recognition agreements with South Korea and Taiwan would streamline cross-border premium product distribution.
Industry Challenges
- Composite layup technician scarcity:Hand-rolling carbon fiber blank production requires multi-year apprenticeship pipelines that regional vocational programs under-supply.
- Multi-jurisdiction compliance timeline compression:Simultaneous EPA lead sinker alternatives review and EU REACH substance restriction updates strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fishing Equipments Market |
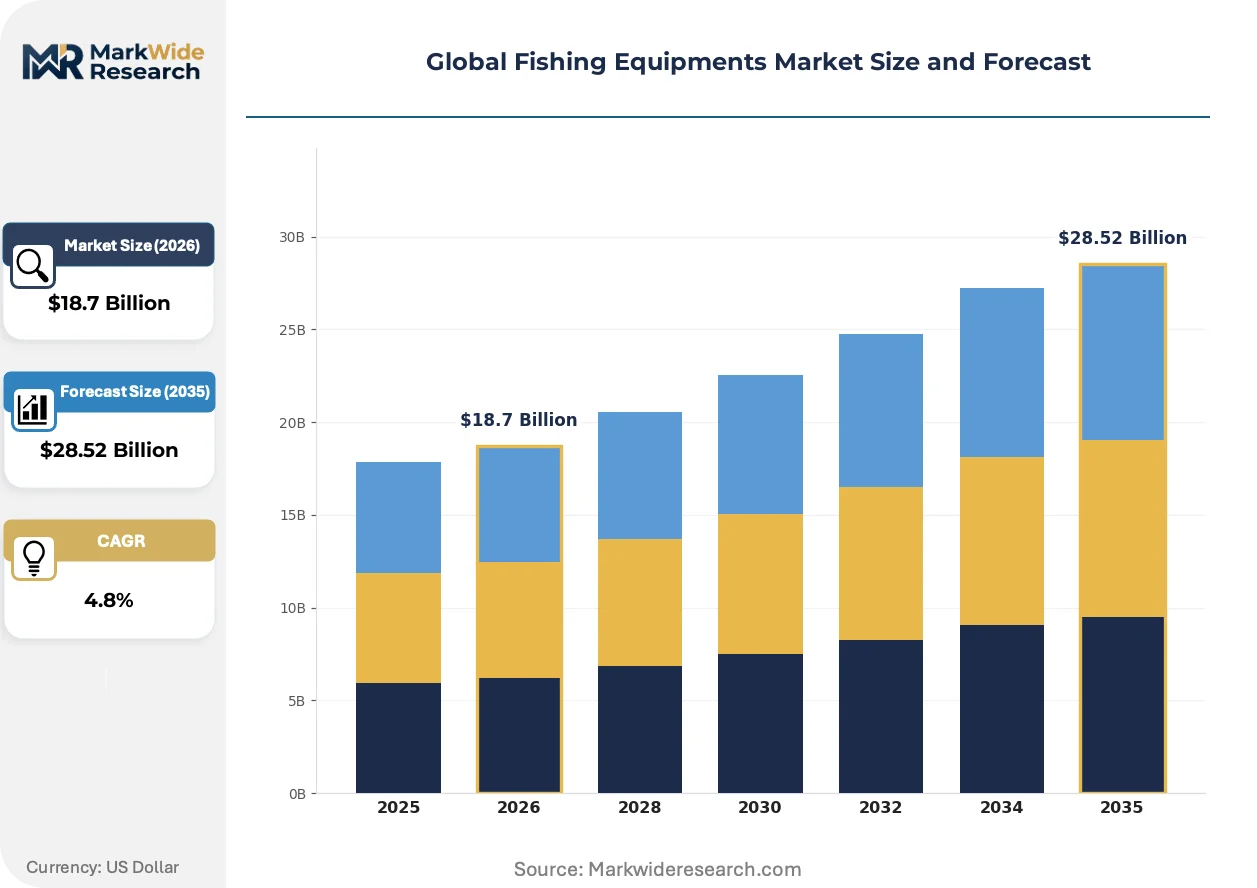
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rods, Reels, Baits, Lines End User: Commercial Fishers, Recreational Anglers, Government Agencies, Sporting Goods Retailers Application: Freshwater Fishing, Saltwater Fishing, Ice Fishing, Fly Fishing Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale Distributors |
| Companies Covered | Shimano Inc., Pure Fishing, Inc., Daiwa Corporation, Rapala VMC Corporation, Newell Brands, Johnson Outdoors Inc., Gamakatsu Co., Ltd., Okuma Fishing Tackle Co., Ltd., Globeride, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fishing Equipments Market Emerging Trajectories
Equipment manufacturers are converging on integrated system design while regulatory pressure accelerates material substitution timelines. Three distinct vectors are compressing traditional component boundaries and reshaping competitive positioning.
Carbon fiber composite blank construction is consolidating rod manufacturing around automated mandrel wrapping and resin infusion processes. Saltwater charter operators and competitive tournament anglers are demanding modulus-matched tip sections with faster action profiles. This consolidation is compressing regional craft producers into specialty niches while scaling automated facilities capture volume tiers.
EPA guidelines on lead sinker alternatives are forcing terminal tackle reformulation across freshwater product lines. Tungsten-nickel alloys and biodegradable ceramic composites are displacing traditional lead weights in retail channels serving environmentally regulated watersheds. Manufacturers with pre-validated non-toxic portfolios are securing shelf space in California, New York, and Great Lakes state markets where restrictions are most advanced.
Performance-tier anglers are rotating toward subscription-based tackle curation services that displace seasonal retail purchasing. Direct-to-consumer platforms with species-specific algorithmic matching are capturing coastal United States and Japanese metropolitan demand. This channel shift is fragmenting traditional wholesale relationships and compressing brand loyalty into data-driven recommendation engines.
Global Fishing Equipments Market Segmentation
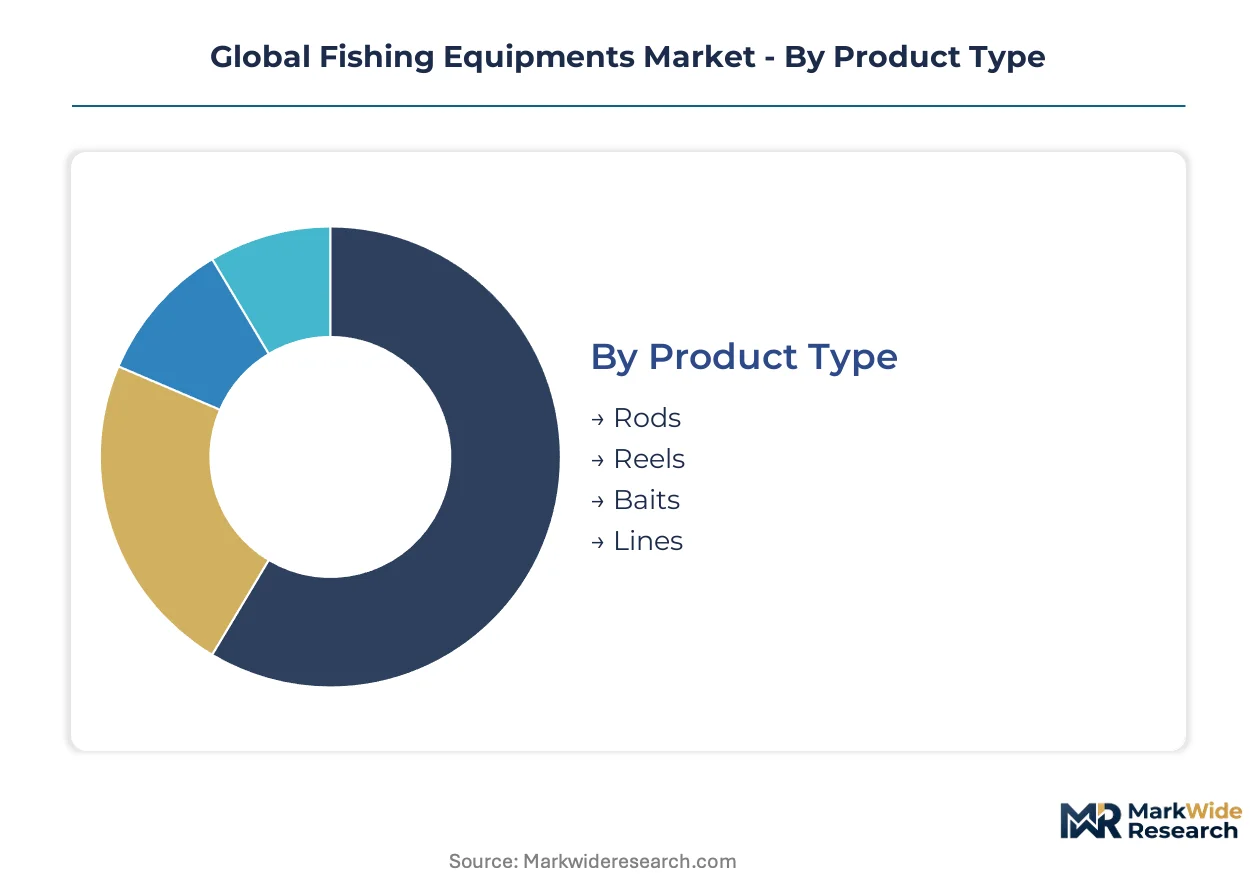
Segmentation in fishing equipment reveals how regulatory burdens and performance requirements split demand across incompatible use cases. Certification requirements from Japan's METI, China's GB standards, and EU REACH create divergent compliance pathways that manufacturers cannot serve simultaneously without dedicated product lines.
Product Type:
Rods and reels carry Japan METI quality certifications and China's GB tensile rating standards, while lines and baits face EU REACH fluorocarbon restrictions and EPA lead sinker guidelines.
- Rods:Carbon fiber composite blanks with modulus-matched tip sections dominate performance tiers. Hand-rolled mandrel construction requires certified technicians, constraining supply from Japan, China, and the United States where marine leisure infrastructure has expanded most aggressively.
- Reels:Precision-machined aluminum and graphite chassis with drag ratings from 5 to 80 pounds serve species-specific applications. Saltwater corrosion resistance demands aerospace-grade alloys, tying production capacity to Toray Industries and Mitsubishi Chemical fiber allocation decisions.
- Baits:Terminal tackle reformulation accelerates as tungsten-nickel alloys and biodegradable ceramics displace lead weights in California, New York, and Great Lakes watersheds.
- Lines:Fluorocarbon and monofilament formulations face EU REACH perfluorinated compound restrictions, redirecting coating chemistry among export-oriented manufacturers.
Rods sit at the top of the volume ranking, with reels climbing the fastest as replacement cycles compress around integrated drivetrain designs.
End User:
Cost tier stratification separates commercial procurement from recreational upgrade cycles, with government and retail channels occupying distinct margin structures.
- Commercial Fishers:Volume purchasers prioritize durability and repairability over performance specifications. Fleet operators in coastal China and Japan negotiate direct manufacturer relationships, bypassing retail markup.
- Recreational Anglers:The fastest-expanding channel as participation rates climb in developed economies. Performance-tier combo upgrades concentrate in the United States, Japan, and coastal China where marine leisure infrastructure investment has created sustained equipment refresh demand.
- Government Agencies:Procurement focuses on stock management and enforcement equipment with standardized specifications and extended replacement timelines.
- Sporting Goods Retailers:Inventory breadth requirements favor suppliers with portfolio depth across price tiers, compressing single-brand shelf space.
Recreational anglers command the steepest expansion trajectory, with commercial fishers retaining the largest absolute volume position.
Application:
Environmental exposure dictates material selection and pricing multiples, with saltwater corrosion resistance requiring premium alloy and coating investments.
- Freshwater Fishing:Aluminum and graphite constructions dominate with lower corrosion barriers. EPA lead sinker alternatives drive terminal tackle substitution in regulated United States watersheds.
- Saltwater Fishing:Premium pricing multiples reflect titanium and sealed bearing requirements. Charter operators in Japan, the United States, and coastal China demand modulus-matched fast-action rods for competitive tournament performance.
- Ice Fishing:Short blanks and compact reel designs prioritize portability over casting distance. Seasonal demand concentration in the northern United States, Canada, and Scandinavia creates inventory timing challenges.
- Fly Fishing:Specialized line weights and action profiles serve precise casting requirements. Artisan blank producers in Japan and the United States maintain niche positioning against automated volume manufacturers.
Freshwater application retains volume leadership, with saltwater segments gaining share fastest on premium pricing expansion.
Distribution Channel:
Customer acquisition cost and inventory velocity determine channel viability, with digital platforms fragmenting traditional wholesale relationships.
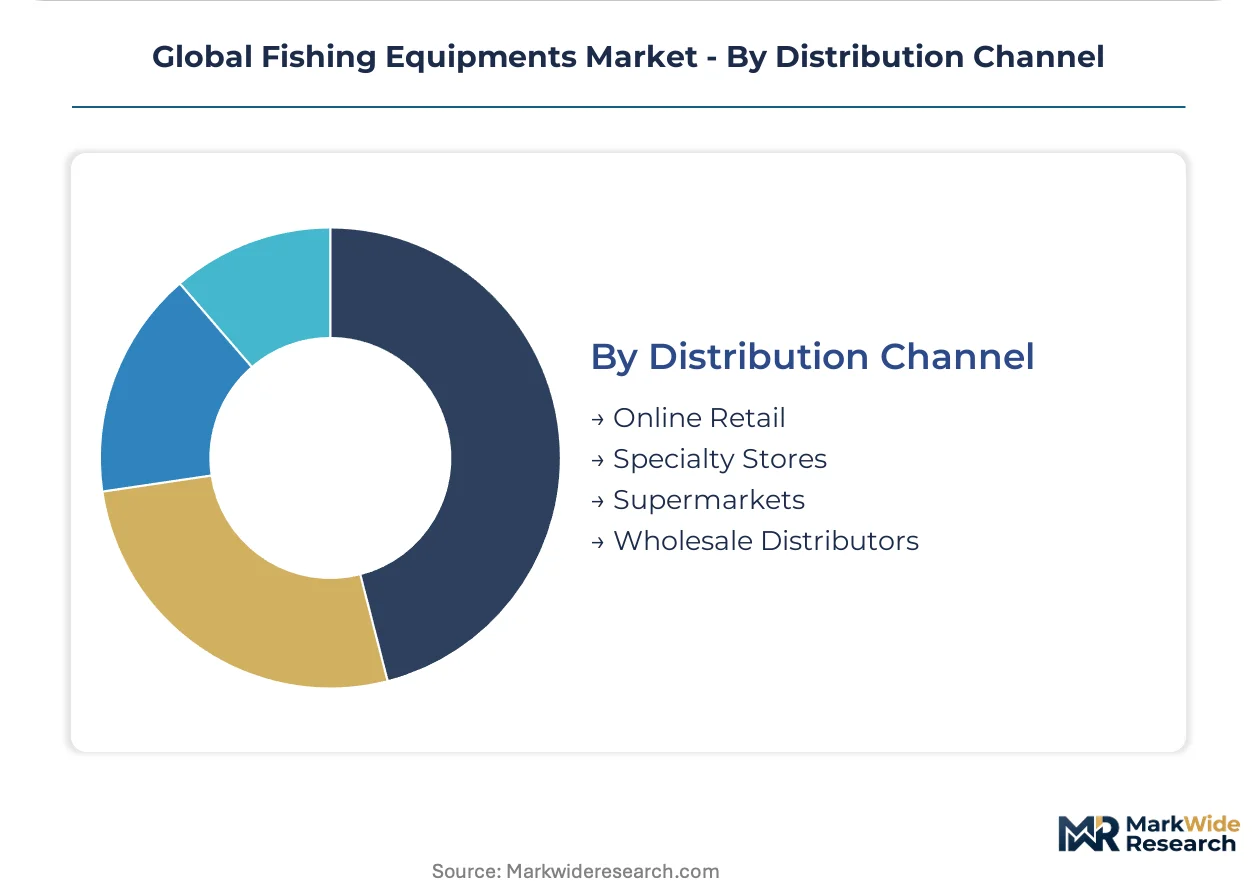
- Online Retail:Direct-to-consumer platforms with species-specific algorithmic matching capture coastal United States and Japanese metropolitan demand. Subscription-based tackle curation services displace seasonal purchasing patterns.
- Specialty Stores:Technical consultation and custom fitting services defend margin against digital price transparency. Certified rod builders and reel technicians create switching costs for performance-tier buyers.
- Supermarkets:Mass-market combo packs serve casual entry-level participation with limited SKU breadth and high inventory turns.
- Wholesale Distributors:Regional logistics networks consolidate fragmented manufacturer output for independent retailers, facing compression from brand-direct digital strategies.
Specialty stores hold the volume position, with online retail expanding most quickly as recommendation engines fragment brand loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern fishing equipment manufacturing traces its industrial lineage to post-war Japan, where carbon fiber blank technology first achieved commercial scale in the 1970s. This technical foundation established supply chain patterns that persist across contemporary production networks. Today's market geography reflects both this heritage and recent infrastructure investments in coastal leisure markets.
Japan
Marine leisure participation rates in coastal prefectures drive sustained equipment refresh demand among recreational anglers. METI fishing gear quality certifications create compliance thresholds that domestic manufacturers leverage for premium positioning. Osaka-based precision machining clusters supply drag system components to regional reel assemblers.
United States
Performance-tier combo upgrades concentrate in Florida, California, and Great Lakes states where tournament fishing infrastructure expanded. EPA guidelines on lead sinker alternatives accelerate terminal tackle reformulation across freshwater product lines. Coastal metropolitan markets from Seattle to Miami host subscription-based tackle curation services that fragment traditional wholesale channels.
China
Carbon fiber tensile certification under GB standards rewards compliant producers with quality-tier differentiation in export markets. Coastal provinces including Guangdong, Fujian, and Zhejiang expanded marine leisure infrastructure that generates equipment demand from domestic recreational anglers. Ningbo and Qingdao industrial zones concentrate automated mandrel wrapping facilities serving volume-tier rod production.
Germany
EU REACH restrictions on perfluorinated compounds redirect coating chemistry among export-oriented manufacturers serving European markets. Bavarian and North Rhine-Westphalian sporting goods distributors consolidate fragmented manufacturer output for independent retailers. Stuttgart-area engineering clusters contribute precision-machined reel components to regional assembly operations.
South Korea
Coastal tourism development around Busan and Jeju Island generates equipment demand from emerging recreational angler populations. Bilateral certification reciprocity discussions with Japan would streamline cross-border premium product distribution for compliant manufacturers. Seoul Capital Area retail channels integrate direct-to-consumer platforms with specialty store technical consultation services.
Global Fishing Equipments Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and material specification dimensions. The vendor base organizes into three layers: integrated drivetrain designers with proprietary blank technology, multi-brand portfolio operators spanning price tiers, and regional craft producers occupying specialty niches. Strategic moves concentrate on modular bundling architectures and automated manufacturing scale-up.
Within the integrated design tier, Shimano Inc. and Daiwa Corporation exemplify precision-manufacturing archetypes that anchor premium saltwater and freshwater portfolios. Pure Fishing, Inc. represents the multi-brand portfolio model with breadth across recreational price segments. These three Japanese and US-based entities occupy positions that reflect divergent competitive vectors: proprietary technology specialization versus brand portfolio diversification.
| Leading Market Players |
|---|
| Shimano Inc. |
| Pure Fishing, Inc. |
| Daiwa Corporation |
| Rapala VMC Corporation |
| Newell Brands |
| Johnson Outdoors Inc. |
| Gamakatsu Co., Ltd. |
| Okuma Fishing Tackle Co., Ltd. |
| Globeride, Inc. |
| Others |
Supply Flow & Price Mechanics
EU REACH fluorocarbon mandates gate qualified supply and premium-tier pricing access by forcing export-oriented manufacturers to reformulate coating chemistry, compressing margins for non-compliant producers while rewarding certified operators with shelf space in regulated European markets. This regulatory filter concentrates pricing power among Japanese and German manufacturers with pre-validated REACH portfolios, segmenting the market into compliance-tier price bands that recreational anglers in coastal China and the United States must navigate.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates modulus-matched carbon fiber blanks with METI certification from volume-tier mandrel-wrapped rods and entry-level fiberglass alternatives. Price differentiation hinges on GB tensile rating compliance and drag system precision grades, with saltwater corrosion-resistant reels commanding multiples over freshwater equivalents. Cost compression in the economy tier intensifies because aluminum alloy LME futures fluctuation feeds directly into reel chassis manufacturing, while commercial fleet operators in coastal China exhibit highest price sensitivity and tournament anglers in Japan and Florida show least.
Supply Chain Analysis
Japan's METI quality certification reciprocity discussions with South Korea and Taiwan are reshaping sourcing patterns for premium reel components and drag system subassemblies. Raw material feeds from Toray Industries and Mitsubishi Chemical in Japan, aluminum alloy smelters in China, and precision machining clusters in Germany anchor carbon fiber blank and reel chassis production. Single-source vulnerability concentrates in aerospace-grade prepreg fiber allocation, where fishing rod manufacturers compete with aviation for limited Toray output. Distribution runs through wholesale distributors in Bavaria and North Rhine-Westphalia, direct-to-consumer platforms in coastal United States metropolitan markets, and specialty retailers with certified rod builders in Osaka and Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where manufacturers can exploit the gap between China's GB certification costs and Japan's METI premium positioning to capture margin in Southeast Asian coastal tourism development.
For Market Incumbents: Hedge against REACH fluorocarbon mandate expansion by accelerating tungsten-nickel alloy terminal tackle portfolios and securing captive supply of aerospace-grade carbon fiber through long-term offtake agreements with Toray Industries. Backward integration into automated mandrel wrapping facilities in Ningbo and Qingdao industrial zones defends volume-tier positioning against emerging Chinese competitors with state-backed GB certification support. For New Entrants and Emerging Players: Begin with Thailand, Vietnam, and Indonesia coastal tourism infrastructure where equipment retail penetration lags marine leisure investment, targeting subscription-based tackle curation services with species-specific algorithmic matching for metropolitan recreational anglers. The most penetrable segment is performance-tier saltwater combos for charter operators, using direct-to-consumer platforms to bypass established wholesale relationships in Busan and Jeju Island. For Investors and Strategic Acquirers: Roll-up economics work for regional craft producers with artisan blank capabilities because METI certification scarcity and multi-year composite layup technician apprenticeship pipelines create defendable niche positioning against automated volume manufacturers. Acquisition targets should show established Japan-US distribution reciprocity and carbon fiber modulus-matched tip section IP, with the signal to watch being bilateral certification agreements between Japan and South Korea that would unlock cross-border premium product flow.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Prepreg | Captive supply from Toray Industries reduces aerospace-grade fiber allocation risk for premium rod blank production. |
| REACH-Compliant Coating Formulation Investment | EU ECHA substance restriction compliance secures shelf space in German and French retail channels. |
| Automated Mandrel Wrapping Scale-Up | Ningbo and Qingdao facilities compress unit costs for volume-tier recreational angler demand in coastal China. |
| Subscription-Based Tackle Curation Launch | Algorithmic species-matching platforms fragment traditional wholesale relationships in Seattle and Miami metropolitan markets. |
| Bilateral Certification Reciprocity Pursuit | Japan METI-South Korea MFDS mutual recognition streamlines premium reel distribution across Busan retail channels. |
Methodological Framework
Coverage spans Japan, the United States, China, Germany, and South Korea, with primary inputs from each market combining interviews with carbon fiber blank production technicians, reel drag system engineers, sporting goods category buyers, marine leisure infrastructure developers, and regulatory affairs specialists at export-oriented manufacturers. Secondary validation draws from Japan METI certification databases, China GB standards filings, EU ECHA REACH substance restriction updates, EPA lead sinker guideline dockets, and customs trade data for carbon fiber composite imports. Bottom-up equipment shipment analysis triangulates against top-down marine leisure participation rate projections.
Granularity-level modeling disaggregates volume and value across the analysis window by product type, end user, application, and distribution channel, with additional segmentation by certification tier and corrosion resistance specification. CAGRs derive from equipment replacement cycle compression rates tied to blank technology advances and recreational participation growth trajectories. Industry-specific forecast inputs include Toray Industries fiber allocation decisions, LME aluminum futures curves, and coastal tourism infrastructure investment pipelines in Southeast Asia.
Several conditions sit outside the modeled scope, including abrupt EPA lead sinker ban implementation timelines, aerospace sector carbon fiber demand spikes, and geopolitical disruption to Japan-China certification reciprocity negotiations. Forecasts reflect assumptions around sustained marine leisure infrastructure investment and stable regulatory compliance cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Greenhouse Heaters Market
Agricultural Equipment
Industrial Potato Graders Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Lawn Shredder Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Bulk Reception Feeder Market
Agricultural Equipment
Farm Implements Market
Agricultural Equipment
Flexible Silos Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
India Color Sorter Market
Agricultural Equipment
Plows Market