
 Europe Hospital-Acquired Infection Diagnostics Market | 2026-2036
Europe Hospital-Acquired Infection Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hospital-Acquired Infection Diagnostics Market Analytics
The divergence between premium molecular platforms and commodity culture-based testing is shifting procurement priorities across European hospital systems. bioMérieux leverages its syndromic panel portfolio to anchor high-complexity laboratory contracts in France and Benelux. Abbott competes through integrated random-access immunoassay systems that sustain throughput economics for mid-size hospitals. Siemens Healthineers AG dominates imaging-linked diagnostic workflows, extending its installed base into infectious disease testing corridors.
Hospital-acquired infection diagnostics encompass laboratory methods and instruments designed to detect pathogens contracted during medical care, typically requiring turnaround times under 24 hours for bloodstream infection panels and antimicrobial resistance profiling to guide therapeutic decisions. Molecular diagnostics leads technology adoption as polymerase chain reaction and next-generation sequencing platforms displace slower culture workflows in tertiary centers. Immunoassay occupies stable replacement demand in resource-constrained settings where capital-intensive sequencers face budget barriers. Application concentration tilts toward bloodstream infections and surgical site infections, where delayed detection carries direct reimbursement penalties under EU patient safety frameworks.
EMA coordinates centralized performance evaluations for novel diagnostic platforms, while the EU Medical Device Regulation mandates post-market surveillance systems that shape manufacturer compliance investments. National regulators including France's ANSM and Germany's BfArM enforce localized quality management audits that filter market access for non-compliant suppliers. Stakeholders must monitor evolving antimicrobial stewardship mandates and reimbursement coding revisions as hospitals consolidate purchasing through regional procurement alliances.
Market Dynamics
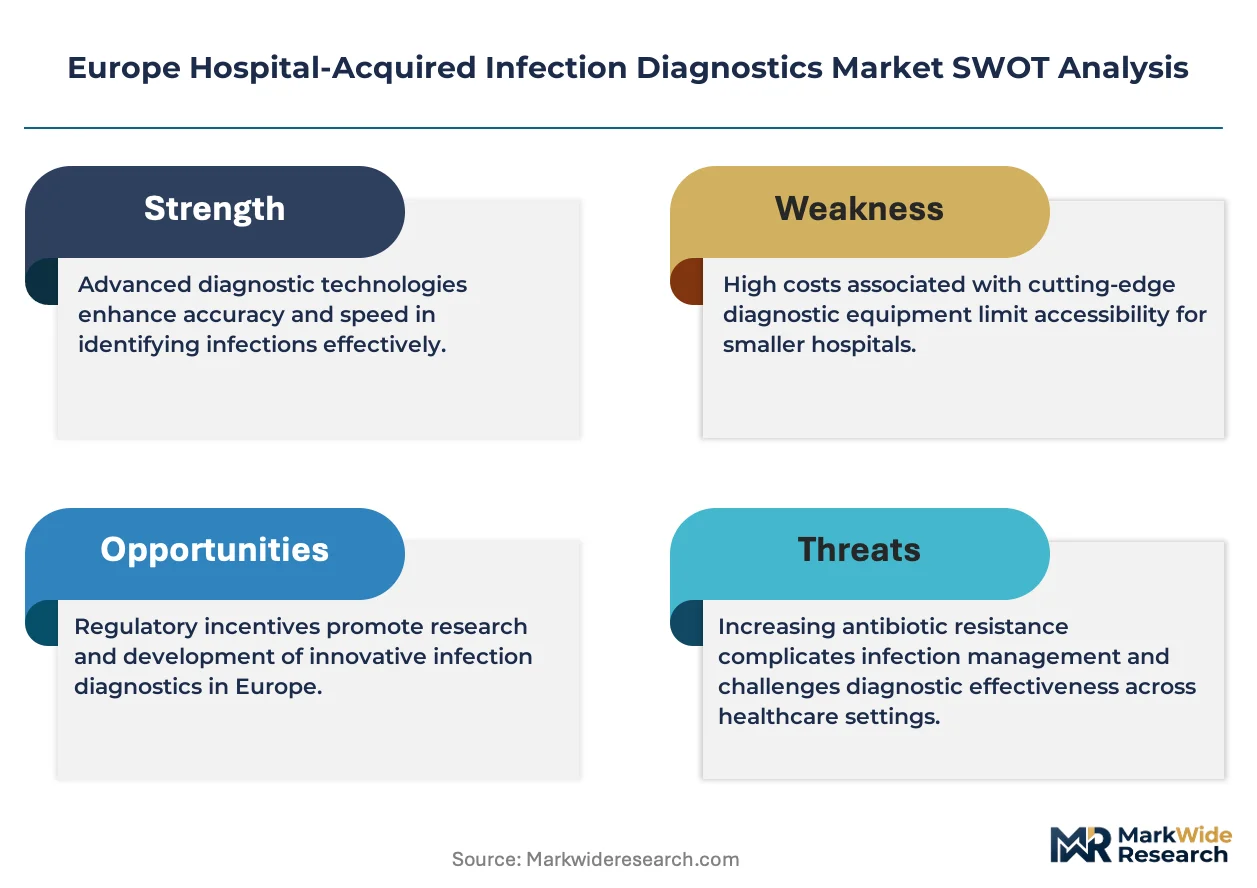
The EU Medical Device Regulation is compressing market access timelines while molecular diagnostic platforms capture laboratory capital budgets from slower culture-based workflows across Western European tertiary centers.
Growth Catalysts
- Antimicrobial Stewardship Mandates:France's ANSM and Germany's BfArM enforce hospital-level resistance monitoring protocols that mandate rapid diagnostic turnaround. These frameworks pull molecular panels into mandatory compliance workflows.
- ICU Expansion:Intensive care unit bed capacity additions across German hospital networks are creating dedicated molecular diagnostic infrastructure demand. Syndromic testing panels anchor these capital deployments.
- Reimbursement Penalty Frameworks:EU patient safety directives impose direct financial penalties on hospitals for delayed bloodstream infection detection. This shifts laboratory procurement toward sub-24-hour molecular platforms.
Market Restraints
- Capital Intensity Barriers:Next-generation sequencing platforms require seven-figure euro investments that exclude mid-size hospitals and peripheral laboratories from molecular adoption.
- Reagent Supply Concentration:Polymerase chain reaction consumable supply chains concentrate among three specialized chemical suppliers, creating input cost volatility and procurement risk.
- Technical Workflow Limitations:Culture-based methods retain diagnostic authority for certain fungal and slow-growing bacterial pathogens where molecular sensitivity remains inadequate.
Strategic Opportunities
- Central and Eastern Europe Penetration:Polish and Romanian hospital networks remain underpenetrated by molecular platforms, presenting first-mover installation opportunities for automated syndromic systems.
- Point-of-Care Convergence:Integration of cartridge-based molecular diagnostics with bedside monitoring equipment creates new deployment channels outside centralized laboratory infrastructure.
- EU Green Deal Procurement Incentives:Sustainability-linked tender scoring favors diagnostic manufacturers with reduced reagent waste profiles and energy-efficient platform designs.
Industry Challenges
- Bioinformatics Talent Scarcity:Next-generation sequencing interpretation requires specialized computational pathology skills that European laboratory workforces currently lack at scale.
- Legacy LIS Integration Complexity:Hospital information system architectures built around culture-based workflows resist seamless data exchange with cloud-connected molecular platforms.
- MDR Certification Timeline Compression:EU Medical Device Regulation technical documentation requirements extend product registration cycles, delaying revenue recognition for novel platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hospital-Acquired Infection Diagnostics Market |
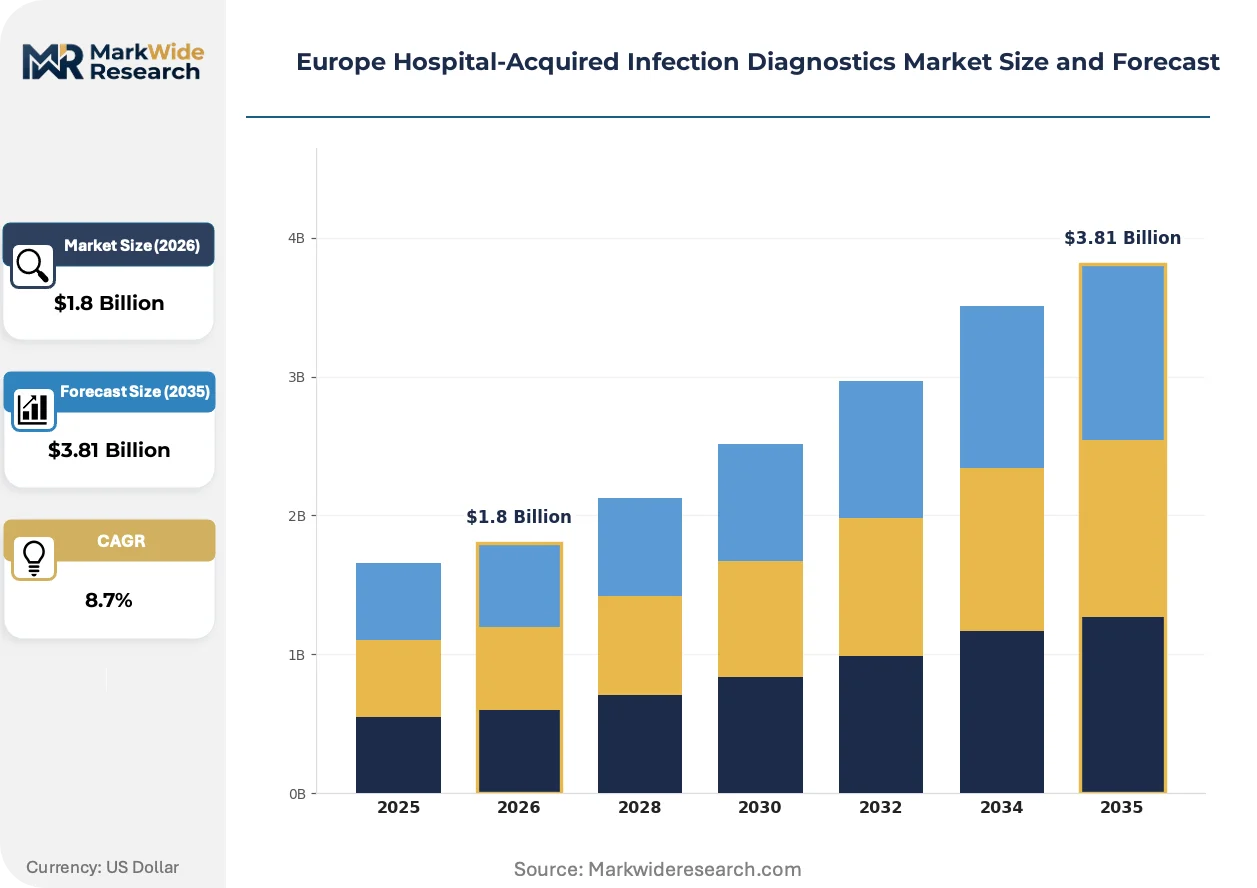
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Culture Tests, Molecular Diagnostics, Antigen Tests, Serology Tests Technology: Polymerase Chain Reaction, Immunoassay, Next-Generation Sequencing, Microbial Culture Application: Bloodstream Infections, Urinary Tract Infections, Surgical Site Infections, Pneumonia End User: Hospitals, Laboratories, Clinics, Diagnostic Centers |
| Companies Covered | bioMérieux, Abbott, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Becton Dickinson, QIAGEN, Thermo Fisher Scientific Inc., Meridian Bioscience, Hologic, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hospital-Acquired Infection Diagnostics Market Evolving Landscape
Multiplex syndromic panels are collapsing the diagnostic pathway from pathogen identification to resistance profiling into single automated workflows, restructuring laboratory staffing models and capital allocation priorities across European hospital systems.
Next-generation sequencing is overtaking targeted polymerase chain reaction panels for complex polymicrobial infections and outbreak investigation scenarios. Tertiary reference laboratories in France and the Netherlands are deploying these platforms for routine surveillance. The technology is compressing the time from specimen collection to resistance gene identification from days to hours.
EU Medical Device Regulation post-market surveillance requirements are mandating continuous performance monitoring for in vitro diagnostic devices. Manufacturers must maintain automated adverse event reporting systems and periodic safety update reports. This regulatory architecture most heavily affects small and mid-size diagnostic firms lacking established quality management infrastructure.
Regional procurement alliances in Benelux and Scandinavia are consolidating purchasing authority away from individual hospital laboratories. These cooperative frameworks standardize device specifications across multiple institutions and unbundle service contracts from equipment supply agreements. The shift is most visible in Dutch hospital networks where five purchasing cooperatives now control diagnostic capital spending.
Europe Hospital-Acquired Infection Diagnostics Market Segmentation
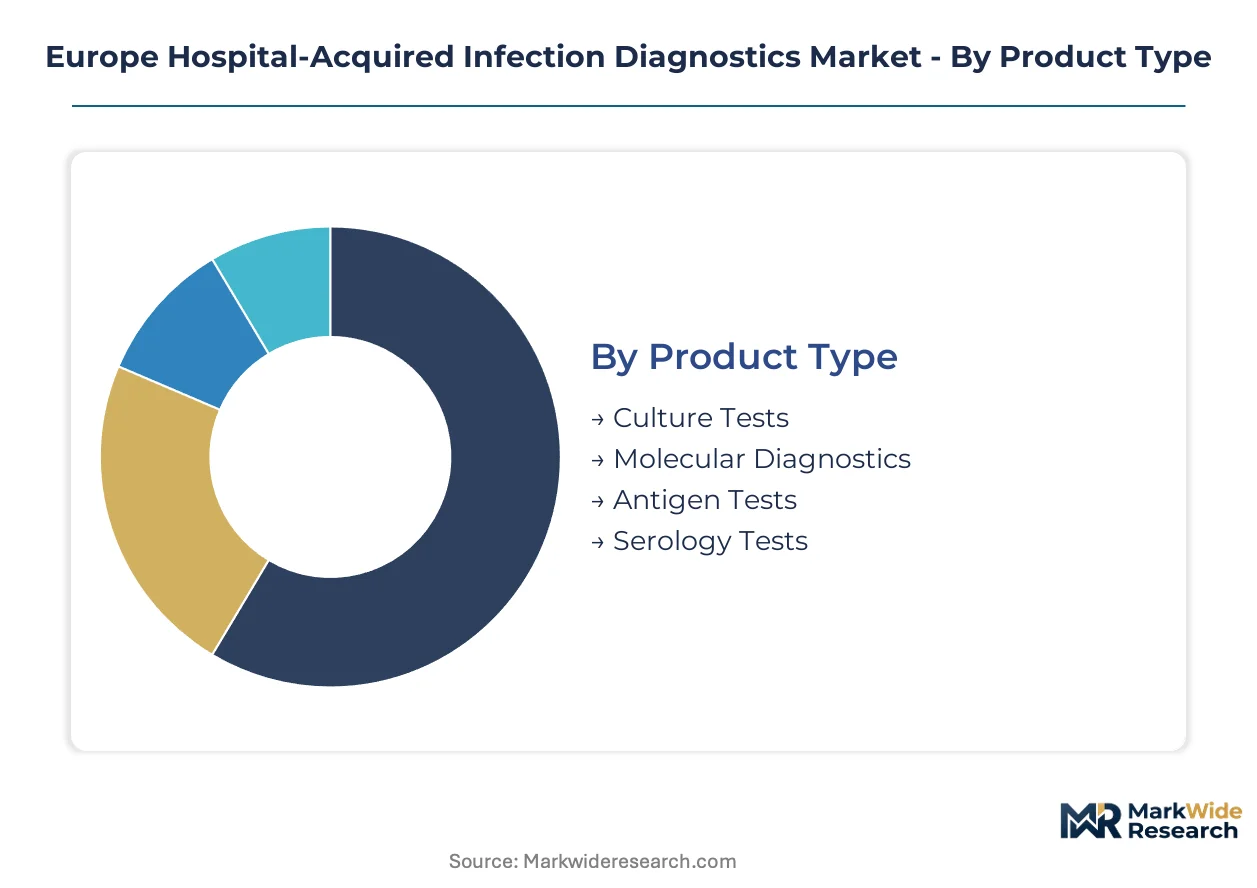
Segmentation in the Europe Hospital-Acquired Infection Diagnostics Market reveals how procurement priorities diverge across capital-intensive molecular platforms and commodity testing workflows. Laboratory infrastructure maturity and antimicrobial stewardship mandates reshape demand patterns within each category.
Product Type:
Capital deployment capacity separates buyers, with tertiary hospital networks absorbing seven-figure platform investments while peripheral facilities prioritize consumable economics.
- Molecular Diagnostics:Polymerase chain reaction and next-generation sequencing platforms deliver pathogen identification and resistance profiling within hours. German and French ICU expansions anchor syndromic panel installations in high-complexity laboratories.
- Culture Tests:Conventional microbiological cultivation remains the diagnostic authority for fungal pathogens and slow-growing bacteria where molecular sensitivity falls short. Mid-size hospitals across Poland and Romania retain these workflows due to capital constraints.
- Antigen Tests:Rapid immunochromatographic assays serve screening protocols in emergency departments.
- Serology Tests:Antibody detection methods support retrospective outbreak investigation and immune status verification.
Volume sits with Culture Tests; growth tilts toward Molecular Diagnostics.
Technology:
Workflow speed requirements determine technology selection, with reimbursement penalty frameworks favoring sub-24-hour turnaround systems.
- Polymerase Chain Reaction:Targeted nucleic acid amplification dominates bloodstream infection panels with established regulatory pathways under EU MDR. French ANSM quality audits validate PCR platform performance for mandatory resistance monitoring protocols.
- Next-Generation Sequencing:Untargeted metagenomic detection captures polymicrobial infections and novel resistance genes. Dutch reference laboratories deploy these systems for routine surveillance and outbreak investigation.
- Immunoassay:Enzyme-linked and chemiluminescent methods sustain throughput economics in mid-volume settings.
- Microbial Culture:Phenotypic testing retains reimbursement authority for definitive susceptibility determination.
Installed base concentrates in Polymerase Chain Reaction; capability expansion centers on Next-Generation Sequencing.
Application:
Financial penalty exposure shapes application prioritization, with EU patient safety directives imposing direct costs for delayed detection in high-mortality categories.
- Bloodstream Infections:Sepsis-associated pathogen detection carries the steepest reimbursement consequences for diagnostic delay. German hospital networks mandate molecular panel deployment for positive blood culture verification.
- Surgical Site Infections:Orthopedic and cardiac procedure surveillance requires extended monitoring windows. Belgian and Dutch procurement alliances standardize molecular screening protocols across tertiary networks.
- Urinary Tract Infections:Catheter-associated cases drive screening volume in long-term care settings.
- Pneumonia:Ventilator-associated detection demands rapid differentiation of bacterial and viral etiology.
Procurement weight falls on Bloodstream Infections; capability investment flows toward Surgical Site Infections.
End User:
Specimen volume and capital access stratify end-user requirements, with centralized laboratory infrastructure consolidating purchasing authority.
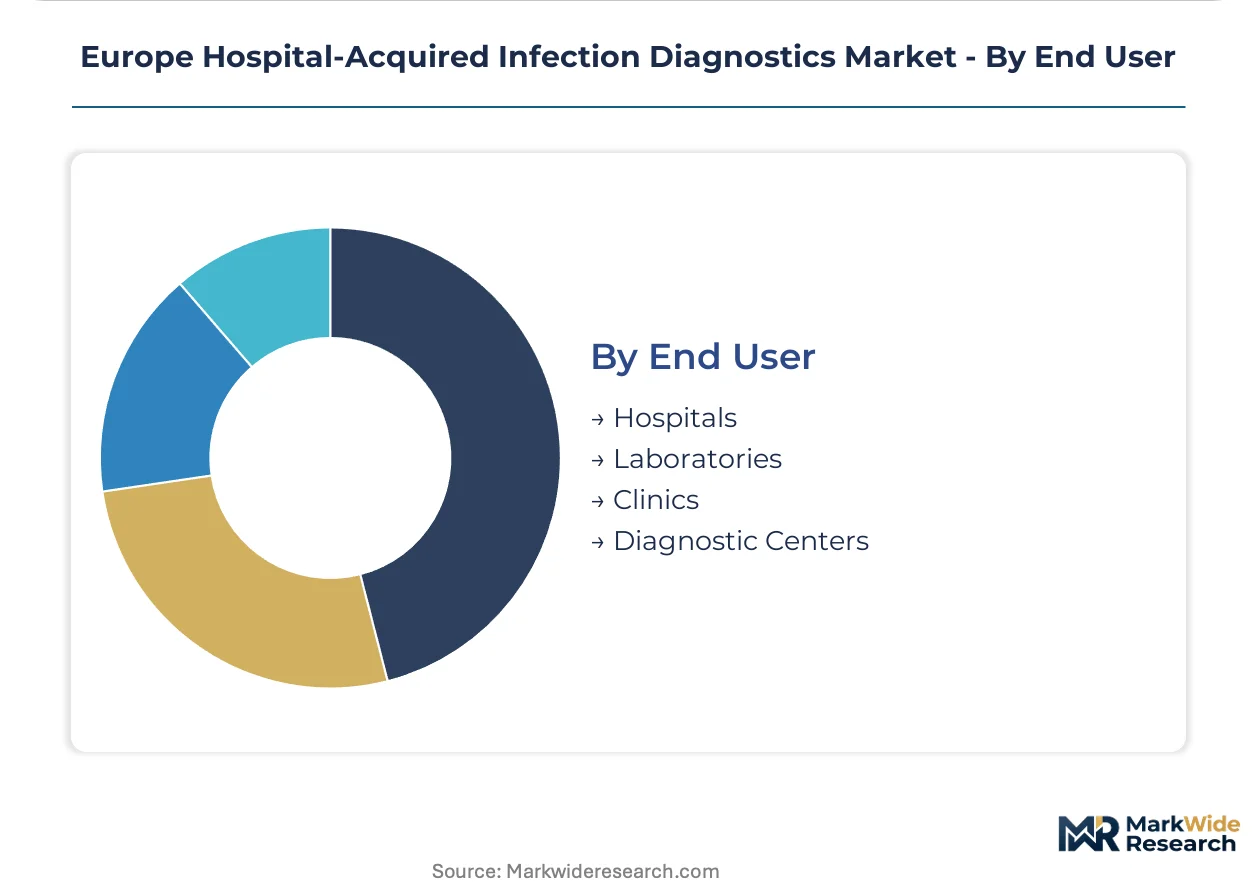
- Hospitals:Tertiary medical centers host high-complexity laboratories with automated molecular platforms. ICU bed expansion across German networks drives syndromic panel installations with integrated antimicrobial stewardship workflows.
- Laboratories:Independent and hospital-affiliated reference facilities process outsourced specimens from peripheral institutions. Regional procurement alliances in Scandinavia consolidate capital spending across multiple laboratory sites.
- Clinics:Outpatient settings rely on rapid antigen methods with limited technical infrastructure.
- Diagnostic Centers:Specialized infectious disease facilities support outbreak investigation and surveillance reporting.
Revenue concentration rests with Hospitals; outsourcing volume shifts toward Laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors molecular diagnostic deployment across German tertiary hospital networks, with syndromic panel installations concentrated in university medical centers managing ICU expansion programs.
Germany
ICU bed capacity additions across North Rhine-Westphalia and Bavaria drive dedicated molecular diagnostic infrastructure demand. BfArM enforces hospital-level resistance monitoring protocols that mandate rapid diagnostic turnaround for bloodstream infection verification. Berlin-Brandenburg medical centers host reference laboratories deploying next-generation sequencing for outbreak investigation.
France
Parisian hospital networks anchor syndromic panel adoption through centralized laboratory consolidation. ANSM quality audits validate PCR platform performance for mandatory antimicrobial stewardship compliance. Lyon-Grenoble medical clusters deploy integrated random-access systems across mid-volume tertiary facilities.
Netherlands
Five purchasing cooperatives now control diagnostic capital spending across Dutch hospital networks. EMA coordinates centralized performance evaluations that shape manufacturer compliance investments for novel platform introductions. Rotterdam-Utrecht laboratory alliances standardize molecular screening protocols for surgical site infection surveillance.
United Kingdom
NHS England procurement frameworks consolidate purchasing authority toward regional laboratory hubs. MHRA enforces post-market surveillance requirements under retained EU MDR provisions. London-Oxford-Cambridge golden triangle hosts reference facilities deploying metagenomic sequencing for complex polymicrobial detection.
Poland
Hospital networks across Mazovia and Silesia remain underpenetrated by automated molecular platforms, presenting installation opportunities for syndromic systems. The country's national pharmaceutical regulator enforces localized quality management audits that filter market access. Warsaw-based tertiary centers initiate first-mover molecular diagnostic deployments for ICU bloodstream infection panels.
Europe Hospital-Acquired Infection Diagnostics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology vectors in European hospital-acquired infection diagnostics. The market structure concentrates around three strategic tiers: multinational conglomerates with integrated platform portfolios, specialized molecular diagnostic firms with syndromic panel expertise, and regional distributors serving resource-constrained peripheral laboratories. Consolidation pressure intensifies as regional procurement alliances unbundle service contracts from equipment supply agreements. Dominant competitive moves include portfolio diversification into antimicrobial resistance profiling and strategic partnerships with hospital information system vendors.
Among French-based diagnostic specialists, bioMérieux exemplifies the syndromic panel archetype anchoring high-complexity laboratory contracts. Abbott Laboratories, Inc. occupies a position within the integrated random-access immunoassay tier sustaining throughput economics for mid-size hospitals. Siemens Healthineers AG represents the imaging-linked diagnostic workflow archetype extending installed base into infectious disease testing corridors.
| Leading Market Players |
|---|
| bioMérieux |
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Becton Dickinson |
| QIAGEN |
| Thermo Fisher Scientific Inc. |
| Meridian Bioscience |
| Hologic |
| Others |
Value Network & Pricing Analysis
Regional procurement alliance consolidation across Benelux and Scandinavia is compressing vendor margins and forcing manufacturers toward unbundled equipment supply contracts with separate service pricing tiers. This buyer-side concentration reshapes how diagnostic firms structure capital deployment and consumable economics across European hospital networks.
Pricing Analysis
Throughput-based value anchoring dominates molecular diagnostic platform contracts, with pricing tied to annual test volume guarantees and uptime performance rather than capital purchase alone. Three-tier pricing structure across premium syndromic panels, standard PCR workflows, and economy culture-based systems separates tertiary hospital networks from mid-size facilities and peripheral laboratories. Cost compression in the economy tier is intensifying because Polish and Romanian hospital networks prioritize consumable economics over platform investment. Mid-size hospitals across Central Europe exhibit the highest price sensitivity, while German university medical centers accept premium positioning for integrated antimicrobial stewardship workflows.
Supply Chain Analysis
Regional distribution centers in Germany, France, and the Netherlands anchor hub-and-spoke logistics patterns for PCR reagents and sequencing consumables. Manufacturing concentration for polymerase chain reaction thermal cyclers rests on Germany and the United States, while next-generation sequencing instrument assembly draws from the United States and China. Reagent formulation depends on specialized chemical inputs from Switzerland and Japan. Single-source vulnerability in Taq polymerase supply creates procurement risk for European diagnostic laboratories. Distribution runs through manufacturer-authorized distributors with direct service contracts to hospital laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Hospital-Acquired Infection Diagnostics Market is consolidating around procurement alliance power and MDR compliance scale, squeezing mid-tier suppliers lacking quality management infrastructure or capital reserves for certification delays.
For Market Incumbents: Acquire cloud-connected laboratory information system capabilities to anchor integrated diagnostic workflows against emerging platform competitors. bioMérieux and Abbott should expand syndromic panel R&D into antimicrobial resistance gene detection to defend against next-generation sequencing substitution in outbreak investigation scenarios. BfArM and ANSM audit frequency escalation raises compliance costs that filter smaller competitors from tender participation. For New Entrants and Emerging Players: Cartridge-based point-of-care molecular diagnostics offer a technology-first wedge into bedside testing corridors outside centralized laboratory infrastructure. Polish and Romanian hospital networks present the most penetrable geography for automated syndromic systems with financing structures that defer capital burden. Partnership with regional procurement cooperatives in the Netherlands and Scandinavia provides the essential go-to-market angle for platform validation at scale. For Investors and Strategic Acquirers: The window for entry favors specialized molecular diagnostic firms with CE-marked syndromic panels and established ANSM quality audits. Long-term viability hinges on antimicrobial stewardship mandate expansion and ICU infrastructure investment cycles across German and French hospital networks. Watch EMA post-market surveillance requirement enforcement intensity as the inflection signal for compliance cost barriers favoring scaled incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements extend registration cycles for novel platform introductions. |
| Hospital System Partnership | Regional procurement alliances in Benelux consolidate purchasing authority toward standardized device specifications. |
| Software Companion Development | Cloud-connected LIS integration addresses legacy system resistance to molecular platform data exchange. |
| Reimbursement Strategy | EU patient safety penalty frameworks pull sub-24-hour molecular panels into mandatory compliance workflows. |
| Backward Integration into Reagents | Captive supply of PCR consumables mitigates input cost volatility from concentrated chemical suppliers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital laboratory directors, biomedical engineers, GPO contracts managers, and diagnostic platform sales executives. EMA device registration databases, ANSM quality audit reports, BfArM hospital resistance monitoring protocols, and Benelux procurement cooperative tender documents provided structured secondary validation. Bottom-up modeling of installed base and replacement cycles triangulated against top-down healthcare expenditure allocation estimates.
Segment-level granularity modeled product type, technology platform, application severity, and end-user facility tier across the projection horizon. Bloodstream infection and surgical site infection application splits incorporated EU patient safety directive penalty exposure differentials. German ICU bed expansion programs and French antimicrobial stewardship mandate enforcement timelines informed country-level trajectory assumptions. CAGRs derived from weighted average of historical replacement cycle analysis and procurement alliance standardization momentum.
Several conditions sit outside the modeled scope, including unforeseen EMA regulatory timeline extensions, abrupt reagent supply chain disruptions, and hospital network bankruptcy events affecting capital commitment capacity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Sterilization Tunnel Market
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
Alcohol Wipes Market
Infection Control
Virus Filtration Market
Infection Control
Global Pseudomonas Aeruginosa Infection Treatment Market
Infection Control
Global Infection Prevention Devices Market
Infection Control
Intra-Amniotic Infection Treatment Market
Infection Control
North America Hand Sanitizer Market
Infection Control
UV Sterilizer Pouch Market
Infection Control
Intra Abdominal Infection Market
Infection Control
Medical Disinfectant Wipes Market
Infection Control
Pertussis Infection Testing Market
Infection Control
Global Prophylactic Human Vaccine Market
Infection Control
Sterilization Equipment and Disinfectant Market
Infection Control
Multi-Surface Disinfection Booster Systems with Low QAC Load Market
Infection Control
Blood Stream Infection Testing Market