
 Global Scarifiers Market | 2026-2036
Global Scarifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Scarifiers Market Foresight
Buyer concentration among rental service providers is decoupling from traditional construction company dominance as smaller contractors favor short-term equipment access over capital expenditure. Husqvarna anchors its position through geographic dominance in European municipal fleets, while STIHL differentiates via battery-powered technology leadership in residential and light-commercial segments. Makita competes aggressively on manufacturing scale, leveraging its power-tool ecosystem to cross-sell scarifier attachments through existing dealer networks.
Scarifiers are mechanical surface preparation machines employing rotating cutter drums or flails to abrade, groove, or strip hardened materials such as concrete, asphalt, and epoxy coatings; drum speeds typically range from 1,000 to 3,000 RPM with cutting depths adjustable between 1 mm and 10 mm depending on substrate hardness and application requirements. Floor scarifiers occupy the largest installed base due to decades of penetration in warehouse and factory floor maintenance, though battery-powered technology represents the fastest-expanding margin pool as lithium-ion energy density improvements enable cordless operation at previously diesel-dependent power levels. Shot blasters sustain premium positioning in industrial facilities where dust-free surface profiling for coating adhesion meets stringent air quality protocols.
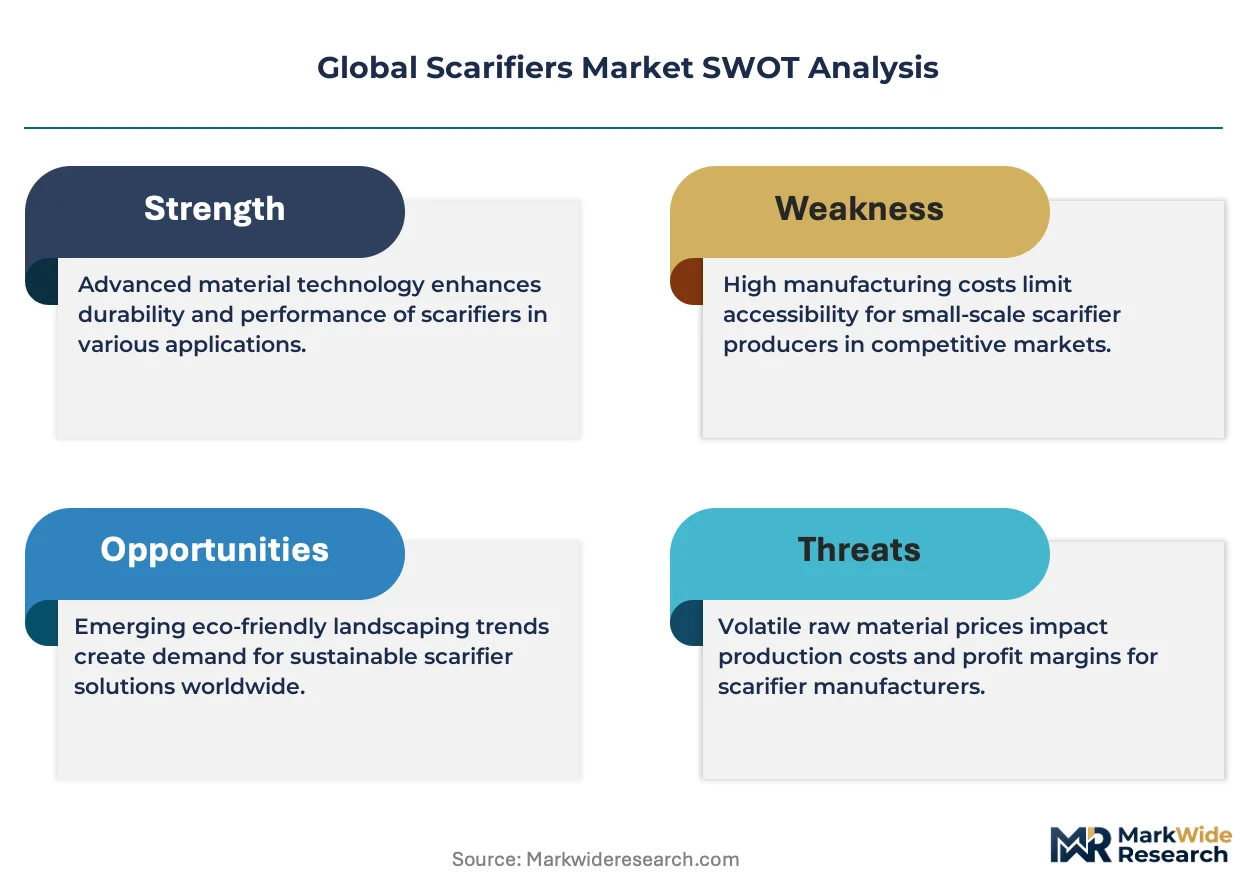
OSHA silica exposure limits and EPA particulate matter standards are reshaping product design priorities, compelling manufacturers to integrate vacuum-assisted dust collection systems as standard rather than optional configurations. The EU F-Gas Regulation and REACH compliance frameworks restrict hydraulic fluid formulations and surface coating chemistries, elevating R&D costs for market access but simultaneously creating competitive moats for firms with certified in-house testing capabilities. Stakeholders must monitor evolving carbon border adjustment mechanisms and battery recycling mandates, as these will determine which technology platforms retain cost competitiveness across major procurement jurisdictions.
Market Dynamics
Battery-electric drivetrain migration is compressing the traditional diesel equipment lifecycle as municipal procurement mandates in Germany and China force premature fleet turnover before mechanical end-of-life.
Growth Catalysts
- EU Green Deal emissions standards:Tightening construction equipment regulations accelerate manufacturer migration to electric platforms, expanding addressable market for zero-emission scarifiers in noise-sensitive urban zones.
- China's high-speed rail rehabilitation:Provincial infrastructure programs sustain concrete surface preparation demand, driving sustained equipment orders for heavy-duty drum scarifiers.
- Lithium-ion energy density improvements:Cordless operation now matches diesel-dependent power levels, enabling battery scarifiers to penetrate warehouse and factory floor maintenance previously reserved for combustion engines.
Market Restraints
- Battery raw material volatility:Lithium and cobalt supply concentration in Chile and the Democratic Republic of Congo creates input cost instability for electric scarifier manufacturers.
- REACH compliance friction:ECHA restrictions on hydraulic fluid formulations and surface coating chemistries elevate R&D costs, delaying market access for uncertified entrants.
- Shot blaster substitution:Dust-free surface profiling alternatives sustain premium positioning in industrial facilities with stringent air quality protocols, capping scarifier penetration in coating adhesion applications.
Strategic Opportunities
- India's warehousing expansion:Underpenetrated logistics infrastructure creates first-mover advantage for floor scarifier rental networks targeting emerging cold-chain facilities.
- OSHA silica mandate convergence:Vacuum-assisted dust collection integration opens premium pricing tier for compliant equipment in US surface preparation contracting.
- Battery recycling mandate preparation:EU battery passport requirements favor manufacturers with certified in-house testing capabilities, creating competitive moats against import-dependent rivals.
Industry Challenges
- Electromechanical technician scarcity:Diesel-to-electric transition outpaces vocational training pipeline, creating service bottleneck for battery-powered fleet maintenance.
- Carbon border adjustment uncertainty:Evolving CBAM implementation timelines complicate multi-year procurement planning for cross-border equipment sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Scarifiers Market |
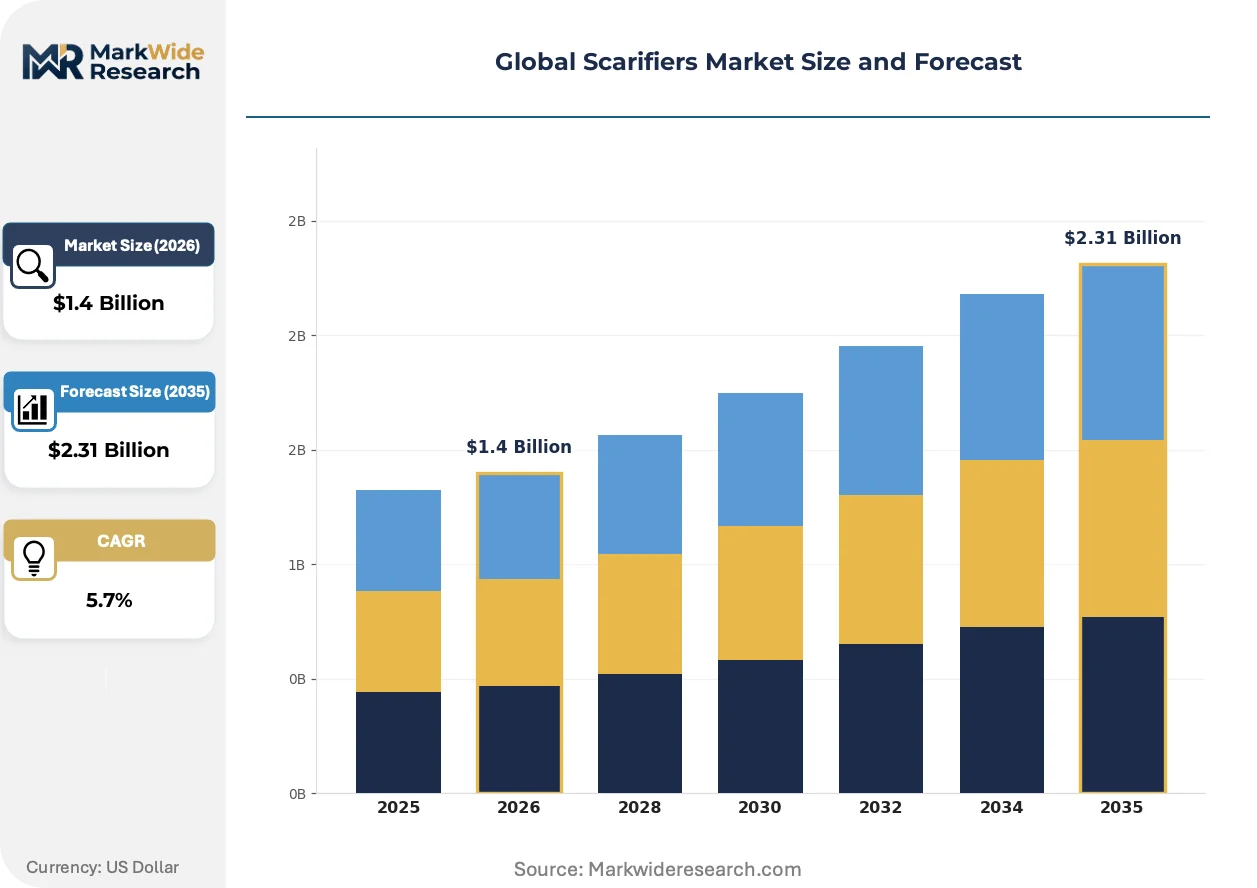
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Scarifiers, Surface Planers, Concrete Grinders, Milling Machines, Shot Blasters Technology: Electric, Hydraulic, Pneumatic, Diesel, Battery-Powered Application: Concrete Surface Preparation, Asphalt Removal, Paint Removal, Grooving, Pavement Repair End User: Construction Companies, Road Maintenance, Industrial Facilities, Rental Service Providers |
| Companies Covered | TORO, Einhell, STIHL, AL-KO, STIGA SpA, Husqvarna, John Deere, Makita, MTD Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Scarifiers Market Shifts & Advancements
Equipment intelligence and connected asset management are redefining scarifier value propositions, shifting competitive advantage from mechanical durability toward data-enabled uptime optimization and predictive maintenance integration.
Brushless DC motor architectures are expanding into scarifier cutter drum drives, delivering torque density previously achievable only through hydraulic systems. German municipal fleets are adopting these electromechanical platforms for urban resurfacing projects where noise ordinances prohibit combustion operation. The technology is expanding into rental service provider inventories, compressing maintenance intervals and enabling remote diagnostics that reduce field service dispatch costs.
REACH and the EU F-Gas Regulation are restricting hydraulic fluid formulations and surface coating chemistries, compelling manufacturers to reformulate legacy product lines. Industrial consequence includes elevated R&D expenditure for market access certification and accelerated phase-out of perfluorinated compounds in corrosion-resistant drum coatings. Floor scarifier segments face compressed compliance timelines, with certified in-house testing capabilities becoming a gating factor for continued European market participation.
Rental service providers are consolidating equipment access decisions previously fragmented across small contractor purchasing departments. Short-term equipment access models displace capital expenditure preference among residential and light-commercial contractors, concentrating buyer power in national rental chains with fleet standardization leverage. This behavioral shift is most visible in Germany, where municipal procurement agencies increasingly specify battery-electric platforms through multi-year rental frameworks rather than direct ownership.
Global Scarifiers Market Segmentation
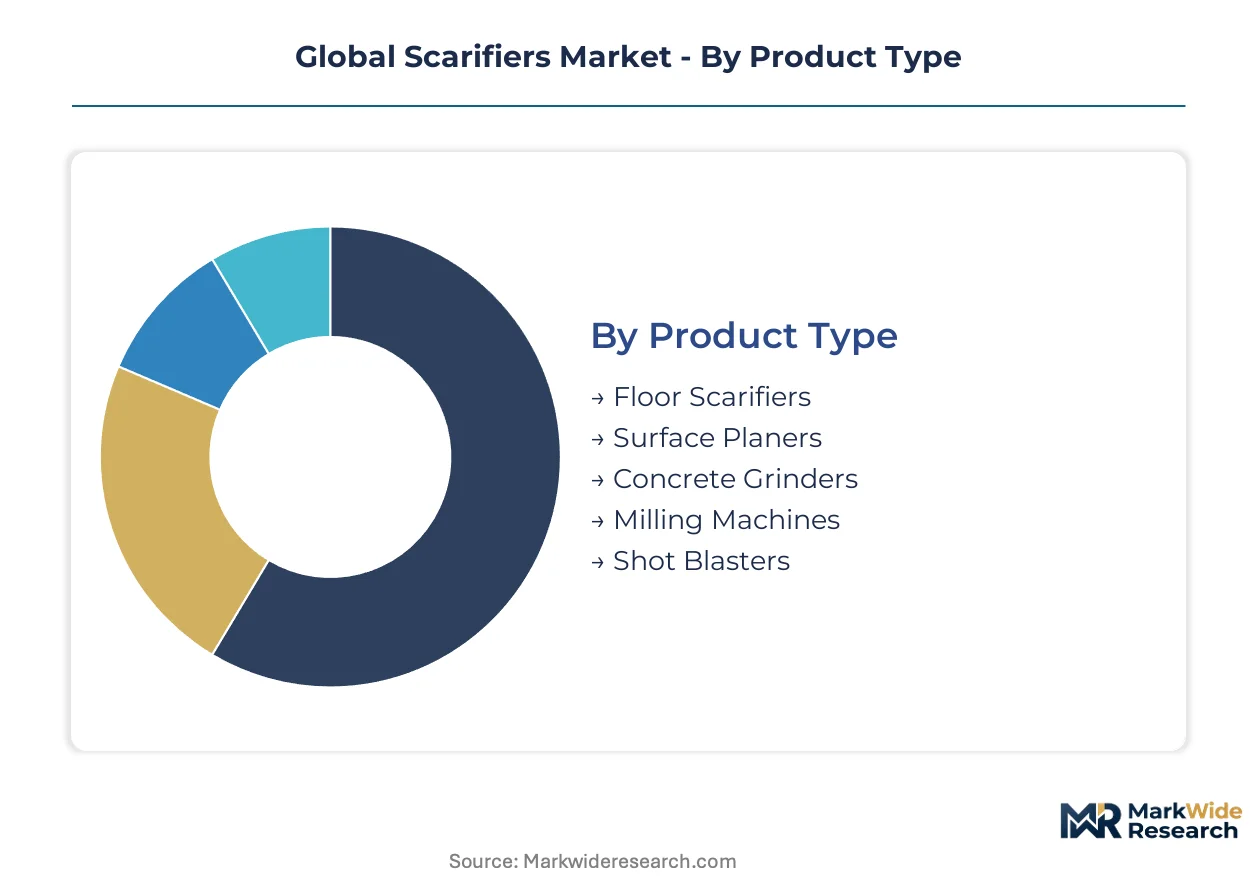
Scarifier procurement patterns diverge sharply across customer archetypes, with rental service providers consolidating equipment decisions previously fragmented among thousands of small contractors. Technology platforms and application requirements further stratify the addressable market, creating distinct margin pools for manufacturers with certified compliance capabilities.
Product Type:
Buyers in this category differentiate by substrate hardness and surface finish requirements rather than capital budget alone.
- Floor Scarifiers:Rotating cutter drum systems abrade concrete and asphalt at depths between 1 mm and 10 mm, with drum speeds from 1,000 to 3,000 RPM. Warehouse and factory floor maintenance in Germany's industrial corridor sustains the largest installed base, though REACH compliance timelines for drum coatings compress replacement cycles.
- Surface Planers:Precision milling heads deliver uniform surface profiling for coating adhesion applications. China's provincial high-speed rail rehabilitation programs concentrate demand for heavy-duty planers capable of concrete substrate preparation at sustained duty cycles.
- Concrete Grinders:Diamond abrasive systems achieve smoother finishes than cutter drums, serving polishing contractors in commercial flooring.
- Milling Machines:Large-format drum assemblies remove full pavement depths for road reconstruction projects.
- Shot Blasters:Centrifugal blast wheel systems propel abrasive media for dust-free surface profiling, commanding premium positioning in industrial facilities with OSHA silica exposure protocols.
Floor scarifiers lead volumes today; shot blasters are gaining share fastest in regulated industrial environments.
Technology:
Power source selection tracks directly to operating environment constraints and local emissions enforcement intensity.
- Electric:Corded AC motor systems deliver continuous power for fixed-site industrial operations without battery weight penalties. German municipal fleets specify electric platforms for indoor warehouse maintenance where ventilation limits combustion exhaust.
- Battery-Powered:Lithium-ion energy density improvements now enable cordless operation matching diesel-dependent power levels. China's urban resurfacing contractors adopt battery scarifiers for noise-sensitive zones under tightening MEE emissions oversight.
- Diesel:Compression ignition engines retain dominance in remote heavy civil projects lacking grid infrastructure.
- Hydraulic:Fluid power systems deliver high torque density for large drum diameters in milling applications.
- Pneumatic:Compressed air drive suits explosive atmosphere environments in petrochemical facilities.
Diesel retains the largest installed base; battery-powered platforms are expanding most quickly into municipal and rental fleets.
Application:
Surface preparation objectives determine equipment specification, with coating adhesion requirements driving the most stringent performance standards.
- Concrete Surface Preparation:Profiling hardened concrete for epoxy, polyurethane, or cementitious overlay bonding represents the highest-volume application segment. China's high-speed rail expansion sustains equipment orders for heavy-duty scarification of bridge decks and platform surfaces.
- Asphalt Removal:Cold planing and full-depth milling of bituminous pavement supports road rehabilitation programs. German municipal road maintenance agencies specify battery-powered equipment for urban resurfacing under noise ordinance constraints.
- Paint Removal:Coating stripping from steel and concrete substrates serves marine and industrial maintenance contractors.
- Grooving:Longitudinal and transverse texturing of runway and highway surfaces improves skid resistance.
- Pavement Repair:Localized full-depth removal and patching preparation targets municipal maintenance budgets.
Concrete surface preparation dominates current procurement; asphalt removal applications are climbing the fastest as battery technology penetrates municipal fleets.
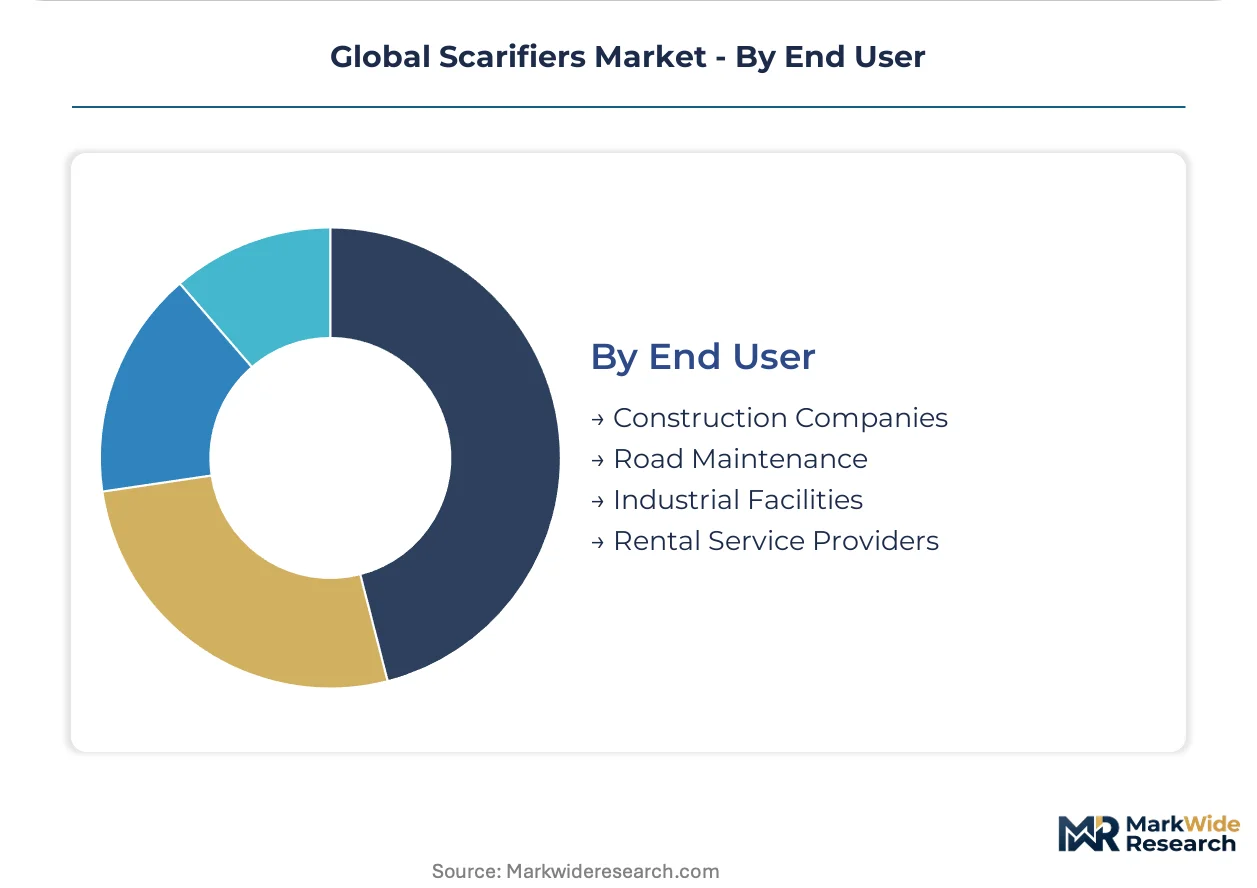
End User:
Customer scale and equipment utilization patterns create divergent purchasing behaviors, with rental access displacing capital ownership among smaller operators.
- Rental Service Providers:National equipment rental chains consolidate fleet standardization decisions previously fragmented across contractor purchasing departments. Battery-electric platform adoption accelerates through multi-year municipal rental frameworks in Germany rather than direct ownership.
- Construction Companies:General and specialty contractors with sustained utilization rates justify capital expenditure for owned equipment, particularly in high-volume concrete and asphalt segments.
- Road Maintenance:Municipal and provincial agencies operate under public procurement mandates specifying zero-emission platforms for urban zones.
- Industrial Facilities:Manufacturing plant maintenance departments prioritize dust collection integration and OSHA silica compliance over acquisition cost.
Rental service providers are capturing share fastest; construction companies retain the largest equipment ownership base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's municipal procurement mandates for battery-powered scarifiers contrast with China's infrastructure-driven demand for heavy-duty diesel platforms, illustrating how regulatory intensity and construction phase create divergent equipment specifications across major markets.
Germany
Municipal road maintenance agencies in Berlin and Munich are expanding rental frameworks for battery-electric scarifiers to comply with urban noise ordinances. The EU Green Deal's emissions standards for construction equipment are accelerating fleet turnover before mechanical end-of-life. The industrial corridor spanning North Rhine-Westphalia and Baden-Württemberg hosts warehouse floor maintenance contractors integrating vacuum-assisted dust collection systems to meet REACH compliance timelines.
China
Provincial infrastructure rehabilitation programs in Sichuan and Jiangsu are driving sustained orders for concrete surface preparation equipment on high-speed rail expansion projects. The Ministry of Ecology and Environment (MEE) is tightening emissions oversight in urban resurfacing zones, pushing contractors toward battery-powered alternatives. The Yangtze River Delta manufacturing cluster around Shanghai is scaling production of lithium-ion powered scarifiers to serve domestic and export demand.
United States
Warehouse and logistics facility construction in Texas and California is sustaining floor scarifier demand from rental service providers consolidating fleet decisions. OSHA silica exposure limits are reshaping product design priorities, compelling manufacturers to integrate dust collection systems as standard configurations. The Southeast industrial belt spanning Georgia and the Carolinas is seeing cold-chain facility expansion creating first-mover opportunities for equipment rental networks.
India
Underpenetrated logistics infrastructure in Maharashtra and Karnataka is creating demand for floor scarifier rental networks targeting emerging warehousing zones. The Bureau of Indian Standards (BIS) is developing construction equipment emissions frameworks that will eventually constrain diesel platform access in urban centers. The Delhi-Mumbai Industrial Corridor is seeing cold-chain facility construction that requires concrete surface preparation for epoxy coating adhesion.
Japan
Manufacturing plant maintenance departments in the Kanto region around Tokyo are prioritizing dust-free surface profiling equipment to meet stringent indoor air quality protocols. METI energy efficiency standards are influencing procurement preferences toward electric and battery-powered platforms in fixed-site industrial operations. The Osaka-Kobe industrial zone is maintaining demand for precision surface planers in automotive and electronics facility coating applications.
Global Scarifiers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across scarifier market tiers, creating a structure where scale advantages in manufacturing ecosystems clash with agility in battery-powered technology segments. The vendor base clusters around three strategic archetypes: power-tool ecosystem leaders leveraging cross-selling through dealer networks, municipal fleet specialists anchoring geographic dominance in European public procurement, and diversified outdoor equipment manufacturers extending lawn-and-garden platforms into surface preparation. Competitive moves concentrate on portfolio electrification and rental channel penetration rather than horizontal consolidation.
Among power-tool ecosystem players, Makita exemplifies manufacturing scale leverage through its existing dealer infrastructure. STIHL occupies a position representing battery-powered technology leadership in residential and light-commercial segments. Husqvarna anchors the municipal fleet specialist archetype through geographic concentration in European public agency procurement. These three companies illustrate how divergent strategic foundations—manufacturing scale, technology specialization, and geographic anchoring—create distinct competitive positions without direct feature-for-feature competition.
| Leading Market Players |
|---|
| TORO |
| Einhell |
| STIHL |
| AL-KO |
| STIGA SpA |
| Husqvarna |
| John Deere |
| Makita |
| MTD Products |
| Others |
Supply & Pricing Matrix
Municipal battery-electric procurement mandates in Germany are forcing manufacturers to absorb lithium-ion cell cost volatility while maintaining price accessibility for rental fleet operators, compressing margin buffers across the supplier base.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing cluster are reshaping price floors for battery-powered scarifier platforms. Three-tier pricing structure across premium, standard, and economy levels separates certified EU-compliant equipment from domestic-tier products and unbranded alternatives. Cost compression in the economy tier is intensifying because REACH certification timelines create compliance barriers for smaller assemblers. Rental service providers demonstrate the highest price sensitivity due to fleet standardization leverage, while industrial facility buyers prioritize dust collection integration over acquisition cost.
Supply Chain Analysis
Freight cost differentials between Asian manufacturing hubs and European distribution centers are amplifying landed cost advantages for regional battery assembly operations. Component sourcing concentrates in China for lithium-ion cells, Germany for precision cutter drum machining, and Japan for brushless DC motor controllers. Raw material dependencies include cobalt from the Democratic Republic of Congo, lithium carbonate from Chile, and high-grade steel alloys from South Korea. Single-source vulnerability in cobalt hydroxide refining creates supply chain risk. Distribution runs through national rental chains with fleet standardization leverage, displacing traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on lithium-ion energy density improvements enabling cordless platforms to command premium positioning previously reserved for diesel equipment, while REACH compliance investments create defensive moats.
For Market Incumbents: Acquire certified in-house testing capabilities to secure EU market access against delayed entrants. Defensive consolidation should prioritize backward integration into lithium-ion pack assembly to reduce cell cost volatility exposure. Shot blaster substitution in industrial facilities with OSHA silica protocols represents the named threat requiring counter-positioning through dust collection integration. For New Entrants and Emerging Players: Rental service provider partnerships offer the fastest channel to fleet standardization decisions previously fragmented across contractor purchasing departments. India's underpenetrated warehousing infrastructure presents the most penetrable geography for cold-chain facility surface preparation equipment. Battery recycling mandate preparation in the EU creates a go-to-market angle for certified compliance-first positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with battery-electric technology specialists possessing certified testing infrastructure and rental channel relationships. Long-term viability over the next decade favors manufacturers with in-house vertical control over drivetrain platforms rather than assembly-dependent operations. The signal to watch is carbon border adjustment mechanism implementation timelines, which will determine cross-border equipment sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Platform Migration | EU Green Deal emissions standards and German municipal mandates accelerate zero-emission fleet turnover. |
| REACH Compliance Certification | ECHA restrictions on hydraulic fluids and drum coatings create competitive moats for certified manufacturers. |
| Rental Channel Penetration | National equipment rental chains consolidate buyer power through multi-year municipal framework agreements. |
| Dust Collection Integration | OSHA silica exposure limits compel vacuum-assisted systems as standard configurations in US industrial facilities. |
| Battery Recycling Infrastructure | EU battery passport requirements favor manufacturers with in-house testing and certified recycling partnerships. |
Research Methodology
Direct dialogue with municipal fleet procurement officers, rental service provider inventory managers, OEM product development directors, and aftermarket service technicians grounded qualitative findings. Secondary validation drew from EU ECHA regulatory filings, German KBA equipment registration databases, Chinese MIIT industrial production statistics, and customs trade flow records. Bottom-up and top-down triangulation cross-checked equipment shipment volumes against infrastructure spending commitments.
Bottom-up modeling segmented the addressable market by power source technology, application substrate type, and end-user procurement mode across the projection horizon. Top-down validation anchored on construction equipment emissions enforcement intensity and infrastructure rehabilitation program budgets. CAGRs were derived from equipment replacement cycle compression and technology platform transition rates. Forecast inputs included lithium-ion cell cost curves and REACH compliance timeline enforcement patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment implementation and battery raw material supply concentration. Forecasts reflect documented assumptions about regulatory enforcement continuity and technology cost reduction trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Forging Press Market
Tools
Tile Saw Market
Tools
Wire Cutters Market
Tools
Cordless Multi Rotary Tools Market
Tools
Global DC Torque Tool Market
Tools
Deburring Tool Market
Tools
Global Construction Camera Market
Tools
Mortiser Market
Tools
CNC Metal Cutting Machine Tools Market
Tools
Masonry Cleaners Market
Tools
Woodworking Router Bits Market
Tools
Welding Guns Market
Tools
Bandsaw Machines Market
Tools
Global Standard Parts for Tool Making Market
Tools
Rotary Tools Market
Tools
Gas Cutting Machine Market