
 GCC Home Textile Market | 2026-2036
GCC Home Textile Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Home Textile Market Foresight
Asset-light leasing and project finance for hospitality fit-outs is narrowing the competitive field for mid-scale suppliers. Al-Abdullatif Industrial Investment Company leverages captive spinning capacity to anchor its position in Saudi institutional contracts. Orient Textiles International LLC sustains regional dominance through vertical control over dyeing and finishing operations in the UAE. IKEA competes on flat-pack logistics and standardized cotton-polyester blends that reduce inventory risk for franchise partners.
GCC home textiles encompass woven, knitted, and non-woven fabric products engineered for interior residential and commercial environments, typically specified by thread count, GSM weight, and flammability ratings per hospitality procurement standards. These products serve functional purposes including thermal insulation, acoustic dampening, and hygiene maintenance in climate-controlled Gulf interiors. Bedsheets and towels command the largest volume pools, though cushion covers and rugs carry higher margin concentration in boutique hotel and vacation rental channels. Cotton remains the preferred material for skin-contact applications, while polyester blends dominate institutional procurement where wash durability and cost predictability outweigh natural fiber premiums.
Saudi Standards, Metrology and Quality Organization (SASO) textile labeling requirements and UAE MOIAT product conformity schemes shape import clearance protocols and local testing obligations for foreign suppliers. The EU Green Deal's indirect influence through GCC hospitality brand owners is elevating OEKO-TEX and GOTS certification requirements in procurement tenders. Stakeholders must monitor how Dubai Municipality building codes and Saudi Building Code updates integrate textile flammability standards with broader interior fit-out regulations across new hospitality and residential developments.
Market Dynamics
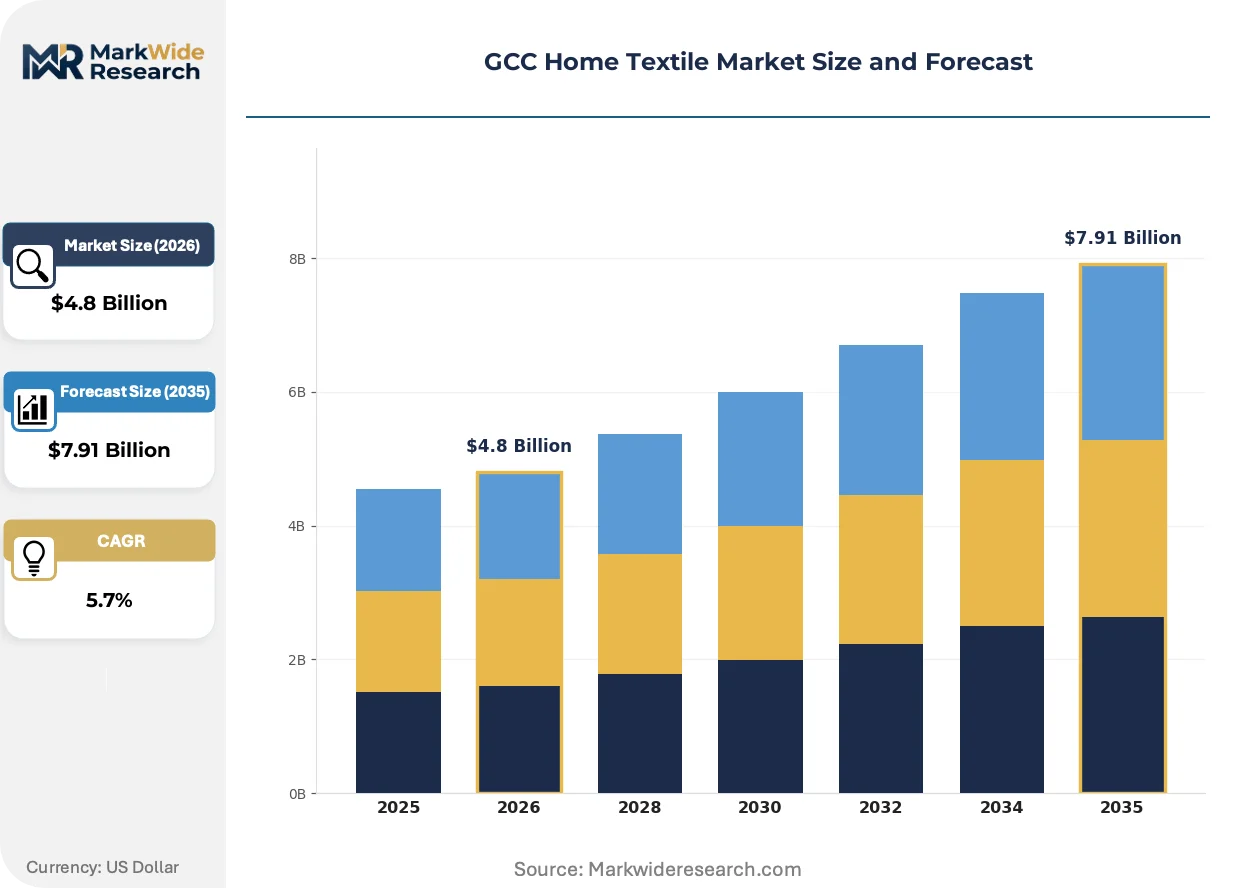
Hospitality procurement mandates under Saudi Vision 2030 are forcing rapid recalibration of supplier capabilities, with fire-retardant certification and sustainable sourcing requirements now embedded in institutional tender specifications. This regulatory compression is squeezing mid-scale suppliers while rewarding vertically integrated players with captive testing and certification infrastructure.
Growth Catalysts
- Saudi Vision 2030 hospitality mandates:Institutional procurement specifications now require OEKO-TEX and GOTS certifications for all linen and soft furnishing contracts above threshold values. This creates qualified supplier scarcity that benefits certified incumbents.
- Dubai design district clustering:Concentrated boutique hotel development in D3 and Alserkal Avenue corridors generates localized demand spikes for premium cushion covers and artisan rugs with compressed delivery timelines.
- Fire-retardant textile standards:SASO and UAE MOIAT conformity schemes are accelerating substitution of untreated cotton with inherently flame-resistant fiber blends in commercial fit-outs.
Market Restraints
- Cotton price volatility:Raw material cost swings tied to Pakistani and Indian monsoon patterns compress margin predictability for spinners without backward integration into fiber trading.
- Testing infrastructure concentration:SASO-authorized laboratories cluster in Riyadh and Jeddah, creating clearance bottlenecks for suppliers based in Dammam or smaller Emirates.
- Polyester blend substitution:Institutional buyers in healthcare and budget hospitality segments are prioritizing wash durability over natural fiber premiums, capping cotton volume expansion.
Strategic Opportunities
- Kuwait and Bahrain underpenetration:These markets lack domestic dyeing and finishing capacity, creating import dependency that regional UAE-based suppliers can exploit with bonded warehousing.
- EU Green Deal regulatory tailwind:European hospitality brand owners operating GCC properties are extending OEKO-TEX requirements to their Middle Eastern supply chains, opening certified supplier premiums.
- Direct-to-hotel digital platforms:Procurement departments at mid-scale hotel groups are bypassing traditional trading houses through specialized B2B textile marketplaces with specification filtering tools.
Industry Challenges
- Certification timeline compression:SASO textile labeling requirements now demand concurrent submission of fiber composition and flammability test reports, extending new product introduction cycles by 6-8 weeks.
- Skilled dyehouse technician scarcity:UAE-based finishing operations face recruitment gaps for specialists capable of managing low-water dyeing equipment and color-matching to hospitality brand standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Home Textile Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedsheets, Curtains, Cushion Covers, Towels, Table Linens, Rugs Material: Cotton, Polyester, Silk, Linen, Wool, Jute Application: Residential, Boutique Hotels, Vacation Rentals, Corporate Housing, Boutique Stores, Home Staging Distribution Channel: Retail Stores, E-Commerce Platforms, Wholesale Suppliers, Specialty Boutiques, Department Stores |
| Companies Covered | Al-Abdullatif Industrial Investment Company, Orient Textiles International LLC, IKEA, Frugado, Dicitex, Al Sorayai Group, Housetex, Zara Home, Bycop Group, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Home Textile Market Shifts & Advancements
Material science advances and procurement digitization are converging to reshape competitive positioning in GCC home textiles. Suppliers are racing to integrate certification compliance with production flexibility.
Recycled cotton-polyester hybrid fiber is hybridizing conventional bedding manufacturing, blending post-industrial cotton waste with virgin polyester to meet SASO recycled content thresholds without sacrificing GSM consistency. Boutique hotel chains in Riyadh's King Abdullah Financial District are piloting these blends for staff uniforms and guest linens simultaneously. This hybridization is compressing the price gap between certified sustainable and conventional virgin fiber tiers.
SASO textile labeling amendments now mandate Arabic-language fiber composition disclosure alongside English, with random market surveillance testing expanded to retail channels beyond import checkpoints. Foreign suppliers face relabeling costs and localized packaging redesign obligations. Dubai-based hospitality distributors are absorbing these compliance burdens through pre-clearance consolidation hubs to protect franchise partner margins.
Boutique hotel procurement departments are consolidating vendor lists and demanding single-source accountability for fire-retardant certification across entire soft furnishing suites. Trading houses with fragmented supplier bases are losing share to vertically integrated mills capable of warranting full specification compliance. This concentration is most visible in Abu Dhabi's Saadiyat Island cultural district developments, where procurement teams have reduced approved linen suppliers from twelve to four qualified vendors.
GCC Home Textile Market Segmentation
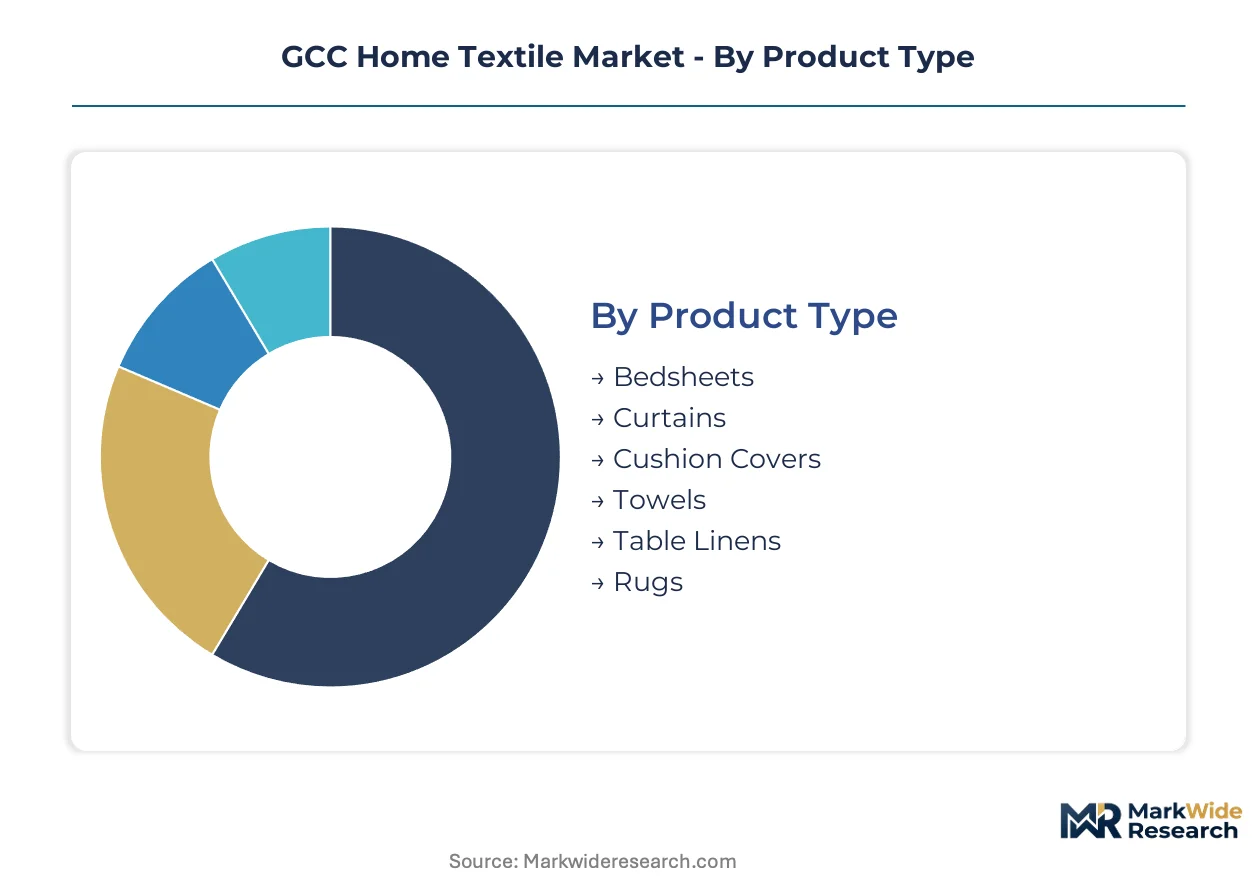
Segmentation in GCC home textiles reveals how procurement specifications diverge across hospitality mandates, residential climate control needs, and retail channel economics. Each dimension exposes different margin structures and certification burdens that reshape supplier positioning.
Product Type:
Mature segments dominate volume throughput while emerging categories capture premium repositioning opportunities.
- Bedsheets:High-thread-count cotton and cotton-polyester blends constitute the baseline specification for institutional procurement. Saudi Vision 2030 hospitality contracts now mandate OEKO-TEX certification for all bedsheet volumes above tender thresholds, compressing qualified supplier pools.
- Towels:GSM-weighted terry cloth specifications vary sharply between healthcare institutional buyers and boutique hotel segments. Dubai's design district hotels are specifying heavier Turkish cotton weaves that command 40% price premiums over standard hospitality grades.
- Curtains:Fire-retardant lining requirements under SASO amendments are accelerating substitution of untreated fabrics.
- Cushion Covers:Artisan and embroidered variants concentrate margin in vacation rental and boutique hotel channels.
- Table Linens:Institutional procurement favors polyester blends for wash durability in high-turnover food service environments.
- Rugs:Hand-tufted wool and jute compositions serve residential and boutique store segments with extended production lead times.
Bedsheets handle the majority of throughput; cushion covers are expanding most quickly on share.
Material:
Cost tier stratification separates natural fiber premiums from synthetic durability plays across institutional and residential buyers.
- Cotton:Long-staple Egyptian and Pima varieties anchor skin-contact applications in hospitality and residential segments. Pakistani and Indian monsoon volatility compresses margin predictability for spinners lacking backward integration into fiber trading.
- Polyester:Virgin and recycled PET fiber blends dominate healthcare and budget hospitality procurement where wash-cycle durability outweighs natural fiber aesthetics. Recycled cotton-polyester hybrids are hybridizing bedding manufacturing to meet SASO recycled content thresholds.
- Silk:Limited to ultra-premium residential and boutique hotel accent applications.
- Linen:Belgian and French flax imports serve climate-conscious residential buyers in Riyadh's emerging luxury corridors.
- Wool:New Zealand and Australian merino grades concentrate in rug and upholstery applications.
- Jute:Bangladeshi and Indian imports supply sustainable-positioned rug and decorative segments.
Polyester commands the largest volume base; recycled cotton-polyester hybrid fiber is climbing the fastest.
Application:
Customer type fragmentation splits between institutional procurement discipline and residential discretionary spending patterns.
- Residential:Individual buyers prioritize thread count and tactile quality for master bedroom and living room investments. Riyadh's King Abdullah Financial District and Dubai's Mohammed Bin Rashid City are generating concentrated demand for premium linen sets.
- Boutique Hotels:Consolidated vendor lists and single-source accountability requirements are squeezing fragmented trading houses. Saadiyat Island cultural district developments have reduced approved linen suppliers from twelve to four qualified vendors.
- Vacation Rentals:Platform-driven standardization is compressing specification variance across short-term hospitality assets.
- Corporate Housing:Extended-stay operators prioritize wash durability and cost predictability over design differentiation.
- Boutique Stores:Curated artisan and limited-run textiles serve design-conscious residential buyers.
- Home Staging:Real estate marketing cycles drive episodic demand for neutral-toned, photograph-ready soft furnishings.
Residential absorbs the greatest absolute volume; boutique hotels are gaining share fastest on certification-driven supplier consolidation.
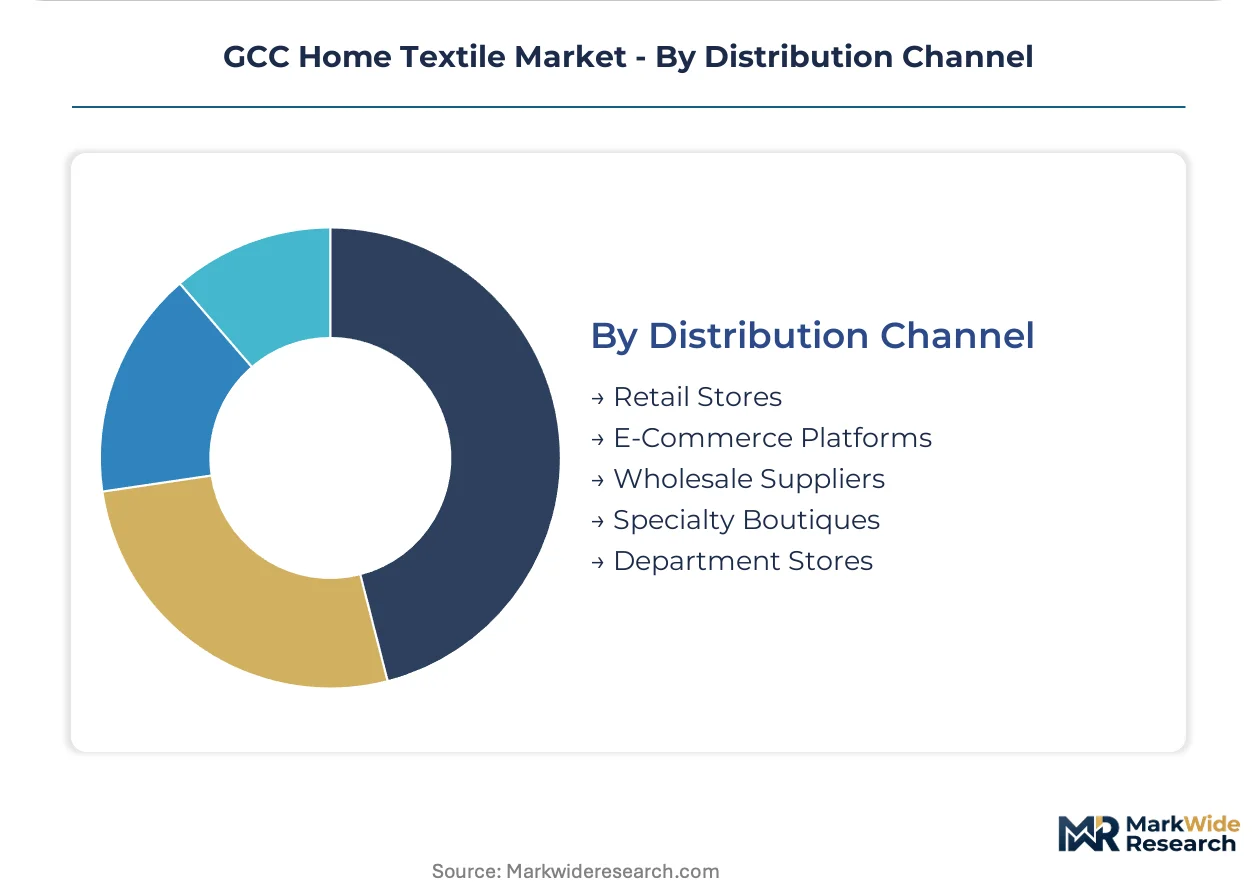
Distribution Channel:
Supply concentration in bonded warehousing and pre-clearance hubs is reshaping channel economics for foreign suppliers.
- Retail Stores:IKEA's flat-pack logistics and standardized cotton-polyester blends reduce inventory risk for franchise partners across Saudi Arabia and the UAE.
- E-Commerce Platforms:Direct-to-hotel digital marketplaces with specification filtering tools are enabling mid-scale hotel groups to bypass traditional trading houses.
- Wholesale Suppliers:Dubai-based hospitality distributors are absorbing SASO relabeling costs through pre-clearance consolidation hubs.
- Specialty Boutiques:Alserkal Avenue and D3 design district clusters generate localized demand spikes with compressed delivery timelines.
- Department Stores:Multi-brand aggregation serves residential buyers seeking one-stop soft furnishing procurement.
Wholesale suppliers handle the majority of institutional throughput; e-commerce platforms are expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Vision 2030 hospitality procurement mandates are redistributing supplier concentration across Gulf markets, with certification requirements now filtering entry into institutional contracts. This policy compression is elevating vertically integrated domestic players while foreign suppliers absorb compliance costs through bonded warehousing hubs.
Saudi Arabia
Riyadh's King Abdullah Financial District and emerging luxury residential corridors are generating concentrated demand for OEKO-TEX certified linens. SASO textile labeling amendments mandate Arabic-language fiber composition disclosure alongside fire-retardant test reports. Jeddah's industrial zones host the kingdom's densest cluster of dyeing and finishing operations serving hospitality fit-outs.
United Arab Emirates
Dubai's design district clusters in D3 and Alserkal Avenue are driving localized spikes for artisan cushion covers and premium rugs with compressed delivery timelines. Dubai Municipality building codes integrate textile flammability standards with interior fit-out regulations across new hospitality developments. Abu Dhabi's Saadiyat Island cultural district has consolidated approved linen suppliers from twelve to four qualified vendors.
Kuwait
Institutional procurement for healthcare and corporate housing segments is expanding without domestic dyeing and finishing capacity to match. The country's national standards body enforces import conformity schemes that create clearance dependencies on regional UAE-based suppliers. Bonded warehousing in Kuwait City is absorbing last-mile distribution for foreign textile traders.
Bahrain
Boutique hotel development in Manama's financial harbor district is sourcing premium soft furnishings through cross-border UAE suppliers. The national commercial regulator maintains product safety labeling requirements aligned with Gulf Cooperation Council harmonized standards. Seef and Muharraq retail corridors concentrate residential demand for imported linen sets.
GCC Home Textile Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated mills capable of warranting full specification compliance across fire-retardant and sustainable certification requirements. Fragmented trading houses with dispersed supplier bases are losing share to captive production operators. Three archetypes dominate: Saudi-based institutional contractors with captive spinning, UAE-based finishers with dyehouse control, and flat-pack logistics specialists serving franchise retail networks. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure SASO-authorized testing access.
Within the vertically integrated tier, Al-Abdullatif Industrial Investment Company anchors Saudi institutional contract flows through captive spinning infrastructure, while Orient Textiles International LLC exemplifies UAE-based finishers controlling dyeing and finishing operations. IKEA occupies a distinct position leveraging flat-pack logistics and standardized cotton-polyester blends that reduce inventory risk for franchise partners across the kingdom and emirates.
| Leading Market Players |
|---|
| Al-Abdullatif Industrial Investment Company |
| Orient Textiles International LLC |
| IKEA |
| Frugado |
| Dicitex |
| Al Sorayai Group |
| Housetex |
| Zara Home |
| Bycop Group |
| Others |
Supply & Pricing Matrix
Cotton price volatility tied to Pakistani and Indian monsoon patterns compresses margin predictability for spinners while simultaneously widening spreads between certified sustainable tiers and conventional virgin fiber grades. This commodity exposure forces buyers into longer-term contracting for OEKO-TEX certified volumes, reshaping procurement timelines and inventory financing structures across institutional hospitality contracts.
Pricing Analysis
Certification level creates the primary spread across GCC home textile procurement, with OEKO-TEX and GOTS-certified products commanding substantial premiums over uncertified alternatives in Saudi Vision 2030 hospitality tenders. Three-tier pricing structure separates fire-retardant institutional grades from standard hospitality weaves and economy polyester blends for healthcare segments. Cost compression in mid-scale cotton bedding is intensifying because Pakistani and Indian fiber supply disruptions cascade through spinning operations without backward integration into fiber trading. Budget hospitality and healthcare buyers exhibit highest price sensitivity, while boutique hotel procurement departments prioritize single-source accountability over unit cost minimization.
Supply Chain Analysis
UAE MOIAT conformity schemes and SASO textile labeling requirements function as de facto export controls, restricting clearance velocity for suppliers lacking pre-certification infrastructure in authorized Riyadh and Jeddah laboratories. Geographic supply concentration centers on Saudi Arabia's captive spinning corridors, UAE's dyeing and finishing zones in Jebel Ali, and India's long-staple cotton export belt. Raw material dependencies draw from Pakistani and Indian cotton harvests, Belgian and French flax imports for linen segments, and Bangladeshi jute for sustainable rug applications. Single-source vulnerability concentrates in SASO-authorized testing capacity clustered around Riyadh and Jeddah, creating clearance bottlenecks for Dammam-based suppliers. Distribution runs through Dubai-based pre-clearance consolidation hubs that absorb relabeling costs for foreign suppliers serving franchise retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC home textile market sits in early-cycle recovery as Saudi Vision 2030 hospitality mandates force capital deployment into certified production capacity, with procurement volume inflections tracking construction completions in Riyadh's King Abdullah Financial District and Dubai's design district clusters.
For Market Incumbents: Insulate institutional contract positions by accelerating captive testing infrastructure investments near SASO-authorized laboratory clusters, while securing multi-year fiber supply agreements with Pakistani and Indian trading houses to neutralize monsoon-driven margin volatility. Al-Abdullatif Industrial Investment Company's spinning integration model offers a template for backward control over fiber procurement that emerging competitors cannot replicate without substantial capital commitments.
For New Entrants and Emerging Players: Build out bonded warehousing capabilities in Kuwait City and Manama to exploit underpenetrated healthcare and corporate housing segments lacking domestic dyeing and finishing capacity, positioning as compliant intermediaries for UAE-based finishers seeking last-mile distribution coverage. Direct-to-hotel digital platforms with specification filtering tools represent the most penetrable channel for bypassing entrenched trading house relationships at mid-scale hotel groups.
For Investors and Strategic Acquirers: SASO textile labeling amendments reshaping the acquisition landscape by elevating the strategic value of vertically integrated mills with in-house certification infrastructure over fragmented trading house aggregators. Long-term viability across the analysis window favors targets with demonstrated compliance velocity under compressed timeline requirements. The signal to watch is boutique hotel procurement department vendor list consolidation rates, particularly in Abu Dhabi's Saadiyat Island cultural district developments where approved supplier pools have compressed from twelve to four qualified vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | SASO-authorized laboratory access accelerates new product introduction cycles for institutional hospitality contracts. |
| Backward Integration into Fiber Trading | Direct Pakistani and Indian cotton sourcing neutralizes monsoon-driven margin compression for spinning operations. |
| Bonded Warehousing Expansion | Kuwait and Bahrain pre-positioning captures healthcare and corporate housing demand without domestic finishing capacity. |
| Direct-to-Hotel Digital Platform Launch | Specification filtering tools enable mid-scale hotel groups to bypass traditional trading house intermediaries. |
| Recycled Content Hybrid Development | Cotton-polyester blends meeting SASO recycled thresholds compress price gaps between certified and conventional tiers. |
Research Methodology
The analysis maps bedsheet, towel, curtain, cushion cover, table linen, and rug sub-sectors, each validated through procurement directors at boutique hotel chains, hospitality fit-out contractors, textile mill operations managers, and SASO compliance officers. Primary interviews with these stakeholders combined with secondary validation from customs trade databases, Saudi Standards, Metrology and Quality Organization regulatory filings, Dubai Municipality building code amendments, and EU Green Deal documentation covering indirect supply chain influence. Bottom-up volume estimates triangulated against top-down hospitality construction pipeline valuations across the analysis window.
Forecast assumptions held fixed the current SASO textile labeling amendment framework and UAE MOIAT conformity scheme structures, while varying cotton price volatility bands, boutique hotel development completion rates, and certification adoption curves across the projection horizon. Segmentation dimensions modeled include product type, material composition, application segment, and distribution channel, with CAGRs derived from regression analysis against hospitality construction spend and procurement specification evolution. Industry-specific forecast inputs incorporated OEKO-TEX and GOTS certification penetration rates and fire-retardant fiber substitution elasticities in commercial fit-out specifications.
Stress conditions across Pakistani and Indian monsoon severity, SASO regulatory enforcement intensity, and EU hospitality brand owner certification extension rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions without claiming predictive certainty for exogenous shocks. Material shifts in Saudi Vision 2030 hospitality mandate scope or Dubai Municipality building code textile flammability integration timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Mexico Home Textile Market
Home Textiles
Baby Crib Sheet Market
Home Textiles
Bangladesh Home Textile Market
Home Textiles
India Home Textile Market
Home Textiles
United Kingdom Home Textile Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Blanket Market
Home Textiles
Bath Towel Market
Home Textiles
Wool Dryer Ball Market
Home Textiles
Europe Home Textile Market
Home Textiles
Global Theater Linen Market
Home Textiles
China Home Textiles Market
Home Textiles
Turkey Home Textile Market
Home Textiles
Fabric Wash and Care Market
Home Textiles
Towel Market
Home Textiles
South Korea Home Textile Market