
 Stained Glass Market | 2026-2036
Stained Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Stained Glass Market Analysis
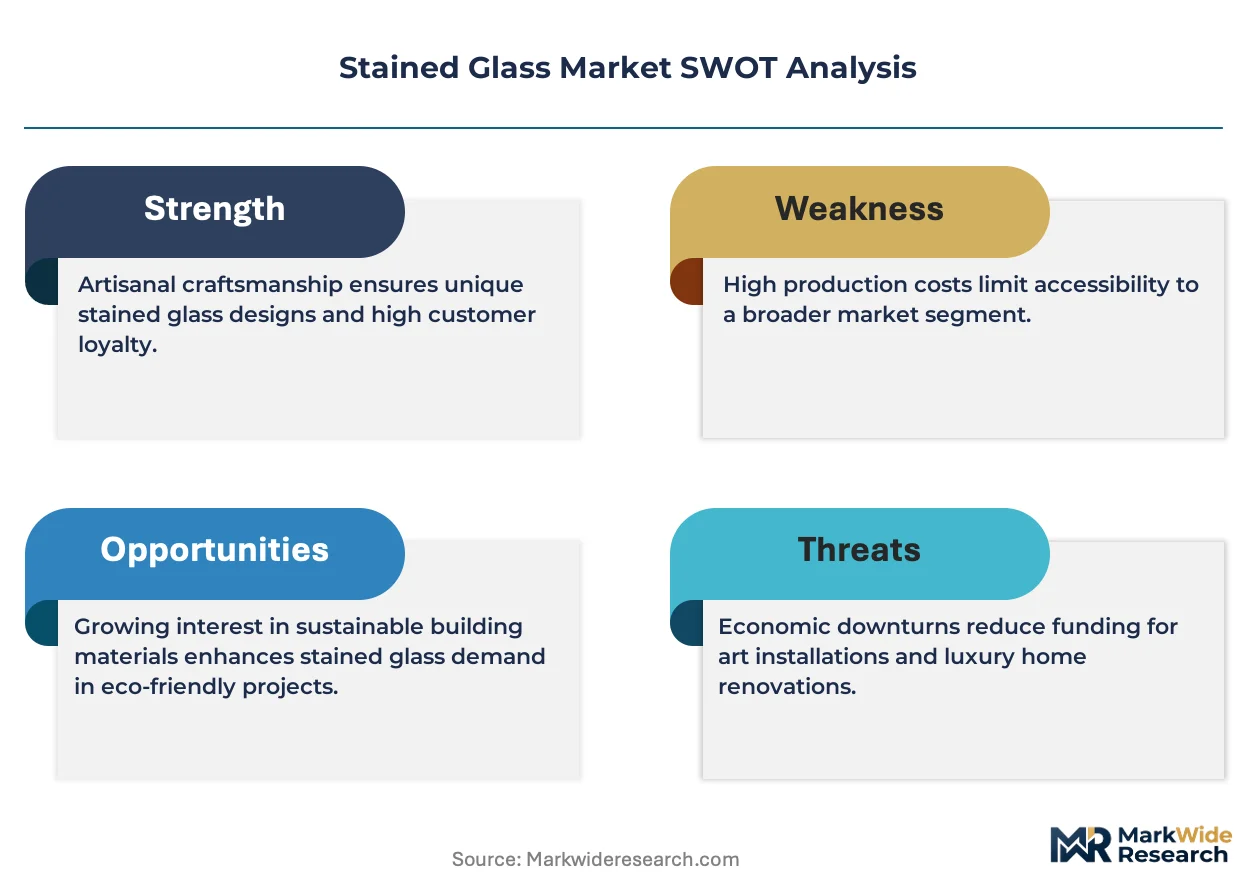
Religious institution renovation is rebalancing toward commercial building integration as hospitality and retail brands commission custom installations. Willet Studios leverages its ecclesiastical heritage to anchor high-value restoration contracts across North American cathedrals. Conrad Schmitt Studios sustains century-old craftsmanship credentials to differentiate in museum and courthouse projects. Bullseye Glass Co. competes through kiln-formed technical capabilities that extend beyond traditional leaded methods.
Stained glass comprises colored glass pieces joined by lead cames or copper foil, fired with metallic oxide pigments at temperatures exceeding 1,200 degrees Fahrenheit to achieve light transmission and weather resistance for architectural and decorative applications. Window Panels dominate value capture due to structural installation requirements and permanence premiums in landmark buildings. Decorative Art registers the fastest expansion as interior designers specify commissioned panels for luxury residential and boutique hospitality environments. Restoration installations concentrate margin pools where specialist labor scarcity and heritage compliance create pricing power unavailable in new construction commodity work.
EPA lead-safe renovation rules govern residential and public building disturbance protocols, while OSHA workplace exposure limits shape studio ventilation and handling requirements across American manufacturing. CE marking under EU construction product regulations mandates structural safety and thermal performance testing for external architectural glazing installations. Stakeholders must monitor evolving chemical restrictions in both jurisdictions to anticipate reformulation costs and certification timelines that will determine competitive viability in premium heritage restoration segments.
Market Dynamics
Heritage restoration mandates across European ecclesiastical architecture are compressing leaded glass supply chains while accelerating lead-free pigment reformulation timelines. REACH compliance deadlines force studios to requalify entire color palettes before cathedral conservation contracts expire.
Growth Catalysts
- ECHA REACH Phase-Down:Lead-free solder mandates in the European Union are redirecting procurement toward certified studios with reformulated pigment portfolios, locking out non-compliant competitors from cathedral restoration tenders.
- Kiln-Formed Technical Glass:Architectural specification of kiln-formed panels for commercial atriums and hospitality lobbies extends addressable demand beyond traditional ecclesiastical commissioning cycles.
- France-Italy-Germany Concentration:State-funded cathedral conservation programs in these three markets concentrate specialist labor premiums and create pricing power unavailable in commodity new construction segments.
Market Restraints
- Cobalt and Cadmium Input Volatility:Metallic oxide pigments essential for color stability face supply concentration from Chinese refiners, compressing margin predictability for studios maintaining heritage-grade color matching.
- Specialist Labor Scarcity:Master glass painters and lead came craftsmen concentrate in aging European guild networks, constraining output expansion regardless of contract backlog.
- Structural Glazing Substitution:Digitally printed ceramic frit glass achieves comparable visual effects at lower installed cost for non-heritage commercial projects, capping price elasticity in new construction.
Strategic Opportunities
- Luxury Residential Commissioning:Interior designers in California and New York are specifying one-off panels for private estates, opening a channel with shorter sales cycles than institutional procurement.
- CE Marking Thermal Performance:Mandated structural safety and thermal testing under EU construction product regulations creates certification barriers that favor established studios with testing capital.
- Copper Foil Tiffany Revival:Convergence of lampworking techniques with architectural scale production is enabling boutique studios to compete for mid-size commercial commissions without lead came infrastructure.
Industry Challenges
- Heritage Color Matching Skill Gap:Fewer than two hundred master craftsmen globally possess the chemical knowledge to replicate nineteenth-century color palettes under modern safety protocols.
- Ventilation Retrofit Capex:EPA lead-safe renovation rules and OSHA workplace exposure limits require studio infrastructure investments that strain small and mid-size fabricators.
- Reformulation Timeline Compression:REACH certification windows for new pigment chemistries lag behind conservation contract award cycles, forcing studios to absorb compliance risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stained Glass Market |
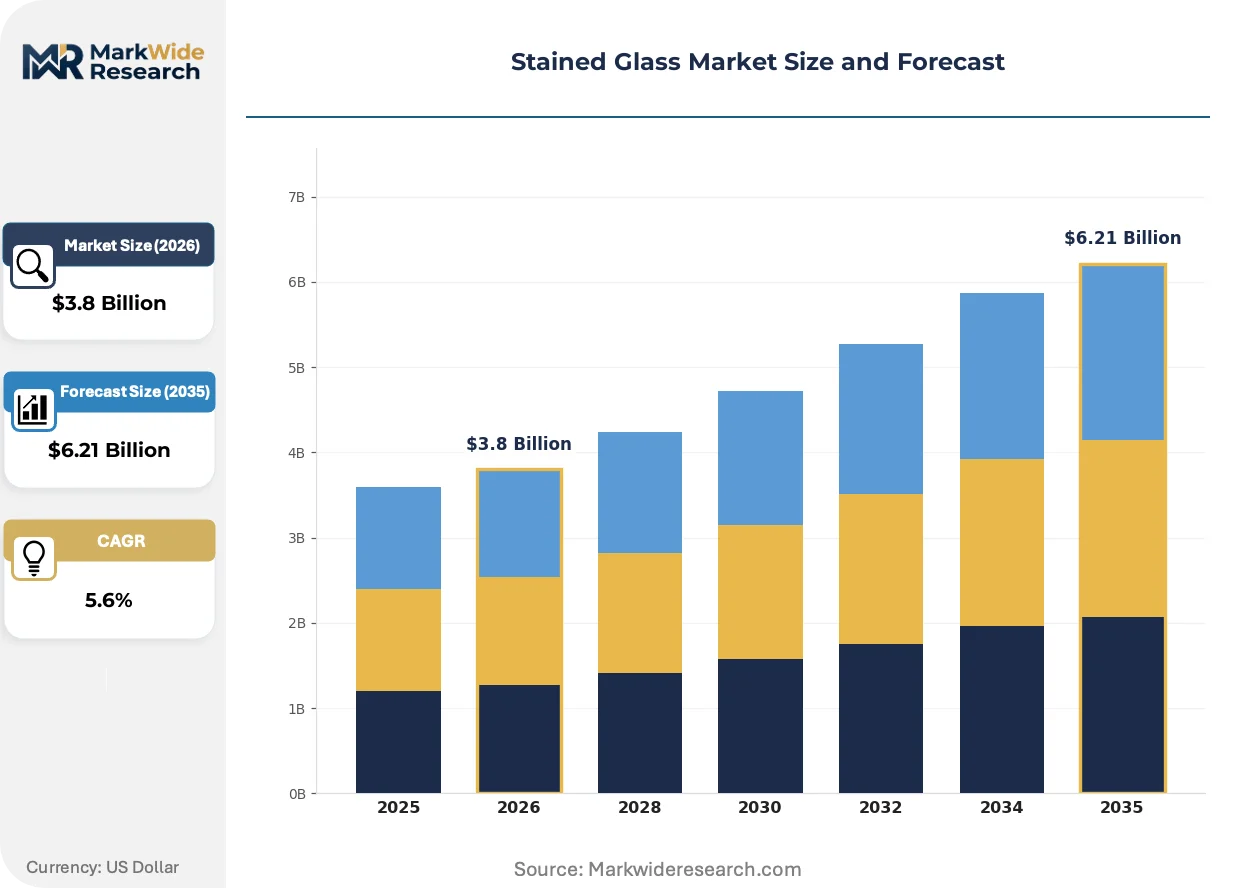
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Window Panels, Decorative Art, Lampshades, Doors End User: Religious Institutions, Commercial Buildings, Residential Homes, Educational Facilities Installation Type: New Construction, Renovation, Restoration, Custom Projects Design Complexity: Simple Patterns, Geometric Designs, Figurative Art, Abstract Styles |
| Companies Covered | Diamond Tech Glass, Willet Studios, Taizhou Wanda-Stained Glass Co., Ltd., Conrad Schmitt Studios, Jahn Studios, Pendle Stained Glass Ltd., Bullseye Glass Co., Kokomo Opalescent Glass Co., Aanraku Studios, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stained Glass Market Emerging Trajectories
Digital design workflows and material science advances are compressing traditional craftsmanship timelines while expanding the addressable surface area for architectural glass. Studios now compete on technical capability breadth rather than ecclesiastical heritage alone.
Copper-foil construction methods adapted from lampworking traditions are electrifying residential and boutique hospitality specifications where lead came weight and weathering constraints previously excluded stained glass. Interior designers specify these panels for feature walls and ceiling installations. The technique is compressing minimum viable project scales and enabling studio participation below traditional ecclesiastical contract thresholds.
REACH substance restrictions are forcing pigment chemistry substitution across European manufacturing. ECHA authorization requirements for lead compounds and certain cadmium derivatives are compressing available color palettes. Studios with in-house analytical laboratories and ECHA pre-registration dossiers are capturing heritage restoration contracts while competitors face reformulation delays.
Direct commissioning via digital portfolio platforms is fragmenting traditional dealer-gallery channels. Private collectors and commercial developers now source directly from studio websites and social media presence, bypassing the regional representative networks that historically controlled access to master craftsmen. This channel shift concentrates margin capture with producers but requires studios to absorb marketing and specification support functions previously outsourced.
Stained Glass Market Segmentation
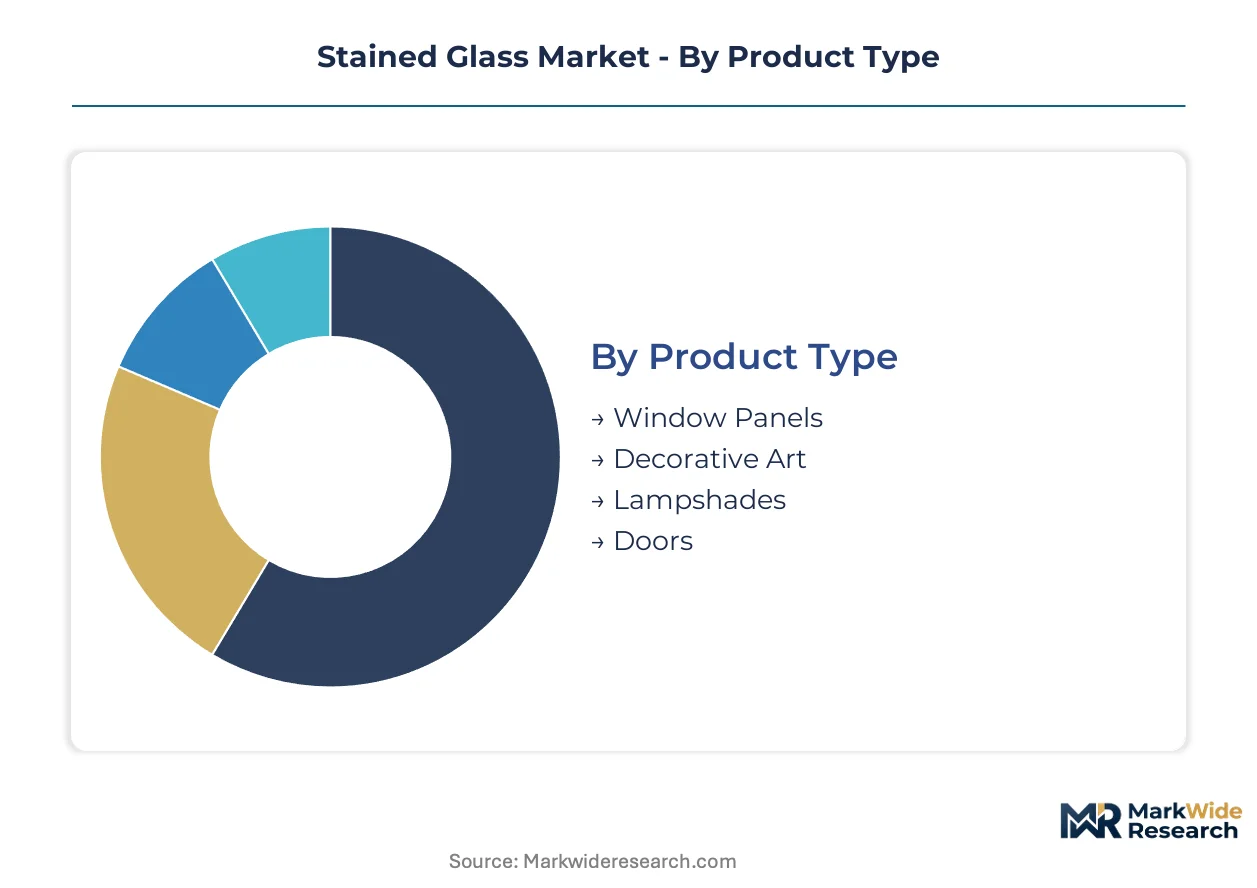
Segmentation in stained glass reveals how value migrates between permanent architectural installations and portable decorative objects. Product architecture determines whether studios compete on structural engineering credentials or artisanal craftsmanship alone.
Product Type:
Standalone architectural elements command structural certification premiums, while embedded decorative pieces compete on design velocity and shorter production cycles.
- Window Panels:Large-format leaded or copper-foil assemblies engineered for weather resistance and thermal performance. Religious institutions in France, Italy, and Germany fund cathedral conservation programs that lock in specialist labor premiums unavailable in commodity segments.
- Decorative Art:Kiln-formed and fused glass panels specified for interior feature walls and ceiling installations. Hospitality designers in California and New York commission one-off pieces, opening channels with shorter sales cycles than institutional procurement.
- Lampshades:Copper-foil Tiffany-method constructions adapted from historical lampworking traditions.
- Doors:Structural glazed entry systems combining stained glass with reinforced framing for heritage building retrofits.
Window Panels lead volumes today; Decorative Art is gaining share fastest.
End User:
Cost tiers separate heritage-funded ecclesiastical work from self-financed residential commissioning, with commercial projects occupying a volatile middle ground sensitive to construction cycles.
- Religious Institutions:Cathedrals, churches, and chapels with conservation mandates under national heritage programs. REACH compliance deadlines in the European Union force pigment reformulation before contract renewal cycles expire.
- Commercial Buildings:Hospitality atriums, retail flagship stores, and corporate lobbies. Kiln-formed technical glass specifications extend demand beyond traditional ecclesiastical commissioning patterns.
- Residential Homes:Luxury estates and boutique properties sourcing through direct digital platforms rather than dealer networks.
- Educational Facilities:Universities and private schools commissioning commemorative windows and donor recognition installations.
Religious Institutions anchor revenue concentration; Residential Homes show the steepest expansion trajectory.
Installation Type:
Volume concentration sits in new construction, yet margin pools concentrate where specialist labor scarcity and heritage compliance create pricing power unavailable in commodity work.
- New Construction:Standardized glazing for contemporary buildings where digitally printed ceramic frit glass substitutes at lower installed cost.
- Renovation:Residential and public building disturbance protocols governed by EPA lead-safe renovation rules in the United States.
- Restoration:Heritage-grade color matching requiring master craftsmen with chemical knowledge of nineteenth-century palettes under modern safety protocols.
- Custom Projects:Bespoke commissions for private collectors and commercial developers sourcing directly through studio digital portfolios.
New Construction dominates unit volumes; Restoration captures the highest margin premiums.
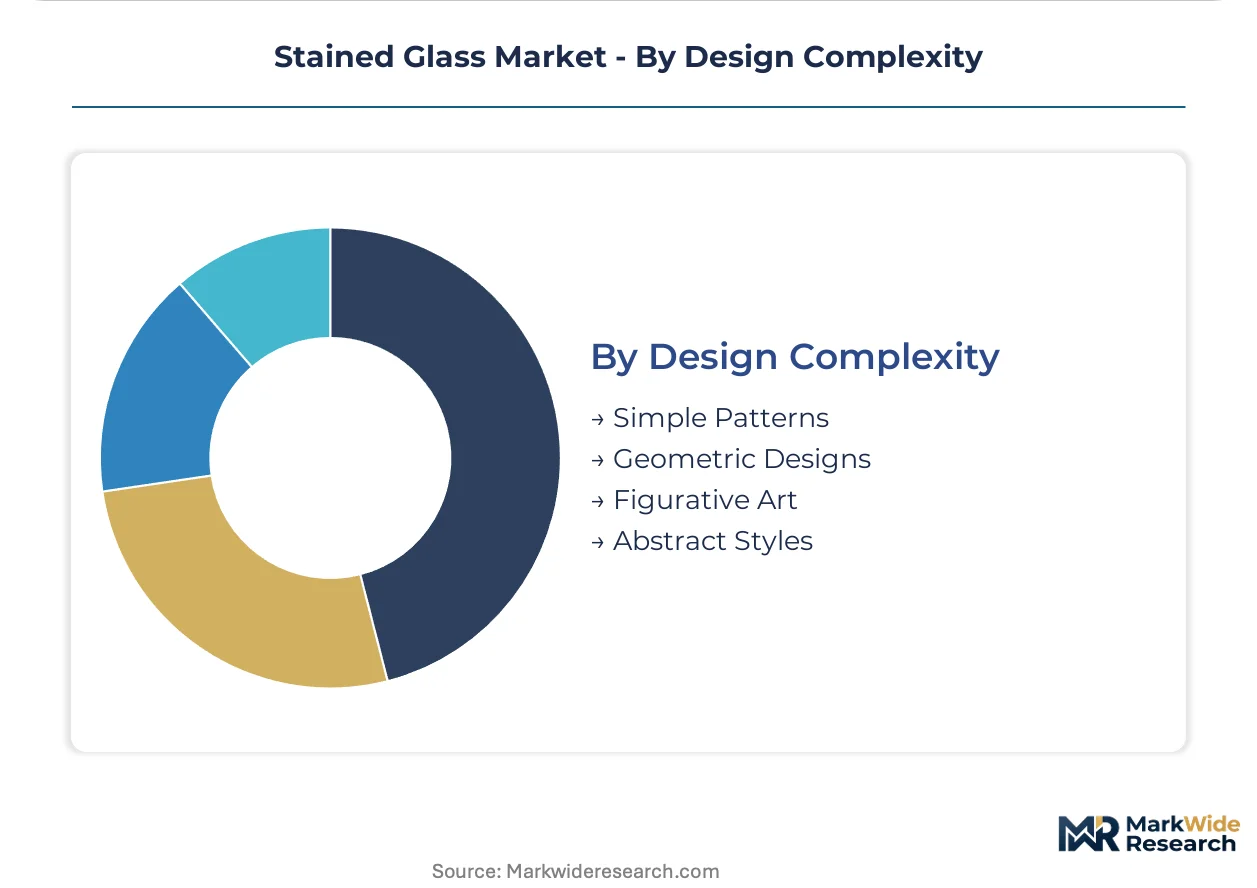
Design Complexity:
Maturity gradients separate mechanized production of repetitive geometries from hand-painted figurative work where skill scarcity constrains output regardless of demand.
- Simple Patterns:Repetitive geometric motifs producible through templated cutting and assembly methods.
- Geometric Designs:Complex tessellations and Islamic-inspired patterns requiring precise angle cutting and lead came fitting.
- Figurative Art:Hand-painted glass with silver stain and enamel firing depicting religious, historical, or narrative scenes. Fewer than two hundred master craftsmen globally possess the chemical knowledge to replicate heritage color palettes under OSHA workplace exposure limits.
- Abstract Styles:Contemporary non-representational compositions exploiting kiln-formed texture and light transmission effects.
Figurative Art commands price premiums; Abstract Styles are climbing fastest among interior designer specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is compressing European studio margins while redirecting investment toward jurisdictions with lower compliance burdens. Kiln-formed technical capabilities are migrating to North American manufacturing clusters where OSHA ventilation standards impose less severe reformulation costs than ECHA REACH mandates.
France
State-funded cathedral conservation programs in Île-de-France and Auvergne-Rhône-Alpes lock in specialist labor premiums for heritage restoration contracts. ANSM oversight of workplace chemical exposure shapes studio infrastructure requirements. The Chartres-Paris corridor concentrates master glass painters serving ecclesiastical procurement cycles.
United States
EPA lead-safe renovation rules govern residential and public building disturbance protocols across California and New York hospitality markets. OSHA workplace exposure limits shape studio ventilation investments in Pacific Northwest manufacturing clusters. Willet Studios anchors high-value restoration contracts through its ecclesiastical heritage positioning.
Germany
KBA technical standards for structural glazing installations create certification barriers favoring established fabricators. CE marking mandates under EU construction product regulations require thermal performance testing for external architectural applications. The Bavaria-Rhineland corridor hosts concentration of lead-free pigment reformulation laboratories.
Italy
Cathedral conservation mandates in Tuscany and Lombardy sustain demand for figurative art specialists capable of nineteenth-century color palette replication. ECHA REACH phase-down deadlines force pigment chemistry substitution timelines. The Florence-Venice axis preserves guild-network concentration of master craftsmen with heritage-grade chemical knowledge.
United Kingdom
Historic England listing protections drive restoration demand across Anglican ecclesiastical architecture. HSE workplace exposure regulations parallel OSHA standards with lower enforcement density than continental EU jurisdictions. The London-Manchester corridor fragments between heritage specialists and contemporary kiln-formed producers.
Stained Glass Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage restoration concentrating around century-old studios while commercial new construction fragments among technical fabricators. The vendor base organizes into three tiers: ecclesiastical heritage houses with conservation credentials, kiln-formed technical specialists, and commodity glass processors. Strategic moves center on pigment reformulation certification under REACH deadlines and direct-to-consumer digital channel development.
Among North American heritage houses, Willet Studios and Conrad Schmitt Studios exemplify the ecclesiastical restoration archetype, leveraging conservation credentials to anchor cathedral contracts. Bullseye Glass Co. occupies a position within the kiln-formed technical tier, extending capabilities beyond traditional leaded methods. Taizhou Wanda-Stained Glass Co., Ltd. represents scale-driven manufacturing from Chinese industrial clusters.
| Leading Market Players |
|---|
| Diamond Tech Glass |
| Willet Studios |
| Taizhou Wanda-Stained Glass Co., Ltd. |
| Conrad Schmitt Studios |
| Jahn Studios |
| Pendle Stained Glass Ltd. |
| Bullseye Glass Co. |
| Kokomo Opalescent Glass Co. |
| Aanraku Studios |
| Others |
Supply Flow & Price Mechanics
Metallic oxide pigments from Chinese refiners cascade through three pricing tiers before reaching cathedral conservation contractors in France and Germany, with REACH-compliant reformulation costs concentrating margin capture among studios with in-house analytical laboratories.
Pricing Analysis
Distributor markups on heritage-grade color palettes compress as direct-to-consumer digital platforms fragment traditional dealer-gallery channels. Project-based pricing stratifies across restoration, renovation, and new construction tiers, with certification grade and specialist labor scarcity driving price differentiation. Cost compression in commodity new construction segments intensifies as digitally printed ceramic frit glass substitutes at lower installed cost. Religious institutions exhibit lowest price sensitivity due to state-funded conservation mandates, while commercial developers in hospitality sectors demonstrate highest elasticity to installed cost alternatives.
Supply Chain Analysis
Domestic-content preferences in French and Italian cathedral conservation programs reshape sourcing toward EU-based pigment reformulation laboratories with ECHA pre-registration dossiers. Manufacturing concentrates in France, Italy, and Germany for ecclesiastical heritage work, with Pacific Northwest clusters serving North American kiln-formed technical glass demand. Raw material dependencies rest on cobalt and cadmium oxide supplies from Chinese refiners, lead-free solder formulations, and metallic oxide pigments. Single-source vulnerability in pigment supply creates exposure to export restriction shocks. Distribution runs through direct studio commissioning via digital portfolio platforms, bypassing historical regional representative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stained glass market functions as a regulatory compounder where ECHA REACH phase-down deadlines for lead compounds force pigment chemistry substitution ahead of conservation contract renewal cycles, locking demand toward certified studios.
For Market Incumbents: Deploy in-house analytical laboratory capacity to capture heritage restoration contracts as competitors face reformulation delays. Expand direct-to-consumer digital channel control to absorb margin previously captured by dealer-gallery networks. Threaten substitution from digitally printed ceramic frit glass in commercial new construction segments pressures pricing power outside restoration tiers. Lever vertical integration into lead-free solder and pigment captive supply to secure REACH compliance ahead of tender deadlines. For New Entrants and Emerging Players: Begin with copper-foil Tiffany revival techniques for luxury residential commissioning in California and New York, where shorter sales cycles and lower capital requirements enable studio participation below ecclesiastical contract thresholds. Target boutique hospitality interior design specifications where kiln-formed technical capabilities differentiate from traditional leaded methods. White-space exists in mid-size commercial commissions abandoned by heritage houses focused on cathedral conservation. Pursue social media portfolio presence and direct commissioning platforms as primary go-to-market angle, bypassing entrenched dealer networks. For Investors and Strategic Acquirers: Consolidation pressure builds where specialist labor scarcity and REACH certification barriers create acquisition premiums for studios with master glass painters and ECHA pre-registration dossiers. Long-term viability favors vertically integrated fabricators with backward control over pigment reformulation and testing capital for CE marking compliance. Acquisition target archetype: mid-size studios with heritage color matching capabilities and underdeveloped digital channels. Signal to watch: conservation contract award cycles compressing against REACH certification windows, forcing distressed divestitures from non-compliant competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Pigment Reformulation Certification | ECHA REACH pre-registration dossiers lock out non-compliant competitors from French and German cathedral tenders. |
| Direct-to-Consumer Digital Channel Development | Studio websites and social media presence bypass dealer-gallery networks to concentrate margin capture with producers. |
| Copper-Foil Technical Capability Expansion | Tiffany-method adaptations enable participation in residential and boutique hospitality segments below ecclesiastical thresholds. |
| In-House Analytical Laboratory Investment | On-site pigment chemistry testing accelerates REACH compliance timelines ahead of conservation contract awards. |
| Kiln-Formed Technical Glass Capacity Addition | Architectural specification for commercial atriums extends demand beyond traditional ecclesiastical commissioning cycles. |
Methodological Framework
Direct dialogue with master glass painters, cathedral conservation procurement officers, hospitality interior designers, and lead-free pigment chemists anchored qualitative findings, cross-referenced with ECHA authorization databases, EU construction product regulation filings, EPA lead-safe renovation guidance documents, and customs trade data for metallic oxide pigment flows. Bottom-up and top-down triangulation validated volume and value estimates across product type, end user, installation type, and design complexity segments.
Bottom-up modeling aggregated individual studio capacity and contract backlog data across the analysis window, while top-down approaches tracked state-funded conservation program allocations and commercial construction permitting activity. Segmentation dimensions included product architecture, buyer archetype, installation methodology, and craft complexity tier. CAGRs derived from regression analysis of historical commissioning patterns against regulatory milestone timelines, with inputs from OSHA workplace exposure limit enforcement trajectories and REACH substance restriction phase-down schedules.
Several conditions sit outside the modeled scope, including macroeconomic construction cycle volatility, unilateral export restrictions on cobalt and cadmium oxide supplies, and acceleration or delay of ECHA authorization deadlines. Forecasts reflect assumptions regarding specialist labor pipeline continuity and pigment reformulation technical success rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Europe Decorative Laminates Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
United Arab Emirates Interior Design Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
United States Wall Covering and Wall Decor Market
Homecare and Decor
Europe Flower Pots and Planters Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
USA Bed Pillow Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
Door Handles Market
Homecare and Decor
Curtains and Window Blinds Market
Homecare and Decor
Asia-Pacific Decor Paper Market
Homecare and Decor
Pillow Market
Homecare and Decor
ASEAN UPVC Doors and Windows Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
India Furniture Hardware Market