
 Non-Dispersive Infrared Sensing Market | 2026-2036
Non-Dispersive Infrared Sensing Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Dispersive Infrared Sensing Market Analytics
Buyer concentration among industrial automation OEMs is hardening across the Non-Dispersive Infrared Sensing landscape. Honeywell International Inc. leverages its distributed control systems footprint to bundle sensor procurement with process control platforms. Siemens AG anchors European demand through its factory automation installed base. Vaisala Corporation specializes in environmental monitoring channels, competing on calibration density rather than price.
Non-dispersive infrared sensing employs a broadband infrared source, optical filter, and thermopile or pyroelectric detector to measure gas-specific absorption at characteristic wavelengths without spectral dispersion. The technique targets selective detection of CO2, hydrocarbons, and refrigerants in industrial process streams and ambient air. Gas sensors dominate product type revenue owing to stationary combustion monitoring mandates, while active infrared technology captures the fastest expansion through its signal-to-noise advantages in low-concentration measurement. Environmental monitoring applications command premium positioning as regulatory baselines tighten for fugitive emission tracking.
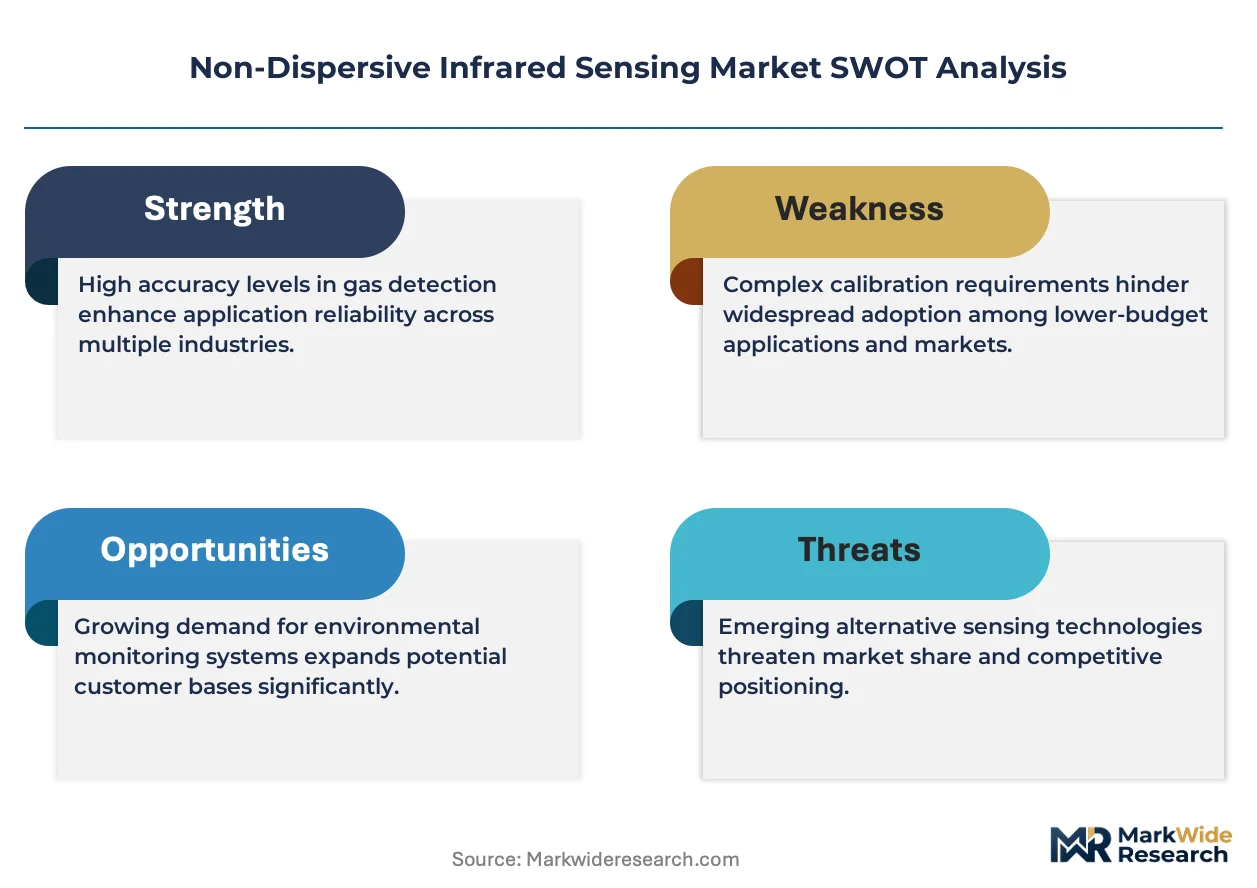
EPA New Source Performance Standards and OSHA permissible exposure limits shape sensor specification requirements in the United States, while EU F-Gas Regulation and REACH compliance dictate filter material and housing chemistry selections for European market access. China's MEE ambient air quality standards and GB emission monitoring protocols drive domestic certification complexity. Stakeholders must monitor divergence between regional calibration protocols and emerging photoacoustic technology substitution threats.
Market Dynamics
EPA New Source Performance Standards and tightening EU F-Gas Regulation are forcing sensor manufacturers to recalibrate filter specifications and detector sensitivity thresholds across industrial automation supply chains.
Growth Catalysts
- Stationary combustion monitoring mandates:EPA regulations require continuous emission tracking at power generation and cement facilities, driving replacement cycles for legacy electrochemical sensors with NDIR-based systems.
- Automotive cabin air quality protocols:China GB standards and EU vehicle interior air mandates embed CO2 sensors into HVAC control loops for passenger safety and energy optimization.
- Refrigerant leak detection:EU F-Gas phase-down schedules and US AIM Act restrictions on HFCs create compliance-driven demand for selective hydrocarbon sensing in commercial refrigeration.
Market Restraints
- Optical filter supply concentration:German and Japanese specialty glass manufacturers control thin-film interference filter production, creating single-source vulnerability for mid-tier sensor assemblers.
- Photoacoustic substitution threat:Emerging photoacoustic spectroscopy achieves comparable selectivity without moving optical components, pressuring NDIR cost structures in premium environmental monitoring.
- Calibration gas cost volatility:Certified reference gas mixtures for CO2 and refrigerant calibration fluctuate with industrial gas supply chain disruptions, eroding service margin predictability.
Strategic Opportunities
- India industrial automation buildout:PLI scheme incentives for manufacturing localization create first-mover advantage for sensor vendors establishing domestic calibration facilities.
- Smart building integration:Convergence of NDIR sensing with BACnet and Modbus protocols enables demand-controlled ventilation systems that reduce HVAC energy consumption.
- Agricultural greenhouse monitoring:Precision agriculture adoption in the Netherlands and Spain drives deployment of distributed CO2 sensors for photosynthesis optimization in controlled environment agriculture.
Industry Challenges
- Cross-border calibration protocol divergence:EPA Method 21 leak detection requirements, EU MCERTS certification, and China GB emission standards impose incompatible test procedures, fragmenting product development roadmaps.
- Thermopile detector integration complexity:Legacy process control systems in heavy industry lack analog-to-digital resolution for low-concentration NDIR outputs, requiring costly signal conditioning retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Dispersive Infrared Sensing Market |
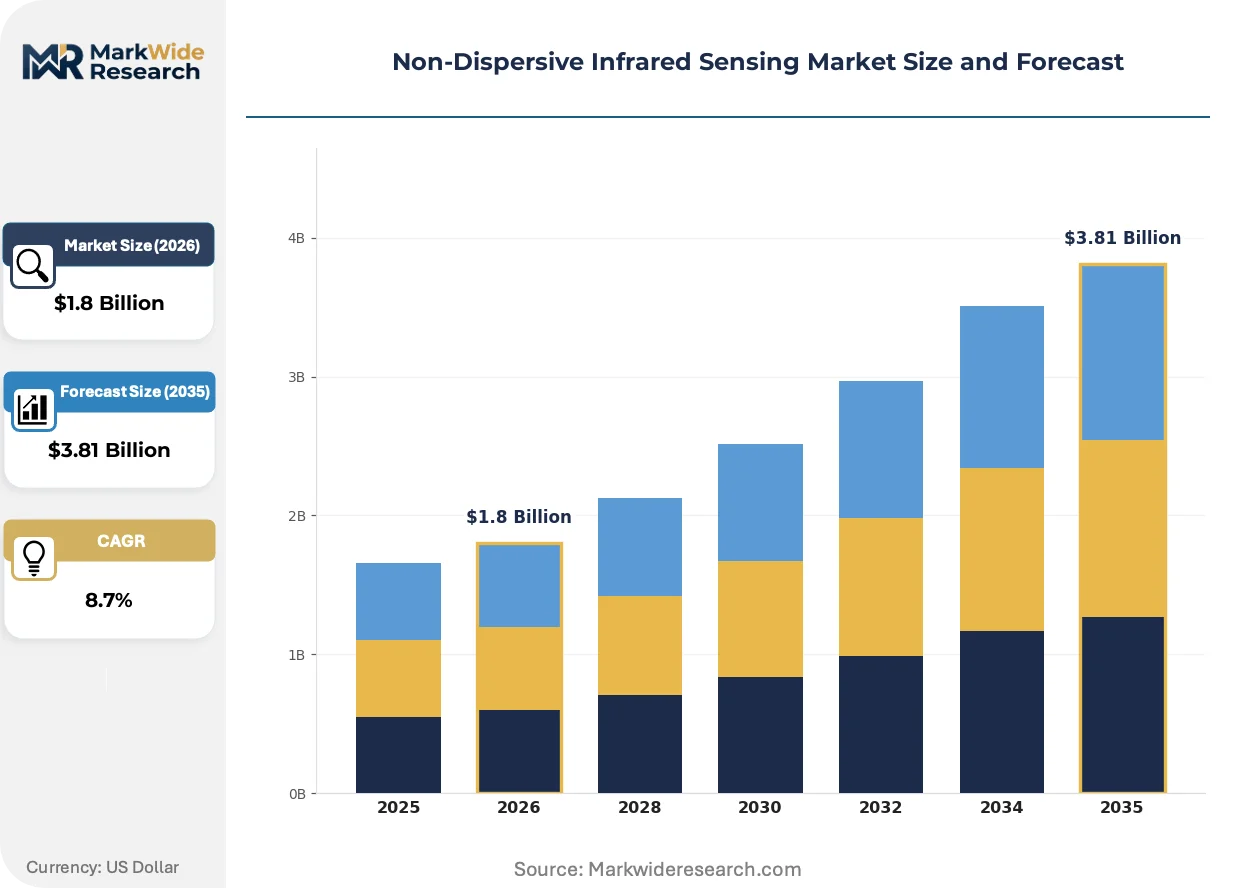
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Sensors, Humidity Sensors, Temperature Sensors, CO2 Sensors Technology: Passive Infrared, Active Infrared, Photoacoustic, Optoelectronics End User: Industrial Automation, Environmental Monitoring, Healthcare, Automotive Application: Air Quality Monitoring, Process Control, Safety Systems, Research |
| Companies Covered | Senseair AB, Dynament Ltd., Honeywell International Inc., Gas Sensing Solutions Ltd., ELT Sensor Corp., Amphenol Advanced Sensors, Figaro Engineering Inc., Vaisala Corporation, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Dispersive Infrared Sensing Market Evolving Landscape
Active infrared signal processing and MEMS-scale source miniaturization are compressing form factors while expanding addressable applications beyond traditional stationary monitoring into portable and wearable formats.
Multi-gas filter arrays with silicon-based micro-hotplate sources are unifying detection of CO2, methane, and refrigerants within single optical benches. Industrial safety OEMs in Germany and Japan are qualifying these platforms for confined-space entry monitors. This unification is collapsing the premium historically commanded by discrete single-gas instruments.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant sensor retrofit mandates across European supermarket chains and cold storage networks. Compliance deadlines in 2027 and 2030 are locking in procurement specifications now. Commercial refrigeration contractors face compressed installation windows, favoring pre-calibrated plug-and-play NDIR modules over field-configurable alternatives.
Buyer concentration among industrial automation OEMs is compressing distribution layers. Honeywell and Siemens are consolidating sensor procurement through captive supply agreements, bypassing traditional distributor markups. Equipment-as-a-service models in North American oil and gas are unbundling hardware ownership from calibration service contracts, shifting revenue recognition toward recurring maintenance streams.
Non-Dispersive Infrared Sensing Market Segmentation
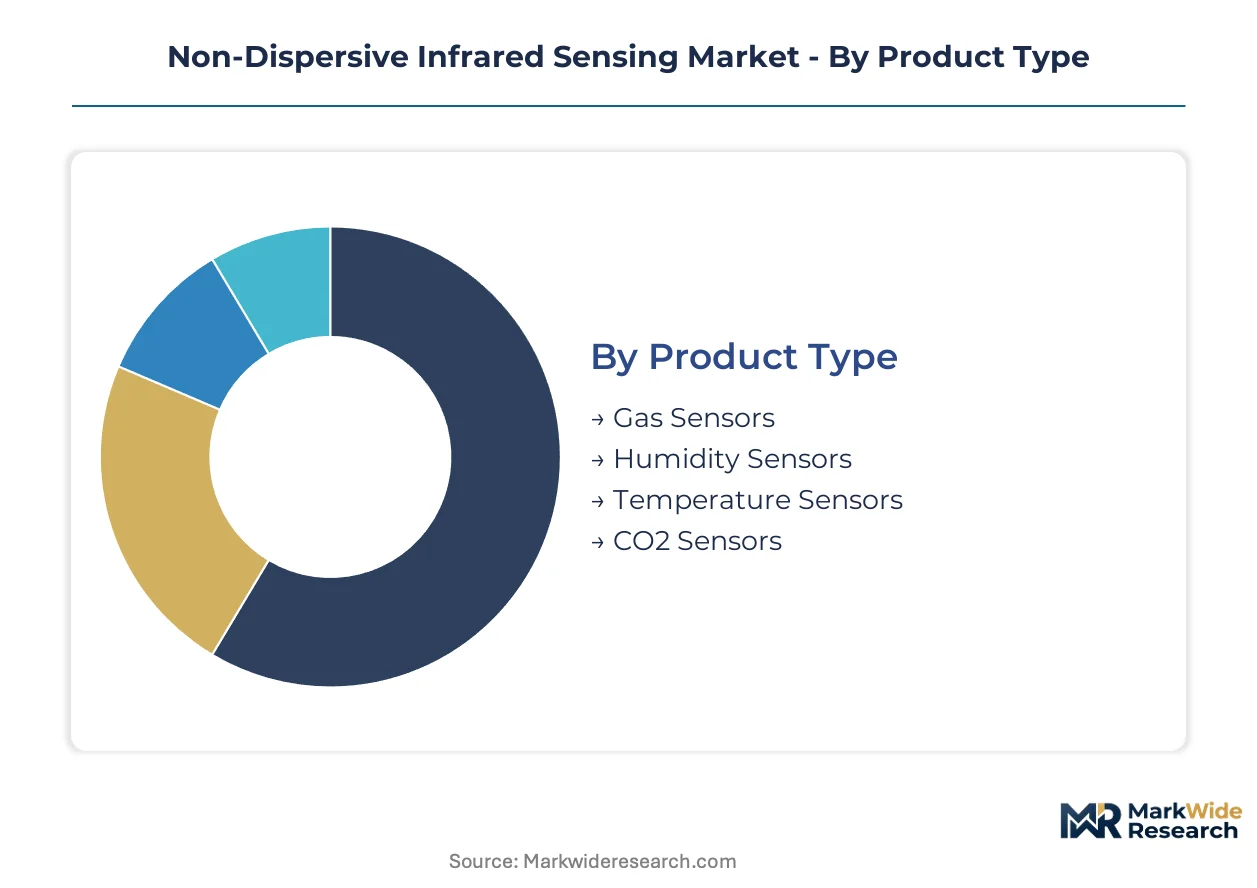
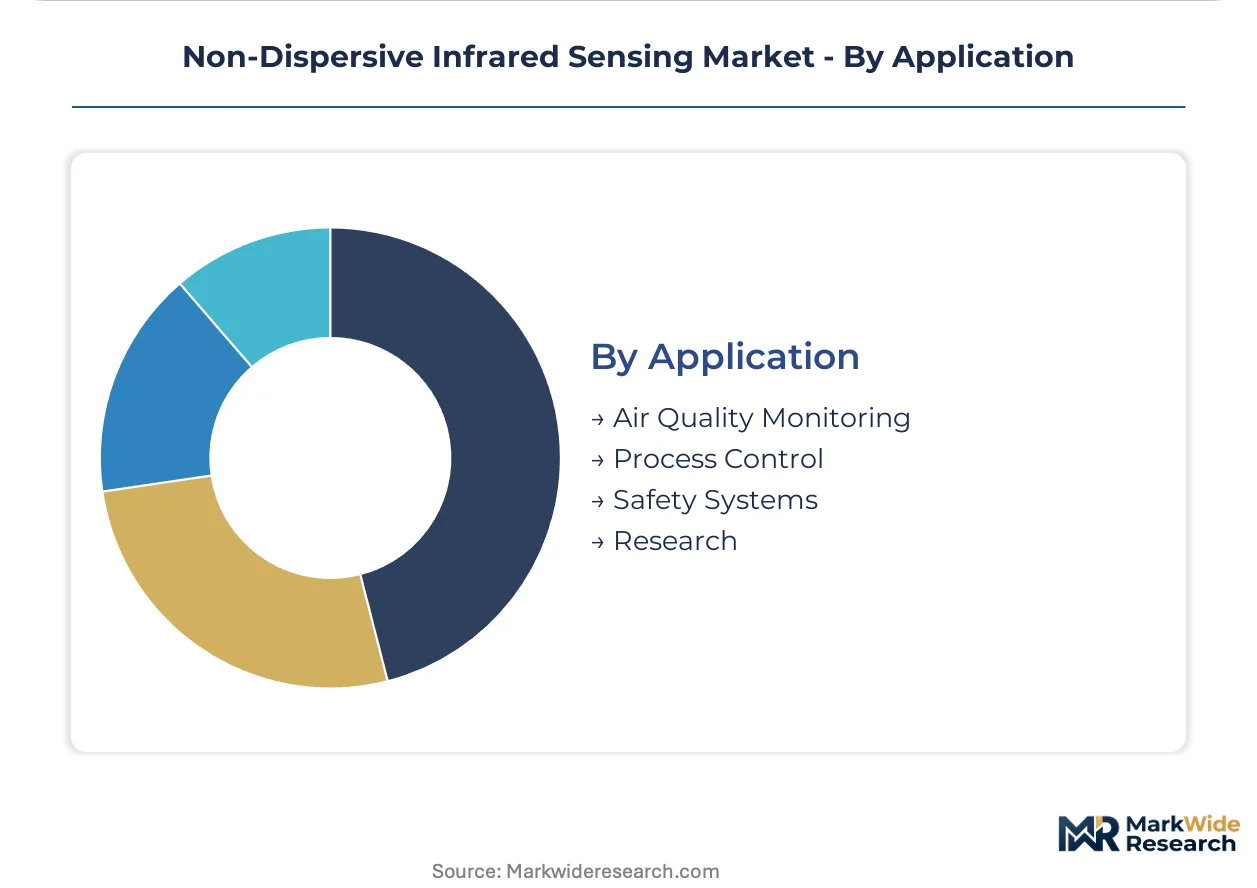
NDIR sensing architectures diverge sharply across detection targets, signal generation methods, and integration complexity. Procurement patterns in this market cluster around regulatory-mandated applications rather than discretionary upgrades, making segment selection a strategic commitment with decade-long lock-in effects.
Product Type:
Filter bandwidth and detector chemistry define the performance envelope for each sensor category.
- Gas Sensors:Selective detection of CO2, hydrocarbons, and refrigerants relies on narrowband interference filters matched to molecular absorption peaks. Stationary combustion monitoring mandates at US power generation and cement facilities drive replacement of electrochemical alternatives with NDIR-based systems.
- CO2 Sensors:Dual-channel differential measurement compensates for source aging and optical contamination. Automotive cabin air quality protocols in China and the European Union embed these into HVAC control loops for passenger safety and energy optimization.
- Humidity Sensors:Chilled-mirror NDIR variants measure dewpoint in semiconductor cleanrooms and pharmaceutical stability chambers.
- Temperature Sensors:Non-contact thermal measurement through blackbody radiation analysis serves steel reheating furnaces and glass manufacturing.
Gas sensors lead on scale; CO2 sensors lead on momentum.
Technology:
Signal-to-noise ratio and component count determine total cost of ownership across deployment scales.
- Active Infrared:Modulated sources and lock-in amplification extract weak absorption signals from noisy industrial backgrounds. Low-concentration measurement in fugitive emission tracking and precision agriculture applications favors this architecture despite higher unit costs.
- Passive Infrared:Unmodulated thermal sources with thermopile detectors minimize power consumption and moving parts. Battery-powered portable instruments and wireless sensor networks in agricultural greenhouse monitoring deploy this technology for maintenance-free multi-year operation.
- Photoacoustic:Emerging spectroscopic alternative achieves comparable selectivity without optical filters or mechanical choppers.
- Optoelectronics:Silicon photonics integration enables chip-scale NDIR platforms for consumer electronics and wearable formats.
Passive infrared dominates installed base; active infrared expands most quickly.
End User:
Calibration protocol requirements and integration complexity fragment procurement specifications across verticals.
- Industrial Automation:Distributed control system integration demands 4-20 mA or Modbus outputs with SIL-rated safety integrity. Process control loops in chemical manufacturing and oil refining require continuous validation against EPA Method 21 and OSHA permissible exposure limits.
- Environmental Monitoring:MCERTS certification in Europe and GB protocol compliance in China impose divergent test procedures. Fugitive emission tracking and ambient air quality stations command premium pricing for trace-level detection capability.
- Automotive:Cabin air quality management and powertrain emission control embed sensors into vehicle electronics architectures.
- Healthcare:Capnography and anesthesia monitoring applications require medical-grade biocompatibility and electromagnetic immunity.
Industrial automation leads on scale; environmental monitoring leads on momentum.
Application:
Regulatory enforcement intensity and measurement criticality determine specification stringency.
- Air Quality Monitoring:Networked station deployments in urban centers and industrial perimeters track particulate and gaseous pollutants against tightening national standards. China's MEE ambient air quality protocols and EPA regional haze rules drive continuous analyzer procurement.
- Process Control:Real-time feedback loops optimize combustion efficiency and product yield in cement, steel, and petrochemical operations.
- Safety Systems:Confined-space entry monitors and leak detection alarms require fail-safe response times under ten seconds.
- Research:Laboratory-grade instruments with parts-per-billion resolution support atmospheric science and climate monitoring.
Process control leads on scale; air quality monitoring leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation density exceeds Japan's by a factor of two in per-capita sensor deployment, yet China's environmental monitoring procurement volume now matches both combined. Regulatory divergence across these three markets is fragmenting product roadmaps and calibration protocols.
United States
Power generation and cement facilities drive stationary combustion sensor replacement cycles under EPA New Source Performance Standards. The EPA Method 21 leak detection protocol mandates specific response thresholds for fugitive emission monitors. Houston's petrochemical corridor hosts concentrated demand for process control integration with SIL-rated safety systems.
Germany
Factory automation OEMs anchor European demand through captive supply agreements bypassing traditional distribution. EU F-Gas Regulation phase-down schedules lock in refrigerant sensor specifications for 2027 and 2030 compliance deadlines. The Ruhr industrial basin and Bavarian manufacturing belt concentrate procurement for multi-gas detection platforms.
China
Automotive cabin air quality mandates under GB standards embed CO2 sensors into HVAC control loops for domestic and export vehicle production. MEE ambient air quality protocols drive networked station deployments in urban centers and industrial perimeters. The Yangtze River Delta and Pearl River Delta clusters dominate both manufacturing capacity and domestic consumption.
Japan
Precision agriculture adoption in controlled environment agriculture creates distributed CO2 sensor demand for photosynthesis optimization. METI industrial efficiency programs incentivize combustion monitoring retrofits in steel and chemical operations. The Chubu region around Nagoya anchors automotive supply chain integration for cabin air quality systems.
India
PLI scheme incentives for manufacturing localization attract first-mover sensor vendors establishing domestic calibration facilities. CEA emission monitoring requirements for thermal power plants create compliance-driven procurement windows. Maharashtra and Gujarat industrial corridors concentrate demand for process control integration in chemical and pharmaceutical manufacturing.
Non-Dispersive Infrared Sensing Market Competitive Landscape
German and Japanese producers anchor the premium tier through specialty optical filter and detector manufacturing; Chinese and South Korean assemblers hold volume positions in standardized modules. The vendor base organizes around three strategic archetypes: integrated industrial automation platforms, environmental monitoring specialists, and component-focused sensor module suppliers. Consolidation pressures favor backward integration into optical filter production and captive calibration service networks.
Among diversified industrial technology conglomerates, Honeywell International Inc. and Siemens AG exemplify platform-integrated positioning that bundles sensor procurement with process control system sales. Vaisala Corporation occupies a specialist position within environmental monitoring channels. These three entities represent contrasting competitive vectors: scale-driven vertical integration, regional automation installed base leverage, and calibration-density specialization respectively.
| Leading Market Players |
|---|
| Senseair AB |
| Dynament Ltd. |
| Honeywell International Inc. |
| Gas Sensing Solutions Ltd. |
| ELT Sensor Corp. |
| Amphenol Advanced Sensors |
| Figaro Engineering Inc. |
| Vaisala Corporation |
| Siemens AG |
| Others |
Value Network & Pricing Analysis
EPA New Source Performance Standards and tightening EU F-Gas Regulation gate qualified supply access and premium-tier pricing power for certified NDIR sensor manufacturers serving stationary combustion and refrigerant leak detection markets.
Pricing Analysis
Capacity additions in China are reshaping price floors for standardized CO2 sensor modules while premium-tier active infrared systems retain pricing power through EPA Method 21 and EU MCERTS certification requirements. Three-tier pricing structure across certified reference-grade, industrial-standard, and economy OEM modules separates buyers by calibration traceability and detector sensitivity specifications. Cost compression in economy-tier passive infrared modules is intensifying because Chinese assemblers are scaling MEMS-source production for automotive cabin air quality volumes. Process control buyers at cement and petrochemical facilities show lowest price sensitivity due to SIL-rated safety system mandates, while agricultural greenhouse operators drive hardest bargaining for distributed wireless sensor networks.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty glass manufacturers controlling thin-film interference filter production for narrowband gas detection. Optical bench assembly concentrates in China, Germany, and Japan, drawing from germanium substrate wafers, thermopile detector arrays, and certified reference gas mixtures as critical inputs. Tariff exposure on precision optical components threatens margin stability for mid-tier sensor assemblers lacking captive filter production. Distribution runs through industrial automation OEM captive supply agreements and environmental monitoring instrument distributors, with direct procurement consolidating among Honeywell and Siemens factory automation platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory enforcement intensity across EPA, EU, and Chinese MEE mandates locks in replacement cycles and compliance-driven procurement with decade-long specification lock-in effects.
For Market Incumbents: Anchor defensive positioning through backward integration into optical filter production and captive calibration service networks to neutralize single-source supply risk and photoacoustic substitution threats. Deepen integration with distributed control system platforms at US power generation and German chemical manufacturing accounts to entrench switching costs. Prioritize SIL-rated safety certification investment for process control loops in oil refining and cement production. For New Entrants and Emerging Players: Launch via pre-calibrated plug-and-play NDIR modules targeting European commercial refrigeration contractors facing compressed 2027 and 2030 EU F-Gas Regulation installation windows. Target India's PLI scheme manufacturing localization incentives by establishing domestic calibration facilities ahead of CEA thermal power plant compliance mandates. Penetrate precision agriculture CO2 monitoring in Dutch and Spanish controlled environment agriculture through wireless passive infrared sensor networks. For Investors and Strategic Acquirers: Roll-up economics work for environmental monitoring specialists because calibration protocol divergence across EPA Method 21, EU MCERTS, and China GB standards fragments competition and sustains regional pricing premiums. Target acquisition of MEMS-scale source miniaturization capabilities and multi-gas filter array platforms over the medium-term horizon. Watch photoacoustic spectroscopy cost curves as inflection signal for NDIR displacement risk in premium ambient air quality monitoring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Filter Production | German and Japanese filter manufacturers control narrowband interference specifications, creating margin capture opportunity for captive supply. |
| Multi-Gas Filter Array Platform Launch | Silicon-based micro-hotplate sources unify CO2, methane, and refrigerant detection, collapsing single-gas instrument premiums. |
| Domestic Calibration Facility Establishment | India PLI scheme incentives and CEA emission mandates create first-mover advantage for localized service networks. |
| Smart Building Protocol Integration | BACnet and Modbus convergence enables demand-controlled ventilation systems reducing HVAC energy consumption. |
| Pre-Calibrated Module Distribution | EU F-Gas 2027 and 2030 deadlines compress installation windows favoring plug-and-play over field-configurable alternatives. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with process control engineers, environmental monitoring procurement leads, automotive HVAC system architects, and commercial refrigeration contractors with secondary validation through EPA enforcement databases, EU ETS emissions trading records, China MEE ambient air quality station deployment data, and SEC filings from industrial automation OEMs. Bottom-up sensor shipment analysis and top-down regulatory mandate sizing were triangulated against calibration service revenue disclosures.
Segment-weighted modeling applied technology-type splits across active infrared, passive infrared, and emerging photoacoustic architectures, crossed with end-use verticals spanning industrial automation, environmental monitoring, automotive, and precision agriculture across the projection horizon. CAGRs were derived from regulatory compliance deadline clustering and replacement cycle analysis for legacy electrochemical sensor installed bases. Forecast inputs incorporated EU F-Gas phase-down schedule enforcement probability and China GB automotive cabin air quality mandate adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under photoacoustic spectroscopy cost breakthrough scenarios or optical filter supply disruption events. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and certification protocol stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
RET Controller Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market
Sensors and Controls
DCT Mechatronic Control Unit Market
Sensors and Controls
SCR Dosing Control Modules Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
Vision Sensor Market
Sensors and Controls
Temperature Monitoring Devices Market
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
Digital Pump Controller Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
Rotary Encoders Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
PID Controller Market
Sensors and Controls
Inductive Proximity Sensors Market