
 Global Stock Video Market | 2026-2036
Global Stock Video Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stock Video Market Foresight
Multi-source licensing from specialized platforms is expanding as media buyers diversify beyond single-agency relationships. Shutterstock Inc. leverages its contributor network to sustain breadth across lifestyle and aerial categories. Getty Images Holdings Inc. anchors premium rights-managed collections for broadcast and editorial clients. Adobe Inc. competes through deep integration with creative cloud workflows, reducing friction for existing subscribers.
Stock video comprises pre-produced moving-image content captured at resolutions from HD through 8K, delivered via digital codecs for reuse in commercial, editorial, and educational productions. The primary purpose is to reduce production costs and accelerate timelines for creators lacking resources to capture original footage. Royalty-free licensing dominates transaction volume by removing per-use negotiation friction, while rights-managed footage commands premium pricing for exclusive campaign windows. Subscription models are capturing recurring revenue from advertising agencies and corporate brands with steady content pipelines.
The EU AI Act mandates disclosure of AI-generated or modified video content, directly affecting how platforms label and distribute synthetic stock footage. The FCC in the United States enforces truth-in-advertising standards that extend to video content used in political and commercial messaging. China's SAMR oversees platform content licensing to ensure compliance with GB standards for digital media distribution. Stakeholders must monitor how divergent labeling requirements across jurisdictions reshape content sourcing strategies and platform compliance investments.
Market Dynamics
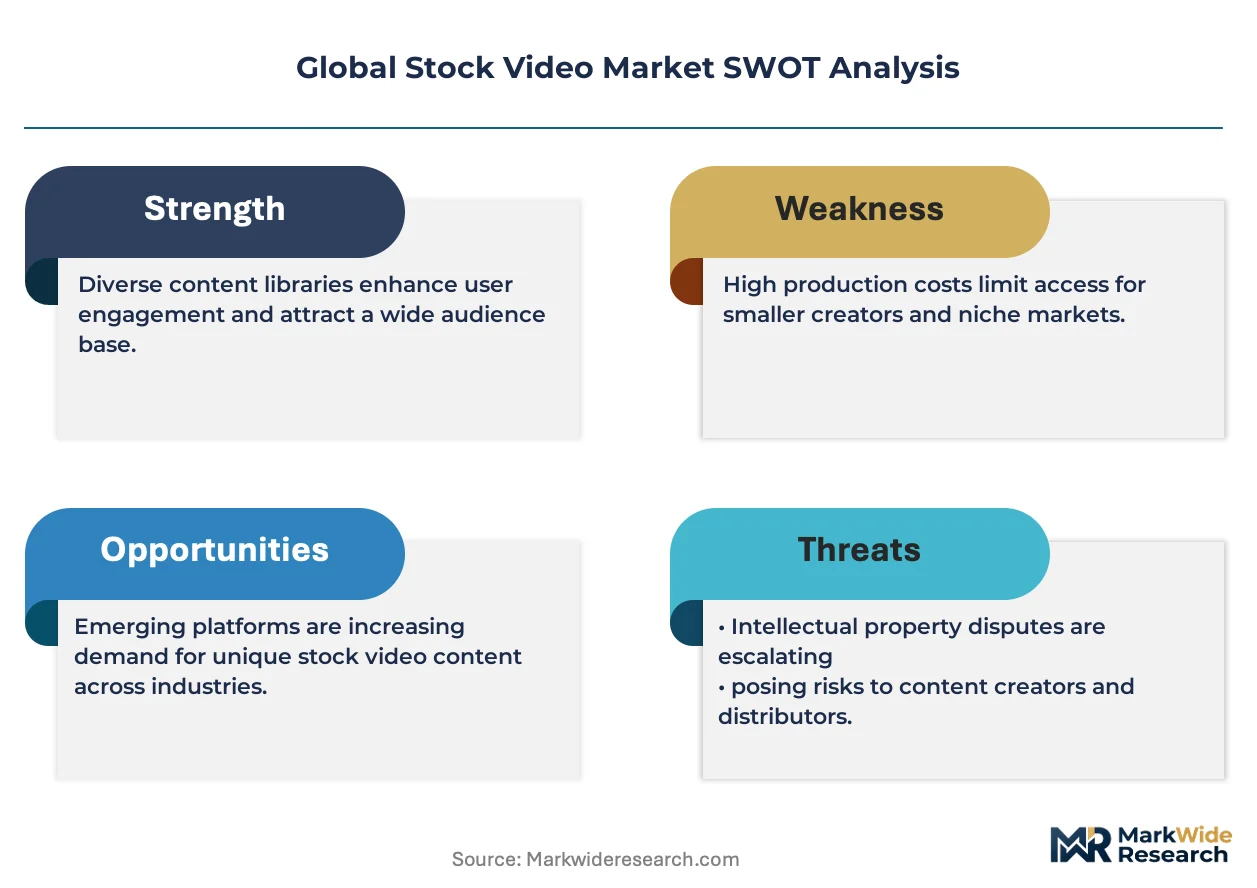
The EU AI Act's disclosure mandates for synthetic media are forcing stock video platforms to rebuild content provenance systems from capture through licensing, compressing margins while creating compliance differentiation.
Growth Catalysts
- Streaming platform content pipelines:Netflix, Disney+, and regional broadcasters license footage at scale to fill programming gaps. Their recurring production schedules sustain subscription revenue for stock video aggregators.
- EU AI Act transparency requirements:Mandatory labeling of AI-modified footage creates demand for verified authentic content. Platforms with clear provenance chains capture premium positioning.
- Social media publisher expansion:TikTok, Instagram Reels, and YouTube Shorts creators source b-roll through integrated marketplace APIs. This embeds stock video into native content workflows.
Market Restraints
- Contributor payout compression:Royalty-free pricing models drive per-clip earnings below sustainable thresholds for professional cinematographers. Talent migrates toward direct client relationships.
- Storage and delivery infrastructure costs:8K and RAW codec distribution demands edge server expansion. AWS, Azure, and Google Cloud pricing tiers consume margin at high resolution tiers.
- Generative video substitution:OpenAI Sora, Runway, and Pika Labs text-to-video tools displace generic lifestyle and abstract footage demand. Commercial buyers pilot synthetic alternatives for non-critical applications.
Strategic Opportunities
- India's creator economy expansion:YouTube's second-largest market by watch time generates unmet demand for region-specific cultural footage. Localized contributor networks capture this white space.
- Drone and aerial cinematography:FAA Part 107 certification barriers limit supply of compliant commercial drone footage. Platforms with pre-cleared aerial libraries command scarcity premiums.
- ISO 27001 and SOC 2 certification:Enterprise procurement teams mandate security attestations for content supply chains. Early certification creates vendor shortlist advantages.
Industry Challenges
- Metadata standardization fragmentation:IPTC, XMP, and platform-native tagging systems create interoperability gaps. Manual reconciliation slows ingestion pipelines.
- Model release documentation gaps:Talent in legacy footage lacks signed commercial usage agreements. Retroactive clearance projects stall library monetization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stock Video Market |
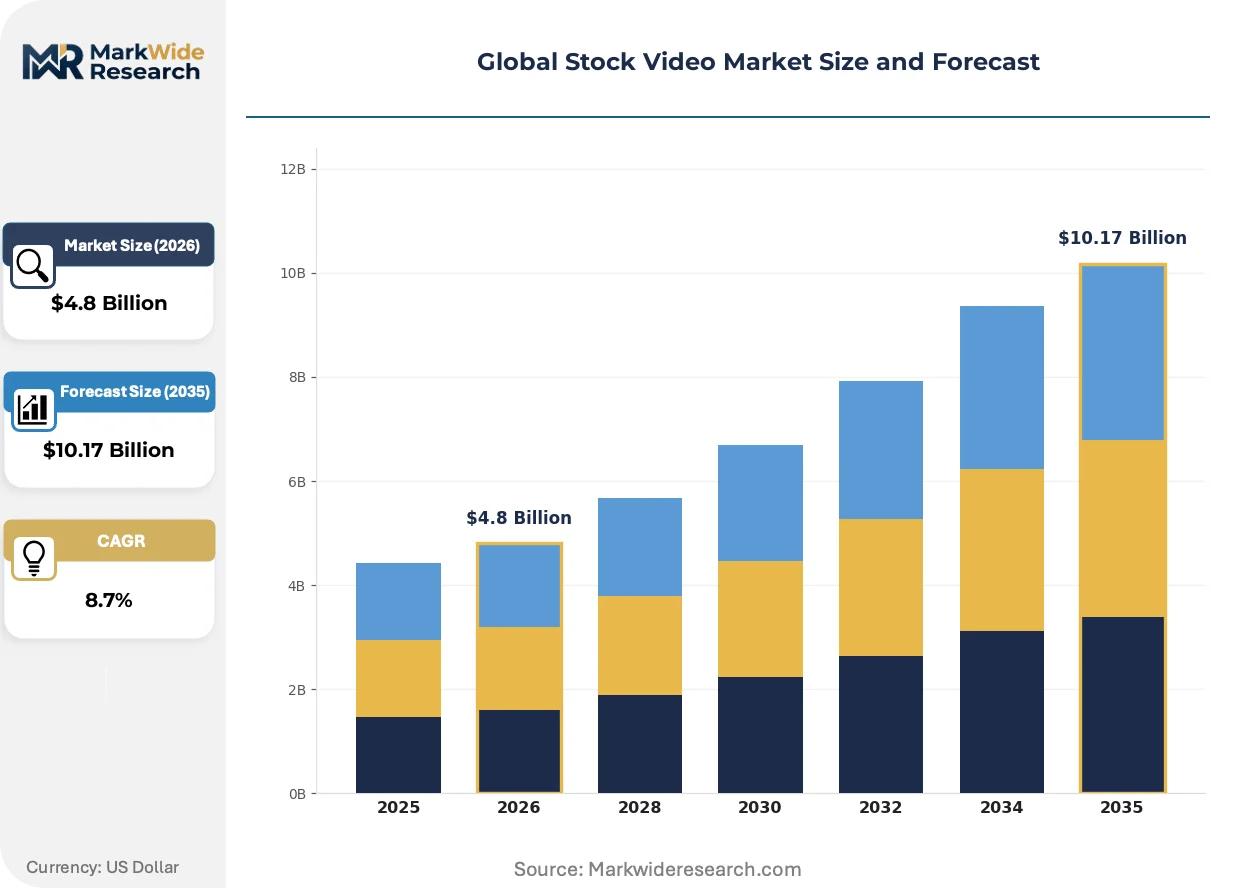
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Animation, Time-Lapse, Drone Footage, Lifestyle, Aerial Shots, Nature License Type: Royalty-Free, Rights-Managed, Editorial, Exclusive, Subscription, Single Use End User: Advertising Agencies, Media Production Studios, Freelancers, Educational Institutions, Corporate Brands, Nonprofits Distribution Channel: Online Platforms, Direct Sales, Resellers, Mobile Apps, Social Media, Broadcast Networks |
| Companies Covered | Adobe Inc., Shutterstock Inc., Getty Images Holdings Inc., Envato Pty Ltd., Depositphotos Inc., Pond5 Inc., Alamy Ltd., Can Stock Photo Inc., Dissolve Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stock Video Market Shifts & Advancements
Provenance verification and workflow embedding are displacing raw catalog breadth as the primary competitive axis. Platforms now compete on trust infrastructure rather than clip count alone.
Blockchain-based content authentication is modularizing rights documentation into portable, verifiable credentials. Major broadcasters and advertising holding companies pilot these systems for campaign audit trails. The technology compresses legal review cycles from weeks to hours.
The EU AI Act's synthetic media labeling requirements are forcing platform-wide metadata architecture overhauls. Disclosure obligations extend to AI-upscaled or AI-restored archival footage. European publishers face the steepest compliance curves, with German and French regulators issuing early enforcement guidance.
Enterprise procurement teams now unbundle creative software subscriptions from content licensing. Adobe's Creative Cloud integration advantage is eroding as buyers seek best-of-breed footage independent of editing tools. This pattern concentrates among mid-market advertising agencies in the United States and United Kingdom.
Global Stock Video Market Segmentation
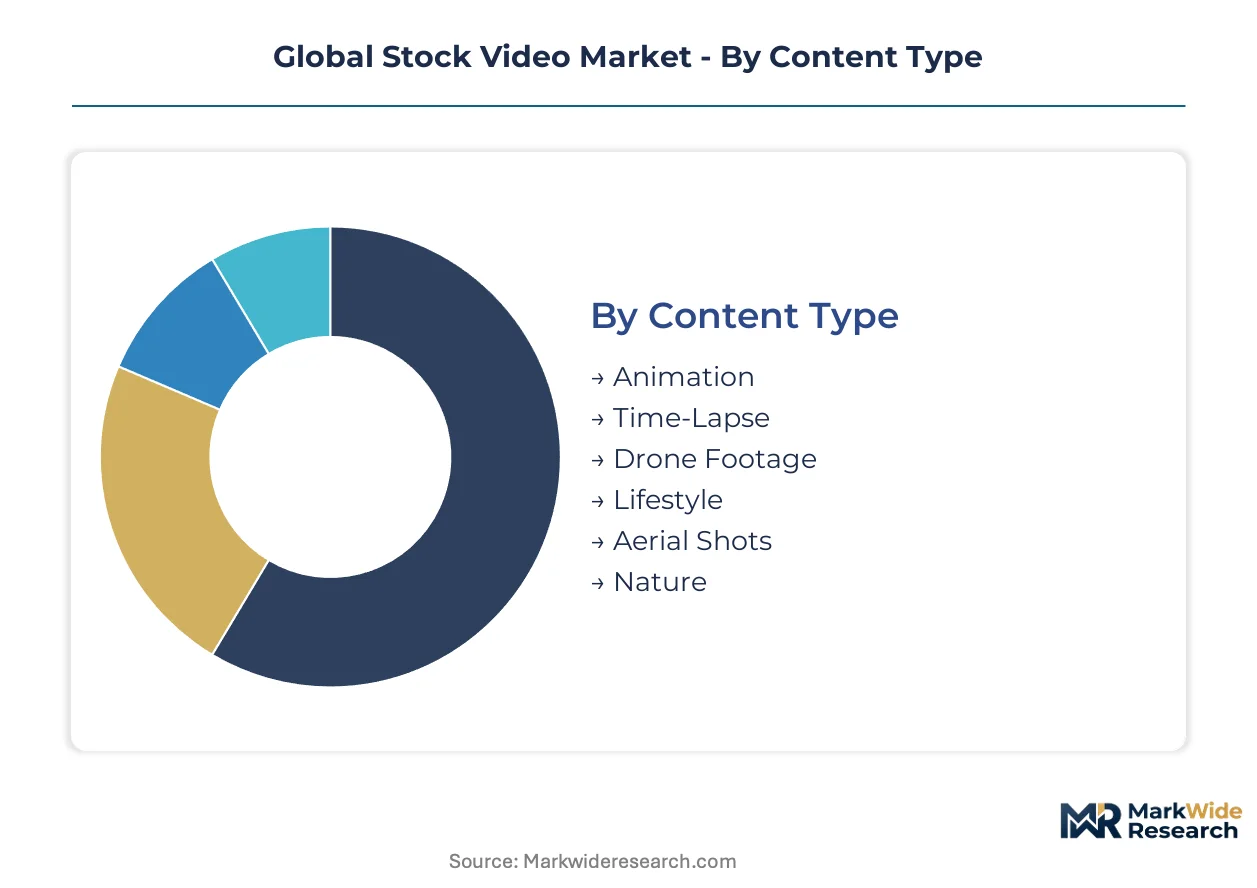
Stock video segmentation reflects divergent production economics and licensing complexity. Content type determines capture equipment and talent costs, while license structure shapes revenue recognition and customer lifetime value. Platforms optimize catalog composition around segments with the steepest margin profiles.
Content Type:
Capital intensity varies dramatically across capture methodologies, from single-camera lifestyle shoots to multi-drone aerial operations with certified pilots.
- Drone Footage:FAA Part 107 certification requirements and liability insurance create supply scarcity. Demand concentrates in real estate marketing and tourism boards across the United States and Australia, where commercial operators face strict altitude and airspace restrictions.
- Lifestyle:Diverse talent pools and studio rental costs dominate production economics. Advertising agencies in Germany and France license recurring volumes for consumer brand campaigns, though contributor payout compression erodes professional cinematographer participation.
- Animation:Motion graphics and 3D renders require software licensing and specialized skill sets.
- Time-Lapse:Interval capture equipment and extended field deployment define production workflows.
- Aerial Shots:Helicopter and fixed-wing capture commands premium pricing for cinematic productions.
- Nature:Location permits and seasonal timing constraints limit supply predictability.
Most installed capacity flows through Lifestyle. Expansion is steepest in Drone Footage.
License Type:
Revenue predictability and legal complexity diverge across pricing models, from frictionless subscription pools to negotiated exclusive windows.
- Royalty-Free:Perpetual usage rights with no recurring fees dominate transaction volume. Corporate brands in China source through platform subscriptions, though per-clip contributor earnings often fall below sustainable thresholds for professional creators.
- Rights-Managed:Usage restrictions by geography, duration, and media type command premium pricing. Broadcast networks in the United Kingdom and Japan negotiate exclusive campaign windows, particularly for high-profile commercial spots requiring competitive differentiation.
- Subscription:Recurring access fees bundle unlimited downloads within tiered consumption limits.
- Editorial:News and documentary usage carries specific publication restrictions and verification requirements.
- Exclusive:Single-buyer control over specified footage for defined periods.
- Single Use:One-time licensing for specific project deliverables.
Transaction volume concentrates in Royalty-Free. Margin expansion is strongest in Rights-Managed.
End User:
Procurement sophistication and content velocity requirements separate enterprise buyers from individual creators.
- Advertising Agencies:Multi-brand portfolios demand diverse catalog breadth and rapid turnaround. Holding companies in the United States unbundle creative software from content licensing, pressuring integrated platform advantages.
- Corporate Brands:In-house production teams seek consistent visual identity across global campaigns. Technology and financial services firms in Singapore and Switzerland mandate ISO 27001 certification for content supply chain security.
- Media Production Studios:Broadcast and streaming pipelines require cleared talent releases and broadcast-safe technical specifications.
- Freelancers:Individual creators prioritize price accessibility and search efficiency over legal complexity.
- Educational Institutions:Curriculum integration and accessibility compliance shape procurement criteria.
- Nonprofits:Budget constraints favor donation-based or discounted licensing programs.
Revenue concentration sits with Advertising Agencies. Fastest adoption is occurring among Corporate Brands building in-house capabilities.
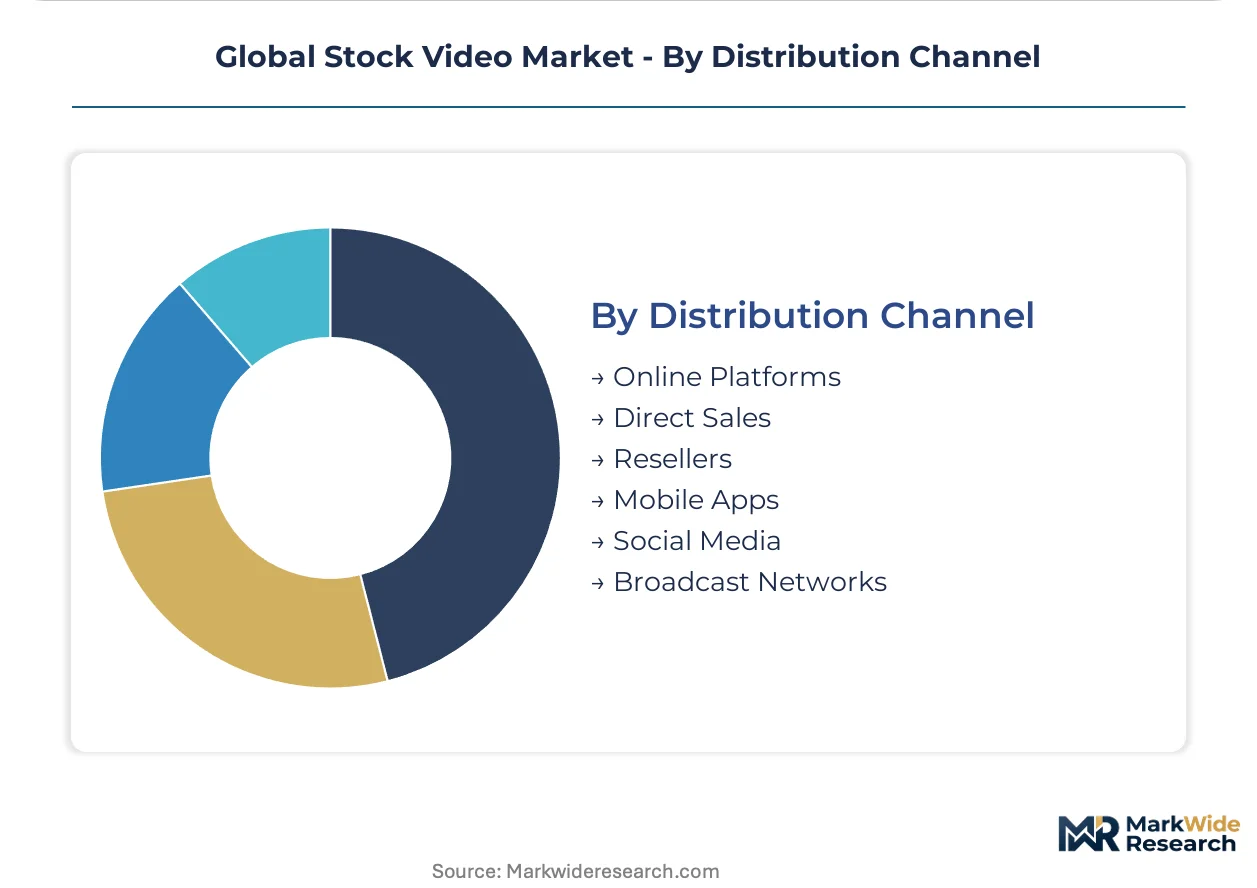
Distribution Channel:
Customer acquisition costs and technical integration requirements determine channel economics.
- Online Platforms:Searchable marketplaces with AI-powered recommendation engines capture the majority of independent creator spend. API integrations with editing software reduce workflow friction for subscribers in Canada and the Netherlands.
- Broadcast Networks:Direct licensing relationships with premium libraries sustain high-value recurring contracts. National public broadcasters in Germany and South Korea negotiate blanket licenses for archival and contemporary footage.
- Direct Sales:Enterprise procurement teams negotiate custom terms outside standard platform structures.
- Resellers:Regional agencies aggregate local content for territory-specific buyers.
- Mobile Apps:Native capture and upload tools embed stock access into smartphone workflows.
- Social Media:Integrated marketplaces within content creation platforms streamline b-roll sourcing.
Volume flows predominantly through Online Platforms. Fastest integration is happening with Social Media native workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors production demand as streaming studios and advertising agencies license footage at scale for commercial campaigns and original programming pipelines.
United States
Netflix, Disney+, and Warner Bros. Discovery sustain bulk licensing contracts for original series and documentary content. The FCC enforces truth-in-advertising standards that extend to video content in political messaging. Production clusters in Los Angeles and New York Metro generate concentrated demand for premium rights-managed footage.
China
TikTok parent ByteDance and regional streaming platforms license b-roll through integrated marketplace APIs for short-form content creators. The SAMR oversees platform content licensing to ensure compliance with GB standards for digital media distribution. Beijing and Shanghai production hubs drive demand for region-specific cultural footage.
Germany
Public broadcasters ARD and ZDF negotiate blanket licenses for archival and contemporary footage across documentary and news programming. The EU AI Act mandates disclosure of AI-generated or modified video content, forcing platform-wide metadata architecture overhauls. Berlin and Hamburg production centers concentrate demand for broadcast-safe technical specifications.
India
YouTube's second-largest market by watch time generates unmet demand for region-specific cultural footage from advertising agencies and independent creators. The country's national media regulator enforces content licensing frameworks for digital platform distribution. Mumbai and Bangalore creator economy clusters drive fastest adoption of subscription-based stock video access.
United Kingdom
BBC and ITV sustain direct licensing relationships with premium libraries for high-value recurring contracts. The country's data protection authority enforces transparency requirements for AI-modified content in commercial messaging. London production houses concentrate demand for exclusive campaign windows in competitive advertising sectors.
Global Stock Video Market Competitive Landscape
Global majors compete with regional champions across content provenance and workflow integration vectors. The vendor base separates into three tiers: integrated creative software platforms, specialized stock media aggregators, and niche contributor networks. Strategic archetypes include subscription-scale operators, premium rights-managed specialists, and API-first marketplace embedders. Dominant competitive moves center on M&A for contributor network expansion and strategic partnerships for editing software integration.
Among US-based platforms, Adobe Inc., Shutterstock Inc., and Getty Images Holdings Inc. occupy positions across the competitive spectrum. Adobe exemplifies the integrated creative software archetype through deep workflow embedding. Shutterstock represents the subscription-scale aggregator model leveraging broad contributor networks. Getty Images anchors the premium rights-managed tier for broadcast and editorial clients demanding exclusive usage windows.
| Leading Market Players |
|---|
| Adobe Inc. |
| Shutterstock Inc. |
| Getty Images Holdings Inc. |
| Envato Pty Ltd. |
| Depositphotos Inc. |
| Pond5 Inc. |
| Alamy Ltd. |
| Can Stock Photo Inc. |
| Dissolve Inc. |
| Others |
Supply & Pricing Matrix
Cloud storage and edge delivery costs cascade through stock video pricing tiers from contributor upload through final license, compressing margins at 8K resolution tiers while subscription pools absorb volume at lower fidelity levels. AWS, Azure, and Google Cloud pricing tiers tether platform economics to hyperscaler rate cards, forcing royalty-free per-clip payouts below sustainable thresholds for professional cinematographers.
Pricing Analysis
Contributor payout compression in cloud storage and bandwidth passes through to per-clip earnings, with AWS egress fees consuming margin at 8K and RAW codec distribution tiers. Pricing stratifies across rights-managed premium windows, royalty-free standard pools, and subscription economy access, with differentiation driven by exclusivity duration and resolution tier. Pricing pressure stems from generative video substitution as OpenAI Sora and Runway displace generic lifestyle demand. Freelancers and independent creators exhibit highest price sensitivity, while broadcast networks tolerate premium positioning for cleared exclusive windows.
Supply Chain Analysis
Enterprise procurement teams now mandate dual-platform qualification, requiring ISO 27001 and SOC 2 certification alongside cleared talent releases before vendor shortlist inclusion. Supply concentrates in the United States, China, and Germany as production hubs and buyer clusters mature, with contributor networks drawing from cinematographers, drone operators certified under FAA Part 107, and motion graphics specialists. Single-source vulnerability sits with hyperscaler cloud dependencies for 8K delivery infrastructure. Distribution runs through online platform marketplaces with API integrations, broadcast network direct licensing, and social media native workflows embedding stock access into TikTok and Instagram Reels creation tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as EU AI Act transparency mandates shift demand toward verified authentic content with clear provenance chains. Premium positioning accrues to platforms with blockchain-based authentication and compliant metadata architecture.
For Market Incumbents: Anchor defensive positioning through exclusive contributor network lockups in drone and aerial cinematography, where FAA Part 107 certification barriers limit supply entry. Pursue backward integration into proprietary capture operations for high-value archival restoration projects. Invest in EU AI Act compliance infrastructure before German and French enforcement guidance hardens, as disclosure obligations for AI-upscaled footage compress competitor margins.
For New Entrants and Emerging Players: Social media platform APIs offer the most penetrable channel wedge, with TikTok and Instagram Reels creators sourcing b-roll through integrated marketplaces at accelerating velocity. Target India's creator economy expansion, where YouTube's second-largest market by watch time generates unmet demand for region-specific cultural footage. Pursue localized contributor recruitment in Mumbai and Bangalore clusters with subscription pricing calibrated to freelancer budget constraints.
For Investors and Strategic Acquirers: Consolidation pressure builds where contributor payout compression drives professional cinematographers toward direct client relationships, eroding platform catalog breadth. Long-term viability favors specialized aggregators with pre-cleared aerial libraries and broadcast-safe technical specifications over undifferentiated volume players. Watch generative video quality inflection as signal for displacement acceleration in lifestyle and abstract footage categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Provenance Infrastructure Investment | EU AI Act compliance creates vendor shortlist differentiation for European broadcasters and publishers. |
| Contributor Network Expansion | Localized recruitment in India and Southeast Asia captures unmet demand for region-specific cultural footage. |
| API-First Marketplace Embedding | Native integration with TikTok and Instagram Reals reduces friction for high-velocity short-form content creators. |
| Security Certification Attainment | ISO 27001 and SOC 2 credentials unlock enterprise procurement pipelines in Singapore and Switzerland. |
| Drone Footage Library Acquisition | FAA Part 107 scarcity premiums command pricing power in real estate and tourism verticals. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with platform product managers, contributor network coordinators, enterprise procurement leads at advertising holding companies, and broadcast licensing executives with secondary validation. SEC 10-K filings from Adobe, Shutterstock, and Getty Images, EU regulatory disclosure databases, hyperscaler capex reports, and customs data on professional camera equipment imports triangulate against contributor payout surveys and platform subscription metrics.
Input-output matrices map content type segments through license structure tiers to end-user procurement patterns across the projection horizon. Segmentation dimensions include capture methodology, resolution tier, exclusivity window, and regional regulatory cluster. CAGRs derive from regression analysis against streaming platform content pipeline disclosures and social media creator economy expansion metrics, with generative video substitution rates and EU AI Act compliance cost curves as industry-specific forecast inputs.
Revisions become necessary when generative video quality thresholds cross commercial viability for lifestyle footage, or when EU AI Act enforcement actions accelerate beyond German and French guidance timelines. Deviation in hyperscaler cloud pricing or FAA regulatory posture toward commercial drone operations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Art App Market
Digital Media
Digital Content Locker Market
Digital Media
3D Animation Market
Digital Media
Middle East and Africa Inflight Entertainment and Connectivity Market
Digital Media
Digital Content Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
Global Location-Based Entertainment Market
Digital Media
Pro AV Market
Digital Media
Asia-Pacific Animation Market
Digital Media
Anime Merchandising Market
Digital Media
Photographic Services Market
Digital Media
Digital Media Switchers Market
Digital Media
Online Entertainment Market
Digital Media
Stock Photography Market
Digital Media
IP in Media and Entertainment Market
Digital Media
United States Sports Betting Market