
 Stock Photography Market | 2026-2036
Stock Photography Market Size, Share, and Industry Trends Forecast 2026-2036
Stock Photography Market Intelligence
Creator talent pools is reorganizing how stock photography platforms source and authenticate visual content. Shutterstock leverages its contributor network across multiple continents to sustain a diverse image catalog. Getty Images anchors premium editorial licensing through direct relationships with photojournalists and news agencies. Adobe Stock competes by integrating native workflows within Creative Cloud applications.
Stock photography constitutes licensable visual media captured or created for commercial reuse, distributed through digital platforms with metadata tagging, resolution tiers, and rights-managed or royalty-free frameworks. The primary commercial purpose spans advertising campaigns, publishing layouts, web design, and corporate communications requiring legally cleared imagery. Editorial and commercial usage categories diverge in margin structure, with commercial licensing commanding premium rates for brand-safe, model-released content while editorial imagery serves news cycles with shorter revenue windows. Subscription models concentrate volume among marketers and designers, whereas pay-per-download formats retain relevance for publishers with intermittent needs.
The U.S. Copyright Office shapes creator compensation frameworks, while the EU AI Act imposes transparency obligations on platforms deploying generative tools. The Federal Trade Commission monitors disclosure standards for AI-modified imagery in advertising contexts. Stakeholders must weigh investments in authentic human-created content against synthetic media capabilities as platform policies and liability standards crystallize.
Market Dynamics
Generative AI capabilities are fragmenting creator compensation models and forcing platforms to restructure authentication workflows around human-verified provenance.
Growth Catalysts
- E-commerce visual asset procurement:Digital marketing teams at online retailers license imagery at scale for product pages and social campaigns, expanding subscription-based revenue pools.
- EU AI Act transparency mandates:Disclosure requirements for synthetic media create competitive differentiation for platforms investing in content provenance infrastructure.
- Mobile-first content consumption:Short-form video platforms drive demand for vertical-format stock footage and rapid-turnaround editorial imagery.
Market Restraints
- Creator supply concentration:Top-contributor networks in North America and Western Europe supply disproportionate catalog volume, creating geographic dependency risk.
- Generative substitution threat:Text-to-image tools compress willingness-to-pay for commodity lifestyle and product photography among cost-conscious buyers.
- Model release compliance friction:GDPR and emerging US state privacy laws extend liability chains for platforms distributing insufficiently documented portrait imagery.
Strategic Opportunities
- India content localization:Underpenetrated regional contributor networks and vernacular-language metadata tagging address demand from domestic digital advertisers.
- 3D asset and AR workflow convergence:Stock platforms integrating volumetric capture and real-time rendering tools capture budget from immersive commerce developers.
- CSRD visual reporting mandates:European corporate sustainability disclosure rules expand addressable market for documentary-style environmental and social imagery.
Industry Challenges
- Provenance verification skill gaps:Platforms lack sufficient forensic analysts to authenticate human-created submissions against synthetic submissions at ingestion scale.
- Legacy DAM integration complexity:Enterprise buyers face friction embedding cloud-native stock subscriptions into on-premise digital asset management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stock Photography Market |
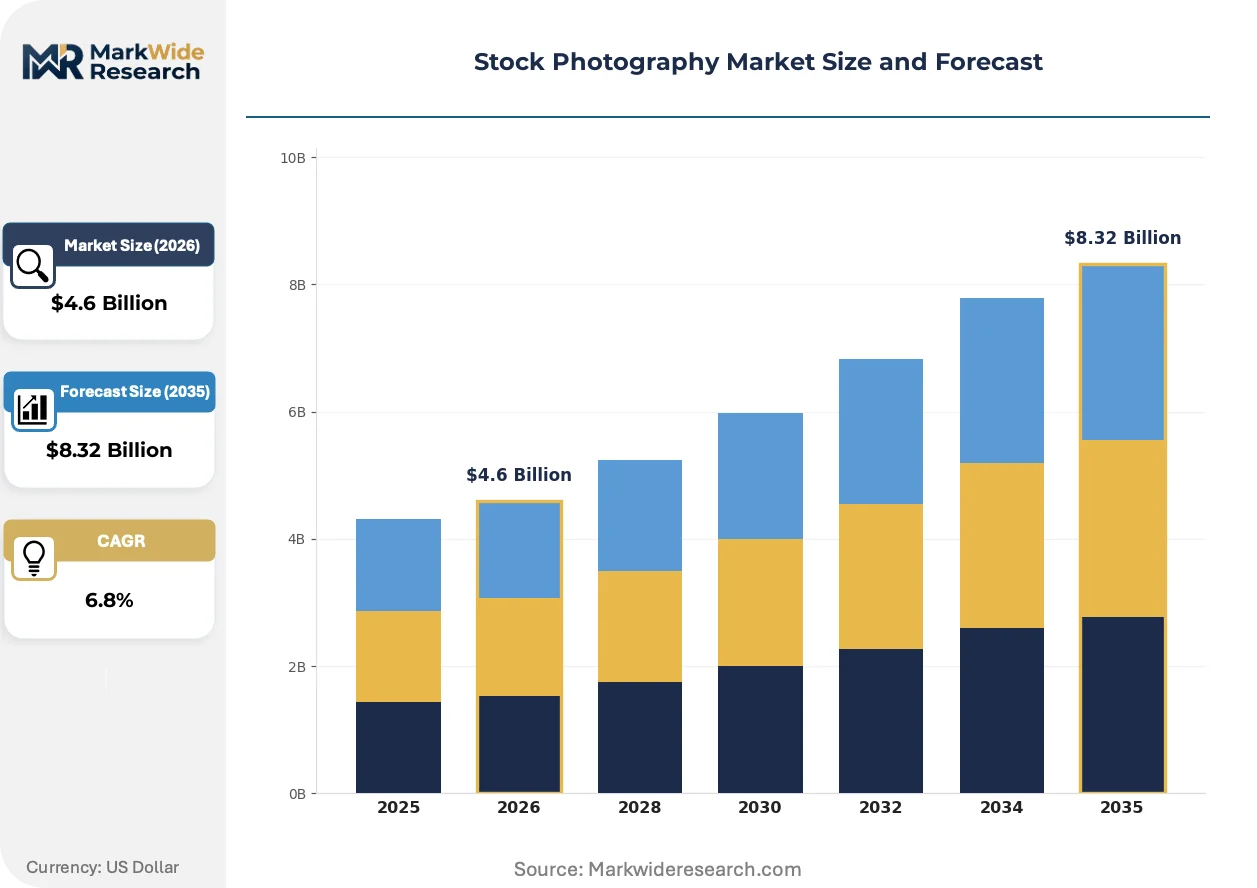
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $8.32 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Images, Illustrations, Videos, Vectors Usage: Commercial, Editorial, Advertising, Personal Subscription Model: Monthly, Yearly, Pay-per-Download, Freemium Target Audience: Marketers, Designers, Publishers, Bloggers |
| Companies Covered | iStock by Getty Images, Unsplash, Shutterstock, Stockphotos.com, Superstock, Getty Images, Alamy, TONL, Adobe Stock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stock Photography Market Strategic Shifts & Innovations
Content authentication technology and procurement platform architecture are diverging sharply between premium editorial and volume commercial segments, reshaping competitive investment priorities.
Blockchain-anchored provenance systems are bifurcating the market for high-integrity imagery. News agencies and documentary archives adopt immutable ledger verification to combat synthetic media misinformation. Premium buyers in financial services and pharmaceutical advertising now mandate cryptographic provenance as a procurement condition, compressing margins for platforms without credentialing infrastructure.
The EU AI Act's transparency obligations for generative content are forcing platform redesigns. Disclosure requirements for AI-modified or AI-generated imagery compel metadata field expansion and user interface overhauls. Commercial stock providers serving European enterprise buyers face the steepest compliance curves, while editorial agencies leverage existing captioning workflows to satisfy provenance mandates.
Self-serve subscription APIs are displacing traditional seat-based licensing among mid-market creative teams. Marketing technology stacks now embed stock search and licensing directly within design and publishing tools, bypassing standalone platform interfaces. This pattern concentrates most visibly among US-based SaaS-enabled creative teams purchasing imagery through integrated workflow triggers rather than deliberate catalog browsing.
Stock Photography Market Segmentation
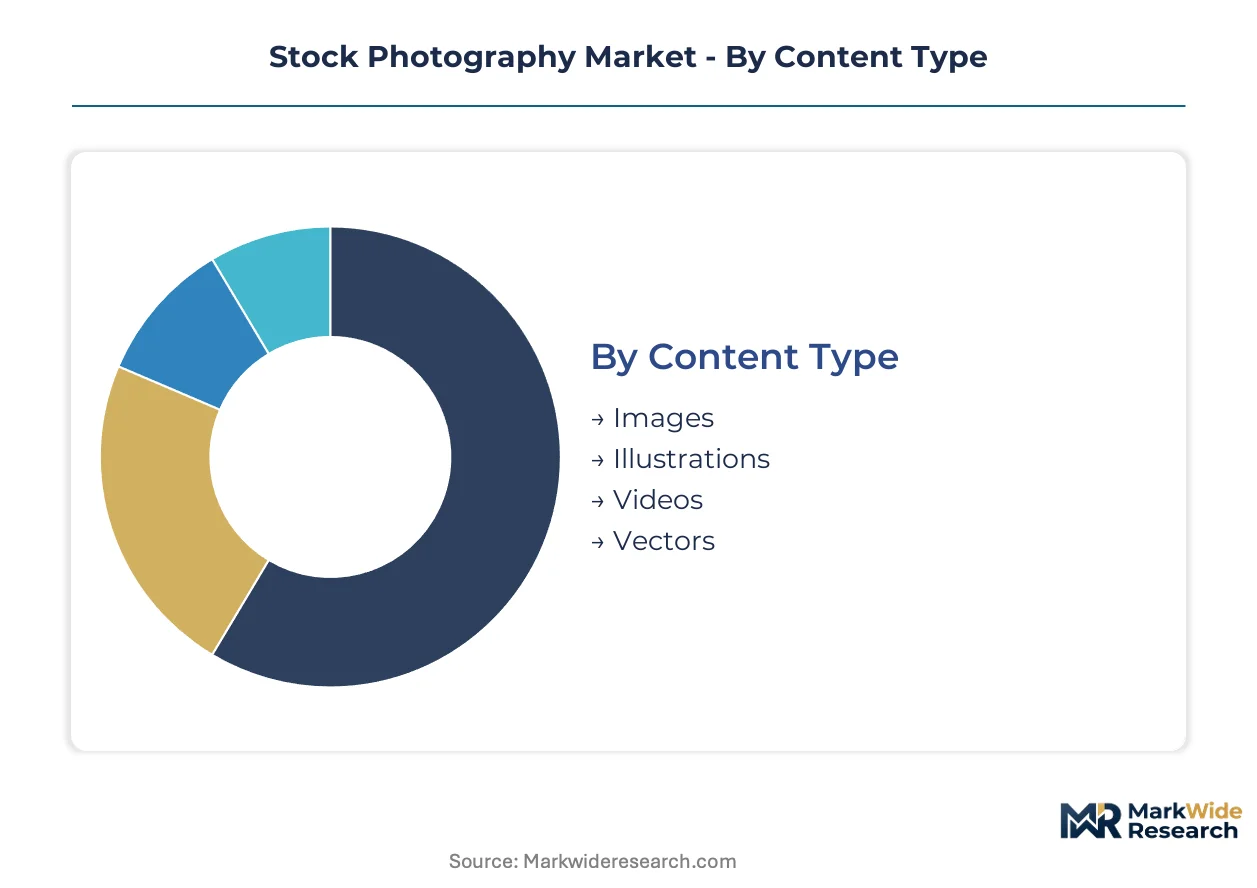
Stock photography platforms segment their offerings to match divergent procurement behaviors across creative workflows. Content type and licensing frameworks determine margin structures, while subscription models align with customer scale and usage frequency.
Content Type:
Channel-mix varies sharply by content format, with video and vectors flowing through API-integrated creative tools while static imagery sustains direct platform traffic.
- Images:Photographic stills constitute the volume foundation, spanning lifestyle, product, and conceptual categories. Marketers at US e-commerce platforms drive concentrated demand for brand-safe, model-released commercial imagery. The FTC monitors disclosure standards for AI-modified imagery in advertising contexts, elevating provenance verification costs.
- Videos:Motion content commands premium licensing rates with tiered resolution and duration structures. Short-form video platforms in the United States generate steep demand for vertical-format stock footage with rapid-turnaround editorial licensing. Mobile-first consumption patterns reshape production specifications toward 9:16 aspect ratios.
- Illustrations:Hand-rendered and digitally painted assets serve publishing and educational markets requiring stylistic differentiation from photography. Publishers with intermittent needs favor pay-per-download formats over subscription commitments for specialized illustration categories.
- Vectors:Scalable graphic elements integrate natively into design software workflows. Designers purchasing through Creative Cloud-embedded marketplaces represent the primary procurement channel for vector assets.
Images dominate installed base. Videos are where expansion concentrates.
Usage:
Cost tier stratification separates premium editorial licensing from volume commercial distribution, with advertising commanding the highest per-asset rates.
- Commercial:Brand-safe imagery with full model and property releases enables unrestricted advertising deployment. Enterprise procurement teams at pharmaceutical and financial services firms now mandate cryptographic provenance as a condition of licensing, compressing margins for platforms lacking verification infrastructure.
- Editorial:News-cycle imagery with event-specific captions serves shorter revenue windows in publishing and broadcast. News agencies leverage existing captioning workflows to satisfy EU AI Act transparency mandates for provenance disclosure.
- Advertising:Campaign-specific licensing with exclusivity options and extended usage rights commands premium rates. Digital marketing teams at online retailers license advertising imagery at scale through subscription-based procurement.
- Personal:Individual creators and small bloggers access entry-tier pricing with limited usage rights. Freemium models concentrate acquisition volume among cost-conscious buyers with intermittent project needs.
Commercial usage anchors revenue per transaction. Advertising licensing is climbing the fastest.
Subscription Model:
Volume concentration among SaaS-integrated creative teams favors API-based subscription access over traditional seat-based arrangements.
- Monthly:Flexible terms attract project-based marketers with seasonal campaign cycles. US-based SaaS-enabled creative teams purchase through integrated workflow triggers rather than deliberate catalog browsing.
- Yearly:Annual commitments unlock discounted rates and priority support tiers. Enterprise procurement of subscription-based visual assets intensifies in the United States as procurement teams consolidate vendor relationships.
- Pay-per-Download:Transactional licensing retains relevance for publishers with intermittent needs and specialized content requirements. Editorial agencies serving European corporate buyers face steeper compliance curves under EU AI Act disclosure requirements.
- Freemium:Limited-resolution access with upgrade pathways converts individual creators to paid tiers. Bloggers and social media managers represent the primary conversion funnel for freemium-to-paid transitions.
Yearly subscriptions dominate installed base. Monthly plans are gaining share fastest.
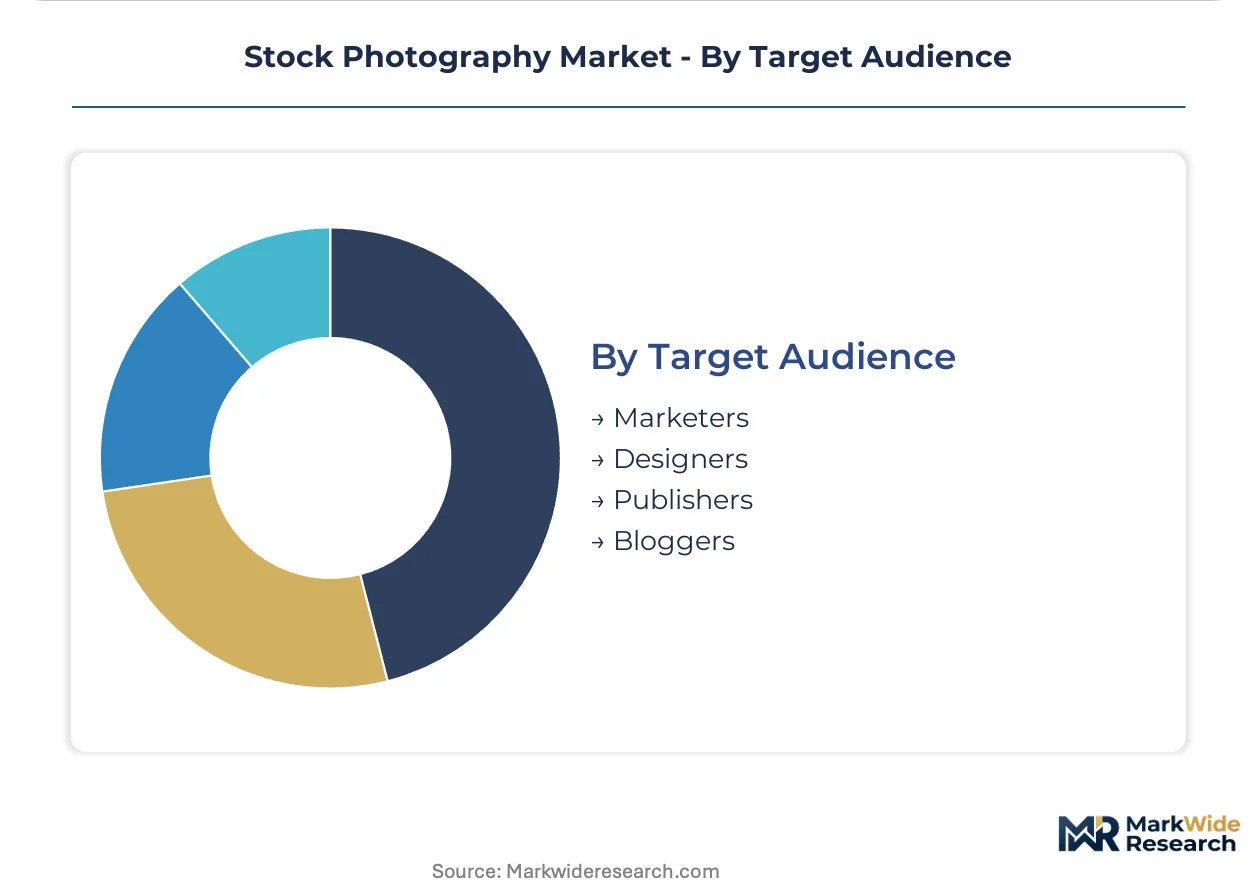
Target Audience:
Customer type determines interface design priorities, with designers requiring native workflow integration and publishers demanding advanced search and metadata capabilities.
- Marketers:Performance-driven buyers prioritize rapid asset discovery and brand safety verification. E-commerce visual asset procurement expands subscription-based revenue pools as digital marketing teams license imagery at scale.
- Designers:Creative professionals require seamless integration with Adobe Creative Cloud and Figma workflows. Self-serve subscription APIs displace traditional licensing interfaces among mid-market creative teams.
- Publishers:Editorial buyers demand precise captioning, rights clarity, and archival search depth. News agencies adopt blockchain-anchored provenance systems to combat synthetic media misinformation.
- Bloggers:Individual content creators seek affordable access with straightforward usage terms. Mobile-first platforms drive demand for simplified licensing interfaces and rapid-download capabilities.
Marketers dominate installed base. Designers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where enterprise subscription procurement commands premium rates, while cost-sensitive buyers in India compress margins through volume-based negotiation. This asymmetry reshapes platform investment priorities across geographies.
United States
Digital marketing teams at e-commerce platforms drive concentrated demand for brand-safe commercial imagery with full model releases. The FTC monitors disclosure standards for AI-modified imagery in advertising contexts, elevating compliance costs for platforms serving enterprise buyers. New York and Los Angeles anchor contributor networks supplying premium editorial and lifestyle content to global buyers.
Germany
Corporate sustainability reporting mandates under the EU CSRD expand demand for documentary-style environmental and social imagery from European enterprises. The EU AI Act imposes transparency obligations on platforms deploying generative tools, forcing metadata infrastructure investments. Berlin and Munich host dense clusters of creative agencies integrating stock subscriptions into marketing technology stacks.
United Kingdom
Publishers and broadcasters sustain demand for rapid-turnaround editorial imagery serving news cycles with shorter revenue windows. The UK Information Commissioner's Office enforces GDPR-aligned model release documentation standards, extending liability chains for portrait distribution. London concentrates premium editorial licensing relationships between news agencies and photojournalists.
India
Domestic digital advertisers generate underpenetrated demand for vernacular-language metadata tagging and regionally specific visual content. The country's central bank monitors cross-border payment flows for digital licensing transactions, affecting platform revenue recognition. Mumbai and Bangalore emerge as contributor hubs addressing localization gaps in South Asian visual catalogs.
Japan
Corporate communications teams license imagery for brand-safe internal and external publishing with strict quality verification requirements. METI guidelines on AI-generated content disclosure influence platform policy adaptations for Japanese enterprise buyers. Tokyo anchors premium commercial photography production serving pan-Asian advertising campaigns.
Stock Photography Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the stock photography ecosystem. The market structures around three tiers: premium editorial agencies with direct contributor relationships, volume platforms with API-integrated distribution, and community-driven repositories with freemium conversion models. Strategic differentiation concentrates on content provenance infrastructure and native workflow integration. Dominant competitive moves include portfolio diversification into video and 3D assets, plus geographic expansion into underpenetrated contributor markets.
Within the premium editorial tier, Getty Images and iStock by Getty Images occupy positions anchored in direct photojournalist relationships and news agency partnerships. Shutterstock exemplifies the volume-platform archetype with multi-continent contributor networks sustaining diverse catalog depth. Adobe Stock sits within the workflow-integrated segment, leveraging Creative Cloud embedding to capture designer procurement flows.
| Leading Market Players |
|---|
| iStock by Getty Images |
| Unsplash |
| Shutterstock |
| Stockphotos.com |
| Superstock |
| Getty Images |
| Alamy |
| TONL |
| Adobe Stock |
| Others |
Cost & Logistics Intelligence
Generative AI substitution for commodity lifestyle photography simultaneously redistributes contributor supply toward premium editorial hubs and compresses pricing power in volume commercial tiers. This dual pressure forces platforms to restructure acquisition economics around provenance verification costs while relocating sourcing investments to underpenetrated regional networks.
Pricing Analysis
Geographic price spreads separate premium editorial licensing in the United States from cost-optimized commercial subscriptions in India. Three-tier pricing structure across premium, standard, and economy levels anchors enterprise procurement, with cryptographic provenance certification and model release documentation quality serving as primary differentiation drivers. Pricing pressure stems from text-to-image tools eroding willingness-to-pay for generic lifestyle imagery among budget-constrained buyers. Small bloggers and individual creators exhibit highest price sensitivity, while pharmaceutical and financial services procurement teams show lowest sensitivity due to compliance mandates.
Supply Chain Analysis
Just-in-time content ingestion dominates platform operations, with real-time contributor uploads replacing strategic stockpiling of pre-produced catalogs. Supply concentrates in the United States, United Kingdom, and Germany for premium editorial content, while India and Southeast Asia emerge as growth hubs for localized commercial imagery. Raw material dependencies include professional camera equipment, model talent pools, and location release documentation. Single-source vulnerability risks concentrate in top-contributor networks supplying disproportionate catalog volume. Distribution runs through API-integrated creative tool marketplaces and direct platform interfaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stock photography market faces high-growth disruption from EU AI Act transparency mandates, which force platform infrastructure investments while creating competitive differentiation for early compliance leaders.
For Market Incumbents: Secure cryptographic provenance infrastructure investments to defend premium licensing relationships against synthetic media substitution threats. Deepen contributor network diversification into India and Southeast Asia to reduce geographic concentration risk. Prioritize backward integration into native workflow tools through Adobe Creative Cloud and Figma embedding partnerships. For New Entrants and Emerging Players: Vernacular-language metadata tagging gaps in Indian digital advertising markets represent immediate white-space opportunities. Target documentary-style environmental imagery serving EU CSRD corporate sustainability reporting mandates as the most penetrable segment. Pursue direct API partnerships with regional marketing technology stacks rather than standalone platform development. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed volume platforms lacking provenance verification infrastructure. Five-to-ten year viability hinges on successful workflow integration and regional localization execution. Acquisition candidates include India-focused contributor networks and blockchain-anchored authentication technology providers. Monitor EU AI Act enforcement actions as the critical inflection signal for platform compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Provenance Infrastructure Investment | Blockchain-anchored verification satisfies EU AI Act mandates for Getty Images and Shutterstock enterprise clients. |
| Regional Contributor Network Expansion | Mumbai and Bangalore hub development addresses localization gaps in South Asian commercial imagery catalogs. |
| API Workflow Integration | Creative Cloud embedding captures designer procurement flows for Adobe Stock against standalone platform competitors. |
| 3D Asset Portfolio Diversification | Volumetric capture capabilities capture immersive commerce developer budgets from AR and virtual production pipelines. |
| Compliance-First Platform Redesign | Metadata field expansion satisfies FTC disclosure standards for AI-modified imagery in US advertising contexts. |
Research Approach
A standing panel of platform content directors, contributor network managers, enterprise procurement officers, and creative agency licensing leads provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against SEC filings, EU regulatory databases, and marketing technology stack integration disclosures. Bottom-up contributor network analysis and top-down enterprise spending pattern triangulation anchored market sizing across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs before finalization. The analytical framework modeled segmentation across content type, licensing framework, subscription model, and geographic contributor cluster throughout the projection horizon. CAGRs derived from historical platform revenue disclosures and forward-looking procurement intention surveys. Industry-specific forecast inputs included EU AI Act implementation timelines and mobile-first content consumption acceleration patterns.
Material uncertainties — generative AI capability advances, cross-border payment regulation shifts, and contributor supply concentration disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about platform compliance cost trajectories and enterprise subscription renewal rates. Revision becomes warranted when synthetic media substitution rates for commercial imagery cross thresholds that fundamentally alter buyer willingness-to-pay structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Global Location-Based Entertainment Market
Digital Media
Global Transport Media Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
Cognitive Media Market
Digital Media
Sound Effects Services Market
Digital Media
Art App Market
Digital Media
Europe Inflight Entertainment and Connectivity Market
Digital Media
Information Short Video Market
Digital Media
Digital Music Content Market
Digital Media
Video Content Management Market
Digital Media
Music Rights Management Market
Digital Media
Anime Derivatives Market
Digital Media
North America Webtoons Market
Digital Media
Global Animation Market
Digital Media
Digital Content Creation Market
Digital Media
Europe Online Video Platform Market