
 Global Digital Painting Market | 2026-2036
Global Digital Painting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Painting Market Foresight
Cloud-native rendering pipelines is reconfiguring how digital painting tools are architected and monetized across the creative software stack. Adobe Inc. leverages its Creative Cloud ecosystem to anchor subscription revenue across professional segments. Corel Corporation sustains its position in illustration through specialized raster and vector toolsets. Wacom Co., Ltd. dominates the hardware-software interface layer with integrated stylus and tablet ecosystems.
Digital painting encompasses the creation, manipulation, and finishing of visual artwork through software-based brush engines, layer compositing, and color management systems operating at resolutions from 72 ppi for web assets to 600 ppi for print reproduction. The technology serves commercial illustration, entertainment pre-production, and interactive media asset generation where iterative revision and non-destructive editing are operational requirements. Raster graphics software occupies the largest installed base among professional artists due to its fidelity in simulating traditional media textures. Vector graphics tools represent the fastest-expanding segment among advertising and marketing workflows where scalability across print and digital channels commands premium licensing. Animation software concentrates margin pools in entertainment production where studio contracts demand enterprise-grade support and pipeline integration.
The EU AI Act shapes algorithmic content generation features within European jurisdictions, requiring transparency disclosures for AI-assisted brush and fill tools. The US FCC oversees bandwidth allocation affecting cloud-synced canvas workflows and real-time collaboration latency. ISO color management standards govern cross-platform consistency for print-ready output demanded by advertising clients. Stakeholders must monitor how regulatory fragmentation around generative AI training data affects feature development roadmaps and territorial product availability.
Market Dynamics
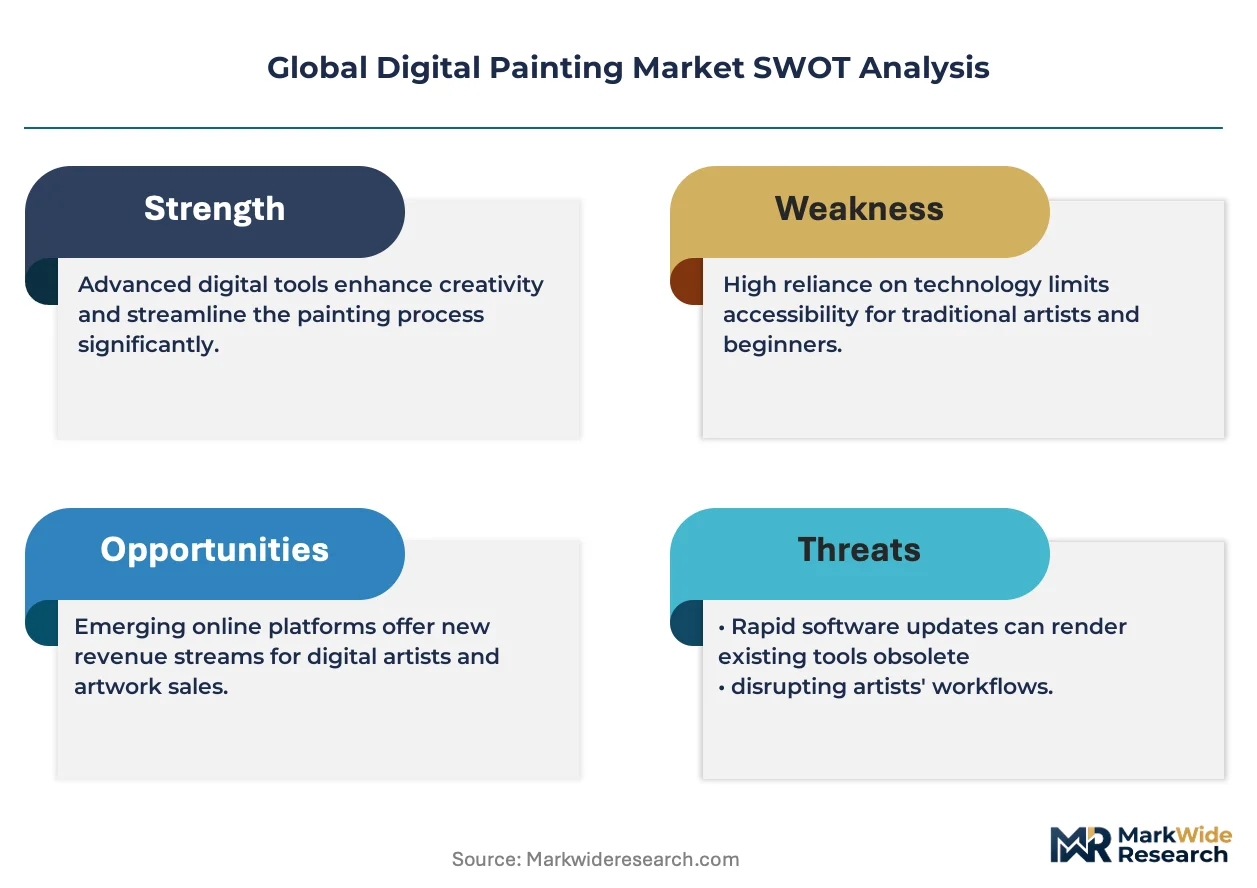
Cloud-native rendering pipelines are compressing hardware barriers and redistributing creative software purchasing power from capital expenditure to operational subscription models across professional and prosumer segments.
Growth Catalysts
- Cloud Rendering Infrastructure:Distributed GPU clusters enable real-time canvas synchronization without local workstation investment, expanding addressable creator bases in emerging markets.
- EU AI Act Transparency Mandates:Disclosure requirements for algorithmic brush engines are accelerating development of auditable, human-in-the-loop creative tools that command enterprise licensing premiums.
- Entertainment Pre-Production Pipelines:Game design studios and animation houses require iterative asset revision capabilities that raster graphics software delivers through non-destructive layer architectures.
Market Restraints
- Input Cost Volatility:Proprietary stylus tip materials and pressure-sensor components concentrate manufacturing in East Asian supplier networks subject to logistics disruption.
- Technical Fidelity Ceilings:Raster graphics resolution scaling creates exponential file size growth that outpaces bandwidth infrastructure in rural creative clusters.
- Regulatory Fragmentation:Divergent training data disclosure requirements between the EU AI Act and US FCC guidelines force territorial feature versioning that elevates compliance overhead.
Strategic Opportunities
- India Creative Professional Expansion:Government PLI scheme incentives for digital content infrastructure are attracting software localization investments for regional language brush engine development.
- Vector-Animation Convergence:Scalable vector graphics tools are penetrating motion design workflows previously dominated by frame-based raster pipelines, opening new licensing tiers.
- ISO Color Management Certification:Cross-platform standardization mandates from advertising procurement departments create preference premiums for certified color-calibrated tablet hardware bundles.
Industry Challenges
- Pipeline Integration Complexity:Legacy studio asset management systems require custom API development for cloud-synced canvas workflows, extending enterprise sales cycles.
- Specialized Talent Scarcity:Brush engine mathematics and GPU shader programming expertise concentrates in gaming industry hubs, constraining independent software vendor R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Painting Market |
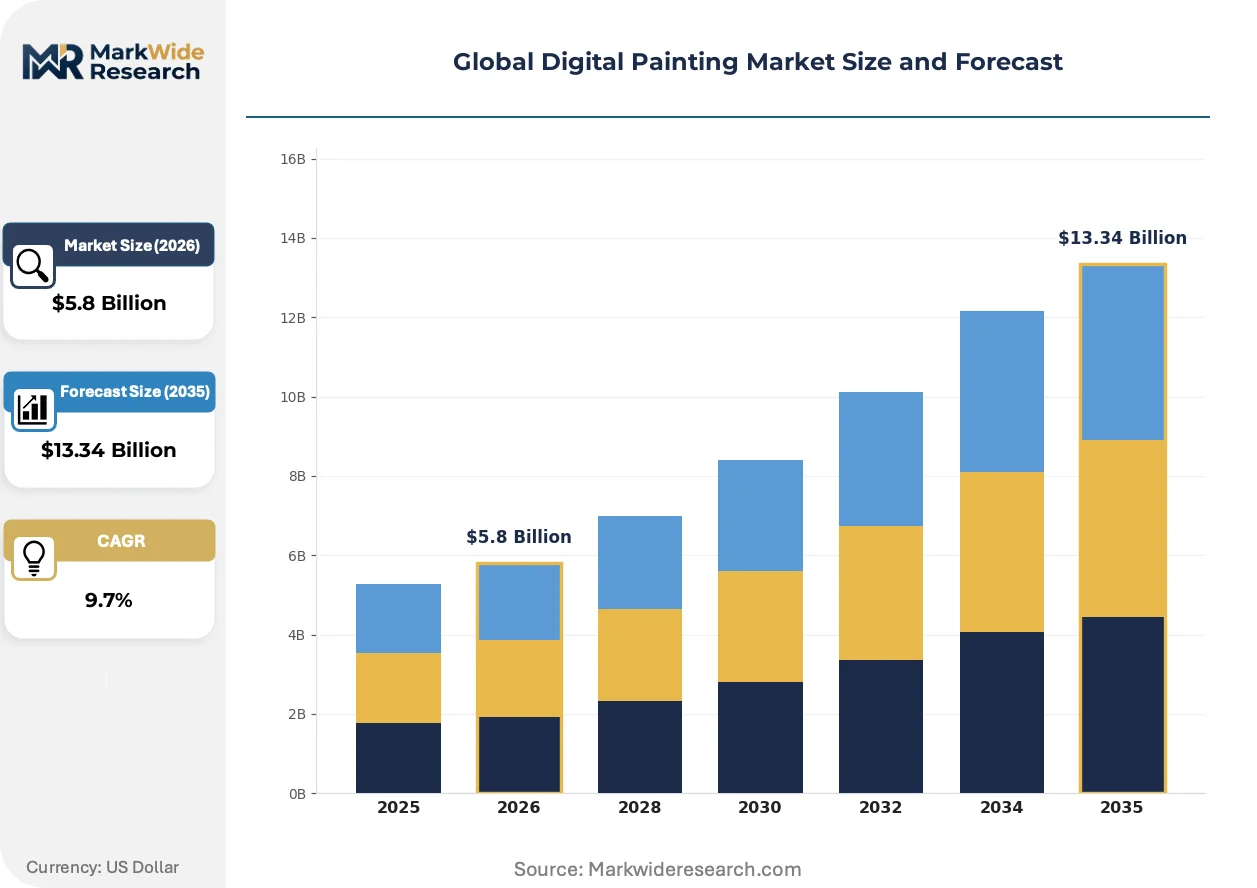
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.34 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Vector Graphics, Raster Graphics, 3D Painting, Animation Software, Motion Graphics, Others Application: Entertainment Production, Education & Training, Advertising & Marketing, Visual Arts, Game Design, E-learning Device Compatibility: Desktop Computers, Graphic Tablets, Smartphones, Laptops, Interactive Whiteboards, Smart TVs End User: Professional Artists, Graphic Designers, Illustrators, Educators, Content Creators, Freelancers |
| Companies Covered | Adobe Inc., Corel Corporation, Autodesk Inc., Celsys, Wacom Co., Ltd., Smith Micro Software, Inc., Ambient Design Ltd., Escape Motions, s.r.o., Pixarra Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Painting Market Shifts & Advancements
Generative brush algorithms and real-time collaboration protocols are reconfiguring how creative assets move from individual workstations into distributed production pipelines across entertainment and advertising verticals.
Neural style transfer engines are hybridizing traditional brush physics with pattern recognition models. Concept art departments at major entertainment studios are adopting these hybrid tools for rapid iteration on environmental matte paintings. The technology is compressing pre-production timelines while elevating demand for human finishing expertise that validates algorithmic outputs against director creative intent.
EU AI Act algorithmic transparency requirements are mandating disclosure labels on AI-assisted fill and texture tools. European software distributors must now embed provenance metadata that traces generative outputs to training data categories. Illustration software vendors serving EU enterprise accounts are responding by partitioning feature sets into fully human-controlled and disclosed-AI-assisted licensing tiers.
Subscription fatigue among freelance illustrators is fragmenting purchasing patterns across perpetual-license holdouts and tiered-cloud hybrid models. Independent creators in the United States are unbundling software suites to purchase single-application licenses through direct-to-developer channels rather than consolidated creative cloud ecosystems. This behavioral shift pressures established vendors to maintain parallel pricing architectures without cannibalizing enterprise contract values.
Global Digital Painting Market Segmentation
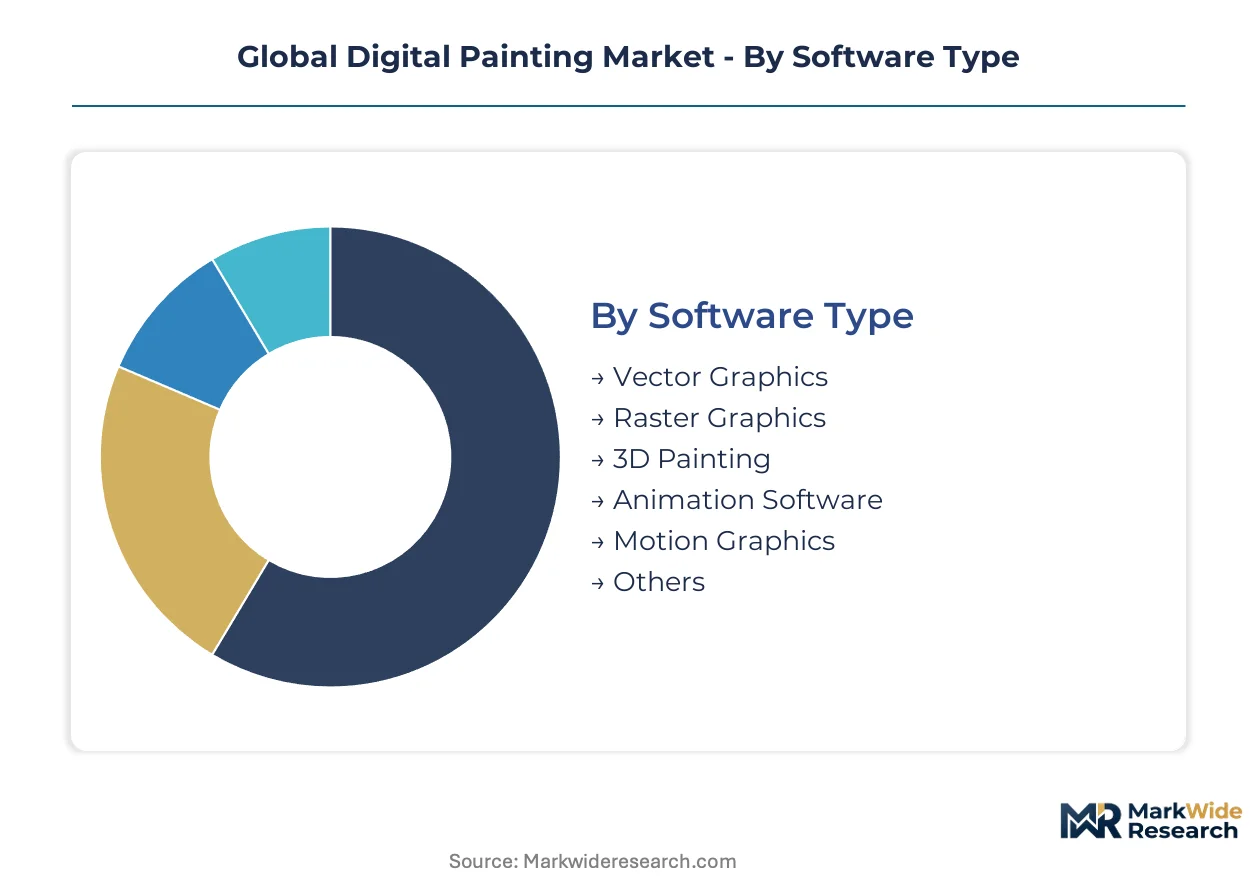
Segmentation in digital painting software determines how vendors architect licensing tiers, cloud resource allocation, and hardware integration roadmaps. Each dimension—software type, application, device compatibility, and end user—creates distinct margin profiles and support intensity requirements that shape competitive positioning.
Software Type:
After-sales-service intensity varies dramatically across software architectures, with enterprise animation suites demanding dedicated pipeline engineers while consumer raster tools rely on community forums.
- Raster Graphics:Pixel-based engines simulate traditional media textures through brush physics algorithms at resolutions scaling from 72 ppi to 600 ppi. Entertainment pre-production houses in the United States concentrate procurement here for matte painting and concept art workflows where iterative revision cycles dominate production schedules.
- Vector Graphics:Mathematical path-based rendering enables infinite scalability across print and digital channels without resolution loss. Advertising agencies in Germany and France are migrating budget toward these tools as ISO color management standards tighten cross-platform consistency requirements for multi-channel campaigns.
- 3D Painting:Texture mapping onto polygonal meshes for game asset pipelines.
- Animation Software:Frame-based and rig-driven motion tools with enterprise support tiers.
- Motion Graphics:Time-based vector animation for broadcast and social video.
- Others:Specialized tools including procedural texture generators and AI-assisted fill engines.
By volume, Raster Graphics leads. By growth pace, Vector Graphics is ahead.
Application:
Cost tier stratification separates enterprise site licenses from individual creator subscriptions, with entertainment studios paying 10-40x per seat versus freelance illustrators.
- Entertainment Production:Studio pipelines for film, television, and streaming content requiring non-destructive layer architectures and version control integration. Major production houses in Los Angeles and London drive demand for cloud-synced canvas workflows that compress pre-production timelines.
- Game Design:Iterative asset generation for interactive environments and character models. Studios in Japan and South Korea are expanding digital asset pipelines as mobile and console release cycles accelerate.
- Advertising & Marketing:Scalable campaign asset creation across print, digital, and out-of-home channels.
- Education & Training:Institutional licensing for curriculum-integrated digital art instruction.
- Visual Arts:Gallery and print-oriented fine art production with archival color requirements.
- E-learning:Courseware illustration and interactive content for online education platforms.
Entertainment Production captures the largest revenue pool. Game Design is expanding most quickly as live-service content models proliferate.
Device Compatibility:
Customer type segmentation separates workstation-dependent professionals from mobile-first creators, with distinct peripheral ecosystems and synchronization requirements.
- Graphic Tablets:Pressure-sensitive stylus interfaces with integrated display or opaque digitizer surfaces. Professional artists in the United States and Japan concentrate adoption here, where Wacom and competitors anchor hardware-software bundles that reduce switching costs.
- Desktop Computers:High-performance workstations for resolution-intensive raster workflows. Concept art departments at major studios in California and British Columbia standardize on these configurations for environmental matte painting.
- Laptops:Mobile workstations with discrete GPU acceleration for location-based production.
- Smartphones:Touch-based creation tools for rapid sketching and social content.
- Interactive Whiteboards:Large-format collaborative surfaces for education and presentation.
- Smart TVs:Living-room display integration for portfolio review and client presentation.
Graphic Tablets dominate professional segment revenue. Smartphones are gaining share fastest among emerging creator demographics.
End User:
Supply concentration in brush engine mathematics expertise concentrates vendor R&D investment toward professional segments where annual contract values justify specialized development.
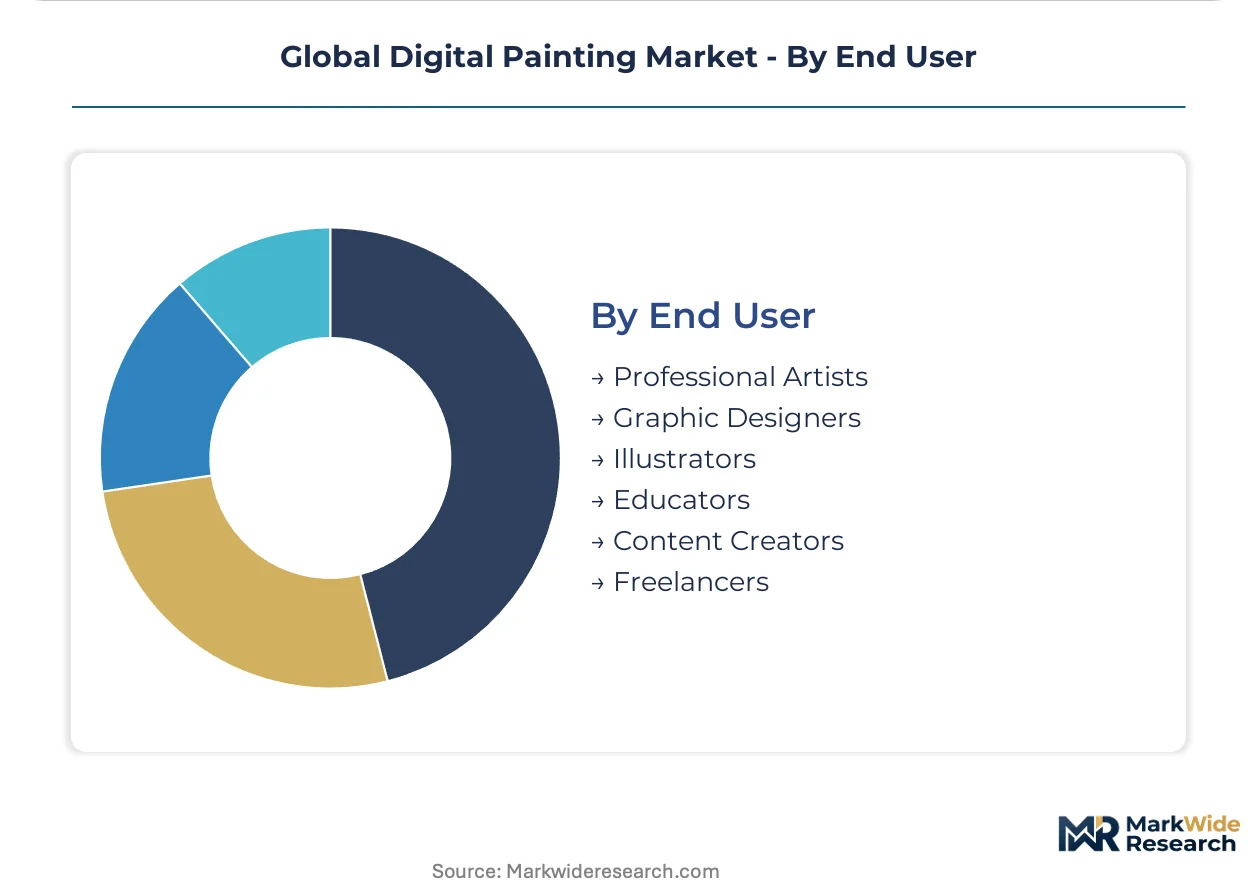
- Professional Artists:Full-time creators requiring advanced color management, custom brush scripting, and print-calibrated output. This segment in France and Germany faces EU AI Act transparency mandates that elevate preference for auditable, human-in-the-loop tool licensing.
- Graphic Designers:Cross-functional visual communicators integrating typography, layout, and illustration. Marketing agencies in the United Kingdom concentrate demand here for rapid-turnaround campaign asset production.
- Illustrators:Narrative and editorial image specialists with distinct workflow requirements.
- Content Creators:Social media and streaming-focused producers with platform-specific format needs.
- Educators:Institutional instructors requiring volume licensing and curriculum alignment.
- Freelancers:Independent operators driving subscription fatigue and unbundled purchasing patterns.
Professional Artists generate the highest per-user lifetime value. Content Creators are climbing the fastest as platform economics expand addressable bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net export positions in creative software concentrate in the United States and Japan, while import-dependent markets in India and Southeast Asia drive localization investments. Cloud infrastructure expansion is redistributing value capture from hardware manufacturers toward subscription-based software platforms.
United States
Entertainment production houses in Los Angeles and independent game studios in Austin concentrate procurement of raster graphics suites for iterative concept art workflows. The FCC oversees bandwidth allocation affecting real-time cloud canvas synchronization latency. Seattle-based cloud providers anchor distributed GPU cluster infrastructure that reduces workstation capital requirements for emerging creators.
Germany
Advertising agencies in Hamburg and Munich are migrating budgets toward vector graphics tools as ISO color management standards tighten cross-platform consistency mandates. The EU AI Act transparency requirements elevate preference for auditable, human-in-the-loop licensing tiers. The Cologne-Düsseldorf corridor hosts specialized print-calibration service bureaus supporting multi-channel campaign asset production.
Japan
Animation studios in Tokyo and Osaka drive enterprise-grade animation software contracts demanding pipeline integration and dedicated support engineers. METI industrial policy supports digital content infrastructure investments for export-oriented creative industries. The Kyoto-Osaka-Kobe zone concentrates brush engine mathematics expertise inherited from gaming industry shader programming talent pools.
India
Government PLI scheme incentives for digital content infrastructure attract software localization investments for regional language brush engine development. The central bank monitors foreign exchange flows affecting cloud subscription pricing in rupee terms. Bengaluru and Hyderabad clusters host expanding game design studios adopting cloud-native rendering pipelines for mobile and console asset production.
South Korea
Game design studios in Seoul and Busan expand digital asset pipelines as live-service content models accelerate release cycles. The national broadcasting regulator shapes bandwidth allocation for real-time collaborative workflows. The Pangyo Techno Valley concentration houses entertainment technology firms integrating stylus hardware with proprietary software ecosystems.
Global Digital Painting Market Competitive Landscape
On the supply side, the industry is consolidating around integrated creative cloud ecosystems while fragmenting across specialized tool vendors serving distinct workflow niches. Two strategic archetypes dominate: platform consolidators anchoring subscription revenue across professional segments, and vertical specialists defending margin pools in hardware-software interface layers. Competitive moves concentrate on API-level pipeline integration for enterprise studio contracts and territorial feature versioning to satisfy divergent regulatory disclosure requirements.
Within the platform consolidator tier, Adobe Inc. and Autodesk Inc. exemplify ecosystem-centric positioning where subscription architectures span multiple creative disciplines. Corel Corporation occupies a specialist position in illustration toolsets. Wacom Co., Ltd. anchors the hardware-software interface layer through integrated stylus and tablet ecosystems.
| Leading Market Players |
|---|
| Adobe Inc. |
| Corel Corporation |
| Autodesk Inc. |
| Celsys |
| Wacom Co., Ltd. |
| Smith Micro Software, Inc. |
| Ambient Design Ltd. |
| Escape Motions, s.r.o. |
| Pixarra Inc. |
| Others |
Supply & Pricing Matrix
Shanghai-Los Angeles transpacific freight corridors transmit cost volatility from East Asian stylus component manufacturing clusters into downstream subscription pricing tiers for professional creative hardware bundles.
Pricing Analysis
Enterprise studio buyers anchor value-based licensing structures across cloud-native rendering tiers. Three-tier pricing structure across premium, standard, and economy levels separates enterprise pipeline integration from prosumer feature sets and entry-level mobile subscriptions. Price differentiation rests on ISO color management certification status and dedicated support engineer allocation. Cost compression in the prosumer tier is intensifying because independent creators are unbundling suite purchases into single-application licenses through direct channels.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic sourcing decisions for pressure-sensor digitizer assemblies. Manufacturing concentrates in Taiwan, South Korea, and Japan for GPU shader components, proprietary stylus tip materials, and display panel integration. Raw material dependencies draw from rare-earth magnet suppliers, specialized polymer substrates, and precision-machined aluminum chassis. Single-source vulnerability in East Asian brush engine mathematics talent pools elevates recruitment costs for independent software vendors. Distribution runs through direct-to-creator digital storefronts and enterprise sales teams serving entertainment production houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud rendering infrastructure expansion signals early-cycle penetration acceleration as hardware capital barriers collapse across emerging creator demographics.
For Market Incumbents: Pre-empt subscription fatigue fragmentation by maintaining parallel perpetual-license architectures alongside cloud tiers without cannibalizing enterprise contract values. Deepen backward integration into proprietary stylus hardware ecosystems to defend margin position against tablet OEMs bundling third-party software. Anchor pipeline API development resources toward Los Angeles and Tokyo studio clusters where custom integration demands extend sales cycles but lock in multi-year commitments. For New Entrants and Emerging Players: Establish a beachhead in regional language brush engine localization for India government PLI scheme beneficiaries. Target vector-animation convergence workflows where scalable tools penetrate motion design pipelines previously dominated by frame-based raster systems. Deploy ISO color management certification bundling as a go-to-market wedge against uncalibrated hardware competitors serving European advertising procurement departments. For Investors and Strategic Acquirers: Carve-out targets emerge from gaming industry shader programming talent pools holding brush engine mathematics expertise that constrains independent vendor R&D velocity. Long-term viability favors vertical specialists defending hardware-software interface layers over platform consolidators facing subscription saturation. Monitor EU AI Act territorial feature versioning overhead as an inflection signal for compliance-cost-driven consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Rendering Pipeline Launch | Reduces workstation capital barriers for Bengaluru and Hyderabad studio clusters adopting distributed GPU infrastructure. |
| ISO Color Management Certification Program | Creates preference premiums among Hamburg and Munich advertising agencies tightening cross-platform consistency mandates. |
| Regional Language Brush Engine Localization | Captures India PLI scheme incentives for digital content infrastructure targeting government-supported creator demographics. |
| API-Level Pipeline Integration Partnership | Compresses enterprise sales cycles for Los Angeles entertainment houses requiring custom asset management system connectivity. |
| Acquisition of Shader Programming Specialist | Secures scarce brush engine mathematics expertise concentrated in Kyoto-Osaka-Kobe gaming industry talent pools. |
Research Methodology
Cross-validation between primary interviews with creative software product managers, studio pipeline engineers, and hardware procurement leads and secondary validation against SEC creative cloud revenue disclosures, hyperscaler GPU capex reports, and EU regulatory filing databases anchors the qualitative findings. Bottom-up triangulation across individual application licensing trends and top-down analysis of enterprise contract value pools were reconciled through iterative stakeholder feedback.
Calibration against historical adoption curves for raster-to-vector workflow migrations and cloud rendering infrastructure deployment shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include software architecture type, end-use application vertical, device compatibility tier, and regional regulatory cluster. CAGRs were derived from S-curve penetration analysis applied to entertainment pre-production pipeline spend and independent creator hardware refresh cycles.
Stress conditions across EU AI Act compliance cost trajectories, transpacific logistics disruption scenarios, and subscription fatigue unbundling velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cloud infrastructure buildout pacing and generative AI feature adoption ceilings. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
US Automatic Content Recognition Market
Digital Media
Sports Broadcasting Technology Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
In Flight Entertainment Market
Digital Media
US Webtoons Market
Digital Media
Adult Entertainment Market
Digital Media
Digital Music Content Market
Digital Media
Europe Anime Merchandising Market
Digital Media
Stream Hosting Market
Digital Media
North America Webtoons Market
Digital Media
United Kingdom Webtoons Market
Digital Media
Anime Merchandising Market
Digital Media
Sports Graphics Market
Digital Media
ACGN Subculture Market
Digital Media
Social TV Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market