
 Spiral Freezer Market | 2026-2036
Spiral Freezer Market Size, Share, and Industry Trends Forecast 2026-2036
Spiral Freezer Market Analysis
Multi-source procurement among frozen food manufacturers is consolidating around fewer specialized equipment vendors with proven cryogenic expertise. GEA Group leverages its refrigeration systems portfolio to anchor large-scale protein processing contracts across Northern Europe. John Bean Technologies Corporation sustains competitive positioning through technology leadership in hygienic conveyor design for ready-to-eat applications. Mayekawa Mfg. Co., Ltd. dominates Asian installations with ammonia-based systems engineered for tropical operating conditions.
A spiral freezer employs a continuous belt wound in a vertical helical path to maximize surface exposure to refrigerated air or cryogenic gas within a compact footprint, typically achieving core temperatures of minus 18 degrees Celsius or lower for food safety and preservation. Continuous freezers lead installed capacity across high-volume poultry and seafood plants where throughput exceeds five metric tons per hour. Cryogenic technology segments command premium positioning in applications requiring rapid surface freezing to preserve cellular structure, while carbon dioxide systems face refrigerant cost pressures from tightening environmental protocols.
EPA regulations under the Significant New Alternatives Policy program restrict high-global-warming-potential refrigerants in industrial freezing equipment, compelling engineering redesigns across US manufacturing bases. EMA and EFSA frameworks indirectly shape equipment standards through pharmaceutical cold-chain validation requirements that spiral freezer vendors must address for drug substance applications. Stakeholders should monitor refrigerant transition timelines and validate supplier readiness for next-generation low-GWP alternatives before committing to multi-decade capital installations.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant choice sets while Southeast Asian seafood processors expand capacity, creating a bifurcation between compliance-driven retrofits and greenfield ammonia installations.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants is compelling protein processors across Northern Europe to replace aging equipment with next-generation low-GWP systems, accelerating replacement cycles.
- Frozen seafood expansion:Vietnam's Mekong Delta processing zones are adding capacity to serve export markets, driving demand for continuous freezers capable of handling tropical humidity loads.
- Ammonia technology maturation:Advances in packaged ammonia systems with reduced charge volumes are enabling safer deployment in densely populated processing corridors.
Market Restraints
- Refrigerant cost volatility:Carbon dioxide system operating costs are escalating as environmental protocols tighten supply chains for industrial-grade CO₂.
- Engineering talent concentration:Cryogenic system design expertise pools in Germany and Japan, creating procurement bottlenecks for projects in emerging processing regions.
- Legacy asset inertia:US poultry plants carry decades-old CFC-era infrastructure that resists cost-justified replacement despite EPA SNAP restrictions.
Strategic Opportunities
- Indian cold-chain buildout:FSSAI enforcement of mandatory freezing protocols for frozen food distribution is opening demand for compact spiral units in secondary cities.
- Pharmaceutical validation:EMA cold-chain requirements for drug substances are extending spiral freezer applications into active pharmaceutical ingredient processing.
- Hybrid cryogenic-mechanical systems:Convergence of liquid nitrogen surface freezing with mechanical refrigeration is enabling premium seafood processors to optimize cell-structure preservation.
Industry Challenges
- Ammonia safety certification:Operator licensing requirements under OSHA Process Safety Management are extending commissioning timelines for US installations.
- Integration complexity:Retrofitting spiral freezers into existing HACCP-validated lines without disrupting continuous operation demands specialized project management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spiral Freezer Market |
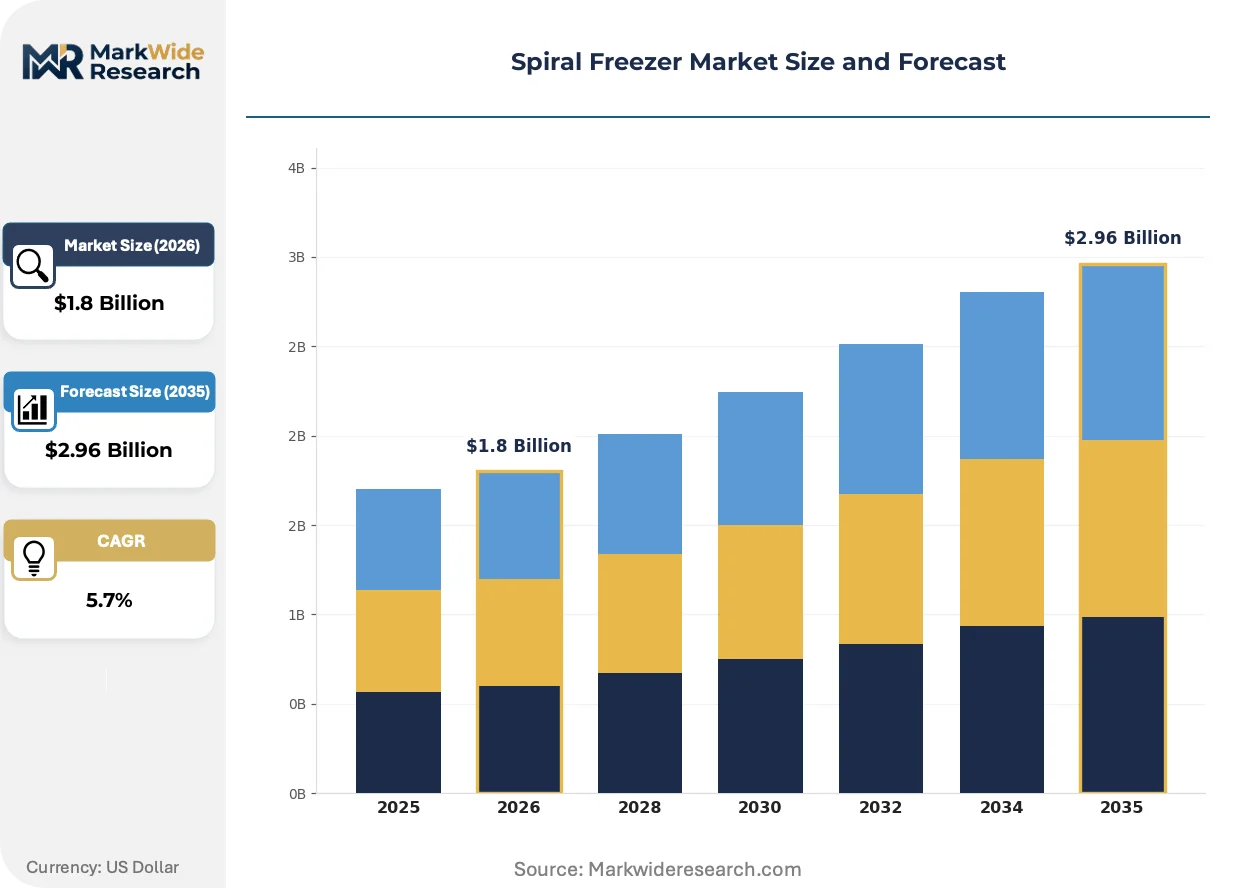
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Freezer, Batch Freezer, Self-Contained Freezer, Blast Freezer Technology: Air Blast, Liquid Nitrogen, Carbon Dioxide, Cryogenic End User: Food Processing, Pharmaceuticals, Chemical Industry, Retail Capacity: Small Scale, Medium Scale, Large Scale, Industrial Scale |
| Companies Covered | GEA Group, John Bean Technologies Corporation, Linde PLC, Air Liquide, Mayekawa Mfg. Co., Ltd., FPS Food Process Solutions, VDL Systems BV, SCANICO A/S, RMF Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spiral Freezer Market Emerging Trajectories
Equipment architecture is fragmenting as modular designs challenge monolithic installations, while refrigerant chemistry shifts and buyer consolidation reshape vendor relationships.
Variable-frequency drive technology is decentralizing energy management across spiral freezer operations. High-volume poultry processors in the US Southeast are retrofitting existing mechanical systems with VFD-controlled evaporator fans, cutting peak demand charges. This distributed control architecture is compressing the advantage of centralized plant refrigeration management.
EPA SNAP program restrictions on HFC refrigerants are forcing engineering redesigns across US manufacturing bases. Equipment vendors must validate alternative chemistries under Significant New Alternatives Policy timelines while maintaining performance guarantees. The protein processing segment is responding by accelerating ammonia adoption despite higher upfront capital requirements.
Buyer concentration among frozen food manufacturers is consolidating vendor relationships around fewer equipment suppliers with integrated service capabilities. Large-scale ready-to-eat processors are unbundling maintenance contracts from initial capital purchases, selecting vendors based on regional spare-parts inventory depth. This pattern is most visible in Northern Europe where GEA Group and JBT compete on aftermarket responsiveness.
Spiral Freezer Market Segmentation
Spiral freezer procurement decisions hinge on throughput requirements, refrigerant compliance obligations, and integration complexity with existing processing lines. Buyers prioritize total cost of ownership over upfront capital expenditure, particularly in regulated markets facing refrigerant transition deadlines.
Product Type:
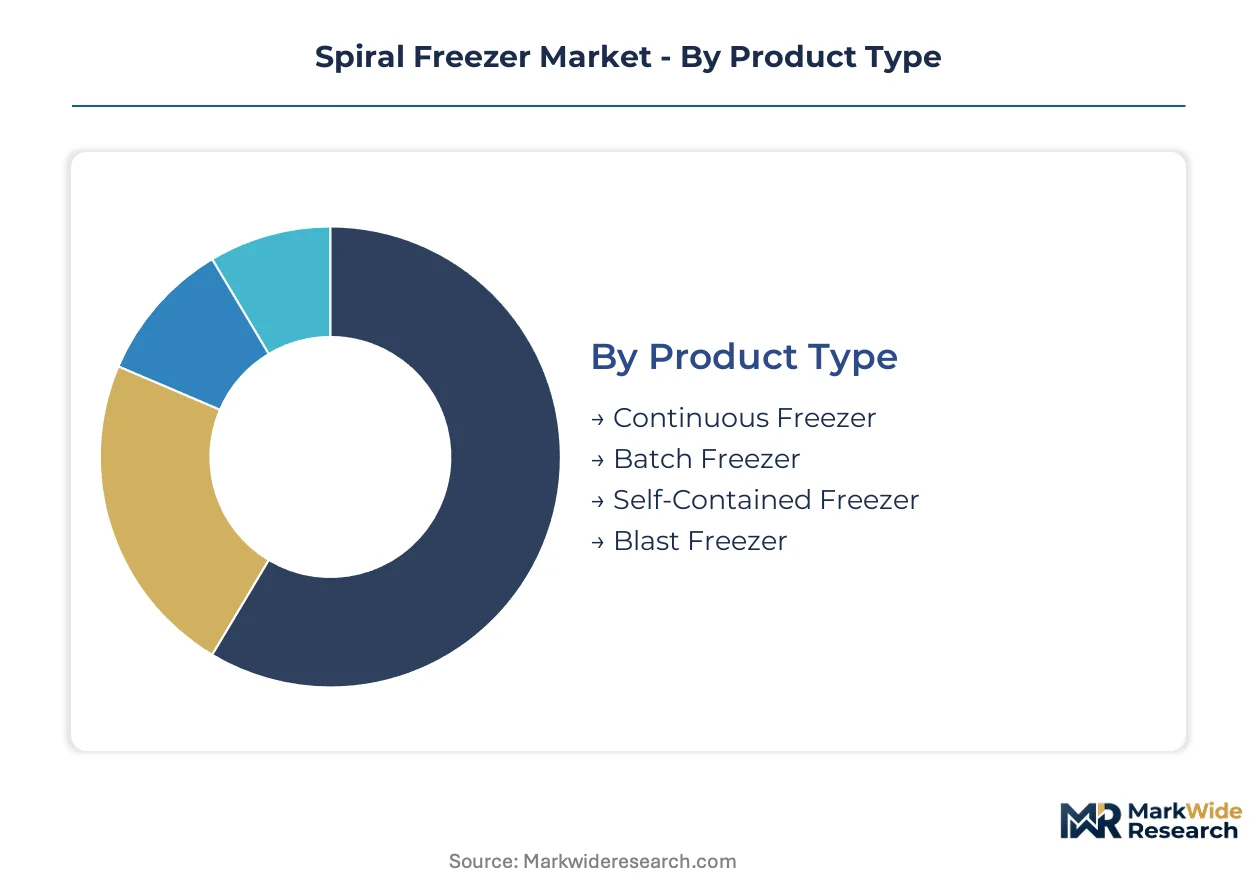
Volume throughput and line integration complexity drive selection between continuous and batch architectures.
- Continuous Freezer:Belt-driven helical configurations achieve sustained throughputs exceeding five metric tons per hour in high-volume poultry and seafood plants. Demand concentrates in Vietnam's Mekong Delta processing zones where export capacity expansion requires uninterrupted freezing cycles under tropical humidity loads.
- Batch Freezer:Chamber-based designs accommodate variable product mixes and smaller production runs with flexible loading configurations. European protein processors facing EU F-Gas Regulation retrofit deadlines favor batch systems for legacy line integration where continuous belt installation proves structurally impractical.
- Self-Contained Freezer:Packaged units with integrated refrigeration circuits reduce field commissioning complexity for mid-scale processors.
- Blast Freezer:High-velocity air circulation systems serve applications requiring rapid temperature pulldown for dense protein blocks.
Continuous Freezer leads on scale; Self-Contained Freezer leads on momentum.
Technology:
Refrigerant chemistry selection now dominates engineering specifications as environmental protocols compress viable alternatives.
- Air Blast:Mechanical refrigeration systems using ammonia or HFC alternatives circulate chilled air across product surfaces in controlled velocity profiles. Northern European installations under EU F-Gas Regulation phasedown timelines are accelerating ammonia-based air blast retrofits despite higher capital requirements.
- Liquid Nitrogen:Cryogenic injection systems achieve rapid surface freezing that preserves cellular structure in premium seafood applications. Japanese engineering expertise in liquid nitrogen system design creates procurement bottlenecks for Southeast Asian processors seeking hybrid cryogenic-mechanical configurations.
- Carbon Dioxide:CO₂-based systems face escalating operating cost pressures as environmental protocols tighten industrial-grade supply chains.
- Cryogenic:Broad category encompassing liquid nitrogen and carbon dioxide approaches for ultra-rapid freezing applications.
Air Blast dominates installed base; Liquid Nitrogen climbs the fastest on premium segment demand.
End User:
Validation requirements and hygiene protocols create divergent specification standards across buyer categories.
- Food Processing:Frozen seafood and poultry processors specify stainless steel construction with HACCP-compliant conveyor designs. Indian frozen food manufacturers responding to FSSAI mandatory freezing protocols are driving compact spiral unit demand in secondary cities beyond traditional cold-chain hubs.
- Pharmaceuticals:Active pharmaceutical ingredient processing requires EMA-validated cold-chain documentation and temperature mapping protocols. Drug substance manufacturers are extending spiral freezer applications into chemical synthesis cooling where precise thermal control preserves molecular stability.
- Chemical Industry:Specialty chemical producers employ modified designs for intermediate cooling in batch synthesis operations.
- Retail:Central kitchen and prepared food operations specify smaller-footprint units for in-house freezing capacity.
Food Processing anchors volume; Pharmaceuticals shows steepest expansion trajectory.
Capacity:
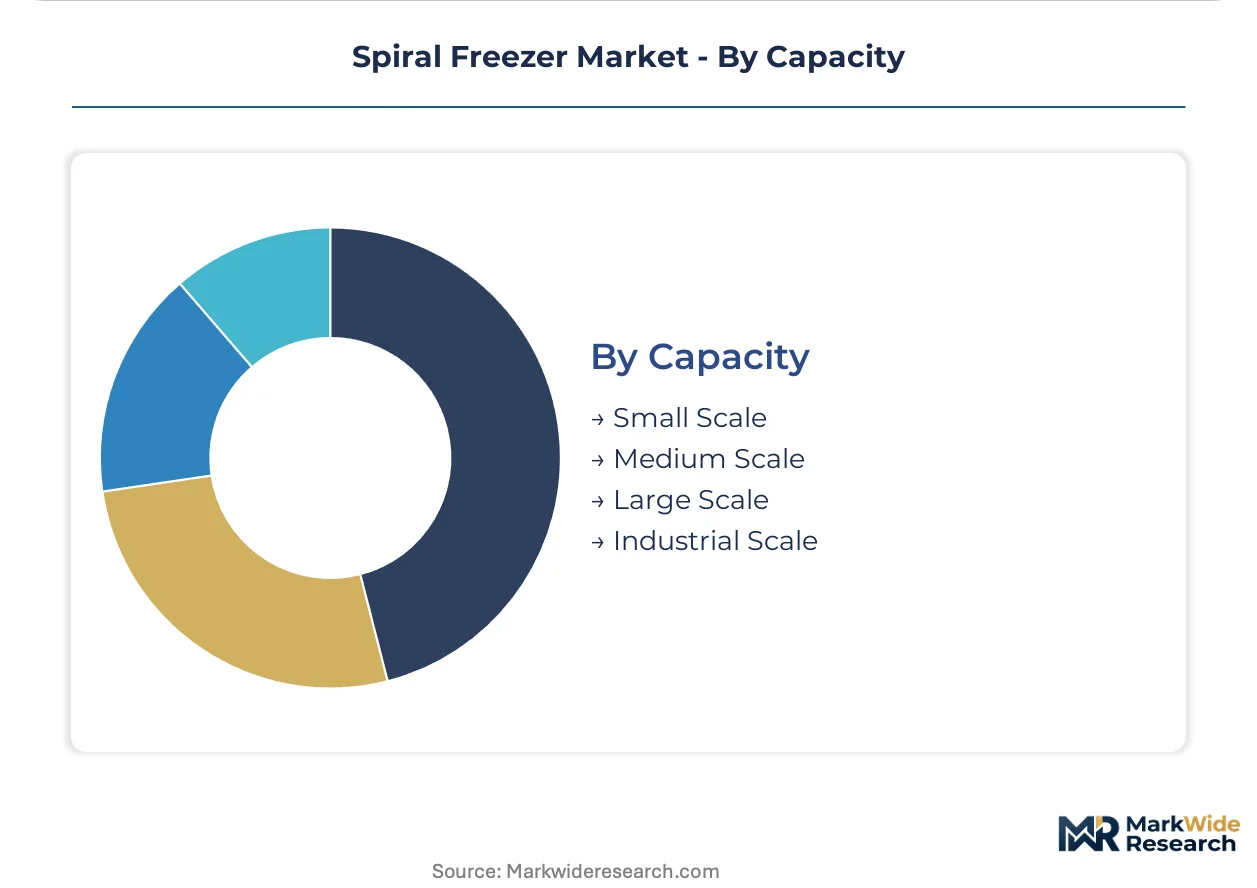
Scale selection correlates directly with automation level and refrigerant charge volume regulatory thresholds.
- Small Scale:Compact footprints under 50 square meters serve artisanal processors and retail central kitchens with limited floor space. Urban food manufacturers in densely populated processing corridors favor small-scale ammonia systems with reduced charge volumes that satisfy OSHA Process Safety Management thresholds.
- Medium Scale:Intermediate configurations bridge artisanal production and industrial throughput requirements.
- Large Scale:High-capacity installations exceed 200 kilowatts of refrigeration duty for regional processing facilities.
- Industrial Scale:Integrated plant-wide systems serve export-oriented protein complexes with dedicated ammonia central refrigeration plants.
Industrial Scale commands capital allocation; Small Scale gains share fastest on urban density constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting capital toward jurisdictions with refrigerant compliance cost advantages. Southeast Asian processors exploit this gap while European retrofits accelerate under phasedown deadlines.
United States
Poultry processors across the Southeast are retrofitting aging mechanical systems with VFD-controlled evaporator fans to cut peak demand charges. EPA SNAP program restrictions on HFC refrigerants force engineering redesigns across manufacturing bases. Georgia and Alabama processing corridors concentrate ammonia system adoption despite OSHA Process Safety Management licensing delays.
Germany
Protein processors under EU F-Gas Regulation timelines accelerate ammonia-based air blast retrofits despite higher capital requirements. EMA cold-chain validation requirements extend equipment standards into pharmaceutical applications. Bavarian engineering clusters supply cryogenic system design expertise that creates procurement bottlenecks for distant markets.
Vietnam
Frozen seafood processors in the Mekong Delta expand export capacity with continuous freezers engineered for tropical humidity loads. FSSAI-equivalent national standards tighten food safety protocols. Ho Chi Minh City processing zones concentrate demand for compact spiral units with stainless steel HACCP-compliant conveyor designs.
India
FSSAI enforcement of mandatory freezing protocols for frozen food distribution opens demand for compact spiral units in secondary cities. BIS certification requirements shape equipment specifications for domestic manufacturers. Gujarat and Maharashtra cold-chain buildouts favor small-scale ammonia systems with reduced charge volumes satisfying urban density constraints.
Japan
Engineering expertise in liquid nitrogen system design creates procurement bottlenecks for Southeast Asian processors seeking hybrid configurations. METI industrial standards govern cryogenic equipment safety certifications. Osaka and Nagoya industrial corridors anchor technology leadership in hygienic conveyor design for ready-to-eat applications.
Spiral Freezer Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular and self-contained configurations for mid-scale processors. The vendor base concentrates around integrated refrigeration specialists with aftermarket service depth. Three archetypes dominate: European systems integrators with ammonia expertise, Asian fabricators optimized for tropical conditions, and cryogenic gas suppliers leveraging industrial gas infrastructure. Competitive moves center on unbundling maintenance contracts from capital purchases and accelerating ammonia technology maturation for reduced-charge packaged systems.
Among European-based systems integrators, GEA Group and John Bean Technologies Corporation exemplify the integrated service archetype, anchoring vendor selection criteria around regional spare-parts inventory depth. Mayekawa Mfg. Co., Ltd. occupies a position representing Asian engineering optimization for ammonia deployment in densely populated processing corridors.
| Leading Market Players |
|---|
| GEA Group |
| John Bean Technologies Corporation |
| Linde PLC |
| Air Liquide |
| Mayekawa Mfg. Co., Ltd. |
| FPS Food Process Solutions |
| VDL Systems BV |
| SCANICO A/S |
| RMF Works |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance deadlines are compressing procurement timelines for Northern European protein processors, forcing supply chains to prioritize ammonia-based system components and accelerating price premiums for low-GWP engineering expertise.
Pricing Analysis
Input-cost pass-through from refrigerant chemistry transitions dominates pricing structures. Equipment vendors operate on project-based contract pricing with premiums attached to EMA-validated pharmaceutical configurations and ammonia safety certifications. Price differentiation separates cryogenic liquid nitrogen systems from mechanical air blast alternatives, with Japanese engineering commanding scarcity premiums. Cost compression in carbon dioxide-based installations is intensifying because industrial-grade CO₂ supply chains face environmental protocol constraints. Mid-scale processors in India's secondary cities exhibit highest price sensitivity, while export-oriented seafood complexes in Vietnam's Mekong Delta prioritize performance guarantees over capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with Japanese engineering houses for liquid nitrogen system design and German fabricators for precision refrigeration components. Manufacturing concentration centers on Germany, Japan, and Denmark for specialized cryogenic equipment, with stainless steel conveyor fabrication drawing from Italian and Chinese metalworking clusters. Raw material dependencies include specialized aluminum alloys for evaporator coils, food-grade stainless steel for HACCP-compliant contact surfaces, and industrial-grade ammonia with purity specifications. Tariff exposure runs through EU-China steel trade dynamics affecting conveyor fabrication costs. Distribution runs through authorized systems integrators with regional spare-parts inventory obligations rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spiral Freezer Market compounds steadily as frozen food export infrastructure in tropical zones requires continuous capacity additions under tightening safety protocols.
For Market Incumbents: Anticipate refrigerant transition bottlenecks by securing ammonia charge-reduction engineering partnerships before EU F-Gas Regulation retrofit peaks strain German and Japanese technical talent pools. Deepen backward integration into stainless steel conveyor fabrication to insulate margins from Italian metalworking cost volatility. Prioritize aftermarket service contract unbundling to lock in multi-decade revenue streams from installed base expansion in Vietnam and India. For New Entrants and Emerging Players: Enter via compact self-contained freezer configurations for India's secondary city cold-chain buildout, where FSSAI enforcement creates demand without incumbent service infrastructure. Target pharmaceutical validation capabilities as a white-space segment where EMA cold-chain documentation requirements exceed standard food-processing specifications. Pursue regional spare-parts inventory partnerships with established ammonia systems integrators rather than greenfield manufacturing investments. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale ammonia packaging specialists possessing OSHA Process Safety Management certification track records and reduced-charge system deployments in densely populated processing corridors. Long-term viability hinges on refrigerant chemistry transition execution across the next decade. Acquisition focus should center on engineering teams with hybrid cryogenic-mechanical system integration experience. Monitor EPA SNAP program enforcement intensity as the signal indicating North American replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia Charge Reduction Engineering | Packaged systems with sub-threshold refrigerant volumes unlock OSHA-compliant deployment in urban processing corridors. |
| Pharmaceutical Validation Investment | EMA cold-chain documentation capabilities extend addressable market into drug substance manufacturing applications. |
| Regional Spare-Parts Inventory Buildout | Aftermarket responsiveness anchors vendor selection criteria for large-scale ready-to-eat processors in Northern Europe. |
| Hybrid Cryogenic-Mechanical Development | Liquid nitrogen surface freezing combined with mechanical refrigeration optimizes cell-structure preservation for premium seafood. |
| Tropical Humidity Engineering Adaptation | Stainless steel HACCP-compliant designs engineered for Mekong Delta conditions capture Southeast Asian export capacity expansion. |
Methodological Framework
Multiple input streams — primary interviews with plant engineers and aftermarket service directors, secondary validation through customs trade data and refrigeration industry association filings, and equipment specification database analysis — were reconciled through bottom-up installation tracking and top-down market sizing triangulation. Stakeholder consultations included maintenance directors at poultry processing complexes, procurement leads at frozen seafood exporters, OEM sales engineers specializing in ammonia systems, and regulatory compliance officers navigating EPA SNAP and EU F-Gas timelines.
Data-stream reconciliation across product type, technology chemistry, end-use validation requirements, and capacity scale dimensions anchored the analytical framework. CAGRs were derived from trajectory fitting to historical installation patterns and regulatory deadline impacts. Forecast inputs incorporated refrigerant phasedown schedules, FSSAI enforcement intensity in Indian secondary cities, and Southeast Asian export capacity expansion pipelines.
Inputs from equipment vendor order backlogs and regulatory filing databases were available through the study window; gaps in proprietary aftermarket service revenue data introduce uncertainty bands around vendor market position estimates. Forecasts reflect documented assumptions regarding refrigerant transition timelines and regional cold-chain infrastructure investment rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
US Frozen Dessert Market
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
Cambodia Frozen Food Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
Asia-Pacific Frozen Pizza Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
North America Frozen Food Market
Processed and Frozen Foods
Cold Cuts Market
Processed and Frozen Foods
South America Frozen Food Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Asia-Pacific Frozen Food Market
Processed and Frozen Foods
Dry Mix Base for Frozen Desserts Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
Individual Quick Frozen Cheese Market
Processed and Frozen Foods
Frozen Snacks Market
Processed and Frozen Foods
Europe Frozen Pizza Market