
 Dishwashing Detergent Market | 2026-2036
Dishwashing Detergent Market Size, Share, and Industry Trends Forecast 2026-2036
Dishwashing Detergent Market Intelligence
Market Dynamics and Strategic Positioning
Southeast Asia is fragmenting as Vietnam, Indonesia, and Thailand add surfactant compounding capacity to serve domestic and export demand. Procter & Gamble leverages its North American manufacturing scale to control retail shelf space across mass-market channels. Henkel anchors its position in European private-label and branded segments through concentrated gel formulations. Unilever competes in emerging markets with sachet and refill-pack economics tailored to lower-income households.
Product Architecture and Segment Structure
Dishwashing detergent comprises synthetic or bio-based surfactant blends, builders, enzymes, and rinse aids formulated to reduce surface tension and suspend food soils in aqueous solutions. Liquid formulations dominate household penetration due to dosing convenience and cold-water solubility, though tablets sustain premium pricing in European dishwasher markets where machine ownership is mature. The commercial end-user segment generates disproportionate margin pools through institutional bulk contracts, while eco-friendly feature claims are displacing conventional antibacterial positioning in Nordic and German retail channels.
Regulatory Environment and Strategic Imperatives
EPA Safer Choice, EU REACH, and ECHA detergent-specific restrictions on phosphates and microplastics are reshaping formulation chemistry and raw-material sourcing across all major production geographies. Compliance costs are rising fastest for powder formats with legacy builder systems, advantaging liquid and tablet producers with reformulation flexibility. Stakeholders must monitor pending restrictions on per- and polyfluoroalkyl substances in cleaning products, as these would force additional R&D redirection across the supplier base.
Market Dynamics
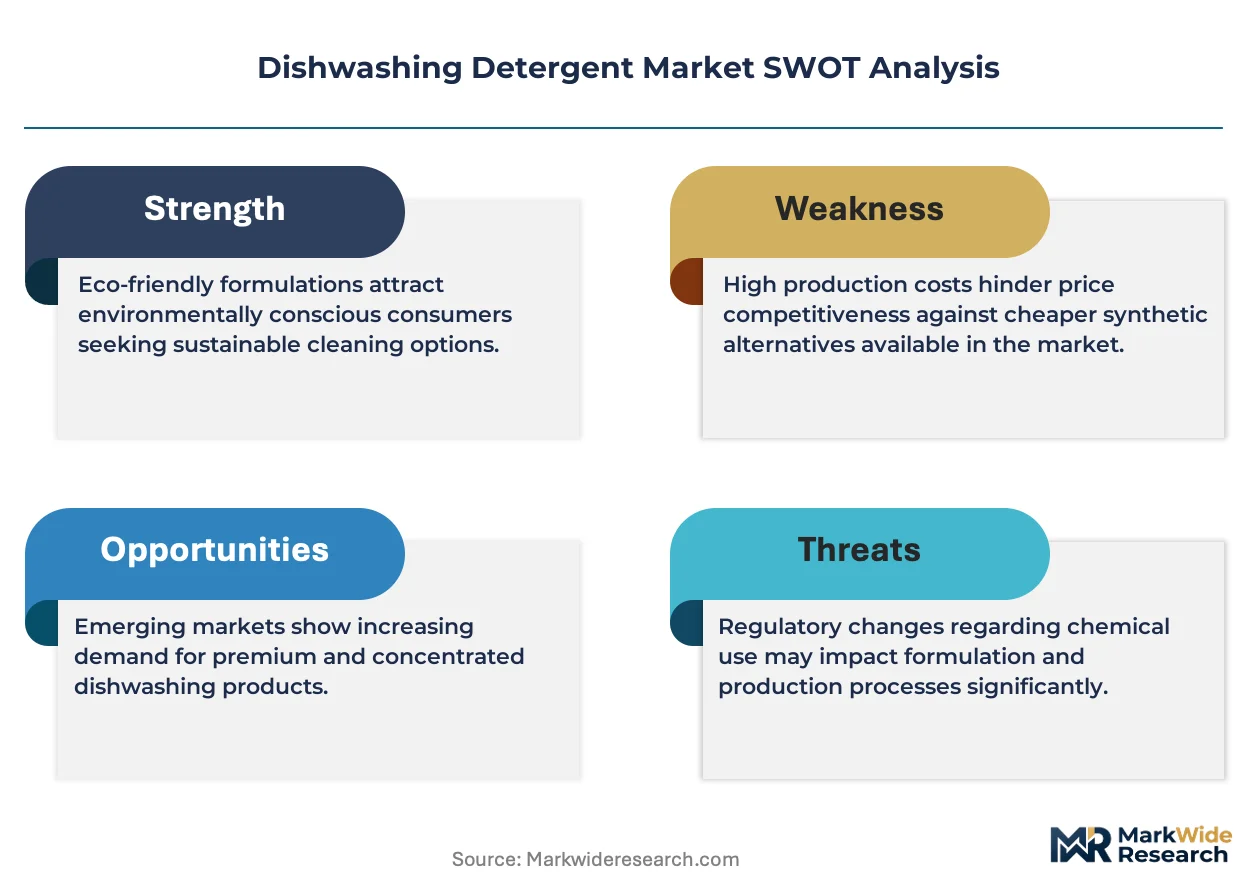
EPA Safer Choice and ECHA phosphate restrictions are forcing surfactant reformulation across all major production geographies, compressing legacy powder margins while advantaging liquid and tablet producers with reformulation flexibility.
Growth Catalysts
- Machine dishwasher penetration:Rising household appliance ownership in China and Brazil expands automatic dishwashing detergent demand beyond hand-wash liquids.
- EPA Safer Choice certification:Retail buyers in the United States now mandate eco-label compliance for shelf placement, accelerating biodegradable surfactant adoption.
- Commercial kitchen expansion:Institutional-grade procurement from hospitality and foodservice sectors generates disproportionate margin pools through bulk supply contracts.
Market Restraints
- Palm oil and coconut oil volatility:Bio-based surfactant feedstock prices swing with agricultural commodity cycles, compressing margin predictability for natural-positioned brands.
- Linear alkylbenzene sulfonate supply concentration:Three Asian petrochemical clusters control over 70% of global synthetic surfactant precursor output, creating geographic chokepoint risk.
- Cold-water solubility limits:Enzyme-stabilized formulations face performance degradation below 15°C, restricting market penetration in northern climates without heating infrastructure.
Strategic Opportunities
- Sachet economics in India:Single-use refill packaging unlocks lower-income household penetration where bottle deposits exceed weekly detergent spend.
- EU Green Deal chemistry incentives:Biodegradable builder system R&D qualifies for circular economy innovation funding, offsetting reformulation capex.
- Direct-to-hotelier digital channels:Bypassing institutional distributors lets manufacturers capture margin from mid-size hospitality chains seeking customized bulk formulations.
Industry Challenges
- Enzyme stability engineering:Protease and amylase preservation in high-water-activity gels demands specialized formulation chemists, creating talent scarcity in emerging market R&D centers.
- REACH pre-registration timelines:Novel bio-surfactant approval cycles stretch 18-24 months, delaying product launch windows and locking capital in regulatory limbo.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dishwashing Detergent Market |
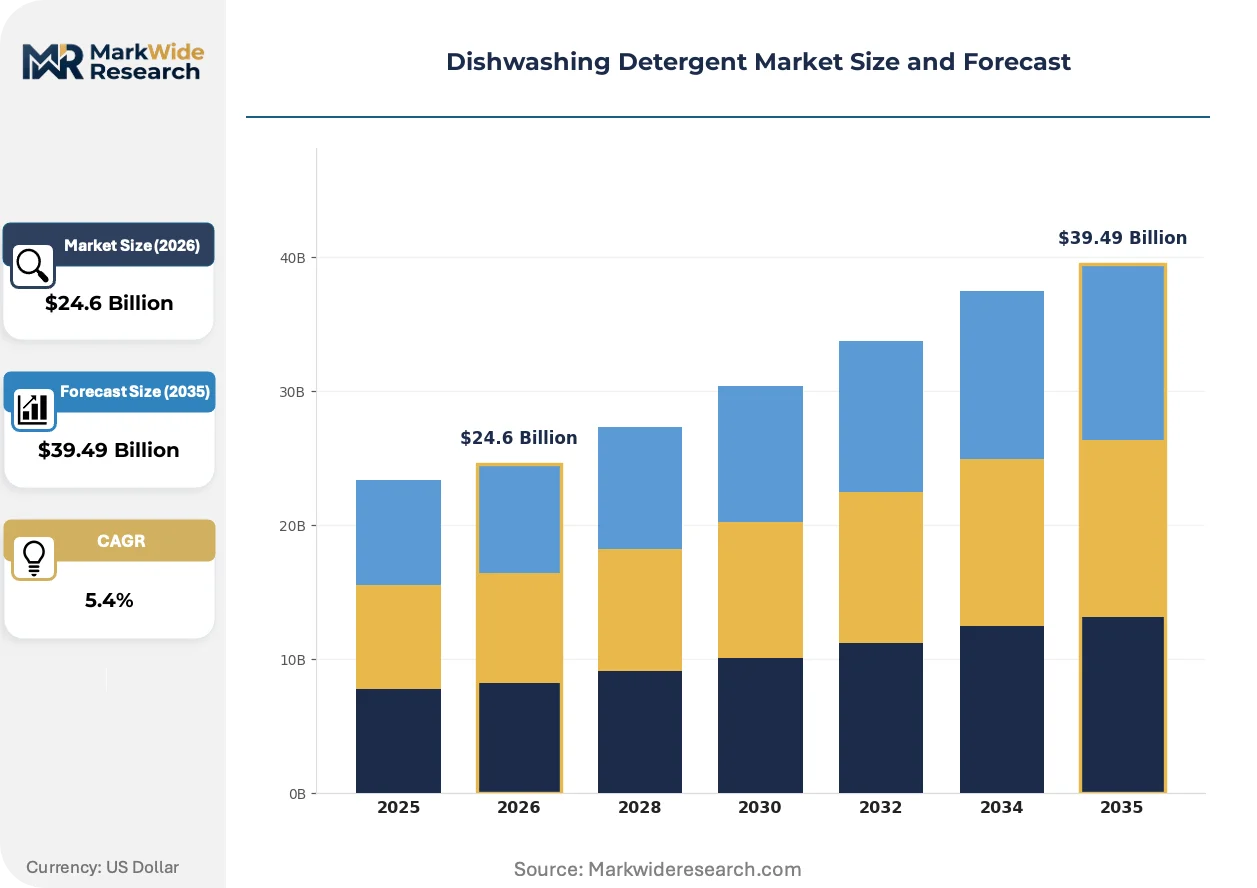
| Market Size in 2026 | $24.6 Billion |
| Market Size in 2035 | $39.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Liquid, Powder, Tablet, Gel Packaging Type: Bottle, Pouch, Refill Pack, Box End User: Household, Commercial, Institutional, Industrial Feature: Eco-friendly, Antibacterial, Grease Cutting, Scented |
| Companies Covered | Henkel, The Clorox Company, Procter & Gamble, Church & Dwight, Kao Corporation, Unilever, Colgate-Palmolive, SC Johnson, Reckitt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dishwashing Detergent Market Strategic Shifts & Innovations
Formulation chemistry is converging with packaging engineering and digital dosing systems to redefine how detergents perform, prove efficacy, and reach end-users across income tiers.
Enzyme-boosted gel concentrates are hybridizing performance claims across hand-wash and machine-wash applications. Mid-market European households now adopt dual-purpose formulas that auto-dose via connected dishwasher interfaces. This convergence is hybridizing what were historically separate R&D tracks and retail shelf positions.
ECHA restrictions on microplastics in leave-on products are extending to rinse-off cleaning categories, with draft guidance expected to capture encapsulated fragrance technologies. Formulators are pivoting to starch-based encapsulation or free-oil perfumery. Nordic and German private-label suppliers face the steepest compliance curves given their early-adopter positioning on sustainability claims.
Subscription-based refill systems are displacing supermarket replenishment among urban dual-income households. Concentrate pouches shipped by mail reduce last-mile plastic intensity and lock in brand loyalty through auto-renewal. This channel shift concentrates most visibly in United Kingdom metropolitan zones where grocery delivery penetration already exceeds 40%.
Dishwashing Detergent Market Segmentation
Dishwashing detergent formulation and delivery systems fragment across usage intensity, regulatory compliance thresholds, and income-tier accessibility. Each segmentation axis reveals distinct margin structures and competitive entry points for manufacturers.
Form:
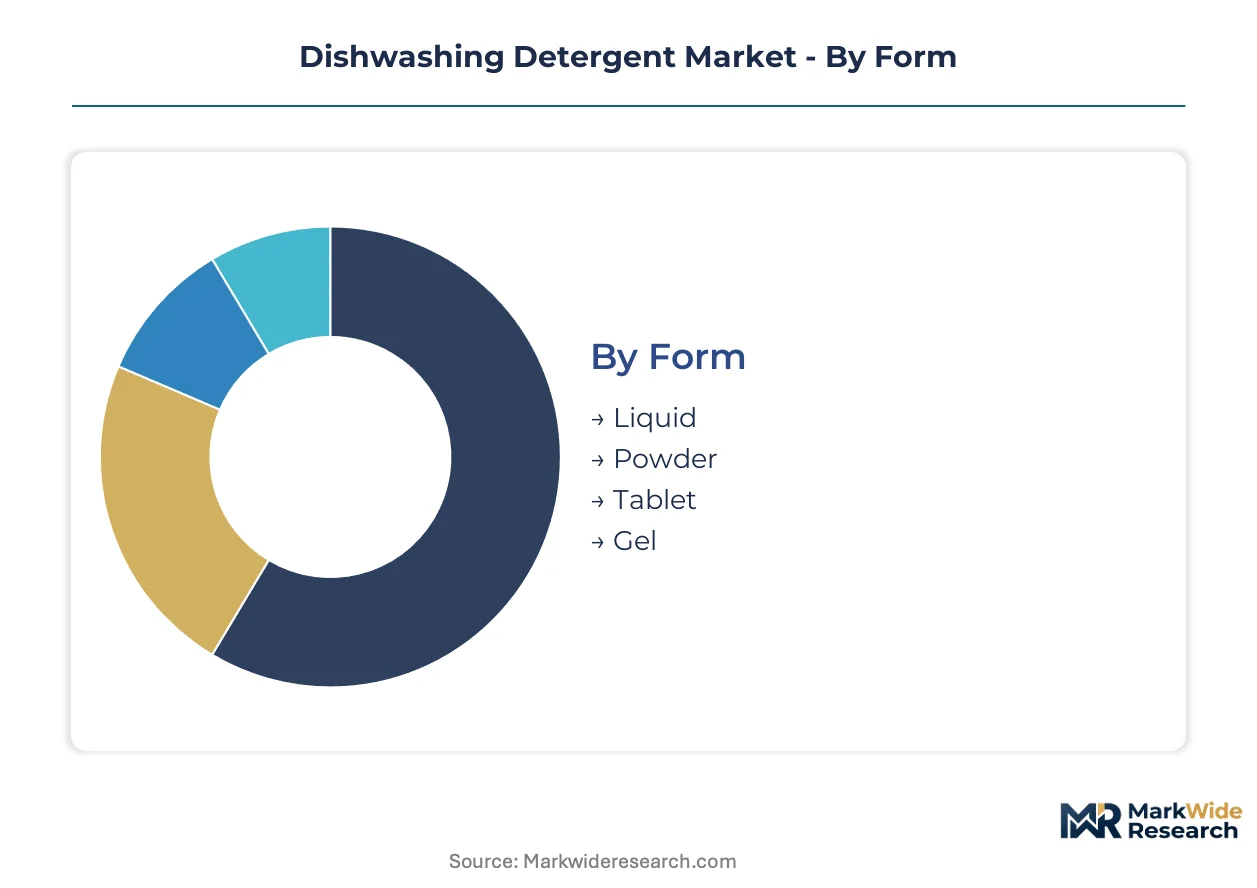
Liquid concentrates, solid tablets, viscous gels, and legacy powders serve machine versus hand-wash use-cases with divergent solubility and dosing precision requirements.
- Liquid:Cold-water soluble surfactant blends dominate household penetration where tap temperature varies seasonally. Demand concentrates in Brazil and India as modern retail expands beyond tier-one cities.
- Tablet:Pre-dosed enzyme and builder combinations lock in premium pricing for European dishwasher markets where machine ownership saturates urban households. German and Nordic retail channels favor tablet SKUs with Ecolabel Nordic Swan certification.
- Powder:Legacy builder systems face phosphate restriction compliance costs under EU REACH and EPA frameworks, compressing margins in price-sensitive emerging markets.
- Gel:Viscous concentrates enable precise squeeze dosing in commercial kitchens where portion control reduces waste.
The dominant share belongs to Liquid, while Tablet is closing the gap fastest in Western European premium channels.
Packaging Type:
Unit economics and last-mile logistics shape competitive positioning across rigid containers, flexible films, and bulk refill systems.
- Bottle:HDPE and PET containers retain shelf visibility in hypermarket formats where brand recognition drives impulse purchase.
- Pouch:Flexible laminated films slash material cost and shipping cube, enabling sachet economics for Indian households where weekly detergent spend falls below bottle deposit thresholds.
- Refill Pack:Concentrate pouches shipped via subscription channels reduce plastic intensity per wash cycle; United Kingdom metropolitan adoption exceeds 15% of liquid category volume.
- Box:Corrugated containment sustains powder formats in institutional procurement where bulk stacking and warehouse handling prioritize durability over shelf appeal.
Pouch formats are expanding most quickly in Southeast Asian modern trade, though Bottle retains structural share in North American mass retail.
End User:
Volume scale, price sensitivity, and specification rigor diverge sharply between domestic consumption and professional foodservice operations.
- Household:Individual purchase decisions prioritize fragrance, skin mildness, and cold-water performance; sachet and refill-pack formats unlock lower-income penetration.
- Commercial:Restaurants and catering operations generate disproportionate margin pools through institutional bulk contracts with customized grease-cutting specifications.
- Institutional:Hospitals, schools, and government facilities mandate EPA Safer Choice or equivalent eco-label compliance for procurement eligibility.
- Industrial:Food processing plants require heavy-duty alkaline formulations with documented kill-log certificates for sanitation audits.
Household commands absolute volume, yet Commercial delivers superior per-unit profitability through formulation customization.
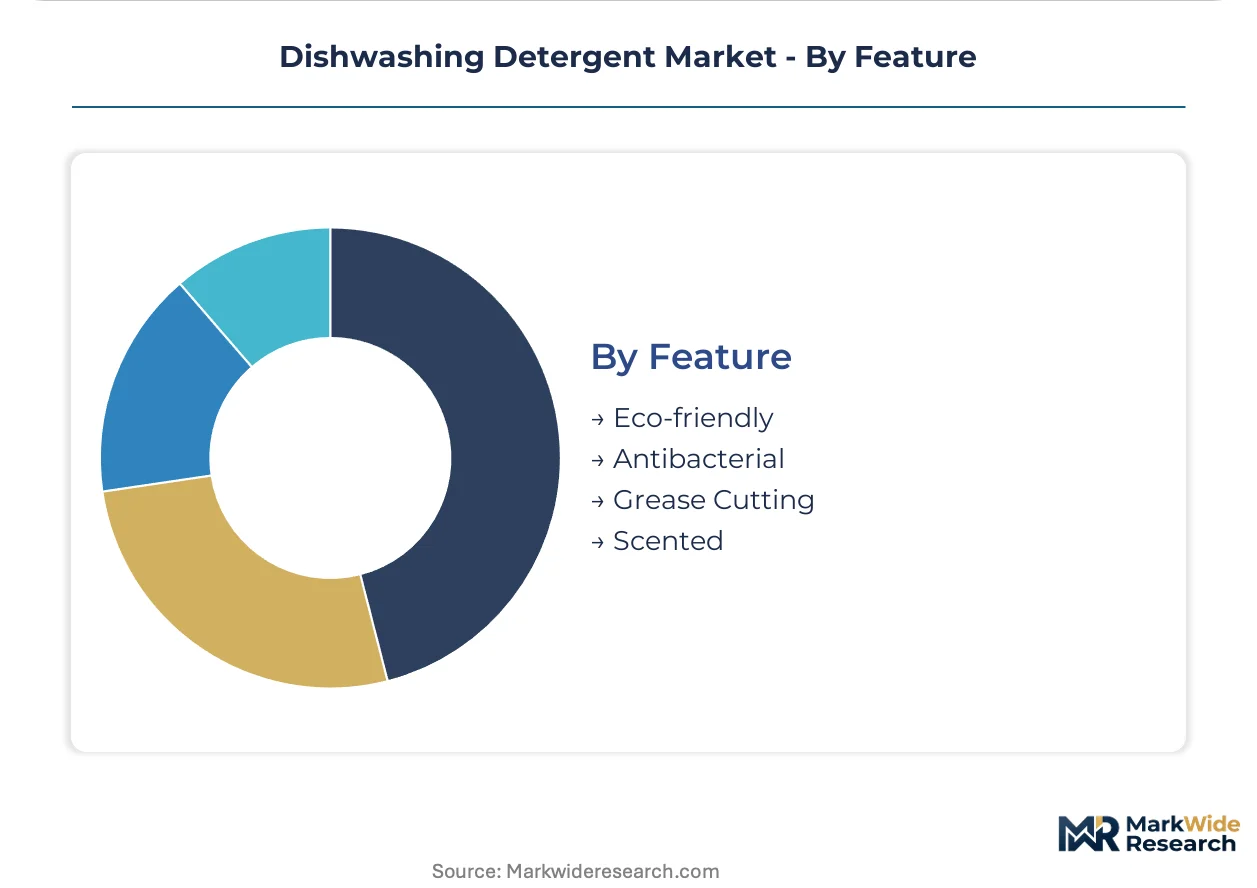
Feature:
Positioning claims increasingly pivot from functional efficacy to environmental and health credentials as regulatory labeling frameworks mature.
- Eco-friendly:Biodegradable surfactant and builder systems qualify for EPA Safer Choice, EU Ecolabel, and Nordic Swan shelf placement; reformulation capex is offset by circular economy innovation funding in EU Green Deal jurisdictions.
- Antibacterial:Triclosan and quaternary ammonium claims face regulatory contraction; formulators pivot to enzyme-based soil removal without biocidal registration.
- Grease Cutting:Protease and lipase enzyme blends target protein and fat soils in commercial kitchen applications with high-temperature wash cycles.
- Scented:Fragrance encapsulation technologies face ECHA microplastic draft restrictions; suppliers trial starch-based alternatives or free-oil perfumery.
Eco-friendly claims are displacing Antibacterial positioning fastest in German and Nordic retail, though Grease Cutting retains structural importance in commercial channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific surfactant trade flows, handling bulk imports of palm oil and coconut oil derivatives that feed compounding plants across the Yangtze Delta.
United States
Machine dishwasher penetration in suburban households drives automatic detergent demand beyond hand-wash liquids. EPA Safer Choice certification now gates retail shelf placement for mass-market brands. Gulf Coast petrochemical clusters near Houston supply linear alkylbenzene sulfonate precursors to domestic formulators.
Germany
European dishwasher ownership saturation sustains premium tablet demand in urban households. EU REACH phosphate restrictions force reformulation of legacy builder systems. The Rhine-Ruhr industrial corridor hosts concentrated gel production for private-label and branded segments.
China
Urban household penetration and modern retail expansion concentrate demand in tier-one and tier-two cities. The country's national environmental regulator enforces dual carbon goals that push surfactant plants toward bio-based feedstocks. Zhejiang and Jiangsu provinces add surfactant compounding capacity to serve domestic and export markets.
India
Sachet economics unlock lower-income household penetration where bottle deposits exceed weekly detergent spend. The Bureau of Indian Standards governs product safety labeling for cleaning chemicals. Maharashtra and Gujarat house flexible packaging converters that supply laminated pouch formats to modern trade channels.
Brazil
Seasonal cold-water solubility requirements shape liquid formulation specifications for Southeast Asian climates. The country's national environmental agency oversees biodegradable surfactant registration for eco-labeled products. São Paulo state anchors production of enzyme-stabilized concentrates for Latin American distribution.
Dishwashing Detergent Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in surfactant and enzyme supply. The vendor base organizes around three tiers: multinational consumer goods conglomerates with retail shelf dominance, regional private-label suppliers with formulation flexibility, and specialty chemical houses with captive surfactant technology. Strategic moves concentrate on M&A to secure bio-surfactant pipelines and capacity expansion in Southeast Asian compounding hubs.
Among diversified consumer goods conglomerates, Henkel and Procter & Gamble exemplify platform-scale positioning across branded and private-label segments. Unilever occupies a distinct archetype serving emerging markets through sachet and refill-pack economics. These three anchors represent divergent geographic and format strategies within the consolidated top tier.
| Leading Market Players |
|---|
| Henkel |
| The Clorox Company |
| Procter & Gamble |
| Church & Dwight |
| Kao Corporation |
| Unilever |
| Colgate-Palmolive |
| SC Johnson |
| Reckitt |
| Others |
Cost & Logistics Intelligence
Overcapacity in Southeast Asian surfactant compounding is forcing suppliers to absorb feedstock volatility rather than pass through costs, compressing margins for natural-positioned brands while concentrating pricing power among buyers with volume scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Ecolabel-certified tablets from mass-market liquids and sachet-format hand-wash powders. Price differentiation hinges on certification grade and volume scale, with institutional bulk contracts commanding steepest discounts. Pricing pressure stems from palm oil and coconut oil commodity swings, which erode margin predictability for bio-surfactant formulators. Commercial kitchens exhibit lowest price sensitivity due to grease-cutting performance requirements, while Indian household sachet buyers face highest elasticity.
Supply Chain Analysis
Palm oil and coconut oil derivatives from Malaysia and Indonesia feed surfactant production across China, India, and Brazil. The supply chain draws from linear alkylbenzene sulfonate precursors concentrated in Asian petrochemical clusters, with enzyme stabilization chemistry sourced from European and Japanese specialty houses. Single-source vulnerability runs through the three dominant LAB sulfonate production sites. Distribution runs through institutional distributors for commercial accounts and modern retail channels for household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is widening as EPA Safer Choice and ECHA phosphate restrictions splinter legacy powder positions, creating niches for reformulation-flexible entrants across certification tiers and regional markets.
For Market Incumbents: Insulate tablet and gel positions through captive bio-surfactant supply agreements in Southeast Asia, while accelerating REACH pre-registration for novel builder systems to lock out followers. Vertical integration into flexible packaging converters in Maharashtra and Gujarat secures sachet economics against emerging local competitors. For New Entrants and Emerging Players: Tier-three Chinese cities and Brazilian interior states offer underpenetrated modern retail expansion where bottle deposits still deter household penetration. Direct-to-hotelier digital channels bypass institutional distributors for mid-size hospitality chains seeking customized bulk formulations, with subscription refill systems capturing UK metropolitan loyalty. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based refill platforms with auto-renewal mechanics and concentrate pouch economics. Five-to-ten-year viability favors acquisition targets with EPA Safer Choice certification pipelines and Southeast Asian compounding capacity. The signal to watch is ECHA draft guidance on microplastic encapsulation, which would force fragrance technology pivots and strand legacy perfumery investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Surfactant Feedstocks | Captive palm oil and coconut oil sourcing insulates margin volatility from agricultural commodity cycles. |
| Subscription Refill Platform Launch | Auto-renewal mechanics lock UK metropolitan households into reduced plastic-intensity concentrate economics. |
| EPA Safer Choice Certification Investment | Retail shelf placement gating by US mass-market buyers mandates biodegradable surfactant compliance. |
| Sachet Format Expansion in India | Flexible laminated pouches unlock tier-two and tier-three city penetration where bottle deposits exceed weekly spend. |
| Direct-to-Hotelier Digital Channel Buildout | Bypassing institutional distributors captures margin from mid-size hospitality chains seeking grease-cutting customization. |
Research Approach
Initial hypotheses were tested against primary input from surfactant plant managers, procurement leads at hospitality and foodservice operators, retail category buyers, and technical R&D directors at formulation houses, and refined through secondary validation against customs trade data, EPA Safer Choice certified product registries, SEC 10-K filings, and Nielsen retail audit records. Bottom-up volume builds across form, packaging type, end user, and feature segments were triangulated against top-down macroeconomic anchors.
Demand-supply-balance modeling across the analysis window incorporated machine dishwasher penetration curves, urban household formation rates, and regulatory compliance cost trajectories. Segmentation dimensions included formulation chemistry, delivery system, end-use intensity, and certification tier. CAGRs were derived from slope analysis of segment-level volume trajectories, with enzyme stability engineering timelines and REACH pre-registration cycles as industry-specific forecast inputs.
Practitioners should monitor palm oil futures volatility, ECHA microplastic draft guidance advancement, and Southeast Asian capacity utilization rates for early signals of forecast revision. Cross-checking against customs import data for surfactant precursor flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Laundry Care Market
Cleaning Equipment
Household Wipes Market
Cleaning Equipment
Household Cleaners Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Cleaning Trolleys Market
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
US Cleaning Products Market
Cleaning Equipment
Cleaning Services Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Janitorial Cleaning Equipment and Supplies Market
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Cleaning and Hygiene Products Market
Cleaning Equipment
Carpet Extraction Cleaner Market
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
Floor Cleaning Device Market