
 Car Wash Detergents and Soaps Market | 2026-2036
Car Wash Detergents and Soaps Market Size, Share, and Industry Trends Forecast 2026-2036
Car Wash Detergents and Soaps Market Analysis
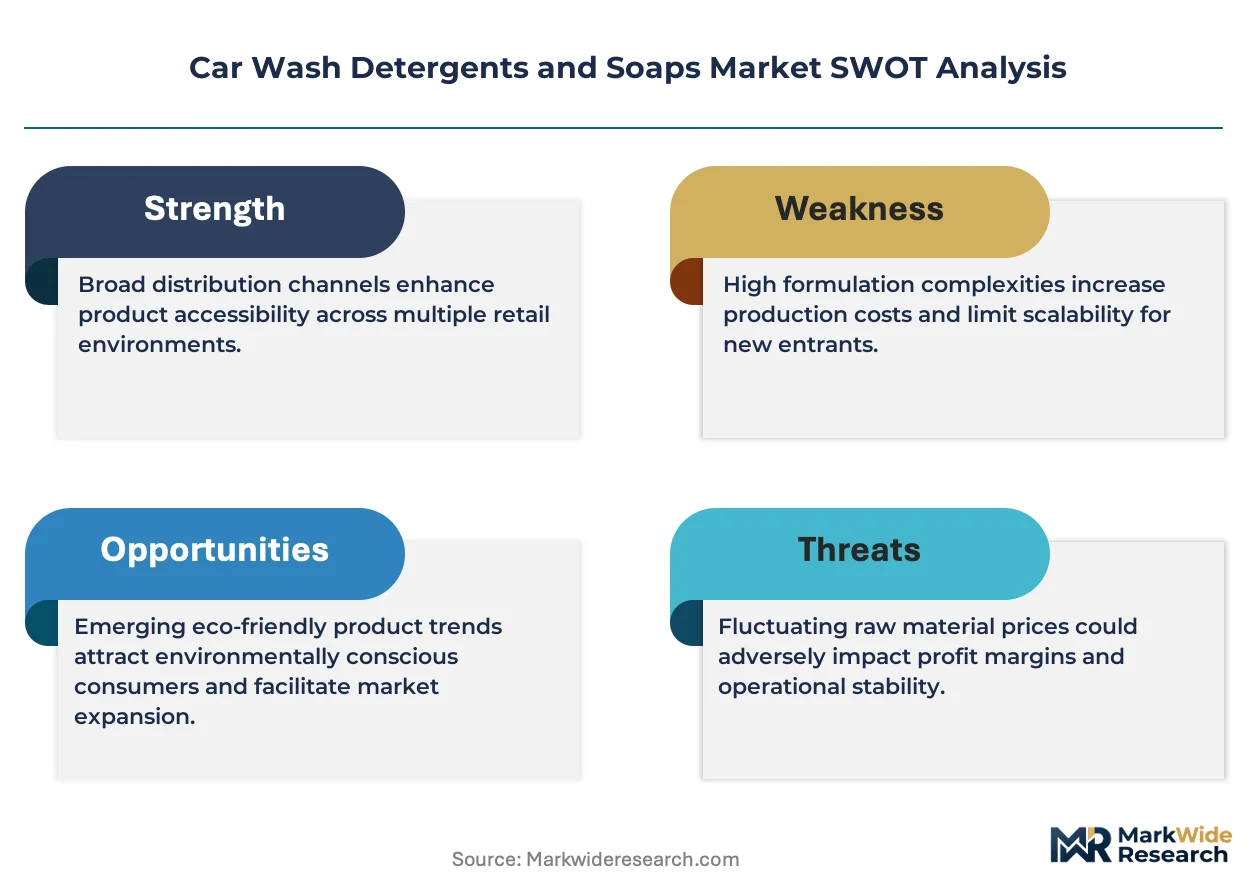
Premium pH-neutral formulations is collapsing the distinction between professional-grade and consumer-grade car wash chemistry. Ecolab Inc. leverages its institutional foodservice distribution network to cross-sell vehicle care programs into fleet accounts. Turtle Wax, Inc. anchors its position through retail shelf dominance that feeds brand recognition into professional channel migration. Chemical Guys, LLC specializes in enthusiast-grade concentrates that command per-ounce premiums through social media-driven education.
Car wash detergents and soaps comprise surfactant blends, chelating agents, and pH buffers engineered to lift road film, brake dust, and organic contaminants without degrading clear-coat or ceramic sealant layers; these formulations typically operate between pH 6.5 and 11.5 depending on soil type and substrate sensitivity. Liquid concentrates lead volume throughput in commercial tunnel operations where dilution ratios of 128:1 to 400:1 minimize freight cost and storage footprint. Foam pre-soaks represent the fastest-growing product type as touchless wash formats multiply, since thick cling time substitutes for mechanical friction in soil removal. Biodegradable formulations command margin premiums in regions with discharge permitting requirements, while alkaline degreasers retain stable demand from fleet services managing petroleum-based road film.
EPA NPDES permitting and state-level VOC regulations constrain formulation chemistry in the United States, while REACH registration requirements govern surfactant imports into Europe. OSHA hazard communication standards and California Proposition 65 labeling obligations add compliance layers that favor suppliers with dedicated regulatory affairs staff. Stakeholders must monitor how PFAS restrictions propagate from packaging into cleaning chemistry, as precursor scrutiny could force surfactant reformulation cycles ahead of explicit bans.
Market Dynamics
The EPA Clean Water Act's biodegradable formulation mandates are redirecting R&D budgets toward surfactant chemistry engineered for wastewater breakdown, compressing legacy petroleum-based formulation margins while tunnel wash operators expand chemical procurement to match automatic system rollouts.
Growth Catalysts
- Touchless wash proliferation:Tunnel operators in Texas, Florida, and California corridors are installing foam pre-soak arches that demand high-cling chemistry. This format substitution multiplies detergent volume per vehicle.
- California Proposition 65 labeling:Compliance obligations favor suppliers with dedicated regulatory affairs staff, concentrating procurement among formulation houses with pre-certified surfactant portfolios.
- Fleet electrification:Battery-electric commercial vehicles generate distinct road film chemistry—reduced petroleum residue but elevated copper brake dust—requiring reformulated chelating agents.
Market Restraints
- Petrochemical feedstock volatility:Ethylene oxide and fatty alcohol price swings compress surfactant blend margins, particularly for mid-tier concentrate suppliers without backward integration into oleochemical supply.
- PFAS precursor scrutiny:Fluorinated surfactant phase-outs in Maine and Washington state signal broader fluorine chemistry restrictions that could force reformulation cycles ahead of explicit federal bans.
- REACH registration bottlenecks:European surfactant import compliance adds 18-24 month lead times for non-EU formulation houses, constraining market access for US-based mid-cap producers.
Strategic Opportunities
- Ceramic sealant compatibility:pH-neutral formulations certified for graphene and SiO2 coatings command per-gallon premiums in express exterior channels as ceramic protection penetration deepens.
- On-site generation systems:Electrolyzed water and ozone injection hardware at wash sites reduces shipped chemical volume, opening recurring service contracts for chemistry-as-a-service models.
- Texas metropolitan corridor density:Dallas-Fort Worth and Houston express wash counts have multiplied, creating localized demand concentration for high-volume concentrate distribution partnerships.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in biodegradable surfactant synthesis and chelation engineering concentrates among legacy institutional suppliers, constraining mid-tier R&D velocity.
- Legacy equipment compatibility:Tunnel operators running 10-15 year-old dosing pumps face calibration drift with low-viscosity concentrates, requiring field service intervention that erodes chemical supplier margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Wash Detergents and Soaps Market |
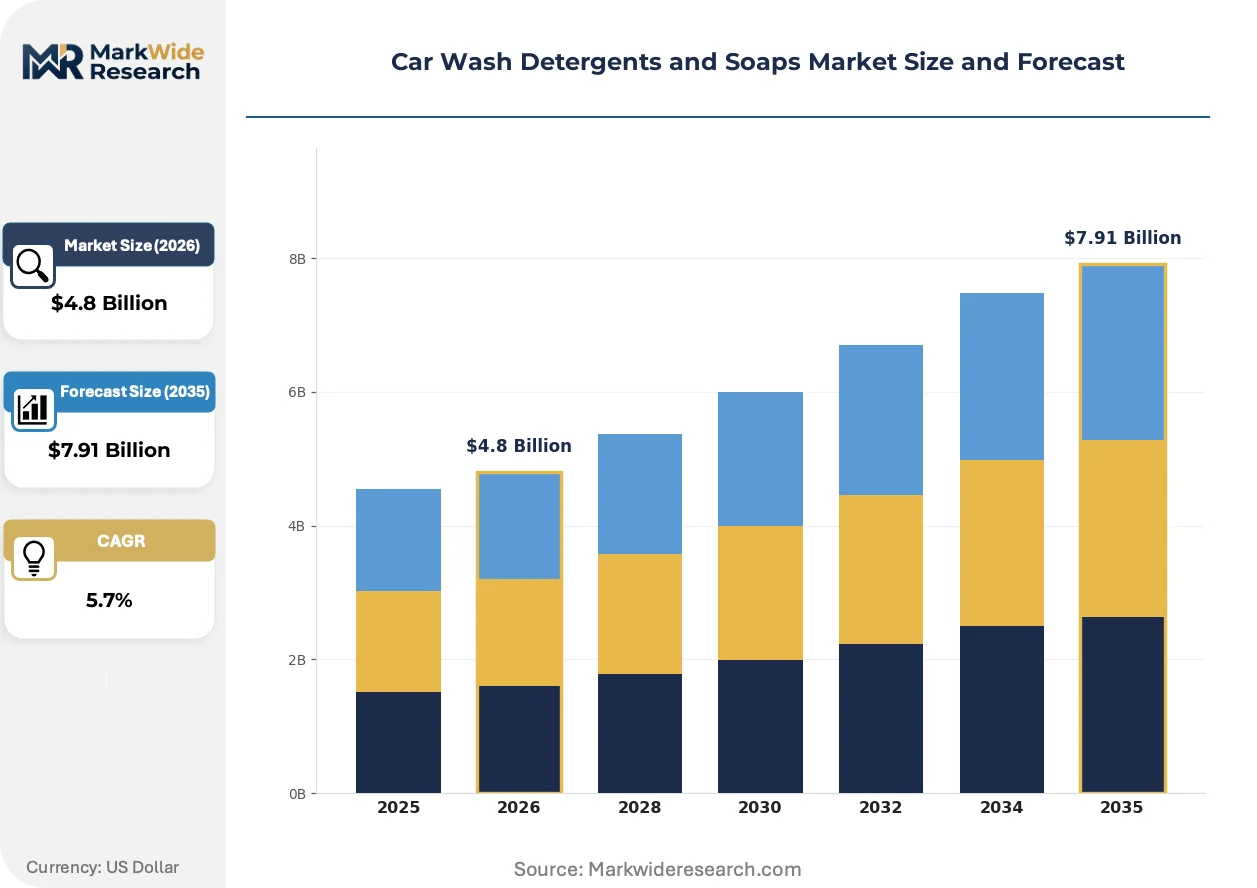
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Liquid, Paste, Concentrate End User: Commercial Wash Stations, Residential Users, Fleet Services, Detail Shops Application: Exterior Cleaning, Interior Cleaning, Waxing, Decontamination Formulation: Biodegradable, Non-toxic, Acidic, Alkaline |
| Companies Covered | 3M Company, Ecolab Inc., Turtle Wax, Inc., Meguiar's, Inc., Simoniz USA, Inc., DuBois Chemicals, Inc., Chemical Guys, LLC, Zep, Inc., Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Wash Detergents and Soaps Market Emerging Trajectories
Formulation chemistry is pivoting toward environmental compatibility without performance sacrifice, as regulatory pressure and operational efficiency demands converge on surfactant architecture.
Enzymatic pre-soak concentrates are supplanting alkaline degreasers in touchless tunnel applications. These bio-catalytic blends target protein-based organic soils with lower pH profiles that reduce clear-coat etching risk. Major express exterior chains in California and Texas are adopting enzyme chemistry at 200:1 dilution ratios, compressing freight costs while extending equipment life through reduced caustic exposure.
REACH registration requirements are tightening surfactant import pathways into Europe, forcing non-EU suppliers to establish EU-based toll manufacturing or absorb extended compliance timelines. The industrial consequence is supply concentration among registrant-holding formulation houses with existing ECHA dossiers. Professional wash operators in Germany and France are consolidating procurement around REACH-compliant suppliers to avoid batch discontinuity risk.
Fleet maintenance managers are unbundling chemical supply from equipment service contracts, shifting toward specification-driven tendering that separates wash chemistry from tunnel hardware. This procurement fragmentation favors pure-play chemical suppliers with dedicated fleet technical sales teams over integrated equipment-chemistry vendors. The pattern is most visible in US municipal and corporate fleet operations with centralized procurement functions.
Car Wash Detergents and Soaps Market Segmentation
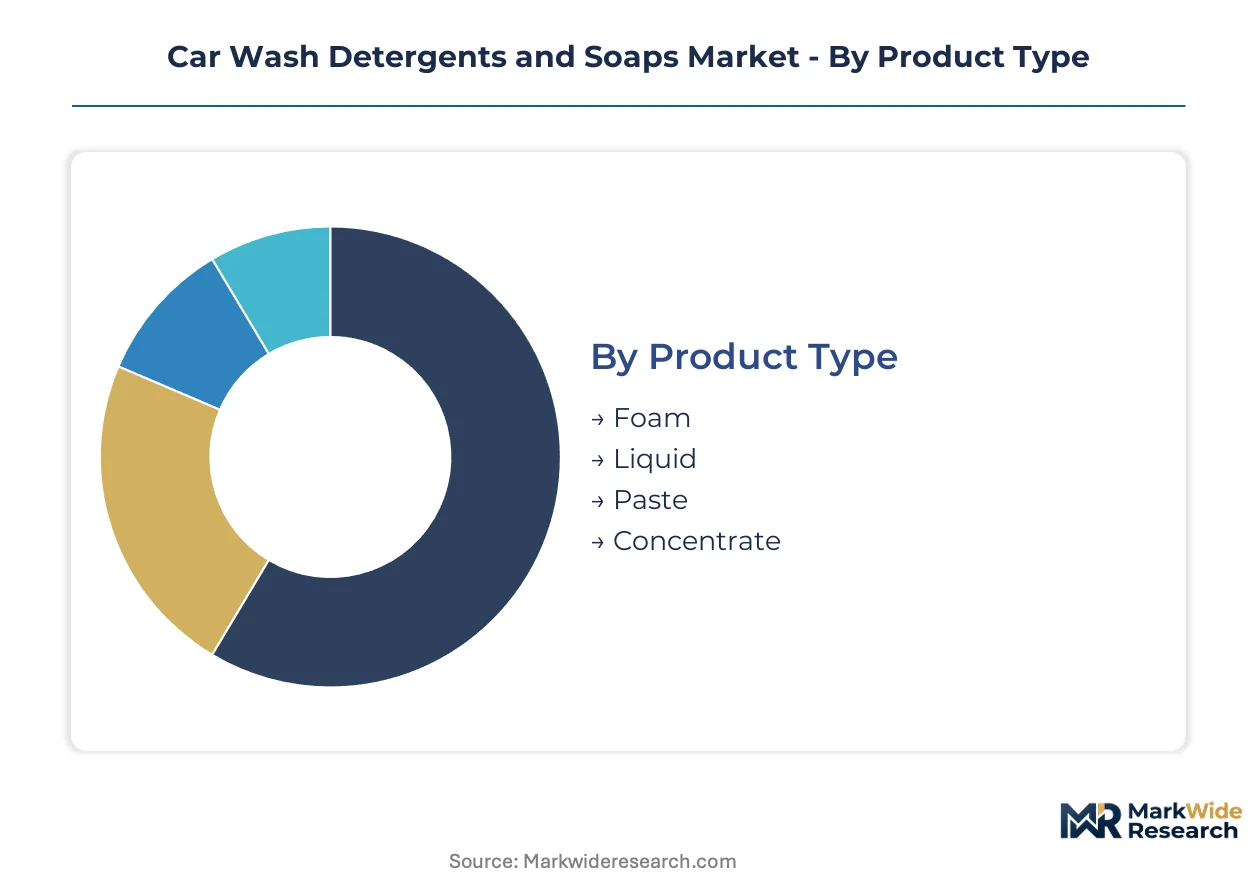
Car wash chemistry procurement splits sharply between high-volume tunnel operators seeking freight-efficient concentrates and residential buyers prioritizing retail accessibility. Formulation mandates under EPA Clean Water Act provisions and state-level discharge rules further segment supply by environmental compliance tier.
Product Type:
Domestic demand concentrates in liquid formats shipped to tunnel operators across Texas, Florida, and California corridors, while concentrate exports face REACH registration bottlenecks into Europe.
- Liquid:pH-buffered surfactant blends engineered for automated dosing systems dominate commercial tunnel throughput. Demand clusters in express exterior chains across Dallas-Fort Worth and Houston where dilution ratios of 128:1 to 400:1 minimize freight cost and storage footprint.
- Foam:High-cling pre-soak chemistry substitutes for mechanical friction in touchless wash formats. Tunnel operators in California metro corridors are installing foam arches that multiply detergent volume per vehicle as touchless configurations spread.
- Concentrate:Freight-optimized formulations for professional dilution equipment.
- Paste:Solid-form chemistry for manual application in detail shops.
Liquid commands the established base. The steepest expansion runs through Foam.
End User:
Procurement scale separates national tunnel chains running multi-site chemical tenders from fragmented residential buyers purchasing through retail channels.
- Commercial Wash Stations:High-volume tunnel and in-bay automatic systems drive chemical procurement budget expansion. Operators across Texas, Florida, and California corridors are scaling surfactant orders to match automatic system rollouts.
- Fleet Services:Specification-driven tendering unbundles chemical supply from equipment service contracts. Municipal and corporate fleet operations with centralized procurement functions favor pure-play chemical suppliers over integrated vendors.
- Detail Shops:Labor-intensive hand-wash operations requiring specialized decontamination chemistry.
- Residential Users:Brand-recognition-driven retail purchasers feeding professional channel migration.
Commercial Wash Stations absorb the dominant procurement volume. Fleet Services is climbing the fastest as electrification forces chelating agent reformulation.
Application:
Exterior-focused chemistry generates substantially higher volume throughput than interior formulations, though ceramic sealant compatibility requirements are expanding waxing-category premiums.
- Exterior Cleaning:Surfactant blends targeting road film, brake dust, and organic contaminants without degrading clear-coat layers. Tunnel operators in California and Texas are adopting enzymatic pre-soak chemistry at 200:1 dilution ratios.
- Decontamination:Iron-fallout and industrial-pollutant removal chemistry for ceramic coating preparation. Demand concentrates among enthusiast-grade detail shops commanding per-ounce premiums through specification-driven sourcing.
- Waxing:SiO2 and graphene-compatible protection chemistry.
- Interior Cleaning:pH-neutral formulations for leather, vinyl, and fabric substrates.
Exterior Cleaning holds the volume base. Decontamination is gaining share fastest as ceramic protection penetration deepens.
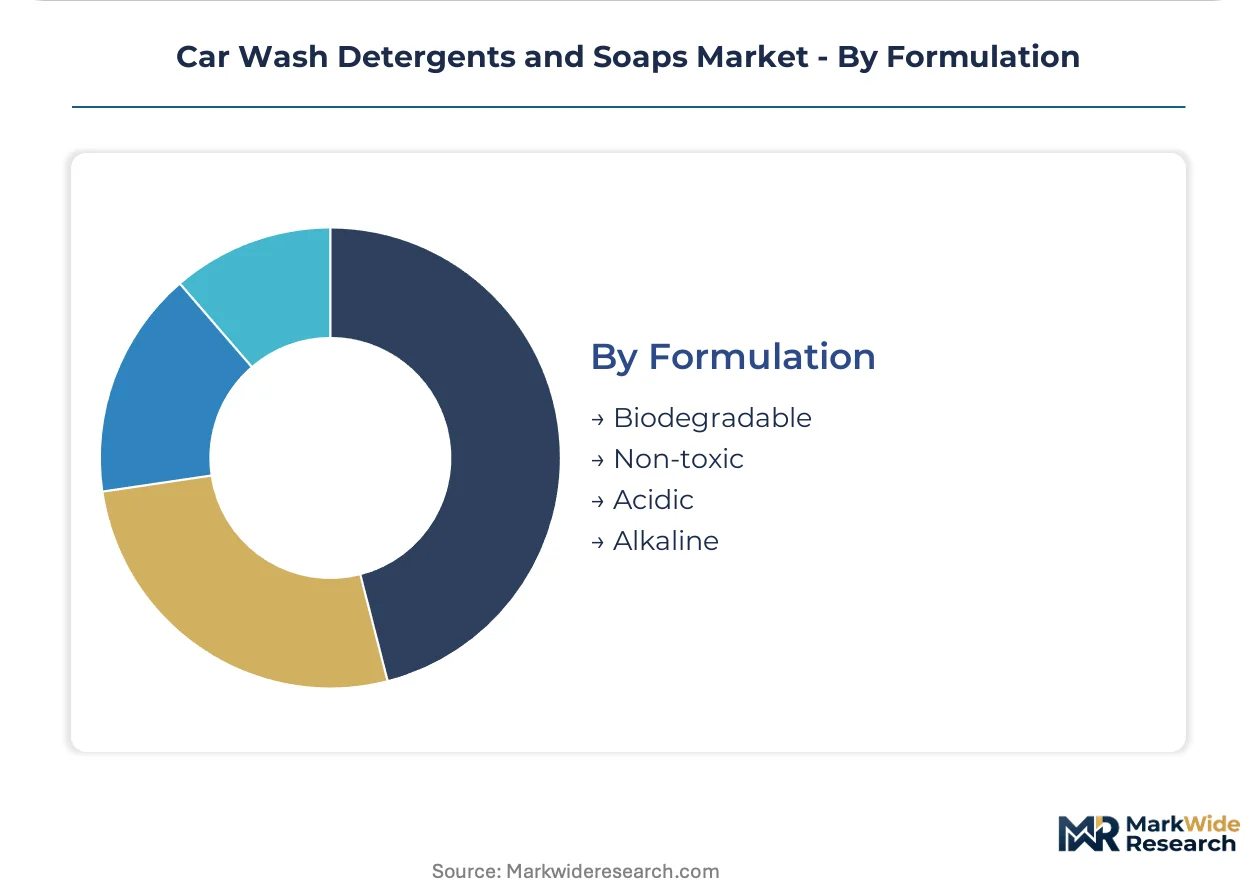
Formulation:
Regulatory pressure under EPA NPDES permitting and state-level discharge rules is compressing legacy petroleum-based chemistry margins while biodegradable alternatives command compliance premiums.
- Biodegradable:Surfactant architecture engineered for wastewater breakdown under Clean Water Act mandates. Formulations command margin premiums in regions with discharge permitting requirements.
- Alkaline:High-pH degreasers retaining stable demand from fleet services managing petroleum-based road film despite enzymatic displacement in touchless tunnels.
- Non-toxic:Reduced hazard communication classification for OSHA compliance.
- Acidic:Mineral deposit and oxidation removal chemistry for specialized decontamination.
Alkaline retains the installed base. Biodegradable formulations are expanding most quickly as PFAS precursor scrutiny propagates into surfactant regulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in car wash chemistry tilt toward import dependence in regions lacking domestic surfactant manufacturing, while formulation houses with captive oleochemical supply anchor export capacity. Regulatory divergence across discharge permitting regimes fragments procurement patterns.
United States
Express exterior wash chains across Texas, Florida, and California corridors multiply tunnel installations and drive concentrate demand. EPA NPDES permitting under the Clean Water Act mandates biodegradable surfactant architectures. Dallas-Fort Worth and Houston metro areas concentrate procurement volume for high-dilution chemistry.
Germany
Professional wash operators in Germany consolidate procurement around REACH-compliant suppliers to avoid batch discontinuity risk. ECHA registration requirements impose 18-24 month lead times on non-EU surfactant imports. Industrial clusters in North Rhine-Westphalia and Bavaria host formulation houses with existing ECHA dossiers.
China
Domestic tunnel wash expansion in Yangtze River Delta and Pearl River Delta metro corridors generates surfactant demand at scale. MEE wastewater discharge standards tighten biodegradable formulation requirements. Shanghai and Shenzhen anchor manufacturing capacity for pH-neutral concentrate exports.
Brazil
Fleet service operators in São Paulo and Rio de Janeiro metro areas drive specification-driven chemical tendering. ANVISA hazard communication standards add labeling compliance layers for imported formulations. Southeast industrial corridors concentrate procurement for alkaline degreasers managing petroleum-based road film.
Canada
Cross-border supply chains from US formulation houses serve Ontario and Quebec tunnel operators with minimal freight friction. Health Canada/PMRA regulates surfactant environmental fate under pesticide analog provisions. Toronto and Montreal metro corridors absorb volume shipments of liquid concentrates.
Car Wash Detergents and Soaps Market Vendor Landscape
Concentration sits with institutional chemical conglomerates possessing regulatory affairs infrastructure and backward integration into oleochemical supply. Mid-tier formulation houses compete on specialty concentrates for enthusiast channels. Three archetypes dominate: diversified chemical conglomerates with cross-selling distribution networks, pure-play vehicle care specialists with social media-driven brand equity, and toll manufacturers serving private-label retail programs. Competitive moves center on REACH registration acquisition for European market access and enzymatic formulation R&D partnerships with tunnel equipment OEMs.
Among US-based institutional suppliers, Ecolab Inc. and Turtle Wax, Inc. occupy positions reflecting divergent channel strategies—Ecolab leveraging foodservice distribution into fleet accounts, Turtle Wax anchoring retail shelf presence that feeds professional migration. Chemical Guys, LLC exemplifies the enthusiast-grade specialist archetype commanding per-ounce premiums through education-driven community building.
| Leading Market Players |
|---|
| 3M Company |
| Ecolab Inc. |
| Turtle Wax, Inc. |
| Meguiar's, Inc. |
| Simoniz USA, Inc. |
| DuBois Chemicals, Inc. |
| Chemical Guys, LLC |
| Zep, Inc. |
| Henkel |
| Others |
Supply Flow & Price Mechanics
Long-term concentrate supply contracts with take-or-pay clauses dominate procurement between tunnel operators and formulation houses, locking in multi-year price visibility while securing surfactant allocation against oleochemical feedstock volatility. This structure concentrates purchasing power among express exterior chains in Texas and California corridors while compressing margin flexibility for mid-tier suppliers lacking backward integration into fatty alcohol supply.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the car wash detergent market. Price differentiation stems from certification grade for ceramic sealant compatibility and volume scale commitments measured in annual concentrate offtake. Cost compression in standard-tier surfactant blends is intensifying because ethylene oxide price swings erode blend margins for non-integrated suppliers. Fleet procurement teams exhibit the highest price sensitivity due to unbundled tendering practices, while ceramic-certified premium formulations command inelastic demand from express exterior operators.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes from Shanghai and Busan elevate inbound logistics costs for US-based formulation houses sourcing oleochemical precursors. Geographic supply concentration centers on China for ethoxylated surfactant intermediates, Malaysia and Indonesia for palm-derived fatty alcohols, and Germany for specialty chelating agents. The supply chain rests on single-source vulnerability for high-purity ethylene oxide derivatives subject to EPA NPDES discharge scrutiny. Distribution runs through regional chemical distributors serving tunnel operators with just-in-time concentrate replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car wash detergent market is recovering from cyclical lows as express exterior wash construction rebounds across Sun Belt metropolitan corridors. Tunnel installation rates serve as the primary cyclical driver, with chemical procurement budgets expanding in lockstep with automatic system rollouts.
For Market Incumbents: Fortify regulatory affairs infrastructure to preempt PFAS precursor restrictions propagating from Maine and Washington into federal surfactant standards. Expand captive oleochemical supply through toll manufacturing partnerships in Southeast Asia to offset ethylene oxide price volatility. Prioritize enzymatic formulation R&D partnerships with tunnel equipment OEMs to defend against alkaline degreaser displacement.
For New Entrants and Emerging Players: Ceramic sealant compatibility certification gaps among legacy institutional suppliers create white-space for specialist formulation houses. Target decontamination chemistry for enthusiast-grade detail shops in California and Texas metro areas where specification-driven sourcing commands per-ounce premiums. Pursue direct technical sales teams as the primary go-to-market angle, bypassing distributor markups that erode challenger margins.
For Investors and Strategic Acquirers: Pure-play vehicle care specialists with established REACH dossiers represent acquisition targets with defensible European market access. Long-term viability across a 5-10 year window hinges on biodegradable surfactant architecture adoption rates. Monitor EPA Clean Water Act enforcement intensity as the inflection indicator for compliance-premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Supply | Captive fatty alcohol production insulates Ecolab and DuBois from ethylene oxide price swings. |
| REACH Registration Acquisition | ECHA dossier holdings unlock 18-24 month compliance advantages for European tunnel operator contracts. |
| Enzymatic Formulation R&D Partnership | Collaboration with tunnel OEMs accelerates alkaline degreaser displacement in touchless configurations. |
| Ceramic Sealant Compatibility Certification | SiO2 and graphene validation commands per-gallon premiums in express exterior channels. |
| On-Site Generation Systems Deployment | Electrolyzed water hardware at wash sites creates recurring chemistry-as-a-service revenue streams. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with tunnel operations managers, fleet procurement directors, formulation chemists at institutional suppliers, and regional chemical distributors. Secondary validation drew from EPA NPDES permit filings, customs trade data for surfactant imports, SEC 10-K disclosures from diversified chemical conglomerates, and state-level discharge enforcement records. Bottom-up volume estimates from tunnel operator concentrate offtake were triangulated against top-down surfactant production capacity data.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, end-user segment, application category, and formulation compliance tier. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation. Key inputs included express exterior wash installation pipelines in Dallas-Fort Worth and Houston, fleet electrification penetration curves affecting brake dust chemistry requirements, and biodegradable formulation mandate adoption timelines under EPA Clean Water Act provisions.
Material uncertainties — petrochemical feedstock volatility, PFAS regulatory propagation timelines, and REACH registration bottlenecks for non-EU suppliers — sit outside the modeled envelope. Forecasts reflect assumptions regarding tunnel construction continuity and ceramic sealant penetration rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
Smart Cleaning and Hygiene Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Household Cleaners Market
Cleaning Equipment
Cleaning Appliance Market
Cleaning Equipment
Carpet Extraction Cleaner Market
Cleaning Equipment
Spin Mops Market
Cleaning Equipment
Global Carpet and Upholstery Cleaning Services Market
Cleaning Equipment
North America Smart Commercial Restroom Products Market
Cleaning Equipment
Furniture Polish Market
Cleaning Equipment
Countertop Spray Market
Cleaning Equipment
Commercial Vacuum Cleaners Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Brush Cleaner Market
Cleaning Equipment
Household Wipes Market
Cleaning Equipment
Bathroom Mirror Wiper Market