
 Carpet Extraction Cleaner Market | 2026-2036
Carpet Extraction Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Carpet Extraction Cleaner Market Outlook
Buyer concentration among national hospitality chains and healthcare facility management groups is repositioning procurement toward fleet-scale extraction equipment contracts. Alfred Kärcher SE & Co. KG leverages its European service network to anchor institutional accounts with preventive maintenance bundling. Tennant Company competes through robotic integration into its commercial extraction platforms. Nilfisk Group specializes in compact portable units for multi-site cleaning service operators navigating tight storage constraints.
Carpet extraction cleaners are machines that inject pressurized cleaning solution into carpet pile and simultaneously recover dirty water through vacuum extraction, typically operating at solution temperatures between 120°F and 210°F and extraction pressures from 100 to 500 PSI depending on soil classification. Their primary purpose is deep soil removal from synthetic and natural fiber installations without the residue accumulation associated with rotary shampoo methods. Portable cleaners lead the product type dimension for residential and small commercial penetration, while truck-mounted systems command the margin pool in municipal and large hospitality contracts where extraction speed and waste capacity determine labor economics. Hot water extraction dominates the technology category for its soil suspension efficacy, though dry extraction systems are gaining traction in water-sensitive healthcare environments where rapid drying prevents microbial colonization.
EPA Safer Choice certification and EU REACH chemical restrictions are reshaping formulation requirements for extraction solutions, compelling manufacturers to document biodegradability profiles and volatile organic compound thresholds. OSHA workplace exposure standards and the EU Machinery Directive govern operator safety features including automatic shutoff systems and noise emission ceilings. Stakeholders must monitor evolving state-level chemical disclosure laws in California and New York alongside pending EU Ecodesign requirements that could mandate energy recovery systems in heated extraction equipment.
Market Dynamics
Hospitality chains and healthcare facility management groups are consolidating procurement around fleet-scale extraction equipment contracts, forcing manufacturers to bundle preventive maintenance and chemical supply agreements into multi-year service relationships rather than transactional equipment sales.
Growth Catalysts
- EPA Safer Choice certification mandates:Commercial cleaning contracts in the United States increasingly specify certified extraction solutions, expanding the addressable market for compliant chemical suppliers.
- Robotic integration into commercial platforms:Autonomous navigation systems reduce labor hours per square meter in large-format retail and airport terminals.
- Healthcare infection control protocols:Rapid-dry extraction technology prevents microbial colonization in surgical suites and long-term care wards across Germany and Japan.
Market Restraints
- Heating element input cost volatility:Stainless steel and copper pricing fluctuations compress margins on hot water extraction units.
- EU REACH chemical registration timelines:Biodegradability documentation requirements delay new formulation launches by 18-24 months.
- Surface cleaning method substitution:Encapsulation chemistry and low-moisture systems compete for maintenance cleaning contracts in commercial office segments.
Strategic Opportunities
- Water-sensitive healthcare environments:Dry extraction systems penetrate surgical centers and pharmaceutical manufacturing cleanrooms where moisture control is critical.
- EU Ecodesign energy recovery mandates:Pending requirements for heated extraction equipment create first-mover advantage for heat-exchange technology developers.
- Multi-site cleaning service operators:Compact portable units address storage constraints in urban facilities across the United States and Germany.
Industry Challenges
- Technician certification requirements:IICRC and WoolSafe credentialing programs create hiring bottlenecks for service contractors scaling operations.
- Integration complexity with building management systems:Fleet telemetry and IoT connectivity protocols vary across hospitality property management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carpet Extraction Cleaner Market |
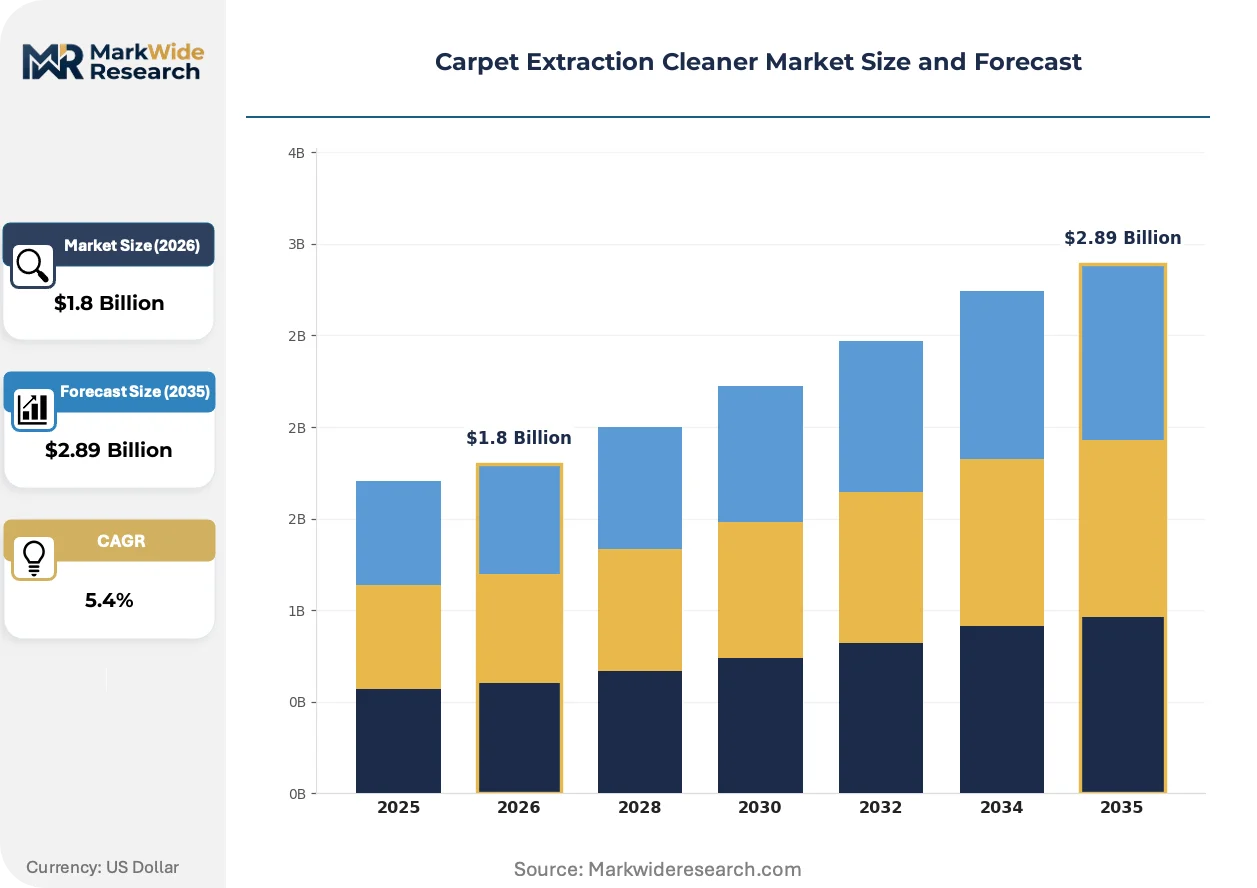
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Cleaners, Truck-Mounted Cleaners, Stationary Cleaners, Brush Roll Cleaners Application: Residential Use, Commercial Use, Industrial Use, Hospitality Use Technology: Steam Cleaning, Dry Extraction, Hot Water Extraction, Chemical Extraction End User: Households, Cleaning Services, Hotels, Healthcare Facilities |
| Companies Covered | BISSELL Homecare, Inc., Alfred Kärcher SE & Co. KG, Rug Doctor, Hoover, Tennant Company, Nilfisk Group, Techtronic Industries Co. Ltd, Windsor Kärcher Group, SEBO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carpet Extraction Cleaner Market Strategic Shifts
Equipment architecture is fragmenting into interoperable subsystems, allowing operators to configure extraction platforms for specific soil classifications and facility constraints rather than purchasing fixed-capability machines.
Heated extraction technology is modularizing around swappable heat-exchange cores and variable-pressure pump modules. Hospitality chains in the United States are standardizing on platforms that technicians reconfigure between 150 PSI maintenance cleaning and 500 PSI restorative extraction. This architecture compresses fleet inventory requirements and extends equipment lifecycle through component replacement rather than full unit retirement.
EU REACH restrictions on perchloroethylene and N-methyl-2-pyrrolidone are eliminating solvent-based extraction chemistries from commercial formulations. Manufacturers reformulate around plant-derived surfactants and low-VOC builders to maintain efficacy against petroleum-based soils. Healthcare and education end-uses in Germany and France show strongest preference for certified biodegradable solutions.
Facility management groups are unbundling after-sales service contracts from equipment procurement, creating independent service markets for preventive maintenance and chemical supply. Third-party service networks in Japan now compete directly with manufacturer-authorized technicians for multi-site hospitality accounts. This fragmentation pressures OEM margins on attach-rate dependent business models.
Carpet Extraction Cleaner Market Segmentation
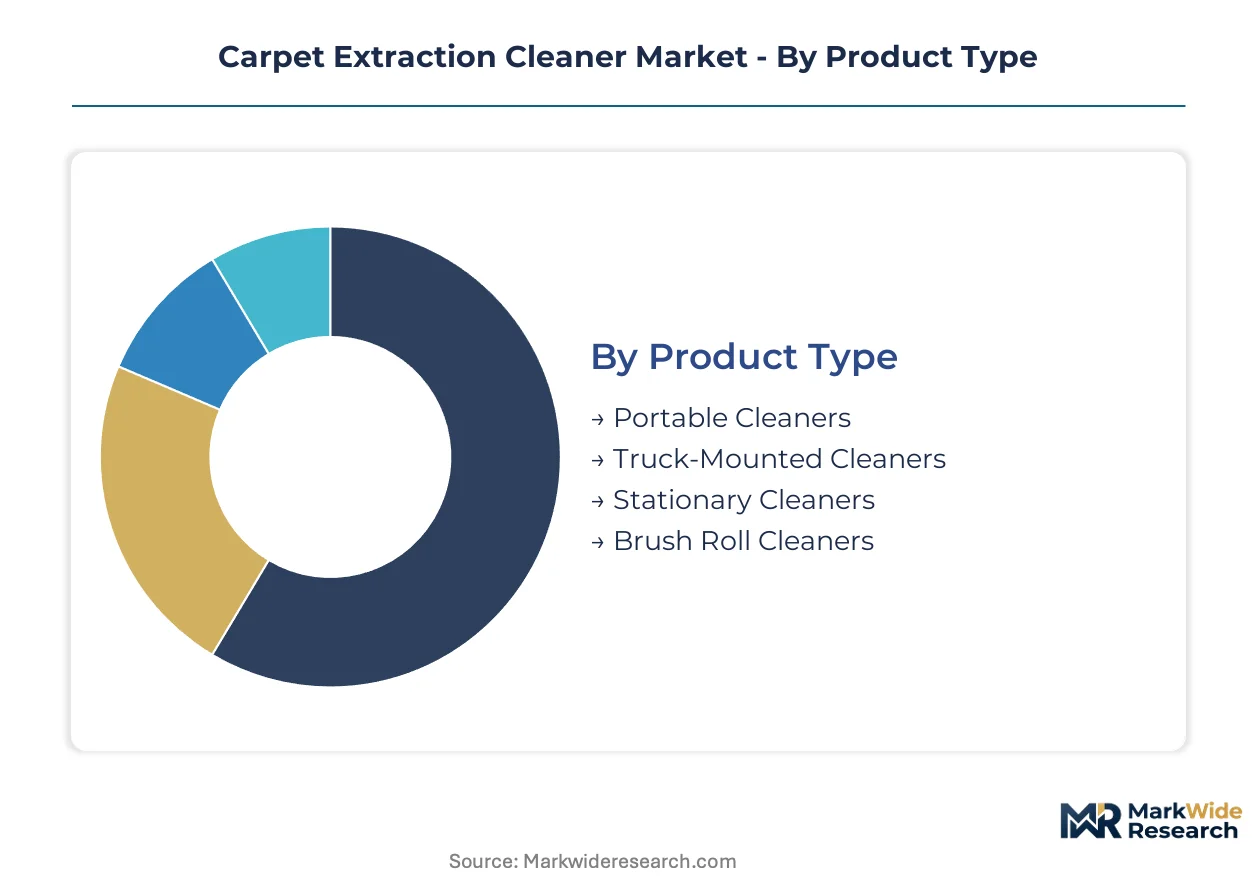
Carpet extraction cleaner procurement varies sharply by operational scale and facility constraints. Understanding segment boundaries clarifies why manufacturers maintain divergent product architectures and service bundling strategies across customer types.
Product Type:
Standardized fleet platforms dominate high-volume contracts, while customized configurations prevail in specialized restoration and constrained-access environments.
- Portable Cleaners:Self-contained units with onboard solution tanks and recovery canisters, typically rated between 100-250 PSI extraction pressure. Demand concentrates among multi-site cleaning service operators in Germany and the United States where urban facilities impose severe storage limitations and elevator access restrictions.
- Truck-Mounted Cleaners:Vehicle-integrated systems delivering 400-500 PSI with continuous fresh water supply and high-capacity waste tanks. Municipal contracts and large hospitality chains across Japan specify these units for rapid area coverage where labor economics favor maximum extraction speed over equipment mobility.
- Stationary Cleaners:Fixed-installation systems plumbed directly to facility utilities for continuous operation in industrial settings.
- Brush Roll Cleaners:Aggitation-enhanced units combining rotary brush action with extraction recovery for heavily soiled commercial environments.
Leading the category by volume: Portable Cleaners. Growing fastest: Truck-Mounted Cleaners.
Application:
Contract specifications increasingly differentiate maintenance cleaning from restorative extraction, fragmenting equipment requirements by soil severity and frequency.
- Commercial Use:Office buildings, retail centers, and institutional facilities requiring scheduled maintenance programs with documented cleaning intervals. Property management groups in the United States specify extraction-based protocols over encapsulation methods for lease compliance and warranty preservation on synthetic fiber installations.
- Hospitality Use:Hotels, resorts, and conference centers with high-traffic public areas and rapid turnaround requirements. Chains across Europe mandate fleet-standardized equipment to simplify technician training and chemical inventory management across dispersed properties.
- Residential Use:Single-family homes and small multi-family dwellings with intermittent deep cleaning needs.
- Industrial Use:Manufacturing facilities, warehouses, and logistics centers with petroleum-based soil loads and heavy equipment traffic.
Commercial Use generates the largest equipment volume. Hospitality Use shows the steepest expansion trajectory as chains consolidate procurement.
Technology:
Temperature and moisture control parameters determine technology selection, with regulatory pressure accelerating shifts away from solvent-based methods.
- Hot Water Extraction:Pressurized heated solution injection at 120-210°F combined with immediate vacuum recovery, the dominant method for synthetic fiber restoration. EPA Safer Choice certification requirements in the United States are expanding the compliant chemical supply base for this technology category.
- Dry Extraction:Low-moisture compound application and mechanical agitation without liquid recovery, critical for water-sensitive environments. Healthcare facilities in Germany and Japan specify dry systems for surgical suites and pharmaceutical cleanrooms where rapid drying prevents microbial colonization.
- Steam Cleaning:Saturated vapor application at elevated temperatures for sanitization-focused protocols.
- Chemical Extraction:Solvent-based soil removal systems facing contraction under EU REACH restrictions on perchloroethylene and N-methyl-2-pyrrolidone.
Hot Water Extraction dominates installed base. Dry Extraction is climbing the fastest as healthcare infection control protocols tighten.
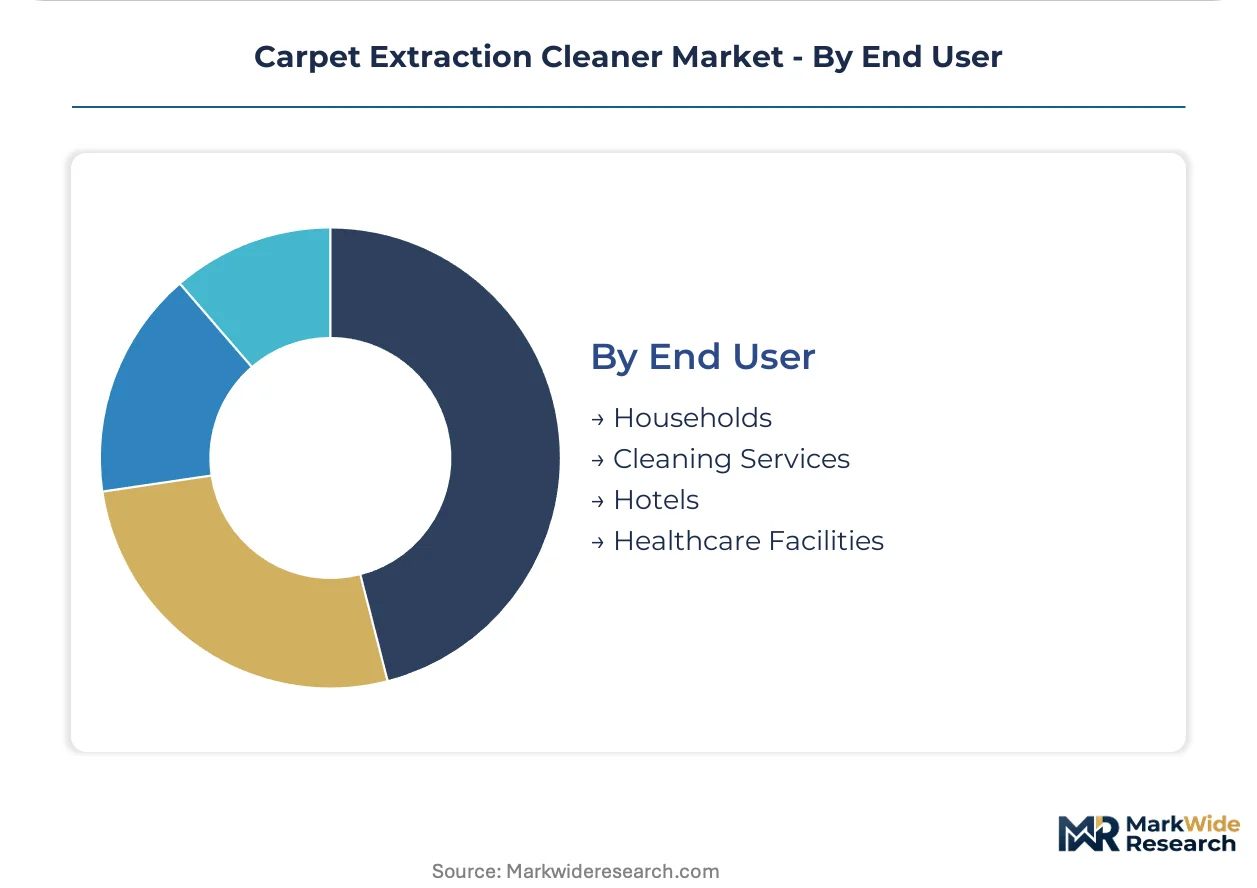
End User:
Procurement authority concentrates in facility management groups and national service chains, compressing the direct household market to replacement and rental channels.
- Cleaning Services:Independent and franchise operators performing contracted maintenance for commercial and residential accounts. Multi-site operators in the United States and Germany drive demand for compact portable units compatible with vehicle fleets and urban parking constraints.
- Healthcare Facilities:Hospitals, long-term care wards, and outpatient clinics with stringent infection control documentation. German healthcare procurement specifies rapid-dry extraction technology to minimize downtime in clinical areas while satisfying hygiene audit requirements.
- Households:Individual consumers purchasing through retail or rental channels for intermittent residential use.
- Hotels:Property-level and chain-level procurement of equipment for in-house housekeeping operations.
Cleaning Services represent the largest equipment volume. Healthcare Facilities are gaining share fastest as regulatory compliance intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility management contracts in the United States, Germany, and Japan concentrate procurement authority for carpet extraction equipment, with hospitality chains and healthcare systems driving specification standards that ripple through adjacent markets.
United States
National hospitality chains and healthcare facility management groups consolidate procurement around fleet-scale extraction equipment contracts. EPA Safer Choice certification mandates now appear in most commercial cleaning specifications, expanding the compliant chemical supply base. Chicago and Dallas anchor major distribution corridors serving institutional accounts across the Midwest and Southwest.
Germany
Healthcare infection control protocols in surgical suites and long-term care wards specify rapid-dry extraction technology to minimize downtime while satisfying hygiene audit requirements. EU REACH chemical restrictions on perchloroethylene and N-methyl-2-pyrrolidone eliminate solvent-based formulations, pushing demand toward plant-derived surfactants. Stuttgart and Munich host clusters of equipment manufacturers serving institutional buyers.
Japan
Municipal contracts and large hospitality chains specify truck-mounted systems for rapid area coverage where labor economics favor maximum extraction speed. METI workplace safety standards govern operator exposure limits and noise emission ceilings for commercial cleaning equipment. Osaka and Tokyo concentrate facility management groups unbundling after-sales service contracts from equipment procurement.
United Kingdom
Property management groups in London and Southeast England specify extraction-based protocols over encapsulation methods for lease compliance and warranty preservation on synthetic fiber installations. CE marking requirements under the EU Machinery Directive govern safety features including automatic shutoff systems. Birmingham serves as a logistics hub for equipment distribution to regional cleaning service operators.
France
Healthcare and education end-uses in Paris and Lyon show strongest preference for certified biodegradable extraction solutions as EU Ecodesign requirements for energy recovery systems advance through regulatory consultation. ANSM hygiene standards in pharmaceutical manufacturing cleanrooms drive specification of dry extraction systems where moisture control prevents contamination. Île-de-France anchors demand for compact portable units addressing urban storage constraints.
Carpet Extraction Cleaner Market Competitive Environment
German producers anchor one tier; United States specialists hold institutional service bundling positions. The vendor base organizes around three tiers: integrated multinationals with preventive maintenance networks, robotics-focused platform developers, and compact portable specialists serving multi-site operators. Strategic moves concentrate on M&A for service network expansion and portfolio diversification into adjacent surface cleaning technologies.
Within the integrated multinational tier, Alfred Kärcher SE & Co. KG and Windsor Kärcher Group exemplify European anchoring of institutional accounts through service bundling. Tennant Company occupies a position on the robotics-integration vector, while Nilfisk Group represents the compact portable specialization archetype. These three patterns—preventive maintenance bundling, autonomous platform development, and constrained-access mobility—capture the dominant competitive positioning strategies across procurement segments.
| Leading Market Players |
|---|
| BISSELL Homecare, Inc. |
| Alfred Kärcher SE & Co. KG |
| Rug Doctor |
| Hoover |
| Tennant Company |
| Nilfisk Group |
| Techtronic Industries Co. Ltd |
| Windsor Kärcher Group |
| SEBO |
| Others |
Value Chain & Pricing Dynamics
Technician certification density in Germany and the United States creates labor-cost differentials that widen pricing-tier spreads between premium service-bundled equipment and transactional portable units. EPA Safer Choice compliance investments and EU REACH documentation burdens concentrate margin pressure on mid-tier manufacturers lacking scale economies in formulation testing.
Pricing Analysis
Volume concentrates in portable cleaners while margins pool in truck-mounted systems and preventive maintenance contracts. Three-tier pricing structure across premium robotic-integrated platforms, standard heated extraction units, and economy portable equipment reflects divergence in after-sales service bundling and certification grade. Pricing pressure stems from stainless steel and copper input volatility compressing margins on hot water extraction units. Multi-site cleaning service operators exhibit highest price sensitivity, whereas national hospitality chains prioritize fleet standardization over unit cost.
Supply Chain Analysis
EPA Safer Choice and EU REACH certification gating filters component suppliers and chemical formulators, eliminating non-compliant upstream participants. Manufacturing concentrates in Germany, the United States, and China, with stainless steel heating elements and precision pump assemblies drawing from specialized metalworking clusters. Supply chain risk centers on single-source vulnerability for high-pressure pump modules. Distribution runs through manufacturer-direct institutional contracts, authorized dealer networks, and third-party service unbundlers competing for aftermarket revenue pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EPA Safer Choice and EU REACH documentation requirements erect barrier-to-entry moats favoring incumbents with captive testing infrastructure and established regulatory affairs capabilities.
For Market Incumbents: Anchor institutional accounts through multi-year preventive maintenance bundling that locks in chemical supply revenue streams and raises switching costs for hospitality chains. Invest in heat-exchange technology development to capture first-mover advantage under pending EU Ecodesign energy recovery mandates. Defend against third-party service unbundlers by integrating IoT telemetry that enables predictive maintenance and remote diagnostics. For New Entrants and Emerging Players: Begin with dry extraction systems for healthcare surgical suites and pharmaceutical cleanrooms in Germany and Japan, where rapid-dry protocols command premium positioning and regulatory compliance creates defensible niches. Target compact portable configurations for urban multi-site operators facing storage constraints in the United States and France. Pursue white-label manufacturing partnerships with established chemical suppliers to bypass 18-24 month REACH registration timelines. For Investors and Strategic Acquirers: Re-rating potential sits with robotics-integrated platform developers given autonomous navigation adoption in airport terminals and large-format retail. Long-term viability favors manufacturers with backward integration into heat-exchange components and certified chemical formulation capabilities. Watch for inflection signals in third-party service contract unbundling rates, which indicate shifting power dynamics between OEMs and independent maintenance networks.| Strategic Initiative | Industry Significance |
|---|---|
| Preventive Maintenance Bundling | Multi-year service contracts lock in chemical supply revenue and raise account switching costs for hospitality chains. |
| Heat-Exchange Technology Development | EU Ecodesign energy recovery mandates create first-mover positioning for compliant heated extraction equipment. |
| Robotic Platform Integration | Autonomous navigation reduces labor hours per square meter in airport terminals and large-format retail environments. |
| Dry Extraction System Expansion | Healthcare infection control protocols in Germany and Japan drive specification for water-sensitive surgical suite applications. |
| Third-Party Service Network Acquisition | Independent maintenance unbundling pressures OEM attach-rate models and fragments aftermarket revenue capture. |
Study Parameters
Multi-period observation of equipment procurement volumes, chemical formulation registrations, and technician certification rates anchored the trend analysis, supplemented by interviews with facility management procurement directors, commercial cleaning service operators, OEM product managers, and regulatory compliance officers. Secondary validation drew from EPA Safer Choice certified product listings, EU REACH registration databases, OSHA workplace exposure standards, and hospitality chain sustainability reports. Bottom-up segment sizing triangulated against top-down market value estimates derived from manufacturer revenue disclosures and distribution channel audits.
Segment-weighting approaches applied differential growth assumptions across portable, truck-mounted, and stationary cleaner categories, with technology splits between hot water extraction, dry extraction, and steam cleaning systems modeled throughout the projection horizon. End-user segmentation incorporated cleaning services, healthcare facilities, hospitality chains, and residential channels. CAGR derivation incorporated equipment replacement cycles, regulatory compliance cost pass-through rates, and labor cost inflation differentials across major national markets.
Underlying measurement precision varies by segment; truck-mounted cleaner volumes in municipal and large hospitality contracts carry tighter precision than fragmented residential portable sales. Forecasts reflect assumptions regarding EPA enforcement continuity, EU Ecodesign implementation timelines, and stainless steel input cost trajectories. A model refresh is warranted upon material change in REACH chemical registration timelines or hospitality chain consolidation patterns affecting fleet procurement scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Household Wipes Market
Cleaning Equipment
Consumer Wet Wipes Market
Cleaning Equipment
Laundry Detergent Market
Cleaning Equipment
Dry Laundry Detergents Market
Cleaning Equipment
Liquid Laundry Detergent Market
Cleaning Equipment
Hand Cleaning Accessories Market
Cleaning Equipment
Furniture Polish Wipes Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Countertop Spray Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
Furniture Polish Market
Cleaning Equipment
Brush Cleaner Market
Cleaning Equipment
Carpet Steamers Market
Cleaning Equipment
Cleaning and Hygiene Products Market
Cleaning Equipment
Sponge Cloth Market