
 Natural Fiber Reinforced Composites Market | 2026-2036
Natural Fiber Reinforced Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Fiber Reinforced Composites Market Foresight
Buyer concentration in the automotive sector is shifting as tier-one suppliers fragment their sourcing across multiple biocomposite specialists rather than relying on traditional glass fiber houses. Bcomp leverages its ampliTex flax fiber portfolio to anchor premium interior programs with European OEMs. TECNARO GMBH sustains leadership in ARBOFORM lignin-based compounds through deep specialization in injection molding grades for consumer electronics housings. Green Dot Bioplastics competes by extending its Terratek biocomposite platform across a broad material spectrum including hemp and kenaf reinforcements.
Natural fiber reinforced composites combine cellulosic fibers such as flax, hemp, or jute with thermoplastic or thermoset matrices to achieve density reductions of 25-40% versus glass fiber equivalents while maintaining comparable stiffness-to-weight ratios. These materials serve primarily as structural substitutes in load-bearing automotive panels, construction profiles, and durable goods where weight reduction and end-of-life recyclability carry premium value. Compression molding occupies the dominant share of current production volume owing to its compatibility with longer fiber lengths and lower equipment capital requirements. Injection molding represents the fastest-expanding process category as compounders achieve improved fiber dispersion through twin-screw compounding advances. Among end users, automotive interior components command the largest existing application base, while construction structural parts emerge as the highest-margin growth corridor due to building code recognition of bio-based materials in Germany and the Netherlands.
The EU Green Deal's carbon border adjustments and REACH restrictions on synthetic fiber additives are reshaping supplier qualification criteria across European manufacturing. ECHA substance evaluations and forthcoming CSRD disclosure mandates force compounders to document full lifecycle environmental footprints for composite feedstocks. Germany's national implementation of EU construction product regulations through DIBt approvals creates differentiated market access for hemp-reinforced building materials. Stakeholders must monitor evolving bio-based content thresholds in public procurement specifications and pre-position supply chain certifications before these criteria harden into mandatory bid requirements.
Market Dynamics
The EU Green Deal's carbon border adjustments and REACH restrictions on synthetic fiber additives are forcing compounders to requalify entire feedstock portfolios. Tier-one automotive suppliers now demand documented lifecycle footprints before contract renewal, compressing qualification timelines from 18 months to under 9 months for biocomposite alternatives.
Growth Catalysts
- REACH synthetic fiber restrictions:ECHA substance evaluations ban specific glass fiber sizing chemistries, accelerating substitution toward flax and hemp reinforcements in German automotive programs.
- Automotive mass reduction mandates:OEM interior targets favor cellulosic fiber composites achieving 25-40% density reduction versus conventional glass mat solutions.
- Construction bio-material recognition:DIBt approvals in Germany and Dutch building code amendments legitimize hemp-reinforced structural profiles for load-bearing applications.
Market Restraints
- Natural fiber supply concentration:European flax cultivation concentrates in northern France and Belgium, creating single-source dependency for premium textile-grade fiber.
- Moisture sensitivity limitations:Unmodified cellulosic fibers exhibit dimensional instability above 8% moisture content, restricting exterior automotive and marine applications without capstock barriers.
- Competing bio-based substitutes:Recycled carbon fiber from aerospace scrap achieves comparable stiffness-to-weight at declining cost curves, threatening premium positioning of natural fiber solutions.
Strategic Opportunities
- CSRD disclosure mandates:The EU Corporate Sustainability Reporting Directive creates first-mover advantage for compounders with certified lifecycle data, embedding suppliers into Scope 3 reduction programs.
- Injection molding grade expansion:Twin-screw compounding advances enable shorter fiber dispersion in PP and PLA matrices, opening appliance housings and consumer electronics beyond compression-molded panels.
- Public procurement thresholds:Bio-based content minimums in Dutch and French government construction tenders pre-qualify certified hemp and flax composites for infrastructure bids.
Industry Challenges
- Fiber-matrix interface engineering:Silane and maleic anhydride coupling chemistry requires application-specific optimization, stretching R&D timelines for each new resin system.
- End-of-life certification complexity:Industrial composting facilities lack standardized acceptance criteria for biocomposite waste streams, blocking circularity claims in consumer-facing markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Fiber Reinforced Composites Market |
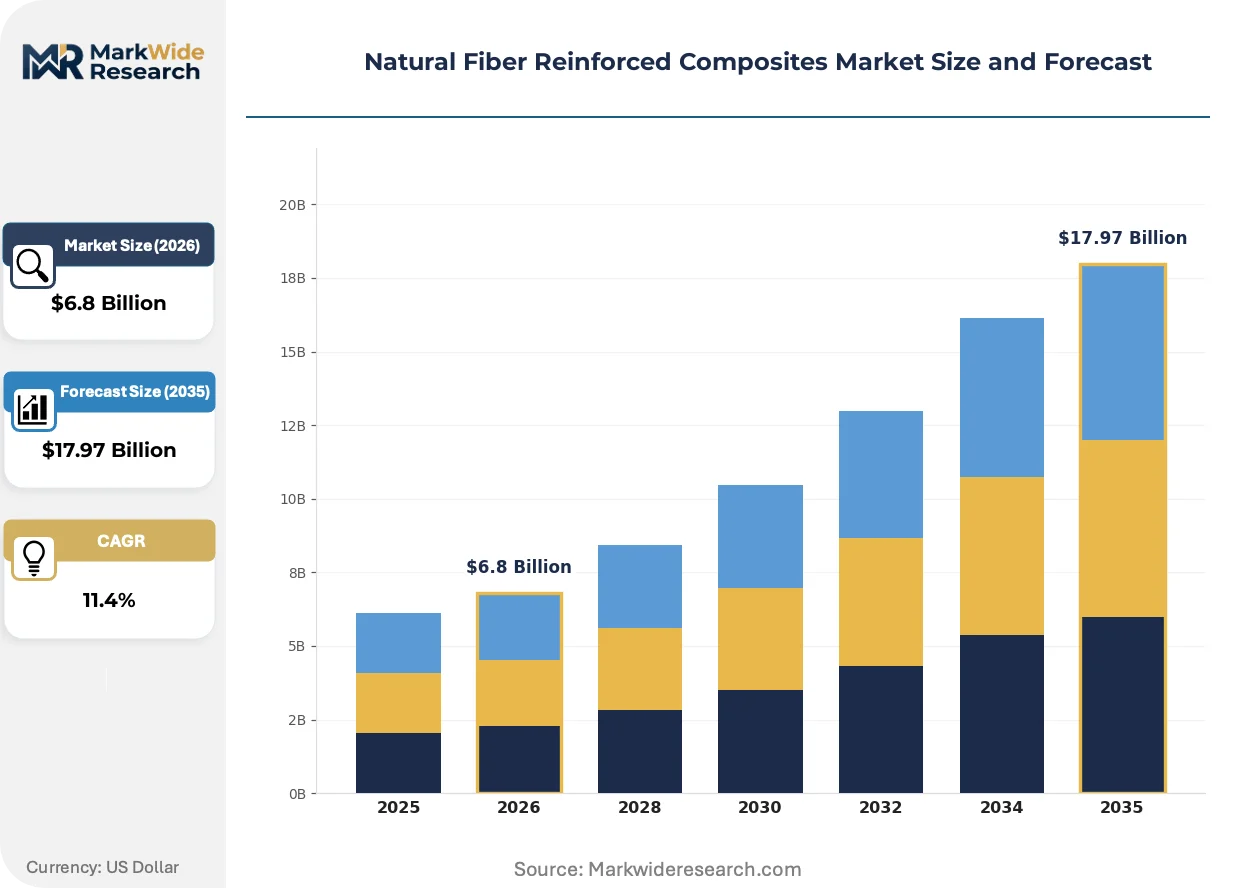
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Extrusion, Thermoforming, Compression Molding End User: Automotive, Construction, Consumer Goods, Aerospace Material: Hemp, Flax, Jute, Kenaf Application: Interior Components, Structural Parts, Packaging, Sports Equipment |
| Companies Covered | Meshlin Composites Zrt., Bcomp, Polyvlies Franz Beyer GmbH, BUSS AG, INCA Renewable Technologies Inc., TECNARO GMBH, GreenGran BN, Green Dot Bioplastics, FlexForm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Fiber Reinforced Composites Market Shifts & Advancements
Process technology convergence is collapsing the traditional divide between compression and injection molding capabilities. Equipment suppliers now deliver modular systems enabling mid-volume producers to pivot between fiber lengths and matrix types without full line replacement.
Hybrid natural-synthetic fiber preforms are unifying the performance benefits of flax stiffness with impact resistance from recycled PET or PP fiber matrices. Automotive seating and door panel programs in France and Germany adopt these hybrids at accelerating rates. The technology is unifying previously separate supply chains for natural fiber specialists and conventional composite houses, forcing compounders to master both cellulosic handling and thermoplastic processing in single facilities.
REACH authorization requirements for boron-based glass fiber additives are tightening compounder qualification burdens across European manufacturing. ECHA substance evaluations now demand substitution plans for persistent chemistries in composite sizings. German tier-one suppliers respond by accelerating ARBOFORM and ampliTex validation programs to lock in approved supplier status before 2027 reauthorization deadlines.
Buyer specification patterns are fragmenting as OEM sustainability teams bypass traditional purchasing departments to set fiber content minimums. Tier-one interior suppliers in the Netherlands now maintain parallel technical and sustainability qualification tracks, with the latter possessing veto authority over material selection. This bifurcation is most visible in German premium automotive programs where biocomposite content thresholds appear in RFP technical appendices rather than commercial terms.
Natural Fiber Reinforced Composites Market Segmentation
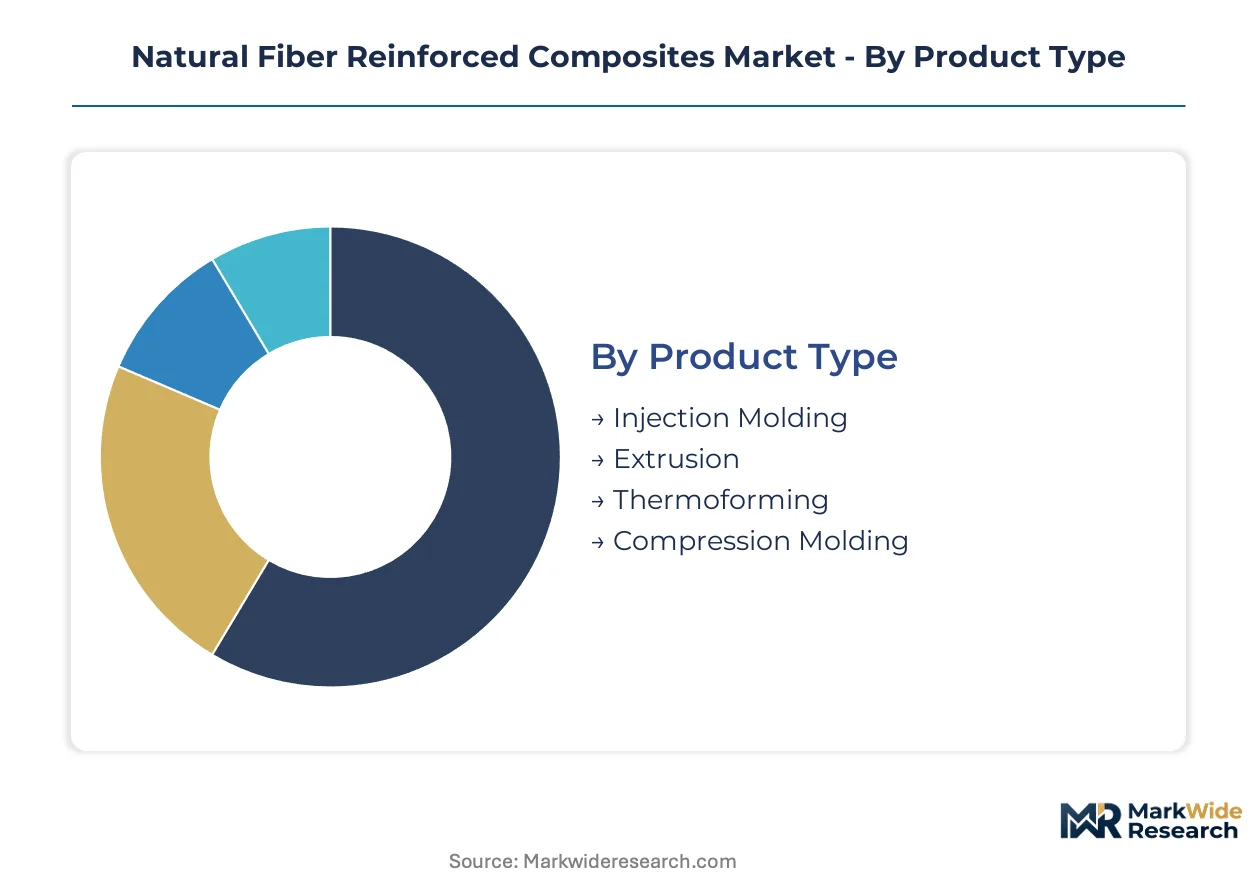
Natural fiber reinforced composites demand diverges sharply across processing technologies and end-use specifications. Material selection and manufacturing method determine performance ceilings, regulatory compliance pathways, and supplier qualification requirements in ways that reshape competitive boundaries.
Product Type:
Processing technology dictates fiber length retention, cycle economics, and surface finish quality in finished components.
- Compression Molding:Accommodates longer fiber lengths up to 50mm, preserving stiffness-to-weight ratios critical for automotive door panels and roof liners. German tier-one suppliers dominate capacity deployment for this process category.
- Injection Molding:Twin-screw compounding advances now disperse shorter fibers in PP and PLA matrices without agglomeration, opening appliance housings and consumer electronics where dimensional tolerance requirements are tighter.
- Extrusion:Continuous profile production serves construction applications requiring consistent cross-sectional properties for decking and cladding systems.
- Thermoforming:Sheet-based processing enables deep-draw geometries for packaging trays and disposable goods with thinner wall sections.
Compression molding leads on scale; injection molding leads on momentum.
End User:
Customer procurement patterns fragment across industries with divergent qualification timelines and sustainability disclosure obligations.
- Automotive:Interior component mandates from European OEMs specify bio-based content thresholds in technical appendices, with sustainability teams possessing veto authority over material selection. Mass reduction targets favor cellulosic fiber density advantages.
- Construction:DIBt approvals in Germany and Dutch building code amendments legitimize hemp-reinforced structural profiles for load-bearing applications, creating the highest-margin growth corridor.
- Consumer Goods:Electronics housings and durable goods demand injection-molding compatibility and surface aesthetics that compete with conventional plastics.
- Aerospace:Secondary structural applications explore natural fiber hybrids where fire resistance requirements permit, though certification timelines extend qualification cycles.
Automotive commands existing volume concentration; construction climbs the fastest.
Material:
Fiber sourcing geography and cultivation economics determine supply security and cost structure stability.
- Flax:Premium textile-grade bast fibers from northern France and Belgium deliver optimal stiffness-to-weight ratios for automotive interior panels, though single-source dependency creates supply vulnerability.
- Hemp:German and Dutch cultivation expansion supports construction-grade reinforcement with lower input intensity, aligning with DIBt certification pathways for structural profiles.
- Jute:Cost-positioned fiber for packaging and disposable applications where moisture sensitivity constraints are manageable through barrier design.
- Kenaf:Emerging cultivation in southern European regions offers drought tolerance advantages and alternative supply geography for compounders diversifying sourcing risk.
Flax dominates premium applications; hemp gains share fastest.
Application:
Functional requirements for load-bearing capacity, surface exposure, and end-of-life handling reshape material-process pairings.
- Interior Components:Automotive door panels, seat backs, and dashboard carriers specify flax-reinforced compression-molded grades where OEM sustainability scorecards weight bio-based content.
- Structural Parts:Construction profiles and load-bearing elements demand hemp-based formulations with documented mechanical properties under DIBt approval frameworks.
- Packaging:Thermoformed trays and protective dunnage utilize jute and kenaf in cost-sensitive applications with shorter service life expectations.
- Sports Equipment:Niche positioning for flax and hemp in skis, snowboards, and bicycle components where stiffness-to-weight marketing claims support premium pricing.
Interior components anchor current volume; structural parts show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the most advanced biocomposite manufacturing infrastructure, while France dominates premium flax fiber cultivation. The Netherlands and Belgium anchor complementary supply chain positions through specialized compounding and textile-grade fiber production.
Germany
Automotive OEMs in Stuttgart and Munich specify flax-reinforced interior panels for mass reduction programs. DIBt approvals legitimize hemp-based structural profiles for load-bearing construction applications. The Baden-Württemberg cluster hosts dedicated biocomposite manufacturing lines serving tier-one automotive suppliers.
France
Northern France concentrates over 80 percent of European textile-grade flax cultivation for premium composite reinforcement. ECHA REACH restrictions on synthetic fiber sizing chemistries accelerate substitution toward domestically sourced bast fibers. The Hauts-de-France region anchors supply security for automotive programs requiring documented lifecycle footprints.
Netherlands
Dutch building code amendments recognize bio-based materials in public infrastructure tenders. CSRD disclosure mandates create first-mover advantage for compounders with certified environmental data. The Eindhoven region hosts sustainability qualification tracks where procurement teams possess veto authority over conventional material selection.
Belgium
Flax processing infrastructure in Flanders supplies premium fiber grades to German automotive programs. EU Green Deal carbon border adjustments reshape supplier qualification criteria for cross-border compounders. The Ghent-Antwerp corridor concentrates textile technology expertise for bast fiber refinement and surface treatment.
United Kingdom
Construction sector procurement specifications increasingly weight bio-based content thresholds for structural applications. The national implementation of EU-derived product regulations maintains alignment with continental certification pathways. The Midlands region hosts emerging hemp cultivation trials aimed at reducing import dependency for composite reinforcement.
Natural Fiber Reinforced Composites Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct value chain positions. The vendor base stratifies into three tiers: integrated fiber-to-compound producers, independent compounders licensing dispersion technologies, and specialized equipment suppliers enabling process convergence. Consolidation pressure concentrates among mid-scale compounders lacking captive fiber supply or certified lifecycle data capabilities. Dominant competitive moves include backward integration into flax and hemp cultivation partnerships, plus technology licensing agreements for twin-screw compounding advances.
Among Swiss and German specialists, Bcomp and TECNARO GMBH occupy positions exemplifying divergent strategic archetypes. Bcomp anchors the premium fiber portfolio segment through its ampliTex flax reinforcement platform, while TECNARO GMBH represents deep specialization in lignin-based injection molding compounds. Green Dot Bioplastics sits within the broad-spectrum compounder tier, extending platform coverage across multiple cellulosic fiber types. Meshlin Composites Zrt. exemplifies the emerging Central European manufacturing footprint, leveraging geographic proximity to both French fiber supply and German automotive demand clusters.
| Leading Market Players |
|---|
| Meshlin Composites Zrt. |
| Bcomp |
| Polyvlies Franz Beyer GmbH |
| BUSS AG |
| INCA Renewable Technologies Inc. |
| TECNARO GMBH |
| GreenGran BN |
| Green Dot Bioplastics |
| FlexForm Technologies |
| Others |
Supply & Pricing Matrix
Flax fiber spot prices in northern France cascade through three distinct pricing tiers as compounders absorb cultivation volatility and pass through qualification premiums to automotive tier-one suppliers.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for injection-molding-grade compounds. Three-tier pricing structure across premium, standard, and economy levels separates DIBt-certified hemp formulations from uncertified construction grades and commodity jute blends. Cost compression in standard-tier PP-flax compounds is intensifying because twin-screw compounding equipment spreads across mid-scale producers. Consumer electronics OEMs exhibit highest price sensitivity due to competing recycled carbon fiber substitutes, while German automotive interior programs show lowest sensitivity given sustainability scorecard weightings.
Supply Chain Analysis
ECHA REACH authorization timelines for glass fiber sizing chemistries are gating supplier qualification and fragmenting procurement across multiple fiber sources. Geographic concentration rests on France for textile-grade flax, Germany for hemp cultivation expansion, and Belgium for fiber processing infrastructure. Raw material dependencies center on northern French bast fiber harvests, German lignin feedstock from pulp mills, and Dutch bio-based PP resin supply. Single-source vulnerability in premium flax varieties creates supply risk during adverse growing seasons. Distribution runs through tier-one automotive compounders holding approved supplier status with documented lifecycle footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as EU Green Deal carbon border adjustments entrench bio-based material thresholds across European manufacturing procurement.
For Market Incumbents: Cement backward integration into French flax cultivation partnerships to lock fiber supply before 2027 REACH reauthorization deadlines. Expand twin-screw compounding capacity in Baden-Württemberg to capture injection-molding grade demand from appliance OEMs. Recycled carbon fiber cost curves represent the primary substitution threat requiring performance differentiation through stiffness-to-weight marketing. For New Entrants and Emerging Players: Begin with Dutch public construction tenders where bio-based content minimums pre-qualify uncertified suppliers against incumbent glass fiber houses. Target thermoformed packaging applications for jute-kenaf blends where moisture sensitivity constraints are manageable through barrier design. Pursue equipment supplier partnerships for modular compression-injection systems enabling process pivoting without full line replacement. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale compounders lack captive fiber supply or CSRD-certified lifecycle data capabilities. Five-to-ten-year viability favors integrated fiber-to-compound producers with DIBt approval pathways and OEM sustainability qualification tracks. Watch ECHA substance evaluation timelines as inflection signals for accelerated substitution mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flax Cultivation | Captures northern French fiber supply before REACH reauthorization tightens qualification. |
| Twin-Screw Compounding Capacity Expansion | Enables injection-molding grade production for appliance and electronics OEM specifications. |
| DIBt Certification Investment | Unlocks German construction structural profile tenders with highest-margin growth potential. |
| CSRD Lifecycle Data Certification | Embeds suppliers into OEM Scope 3 reduction programs with veto authority over selection. |
| Hybrid Fiber Preform Development | Unifies flax stiffness with recycled PET impact resistance for automotive seating programs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate supply-side capacity and demand-side procurement patterns. Primary discussions included composite compounder technical directors, tier-one automotive supplier sustainability officers, ECHA regulatory affairs consultants, and Dutch construction procurement managers. Secondary validation drew from EU Green Deal implementation documents, ECHA substance evaluation registries, DIBt approval databases, and German automotive production statistics. Bottom-up fiber cultivation estimates and top-down composite consumption figures were reconciled across segmentation dimensions.
Segment-weighting approaches distributed value across processing technology, fiber type, and end-use application. Modeled dimensions included compression versus injection molding process categories, flax-hemp-jute-kenaf material splits, and automotive-construction-consumer goods-aerospace end-user segments. CAGRs were derived from production capacity deployment timelines and OEM program launch schedules. Forecast inputs incorporated REACH authorization deadlines and CSRD disclosure phase-in obligations.
Several conditions sit outside the modeled scope, including extreme weather impacts on northern European flax harvests and unilateral national deviations from EU construction product regulations. Forecasts reflect assumptions about ECHA reauthorization timelines and DIBt approval velocity. Deviation in carbon border adjustment implementation schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Silk Fabric Market
Natural Fibers
Down and Feather Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Gum Fiber Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Acoustic Cotton Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Silk Mask Market
Natural Fibers
Textile Staples Market
Natural Fibers
Green Fibers Market
Natural Fibers
Jute Bags Market
Natural Fibers
Thailand Textile Market
Natural Fibers
Global Cotton Market
Natural Fibers
Wood-Based Fibers Market
Natural Fibers
Indonesia Textiles Market