
 Acacia Fiber Powder Market | 2026-2036
Acacia Fiber Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Acacia Fiber Powder Market Outlook
Sudan is tilting the upstream supply landscape for acacia fiber powder through its dominant gum arabic belt cultivation. Nexira leverages backward integration into Sahelian sourcing corridors to secure raw material consistency. Kerry Group anchors its position through specialized prebiotic ingredient portfolios for European nutraceutical clients. ADM competes on manufacturing scale across multiple extraction and purification facilities.
Acacia fiber powder consists of dried, milled exudate from Acacia senegal or Acacia seyal trees, containing minimum 90% soluble dietary fiber with molecular weights ranging 200,000 to 600,000 Daltons, functioning primarily as a prebiotic bulking agent and emulsifier in food and pharmaceutical systems. Organic acacia commands premium positioning in nutraceutical channels where EFSA health claim scrutiny elevates traceability requirements. Dietary supplements represent the fastest-growing application segment as consumer microbiome awareness translates into formulated capsule and powder demand. Powder form maintains volume dominance due to superior blending characteristics in industrial-scale food processing operations.
FDA GRAS status and EFSA novel food evaluations shape ingredient approval timelines for new market entrants, while USDA organic certification and EU organic regulation constrain supply pool eligibility. Sudan's Gum Arabic Council and Chad's rural development ministries influence export quota structures that ripple through European and North American processor inventories. Stakeholders must monitor Sahelian rainfall patterns and corresponding harvest yields as the primary supply uncertainty variable.
Market Dynamics
Sudan's dominance in gum arabic cultivation concentrates upstream supply control, while EFSA's tightening Novel Food Regulation and clean-label certification requirements reshape downstream formulation standards across European nutraceutical channels.
Growth Catalysts
- Prebiotic formulation expansion:German and French nutraceutical formulators are accelerating acacia fiber inclusion in microbiome-targeted supplements, responding to consumer demand for digestive health solutions.
- EU organic regulation alignment:USDA organic certification and EU organic regulation create dual-qualified supply pools, unlocking premium channel access for compliant processors.
- Sahelian harvest zone concentration:Sudan's Gum Arabic Council export structures and Chad's rural development ministry quotas channel raw material flows toward established European and North American processors.
Market Restraints
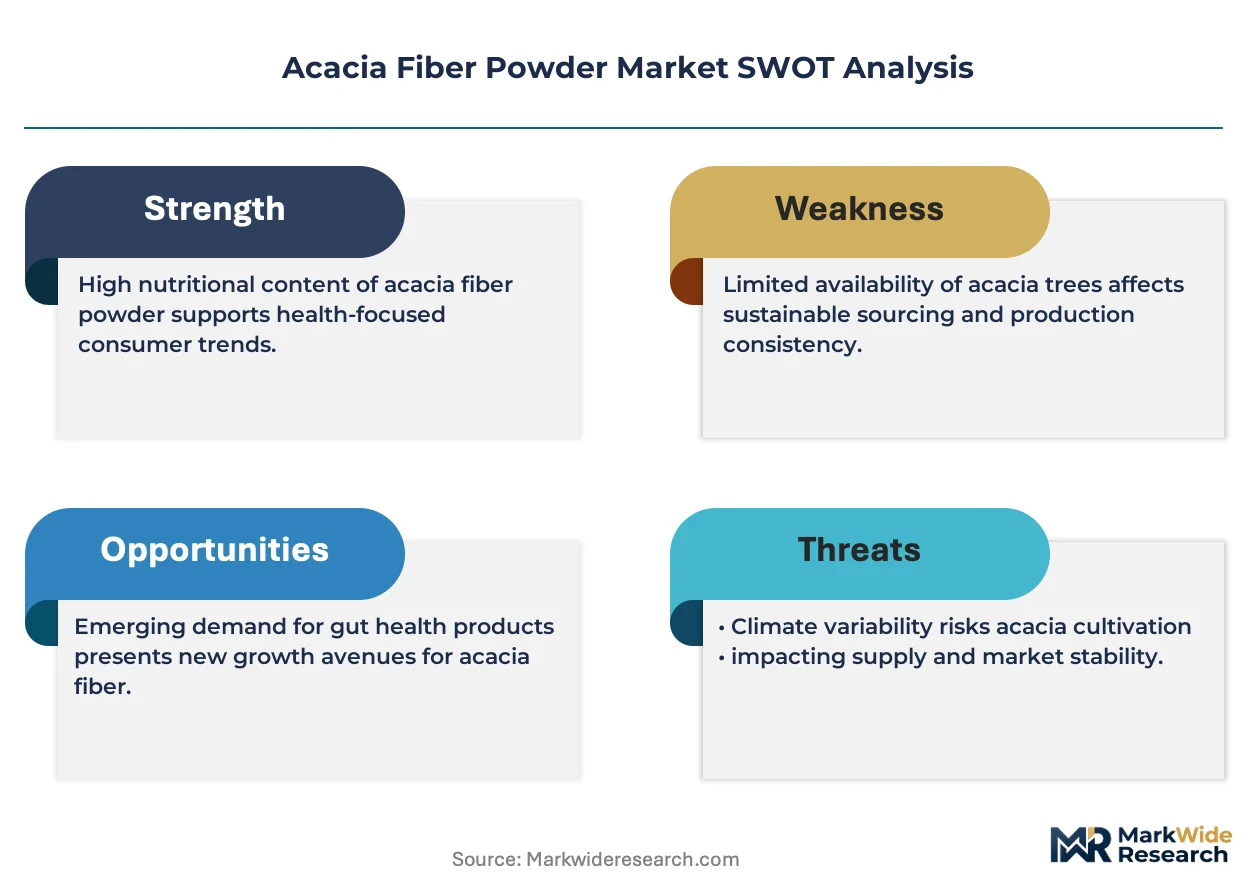
- Climate volatility exposure:Irregular Sahelian rainfall patterns threaten gum arabic yield consistency from Acacia senegal and Acacia seyal cultivation belts.
- Regulatory approval friction:FDA GRAS status petitions and EFSA novel food evaluations impose multi-year timelines on new market entrants seeking ingredient authorization.
- Plant-based fiber substitution:Inulin, resistant maltodextrin, and psyllium husk compete for prebiotic formulation slots in cost-sensitive food manufacturing segments.
Strategic Opportunities
- Capsule and powder supplement channels:Dietary supplements represent underpenetrated white space as microbiome awareness translates into direct-to-consumer formulated product demand.
- Clean-label bakery and beverage applications:Industrial food processors seek soluble fiber solutions that maintain emulsification performance without synthetic additive declarations.
- Pharmaceutical excipient qualification:USP-NF monograph alignment and EP compliance open tablet binder and controlled-release matrix applications for high-purity acacia grades.
Industry Challenges
- Traceability system implementation:EFSA health claim scrutiny and EU organic regulation mandate farm-to-finished-good documentation systems that strain mid-tier processor IT infrastructure.
- Extraction and purification capex cycles:Minimum 90% soluble dietary fiber purity requirements demand centrifugation and membrane filtration equipment investments that compress working capital availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acacia Fiber Powder Market |
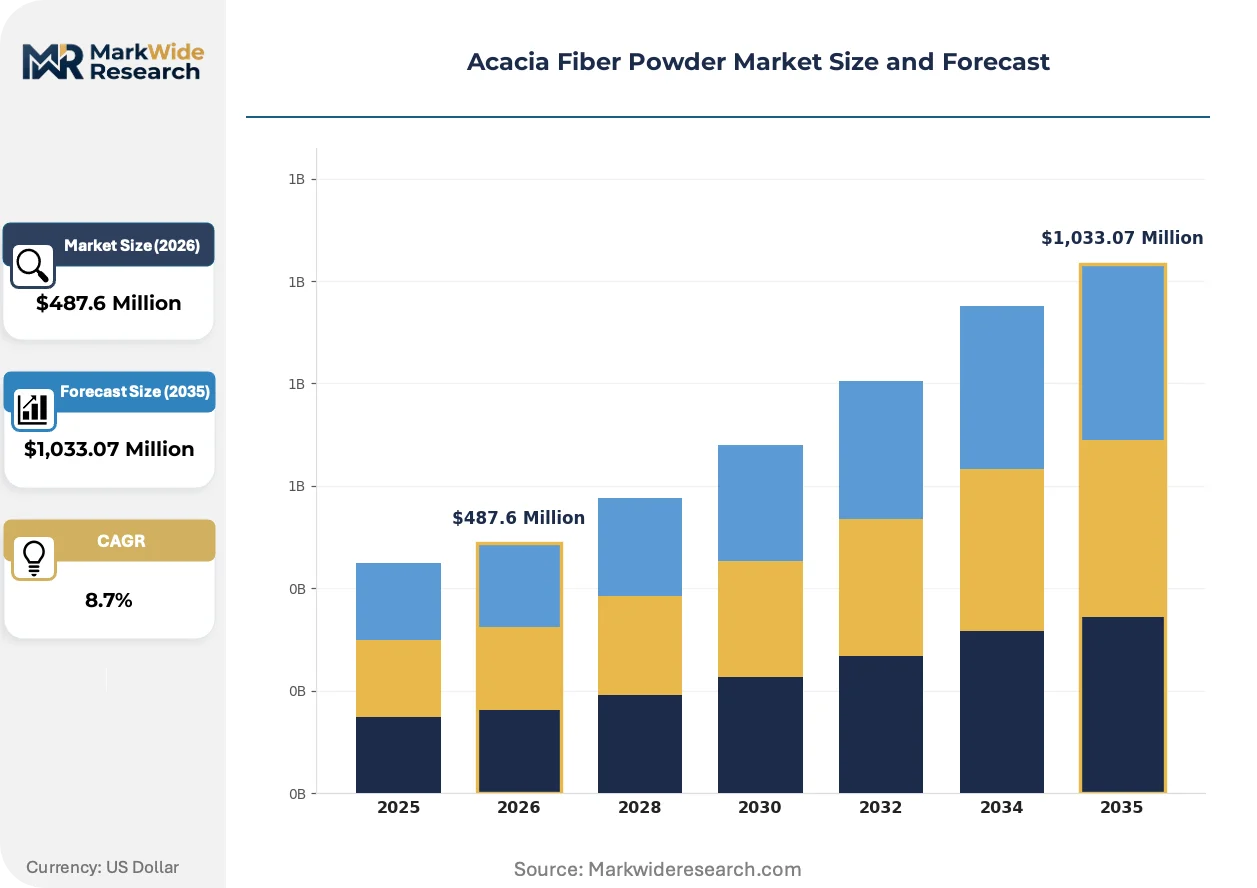
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Acacia, Conventional Acacia, Instant Acacia, Acacia Capsules Application: Nutraceuticals, Food & Beverages, Pharmaceuticals, Dietary Supplements Form: Powder, Granule, Tablet, Liquid End User: Consumers, Manufacturers, Retailers, Healthcare Providers |
| Companies Covered | Nexira, Ingredion Inc., Kerry Group, Alland & Robert, Gum Arabic Company, Sari Foods Company, ADM, Tate & Lyle, Lonza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acacia Fiber Powder Market Strategic Shifts
Acacia fiber powder markets are experiencing active restructuring through technology convergence in extraction methods, regulatory recalibration of health claim frameworks, and procurement model evolution among industrial buyers.
Spray-drying and encapsulation technology is hybridizing with traditional sun-drying methods to produce cold-water soluble acacia fiber grades with enhanced dispersibility characteristics. Nutraceutical contract manufacturers in Germany and France are adopting these hybrid-processed materials for effervescent and ready-to-drink formulations. The resulting supply bifurcation is compressing margins for conventional powder grades while creating premium positioning for standardized molecular weight fractions.
EFSA's 2024 updated guidance on prebiotic health claim substantiation requires human intervention studies demonstrating selective microbiome modulation. This regulatory tightening disqualifies generic fiber content claims and forces reformulators toward clinically validated dosage thresholds. Dietary supplement brands targeting Northern European markets are responding with dedicated clinical trial programs to secure Article 13.5 health claim authorization.
Long-term supply agreements are displacing spot-market purchasing among major European food manufacturers seeking EFSA-compliant traceability documentation. Industrial buyers now require certified organic chain-of-custody records from Sahelian harvest through final processing. This contractual shift concentrates procurement relationships with vertically integrated processors capable of delivering multi-year quota commitments from Sudanese and Chadian sourcing corridors.
Acacia Fiber Powder Market Segmentation
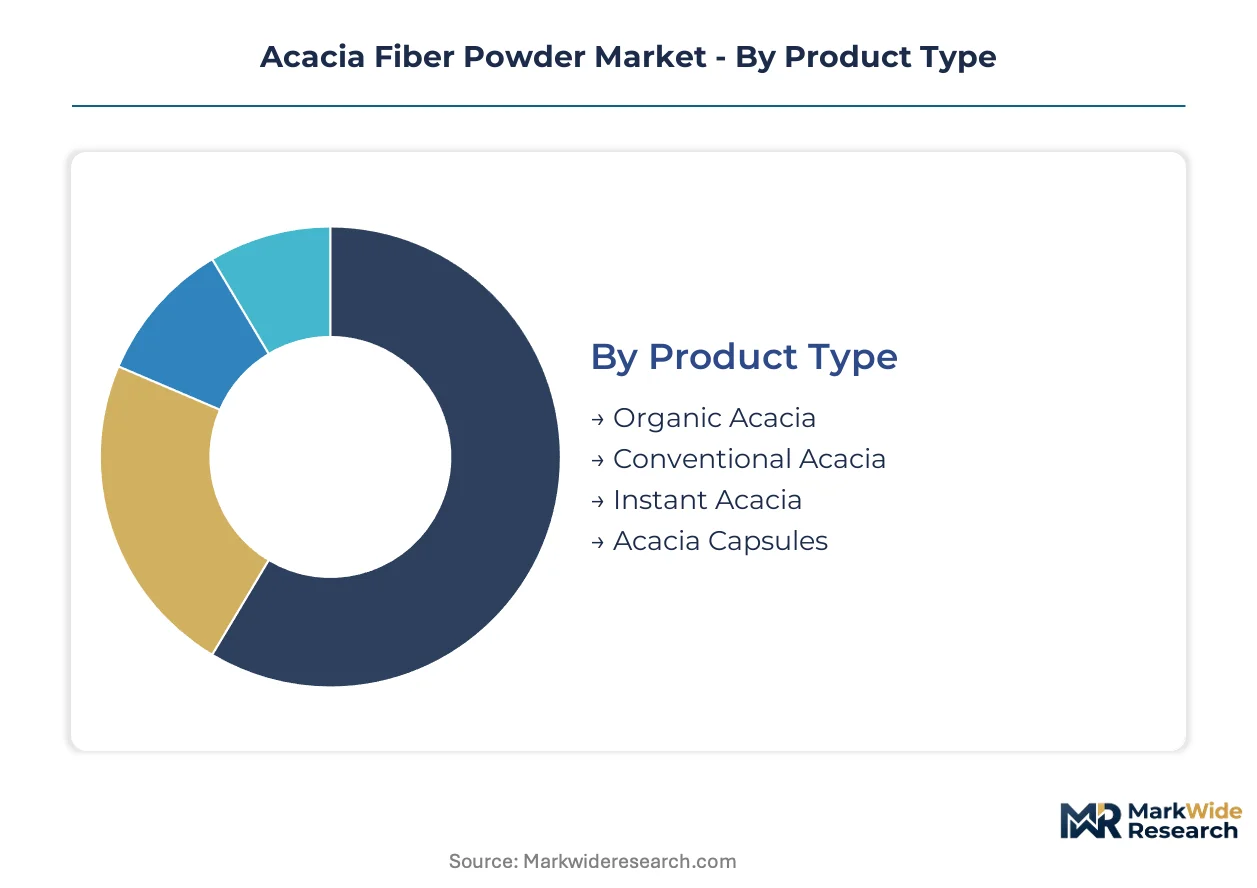
Segmentation in acacia fiber powder markets reveals divergent margin structures and inventory velocity patterns. Product certification tiers and formulation formats create distinct procurement cycles that reshape processor capacity allocation and distributor stocking strategies.
Product Type:
Inventory turns vary sharply across certification tiers, with organic-certified SKUs cycling faster through nutraceutical channels while conventional grades move through bulk food manufacturing on longer contract horizons.
- Organic Acacia:Minimum 95% organic content under USDA NOP and EU organic regulation, commanding premium positioning in EFSA-scrutinized health claim applications. German and French formulators concentrate procurement here for prebiotic supplement lines requiring dual-certification traceability.
- Conventional Acacia:Standard gum arabic-derived fiber meeting minimum 90% soluble dietary fiber specification without organic certification. Industrial food processors in cost-sensitive bakery and beverage segments anchor volume demand for this grade.
- Instant Acacia:Spray-dried or agglomerated grades engineered for cold-water dispersibility without mechanical shear.
- Acacia Capsules:Pre-encapsulated dosage forms targeting direct-to-consumer supplement brands seeking manufacturing outsourcing.
Conventional Acacia anchors the volume base while Organic Acacia gains share at the steepest rate.
Application:
End-use concentration determines formulation complexity and regulatory pathway investment, with pharmaceutical qualification timelines stretching years beyond food-grade approvals.
- Nutraceuticals:Prebiotic formulations targeting microbiome modulation with EFSA Article 13.5 health claim substantiation requirements. German contract manufacturers drive specification tightening toward clinically validated dosage thresholds.
- Dietary Supplements:Capsule, powder, and ready-to-drink formats for direct-to-consumer digestive health positioning. This segment expands most quickly as microbiome awareness translates into formulated product demand.
- Food & Beverages:Clean-label emulsification and soluble fiber fortification in bakery, dairy, and beverage systems.
- Pharmaceuticals:USP-NF and EP-compliant excipient grades for tablet binding and controlled-release matrices.
Nutraceuticals command the highest purity premiums while Dietary Supplements deliver the steepest volume expansion trajectory.
Form:
Processing characteristics and dissolution kinetics segment procurement relationships, with powder maintaining industrial dominance against emerging convenience formats.
- Powder:Milled and classified acacia fiber with standardized particle size distribution for homogeneous blending in high-throughput food processing. Superior flow characteristics and bulk density control sustain volume concentration.
- Liquid:Pre-hydrated acacia solutions or concentrates for ready-to-drink beverage manufacturing and reduced handling operations.
- Granule:Agglomerated grades for reduced dusting and improved handling in manual blending operations.
- Tablet:Direct-compression ready granulations for pharmaceutical and supplement tableting lines.
Powder dominates manufacturing throughput while Liquid formats climb fastest in beverage application development.
End User:
Decision-making authority and technical specification involvement separate procurement patterns across the value chain.
- Manufacturers:Industrial food, pharmaceutical, and supplement processors defining raw material specifications and conducting supplier audits. Technical qualification requirements and multi-year contract structures concentrate purchasing power.
- Consumers:Direct purchasers of finished supplement and functional food products, influencing brand formulation decisions through microbiome health positioning preferences.
- Retailers:Grocery, pharmacy, and e-commerce channels setting clean-label and organic certification requirements for shelf placement.
- Healthcare Providers:Clinicians and dietitians recommending prebiotic interventions, driving professional-grade supplement demand.
Manufacturers control upstream specification authority while Consumers reshape downstream brand positioning fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sudan and Chad concentrate upstream gum arabic cultivation, while European nutraceutical demand and North American clean-label food manufacturing anchor downstream value capture. Procurement relationships increasingly favor vertically integrated processors capable of delivering certified organic chain-of-custody documentation from Sahelian harvest through final formulation.
United States
FDA GRAS status petitions and USDA organic certification requirements shape ingredient approval pathways for acacia fiber entering dietary supplement and food fortification channels. Clean-label bakery and beverage manufacturers in Chicago and Minneapolis-St. Paul metropolitan areas drive soluble fiber demand for emulsification applications. Major processors maintain inventory buffers against Sahelian supply volatility.
Germany
Nutraceutical contract manufacturers in Bavaria and North Rhine-Westphalia accelerate acacia fiber inclusion in microbiome-targeted prebiotic formulations. EFSA Novel Food Regulation compliance and Article 13.5 health claim substantiation requirements elevate purity and traceability benchmarks. Cologne and Frankfurt clusters specialize in clinically validated dosage formulations for Northern European markets.
France
Paris and Lyon-based formulators expand acacia fiber procurement for organic-certified supplement lines targeting EFSA-scrutinized health claim applications. ANSM oversight of novel food ingredients intersects with EU organic regulation dual-certification requirements. Alland & Robert maintains processing operations in Normandy serving European nutraceutical clients.
Sudan
The Gum Arabic Council export quota structures channel raw material flows toward established European and North American processors. Kordofan and Darfur cultivation belts face climate volatility from irregular Sahelian rainfall patterns. Harvest yield fluctuations ripple through downstream processor inventory planning cycles.
Chad
Rural development ministry quotas and Sahelian cultivation corridor expansion support upstream supply diversification beyond Sudanese dominance. N'Djamena-based export coordination structures channel gum arabic toward European processors seeking certified organic traceability. Climate adaptation investments target yield stability in southern cultivation zones.
Acacia Fiber Powder Market Competitive Environment
Vertically integrated specialists and diversified ingredient conglomerates split the market into distinct capability tiers. Sudan's Gum Arabic Company anchors upstream raw material control through Sahelian sourcing corridors, while European and North American processors compete on extraction scale and certification compliance. Three archetypes dominate: backward-integrated harvest-to-powder operators, nutraceutical-focused formulation specialists, and diversified food ingredient conglomerates with multi-fiber portfolios. Competitive moves concentrate on long-term supply agreement structures and dual organic certification acquisition to unlock premium channel access.
Among French specialists, Nexira and Alland & Robert exemplify the nutraceutical-formulation archetype through European processing presence and EFSA-aligned health claim capabilities. Ingredion Inc. represents the diversified conglomerate model with multi-fiber ingredient portfolios spanning prebiotic and clean-label applications. Kerry Group anchors the formulation-specialist tier through dedicated prebiotic ingredient divisions serving German and French contract manufacturing demand.
| Leading Market Players |
|---|
| Nexira |
| Ingredion Inc. |
| Kerry Group |
| Alland & Robert |
| Gum Arabic Company |
| Sari Foods Company |
| ADM |
| Tate & Lyle |
| Lonza |
| Others |
Value Chain & Pricing Dynamics
Port Sudan-to-Rotterdam freight corridors transmit Sahelian harvest volatility directly into European processor cost bases, compressing margins on conventional grades while amplifying premium capture for dual-certified organic tiers. This logistics-cost dynamic intertwines with Sudan's export quota structures to create divergent pricing power across certification levels.
Pricing Analysis
EFSA Novel Food Regulation dictates the pricing tier structure by elevating traceability documentation costs for health claim-eligible grades. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified nutraceutical grades from conventional food-grade powders and unstandardized raw gum. Cost compression in conventional tiers is intensifying because inulin and resistant maltodextrin substitution threatens volume contracts. Industrial food manufacturers exhibit highest price sensitivity, while German nutraceutical formulators absorb premiums for EFSA-compliant chain-of-custody documentation.
Supply Chain Analysis
Climate volatility across Sudan's Kordofan belt and Chad's southern cultivation zones dominates supply risk exposure for downstream processors. Raw material flows draw from Acacia senegal and Acacia seyal harvest belts, membrane filtration equipment, and centrifugation purification systems. Single-source vulnerability concentrates in Sudan's Gum Arabic Council quota structures, where export authorization bottlenecks ripple through European inventory cycles. Distribution runs through vertically integrated harvest-to-powder operators with captive Sahelian sourcing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inulin substitution in cost-sensitive prebiotic formulations threatens acacia fiber's volume base, compelling incumbents to defend through certification differentiation and clinical validation investments.
For Market Incumbents: Harden EFSA Article 13.5 health claim portfolios through sponsored human intervention studies demonstrating selective microbiome modulation. Deepen upstream control over Sudanese and Chadian cultivation corridors via long-term quota commitments with the Gum Arabic Council. This dual maneuver raises substitution barriers against plant-based fiber competitors while securing raw material preference during harvest shortfalls. For New Entrants and Emerging Players: Instant acacia grades for ready-to-drink beverage manufacturing represent the most penetrable entry point, as German and French contract manufacturers seek cold-water soluble alternatives to conventional powder processing. Target pharmaceutical excipient qualification as a secondary channel, where USP-NF monograph alignment commands scarcity premiums. A technical-sales hybrid go-to-market model—combining formulation support with certified organic supply—accelerates customer acquisition against established distributors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food ingredient conglomerates with underperforming prebiotic divisions lacking Sahelian sourcing integration. Position acquisitions around five-to-ten-year windows where climate adaptation investments in Chad yield harvest stability premiums. Monitor EFSA prebiotic health claim authorization timelines as the critical inflection signal—successful Article 13.5 approvals for portfolio companies trigger multiple expansion in Northern European nutraceutical channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sahelian Sourcing | Captive supply from Sudan's Gum Arabic Council quotas insulates processors against harvest volatility. |
| EFSA Health Claim Clinical Trial Investment | Article 13.5 authorization unlocks premium positioning in German and French nutraceutical channels. |
| Spray-Drying Capacity Expansion | Instant-grade production captures ready-to-drink beverage formulation demand from contract manufacturers. |
| Dual Organic Certification Acquisition | USDA NOP and EU organic regulation compliance opens premium channel access for nutraceutical clients. |
| Pharmaceutical Excipient Qualification | USP-NF monograph alignment creates tablet binder applications with higher purity thresholds. |
Study Parameters
A standing panel of nutraceutical formulation directors, Sahelian gum arabic exporters, membrane filtration equipment suppliers, and EFSA regulatory consultants provided ongoing calibration throughout the study period. Primary interviews with German contract manufacturers and French organic certification auditors combined with secondary validation from EU organic regulation filings, Sudanese export statistics, and EFSA novel food guidance documents. Bottom-up volume modeling across certification tiers and application segments triangulated against top-down ingredient demand estimates from food and pharmaceutical channels.
Scenario-bracketing around Sahelian rainfall variability and EFSA health claim authorization timelines framed the analytical approach across the projection horizon. Segmentation dimensions modeled include certification tier, application category, form factor, and end-user decision authority. CAGRs derived from weighted average growth contributions across these dimensions, with specific inputs from prebiotic supplement penetration rates and clean-label bakery reformulation cycles.
Stress conditions across Kordofan drought frequency, EU organic regulation enforcement intensity, and inulin price competitiveness were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding harvest yield stability and regulatory approval timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Jute Bags Market
Natural Fibers
Jute Market
Natural Fibers
Apple Fiber Market
Natural Fibers
Textile Staples Market
Natural Fibers
Cellulose Market
Natural Fibers
North America Alpaca Fiber Market
Natural Fibers
Global Cellulosic Man-Made Fibers Market
Natural Fibers
Silk Market
Natural Fibers
Global Alpaca Fiber Market
Natural Fibers
Silk Stocking Market
Natural Fibers
Gum Fiber Market
Natural Fibers
Cellulose Fiber Market
Natural Fibers
Fenugreek Fiber Market
Natural Fibers
Acoustic Cotton Market
Natural Fibers
Organic Cotton Market
Natural Fibers
Asia-Pacific Alpaca Fiber Market