
 Global AI and Machine Learning Operationalization Software Market | 2026-2036
Global AI and Machine Learning Operationalization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global AI and Machine Learning Operationalization Software Market Foresight
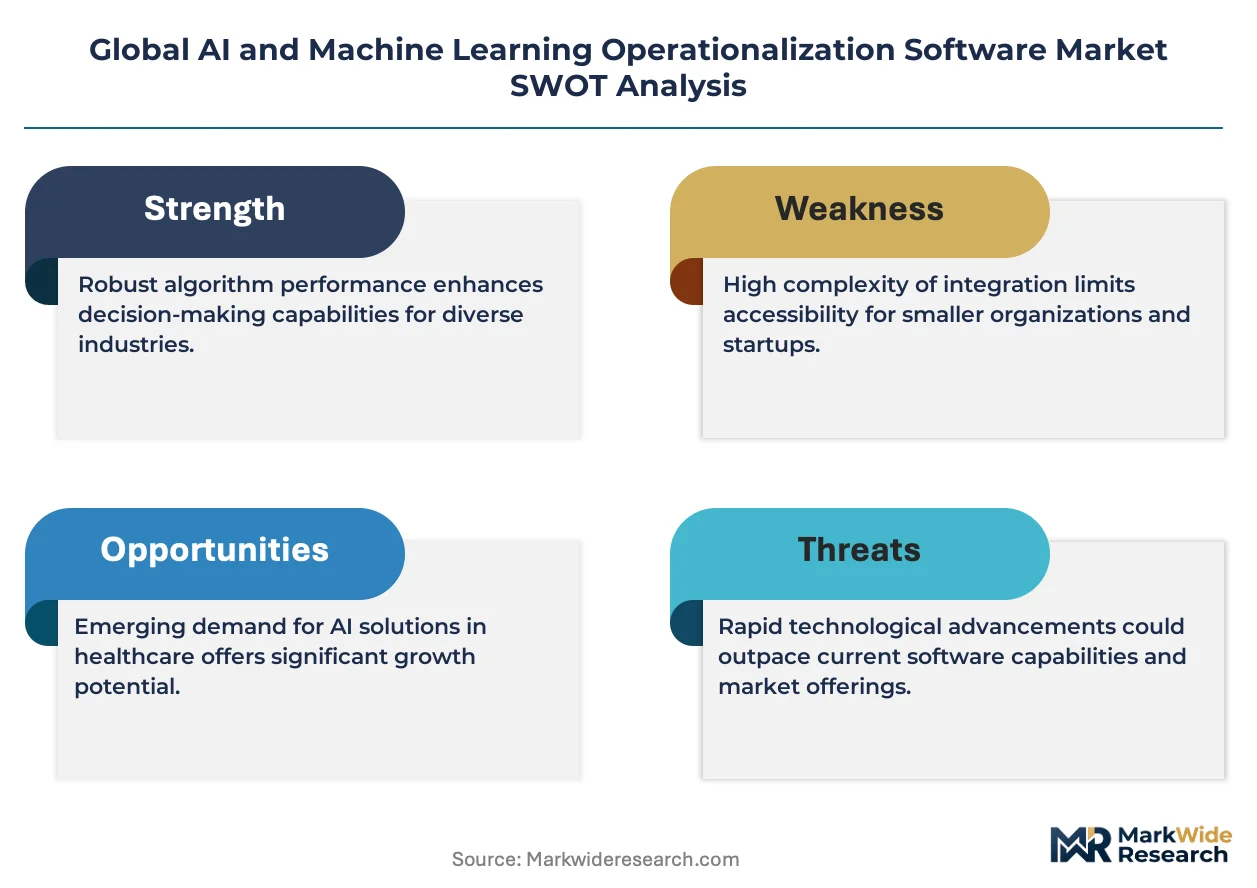
Healthcare provider demand for real-time inference infrastructure is hardening as clinical AI workflows move from research into production environments. NVIDIA Corporation dominates GPU-accelerated serving stacks for low-latency medical imaging pipelines. Microsoft Corporation leverages its Azure ML managed endpoints to anchor enterprise contracts with hospital networks. IBM competes through Watson OpenScale governance modules that address audit requirements in regulated diagnostics.
AI and machine learning operationalization software encompasses the tooling, runtime environments, and governance layers that convert trained models into sustained production services, typically requiring container orchestration, A/B testing frameworks, and drift detection algorithms operating at millisecond-scale latency. Cloud-based deployment captures the dominant margin pool as hyperscalers bundle inferencing with storage and security primitives. Workflow automation within solution types is accelerating fastest where MLOps teams seek to compress release cycles from weeks to hours. Feature engineering remains comparatively mature, with established vendors defending entrenched data pipeline integrations.
The EU AI Act imposes conformity assessments on high-risk AI systems, directly expanding demand for monitoring and governance modules that provide audit trails and explainability documentation. The FDA's software-as-a-medical-device framework shapes validation requirements for clinical operationalization platforms in the United States. China's SAMR algorithm recommendation provisions add compliance overhead for multinational deployments. Stakeholders must weigh regulatory fragmentation against unified platform architectures when selecting vendor stacks for cross-border model serving.
Market Dynamics
The EU AI Act's conformity assessment mandate is compressing vendor roadmaps as enterprises race to embed audit-ready governance layers before enforcement deadlines.
Growth Catalysts
- EU AI Act compliance mandates:High-risk AI system classification drives procurement of explainability and drift-monitoring modules across financial services and healthcare diagnostics.
- Container orchestration maturation:Kubernetes-native serving infrastructure slashes deployment latency from weeks to hours for cloud-native enterprises in United States banking.
- Real-time clinical AI workflows:Medical imaging pipelines demand GPU-accelerated inference stacks as research models migrate into production radiology departments.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in AI accelerators creates single-source vulnerability for low-latency serving stacks.
- Cross-border regulatory friction:China's SAMR algorithm recommendation provisions impose divergent compliance architectures on multinational deployments.
- Legacy system integration costs:Mainframe-bound financial institutions face prohibitive re-platforming expenses for hybrid cloud operationalization.
Strategic Opportunities
- India's PLI scheme for AI:Domestic data center buildouts create demand for localized model serving infrastructure outside hyperscaler control.
- FDA software-as-medical-device framework:Validation-ready operationalization platforms capture hospital network contracts through pre-cleared deployment pathways.
- Edge inference convergence:5G MEC infrastructure and federated learning protocols enable millisecond-latency serving without cloud egress.
Industry Challenges
- MLOps talent scarcity:Production-grade ML engineering expertise concentrates in United States and European technology hubs, inflating compensation premiums.
- Model versioning complexity:Continuous training pipelines generate audit trail fragmentation under EU AI Act documentation requirements.
- Multi-cloud orchestration overhead:Enterprises struggle to maintain consistent governance posture across AWS, Azure, and GCP serving endpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AI and Machine Learning Operationalization Software Market |
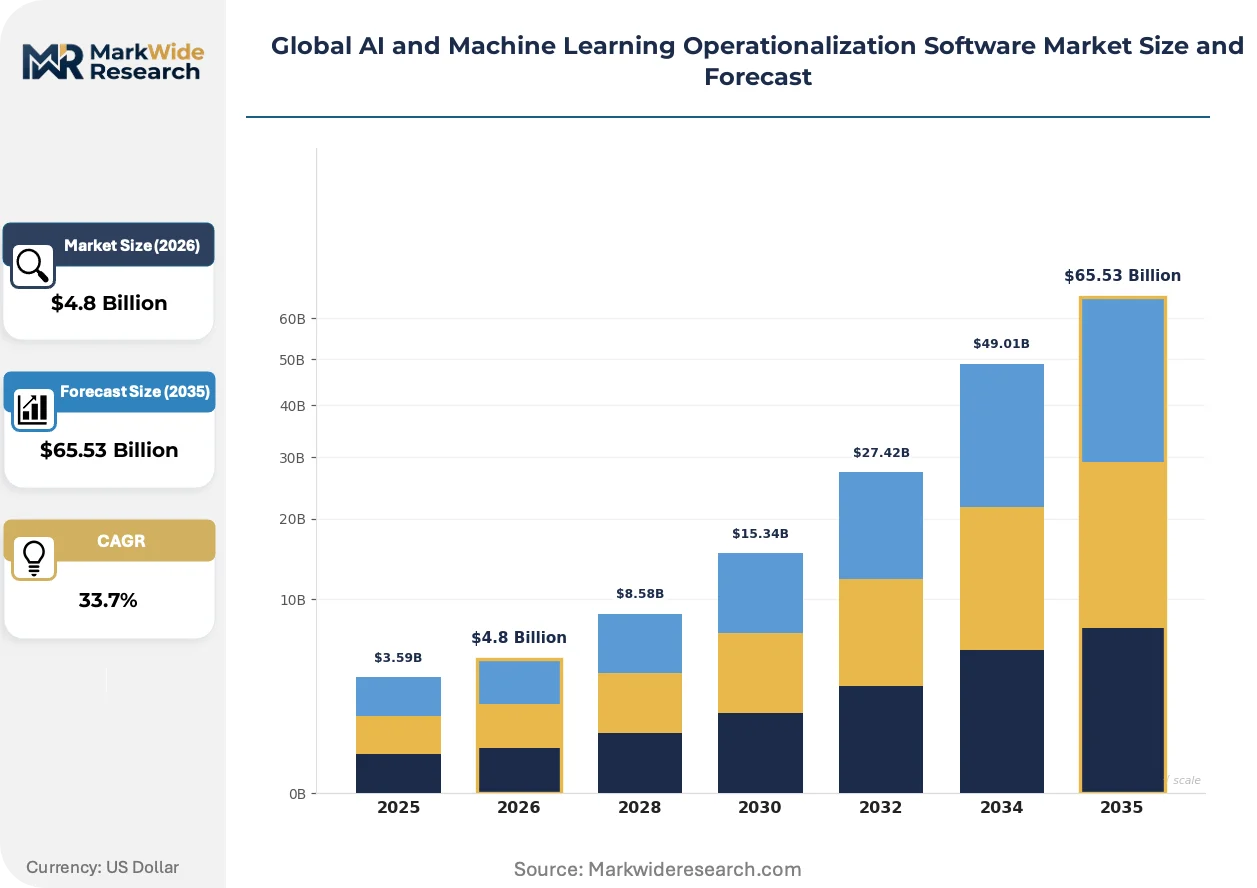
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $65.53 Billion |
| CAGR (2026 – 2036) | 33.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution Type: Model Management, Data Preparation, Workflow Automation, Monitoring & Governance, Feature Engineering Use Case: Fraud Detection, Predictive Maintenance, Customer Segmentation, Risk Analysis, Demand Forecasting End User Industry: Banking, Telecommunications, Manufacturing, Insurance, Energy, Pharmaceuticals |
| Companies Covered | Amazon Web Services, DataRobot, Databricks, Hewlett Packard Enterprise Company, NVIDIA Corporation, IBM, Google LLC, SAS Institute, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AI and Machine Learning Operationalization Software Market Shifts & Advancements
Model serving architectures are converging around unified control planes that collapse the gap between experimentation environments and production infrastructure.
Vector databases specialized for embedding storage and retrieval are consolidating the feature store layer into serving stacks. Healthcare AI teams in United States hospital networks adopt Pinecone and Weaviate to cut retrieval latency for clinical decision support. This consolidation compresses vendor count in the operationalization stack from five to three layers.
The EU AI Act's risk-based classification system forces model registry vendors to embed conformity assessment workflows directly into deployment pipelines. Financial institutions in Germany and France must demonstrate traceability across model versions to national regulators. High-risk diagnostic AI systems face mandatory human-in-the-loop verification gates before automated inference authorization.
Enterprise procurement of operationalization software now prioritizes consumption-based pricing over perpetual licenses as inferencing volumes fluctuate seasonally. United States cloud-native enterprises negotiate burst capacity clauses for quarterly financial reporting spikes. This shift displaces upfront capital commitments with metered serving costs tied to actual inference throughput.
Global AI and Machine Learning Operationalization Software Market Segmentation
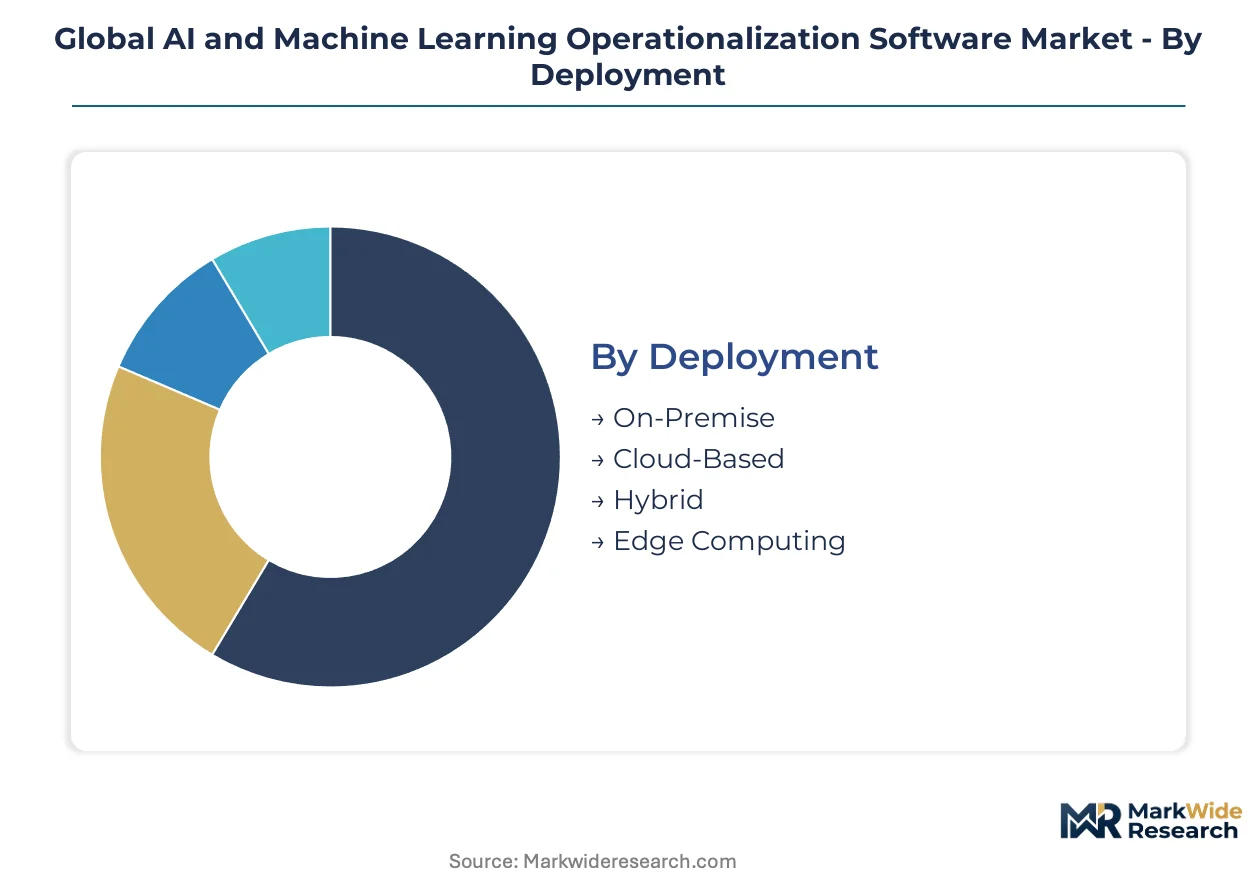
Operationalization software buyers diverge sharply across infrastructure maturity, regulatory exposure, and latency requirements. Deployment modality determines total cost of ownership more than any other dimension, while solution type reflects where enterprises sit on the MLOps maturity curve.
Deployment:
Cost tier separates buyers in this category, with hyperscaler-native enterprises pursuing fundamentally different economics than regulated institutions managing sovereign data.
- Cloud-Based:Hyperscaler-managed Kubernetes and serverless inference dominate new procurement. United States banking and healthcare networks anchor demand through Azure ML and AWS SageMaker endpoints, driven by consumption-based pricing flexibility and burst capacity for quarterly reporting spikes.
- On-Premise:Air-gapped GPU clusters serve classified government workloads and pharmaceutical manufacturing quality systems. German automotive suppliers and French defense contractors maintain these deployments under EU data sovereignty mandates and FDA 21 CFR Part 11 validation requirements.
- Hybrid:Split inference architectures route sensitive preprocessing on-premise while leveraging cloud burst for training. Energy sector operators in Texas and Alberta favor this model for operational technology isolation.
- Edge Computing:5G MEC nodes and factory-floor inference hardware cut milliseconds from industrial vision pipelines. Japanese automotive plants and South Korean electronics assembly lines drive specialized hardware procurement.
Cloud-Based deployments lead volumes today; Edge Computing is gaining share fastest.
Solution Type:
Application criticality shapes purchasing patterns, with governance modules commanding premium pricing where regulatory deadlines loom.
- Monitoring & Governance:Drift detection, bias auditing, and explainability documentation layers embed directly into deployment pipelines. EU AI Act conformity assessments in France and Germany are forcing financial institutions to procure these modules ahead of enforcement windows.
- Workflow Automation:CI/CD pipelines for model retraining compress release cycles from weeks to hours. Cloud-native enterprises in United States technology and banking sectors prioritize these tools to saturate feature velocity advantages.
- Model Management:Version registries and artifact storage provide lineage tracking for audit defense. Pharmaceutical companies preparing FDA software-as-medical-device submissions anchor this segment.
- Data Preparation:Feature stores and transformation pipelines remain comparatively mature, with established vendors defending entrenched data integrations in legacy enterprise data warehouses.
- Feature Engineering:Vector database consolidation into serving stacks is displacing standalone feature store procurement among healthcare AI teams running clinical decision support.
Monitoring & Governance leads volumes today; Workflow Automation is expanding most quickly.
Use Case:
Customer type determines latency tolerance and explainability depth, with real-time inference requirements fragmenting vendor selection criteria.
- Fraud Detection:Sub-100 millisecond inference demands drive GPU-accelerated serving stacks in United States card networks and European open banking platforms. Transaction volume spikes during holiday periods necessitate elastic scaling architectures.
- Predictive Maintenance:Industrial sensor fusion models run at the edge in German automotive plants and Japanese steel mills, prioritizing uptime guarantees over cloud cost optimization.
- Risk Analysis:Credit and underwriting models in Indian banking and Brazilian insurance require documented fairness metrics under emerging central bank guidance.
- Customer Segmentation:Batch inference workloads tolerate higher latency, allowing cost-optimized CPU-based serving in retail and telecommunications marketing operations.
- Demand Forecasting:Supply chain models in consumer goods and energy trading blend historical time-series with external signals, demanding specialized feature engineering for seasonality decomposition.
Fraud Detection leads volumes today; Predictive Maintenance shows the steepest expansion trajectory.
End User Industry:
Margin concentration and regulatory scrutiny create divergent procurement patterns across verticals.
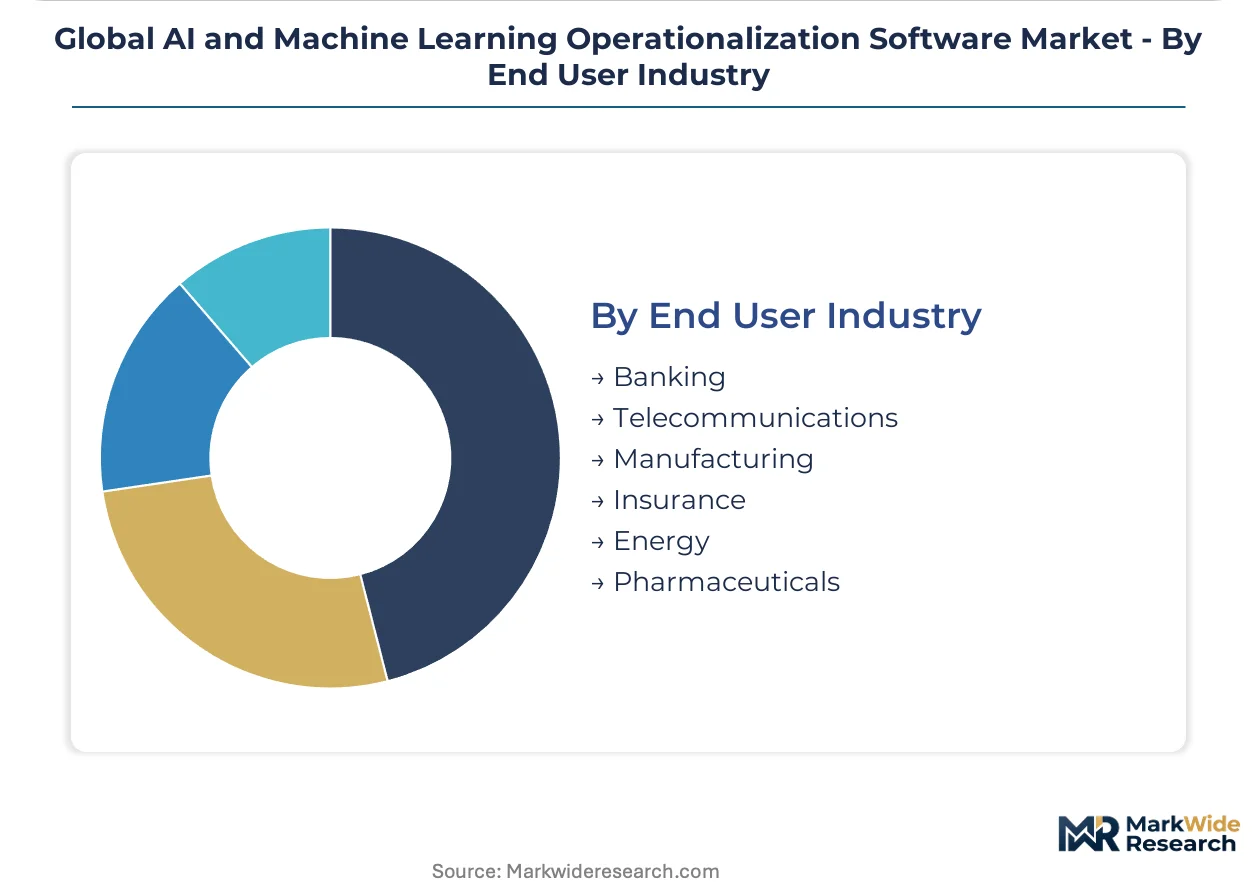
- Banking:Real-time transaction scoring and credit decisioning drive the highest inference volume intensity. United States and European institutions face overlapping SEC, ECB, and EU AI Act compliance architectures.
- Pharmaceuticals:FDA software-as-medical-device validation requirements shape procurement of pre-cleared operationalization platforms for diagnostic imaging and clinical decision support.
- Insurance:Claims automation and actuarial model governance concentrate demand in German and French markets under Solvency II and emerging AI liability frameworks.
- Manufacturing:Vision-based quality inspection and predictive maintenance anchor edge deployment investment in Japan, Germany, and South Korea.
- Telecommunications:Network optimization and customer churn models run at hyperscale, with Indian and Brazilian operators driving emerging market demand.
- Energy:Grid balancing and trading algorithms require sub-second inference in Texas, Alberta, and Australian power markets with volatile renewable intermittency.
Banking leads volumes today; Pharmaceuticals is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing operationalization software procurement toward jurisdictions with clearer compliance pathways. Enterprises in the United States and Germany absorb premium governance costs to secure audit-ready deployment pipelines, while emerging clusters in India and Singapore exploit cost-of-compliance gaps to capture cloud-native workloads.
United States
FDA software-as-medical-device frameworks and SEC algorithmic trading rules drive hospital network and banking procurement of validation-ready platforms. Cloud-native enterprises in New York and San Francisco anchor hyperscaler-managed Kubernetes adoption for real-time fraud detection pipelines.
Germany
EU AI Act conformity assessments and automotive industry edge-computing requirements concentrate demand in Stuttgart and Munich industrial corridors. German financial institutions in Frankfurt embed drift-monitoring modules ahead of enforcement deadlines for high-risk credit decisioning systems.
India
PLI scheme incentives for domestic data center buildouts and RBI emerging guidance on AI governance attract localized model serving infrastructure outside hyperscaler control. Bengaluru and Hyderabad technology clusters host MLOps talent pools serving banking and telecommunications operators.
Singapore
Monetary Authority of Singapore's Veritas framework for responsible AI and sovereign cloud mandates position the city-state as a regional hub for cross-border compliance architecture. Financial institutions deploy hybrid inference stacks to satisfy data residency requirements across ASEAN markets.
United Kingdom
Financial Conduct Authority expectations on algorithmic accountability and NHS AI deployment guidelines shape procurement in London and Cambridge clusters. UK banking networks prioritize explainability documentation layers for automated underwriting and customer segmentation models.
Global AI and Machine Learning Operationalization Software Market Competitive Landscape
Platform consolidation dominates the current landscape as hyperscalers bundle inferencing with adjacent cloud primitives. The vendor base separates into three tiers: full-stack cloud providers, specialized MLOps independents, and hardware-anchored serving stack vendors. Strategic archetypes include governance-module specialists, workflow-automation pure-plays, and GPU-accelerated inference stack providers. Competitive moves center on consumption-based pricing restructuring and embedded compliance workflow integration.
Within the hyperscaler tier, Amazon Web Services, Microsoft Corporation, and Google LLC exemplify platform consolidation strategies that collapse experimentation-to-production gaps through unified control planes. These entities anchor enterprise contracts via managed endpoint services and burst capacity clauses. Specialized independents occupy positions emphasizing modular governance and cross-cloud orchestration capabilities.
| Leading Market Players |
|---|
| Amazon Web Services |
| DataRobot |
| Databricks |
| Hewlett Packard Enterprise Company |
| NVIDIA Corporation |
| IBM |
| Google LLC |
| SAS Institute |
| Microsoft Corporation |
| Others |
Supply & Pricing Matrix
Captive GPU fabrication at NVIDIA anchors supply-side pricing power across low-latency inference stacks, while hyperscaler bundling of Kubernetes orchestration with storage primitives compresses standalone software margins. This vertical integration dynamic forces independent MLOps vendors to differentiate through governance module premiums or cede ground to cloud-native consumption models.
Pricing Analysis
Direct-to-OEM discount structures dominate enterprise procurement as hospital networks and banking consortia negotiate burst capacity clauses tied to quarterly reporting spikes. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated diagnostic pipelines from experimental research workloads. Cost compression in the standard tier is intensifying because hyperscalers are absorbing orchestration tooling into base infrastructure bundles. Cloud-native enterprises in United States technology clusters exhibit the lowest price sensitivity, while legacy mainframe-bound financial institutions in Europe face prohibitive re-platforming costs that amplify total cost of ownership sensitivity.
Supply Chain Analysis
FDA software-as-medical-device qualification and EU AI Act conformity certification gates concentrate specialized operationalization platform development in the United States, Germany, and India. NVIDIA GPU accelerators, ARM-based edge inference chips, and vector database software constitute critical input dependencies. Single-source vulnerability in AI accelerators exposes serving stack vendors to allocation constraints during demand surges. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams, with channel partners capturing margin only in mid-market segments lacking internal MLOps expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act enforcement timeline compounds procurement urgency for audit-ready governance modules, converting regulatory compliance from cost center to competitive differentiator across financial services and healthcare diagnostics.
For Market Incumbents: Deepen embedded compliance workflow integration to defend against modular governance pure-plays threatening to unbundle the serving stack. Expand GPU-accelerated inference capacity in India and Singapore data centers to capture PLI scheme incentives and sovereign cloud demand. Fortify against hyperscaler bundling by anchoring hospital network contracts through pre-cleared FDA validation pathways. For New Entrants and Emerging Players: Launch via consumption-based pricing models targeting European mid-market financial institutions racing to meet EU AI Act deadlines. Penetrate the German automotive edge-computing segment where 5G MEC infrastructure creates greenfield deployment opportunities. Position through explainability-as-a-service offerings that collapse conformity assessment overhead for resource-constrained compliance teams. For Investors and Strategic Acquirers: Roll-up economics work for specialized governance-module vendors because regulatory fragmentation across FDA, EU AI Act, and China's SAMR provisions prevents hyperscalers from delivering one-size-fits-all compliance solutions. Target acquisition profiles emphasizing drift-detection and bias-auditing tooling with existing deployments in Frankfurt and Paris banking networks. Monitor enforcement action velocity from EU national regulators as the signal to watch for demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified control planes collapsing experimentation-to-production gaps anchor Azure ML and AWS SageMaker enterprise retention. |
| Acquisition of Specialist Firm | Vector database consolidation into serving stacks displaces standalone feature store procurement among United States hospital networks. |
| Regulatory Compliance Module | Embedded conformity assessment workflows capture EU AI Act-driven procurement from German and French financial institutions. |
| Geographic Expansion | Localized model serving infrastructure in Bengaluru and Hyderabad exploits India's PLI scheme outside hyperscaler control. |
| Strategic Partnership | 5G MEC infrastructure alliances with Japanese automotive plants enable millisecond-latency edge inference without cloud egress. |
Research Methodology
Direct dialogue with MLOps platform engineers, hospital IT procurement officers, regulatory affairs leads at pharmaceutical manufacturers, and financial services compliance directors grounded qualitative assessment of deployment friction and governance module prioritization. Secondary validation drew from SEC hyperscaler capex disclosures, FDA software-as-medical-device submission databases, EU AI Act implementation guidance from national regulators, and cloud infrastructure spending trackers. Bottom-up vendor revenue estimates and top-down enterprise IT budget allocations were triangulated against reported consumption metrics.
Segment-level projections across deployment modality, solution type maturity curve positioning, and end-user industry regulatory exposure were generated through the analytical framework. CAGRs were derived from inference volume elasticity models calibrated to historical cloud infrastructure consumption patterns and compliance-driven procurement acceleration signals. Key inputs included GPU supply allocation forecasts, EU AI Act enforcement timeline assumptions, and hospital network EMR integration complexity indices.
Several conditions sit outside the modeled scope, including sovereign AI export control expansions, fundamental transformer architecture displacements, and hyperscaler vertical integration into specialized silicon. Forecasts reflect assumptions regarding regulatory enforcement consistency and enterprise cloud migration velocity. A model refresh is warranted upon material change in EU AI Act penalty structures or FDA diagnostic AI validation pathway revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Global Cognitive Data Management Market
Machine Learning and Data Science
Global Computational Creativity Market
Machine Learning and Data Science
Global Data Annotation Tools Market
Machine Learning and Data Science
Speech-To-Text API Market
Machine Learning and Data Science
Semantic Knowledge Graphing Market
Machine Learning and Data Science
Europe Machine Learning As a Service Market
Machine Learning and Data Science
Europe Data Science Platform Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Machine Learning Operation Technology Market
Machine Learning and Data Science
Global Data Annotation Service Market
Machine Learning and Data Science
Asia-Pacific Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
Europe Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Global Image Recognition in CPG Market