
 Baking Mats Market | 2026-2036
Baking Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Baking Mats Market Analytics
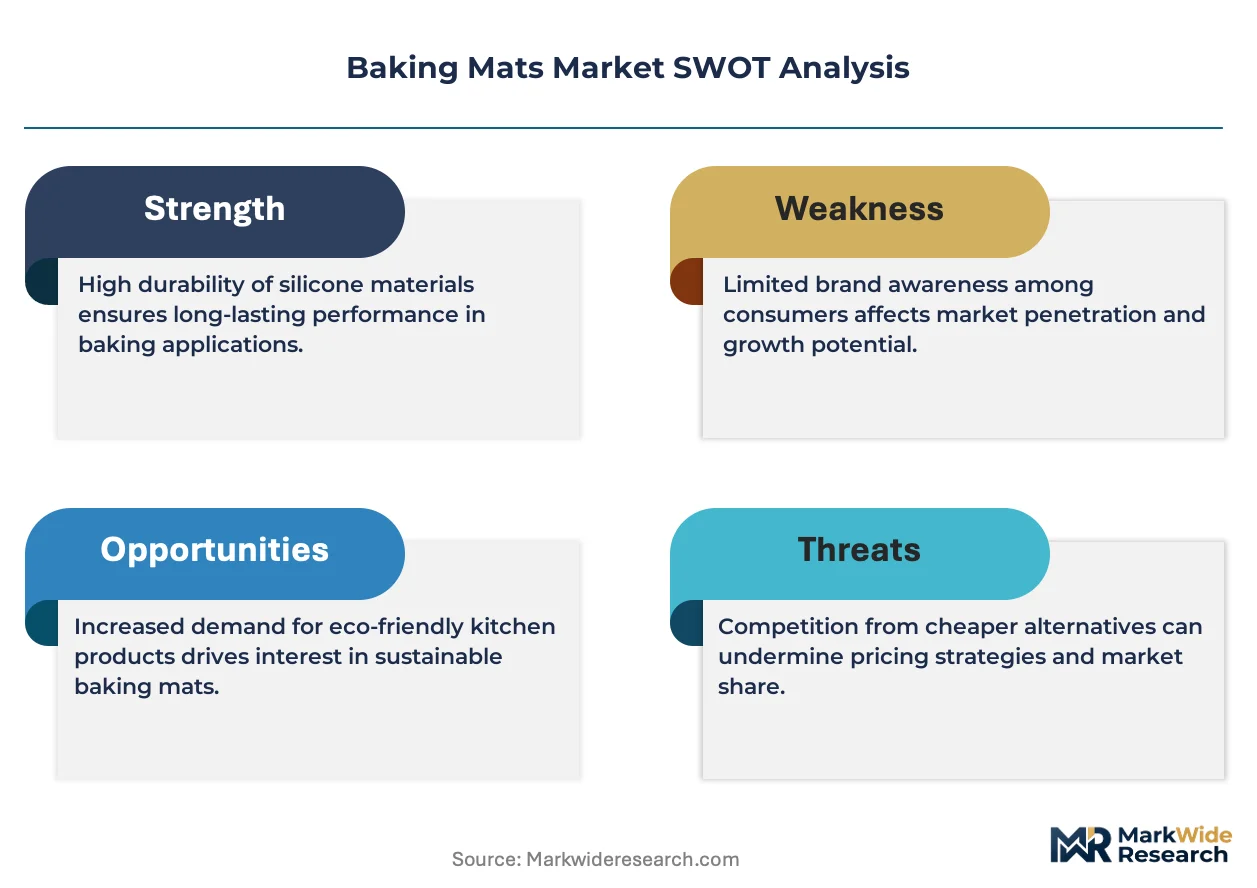
Aftermarket accessory revenue is fragmenting across direct-to-consumer channels and specialty kitchenware distributors. Silpat leverages its French manufacturing heritage to anchor premium positioning in professional segments. Nordic Ware competes through domestic production scale and bundling with bakeware sets. AmazonBasics extends its private-label reach via aggressive online retail placement and volume pricing.
Baking mats are flexible, heat-resistant sheets, typically manufactured from food-grade silicone reinforced with fiberglass mesh, designed to provide non-stick surfaces for dough handling and oven baking up to temperatures exceeding 230°C. Their primary commercial purpose centers on eliminating disposable liner costs while ensuring consistent thermal distribution across commercial and residential ovens. Silicone formulations dominate material type segmentation due to thermal stability and regulatory acceptance, while professional baking applications capture the fastest expansion as commercial kitchens standardize reusable workflows. Distribution through online retail channels now occupies the largest volume share, though specialty stores sustain margin pools through consultative selling and custom size configurations.
FDA food-contact regulations in the United States and EU REACH restrictions on fluorinated compounds jointly shape material compliance requirements across export-bound production. BIS certification requirements in India add another compliance layer for manufacturers targeting emerging market expansion. Stakeholders must monitor evolving perfluorinated substance bans and regional certification divergence to align product portfolios with shifting market access rules.
Market Dynamics
REACH restrictions on perfluorinated compounds are forcing manufacturers toward platinum-cured silicone formulations, restructuring material sourcing across European production hubs and export-oriented facilities.
Growth Catalysts
- EU REACH compliance mandates:Bans on fluorinated compounds accelerate platinum-cured silicone adoption in German industrial baking corridors, where large-scale producers retrofit equipment for standardized mat dimensions.
- Commercial kitchen cost reduction:Professional bakeries eliminate disposable parchment expenses through reusable silicone surfaces, converting operational savings into capital procurement budgets.
- Online retail channel expansion:Direct-to-consumer platforms capture volume share from specialty distributors, enabling manufacturers to bypass wholesale margin compression.
Market Restraints
- Platinum catalyst cost volatility:Precious metal price swings compress formulation margins for silicone producers dependent on catalytic chemistry.
- FDA food-contact certification timelines:Extended approval cycles for new material compositions delay US market entry for modified product lines.
- Parchment paper substitution threat:Low-cost disposable liners retain cost advantage in price-sensitive residential segments and emerging market penetration.
Strategic Opportunities
- India BIS certification pathway:Unmet compliance infrastructure creates first-mover advantage for manufacturers establishing certified production ahead of domestic competitor scaling.
- Smart kitchen integration:Convergence of silicone substrates with embedded temperature sensors enables connected baking workflows for premium residential segments.
- Specialty store consultative channel:Custom size configuration services sustain margin pools through technical specification support unavailable via mass retail.
Industry Challenges
- Equipment retrofit compatibility:Legacy commercial ovens require dimensional standardization engineering, extending sales cycles for industrial accounts.
- Fiberglass mesh supply concentration:Reinforcement material sourcing bottlenecks in Asian textile manufacturing create inventory risk for integrated producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baking Mats Market |
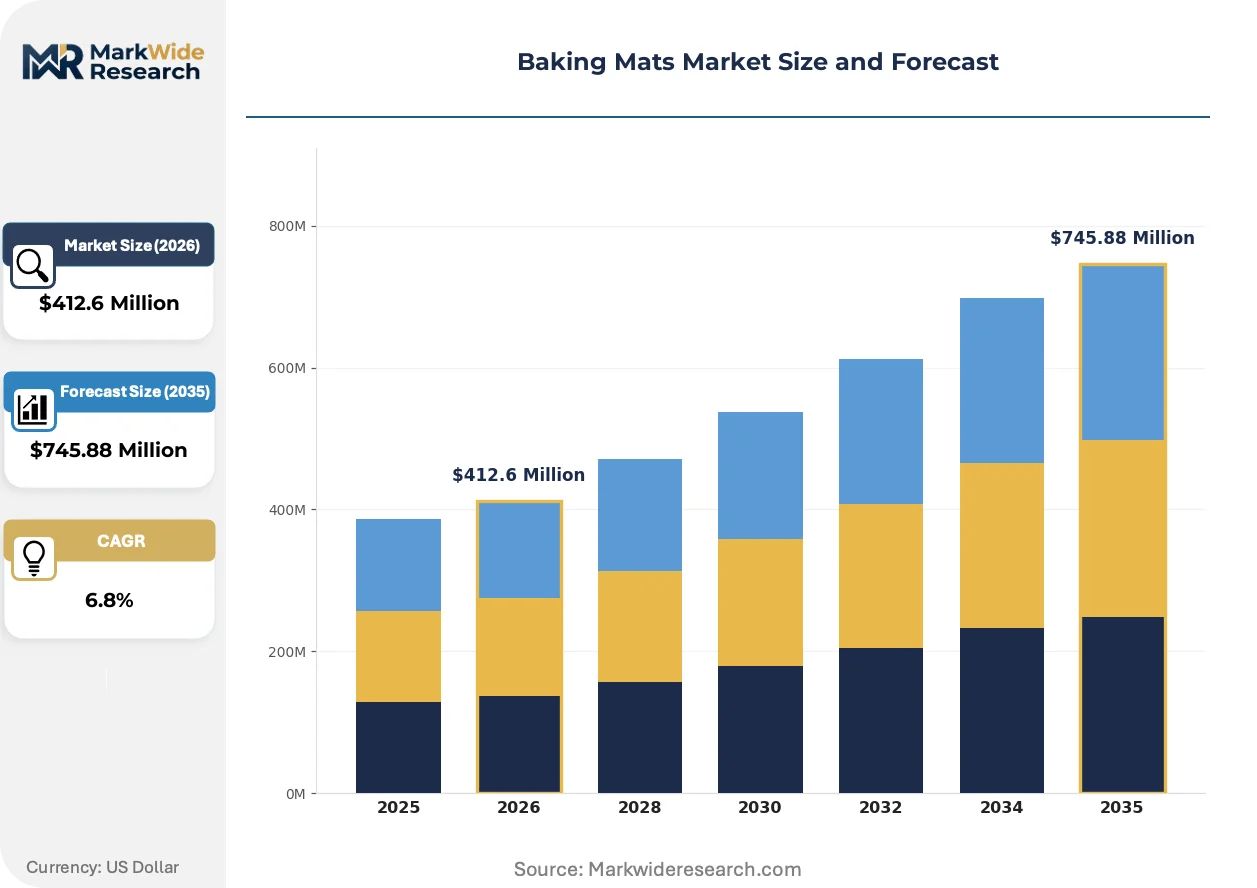
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Silicone, Teflon, Cotton, Fiberglass Application: Home Baking, Professional Baking, Culinary Schools, Confectionery Production Size: Standard, Mini, Extra Large, Custom Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Kitchenware Shops |
| Companies Covered | Silpat, AmazonBasics, Nordic Ware, OXO, Meyer Corporation, Matfer Bourgeat, Wilton, COOKINA, Kitzini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baking Mats Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to reshape competitive positioning across formulation tiers and end-use specifications.
Platinum-cured silicone formulations are digitizing quality assurance protocols through embedded batch tracking and thermal performance logging. Commercial bakery chains in Germany and France adopt these traceable surfaces for HACCP documentation compliance. The technology is digitizing supply chain transparency requirements, compressing certification timelines from months to weeks.
EU REACH Annex XVII restrictions on perfluorinated substances are eliminating legacy PTFE-coated alternatives from professional kitchen procurement lists. Manufacturers face reformulation costs exceeding standard R&D budgets for compliant material development. German industrial baking corridors show fastest response, with retrofit programs accelerating platinum-cured standardization.
Direct-to-consumer platforms are fragmenting aftermarket accessory revenue previously captured by specialty kitchenware distributors. AmazonBasics placement strategies and private-label expansion compress branded premium positioning in residential segments. This channel rotation is most visible in North American and Western European markets where online grocery integration enables impulse-category bundling.
Baking Mats Market Segmentation
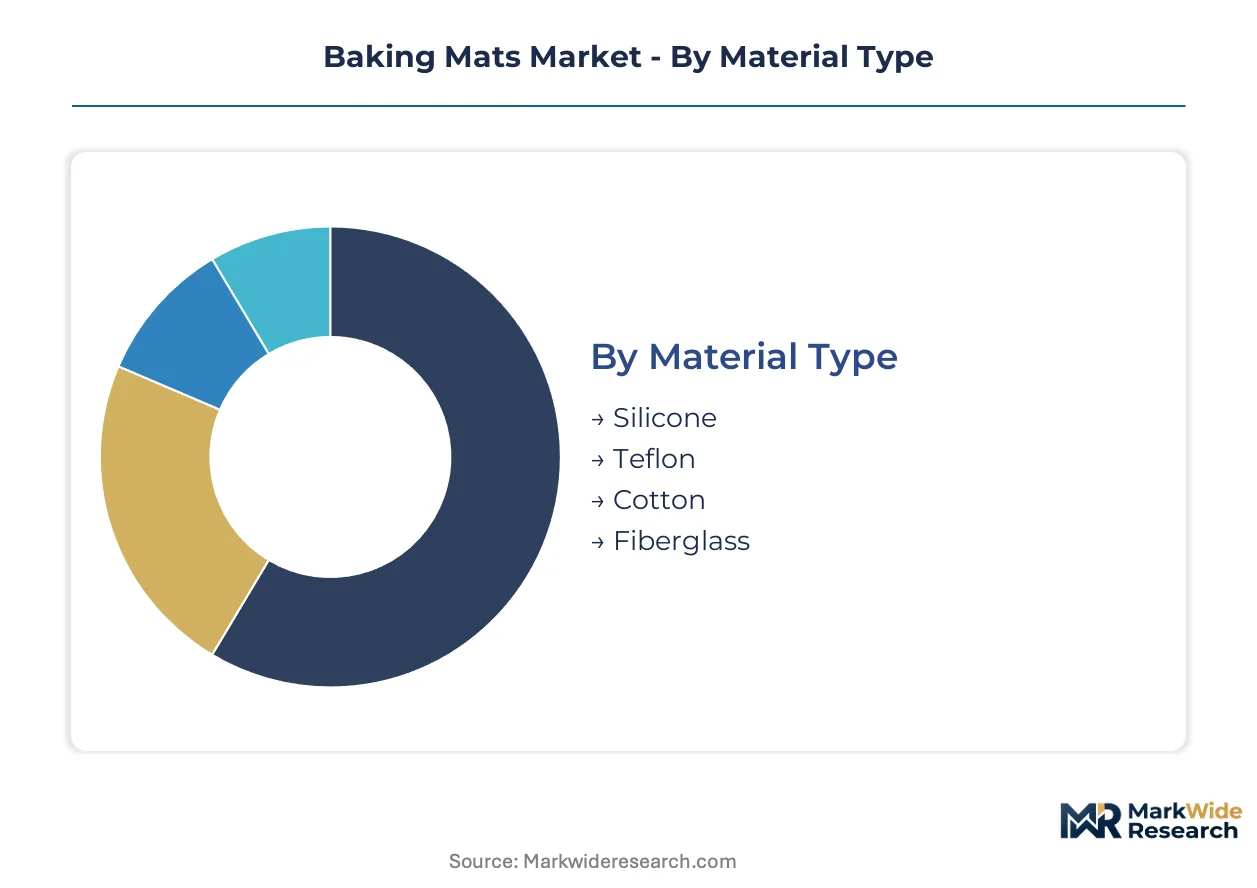
Segmentation in baking mats reflects divergent performance requirements across thermal stability, regulatory compliance, and end-use workflow intensity. Material chemistry and distribution channel selection determine margin capture and market access velocity for manufacturers.
Material Type:
Mature silicone formulations coexist with emerging alternatives as regulatory pressure reshapes acceptable chemistry portfolios.
- Silicone:Food-grade formulations reinforced with fiberglass mesh deliver thermal stability above 230°C and dominate professional procurement specifications. German industrial baking corridors drive volume concentration as retrofit programs standardize platinum-cured surfaces for HACCP traceability.
- Teflon:PTFE-coated substrates face accelerating displacement under EU REACH Annex XVII restrictions on perfluorinated compounds. Legacy inventory clears through price-sensitive residential channels while reformulation investments redirect toward compliant alternatives.
- Cotton:Natural fiber liners serve niche artisanal segments requiring breathable dough resting surfaces. French and Italian traditional bakeries sustain limited procurement volumes.
- Fiberglass:Reinforcement material functions primarily as composite substrate rather than standalone surface, with supply concentration in Asian textile manufacturing creating inventory risk for integrated producers.
Silicone retains volume leadership; platinum-cured variants hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive commercial adoption from discretionary residential purchasing patterns.
- Home Baking:Residential consumers prioritize unit economics and storage convenience over thermal performance specifications. AmazonBasics and mass-market private labels capture dominant share through online retail bundling strategies.
- Professional Baking:Commercial kitchens eliminate disposable parchment expenses through reusable silicone surfaces, converting operational savings into capital procurement budgets for standardized mat dimensions. German and French bakery chains lead equipment retrofit adoption.
- Culinary Schools:Training institutions require durable surfaces withstanding repetitive student use and aggressive cleaning protocols. Procurement concentrates through specialty kitchenware distributors offering volume pricing.
- Confectionery Production:Precision temperature control demands drive specification for embedded sensor compatibility in premium silicone formulations.
Professional baking commands premium pricing tiers; home baking delivers aggregate volume scale.
Size:
Customer type differentiation separates standardized equipment compatibility from bespoke workflow integration requirements.
- Standard:Dimensions align with conventional commercial oven specifications prevalent in German industrial baking corridors. Volume procurement locks in multi-year supply agreements.
- Mini:Compact formats target residential toaster ovens and single-serve preparation workflows. Impulse purchasing through online retail channels sustains margin compression.
- Extra Large:Extended surfaces accommodate artisanal bread production and commercial pastry sheet handling. Custom equipment retrofit requirements extend sales cycles.
- Custom:Specialty stores and consultative distributors capture margin pools through technical specification support and dimensional engineering services unavailable via mass retail.
Standard sizes anchor equipment compatibility; custom configurations extract premium margins through specification support.
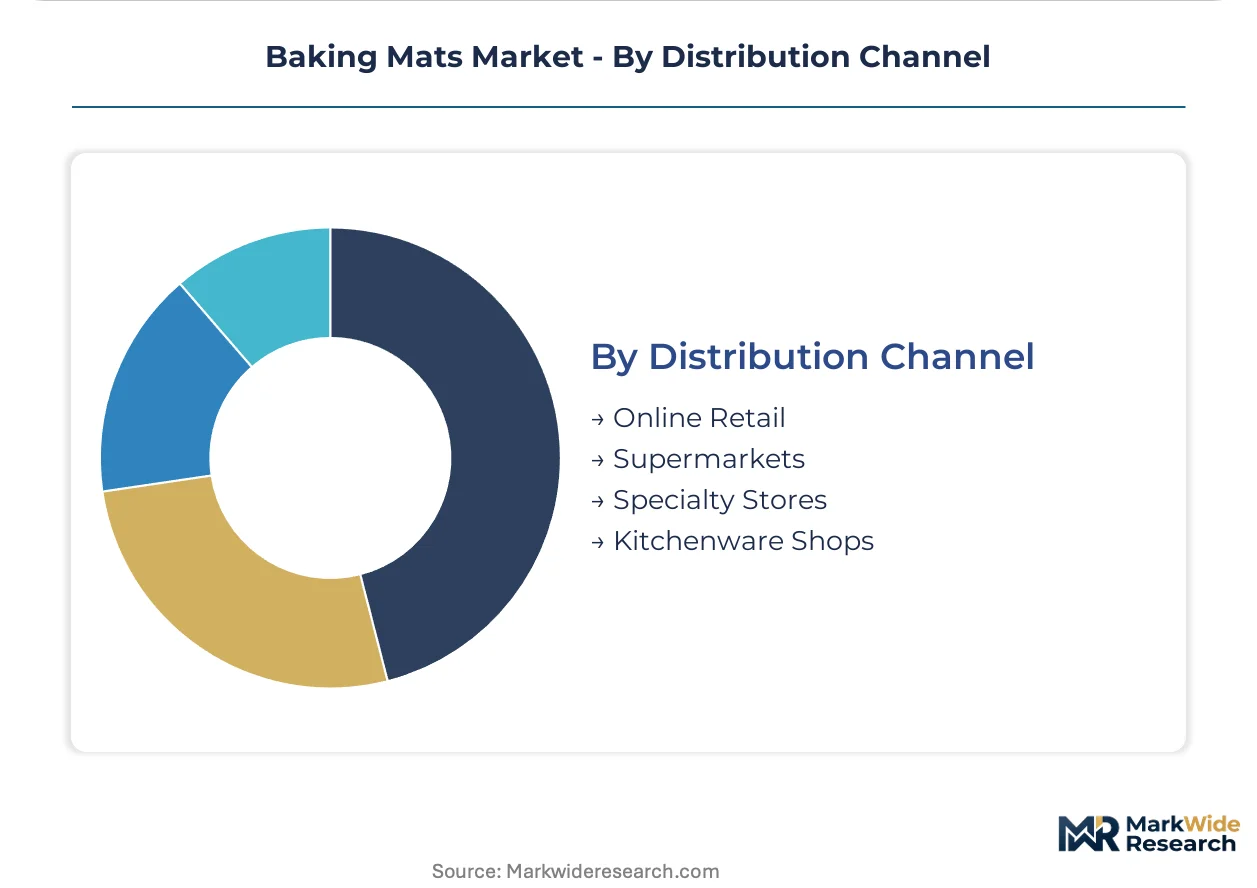
Distribution Channel:
Geography-agnostic platform expansion is fragmenting legacy wholesale structures across developed markets.
- Online Retail:Direct-to-consumer platforms capture volume share from specialty distributors, enabling manufacturers to bypass wholesale margin compression. North American and Western European markets show fastest channel rotation through grocery integration and impulse-category bundling.
- Supermarkets:Mass retail placement emphasizes price-point accessibility and seasonal promotional cycles. Private-label penetration compresses branded positioning.
- Specialty Stores:Consultative selling sustains margin pools through technical specification support and custom size configuration services. Professional bakery procurement concentrates here for compliance documentation requirements.
- Kitchenware Shops:Independent retailers serve localized artisanal producer networks with curated product assortments and relationship-based repeat purchasing.
Online retail is gaining share fastest; specialty stores defend margin extraction through consultative services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. German industrial bakeries absorb premium platinum-cured silicone costs for HACCP compliance, while Indian residential buyers prioritize unit economics over thermal specifications.
United States
FDA food-contact certification timelines structure competitive entry for reformulated silicone products. Commercial bakery chains in the Midwest retrofit standardized equipment for reusable mat workflows. California's Proposition 65 enforcement accelerates displacement of fluorinated compound alternatives from professional kitchen procurement.
Germany
EU REACH Annex XVII restrictions on perfluorinated compounds eliminate legacy PTFE-coated inventory from industrial baking corridors. ECHA compliance documentation requirements digitize through embedded batch tracking in platinum-cured formulations. Bavarian large-scale producers anchor equipment standardization programs for multi-site bakery operations.
France
Traditional artisanal bakeries sustain niche cotton liner demand alongside silicone conversion. ANSM food-contact material surveillance tightens import scrutiny for Asian-manufactured substrates. Parisian confectionery production clusters specify embedded sensor compatibility for precision temperature control applications.
India
BIS certification requirements create compliance infrastructure gaps for domestic and import suppliers. Price-sensitive residential segments retain parchment paper dominance despite silicone penetration in urban metros. Maharashtra's emerging commercial baking sector pilots reusable surface adoption through equipment leasing programs.
China
GB standards for food-contact silicone diverge from EU and US specifications, fragmenting export-oriented production compliance. Yangtze River Delta manufacturing hubs concentrate fiberglass mesh reinforcement supply. Domestic online retail platforms capture volume share through aggressive private-label placement and impulse-category bundling.
Baking Mats Market Competitive Landscape
Capability concentration sits with heritage manufacturers possessing formulation chemistry expertise; scale advantage sits with retail-integrated private labels and domestic production specialists. The vendor base separates into three strategic tiers: premium heritage brands, mass-market private labels, and specialty consultative distributors. Dominant competitive moves include geographic certification pre-positioning ahead of regulatory deadlines and channel rotation toward direct-to-consumer platforms bypassing wholesale margin compression.
Within the heritage formulation tier, Silpat and Matfer Bourgeat occupy positions anchored by European manufacturing provenance and professional kitchen specification authority. Nordic Ware exemplifies domestic production scale advantage through bundling integration with complementary bakeware assortments. AmazonBasics represents the retail-integrated private-label archetype, leveraging platform placement density and volume pricing to compress branded premium positioning in residential segments.
| Leading Market Players |
|---|
| Silpat |
| AmazonBasics |
| Nordic Ware |
| OXO |
| Meyer Corporation |
| Matfer Bourgeat |
| Wilton |
| COOKINA |
| Kitzini |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese silicone manufacturing hubs is compressing raw material input costs while simultaneously eroding pricing power for mid-tier producers dependent on commodity-grade formulations. This utilization dynamic pushes suppliers toward platinum-cured specialty grades where German industrial buyers absorb premium positioning for compliance documentation.
Pricing Analysis
Aftermarket accessory revenue through replacement mat programs and extended kitchenware service contracts drives lifetime value capture for heritage manufacturers. Three-tier pricing structure across platinum-cured premium, standard food-grade, and economy private-label tiers separates professional bakery procurement from residential impulse purchasing. Pricing pressure stems from AmazonBasics volume placement and direct-to-consumer channel rotation compressing branded premium positioning in North American and Western European residential segments. Home baking consumers exhibit highest price sensitivity, while German commercial bakery chains demonstrate lowest sensitivity due to HACCP traceability requirements.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for fiberglass mesh reinforcement sourcing. Manufacturing concentrates in China's Yangtze River Delta, Germany's industrial baking corridor, and domestic North American production facilities for Nordic Ware bundling integration. Raw material dependencies center on platinum catalysts for silicone curing, food-grade silicone polymers, and woven fiberglass textile substrates. Single-source vulnerability in Asian textile manufacturing for reinforcement mesh creates inventory risk for integrated producers. Distribution runs through direct-to-consumer platforms, specialty kitchenware distributors, and mass retail bundling programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH Annex XVII restrictions on perfluorinated compounds constitute a regulatory inflection eliminating legacy PTFE alternatives and accelerating platinum-cured silicone conversion across professional kitchen procurement.
For Market Incumbents: Build formulation chemistry moats through platinum-cured silicone certification pre-positioning ahead of regulatory deadline enforcement. Secure backward integration into fiberglass mesh reinforcement supply to mitigate Asian textile manufacturing concentration risk. Defend against AmazonBasics private-label encroachment by anchoring premium positioning in professional segments through HACCP documentation bundling. For New Entrants and Emerging Players: Pursue BIS certification pathway establishment in India ahead of domestic competitor scaling, exploiting compliance infrastructure gaps for first-mover advantage. Target Maharashtra's emerging commercial baking sector through equipment leasing program partnerships as the most penetrable white-space geography. Deploy consultative technical specification support as the primary go-to-market angle to extract premium margins unavailable via mass retail. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across platinum-cured silicone formulation tiers due to precious metal catalyst requirements and embedded sensor integration R&D. Long-term viability favors heritage manufacturers with European manufacturing provenance and professional kitchen specification authority over retail-integrated private labels vulnerable to channel rotation. Acquisition target archetype: mid-cap specialists possessing REACH-compliant formulation expertise and German industrial bakery supply relationships. Monitor ECHA enforcement timeline acceleration as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platinum-Cured Formulation Transition | ECHA REACH compliance eliminates PTFE alternatives from German industrial bakery procurement specifications. |
| Backward Integration into Fiberglass Mesh | Captive supply of reinforcement substrates mitigates Yangtze River Delta textile manufacturing concentration risk. |
| Direct-to-Consumer Channel Expansion | Online retail placement bypasses wholesale margin compression from specialty kitchenware distributors. |
| Embedded Sensor Integration Development | Smart kitchen convergence enables premium positioning in Parisian confectionery production clusters. |
| BIS Certification Pre-Positioning | First-mover compliance infrastructure in India creates defensive moat against domestic competitor scaling. |
Research Methodology
Cross-validation between primary interviews with silicone formulation chemists, commercial bakery procurement directors, specialty kitchenware distributor category managers, and regulatory compliance officers anchors the qualitative findings. Secondary validation draws from ECHA REACH substance restriction databases, FDA food-contact notification filings, customs trade data for silicone polymer imports, and BIS certification registry records. Bottom-up demand modeling from equipment retrofit programs and top-down market sizing from channel shipment data complete the triangulation.
Calibration against historical adoption curves for reusable kitchenware and platinum-cured silicone penetration rates structures the analytical framework across the projection horizon. Segmentation dimensions include material chemistry tier, application intensity, distribution channel type, and regional regulatory cluster. CAGRs derive from fitted growth curves adjusted for equipment replacement cycles and compliance-driven procurement acceleration. Industry-specific inputs incorporate ECHA enforcement timeline scenarios and German industrial bakery corridor retrofit program commitments.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese silicone manufacturers or accelerated BIS enforcement in India would shift outcomes. Macroeconomic softness in European commercial baking, regulatory divergence in Chinese GB standards, or breakthroughs in biodegradable liner alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Wedding Cakes Market
Bakery Products
Bread Improver Market
Bakery Products
North America Fortified Bakery Products Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
Flour Mixes Market
Bakery Products
Teaseed Cake Market
Bakery Products
Tunnel Bakery Oven Market
Bakery Products
Bakery Improvers Market
Bakery Products
On-The-Go Breakfast Products Market
Bakery Products
Ice Cream Cake Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market
Bakery Products
Low Fat Bread Market
Bakery Products
Low Fat Baked Goods Market
Bakery Products
Pastry Premixes Market
Bakery Products
Fondant Market