
 Asia-Pacific Abrasives Market | 2026-2036
Asia-Pacific Abrasives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Abrasives Market Outlook
Multi-source procurement for fused alumina and silicon carbide feedstock is realigning supply security priorities across the Asia-Pacific abrasives value chain. Saint-Gobain leverages captive bauxite refining in the region to sustain margin control across bonded abrasive lines. Fujimi Corporation specializes in precision lapping compounds for semiconductor wafer processing, occupying a defensible niche in superabrasive formulations. Carborundum Universal Limited anchors South Asian distribution through direct technical service teams serving metalworking shops.
Abrasives are hard particles or minerals bonded into wheels, discs, belts, or slurries for material removal through grinding, cutting, polishing, or finishing operations, with specifications typically graded by grit size from coarse macro-grains below 60 mesh to ultrafine micro-grains exceeding 1000 mesh for precision surface engineering. Bonded abrasives dominate volume throughput in heavy metalworking and construction applications where structural integrity of the grinding wheel withstands high mechanical loads. Superabrasives, encompassing diamond and cubic boron nitride (CBN) segments, command premium positioning as automotive powertrain electrification demands tighter dimensional tolerances for hardened steel gears and ceramic substrates. Coated abrasives sustain broad adoption across woodworking and automotive refinishing where flexible backing materials adapt to contoured surfaces.
China's SAMR enforces GB standards on abrasive product labeling and safety performance, while Japan's METI coordinates JIS certification pathways that constrain market entry for uncertified suppliers. India's BIS mandates ISI marking for bonded abrasive wheels used in industrial metalworking, directly shaping procurement specifications among domestic manufacturers. Stakeholders must monitor divergence between China's evolving national standards and established Japanese certification regimes as cross-border supply chain integration deepens.
Market Dynamics
Automotive electrification across China and India is compressing dimensional tolerances for precision grinding operations, forcing abrasive suppliers to requalify product lines for hardened steel gears and ceramic substrates.
Growth Catalysts
- China's SAMR enforcement of GB standards:Tightened abrasive product labeling and safety performance mandates are filtering out uncertified suppliers, consolidating procurement toward qualified domestic manufacturers.
- Semiconductor wafer processing expansion:Precision lapping compounds for silicon carbide substrates are experiencing accelerated consumption as foundries in Japan and South Korea scale advanced packaging capacity.
- Yangtze River Delta machine tool density:Superabrasive consumption concentrates in this manufacturing corridor where high spindle speeds and automated grinding cells sustain premium abrasive throughput.
Market Restraints
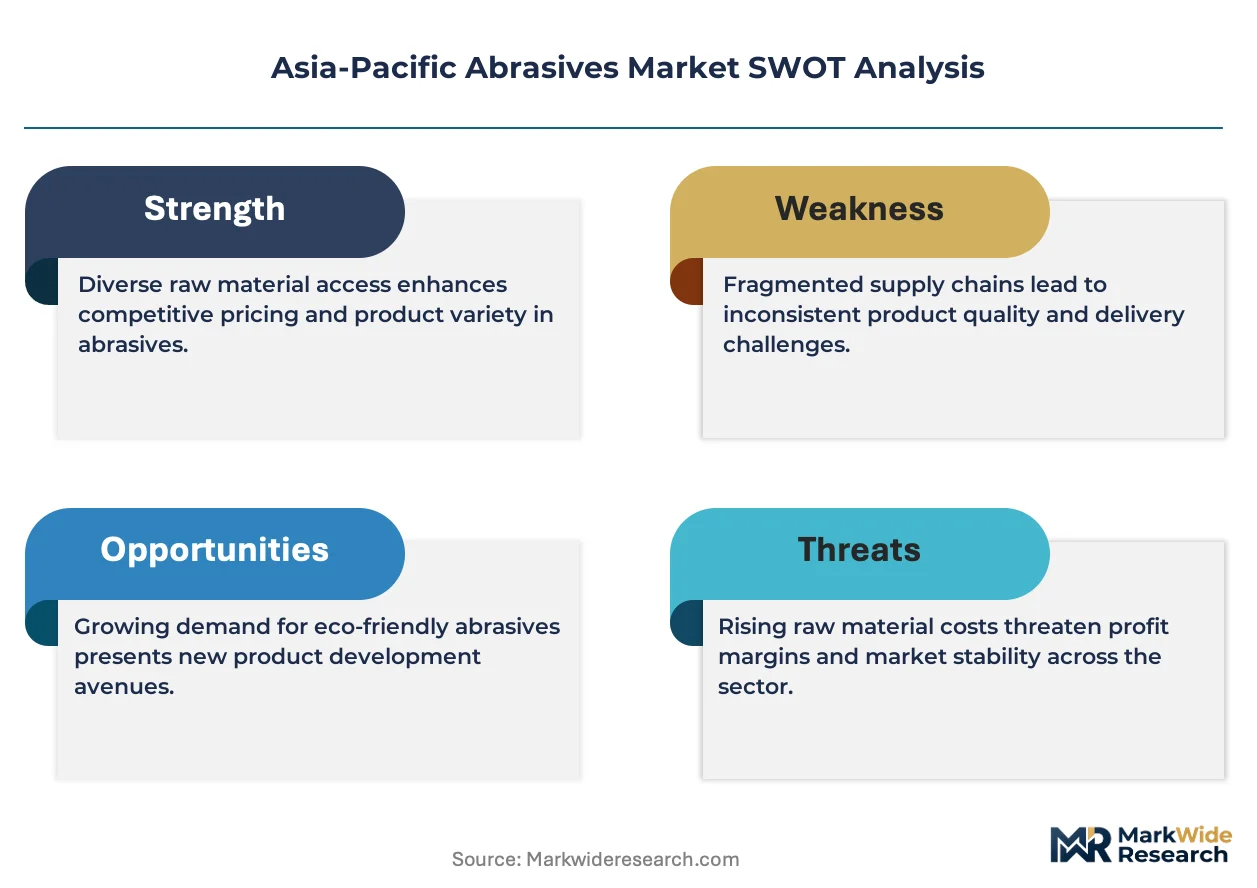
- Bauxite feedstock concentration:Fused alumina production depends on captive refining capacity concentrated among integrated suppliers, exposing non-integrated abrasive manufacturers to input cost volatility.
- Japan's JIS certification pathway rigidity:Uncertified foreign suppliers face extended technical documentation requirements and testing protocols that constrain rapid market entry.
- Silicon carbide substitution in lapping:Synthetic diamond slurries are encroaching on traditional silicon carbide applications in precision optics, pressuring established product line margins.
Strategic Opportunities
- India's BIS ISI marking expansion:Mandatory certification for bonded abrasive wheels creates a compliance moat for early-mover domestic manufacturers serving metalworking shops.
- Electric vehicle motor shaft grinding:Hardened steel rotor components require CBN grinding wheels with specifications exceeding conventional abrasive capabilities, opening premium product tiers.
- Technical service team deployment:Direct field engineering support for grinding parameter optimization represents an underdeveloped channel across Southeast Asian manufacturing clusters.
Industry Challenges
- Superabrasive bonding chemistry expertise:Ceramic and resin bond formulations for diamond and CBN wheels require specialized formulation knowledge that remains concentrated among Japanese and European specialists.
- Cross-border GB-JIS standard divergence:Abrasive suppliers serving both China and Japan must maintain parallel certification documentation and testing regimens, complicating product portfolio management.
- Legacy grinding machine retrofit compatibility:New superabrasive products often require spindle speed upgrades or coolant system modifications that delay adoption in cost-sensitive metalworking facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Abrasives Market |
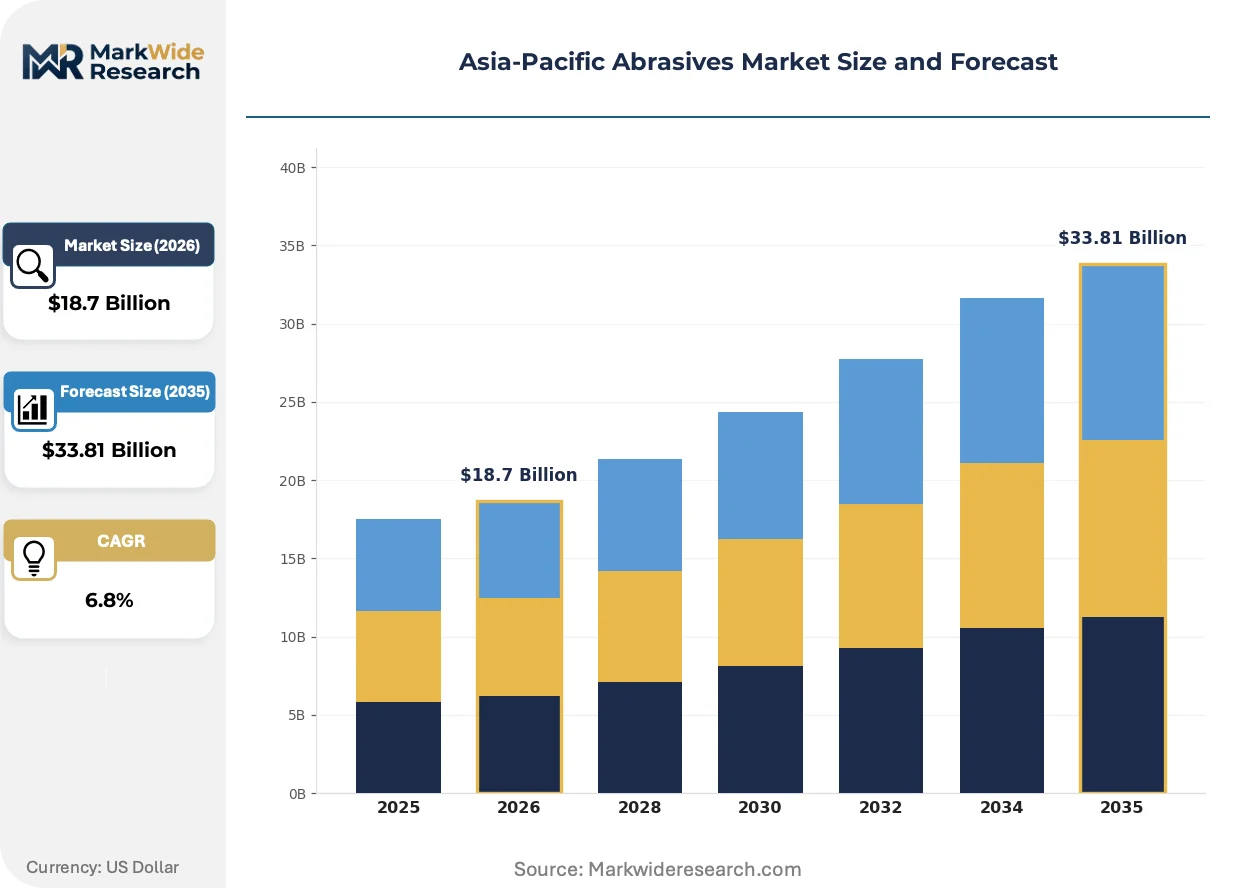
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bonded Abrasives, Coated Abrasives, Superabrasives, Loose Abrasives Application: Metalworking, Woodworking, Construction, Automotive End User: Manufacturers, Distributors, Retailers, Repair Services Material: Alumina, Silicon Carbide, Diamond, CBN |
| Companies Covered | 3M, Saint-Gobain, Asahi Diamond Industrial Co., Ltd., Carborundum Universal Limited, Fujimi Corporation, NORITAKE CO., LIMITED, TYROLIT, DuPont, Hermes Abrasives, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Abrasives Market Strategic Shifts
Grinding process digitization and abrasive specification granularity are compressing traditional supply relationships, with real-time wear monitoring and predictive wheel replacement protocols restructuring procurement cycles.
Vitrified CBN grinding wheels with engineered porosity structures are overtaking conventional aluminum oxide products in automotive camshaft and crankshaft grinding lines. Japanese and Korean powertrain manufacturers have adopted these wheels for high-speed continuous-path grinding operations. The shift is overtaking established supply contracts as OEMs requalify supplier bases around ceramic bond expertise rather than legacy abrasive relationships.
China's evolving GB standards under SAMR oversight are diverging from established Japanese JIS certification regimes in abrasive safety testing protocols and labeling requirements. Industrial end-users in cross-border supply chains now face dual compliance documentation burdens for bonded abrasive wheels. South Korean manufacturers serving both markets are responding by segregating product lines with distinct certification markings rather than pursuing harmonized specifications.
Metalworking shops across China's Pearl River Delta are consolidating abrasive procurement through integrated cutting tool and consumable distributors. Single-source supply agreements covering inserts, grinding wheels, and coated abrasives are displacing fragmented multi-vendor purchasing patterns. This concentration is most visible among mid-tier automotive component suppliers seeking simplified technical service interfaces and consolidated inventory management.
Asia-Pacific Abrasives Market Segmentation
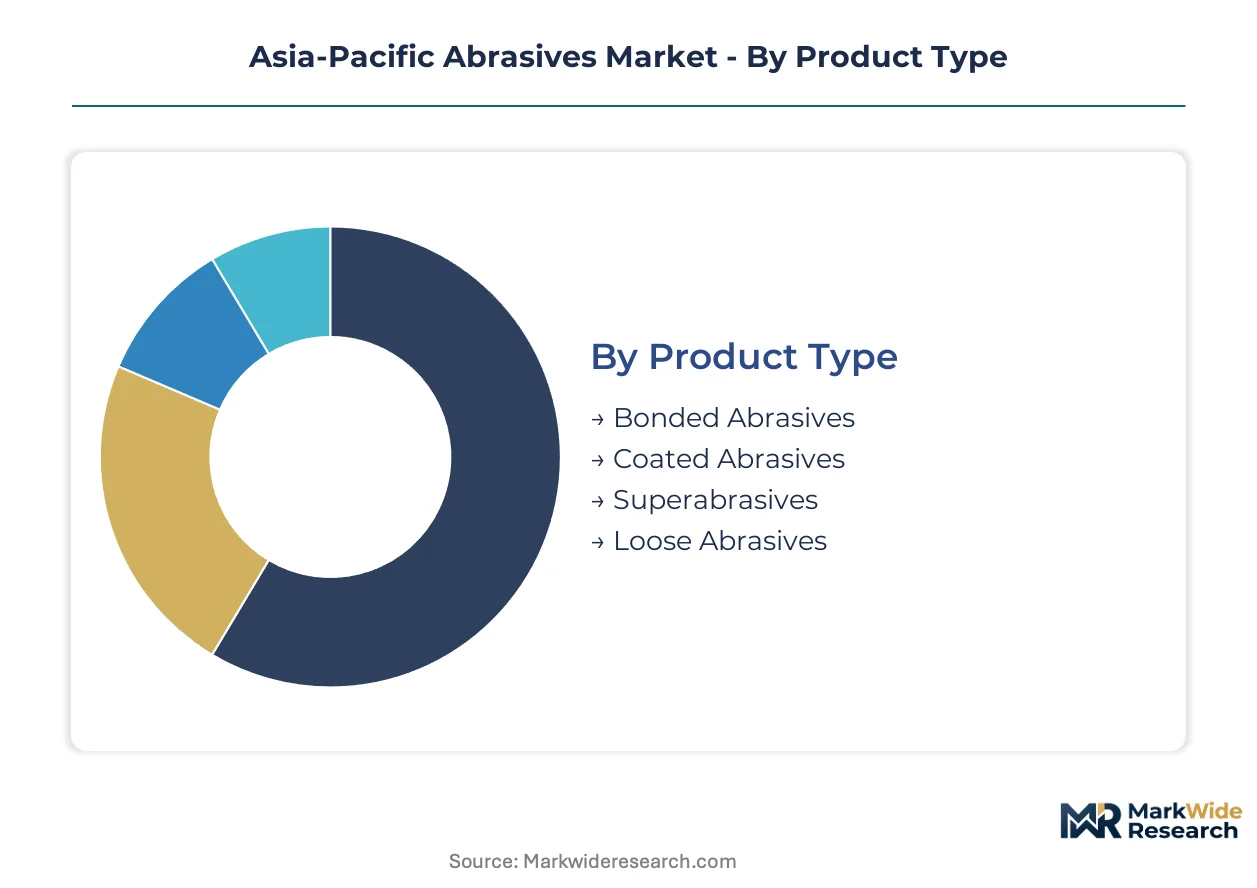
Segmentation in the Asia-Pacific abrasives market reveals how capital intensity, certification requirements, and end-use precision demands fragment procurement patterns. Suppliers must align product portfolios with distinct technical specifications across bonded wheels, coated belts, and superabrasive formulations serving divergent manufacturing clusters.
Product Type:
Bonded abrasives demand the heaviest capital investment due to vitrification kilns and resin curing infrastructure, while superabrasives require specialized diamond/CBN synthesis and ceramic bond chemistry expertise.
- Bonded Abrasives:Grinding wheels, discs, and honing stones formed by fusing abrasive grains with vitrified, resin, or rubber bonds. Demand concentrates in China's Yangtze River Delta machine tool corridors where SAMR-enforced GB standards mandate structural integrity testing for heavy metalworking loads.
- Superabrasives:Diamond and cubic boron nitride (CBN) products commanding premium positioning through engineered ceramic bond porosity structures. Automotive powertrain electrification across Japan and South Korea is compressing dimensional tolerances for hardened steel gear grinding, forcing requalification of conventional aluminum oxide supply relationships.
- Coated Abrasives:Flexible abrasive grains bonded to paper, cloth, or polyester backings for contour adaptation in woodworking and automotive refinishing.
- Loose Abrasives:Free-flowing grains deployed in blasting, lapping, and polishing operations without fixed bonding matrices.
Most installed capacity flows through bonded abrasives. Expansion is steepest in superabrasives.
Application:
Metalworking commands the highest volume throughput, though automotive applications carry the steepest specification escalation as electrification rewrites precision requirements.
- Metalworking:Precision grinding, cutting, and finishing of ferrous and non-ferrous components across machine shops and fabrication facilities. China's Pearl River Delta metalworking clusters are consolidating procurement through integrated cutting tool distributors, displacing fragmented multi-vendor purchasing.
- Automotive:Camshaft, crankshaft, and electric motor rotor grinding requiring CBN wheels with specifications exceeding conventional abrasive capabilities. Japanese and Korean OEMs have adopted vitrified CBN wheels for high-speed continuous-path grinding, overtaking established supply contracts.
- Construction:Heavy material removal in concrete cutting, masonry grinding, and surface preparation where bonded wheel structural integrity withstands mechanical shock.
- Woodworking:Sanding and finishing operations where coated abrasive flexibility adapts to contoured furniture and flooring surfaces.
Metalworking absorbs the greatest abrasive tonnage. Automotive applications are gaining share fastest as powertrain electrification accelerates.
End User:
Manufacturers capture the deepest technical service relationships, while distributors increasingly control inventory consolidation among mid-tier metalworking shops.
- Manufacturers:Tier-1 automotive component producers and precision engineering facilities requiring direct grinding parameter optimization support.
- Distributors:Integrated cutting tool and consumable suppliers consolidating bonded wheels, coated abrasives, and inserts under single-source agreements.
- Retailers:Hardware and industrial supply outlets serving maintenance operations and small-scale metalworking facilities.
- Repair Services:Independent grinding shops and equipment refurbishment contractors requiring flexible procurement quantities.
Direct manufacturer relationships anchor premium superabrasive volumes. Distributor consolidation is reshaping mid-market bonded abrasive procurement patterns.
Material:
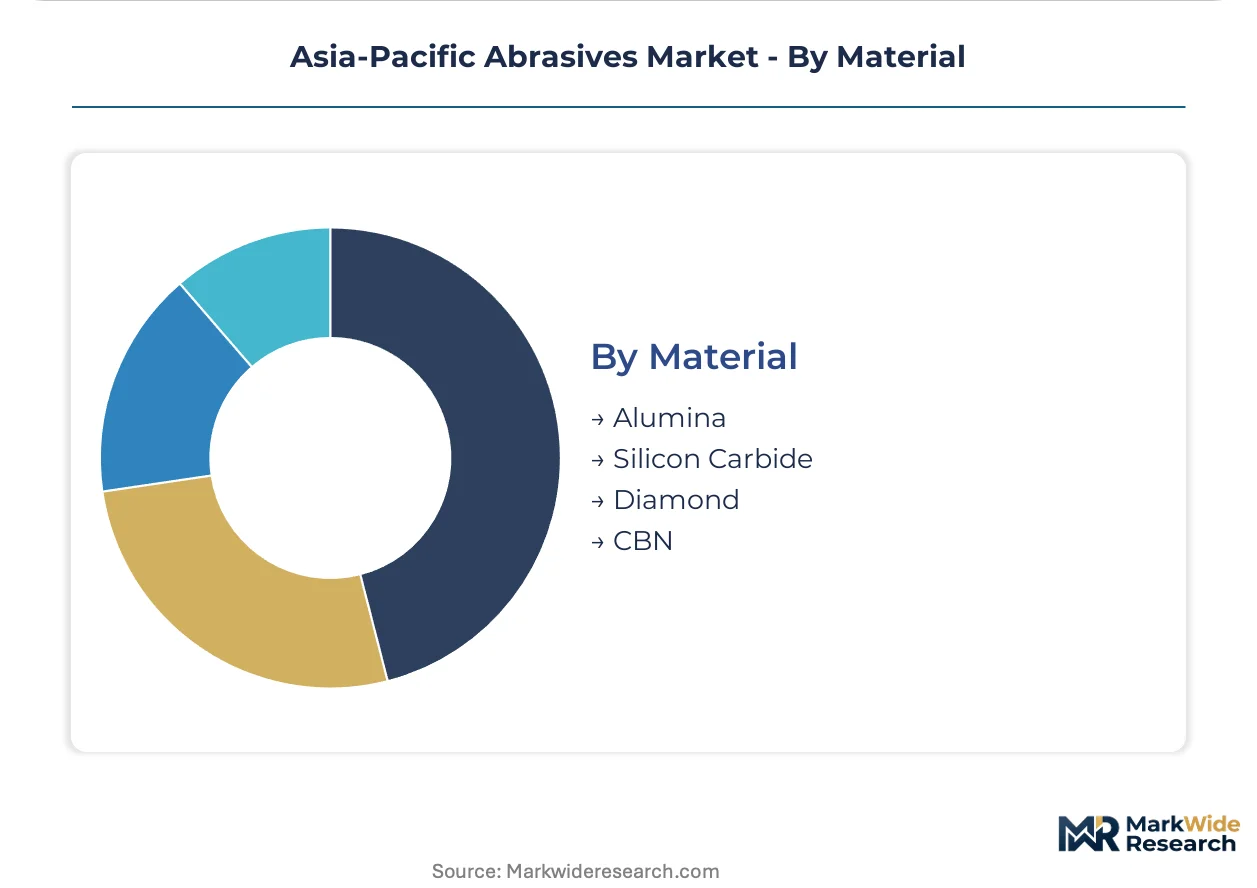
Alumina and silicon carbide dominate volume economics, though diamond and CBN materials command pricing power through synthetic scarcity and bonding expertise concentration.
- Alumina:Fused aluminum oxide grains derived from bauxite refining, serving general-purpose grinding across construction and heavy metalworking. Saint-Gobain leverages captive bauxite refining capacity in the region to sustain margin control.
- Diamond:Synthetic and natural diamond superabrasives for precision lapping of silicon carbide semiconductor substrates. Foundries in Japan and South Korea are scaling advanced packaging capacity, accelerating consumption of precision lapping compounds.
- Silicon Carbide:Hard, sharp grains for grinding cast iron, non-ferrous metals, and glass, facing substitution pressure from synthetic diamond slurries in precision optics applications.
- CBN:Cubic boron nitride synthesized for ferrous material grinding where diamond reactivity limits performance, requiring specialized ceramic and resin bond formulation knowledge concentrated among Japanese specialists.
Alumina retains the largest installed grinding capacity base. Diamond materials are climbing the fastest as semiconductor wafer processing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta manufacturing corridor anchors Asia-Pacific abrasive consumption, where machine tool density and superabrasive grinding cell deployment create concentrated demand clusters across China, Japan, India, South Korea, and Southeast Asian manufacturing hubs.
China
Automotive OEMs in the Yangtze River Delta and Pearl River Delta are scaling precision grinding operations for electric drivetrain components. SAMR-enforced GB standards on abrasive product labeling and safety performance are filtering out uncertified suppliers and consolidating procurement toward qualified domestic manufacturers. Shanghai and Suzhou machine tool corridors sustain the region's highest superabrasive consumption density.
Japan
Powertrain manufacturers have adopted vitrified CBN grinding wheels for high-speed continuous-path grinding of camshafts and crankshafts. METI-coordinated JIS certification pathways impose extended technical documentation requirements that constrain rapid market entry for uncertified foreign suppliers. Nagoya and Osaka industrial zones concentrate ceramic bond formulation expertise for diamond and CBN wheel production.
India
Metalworking shops across Maharashtra and Gujarat are consolidating abrasive procurement through integrated cutting tool distributors under single-source supply agreements. BIS-mandated ISI marking for bonded abrasive wheels creates a compliance moat for early-mover domestic manufacturers. Pune and Ahmedabad manufacturing clusters drive bonded abrasive volume through automotive component supplier networks.
South Korea
Foundries scaling advanced packaging capacity are accelerating consumption of precision lapping compounds for silicon carbide semiconductor substrates. Manufacturers serving both Chinese and Japanese markets are segregating product lines with distinct GB and JIS certification markings rather than pursuing harmonized specifications. Seoul and Suwon semiconductor corridors concentrate demand for superabrasive slurry formulations.
Southeast Asia
Mid-tier automotive component suppliers in Thailand and Vietnam are seeking simplified technical service interfaces and consolidated inventory management for coated abrasives in woodworking and automotive refinishing. Technical service team deployment for grinding parameter optimization remains underdeveloped across Bangkok and Ho Chi Minh City manufacturing clusters.
Asia-Pacific Abrasives Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue certification-compliant positioning in regulated national markets. The market structure reflects moderate consolidation around integrated bauxite refiners and specialized superabrasive formulators, with fragmentation persisting among regional bonded abrasive fabricators. Three archetypes dominate: captive raw material integrators, precision superabrasive specialists, and distributor-anchored regional suppliers. Competitive moves center on backward integration into bauxite refining and technical service team deployment for grinding parameter optimization.
Among Japanese specialists, Asahi Diamond Industrial Co., Ltd. and Fujimi Corporation exemplify precision superabrasive formulation archetypes, while Saint-Gobain represents captive raw material integration through regional bauxite refining capacity. These three anchors illustrate how competitive positioning separates integrated feedstock control from specialized bonding chemistry expertise.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain |
| Asahi Diamond Industrial Co., Ltd. |
| Carborundum Universal Limited |
| Fujimi Corporation |
| NORITAKE CO., LIMITED |
| TYROLIT |
| DuPont |
| Hermes Abrasives |
| Others |
Value Chain & Pricing Dynamics
Tier-1 automotive OEMs in Japan and South Korea anchor pricing power for vitrified CBN grinding wheels through long-term technical qualification contracts. This buyer concentration sustains premium-mid-economy pricing differentiation across superabrasive formulations.
Pricing Analysis
Input-cost pass-through from captive bauxite refining operations determines base pricing for fused alumina bonded wheels. Price differentiation hinges on JIS certification tier and ceramic bond porosity engineering. Cost compression in standard-grade alumina products is intensifying as Chinese SAMR enforcement consolidates procurement toward qualified domestic manufacturers. Mid-tier metalworking shops exhibit highest price sensitivity, while semiconductor foundries tolerate premium positioning for diamond slurry formulations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand for automotive powertrain grinding applications, while integrated cutting tool distributors serve fragmented metalworking procurement. Raw material sourcing draws from bauxite refining in China, synthetic diamond synthesis in Japan, and silicon carbide production in South Korea. Tariff exposure on cross-border GB-JIS certified product lines creates compliance cost layering. Distribution runs through technical service teams for superabrasive parameter optimization and volume distributors for bonded abrasive standard grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific abrasives market compounds steadily as automotive electrification forces precision grinding requalification cycles across OEM supply chains.
For Market Incumbents: Anticipate synthetic diamond slurry substitution pressure in semiconductor lapping applications by deepening ceramic bond formulation expertise for next-generation CBN wheels. Secure backward integration into regional bauxite refining capacity to sustain margin control against feedstock volatility. For New Entrants and Emerging Players: Capture technical service deployment gaps across Southeast Asian manufacturing clusters in Thailand and Vietnam where grinding parameter optimization support remains underdeveloped. Pursue BIS ISI marking compliance early to exploit India's bonded abrasive certification moat. For Investors and Strategic Acquirers: Japanese precision ceramics specialists are the most active acquirer in this space, targeting superabrasive bonding chemistry capabilities. Monitor JIS-GB standard divergence intensity as the signal for cross-border supply chain restructuring inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Refining | Saint-Gobain's captive capacity insulates margin control against alumina feedstock volatility. |
| Ceramic Bond Porosity Engineering | Vitrified CBN wheels with engineered structures displace aluminum oxide in Japanese OEM camshaft lines. |
| JIS Certification Pathway Investment | METI-coordinated documentation requirements constrain rapid entry for uncertified foreign suppliers. |
| Technical Service Team Deployment | Direct field engineering for grinding optimization remains underdeveloped across Southeast Asian clusters. |
| Dual GB-JIS Product Line Segregation | South Korean manufacturers serving both markets maintain parallel certification markings rather than harmonization. |
Study Parameters
Bottom-up machine tool density modeling reconciled against top-down abrasive consumption tracking forms the analytical core of this study. Primary interviews with grinding cell operators, automotive Tier-1 procurement leads, bonded abrasive plant managers, and semiconductor foundry process engineers combined with secondary validation from SAMR GB standard filings, METI JIS certification registries, customs trade data, and BIS ISI marking databases. Triangulation between demand-side installation rates and supply-side production capacity ensures statistical integrity.
Input-output matrices map abrasive grain sourcing through bauxite refining, synthetic diamond synthesis, and silicon carbide production to downstream bonded wheel, coated belt, and superabrasive slurry fabrication. Segmentation modeling spans product type, application intensity, end-user procurement structure, and material chemistry grade. CAGRs derive from spindle speed adoption curves, machine tool replacement cycles, and electrification-driven tolerance compression across the projection horizon. Forecast inputs incorporate SAMR enforcement intensity and JIS requalification timelines.
Raw material price volatility, regulatory certification divergence, and grinding machine retrofit adoption delays are the dominant revision risks. Forecasts reflect documented assumptions on electrification penetration and standard harmonization probability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Glass Abrasives Market
Abrasives
Polishing Powder Market
Abrasives
Global Ceramic Flap Disc Market
Abrasives
Global Rubber Bonded Abrasive Market
Abrasives
Global Abrasives Market
Abrasives
Fine Sandpaper Market
Abrasives
Carborundum Market
Abrasives
Abrasive Base Paper Market
Abrasives
Tungsten Carbide Powder Market
Abrasives
Chemical Mechanical Polishing Market
Abrasives
Abrasive Blasting Nozzle Market
Abrasives
New Zealand Abrasives Market
Abrasives
Boron Carbide Market
Abrasives
Abrasive Tools Market
Abrasives
Tile Abrasion Testing Market
Abrasives
Synthetic Abrasives Market