
 North America Specialty Food Ingredient Market | 2026-2036
North America Specialty Food Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
North America Specialty Food Ingredient Market Analytics
Consolidation among large-scale beverage manufacturers is recalibrating procurement volumes and technical specifications across the supply base. Cargill, Incorporated leverages its integrated supply chain to secure preferred supplier status with these consolidated buyers. Kerry Group plc anchors its position through deep R&D partnerships in flavor modulation and clean-label reformulation.
North America specialty food ingredients comprise functionally active substances added at precise concentrations—typically 0.1% to 5% by weight—to modify sensory properties, extend shelf stability, or enhance nutritional profiles in processed and packaged foods. Their primary commercial purpose centers on enabling manufacturers to meet label-friendly claims while maintaining processability and cost targets. Flavors command the largest revenue pool given their ubiquity across virtually every food category, while natural-source ingredients are outpacing synthetic alternatives in growth velocity as brand owners respond to retailer clean-label mandates. Emulsifiers and stabilizers together represent a concentrated margin segment where technical differentiation barriers protect specialist producers.
The FDA oversees GRAS determinations and food additive petitions, while USDA regulates organic certification pathways that directly shape premium positioning for natural-source suppliers. Health Canada and PMRA coordinate cross-border standards through joint working groups, reducing compliance duplication for suppliers serving both markets. Stakeholders must monitor evolving state-level labeling requirements in California and New York that frequently prefigure federal rulemaking cycles.
Market Dynamics
Clean-label mandates from retail chains are compressing formulation cycles, forcing ingredient suppliers to validate natural-source alternatives against synthetic baselines on accelerated timelines.
Growth Catalysts
- FDA GRAS Modernization:The updated notification framework streamlines novel ingredient pathways, reducing time-to-market for fermentation-derived proteins and bioactive extracts.
- Beverage Reformulation:Carbonated soft drink and ready-to-drink coffee manufacturers are replacing artificial colors and flavors with plant-derived alternatives to meet retailer scorecard requirements.
- California Innovation Clustering:Startup food brands concentrated in Los Angeles and San Francisco Bay Area corridors generate concentrated demand for prototype-scale ingredient sampling and co-development services.
Market Restraints
- Natural Color Stability:Anthocyanin and carotenoid-based alternatives exhibit pH sensitivity and light degradation that synthetic dyes do not, limiting application in transparent packaging formats.
- Organic Acid Supply Concentration:Citric acid production concentrates in Chinese manufacturing clusters, exposing North American formulators to tariff volatility and ocean freight disruptions.
- Clean-Label Cost Structure:Natural emulsifiers derived from sunflower or oat require 3-5x raw material input versus petroleum-based alternatives, compressing margin at price-sensitive tiers.
Strategic Opportunities
- Precision Fermentation Scale-Up:Dairy protein analogs produced via microbial fermentation command premium positioning in sports nutrition and infant formula applications.
- USDA Organic Certification Expansion:The National Organic Program's streamlined handler certification creates pathway for mid-tier suppliers to access private-label organic lines at major retailers.
- Direct-to-Manufacturer Platforms:Digital ingredient marketplaces bypass traditional distribution layers, enabling smaller suppliers to reach craft food producers in Texas and Colorado growth corridors.
Industry Challenges
- Regulatory Affairs Talent Scarcity:GRAS dossier preparation and FDA correspondence management require specialized expertise that outpaces university food science program output.
- Legacy Equipment Retrofit Costs:Natural ingredient handling often demands stainless steel upgrades and modified temperature controls incompatible with existing synthetic processing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Specialty Food Ingredient Market |
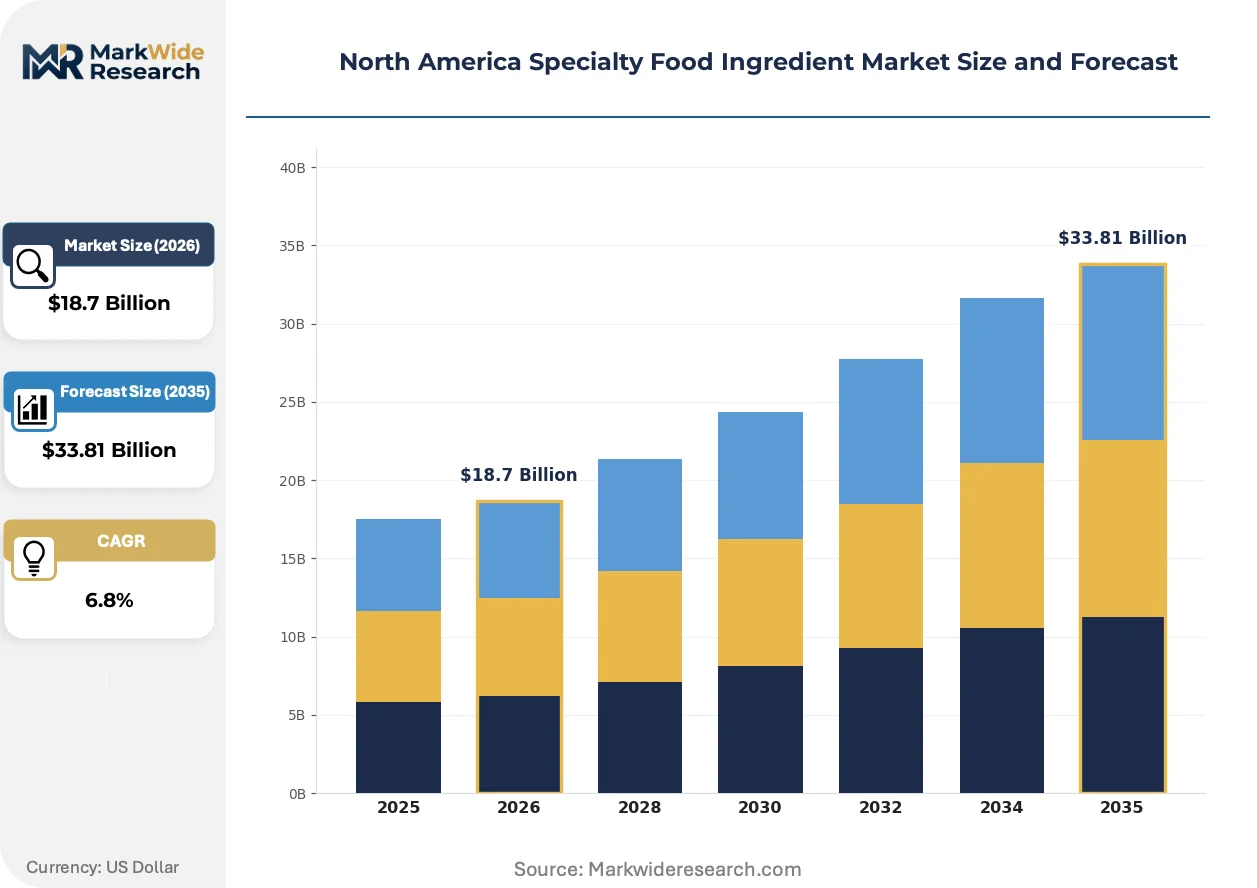
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavors, Sweeteners, Emulsifiers, Stabilizers Source: Natural, Synthetic, Organic, Conventional Form: Powder, Liquid, Granular, Paste End User: Food Manufacturers, Bakeries, Dairy, Beverage Industry |
| Companies Covered | Kerry Group plc, DuPont de Nemours, Inc., Archer Daniels Midland Company, International Flavors & Fragrances Inc., Sensient Technologies Corp., Cargill, Incorporated, Tate & Lyle PLC, DSM-Firmenich AG, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Specialty Food Ingredient Market Evolving Landscape
Biotechnology-enabled ingredient production is collapsing the traditional extraction-to-formulation pipeline, while regulatory data requirements force closer collaboration between suppliers and finished goods manufacturers.
Precision fermentation platforms for whey and casein equivalents are decentralizing protein supply away from concentrated dairy processing regions. Alternative dairy brands in the Northeast and Pacific Northwest are integrating these inputs at commercial scale. The technology is decentralizing procurement risk for manufacturers historically exposed to commodity milk powder price cycles.
Health Canada's expanded novel food notification requirements for cell-cultured and precision-fermented ingredients are extending pre-market review timelines. Ingredient firms must now generate compositional datasets and toxicological profiles earlier in development. Protein hydrolysate and bioactive peptide suppliers targeting cross-border distribution are front-loading regulatory investment to avoid launch delays.
Brand technical directors are compressing supplier qualification cycles from 18 months to 6-8 months to match accelerated product development timelines. This pattern displaces traditional pilot-scale testing in favor of rapid sensory validation and co-manufacturer compatibility checks. The shift is most pronounced in California's alternative protein startup ecosystem where speed-to-shelf determines funding access.
North America Specialty Food Ingredient Market Segmentation
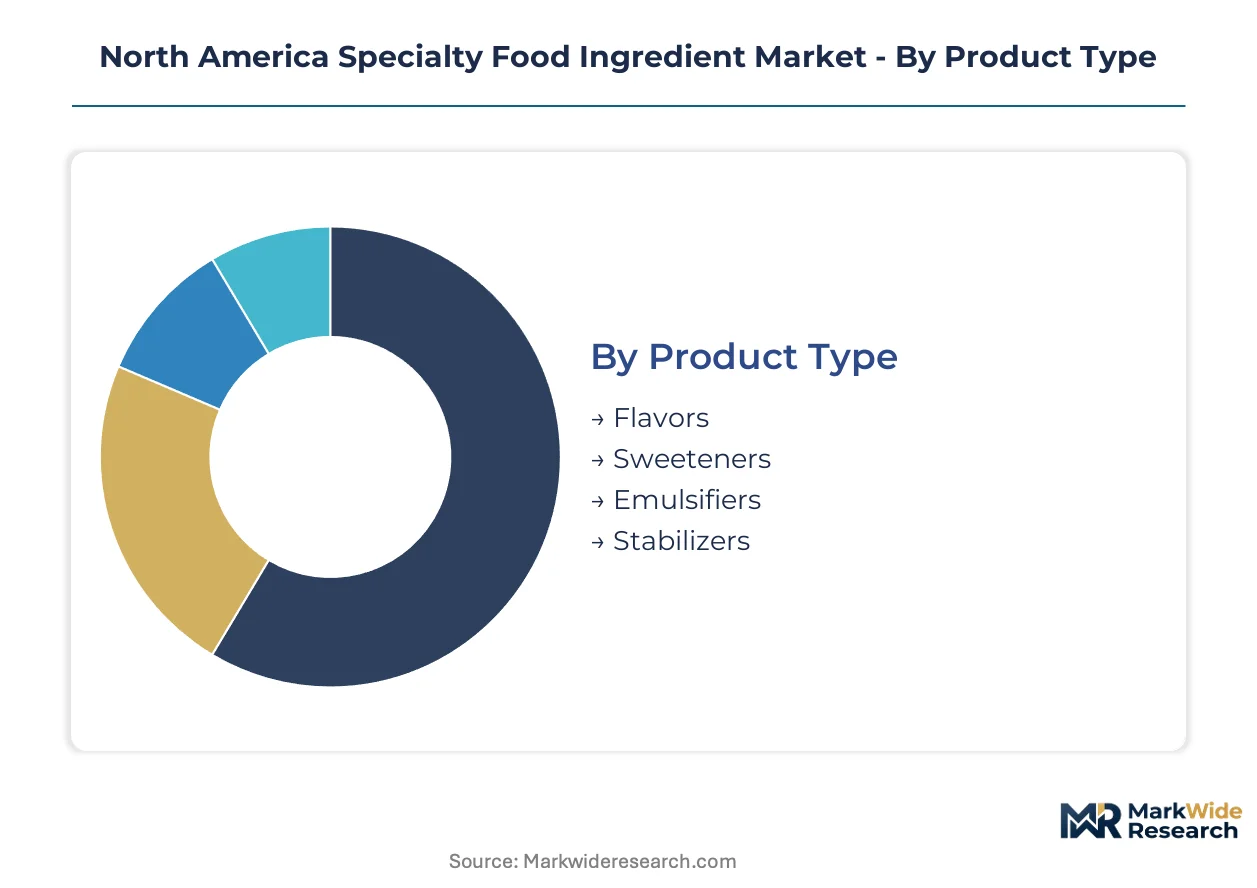
Ingredient suppliers must align technical portfolios with distinct formulation requirements across product categories, sourcing philosophies, and manufacturing formats. Segmentation reveals where premium positioning commands margin versus where scale economies dominate procurement decisions.
Product Type:
Reformulation cycles triggered by clean-label mandates are accelerating replacement demand across functional categories as manufacturers validate natural alternatives against established synthetic baselines.
- Flavors:Complex volatile compounds and reaction flavor systems deliver taste impact at 0.01-0.5% inclusion rates. Beverage manufacturers in California's innovation corridor drive concentrated demand for plant-derived profiles that satisfy retailer scorecard requirements while maintaining shelf stability.
- Emulsifiers:Lecithin, mono- and diglycerides, and polysorbates enable fat-water dispersion in dressings, spreads, and alternative dairy. Margins concentrate here where technical differentiation barriers protect specialist producers from commodity competition.
- Sweeteners:High-intensity and bulk sweetening systems replace or reduce caloric sugars.
- Stabilizers:Hydrocolloid and gum systems control viscosity, suspension, and freeze-thaw integrity.
Flavors sits at the top of the volume ranking, with Emulsifiers climbing the fastest.
Source:
Cost tier stratification separates premium-certified inputs from standard-grade alternatives, with procurement patterns diverging sharply between mass-market and specialty channel manufacturers.
- Natural:Plant, fermentation, and mineral-derived ingredients meeting clean-label definitions without synthetic chemical processing. Retailer mandates in California and New York prefigure federal rulemaking and concentrate demand validation investment.
- Organic:USDA National Organic Program certified inputs with full traceability documentation. The streamlined handler certification pathway enables mid-tier suppliers to access private-label organic lines at major retailers.
- Synthetic:Petrochemical or chemically synthesized ingredients optimized for cost and functional consistency.
- Conventional:Non-certified natural-source ingredients without organic premium positioning.
Natural dominates absolute volume, with Organic expanding most quickly.
Form:
Application-driven processing requirements dictate format selection, with dry blending, liquid injection, and extrusion systems imposing incompatible handling specifications on ingredient procurement.
- Powder:Spray-dried, agglomerated, or crystalline formats with extended shelf stability and precise dosing. Bakery and dry-mix manufacturers prioritize flowability and moisture resistance in climate-controlled Midwest processing facilities.
- Liquid:Aqueous or oil-based solutions, suspensions, and concentrates for direct incorporation. Beverage industry tank-farm operations favor liquid delivery to eliminate hydration steps and reduce dust exposure.
- Granular:Intermediate particle size for controlled dissolution or visual texture contribution.
- Paste:High-solids semi-moist formats for concentrated flavor or color delivery.
Powder leads in shipment volume, with Liquid gaining share fastest.
End User:
Customer-type concentration creates divergent service requirements, with multinational manufacturers demanding technical partnership versus craft producers prioritizing sampling flexibility and minimum order flexibility.
- Beverage Industry:Carbonated soft drink, ready-to-drink coffee, and functional drink manufacturers replacing artificial colors and flavors with plant-derived alternatives. Consolidation among large-scale producers is recalibrating procurement volumes and technical specifications.
- Food Manufacturers:Processed and packaged food producers spanning snacks, sauces, and prepared meals. These buyers enable ingredient suppliers to meet label-friendly claims while maintaining processability and cost targets across broad formulation portfolios.
- Dairy:Milk, cheese, yogurt, and alternative dairy processors.
- Bakeries:Commercial and artisanal bread, pastry, and confectionery operations.
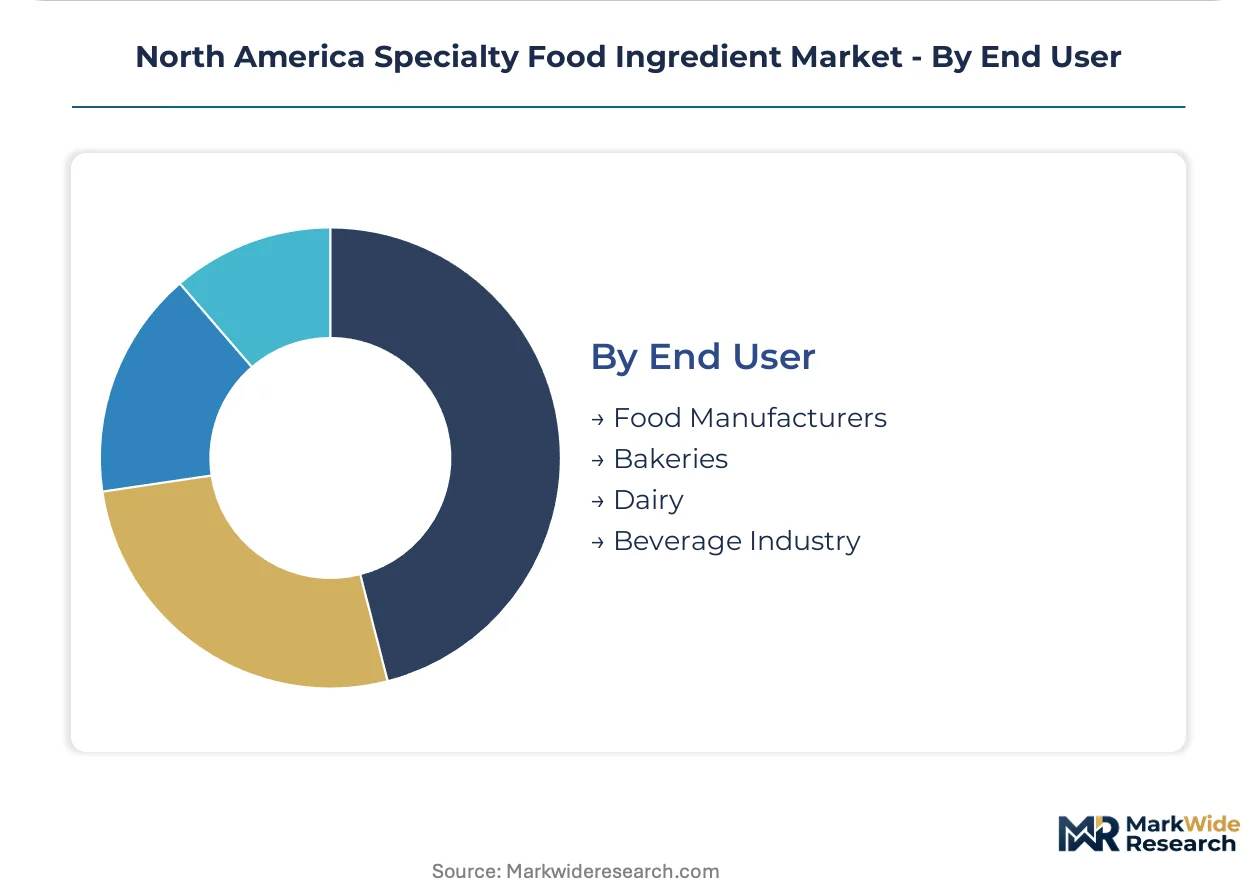
Beverage Industry commands the largest procurement volume, with Food Manufacturers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food science talent pools in the San Francisco Bay Area, Boston, and Toronto anchor North American innovation in enzyme engineering and precision fermentation. These clusters concentrate venture-backed startups alongside established ingredient R&D facilities. Cross-border regulatory coordination between FDA and Health Canada reduces compliance friction for suppliers operating across both markets.
United States
California's Los Angeles and San Francisco corridors concentrate startup food brands demanding prototype-scale sampling and co-development services. The FDA's updated GRAS notification framework streamlines novel ingredient pathways for fermentation-derived proteins. Texas and Colorado growth corridors attract craft food producers purchasing through direct-to-manufacturer digital platforms.
Canada
Health Canada and PMRA coordinate cross-border standards with FDA through joint working groups, reducing compliance duplication for suppliers serving both markets. The National Organic Program's streamlined handler certification creates pathways for mid-tier suppliers to access private-label organic lines. Ontario and Quebec house concentrated dairy processing and alternative protein manufacturing facilities.
Mexico
Beverage manufacturers in Mexico City and Monterrey reformulate carbonated soft drinks with plant-derived color alternatives to meet retailer export requirements. The country's national food safety regulator aligns with FDA protocols for GRAS-equivalent determinations. Northern border states concentrate maize-derived ingredient processing for cross-border supply chains.
North America Specialty Food Ingredient Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across ingredient categories, creating a tiered structure where scale economies clash with technical differentiation. The market consolidates around integrated supply chain operators capable of securing preferred status with multinational beverage manufacturers. Three archetypes dominate: agricultural processors with captive raw material access, flavor houses with deep R&D partnerships, and biotechnology platforms commercializing fermentation-derived inputs. Competitive moves center on backward integration into raw material sourcing and strategic partnerships for clean-label reformulation capabilities.
Among Ireland-based specialists, Kerry Group plc exemplifies the R&D partnership archetype through flavor modulation and clean-label reformulation positioning. Cargill, Incorporated represents the integrated agricultural processor model with supply chain control spanning crop procurement through finished ingredient delivery. DuPont de Nemours, Inc. occupies a position within the biotechnology-enabled tier, anchoring precision fermentation and enzyme technology applications.
| Leading Market Players |
|---|
| Kerry Group plc |
| DuPont de Nemours, Inc. |
| Archer Daniels Midland Company |
| International Flavors & Fragrances Inc. |
| Sensient Technologies Corp. |
| Cargill, Incorporated |
| Tate & Lyle PLC |
| DSM-Firmenich AG |
| Ingredion Incorporated |
| Others |
Value Network & Pricing Analysis
Food science talent concentration in California's innovation corridor establishes labor-cost differentials that widen spreads between premium R&D-partnership tiers and commodity spot pricing for standard-grade inputs.
Pricing Analysis
Bundled technical service contracts incorporating formulation support and regulatory dossier preparation command 40-60% premiums over unbundled ingredient-only transactions. Price differentiation rests on certification grade—USDA Organic and FDA GRAS-tiered documentation—and volume scale, with multinational beverage manufacturers extracting steep discounts for offtake commitments. Pricing pressure stems from clean-label cost compression as natural emulsifiers require 3-5x raw material input versus synthetic baselines. Mass-market retailers exhibit highest price sensitivity, while premium alternative protein startups prioritize speed-to-shelf over per-kilogram economics.
Supply Chain Analysis
Citric acid supply rests on concentrated Chinese manufacturing clusters, exposing North American formulators to tariff volatility and ocean freight disruptions. Raw material dependencies include fermentation feedstocks for precision-derived proteins, sunflower and oat bases for natural emulsifiers, and anthocyanin sources for plant-derived colors. Single-source vulnerability concentrates in organic acid supply chains. Distribution runs through integrated agricultural processors with captive crop procurement, supplemented by direct-to-manufacturer digital platforms for craft producer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where retailer clean-label mandates concentrate procurement toward premium-certified inputs with full traceability documentation.
For Market Incumbents: Anchor defensive positioning through backward integration into fermentation feedstock supply and captive organic certification capacity. Consolidated beverage manufacturers are squeezing supplier margins through volume concentration and accelerated qualification cycles. Kerry Group plc and Cargill, Incorporated demonstrate how R&D partnership depth and supply chain control respectively secure preferred status against commodity competition.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in natural emulsifiers offers white-space entry for mid-tier suppliers achieving USDA Organic handler certification. Texas and Colorado craft food corridors present the most penetrable geography, with digital marketplace access bypassing traditional distribution layers. Precision fermentation scale-up partnerships with alternative dairy brands in the Pacific Northwest provide credible go-to-market validation.
For Investors and Strategic Acquirers: Agricultural processors with integrated supply chains are the most active acquirers in this space, targeting biotechnology platforms for fermentation-derived protein capabilities. Long-term viability favors suppliers with dual natural-synthetic portfolios capable of serving both clean-label premium and cost-sensitive mass-market tiers. Watch FDA GRAS modernization implementation timelines as inflection indicators for novel ingredient pathway velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Decentralizes protein supply from concentrated dairy processing regions toward microbial platforms. |
| USDA Organic Certification Investment | Unlocks private-label organic lines at major retailers through streamlined handler pathways. |
| Direct-to-Manufacturer Platform Launch | Bypasses traditional distribution layers to reach craft producers in Texas and Colorado corridors. |
| GRAS Dossier Capability Buildout | Addresses regulatory affairs talent scarcity slowing novel ingredient time-to-market. |
| Co-Development Service Expansion | Captures California startup demand for prototype-scale sampling and accelerated formulation cycles. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction combined with secondary validation. Interview subjects included formulation scientists at beverage manufacturers, procurement directors at consolidated food producers, regulatory affairs specialists navigating FDA and Health Canada frameworks, and technical directors at precision fermentation startups. Secondary sources incorporated FDA GRAS notification filings, USDA National Organic Program certification databases, Health Canada novel food notifications, and customs trade data tracking citric acid and specialty chemical flows. Bottom-up volume modeling and top-down value triangulation anchored segment-level outputs.
Granularity-level modeling operated at ingredient-type, source-certification, physical-form, and end-user dimensions across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory pathway acceleration and clean-label mandate diffusion. Segment-specific inputs included beverage industry consolidation patterns, California innovation corridor startup formation rates, and cross-border regulatory coordination timelines between FDA and Health Canada.
Caveats apply where FDA GRAS modernization implementation delays, tariff volatility in Chinese organic acid supply, or natural color stability technical failures could materially shift the outlook. A small set of named triggers—regulatory pathway velocity, fermentation platform commercialization rates, and retailer clean-label mandate enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Specialty Shortenings Market
Specialty Ingredients
South America Specialty Food Ingredient Market
Specialty Ingredients
Specialty Carbohydrates Market
Specialty Ingredients
Personal Care Specialty Ingredients Market
Specialty Ingredients
Mango Butter Market
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Global Pet Food Flavors Market
Specialty Ingredients
Cupuacu Butter Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Global Ayurvedic Herbs Market
Specialty Ingredients
Specialty Syrup Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Madecassoside Market