
 Dried Blueberries Market | 2026-2036
Dried Blueberries Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Blueberries Market Analysis
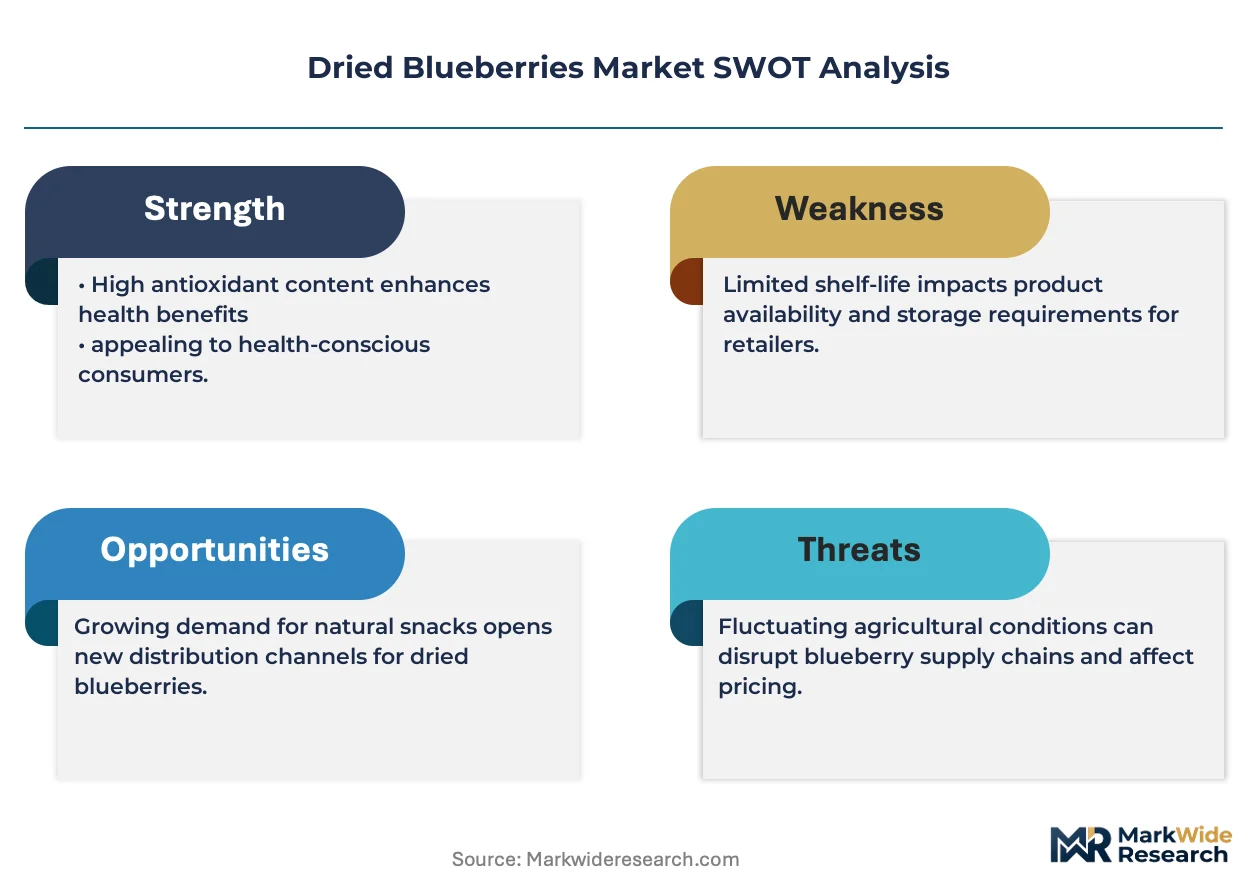
Contract dehydration services is consolidating how dried blueberry supply contracts are structured across the value chain. SunOpta Inc. leverages its integrated organic processing infrastructure to secure multi-year supply agreements with CPG buyers. Graceland Fruit, Inc. anchors its position through proprietary infused-drying technology that extends shelf stability without added preservatives. Meduri Farms, Inc. specializes in small-batch artisanal production, occupying a premium niche that competes on flavor intensity rather than volume scale.
Dried blueberries consist of whole or sliced Vaccinium corymbosum fruit reduced to moisture content below 15% through hot-air, freeze-drying, or infused-dehydration methods, preserving anthocyanin antioxidant levels for shelf-stable food applications. The organic product type commands disproportionate margin pools as certification barriers limit supplier entry and justify price premiums in health food channels. Freeze-dried formats represent the fastest-growing structural segment, driven by clean-label positioning in snack applications and superior texture retention in bakery end uses compared to conventional hot-air dried alternatives.
FDA nutrition labeling standards and USDA organic certification requirements shape product formulation and market access for domestic suppliers, while imported material faces phytosanitary screening under APHIS regulations. The EU's REACH framework and EFSA novel food assessments govern European import eligibility, adding compliance layers for exporters targeting multiple jurisdictions. Stakeholders must monitor evolving residue tolerance thresholds and carbon footprint disclosure mandates that will increasingly determine supplier qualification criteria across major procurement channels.
Market Dynamics
Contract dehydration services are consolidating procurement structures across the dried blueberry value chain, with processors bundling drying capacity into multi-year supply agreements that lock in volume commitments and quality specifications ahead of harvest cycles.
Growth Catalysts
- FDA Nutrition Facts Labeling:Updated declaration requirements for added sugars are pushing bakery manufacturers toward fruit inclusions that deliver sweetness perception without triggering mandatory disclosure thresholds.
- Freeze-Drying Technology:Superior texture retention and clean-label positioning are accelerating adoption in premium snack and cereal applications.
- Pacific Northwest Cultivation Infrastructure:Concentrated highbush blueberry acreage in Washington and Oregon supports industrial-scale drying operations with integrated cold chain logistics.
Market Restraints
- Input Cost Volatility:Fresh blueberry spot pricing fluctuates with weather-driven yield variations, compressing processor margins during poor harvest seasons.
- Supply Concentration Risk:Domestic drying capacity clusters in a limited number of contract dehydration facilities, creating bottlenecks during peak harvest windows.
- Regulatory Friction:APHIS phytosanitary screening requirements for imported material introduce clearance delays that conflict with just-in-time bakery production schedules.
Strategic Opportunities
- Underpenetrated Foodservice Channel:Institutional bakery and hospitality segments remain underserved by current supplier configurations optimized for retail CPG.
- EU Green Deal Alignment:Carbon footprint disclosure mandates create qualification advantages for North American suppliers with verified low-emission drying processes.
- Convergence of Infusion and Freeze-Drying:Hybrid processing methods that combine rapid moisture reduction with controlled sugar infusion open texture customization for confectionery applications.
Industry Challenges
- Organic Certification Timeline:USDA organic transition periods and audit backlogs delay supplier entry into premium-margin distribution channels.
- Skill Gap in Process Engineering:Specialized expertise in anthocyanin retention optimization and moisture uniformity control remains scarce across the processor workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Blueberries Market |
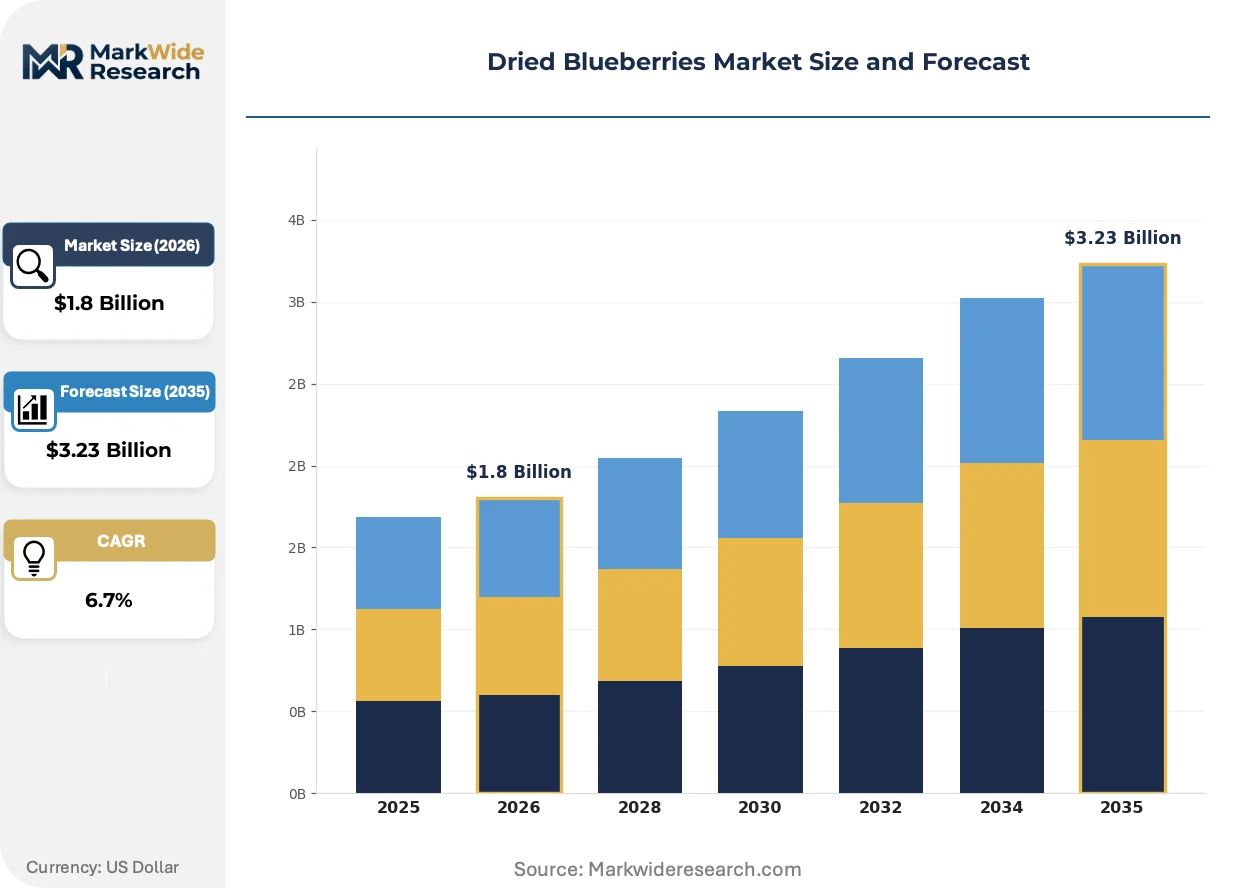
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Freeze-Dried, Sugar-Free Packaging Type: Bulk, Retail Packs, Resealable Bags, Pouches Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Specialty Shops End Use: Food Processing, Bakery Products, Snacks, Beverages |
| Companies Covered | True Blue Farms, SunOpta Inc., Shoreline Fruit LLC, Meduri Farms, Inc., Kiantama Oy, Oregon Berry Packing, Inc., Graceland Fruit, Inc., Wyman's of Maine LLC, Royal Nut Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Blueberries Market Emerging Trajectories
Processing technology differentiation and regulatory disclosure requirements are restructuring competitive advantage in dried blueberry supply, with equipment investments and certification positioning determining access to contracted volume pools.
Freeze-drying systems is overtaking conventional hot-air dehydration in premium product tiers due to superior structural integrity and rehydration performance. Bakery R&D teams at major cereal manufacturers are specifying freeze-dried formats for inclusion in clean-label product lines. This equipment shift is compressing capital recovery timelines for processors while raising barriers for hot-air-only operators.
REACH framework compliance and EFSA novel food assessments are reshaping European import eligibility for infused-dried formats with modified sugar profiles. Exporters must now document substance safety and processing method transparency ahead of market entry. Suppliers targeting EU distribution are restructuring quality assurance protocols to preempt regulatory rejection at port of entry.
Direct contracting between processors and certified organic growers is displacing spot market purchasing for premium product lines. Large CPG buyers are embedding sustainability verification requirements into supply agreements. This relationship compression is most visible in the Pacific Northwest, where multi-year grower contracts now precede drying capacity expansion decisions.
Dried Blueberries Market Segmentation
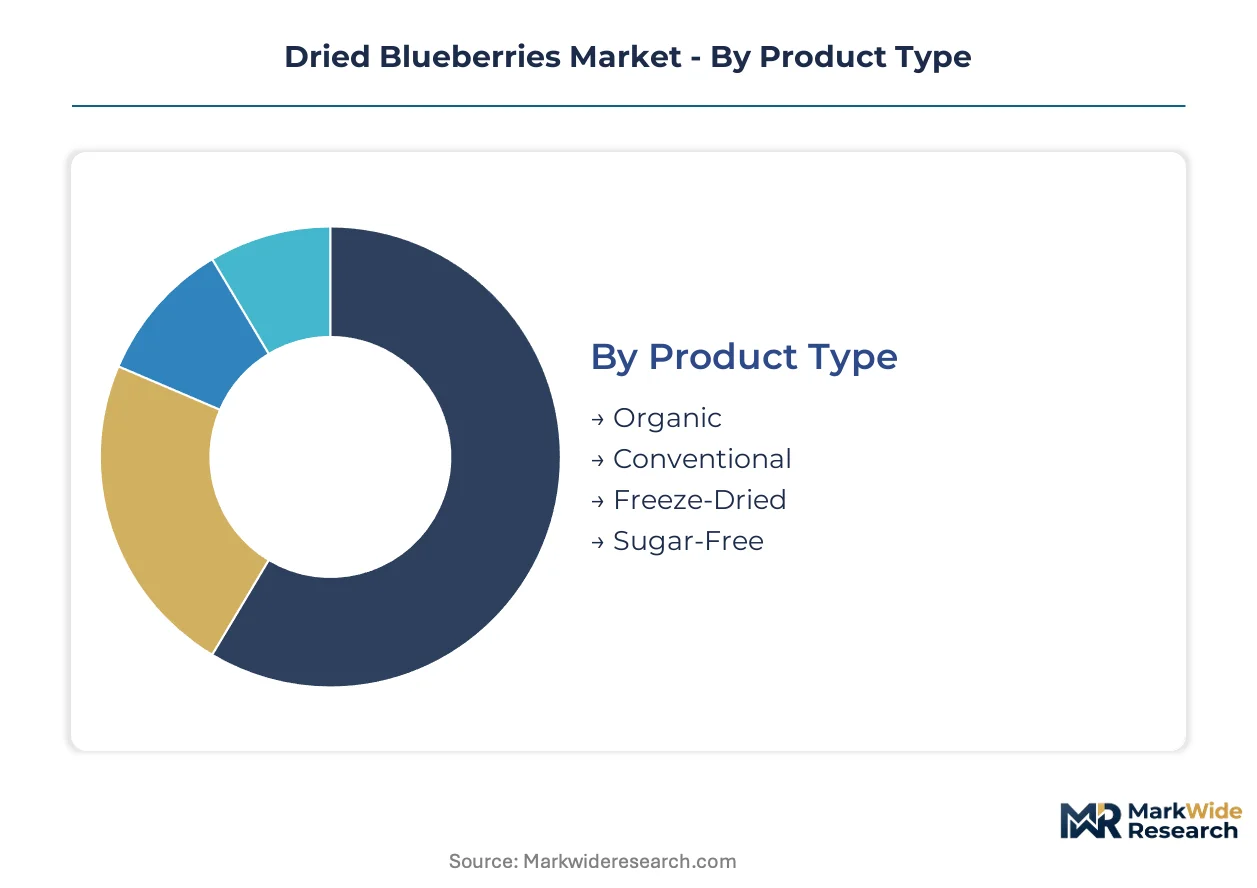
Dried blueberry procurement structures diverge sharply across certification tiers and processing methods. Bakery manufacturers and snack brands configure supply contracts around specific moisture specifications, organic credentials, and rehydration performance that determine formulation compatibility.
Product Type:
Standardization dominates conventional grades while organic and freeze-dried formats command bespoke supply arrangements with dedicated processing lines.
- Organic:USDA certification barriers limit supplier entry to growers completing three-year transition protocols. Pacific Northwest cultivation clusters anchor supply, with CPG buyers embedding multi-year grower contracts into premium product lines to secure volume ahead of harvest cycles.
- Freeze-Dried:Sublimation processing preserves cellular structure for superior rehydration in bakery applications. Clean-label cereal manufacturers specify this format for inclusion in product lines targeting added-sugar disclosure thresholds under FDA nutrition labeling rules.
- Conventional:Hot-air dehydration at industrial scale serves mass-market bakery and foodservice channels with cost-optimized specifications.
- Sugar-Free:Unsweetened formats target diabetic-friendly and ketogenic product formulations with minimal processing additives.
Most installed capacity flows through Conventional. Expansion is steepest in Freeze-Dried.
Packaging Type:
Volume scale and shelf-life requirements segment procurement between industrial bulk and consumer-facing formats with moisture barrier specifications.
- Bulk:Food manufacturers source 10-25kg food-grade containers with nitrogen flushing for production line integration. Washington and Oregon processors dominate this channel through integrated cold chain logistics serving North American bakery operations.
- Retail Packs:Stand-up pouches with window features and portion-controlled sizing target health-conscious snack consumption in conventional grocery.
- Resealable Bags:Zip-lock closure systems extend pantry stability for household purchasing with repeated access patterns.
- Pouches:Flexible laminate structures optimize shipping cube efficiency for direct-to-consumer and club store distribution.
Foodservice and industrial procurement concentrates in Bulk. Consumer channel growth favors Resealable Bags.
Distribution Channel:
Certification verification needs and purchase frequency shape channel selection, with organic credentials requiring specialized retail environments.
- Supermarkets:Conventional dried blueberries occupy center-store baking aisles with price-promotional velocity driving placement decisions.
- Online Retailers:Subscription models and bulk sizing attract pantry-stocking behavior with direct fulfillment bypassing wholesale markups.
- Health Food Stores:Staff-curated assortments emphasize organic certification and clean-label positioning for ingredient-focused shoppers.
- Specialty Shops:Gourmet retailers stock artisanal small-batch formats with provenance storytelling and premium price positioning.
Volume throughput peaks in Supermarkets. Customer acquisition costs favor Online Retailers.
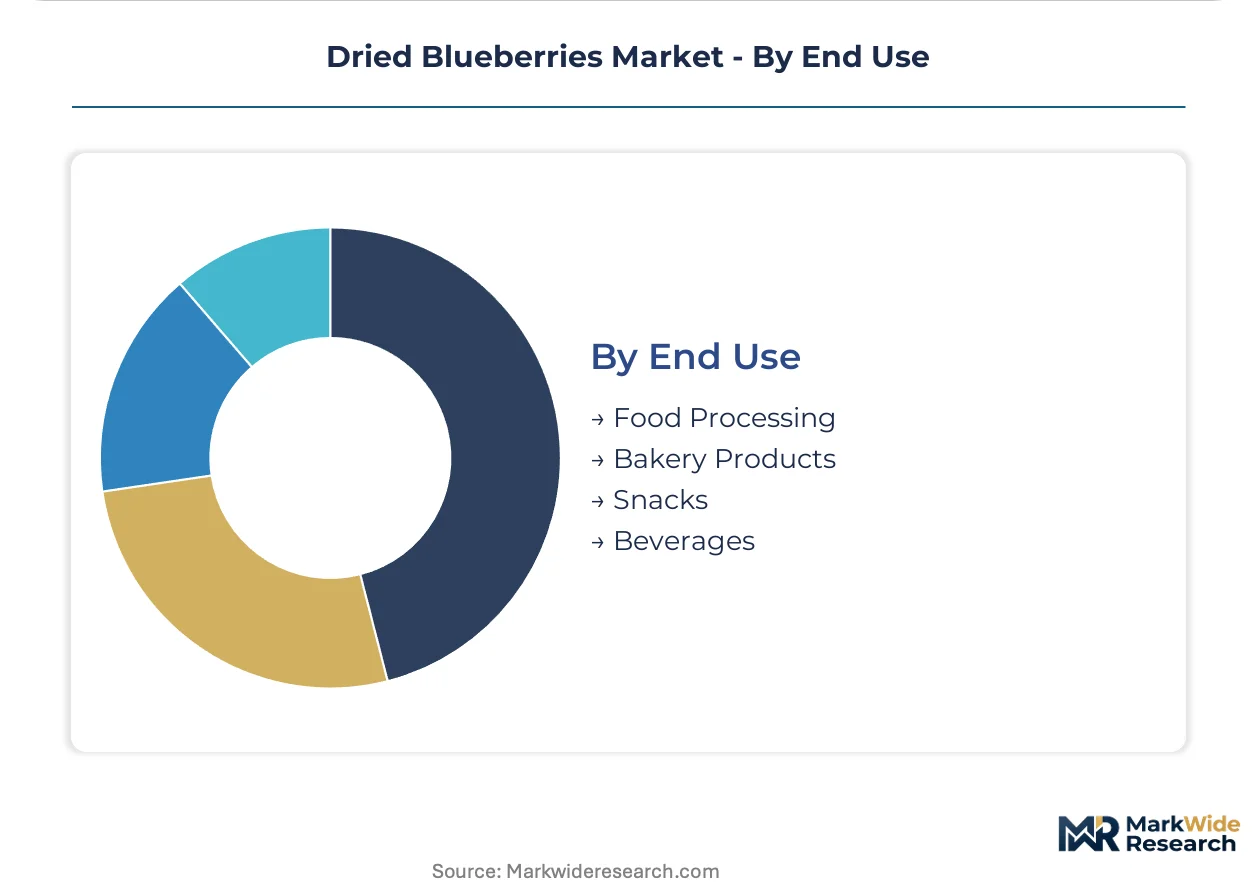
End Use:
Moisture specifications and particle size requirements fragment demand across industrial processing and finished goods manufacturing.
- Bakery Products:Muffin, bread, and cereal applications specify whole berry integrity with controlled rehydration rates. Freeze-dried formats gain specification share in clean-label lines reformulating to meet FDA added-sugar disclosure thresholds.
- Snacks:Trail mix and granola applications prioritize shelf stability and texture contrast with minimal breakage tolerance.
- Food Processing:Ingredient manufacturers incorporate dried blueberries into fruit fillings, sauces, and dairy applications with customized particle sizes.
- Beverages:Powdered smoothie and functional drink formats utilize milled dried fruit for dispersion and solubility performance.
Contracted volume concentrates in Bakery Products. Reformulation activity is accelerating fastest in Snacks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting dried blueberry processing capacity toward jurisdictions with streamlined organic certification pathways and lower energy costs for dehydration operations. Production migration follows compliance-cost differentials rather than raw material proximity alone.
United States
Pacific Northwest cultivation clusters in Washington and Oregon anchor industrial-scale drying infrastructure with integrated cold chain logistics. FDA nutrition labeling requirements for added sugars are accelerating bakery manufacturer procurement of fruit inclusions. Contract dehydration facilities in the Willamette Valley are expanding capacity to secure multi-year CPG supply agreements.
Canada
British Columbia's highbush blueberry acreage supports specialized organic drying operations serving North American health food channels. Health Canada and PMRA residue tolerance standards shape import eligibility for processed fruit entering cross-border distribution. Processing cooperatives in the Fraser Valley are consolidating grower contracts to achieve scale efficiencies.
Germany
REACH framework compliance and EFSA novel food assessments govern eligibility for infused-dried formats entering European distribution. Industrial bakery clusters in Bavaria and North Rhine-Westphalia specify moisture-controlled dried fruit for clean-label product lines. Hamburg-based importers are restructuring quality assurance protocols to preempt port-of-entry regulatory rejection.
China
Domestic consumption of functional snack ingredients is expanding processing capacity in Shandong and Jiangsu provinces. SAMR food safety standards and GB labeling requirements shape product formulation for both domestic sale and export eligibility. Yangtze River Delta processors are investing in freeze-drying equipment to capture premium export margins.
Australia
TGA-equivalent food standards and biosecurity screening under DAWE protocols govern import eligibility for dried fruit entering domestic manufacturing. Victorian and Tasmanian blueberry cultivation supports small-batch artisanal drying operations targeting Asia-Pacific gourmet channels. Melbourne-based specialty food distributors are curating provenance-storytelling formats for premium positioning.
Dried Blueberries Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated processors commanding premium-tier supply agreements while toll dehydration operators serve volume-driven bakery channels. The vendor base organizes around three archetypes: vertically integrated growers with captive drying capacity, specialized contract dehydration services, and artisanal small-batch producers competing on flavor intensity. M&A activity concentrates on acquiring certified organic acreage with transition-period completion, while strategic partnerships between processors and CPG buyers lock in multi-year volume commitments ahead of harvest cycles.
Within the integrated processing tier, SunOpta Inc. and Graceland Fruit, Inc. exemplify divergent strategic positioning—SunOpta leveraging organic certification infrastructure for multi-year supply agreements, Graceland Fruit anchoring market presence through proprietary processing technology. Meduri Farms, Inc. occupies a distinct artisanal niche that competes on product differentiation rather than production scale. These three entities collectively represent the spectrum from industrial-scale contract manufacturing to premium small-batch production.
| Leading Market Players |
|---|
| True Blue Farms |
| SunOpta Inc. |
| Shoreline Fruit LLC |
| Meduri Farms, Inc. |
| Kiantama Oy |
| Oregon Berry Packing, Inc. |
| Graceland Fruit, Inc. |
| Wyman's of Maine LLC |
| Royal Nut Company |
| Others |
Supply Flow & Price Mechanics
Fresh blueberry spot pricing volatility in the Pacific Northwest cascades through three distinct downstream tiers, with organic certification premiums widening spreads between conventional hot-air dried and freeze-dried formats. Energy costs for dehydration operations in Washington and Oregon processing clusters feed directly into contract pricing structures, while FDA nutrition labeling compliance investments compress margins for non-specialized toll operators.
Pricing Analysis
Distributor markup layers separate bulk industrial procurement from retail shelf placement, with health food channel premiums reflecting organic certification audit costs. Three-tier pricing structure across premium freeze-dried, standard conventional, and economy foodservice grades tracks processing method complexity. Cost compression in conventional hot-air tiers is intensifying because Pacific Northwest cultivation concentration exposes processors to synchronized weather-driven yield shocks. Foodservice buyers exhibit highest price sensitivity, while clean-label cereal manufacturers absorb freeze-dried premiums for FDA added-sugar disclosure compliance.
Supply Chain Analysis
Single-source vulnerability sits with Pacific Northwest contract dehydration capacity, where Washington and Oregon facilities process the majority of North American dried blueberry volume. Fresh fruit supply draws from concentrated highbush cultivation in the Willamette Valley and Fraser Valley, with imported Chilean and Peruvian material subject to APHIS phytosanitary clearance delays. Tariff exposure on Chinese processing equipment and European export packaging materials compounds input cost uncertainty. Distribution runs through integrated cold chain logistics serving bakery manufacturing clusters, with direct processor-to-CPG contracting displacing spot market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dried blueberry market functions as a geographic-arbitrage play between Pacific Northwest energy costs for dehydration and British Columbia's streamlined organic certification pathways, with regulatory compliance cost differentials driving processing capacity migration decisions.
For Market Incumbents: Acquire certified organic acreage with completed three-year transition periods to lock in premium-margin supply ahead of harvest cycles. Integrate freeze-drying capacity additions in Oregon to capture clean-label cereal manufacturer procurement shifting from hot-air alternatives. Defend against emerging South American dried fruit entrants by embedding multi-year volume commitments into CPG supply agreements before harvest windows. For New Entrants and Emerging Players: Foodservice channel distributors represent the most accessible partnership pathway for bypassing established retail CPG supply relationships. Target institutional bakery and hospitality segments currently underserved by processor configurations optimized for retail packaging. Enter through private-label manufacturing arrangements with regional bakery cooperatives seeking differentiated fruit inclusions. For Investors and Strategic Acquirers: Consolidation pressure builds where organic certification backlogs delay supplier entry into premium-margin distribution channels, creating acquisition opportunities for transition-period acreage. Long-term viability centers on backward integration into cultivation with captive drying capacity. Watch freeze-drying equipment utilization rates as the inflection signal for premium format demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captures USDA certification premiums by controlling three-year transition timelines. |
| Freeze-Drying Capacity Expansion | Positions processors for FDA clean-label cereal manufacturer procurement shifts. |
| Multi-Year CPG Supply Agreements | Locks in volume commitments ahead of weather-driven fresh blueberry price spikes. |
| EU REACH Compliance Investment | Enables European market access for infused-dried formats with modified sugar profiles. |
| Foodservice Channel Development | Addresses underpenetrated institutional bakery and hospitality procurement segments. |
Methodological Framework
Bottom-up bakery and snack application modeling reconciled against top-down contract dehydration capacity tracking forms the analytical core of this study. Primary interviews with dried fruit procurement managers at cereal manufacturers, organic certification auditors, contract dehydration facility operators, and Pacific Northwest grower cooperative representatives combined with secondary validation from USDA organic certification databases, FDA food labeling guidance documents, and customs trade flow records. Triangulation between processor-reported volume commitments and CPG buyer sourcing disclosures verified supply-side estimates.
Input-output matrices mapped fresh blueberry harvest volumes through processing method yields to end-use consumption across bakery, snack, and foodservice channels. Segmentation dimensions modeled include organic versus conventional certification, freeze-dried versus hot-air versus infused-dehydration processing, bulk versus retail packaging, and regional production cluster. CAGRs were derived from trend extrapolation of contracted volume growth rates adjusted for processing capacity expansion timelines. Forecast inputs incorporated FDA regulatory implementation schedules and EU carbon footprint disclosure mandate adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Pacific Northwest weather pattern shifts and APHIS phytosanitary screening protocol changes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Yacon Fruit Extract Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
Dates Market
Fruits and Vegetables
Egypt Fruits and Vegetables Market
Fruits and Vegetables
Mulberry Market
Fruits and Vegetables
Fresh Apricots Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Spain Lime Market
Fruits and Vegetables
Button Mushroom Products Market
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Canada Fruits and Vegetables Market
Fruits and Vegetables
Global Not from Concentrate (NFC) Puree Market
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
Pineapple Market