
 Acai Berry Market | 2026-2036
Acai Berry Market Size, Share, and Industry Trends Forecast 2026-2036
Acai Berry Market Intelligence
The acai berry trade is rebalancing between premium freeze-dried powders and commodity-grade pulp concentrates as input costs diverge. Sambazon Inc. leverages its Amazon basin sourcing infrastructure to anchor supply security for North American beverage clients. Navitas Organics differentiates through certified organic positioning across multiple formulation tiers. Terrasoul Superfoods competes on price-accessible bulk formats while sustaining direct-to-consumer channel control.
Acai berry denotes the dark purple fruit of Euterpe oleracea, a palm species native to Amazonian floodplains, containing anthocyanins, polyphenols, and omega fatty acids typically preserved through flash-pasteurization or lyophilization for food and nutraceutical applications. Powder formulations lead value capture due to extended shelf stability and concentrated bioactive content, while pulp segments serve high-volume beverage manufacturing with thinner margin structures. Online retail channels are expanding fastest among distribution pathways, though health stores retain stronger unit economics in premium organic and non-GMO positioning.
Brazil's MAPA and the USDA enforce divergent phytosanitary and organic certification protocols that shape export eligibility and label claims for acai-derived products. The EU's Novel Food Regulation and EFSA evaluation frameworks govern market access for new acai formats and blended preparations entering European commerce. Stakeholders must monitor evolving pesticide residue thresholds and deforestation-linked sourcing disclosure requirements that threaten supply continuity from core harvesting regions.
Market Dynamics
Acai berry supply chains are restructuring around flash-freeze logistics networks that preserve anthocyanin potency from Pará state harvest to North American processing facilities, compressing spoilage windows and reshaping procurement geography.
Growth Catalysts
- USDA Organic Certification:Brazilian exporters are retrofitting collection cooperatives to meet USDA organic documentation standards, unlocking premium shelf placement in US natural retail channels.
- Functional Beverage Formulation:Antioxidant-rich smoothie and ready-to-drink categories are absorbing acai pulp concentrates as base ingredients, creating steady offtake volumes from Amazon basin processors.
- Pará State Harvest Concentration:Wild-harvested berry clusters from Belém-adjacent floodplains dominate export-quality raw material flows, anchoring supply security for international buyers.
Market Restraints
- Perishability Infrastructure Costs:Flash-pasteurization and lyophilization equipment requires substantial capital deployment, elevating barriers for new processing entrants.
- EU Novel Food Regulatory Friction:EFSA evaluation frameworks for new acai formats and blended preparations create 18-24 month market access timelines that deter smaller exporters.
- Climate Volatility in Core Harvest Zones:Irregular flooding patterns in Amazonian tributary systems are compressing viable collection windows and elevating raw material price instability.
Strategic Opportunities
- Direct-to-Consumer Powder Formats:Freeze-dried acai powders with extended shelf stability are penetrating subscription-based wellness platforms, bypassing traditional retail markup structures.
- Deforestation-Linked Sourcing Disclosure:EU Green Deal supply chain transparency requirements are creating first-mover advantages for exporters with GPS-tracked collection documentation.
- Cosmeceutical Application Expansion:Topical formulations leveraging omega fatty acid content are entering prestige skincare channels, diversifying beyond ingestible categories.
Industry Challenges
- Phytosanitary Documentation Complexity:Brazil's MAPA and USDA maintain divergent residue testing protocols, forcing exporters to maintain dual certification workflows that strain compliance teams.
- Cold Chain Integrity Maintenance:Pulp concentrate shipments require uninterrupted -18°C transit from Belém port to destination markets, with deviation events triggering total product loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acai Berry Market |
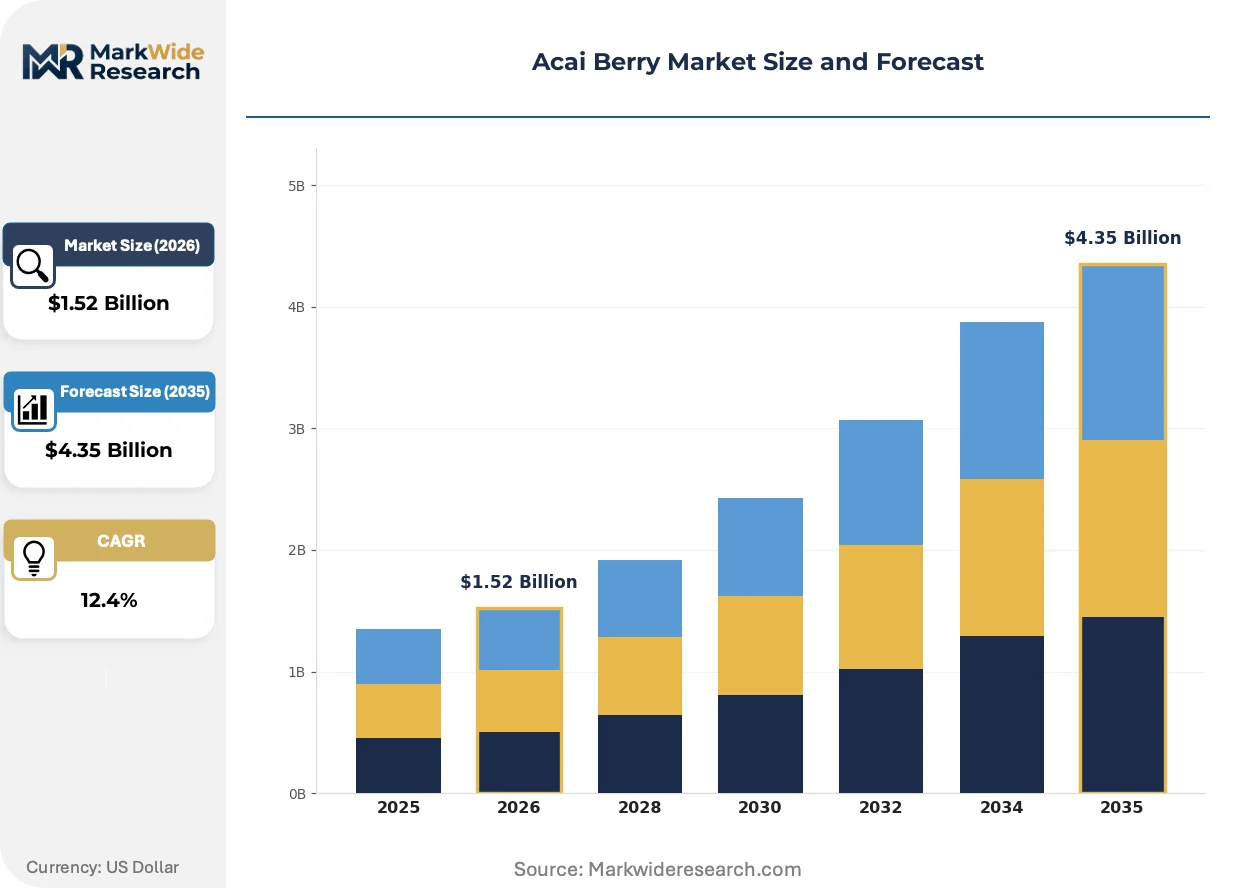
| Market Size in 2026 | $1.52 Billion |
| Market Size in 2035 | $4.35 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Pulp, Juice, Capsules Formulation: Organic, Non-GMO, Freeze-Dried, Blends Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales End User: Food Industry, Beverage Sector, Nutraceuticals, Retail Consumers |
| Companies Covered | Acai Roots Inc., Navitas Organics, The Berry Company Limited, Nativo Acai, Sunfood Superfoods, Sambazon Inc., Terrasoul Superfoods, Oakberry, Amafruits, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acai Berry Market Strategic Shifts & Innovations
Lyophilization technology is compressing the cost-performance gap between commodity pulp and premium powder formats, while regulatory disclosure mandates and channel disintermediation are rewriting how acai products reach end consumers.
Flash-freeze tunnel systems with integrated nitrogen injection are absorbing moisture removal tasks previously handled by slower vacuum-based methods. Mid-scale Brazilian processors are adopting these units to capture powder-grade margins previously reserved for specialized lyophilization facilities. The technology is absorbing capital allocation that would otherwise flow toward pulp concentrate capacity expansion.
EU Green Deal deforestation-free supply chain regulations are mandating geolocation verification for harvested berry clusters entering European commerce. Exporters must now deploy GPS-tracked collection mapping and blockchain-anchored custody documentation to maintain market access. Smallholder cooperatives in Pará state are most affected, with many consolidating into larger associations to share compliance infrastructure costs.
Health store buyers are unbundling after-sales merchandising support from wholesale purchasing agreements, shifting shelf placement negotiations to direct brand-retailer relationships. This disintermediation compresses distributor margins while rewarding acai brands with in-house retail marketing capabilities. The pattern is most visible in California and New York metro natural retail corridors, where local store chains now demand category management services from suppliers rather than intermediaries.
Acai Berry Market Segmentation
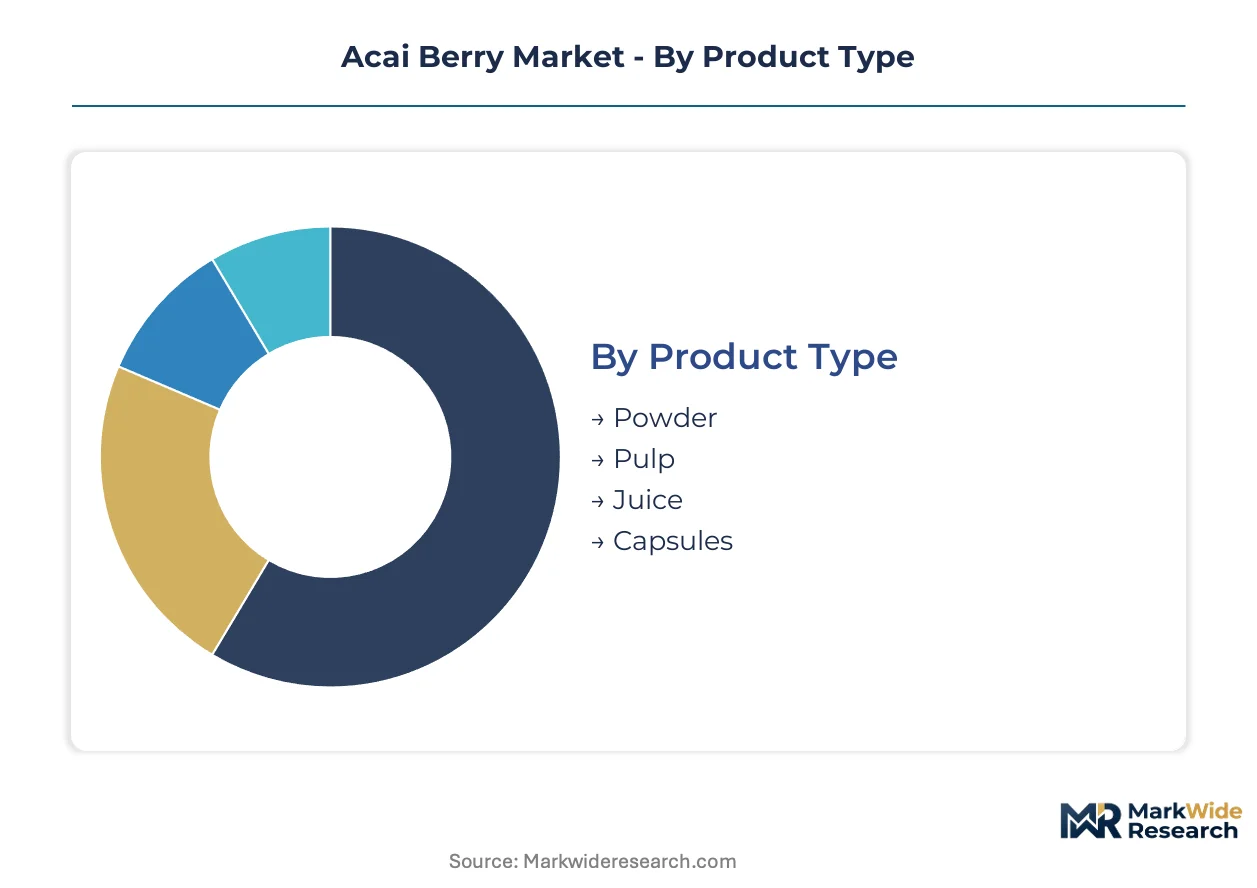
Acai berry value capture diverges sharply across preservation formats and certification tiers, with processing technology determining shelf stability, margin structure, and regulatory complexity. Buyers upgrade from commodity pulp to concentrated powders as application requirements shift from beverage manufacturing to nutraceutical and premium wellness positioning.
Product Type:
Upgrade cycles from perishable pulp to shelf-stable concentrates reshape procurement economics and cold chain infrastructure requirements across downstream industries.
- Powder:Lyophilized or spray-dried particles retain anthocyanin potency at ambient temperatures, enabling extended distribution reach. Demand concentrates in nutraceutical capsule manufacturing and direct-to-consumer wellness subscriptions where bioactive density justifies premium positioning.
- Pulp:Flash-pasteurized puree serves high-volume smoothie chains and ready-to-drink formulation, requiring uninterrupted -18°C logistics from Pará state processing facilities to North American ports. USDA organic certification unlocks placement in natural retail channels.
- Juice:Filtered liquid extracts target beverage dilution and flavoring applications with thinner margin structures than concentrated formats.
- Capsules:Encapsulated powder delivers standardized dosing for supplement regimens, competing on convenience against bulk powder alternatives.
Pulp sits at the top of the volume ranking, with powder climbing the fastest as wellness platforms absorb freeze-dried formats into subscription models.
Formulation:
Cost tiers stratify sharply around certification overhead, with organic documentation adding 15-30% procurement premiums that commodity buyers avoid.
- Organic:USDA and EU organic protocols require GPS-tracked harvest documentation and residue testing that Pará state cooperatives are consolidating to afford. This tier commands shelf placement in Whole Foods and equivalent natural retail chains.
- Non-GMO:Identity preservation systems verify genetic integrity through processing, serving buyers in jurisdictions with labeling mandates or consumer preference for conventional breeding.
- Freeze-Dried:Sublimation-based moisture removal preserves cellular structure and bioactive concentration, bridging powder performance with whole-food positioning.
- Blends:Acai combined with complementary superfruits or protein matrices targets specific functional claims in sports nutrition and meal replacement categories.
Organic formulations lead revenue per kilogram, with freeze-dried formats expanding most quickly as Brazilian processors adopt nitrogen-injection tunnel systems.
Distribution Channel:
Channel disintermediation compresses traditional distributor margins while rewarding brands with direct customer relationships and category management capabilities.
- Online Retail:Amazon, Thrive Market, and brand-owned subscription platforms bypass retail markup structures, capturing recurring revenue from wellness-focused households.
- Supermarkets:Kroger, Safeway, and conventional grocers stock pulp and juice in frozen aisles, prioritizing velocity over margin in competitive smoothie ingredient sets.
- Health Stores:Sprouts, Natural Grocers, and independent co-ops demand in-house merchandising support, shifting shelf negotiations from distributors to brand teams.
- Direct Sales:Multi-level marketing networks and practitioner channels deliver education-intensive positioning for therapeutic applications.
Online retail captures the steepest expansion trajectory, though health stores retain superior unit economics in premium organic positioning.
End User:
Application maturity varies from established beverage manufacturing to emerging cosmeceutical exploration, with regulatory pathways determining market access timelines.
- Food Industry:Bakeries, confectioners, and frozen dessert manufacturers incorporate acai for color and antioxidant claims in granola bowls, sorbets, and chocolate coatings.
- Beverage Sector:Functional drink and smoothie chains anchor pulp offtake volumes, with Sambazon supplying formulation-ready concentrates to North American bottlers.
- Nutraceuticals:Capsule and tablet manufacturers standardize anthocyanin content for cardiovascular and cognitive health positioning, navigating FDA structure-function claim boundaries.
- Retail Consumers:Home preparation of smoothie bowls and wellness recipes drives powder and frozen pack purchases through grocery and digital channels.
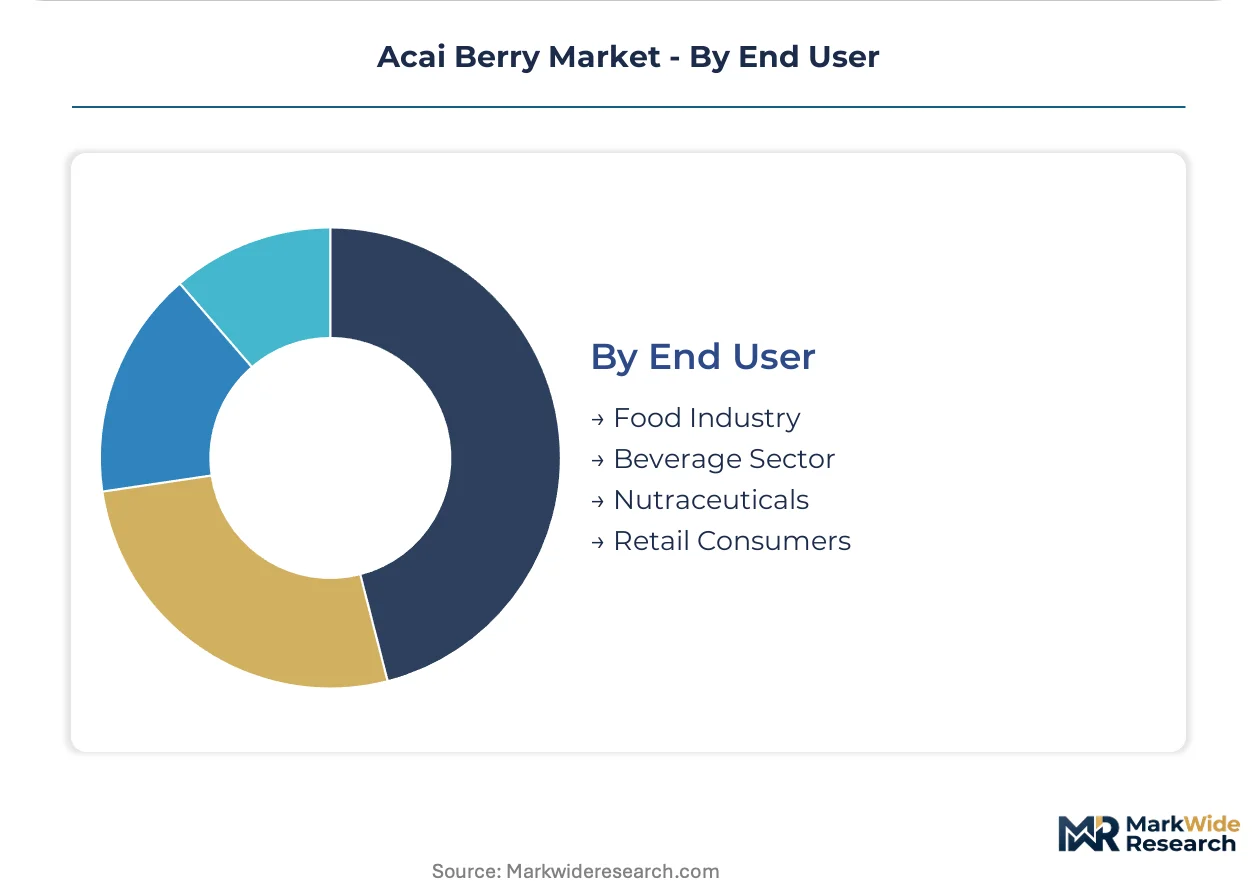
Beverage sector absorption dominates raw material flows, with nutraceuticals gaining share fastest as clinical research validates bioactive mechanisms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Harvesting cooperatives and flash-freeze logistics specialists concentrate workforce capacity in Brazil's Pará state, anchoring raw material flows for international buyers. Processing technicians and cold chain operators distribute across North American and European import hubs, managing lyophilization and distribution infrastructure.
Brazil
Wild-harvested berry clusters from Belém-adjacent floodplains supply export-quality raw material to North American beverage manufacturers and European nutraceutical processors. MAPA enforces phytosanitary documentation standards that shape export eligibility, with residue testing protocols diverging from USDA requirements. Pará state cooperatives are consolidating to share GPS-tracked collection infrastructure mandated by EU Green Deal transparency regulations.
United States
Functional beverage formulators in California and New York metro corridors absorb acai pulp concentrates for antioxidant-rich smoothie and ready-to-drink product lines. USDA organic certification unlocks premium shelf placement in Whole Foods and equivalent natural retail channels, elevating procurement premiums for documented supply chains. Los Angeles-based Sambazon anchors North American distribution through Amazon basin sourcing infrastructure.
Germany
EU Novel Food Regulation compliance specialists in Hamburg and Frankfurt manage EFSA evaluation frameworks for new acai formats entering European commerce. REACH-aligned residue documentation and deforestation-free supply chain verification create 18-24 month market access timelines that favor established exporters with dedicated regulatory teams. Berlin wellness platforms are absorbing freeze-dried powders into subscription-based direct-to-consumer models.
Japan
Cosmeceutical formulators in Tokyo and Osaka are exploring topical applications leveraging omega fatty acid content for prestige skincare channels. METI standards govern import documentation for novel food ingredients, with PMDA consultation required for therapeutic positioning claims. Kanto region distributors are building flash-freeze logistics partnerships to preserve anthocyanin potency through extended supply chains.
Australia
TGA evaluation frameworks govern nutraceutical market access for acai-derived supplements targeting cardiovascular and cognitive health positioning. Sydney and Melbourne health store buyers are unbundling after-sales merchandising support from wholesale agreements, shifting shelf negotiations to direct brand-retailer relationships. Queensland wellness platforms are penetrating subscription models with extended-shelf-stability powder formats.
Acai Berry Market Key Industry Players
Capital-heavy producers with captive Amazon basin harvesting infrastructure compete with asset-light brands outsourcing lyophilization to third-party Brazilian processors. The vendor base stratifies across three tiers: integrated harvest-to-shelf operators commanding supply security premiums, certified organic specialists capturing natural retail placement, and price-accessible bulk competitors sustaining direct channel control. Dominant competitive moves include backward integration into Pará state collection cooperatives and portfolio diversification into cosmeceutical applications.
Within the integrated supply security tier, Sambazon Inc. and Nativo Acai exemplify archetypes anchored in Amazon basin sourcing infrastructure. Navitas Organics occupies a position in the certified organic specialist tier, representing multi-formulation positioning across premium wellness channels. Terrasoul Superfoods sits within the price-accessible bulk format tier, exemplifying direct-to-consumer channel control strategies that bypass traditional retail markup structures.
| Leading Market Players |
|---|
| Acai Roots Inc. |
| Navitas Organics |
| The Berry Company Limited |
| Nativo Acai |
| Sunfood Superfoods |
| Sambazon Inc. |
| Terrasoul Superfoods |
| Oakberry |
| Amafruits |
| Others |
Cost & Logistics Intelligence
Flash-freeze logistics technicians in Pará state anchor labor-cost differentials that widen spreads between commodity pulp and premium powder pricing tiers. These skilled cold-chain operators command wage premiums that processors pass through to organic-certified finished goods, while conventional pulp lines absorb thinner margins from less specialized collection labor pools.
Pricing Analysis
Merchandising support unbundling from wholesale agreements separates health store shelf placement negotiations from distributor-led pricing. Three-tier pricing structure across organic freeze-dried, conventional powder, and commodity pulp levels reflects certification overhead and bioactive concentration. Cost compression in pulp segments intensifies as Brazilian processors divert capital toward lyophilization equipment. Beverage manufacturers show highest price sensitivity, while nutraceutical capsule buyers accept premiums for standardized anthocyanin content.
Supply Chain Analysis
Direct-to-brand channels handle health store and subscription platform demand, bypassing traditional distributor markups. Raw material flows draw from Brazil's Pará state wild-harvest clusters, with secondary processing concentration in California and New York metro corridors. Flash-pasteurized pulp shipments hinge on uninterrupted -18°C transit from Belém port, creating single-source vulnerability from climate-driven harvest compression. Distribution runs through cold-chain logistics partnerships anchored at North American port facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in freeze-dried powder tiers as nitrogen-injection tunnel systems compress processing costs. Premium organic positioning captures shelf placement premiums that commodity pulp cannot access.
For Market Incumbents: Deepen backward integration into GPS-tracked collection cooperatives to secure deforestation-free documentation required by EU Green Deal transparency mandates. Expand captive lyophilization capacity in Pará state to capture powder-grade margins previously reserved for specialized facilities. Climate volatility in Amazonian tributary systems threatens raw material price stability; vertical control over harvest timing mitigates exposure. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms targeting wellness households with extended-shelf-stability powder formats. Cosmeceutical topical applications in prestige skincare channels represent the most penetrable white space, with omega fatty acid positioning distinct from crowded ingestible categories. Practitioner-education partnerships anchor therapeutic credibility without retail slotting fee burdens. For Investors and Strategic Acquirers: Functional beverage manufacturers are the most active acquirer in this space, seeking captive supply security for antioxidant-rich product lines. Long-term viability centers on processors with certified organic infrastructure and EU Novel Food regulatory clearance. Watch for EFSA evaluation timeline acceleration as signal of European market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Cooperatives | Captive supply of GPS-tracked berries satisfies EU Green Deal geolocation verification requirements. |
| Nitrogen-Injection Lyophilization Adoption | Mid-scale Brazilian processors capture powder-grade margins from specialized freeze-dry facilities. |
| Direct-to-Consumer Subscription Launch | Wellness platforms bypass retail markup structures while securing recurring revenue streams. |
| Cosmeceutical Formulation Expansion | Topical omega fatty acid applications diversify revenue beyond crowded ingestible categories. |
| USDA Organic Certification Investment | Documented supply chains unlock premium shelf placement in Whole Foods and natural retail channels. |
Research Approach
Bottom-up beverage and nutraceutical demand modeling reconciled against top-down Brazilian export tracking forms the analytical core. Primary interviews with flash-freeze logistics operators, Pará state cooperative managers, USDA organic certification specialists, and health store category buyers combined with secondary validation from MAPA phytosanitary filings, EU Novel Food registration databases, and customs trade records. Triangulation across these sources anchors volume estimates.
Historical trendline analysis of preservation format adoption and certification tier penetration informed projection frameworks. Segmentation dimensions span product type, formulation grade, distribution channel, and end-use application across the modeling period. CAGRs derived from curve-fitting against documented capacity expansion and channel shift patterns. Climate volatility indices and regulatory evaluation timelines served as industry-specific forecast modifiers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under irregular flooding patterns in Amazonian harvest zones and accelerated EU deforestation disclosure enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
US Fruit Puree Market
Fruits and Vegetables
White Mushroom Market
Fruits and Vegetables
Global Hass Avocado Market
Fruits and Vegetables
South America Olive Market
Fruits and Vegetables
Argentina Fruits & Vegetables Market
Fruits and Vegetables
Asia Pacific Olive Market
Fruits and Vegetables
Sea Buckthorn Market
Fruits and Vegetables
Peaches and Nectarines Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Banana Puree Market
Fruits and Vegetables
Global Dried Apricots Market
Fruits and Vegetables
Lycopene Market
Fruits and Vegetables
Cambodia Fruits and Vegetables Market