
 Cucumber and Gherkins Market | 2026-2036
Cucumber and Gherkins Market Size, Share, and Industry Trends Forecast 2026-2036
Cucumber and Gherkins Market Insights
The EU Green Deal is realigning agricultural sourcing requirements across European fresh produce supply chains. Bayer AG leverages its seed technology portfolio to sustain high-yield cucumber varieties for processors seeking climate-adapted cultivars. Syngenta Group anchors its competitive position through integrated crop protection solutions that dominate protected cultivation segments. Hengstenberg GmbH & Co. KG differentiates through heritage brand strength and controlled-channel distribution across German retail networks.
Cucumbers and gherkins comprise fleshy fruits of Cucumis sativus L., typically harvested at immature stages for fresh consumption or processed into brined, fermented, or acidified products with titratable acidity specifications governing shelf stability. The primary commercial purpose spans raw salad ingredient supply, pickled condiment production, and food manufacturing inputs for sauces and relishes. Fresh cucumbers occupy the largest volume position within product type segmentation, while pickled cucumbers and gherkins command concentrated margin pools through branded jarred formats and food service contracts. Distribution channel dynamics reveal supermarkets sustaining the dominant throughput position, though online retail extends fastest among direct-to-consumer avenues for specialty and organic cucumber variants.
EU REACH and EFSA frameworks govern pesticide residue thresholds and food contact material safety for packaged cucumber products entering European commerce. The F-Gas Regulation shapes controlled-environment agriculture economics by restricting hydrofluorocarbon use in greenhouse climate systems that sustain year-round European cucumber production. Germany's KBA plays no direct role in this sector, while national plant health authorities across France, Spain, and the Netherlands enforce varietal registration and phytosanitary certification for cross-border seed and fresh produce movement. Stakeholders must monitor evolving EU packaging sustainability mandates and their implications for jarred gherkin formats and plastic film use in fresh cucumber retail packs.
Market Dynamics
EU Green Deal agricultural standards are concentrating certified sustainable gherkin procurement within the Benelux corridor, forcing processors to restructure supplier qualification protocols and greenhouse operators to retrofit climate systems for F-Gas Regulation compliance.
Growth Catalysts
- Clean-Label Pickling Protocols:European food processors are adopting minimal-processing brining methods that eliminate artificial preservatives, creating pull for fresh cucumbers with specific brix and firmness specifications.
- Controlled-Environment Agriculture Expansion:Netherlands-based greenhouse operators are deploying supplemental LED lighting and CO2 enrichment systems to extend European cucumber production windows beyond traditional seasonal constraints.
- EU Packaging Sustainability Mandates:The Packaging and Packaging Waste Regulation is accelerating demand for recyclable jar formats and compostable fresh-produce films among German and Dutch retail networks.
Market Restraints
- Input Cost Volatility:Natural gas price fluctuations directly impact Dutch and Belgian greenhouse heating economics, compressing margins for year-round cucumber cultivation operations.
- Phytosanitary Certification Friction:Cross-border seed movement between France, Spain, and the Netherlands faces escalating documentation requirements under national plant health authority enforcement.
- Water Stress Concentration:Spanish Almería production clusters confront irrigation quota restrictions that cap expansion potential for field-grown cucumber volumes destined for European processing.
Strategic Opportunities
- Organic Segment White Space:German supermarket chains are expanding shelf space allocation for organic cucumber SKUs, creating entry points for certified producers outside established Dutch supply networks.
- Food Service Direct Contracts:Branded gherkin suppliers are bypassing traditional wholesale tiers to secure multi-year condiment supply agreements with European quick-service restaurant chains.
- Fermentation Technology Convergence:Integration of precision pH monitoring with traditional barrel-fermentation protocols is enabling heritage-format gherkin production at commercial scale.
Industry Challenges
- Climate System Retrofit Capex:F-Gas Regulation phase-out timelines require Dutch and Belgian greenhouse operators to replace hydrofluorocarbon-based cooling infrastructure ahead of depreciation cycles.
- Phytosanitary Labor Shortage:National plant health authorities in France and Spain report inspection backlogs that delay varietal registration for new disease-resistant cucumber cultivars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cucumber and Gherkins Market |
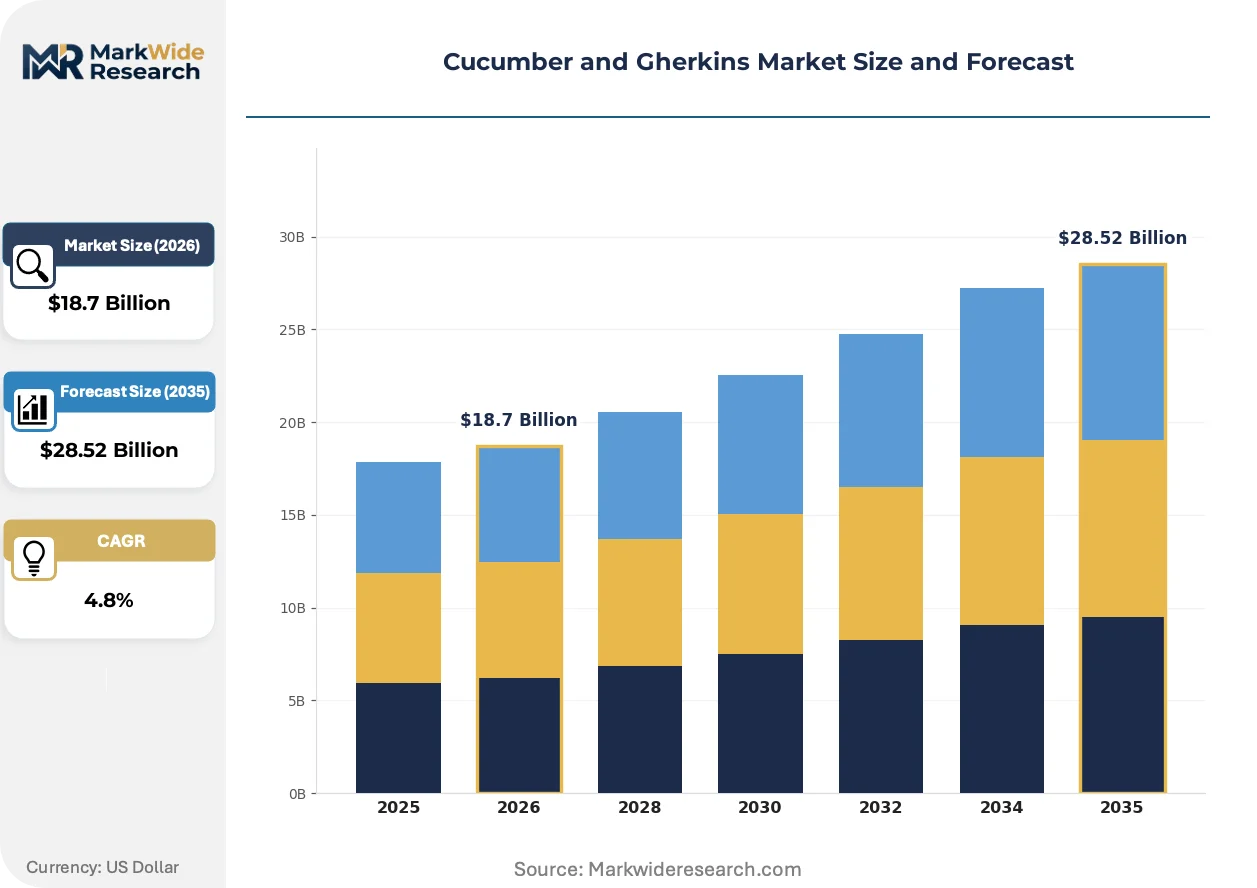
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Cucumbers, Pickled Cucumbers, Gherkins, Sliced Cucumbers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Farm Stands End Use: Household, Food Service, Food Processing, Restaurant Packaging Type: Bottles, Jars, Vacuum Packs, Loose Packaging |
| Companies Covered | Bayer AG, Syngenta Group, Sakata Seed Corporation, BLOSSOM SHOWERS AGRO, Bnazuram Agro Exports Ltd., Ecovinal International Pvt. Ltd., Farm Fresh Bangalore, Hengstenberg GmbH & Co. KG, Mt Olive Pickles Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cucumber and Gherkins Market Trends and Innovations
Precision fermentation monitoring and closed-loop water recycling are compressing resource intensity in European cucumber cultivation, while seed technology advances target climate-adaptive trait stacking for protected agriculture environments.
Sensor-integrated substrate management is decentralizing production expertise away from centralized research stations toward individual greenhouse operations. Dutch and Belgian growers are deploying real-time root-zone monitoring systems that adjust irrigation and nutrient delivery autonomously. This capability diffusion is compressing yield variation between large-scale commercial operations and mid-tier family farms.
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are forcing Dutch greenhouse operators to accelerate heat pump and geothermal adoption for climate control. The industrial consequence is a capital reallocation from crop inputs toward infrastructure retrofitting. Protected cultivation segments in the Netherlands and Belgium are responding by consolidating operations to amortize fixed costs across larger heated acreage footprints.
Direct-to-restaurant procurement is displacing traditional wholesale tiering for specialty gherkin formats. European food service operators are establishing captive supply relationships with specific fermentation houses, bypassing branded jarred intermediaries. This pattern is most visible in Germany's independent restaurant sector, where chefs specify custom acidity profiles and herb-infusion protocols for house-branded condiment programs.
Cucumber and Gherkins Market Segmentation
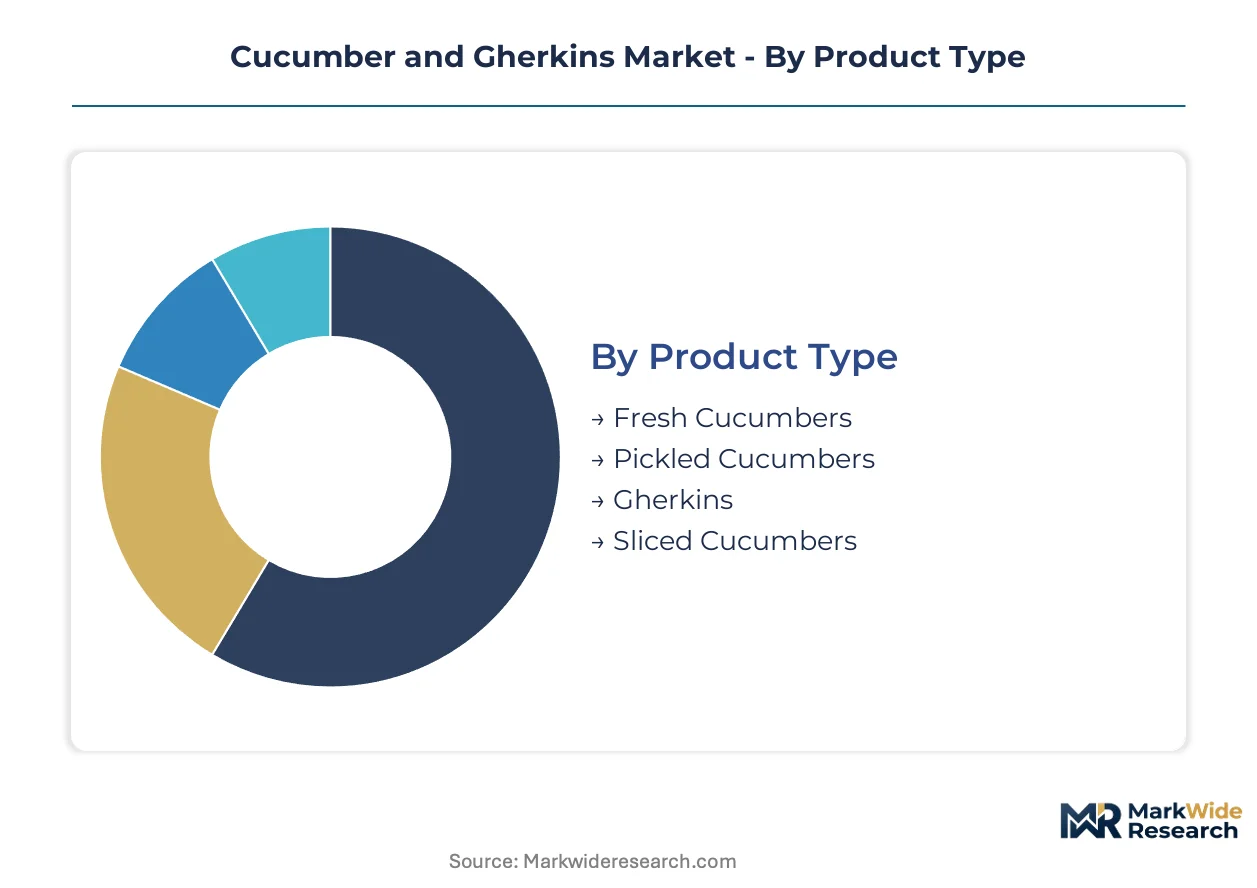
Cucumber and gherkin market segmentation reveals distinct margin structures and supply chain configurations across product formats. Each dimension channels capital toward different operational capabilities, from greenhouse climate control for fresh supply to fermentation infrastructure for processed variants.
Product Type:
Supply concentration in fresh cucumber cultivation centers on Dutch and Belgian greenhouse clusters, while processed formats disperse across fermentation houses in Germany and Poland.
- Fresh Cucumbers:Harvested at immature stages with firm texture and high water content for raw consumption. Dutch greenhouse operators supply the bulk of European supermarket volumes, though Spanish Almería field production competes during seasonal windows.
- Pickled Cucumbers:Brined or acidified products with titratable acidity specifications governing shelf stability. German processors Hengstenberg and Kühne dominate branded jarred formats, commanding concentrated margin pools through retail network penetration.
- Gherkins:Small-fruited varieties harvested at specific size grades for cornichon and cocktail formats. Benelux corridor suppliers face escalating EU Green Deal certification requirements for sustainable procurement contracts.
- Sliced Cucumbers:Pre-cut fresh formats for food service and salad kit manufacturing. Dutch packers leverage controlled-environment supply chains to deliver consistent slice thickness and reduced microbiological load for ready-to-eat applications.
Today's leader: Fresh Cucumbers. Tomorrow's challenger: Gherkins.
Distribution Channel:
Cost tier differentiation separates capital-intensive supermarket slotting from low-barrier direct farm sales, with online retail climbing fastest as delivery infrastructure matures.
- Online Retail:Direct-to-consumer platforms for specialty and organic cucumber variants. German e-grocery operators expand fastest in urban corridors, bypassing traditional wholesale markups for heritage and regional cultivars.
- Supermarkets:Dominant throughput position sustaining year-round volume movement. Dutch retail chains Albert Heijn and Jumbo concentrate procurement through pre-negotiated supply agreements with certified greenhouse consortia.
- Specialty Stores:Ethnic food retailers and organic cooperatives stocking fermented and barrel-aged gherkin formats. Berlin and Amsterdam independent shops source directly from Polish and Romanian small-batch producers.
- Farm Stands:Seasonal direct sales at production sites, primarily active in Spanish field-growing regions and Dutch rural greenhouse zones. Limited to harvest windows without climate-controlled storage infrastructure.
Supermarkets anchor current volume. Online retail gains share fastest.
End Use:
Application-driven specification divergence separates household freshness requirements from food processing firmness and brix standards for industrial brining operations.
- Household:Raw salad ingredient and home-pickling supply. German consumers demonstrate highest per-capita fresh cucumber consumption in Europe, driving supermarket promotional calendar intensity.
- Food Service:Restaurant and catering procurement of both fresh and pickled formats. Quick-service chains specify custom acidity profiles, bypassing traditional wholesale tiers for direct fermentation house contracts.
- Food Processing:Industrial input for sauces, relishes, and condiment manufacturing. Clean-label pickling protocols at European processors create pull for cucumbers with specific brix and firmness specifications.
- Restaurant:Independent chef-driven demand for heritage-format gherkins with herb-infusion protocols. Berlin and Munich establishments specify barrel-fermented small-batch production for house-branded condiment programs.
Food Processing commands specification authority. Restaurant direct procurement expands most quickly.
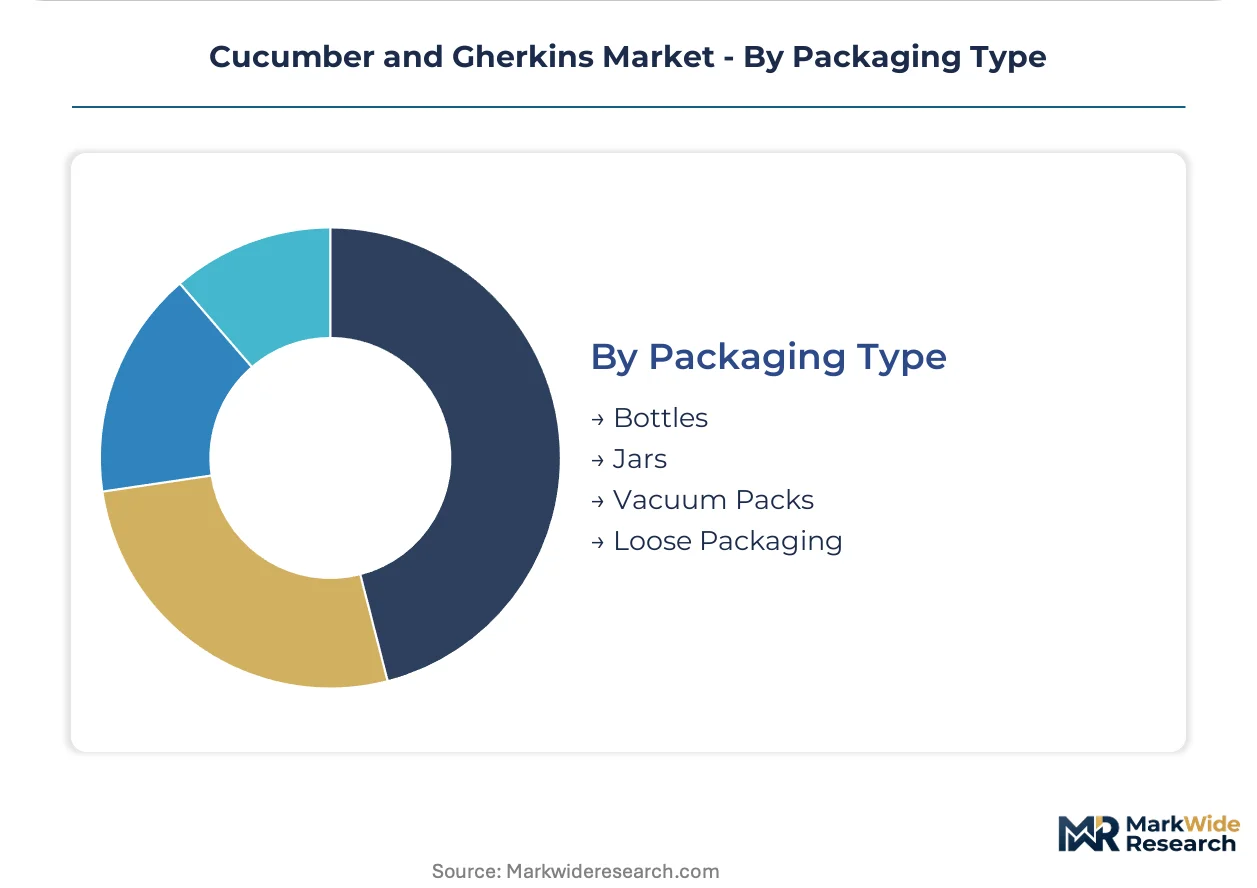
Packaging Type:
EU packaging sustainability mandates are accelerating format transition, with recyclability and plastic reduction now governing procurement decisions across German and Dutch retail networks.
- Bottles:Glass containers for liquid-brined cucumber products. German retailers demand higher recycled content thresholds under national packaging ordinances aligned with EU circular economy targets.
- Jars:Standard format for pickled cucumbers and gherkins with hermetic sealing. Hengstenberg and Kühne heritage brands leverage distinctive jar shapes for shelf differentiation in crowded condiment aisles.
- Vacuum Packs:Modified-atmosphere packaging for fresh sliced and mini-cucumber formats. Dutch packers deploy this technology to extend shelf life for export shipments to Nordic and British markets.
- Loose Packaging:Unwrapped bulk presentation for fresh whole cucumbers. German supermarket chains trial compostable nets and banding to eliminate plastic film while maintaining retail display hygiene standards.
Jars dominate value capture. Vacuum packs show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch greenhouse technicians and Spanish field laborers anchor European cucumber production capacity, while German food processing engineers concentrate gherkin fermentation expertise in industrial clusters.
Germany
Clean-label pickling demand from Hengstenberg and Kühne drives fresh cucumber procurement with specific brix specifications. The EU Green Deal agricultural standards reshape supplier qualification protocols for sustainable gherkin sourcing. Bavarian processing facilities retrofit climate systems to meet F-Gas Regulation phase-out timelines.
Netherlands
Controlled-environment agriculture operators deploy LED lighting and CO2 enrichment to extend production windows beyond seasonal constraints. EFSA pesticide residue thresholds govern fresh produce entering European commerce. Westland greenhouse clusters consolidate operations to amortize geothermal heating infrastructure costs across larger acreage footprints.
Spain
Almería field-grown cucumbers supply seasonal volume for European processing during Dutch winter production gaps. National plant health authority enforcement escalates documentation requirements for cross-border seed movement. Andalusian irrigation quota restrictions cap expansion potential for water-intensive cucumber cultivation.
Poland
Fermentation houses supply barrel-aged gherkin formats to German and Dutch specialty retailers seeking heritage production methods. EU REACH frameworks govern food contact material safety for packaged products. Small-batch producers in rural clusters bypass branded intermediaries through direct contracts with Berlin and Amsterdam independent shops.
Belgium
Benelux corridor suppliers face concentrated EU Green Deal certification requirements for sustainable gherkin procurement contracts. The F-Gas Regulation restricts hydrofluorocarbon use in greenhouse climate systems. Flemish greenhouse operators accelerate heat pump adoption ahead of depreciation cycles.
Cucumber and Gherkins Market Competitive Landscape
Capital-heavy greenhouse operators compete with asset-light seed technology licensors across distinct competitive terrains. The market structures around three tiers: integrated agrochemical conglomerates with breeding programs, regional fermentation specialists with heritage brand equity, and commodity exporters with seasonal cost advantages. Strategic moves concentrate on vertical integration into controlled-environment supply chains and direct-to-restaurant procurement bypassing wholesale tiers.
Within the integrated agrochemical tier, Bayer AG and Syngenta Group exemplify seed technology dominance through climate-adaptive cultivar development. Hengstenberg GmbH & Co. KG anchors the heritage processing archetype with controlled-channel distribution across German retail networks. Sakata Seed Corporation occupies a position bridging vegetable genetics innovation with protected agriculture specifications.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta Group |
| Sakata Seed Corporation |
| BLOSSOM SHOWERS AGRO |
| Bnazuram Agro Exports Ltd. |
| Ecovinal International Pvt. Ltd. |
| Farm Fresh Bangalore |
| Hengstenberg GmbH & Co. KG |
| Mt Olive Pickles Co. Inc. |
| Others |
Pricing and Supply Chain Analysis
Natural gas pricing volatility feeds directly through Dutch and Belgian greenhouse heating economics into fresh cucumber tiering, compressing margins for year-round operators while Spanish field-grown supply captures seasonal arbitrage during winter production gaps.
Pricing Analysis
Fresh versus processed format bundling splits pricing architectures across the value chain. Three-tier pricing structure across premium organic, standard greenhouse, and economy field-grown levels differentiates Dutch certified supply from Spanish seasonal imports. Pricing pressure stems from input cost volatility in protected cultivation, with natural gas exposure forcing margin compression. Food processors exhibit lowest price sensitivity due to specification-locked contracts, while supermarket private-label buyers drive hardest bargain on volume commitments.
Supply Chain Analysis
Seasonal labor availability in Almería field operations and Dutch greenhouse technician pools constrains production scaling across both cultivation modes. Supply concentrates in Netherlands, Spain, and Belgium for fresh formats, with Germany and Poland anchoring processed fermentation capacity. Seed genetics, heating fuel, and brining inputs constitute critical upstream dependencies. Single-source vulnerability sits with Dutch greenhouse climate systems facing F-Gas Regulation retrofit deadlines. Distribution runs through supermarket procurement consortia dominating volume throughput, though direct-to-restaurant channels bypass traditional wholesale markups for specialty gherkin formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Dutch year-round greenhouse supply and Spanish seasonal field production, with the F-Gas Regulation phase-out cost differential reshaping competitive positioning across the Benelux corridor.
For Market Incumbents: Deepen captive supply relationships with certified organic growers outside established Dutch networks to preempt German supermarket shelf-space expansion. Retrofit greenhouse climate systems ahead of regulatory depreciation cycles to lock in cost structures before competitors face stranded asset risk. Prioritize backward integration into seed technology licensing to control climate-adaptive cultivar access.
For New Entrants and Emerging Players: Precision fermentation monitoring systems offer technology-first wedge into heritage-format gherkin production at commercial scale. Target organic cucumber white space in German retail networks where established Dutch supply relationships remain underdeveloped. Pursue direct-to-restaurant procurement channels bypassing branded jarred intermediaries for independent chef-driven condiment programs.
For Investors and Strategic Acquirers: Consolidation pressure builds where F-Gas Regulation compliance costs force sub-scale Dutch greenhouse operators toward distressed divestiture. Long-term viability favors integrated players with captive geothermal infrastructure and direct retail network penetration. Watch for inspection backlog resolution at French and Spanish plant health authorities as signal for varietal registration velocity and new cultivar pipeline inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Geothermal Infrastructure Investment | F-Gas Regulation phase-out forces Dutch operators toward heat pump adoption ahead of depreciation cycles. |
| Direct-to-Restaurant Supply Agreements | European quick-service chains bypass wholesale tiers for custom acidity profile gherkin contracts. |
| Organic Certification Expansion | German supermarket chains expand shelf allocation for certified producers outside Dutch supply networks. |
| Precision Fermentation Technology Deployment | Integrated pH monitoring enables heritage-format gherkin production at commercial scale for specialty retail. |
| Seed Technology Licensing Partnership | Bayer AG and Syngenta Group leverage climate-adaptive cultivar portfolios for processor specification contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Dutch greenhouse operators, German food processing engineers, supermarket category buyers, fermentation house technical directors, and Spanish field-growing cooperatives with secondary validation through EU customs trade data, EFSA pesticide residue reports, SEC filings for listed agrochemical conglomerates, and national plant health authority registration databases. Bottom-up cultivation volume estimates triangulated against top-down retail throughput audits.
Historical reference periods anchored the projection horizon through backward-looking production cost structures and forward-looking regulatory implementation timelines. Segmentation modeling spanned product format, distribution channel, end-use application, and packaging type dimensions across the analysis window. CAGRs derived from volume-weighted price trajectory analysis incorporating natural gas cost pass-through assumptions and EU Green Deal certification penetration curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to F-Gas Regulation enforcement timing and irrigation quota restrictions in Spanish production clusters. Forecasts reflect documented assumptions regarding climate system retrofit adoption rates and clean-label pickling protocol diffusion. Material deviation in EU packaging sustainability mandate implementation or Dutch geothermal infrastructure buildout velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Acai Berry Market
Fruits and Vegetables
Avocado-Based Products Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
Asia Pacific Lime Market
Fruits and Vegetables
North America Organic Fruits Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Fresh Figs Market
Fruits and Vegetables
Adzuki Beans Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
Frozen Vegetables Market
Fruits and Vegetables
North Africa Table Olives Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
Spring Market
Fruits and Vegetables
Europe Kiwi Fruit Market
Fruits and Vegetables
Lemon Juice Concentrate Market