
 Europe Stone Fruits Market | 2026-2036
Europe Stone Fruits Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Stone Fruits Market Foresight
Subscription-based cold-chain monitoring is hardening into a standard service layer that European distributors now bundle with stone fruit shipments. Dole plc leverages integrated logistics networks across Mediterranean growing regions to sustain year-round availability. Hortifrut SA anchors its competitive position through specialized berry and stone fruit breeding programs. PSB Produccion Vegetal SL competes via controlled-environment agriculture systems that extend harvest windows.
Stone fruits comprise fleshy drupes with a single hard endocarp surrounding the seed, typically containing 80-85% water content and requiring controlled atmosphere storage at 0-2°C to preserve organoleptic quality. Their primary commercial purpose spans fresh consumption, industrial processing into jams and juices, and quick-freeze preservation for off-season retail. Fresh peaches and apricots dominate volume flows through European supermarkets, while frozen cherries command premium positioning in food service dessert applications. Dried apricots and plums concentrate margin pools in specialty stores and health-oriented retail channels.
EU Green Deal targets and EFSA residue standards are tightening phytosanitary requirements for stone fruit imports and domestic production. REACH and CE marking protocols govern post-harvest treatment chemicals and sorting equipment deployed across European packing facilities. National regulators in Spain and Italy enforce additional regional quality labels that shape market access conditions. Stakeholders must monitor evolving sustainability disclosure rules under CSRD that will soon require supply chain emissions reporting from large fruit distributors.
Market Dynamics
The EU Green Deal and Farm to Fork Strategy are tightening residue limits and sustainability benchmarks, forcing orchard operators to reconfigure phytosanitary protocols and cold-chain logistics across Mediterranean growing regions.
Growth Catalysts
- EU Green Deal mandates:Carbon footprint disclosure requirements under CSRD are accelerating investments in renewable-powered cold storage and electric transport fleets across Spanish and Italian distribution networks.
- Food service channel expansion:European restaurant and hospitality operators are shortening supply chains through direct procurement partnerships with regional stone fruit cooperatives in Greece and southern France.
- Controlled-atmosphere storage:Modified atmosphere packaging systems extending shelf life of fresh peaches and apricots are penetrating supermarket retail channels at accelerated rates.
Market Restraints
- Input cost volatility:Natural gas and electricity price fluctuations are compressing margins for operators running hydrocooling and controlled-atmosphere storage facilities.
- Phytosanitary compliance friction:EFSA residue standard revisions are creating certification bottlenecks for imports entering EU packing facilities from non-member states.
- Climate concentration risk:Production gravity in Spain, Italy and Greece exposes supply security to drought frequency and irrigation water scarcity in Mediterranean watersheds.
Strategic Opportunities
- Polish and Romanian orchard expansion:Climatic suitability for apricot cultivation in Eastern European growing regions remains underdeveloped relative to Western European demand density.
- Quick-freeze dessert applications:Frozen cherry segments for food service dessert manufacturing represent a margin pool with limited specialized supplier presence.
- CSRD supply chain disclosure:Large fruit distributors must soon report Scope 3 emissions, creating first-mover advantage for operators with verified carbon accounting systems.
Industry Challenges
- Post-harvest pathology expertise gap:Qualified technicians for managing brown rot and monilinia control in organic production systems command premium wages and limited availability.
- Sorting equipment capex cycles:Optical grading systems compliant with CE marking protocols require substantial capital deployment with five-to-seven-year replacement horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Stone Fruits Market |
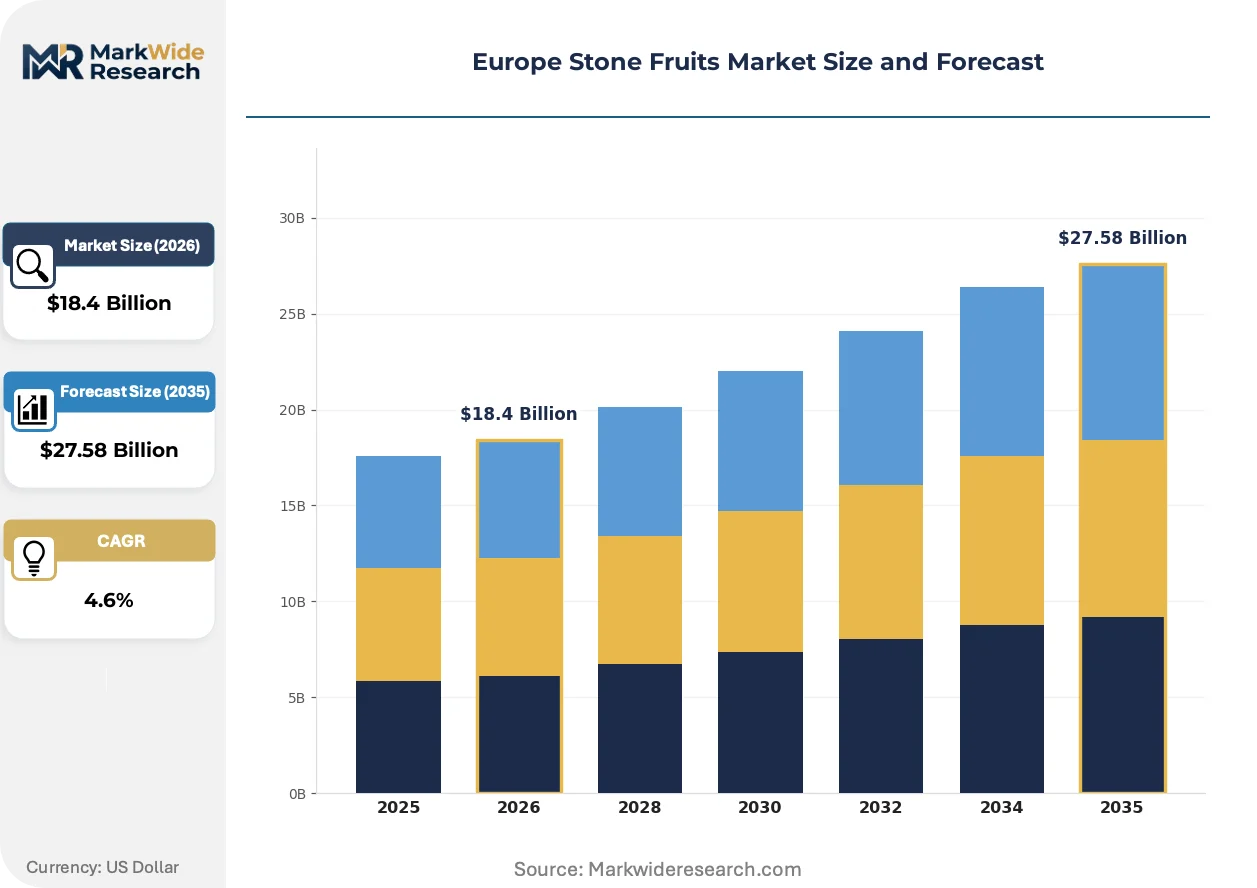
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $27.58 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peaches, Plums, Cherries, Apricots Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale End User: Food Service, Retail Customers, Manufacturers, Processors Form: Fresh, Frozen, Dried, Canned |
| Companies Covered | Dole plc, Hortifrut SA, PSB Produccion Vegetal SL, Salix Fruits, SAT Plus Berries, Family Tree Farms, Pacific Trellis Fruit, Giumarra Vineyards, Driscolls Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Stone Fruits Market Shifts & Advancements
Digital traceability platforms and precision agriculture tools are rewriting operational standards across European stone fruit value chains, compressing information asymmetries between growers and retail buyers.
Hyperspectral imaging systems for non-destructive ripeness assessment are consolidating quality control workflows at Mediterranean packing facilities. Spanish cooperatives are deploying these units at throughput rates exceeding conventional manual sorting by an order of magnitude. The technology is consolidating premium-grade fruit identification into automated decision layers that bypass human grading bottlenecks.
REACH authorization requirements for post-harvest treatment chemicals are tightening formulation approvals across European packing houses. Orchard operators face reformulation costs for fungicide coatings previously standard in conventional supply chains. Fresh apricot exporters to Northern European markets are accelerating transitions to biological control agents ahead of scheduled restriction timelines.
Subscription-based cold-chain monitoring services are displacing one-off hardware purchases among mid-scale distributors. Italian logistics providers now bundle temperature and humidity telemetry as recurring service offerings rather than capital equipment sales. This shift is most visible in intermodal shipments connecting Sicilian growing regions to German retail distribution centers.
Europe Stone Fruits Market Segmentation
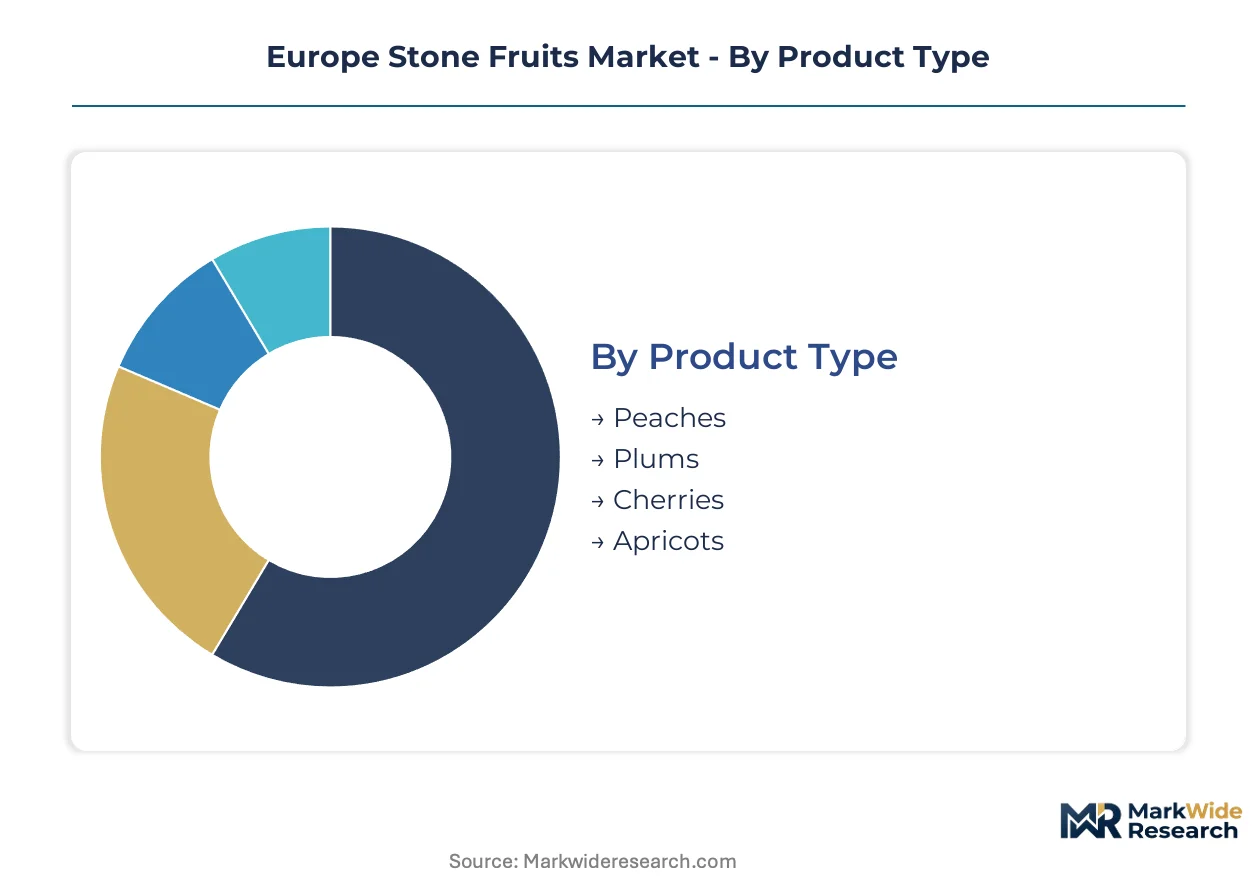
Stone fruit segmentation in Europe reflects divergent compliance burdens across product categories. Certification requirements from EFSA residue standards and national quality labels reshape profitability profiles by segment.
Product Type:
EFSA residue monitoring concentrates heaviest on peaches and apricots due to their thin skins and direct fresh consumption patterns. REACH authorization for post-harvest treatments varies significantly across these categories.
- Peaches:These drupes carry 80-85% water content and demand controlled-atmosphere storage at 0-2°C to preserve texture. Spanish and Italian cooperatives dominate fresh peach flows through German supermarket channels, though EFSA residue standard revisions are forcing reformulation of conventional fungicide coatings.
- Plums:Higher sugar concentration and firmer flesh make plums more tolerant of standard cold-chain logistics. Italian growing regions around Emilia-Romagna supply industrial processors across Northern Europe with specific varieties optimized for jam and juice extraction.
- Cherries:Premium dessert applications in food service drive demand for frozen segments with limited specialized supplier presence.
- Apricots:Greek and Spanish orchards face tightening sustainability benchmarks under EU Green Deal targets for irrigation-intensive cultivation.
Peaches sit at the top of the volume ranking, with cherries climbing the fastest through frozen dessert channels.
Distribution Channel:
Channel selection determines cold-chain infrastructure investment intensity and telemetry bundling requirements. Italian logistics providers now structure service offerings around recurring monitoring subscriptions rather than capital sales.
- Supermarkets:Modified atmosphere packaging systems are penetrating these retail channels at accelerated rates. Spanish cooperatives deploy hyperspectral imaging for automated ripeness assessment, consolidating premium-grade identification into decision layers that bypass human grading bottlenecks.
- Online Retailers:Direct-to-consumer models demand precision in last-mile temperature control. Subscription-based cold-chain monitoring services are displacing one-off hardware purchases among mid-scale distributors serving this channel.
- Specialty Stores:Dried apricots and plums concentrate margin pools in health-oriented retail channels with specific provenance labeling requirements.
- Wholesale:Intermodal shipments connecting Sicilian growing regions to German distribution centers favor bundled telemetry services.
Supermarkets maintain the steepest expansion trajectory for fresh segments, with online retailers gaining share fastest in premium gift-box applications.
End User:
End-user categories diverge sharply in specification tolerance and volume contracting patterns. Food service operators prioritize shorter supply chains through direct procurement partnerships.
- Food Service:European restaurant and hospitality operators are shortening supply chains through direct procurement partnerships with regional cooperatives in Greece and southern France. Frozen cherry segments for dessert manufacturing represent a margin pool with limited specialized supplier presence.
- Retail Customers:Fresh consumption dominates with quality grading enforced through optical systems compliant with CE marking protocols.
- Manufacturers:Industrial processing into jams and juices requires specific Brix and acidity specifications that shape orchard variety selection.
- Processors:Quick-freeze preservation for off-season retail demands hydrocooling infrastructure with substantial electricity exposure.
Food service leads volume concentration, with processors expanding most quickly through quick-freeze dessert applications.
Form:
Form selection dictates storage technology requirements and margin capture potential. Natural gas and electricity price fluctuations compress margins for operators running controlled-atmosphere and hydrocooling facilities.
- Fresh:Organoleptic quality preservation demands renewable-powered cold storage investments accelerated by CSRD carbon footprint disclosure requirements. Spanish and Italian distribution networks are deploying electric transport fleets to meet these mandates.
- Frozen:Quick-freeze preservation commands premium positioning in food service dessert applications with limited specialized supplier presence.
- Dried:Concentrated margin pools in specialty stores require specific moisture content standards and extended shelf-life protocols.
- Canned:Industrial processing applications favor plums and apricots with firmer flesh structures that withstand thermal treatment.
Fresh forms dominate volume flows, with frozen segments gaining share fastest through food service channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish peach exports to German supermarkets outpace Italian apricot flows by volume, yet Greek cooperatives command higher per-kilogram returns through direct food service partnerships in France and the Netherlands.
Spain
Murcia and Valencia growing regions supply hydrocooled peaches through electric transport fleets mandated by CSRD carbon disclosure rules. EFSA residue monitoring concentrates heavily on thin-skinned varieties entering Northern European retail channels. Catalan cooperatives deploy hyperspectral imaging systems at throughput rates exceeding manual sorting by an order of magnitude.
Italy
Emilia-Romagna orchards around Modena and Parma supply industrial processors with plum varieties optimized for jam extraction. REACH authorization requirements are forcing reformulation of conventional fungicide coatings ahead of scheduled restriction timelines. Sicilian intermodal shipments to German distribution centers favor bundled cold-chain telemetry subscriptions over capital equipment purchases.
Greece
Peloponnese apricot cultivation faces tightening sustainability benchmarks under EU Green Deal irrigation efficiency targets. Direct procurement partnerships with French and Dutch restaurant operators shorten supply chains and capture premium positioning. Thessaly cooperatives are accelerating transitions to biological control agents for brown rot management in organic production systems.
France
Provence-Alpes-Côte d'Azur stone fruit growers serve domestic food service channels through regional cooperative structures. National quality labels enforced by ANSM shape market access conditions for fresh segments entering Parisian retail. Languedoc packing facilities invest in renewable-powered controlled-atmosphere storage to meet tightening CSRD supply chain emissions reporting requirements.
Poland
Lesser Poland and Subcarpathian regions exhibit climatic suitability for apricot cultivation that remains underdeveloped relative to Western European demand density. Polish orchard operators lack the hydrocooling infrastructure density of Mediterranean competitors. Warsaw-based distributors are exploring quick-freeze dessert applications for cherry segments with limited specialized supplier presence in neighboring markets.
Europe Stone Fruits Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated logistics networks commanding premium positioning in fresh channels while breeding-focused operators capture margin pools in proprietary varieties. The vendor base clusters around three strategic archetypes: Mediterranean cooperative federations with captive cold-chain assets, South American breeding houses specializing in berry and stone fruit genetics, and controlled-environment agriculture specialists extending harvest windows through substrate systems. Consolidation pressure is accelerating through cooperative mergers in Spanish growing regions and technology licensing agreements for precision agriculture tools.
Among integrated logistics operators, Dole plc and Hortifrut SA exemplify divergent scale strategies within the same value chain tier. Dole plc leverages Mediterranean network density to sustain year-round availability across European retail channels. Hortifrut SA anchors its competitive position through specialized breeding programs that concentrate intellectual property in proprietary fruit varieties. PSB Produccion Vegetal SL occupies a distinct position among controlled-environment specialists, with Spanish-based operations deploying substrate systems that compress seasonality constraints.
| Leading Market Players |
|---|
| Dole plc |
| Hortifrut SA |
| PSB Produccion Vegetal SL |
| Salix Fruits |
| SAT Plus Berries |
| Family Tree Farms |
| Pacific Trellis Fruit |
| Giumarra Vineyards |
| Driscolls Inc. |
| Others |
Supply & Pricing Matrix
Qualified technicians for brown rot management in organic stone fruit production command premium wages across Murcia and Valencia growing regions, compressing margins for mid-tier operators and widening spreads between premium-certified and conventional pricing tiers.
Pricing Analysis
Capacity additions in Polish and Romanian apricot cultivation are reshaping price floors for Eastern European supply entering German retail channels. Three-tier pricing structure across premium organic, standard conventional, and economy-grade segments separates fruit by EFSA residue certification and cold-chain telemetry bundling. Cost compression in economy tiers is intensifying because natural gas price volatility feeds through to hydrocooling facility operators. Food service buyers exhibit lowest price sensitivity due to direct procurement partnerships, while wholesale distributors serving discount supermarkets face acute margin pressure.
Supply Chain Analysis
Direct-to-food-service channels handle premium dessert-grade cherry demand through shortened supply chains anchored in Greek Peloponnese cooperatives. Geographic supply concentration centers on Spain, Italy, and Greece for fresh peach and apricot flows, with Poland and Romania emerging for quick-freeze applications. Raw material dependencies rest on irrigation water access, hydrocooling electricity contracts, and biological control agent formulations. Single-source vulnerability from Mediterranean drought frequency threatens harvest security across concentrated watersheds. Distribution runs through cooperative federations with captive cold-chain assets linking Sicilian growing regions to Northern European retail distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European stone fruits hinges on CSRD-driven carbon accounting investments that unlock premium-tier positioning for early-compliant operators.
For Market Incumbents: To counter biological control agent supply bottlenecks for organic certification, Spanish and Italian cooperatives should deepen backward integration into captive breeding programs for beneficial insects while deploying subscription-based cold-chain telemetry to defend service revenue streams against hardware commoditization. For New Entrants and Emerging Players: Direct-to-consumer online retail routes offer the most penetrable entry vector for Polish and Romanian operators lacking established supermarket slotting relationships, with gift-box premium positioning and last-mile temperature-controlled delivery as the specific go-to-market angle. For Investors and Strategic Acquirers: Mediterranean cooperative federations are the most active acquirer in this space, consolidating packing facility assets to achieve scale economics in optical grading infrastructure. Long-term viability favors targets with verified Scope 3 emissions accounting systems ahead of mandatory CSRD disclosure timelines. The signal to watch is accelerated technology licensing agreements for hyperspectral imaging systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biological Control | Captive supply of beneficial insects secures organic certification pathways ahead of REACH restriction timelines. |
| Cold-Chain Telemetry Subscription Launch | Recurring revenue models displace capital equipment sales among Italian logistics providers serving German retail. |
| Hyperspectral Imaging Deployment | Spanish cooperatives achieve throughput rates exceeding manual sorting by an order of magnitude at packing facilities. |
| Quick-Freeze Dessert Capacity Buildout | Limited specialized supplier presence in frozen cherry segments creates first-mover margin capture in food service. |
| CSRD Carbon Accounting Certification | Verified emissions reporting systems unlock premium-tier positioning for large fruit distributors ahead of mandatory disclosure. |
Research Methodology
Bottom-up food service and retail channel modeling reconciled against top-down orchard production tracking forms the analytical core of this study. Primary interviews with cooperative federation managers, cold-chain logistics operators, supermarket category buyers, and EFSA regulatory affairs specialists combined with secondary validation from EU customs trade data, CSRD disclosure filings, and REACH authorization databases. Triangulation across these sources ensures convergence on volume and value estimates.
Input-output matrices map cultivation area, yield assumptions, and price realization across product type, distribution channel, end user, and form segmentation dimensions. CAGRs derive from slope analysis of annual progression rates throughout the forecast period. Industry-specific forecast inputs include irrigation water availability indices and electricity price trajectories for hydrocooling infrastructure.
Climate-induced harvest volatility, EFSA residue standard revision timing, and CSRD enforcement intensity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on cooperative consolidation pace and technology adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Clean Label Fruit and Vegetable Powder Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
United Kingdom Berries Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
Lingonberry Market
Fruits and Vegetables
Fresh Apricots Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
Banana Puree Market
Fruits and Vegetables
Starchy Roots Market
Fruits and Vegetables
Fresh Fruits Market
Fruits and Vegetables
Fresh Peaches Market
Fruits and Vegetables
Fava Beans Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market