
 Dried Figs Market | 2026-2036
Dried Figs Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Figs Market Foresight
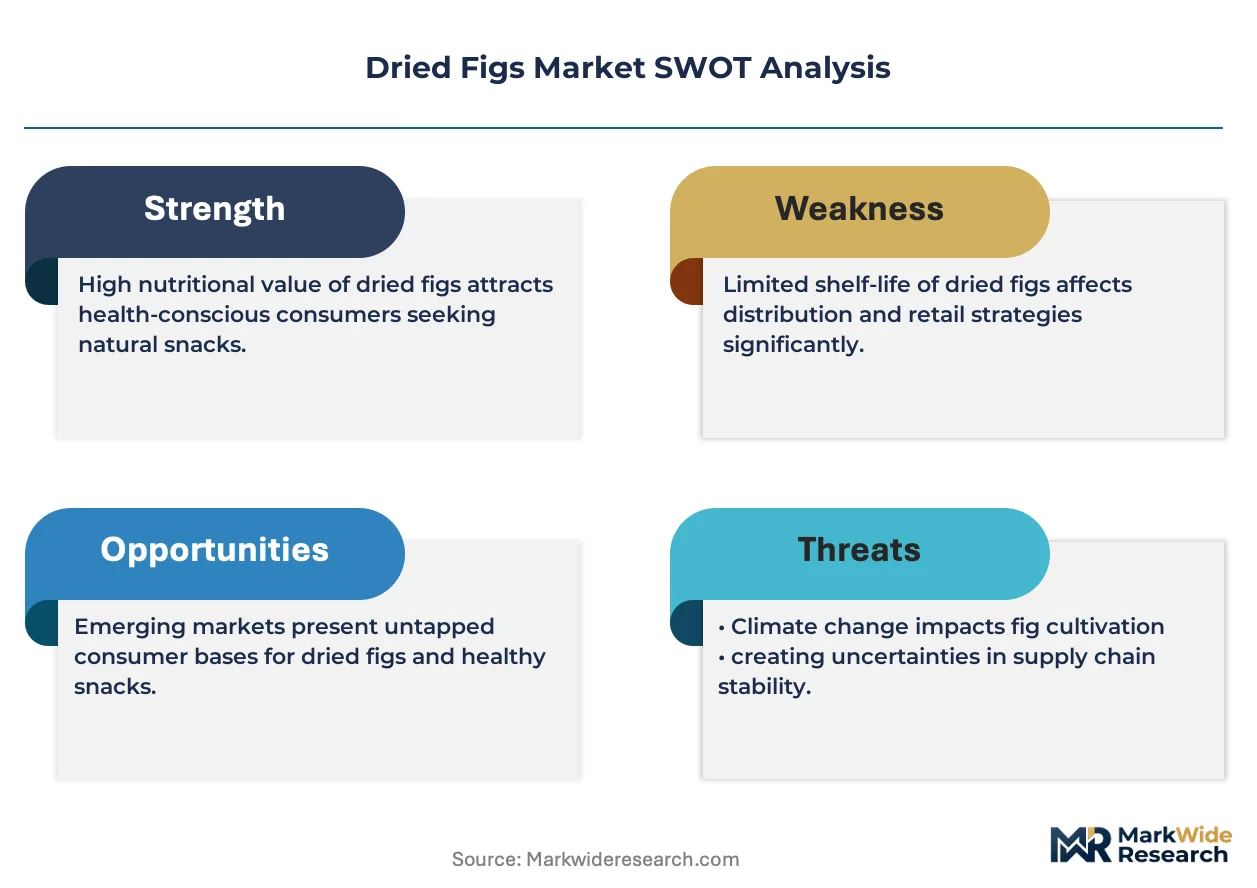
Specialty store distribution is fragmenting as online retail and direct-to-bakery procurement gain share in the dried figs trade. Fruits of Turkey leverages long-standing relationships with European importers to sustain volume commitments. Valley Fig Growers anchors California production through controlled-atmosphere storage investments that extend shipping windows. Izmir Organic differentiates via certified organic orchards in Aydin province that command premium positioning in German and Dutch retail channels.
Dried figs are the dehydrated fruit of Ficus carica, typically reduced to moisture content below 24 percent through sun-drying or controlled mechanical dehydration to inhibit microbial spoilage and enable ambient storage. The product serves as a natural sweetener, fiber source, and textural ingredient across bakery fillings, energy bars, and Mediterranean confectionery formulations. Organic product type leads value contribution as EU Green Deal-aligned procurement policies elevate certified supply premiums. Conventional product type dominates volume throughput in wholesale channels where Turkish and Californian packers compete on landed cost efficiency. Diced format grows fastest within food processing end use as industrial bakeries standardize inclusion rates for fruit breads and cereal bars.
Turkey's national food safety regulator enforces aflatoxin B1 limits that mandate optical sorting and laboratory certification before export release. The EU's REACH framework and EFSA contaminant thresholds shape maximum residue levels that Turkish and Californian exporters must document for customs clearance. Organic certification under USDA National Organic Program and EU organic regulation creates parallel compliance tracks that segment supplier capabilities. Stakeholders must monitor evolving mycotoxin testing protocols and organic equivalency negotiations between Turkey and the European Commission to anticipate supply eligibility shifts.
Market Dynamics
Turkey's aflatoxin enforcement protocols are restructuring export-grade processing capacity, forcing Aegean packers to invest in optical sorting infrastructure that separates compliant from non-compliant lots before EU-bound shipment.
Growth Catalysts
- EU Green Deal procurement alignment:German and Dutch retailers now mandate certified organic supply for private-label fig lines, redirecting procurement toward Aydin province orchards.
- Industrial bakery standardization:Diced format specifications are hardening across European cereal bar and fruit bread formulations, locking in volume commitments from Izmir processing clusters.
- Controlled-atmosphere storage diffusion:Valley Fig Growers and Turkish packers are extending shipping windows through CA technology, enabling year-round supply contracts with confectionery manufacturers.
Market Restraints
- Input cost volatility:Labor-intensive hand-harvesting in Aegean provinces faces wage pressure from competing agricultural sectors, squeezing packer margins on conventional grades.
- Supply concentration risk:Turkey controls approximately three-quarters of export-grade volume, creating single-origin vulnerability for European importers dependent on Izmir-Aydin corridor infrastructure.
- Regulatory friction:REACH documentation requirements and EFSA contaminant thresholds impose batch-level testing costs that disadvantage smaller Turkish packers lacking in-house laboratories.
Strategic Opportunities
- Direct-to-bakery channel expansion:Specialty ingredient distributors are building diced fig blending facilities in proximity to German industrial bakery clusters, bypassing traditional wholesale tiers.
- Organic equivalency negotiation:Pending Turkey-European Commission organic certification mutual recognition would unlock streamlined Dutch and German retail placement for Aydin province growers.
- Energy bar formulation convergence:Natural sweetener demand from sports nutrition manufacturers is pulling fig paste and concentrate into new binding applications beyond traditional confectionery.
Industry Challenges
- Optical sorting technician scarcity:Aegean processing facilities face recruitment gaps for operators capable of calibrating near-infrared aflatoxin detection systems to EU export standards.
- Certification timeline compression:USDA National Organic Program and EU organic regulation parallel audits require 18-24 month conversion periods that delay revenue recognition for orchard expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Figs Market |
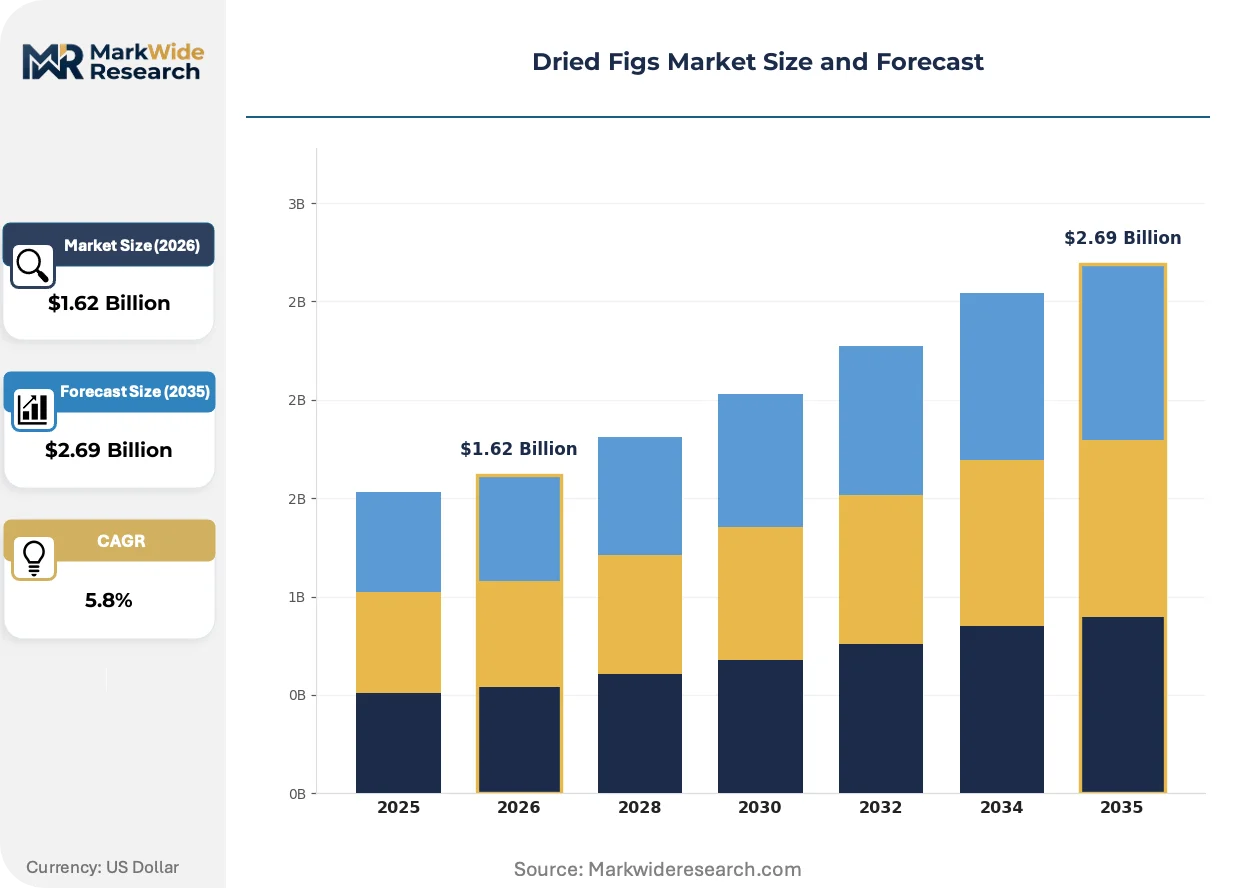
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $2.69 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Diced, Whole Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale End User: Food Processing, Bakery, Confectionery, Retail Packaging Type: Pouches, Boxes, Bulk, Cans |
| Companies Covered | Fruits of Turkey, GzelCanGdaSanVe Tic, Natura Dry Fruit AS, Valley Fig Growers, SEA SPREAD LIMITED, Izmir Organic, BURKAZ FIGS COMPANY, San Joaquin Figs, Aurora Natural, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Figs Market Shifts & Advancements
Dehydration technology and compliance infrastructure are converging to reshape how Aegean packers qualify for European retail placement, with automation investments now determining supplier survival.
Mechanical dehydration is hybridizing with traditional sun-drying protocols in Turkish processing facilities. Industrial bakeries in Germany and France are specifying moisture content tolerances below 20 percent for diced fig inclusions, forcing packers to deploy hybrid thermal systems that combine solar pre-drying with controlled mechanical finish. This technology convergence is compressing the supplier base toward operations capable of precision moisture management at export scale.
EFSA contaminant thresholds are tightening maximum residue documentation requirements for dried fruit imports. Turkish exporters must now submit laboratory certification for aflatoxin B1 levels before customs release, adding 48-72 hour pre-shipment delays. Organic product lines face the steepest compliance burden, as dual-track testing for both mycotoxins and organic integrity stretches lead times for German and Dutch retail channels.
Ingredient buyers are consolidating procurement relationships around vertically integrated Aegean packers with captive orchard operations. Traditional wholesale distributors are losing share to direct contracts between Aydin province processors and European private-label retailers, a pattern most visible in German energy bar and cereal manufacturer supply chains where traceability requirements favor single-source documentation.
Dried Figs Market Segmentation
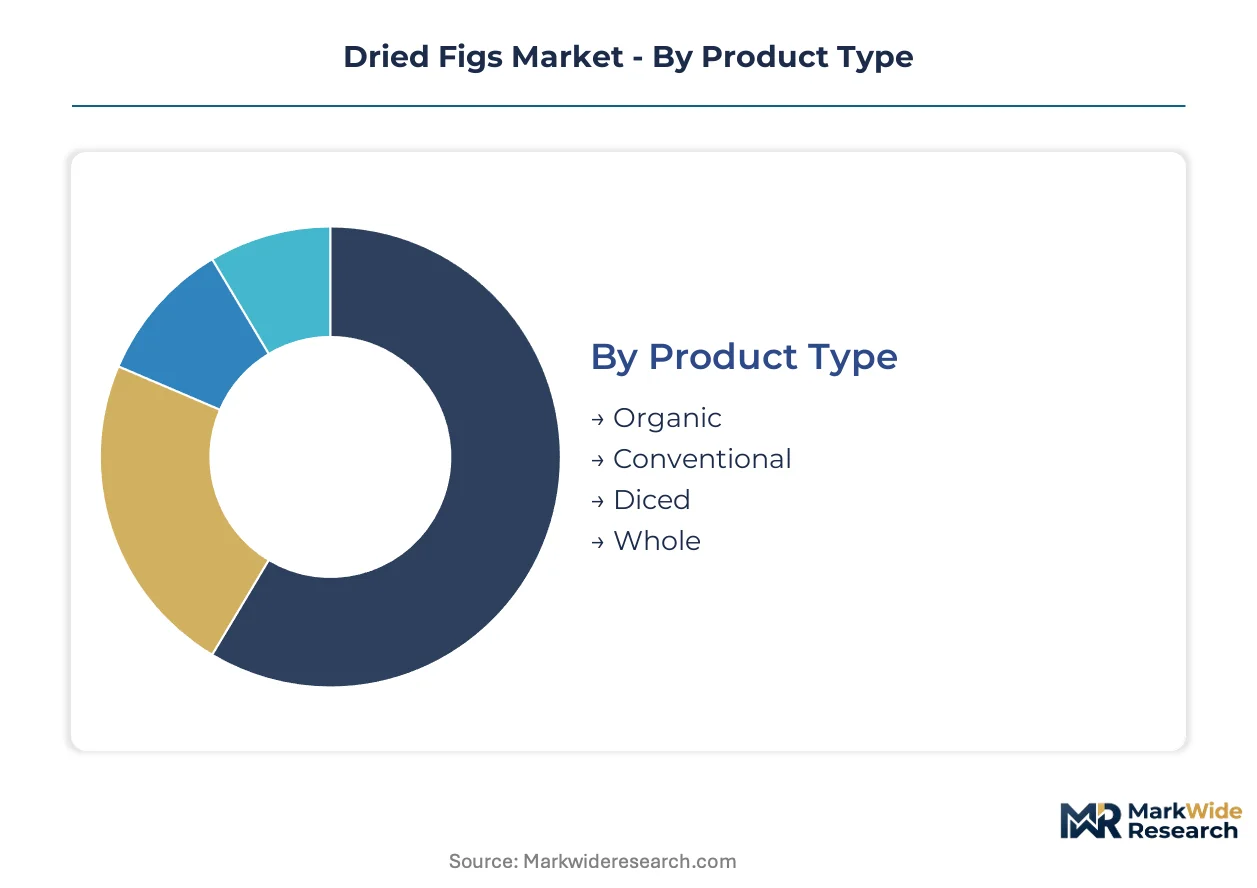
Segmentation in dried figs trade tracks how procurement specifications diverge across compliance regimes and channel economics. Turkish packers calibrate processing investments against these segment boundaries to qualify for EU retail placement.
Product Type:
After-sales service intensity runs highest for organic lines requiring traceability documentation and certification renewal support.
- Organic:Certified orchards in Aydin province undergo annual audits under EU organic regulation and USDA National Organic Program. German and Dutch retailers mandate this grade for private-label energy bars and cereal formulations, paying premiums that absorb 18-24 month conversion timelines for new orchard entrants.
- Conventional:Volume throughput in wholesale channels where Turkish and Californian packers compete on landed cost efficiency. EFSA aflatoxin thresholds still require batch-level testing, but compliance burden sits below dual-track organic certification.
- Diced:Industrial bakeries in Germany standardize inclusion rates for fruit breads.
- Whole:Mediterranean confectionery and retail gifting segments prefer intact fruit presentation.
Conventional holds the largest share; momentum sits with organic.
Distribution Channel:
Channel selection determines margin capture versus volume scale for Aegean processing clusters.
- Supermarkets:German and French retail chains specify moisture content below 20 percent and optical-sorting certification. Direct contracts with Aydin province packers are displacing traditional wholesale tiers as traceability requirements harden.
- Online Retail:Specialty ingredient distributors build diced fig blending facilities near industrial bakery clusters, bypassing wholesale intermediaries. Channel expansion accelerates as procurement teams seek shorter lead times than Izmir port consolidation allows.
- Specialty Stores:Fragmenting share as direct-to-bakery procurement gains ground.
- Wholesale:Landing cost competition between Turkish and Californian packers dominates conventional grade trade.
Wholesale retains volume leadership; online retail climbs the fastest.
End User:
End-use specifications fragment around moisture tolerance and format requirements.
- Food Processing:Cereal bar manufacturers in Germany and France drive diced format standardization. Valley Fig Growers and Turkish packers deploy controlled-atmosphere storage to extend shipping windows for year-round supply contracts.
- Bakery:Industrial fruit bread producers mandate precise inclusion rates that lock in volume commitments from Izmir processing clusters.
- Confectionery:Mediterranean formulations favor whole fig presentation and natural sweetener positioning.
- Retail:Private-label placement requires dual certification for organic and contaminant thresholds.
Food processing commands procurement scale; bakery shows steepest expansion trajectory.
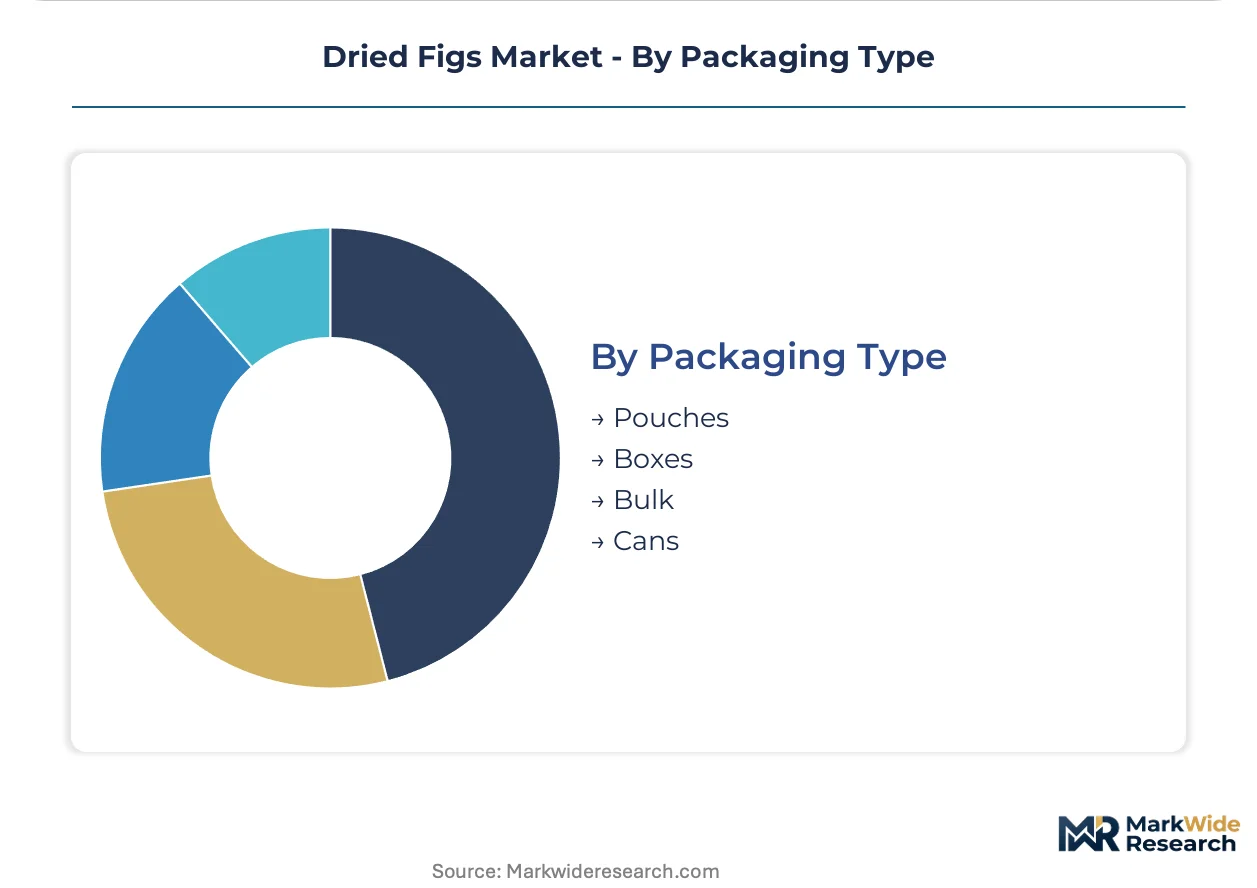
Packaging Type:
Packaging economics track channel destination and shelf-life requirements.
- Pouches:Retail-ready formats for German and Dutch supermarket chains. Oxygen barrier specifications extend ambient shelf life for organic lines with slower inventory turns.
- Boxes:Confectionery and gifting segments in France prefer presentation-grade packaging.
- Bulk:Food processing and bakery end users minimize per-unit packaging cost through tote and bin delivery.
- Cans:Traditional Mediterranean retail channels maintain residual demand for shelf-stable presentation.
Bulk dominates industrial procurement; pouches gain share fastest in retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Izmir anchors Turkish export capacity with dedicated cold storage terminals serving Aegean processing clusters. German rail freight corridors from Rotterdam and Hamburg distribute incoming volumes to industrial bakery clusters in Bavaria and North Rhine-Westphalia. California's Central Valley irrigation infrastructure underwrites year-round supply continuity for North American confectionery manufacturers.
Turkey
Aegean coastal provinces concentrate sun-drying infrastructure and optical sorting facilities for EU-bound shipments. The Turkish Food Codex enforces aflatoxin B1 thresholds that mandate laboratory certification before customs release. Izmir and Aydin processing clusters supply diced formats to German private-label retailers under direct procurement contracts.
Germany
Industrial bakeries in Bavaria and Lower Saxony standardize fig inclusion rates for energy bars and fruit breads. The EU Green Deal procurement alignment mandates certified organic supply for supermarket private-label lines. Hamburg port terminals consolidate Turkish bulk shipments for redistribution to Dutch and French retail channels.
United States
California's Central Valley hosts controlled-atmosphere storage investments that extend shipping windows for domestic confectionery contracts. FDA enforcement of FSMA preventive controls requires hazard analysis documentation from foreign suppliers. Fresno County packers compete with Turkish imports on landed cost for conventional grade wholesale channels.
France
Mediterranean confectionery manufacturers in Provence-Alpes-Côte d'Azur favor whole fig presentation for traditional formulations. ANSM food safety surveillance coordinates with EFSA contaminant threshold updates for dried fruit imports. Marseille port logistics handle bulk arrivals from Turkish Aegean terminals for southern European distribution.
Netherlands
Rotterdam's automated container terminals serve as the primary European entry point for Turkish organic certified volumes. Dutch retailers lead EU Green Deal procurement implementation with mandatory organic certification for dried fruit private labels. Specialized ingredient distributors near Utrecht operate diced fig blending facilities for German bakery cluster supply.
Dried Figs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The supplier base concentrates around Aegean packers with captive orchard operations and Californian growers with controlled-atmosphere infrastructure. Two strategic archetypes dominate: vertically integrated Turkish processors with optical sorting capabilities and specialty distributors building direct-to-bakery blending facilities. Competitive moves center on backward integration into certified organic acreage and geographic expansion of diced format processing near European industrial bakery clusters.
Among Turkish-origin packers, Fruits of Turkey and Izmir Organic occupy positions reflecting Aegean processing concentration and organic certification specialization. Valley Fig Growers anchors the North American supply tier with California-based controlled-atmosphere investments. These three exemplify how geographic origin and infrastructure endowment stratify competitive positioning across conventional and organic grade segments.
| Leading Market Players |
|---|
| Fruits of Turkey |
| GzelCanGdaSanVe Tic |
| Natura Dry Fruit AS |
| Valley Fig Growers |
| SEA SPREAD LIMITED |
| Izmir Organic |
| BURKAZ FIGS COMPANY |
| San Joaquin Figs |
| Aurora Natural |
| Others |
Supply & Pricing Matrix
Undercapacity in Aegean optical sorting facilities is compressing packer margins and amplifying price premiums for export-compliant lots as Turkish processors race to meet EU aflatoxin certification requirements.
Pricing Analysis
Volume-discount tiering structures separate organic certified supply from conventional wholesale grades. Premium-mid-economy pricing differentiation tracks certification burden, with EU organic regulation compliance adding substantial overhead that German retailers absorb through long-term contracts. Price differentiation hinges on optical sorting certification and moisture precision, with industrial bakeries least sensitive due to locked-in formulation specifications. Cost compression in conventional wholesale channels is intensifying because Californian packers compete on landed cost efficiency against Turkish exporters.
Supply Chain Analysis
Contract-manufacturing concentration rests with Izmir and Aydin processing clusters that combine captive orchard operations with optical sorting infrastructure. Geographic supply concentration centers on Turkey, California, and France. Raw material dependencies draw from Aegean fig orchards, sulfur dioxide for preservation, and oxygen-barrier packaging films. Single-source vulnerability runs through Turkey's three-quarter share of export-grade volume. Distribution runs through Rotterdam and Hamburg port terminals for European redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dried figs market is recovering from a cyclical trough driven by EU Green Deal procurement mandates that reset demand baselines for certified organic supply.
For Market Incumbents: Insulate margin position through backward integration into Aydin province organic acreage and controlled-atmosphere storage capacity additions near Izmir port terminals. EFSA contaminant threshold tightening threatens smaller packers lacking in-house laboratories, creating consolidation leverage for operators with existing optical sorting infrastructure. For New Entrants and Emerging Players: Pursue direct-to-bakery channel openings in German industrial bakery clusters where diced format standardization is displacing traditional wholesale tiers. Specialty ingredient distributors near Bavaria and North Rhine-Westphalia represent the most penetrable entry point, with blending facility investments unlocking shorter lead times than Izmir port consolidation allows. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across optical sorting and hybrid dehydration infrastructure as compliance requirements harden. Long-term viability favors vertically integrated Aegean packers with captive organic orchards and EU certification track records. The signal to watch is Turkey-European Commission organic equivalency negotiation progress, which would streamline Dutch and German retail placement and revalue certified supply premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Acreage | Aydin province orchard control secures EU Green Deal-aligned supply commitments from German retailers. |
| Optical Sorting Infrastructure Deployment | Turkish Food Codex aflatoxin enforcement mandates laboratory certification before EU-bound shipment release. |
| Direct-to-Bakery Channel Expansion | Specialty distributors near German industrial clusters bypass wholesale tiers with diced fig blending facilities. |
| Controlled-Atmosphere Storage Investment | Valley Fig Growers and Aegean packers extend shipping windows for year-round confectionery contracts. |
| Organic Equivalency Certification Pursuit | Turkey-European Commission mutual recognition would unlock streamlined Dutch supermarket private-label placement. |
Research Methodology
Operator-level perspectives from Aegean processing facility managers, German industrial bakery procurement heads, Dutch retail category buyers, and Turkish export compliance officers anchored the qualitative base. Secondary validation drew from Turkish Food Codex enforcement records, EFSA contaminant threshold documentation, EU organic regulation audit protocols, and Rotterdam port customs data. Bottom-up volume triangulation against top-down trade flow analysis calibrated segment boundaries.
Scenario-bracketing framed demand projections across the analysis window, modeling product type splits between organic and conventional grades, distribution channel migration from wholesale to direct procurement, and end-use fragmentation across food processing and bakery applications. CAGRs derived from segment-level growth rate reconciliation with macro trade flow trajectories. Forecast inputs incorporated EU Green Deal procurement policy implementation pace and hybrid dehydration technology diffusion curves.
Sensitivities concentrate around EFSA mycotoxin threshold revisions, Turkey-EU organic equivalency negotiation outcomes, and Aegean labor cost inflation. Forecasts reflect assumptions on certification timeline compression and optical sorting capacity buildout rates. Quarterly review of Turkish export laboratory certification volumes and German industrial bakery inclusion rate standardization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
Fruit Pulp Market
Fruits and Vegetables
North America Organic Fruits Market
Fruits and Vegetables
Grapefruit Peel Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Saudi Arabia Fruits and Vegetables Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market
Fruits and Vegetables
Olive Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Canned Fruits and Vegetables Market
Fruits and Vegetables
Japan Fresh Fruits Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
North Africa Table Olives Market