
 Fresh Strawberry Market | 2026-2036
Fresh Strawberry Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Strawberry Market Analysis
Direct-to-consumer subscription channels is tilting toward consolidated berry platforms that bypass traditional wholesale tiers. Driscoll's controls proprietary genetics and licensed varietal programs across North American growing regions. Wish Farms competes through vertical coordination from field packing to retail shelf placement. Naturipe Farms anchors cooperative supply structures that aggregate output from multiple state-level growing associations.
Fresh strawberries constitute the ripe, fleshy aggregate fruit of Fragaria × ananassa, harvested at peak color development with soluble solids typically exceeding 6-8°Brix and maintained under continuous cold-chain temperatures below 4°C to suppress respiration and gray mold incidence. Conventional berries dominate volume throughput due to established spray programs and scale economics, while organic berries command structural margin premiums reflecting labor-intensive weed management and extended field conversion timelines. Freeze-dried strawberries represent the fastest-growing processed format as snack manufacturers and cereal formulators seek clean-label fruit inclusions with extended ambient stability.
USDA grading standards and FDA produce safety rules govern domestic market access, while California's Department of Pesticide Regulation imposes additional residue thresholds that shape varietal breeding priorities and input selection across the state's coastal counties. Stakeholders must monitor water allocation rulings from California's State Water Resources Control Board, as groundwater sustainability mandates threaten acreage expansion in the Pajaro and Salinas valleys. The interplay between varietal patent expirations and climate adaptation investments will determine which growers secure preferred retail shelf space without explicit year-based commitments.
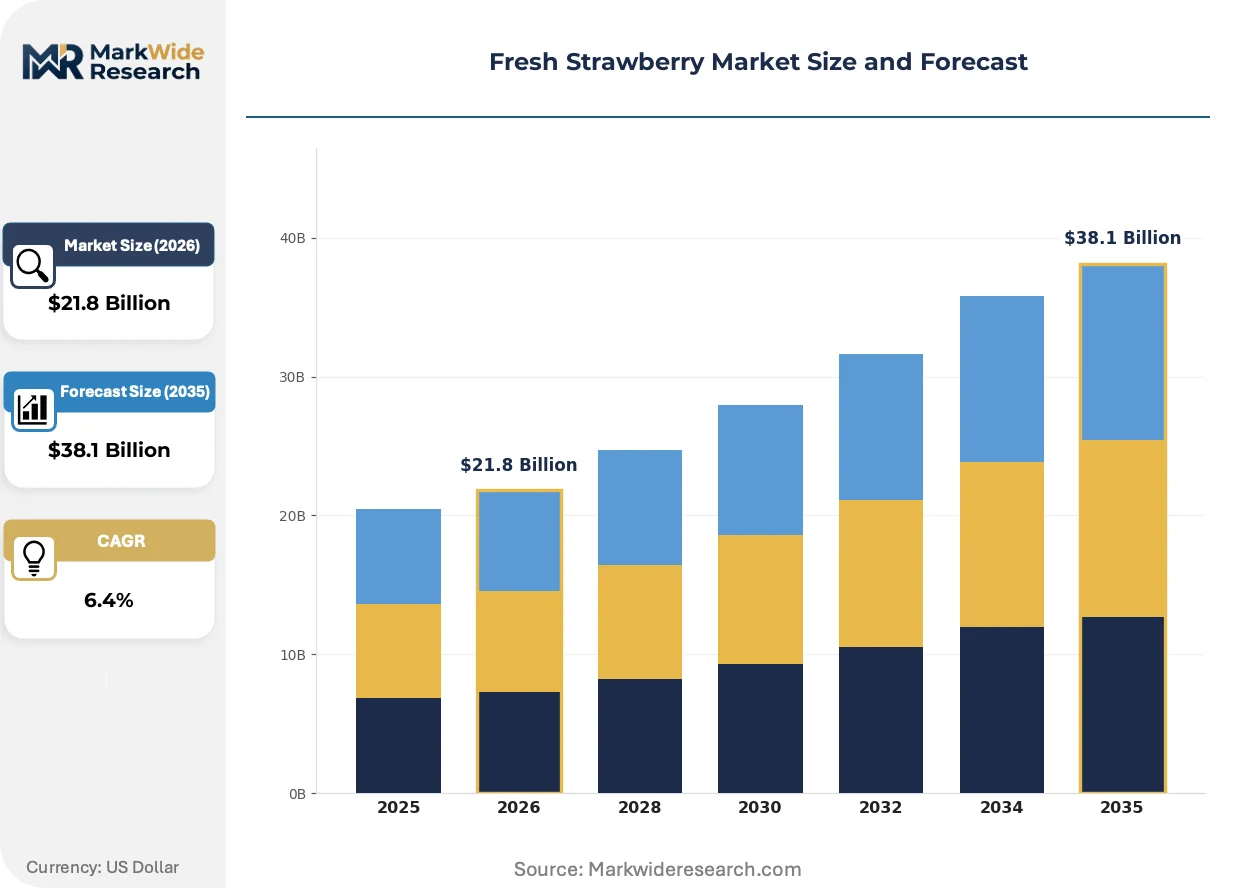
Market Dynamics
California's State Water Resources Control Board groundwater sustainability mandates are forcing acreage consolidation in coastal growing valleys, reshaping how producers secure preferred retail shelf space without explicit year-based commitments.
Growth Catalysts
- USDA Organic Certification:Labor-intensive field conversion timelines create structural margin premiums that reward early-adopter growers with sustained price positioning above conventional tier benchmarks.
- Freeze-dried Processing:Snack manufacturers and cereal formulators drive clean-label fruit inclusion demand, extending ambient stability windows for processed strawberry formats.
- Foodservice Procurement Expansion:Premium dessert and beverage applications concentrate procurement volumes through direct contracting with coastal California microclimate zones.
Market Restraints
- Groundwater Allocation Volatility:California's Sustainable Groundwater Management Act implementation threatens Pajaro and Salinas valley acreage expansion timelines.
- Input Cost Concentration:Labor-intensive weed management in organic systems compresses field-level economics against established conventional spray programs.
- Gray Mold Technical Ceiling:Continuous cold-chain maintenance below 4°C remains non-negotiable, limiting distribution radius extension without infrastructure investment.
Strategic Opportunities
- Direct-to-Consumer Subscription Channels:Consolidated berry platforms bypass traditional wholesale tiers, capturing margin previously distributed across intermediaries.
- Varietal Patent Expiration Windows:Proprietary genetics licensing structures open field-level access for adaptive breeding programs responding to climate pressure.
- Cooperative Supply Aggregation:State-level growing associations pool output through centralized packing and retail shelf placement coordination.
Industry Challenges
- Cold-Chain Infrastructure Capex:Field packing through retail shelf placement requires continuous temperature suppression investment across lengthening distribution legs.
- Residue Threshold Compliance:California's Department of Pesticide Regulation imposes varietal breeding priorities that compress development cycle timelines against input selection constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Strawberry Market |
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $38.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Berries, Conventional Berries, Freeze-Dried Strawberries, Puree End User: Foodservice, Retailers, Wholesalers, Direct-to-Consumer Packaging Type: Clamshell, Bulk Packaging, Pouches, Cans Sales Channel: Online Retail, Supermarkets, Farmers' Markets, Distributors |
| Companies Covered | Driscoll's, Ohalo Genetics, California Giant Berry Farms, Berry Sweet Research, California Strawberry Commission, Wish Farms, Florida Strawberry Growers Association, Chris Christian Nursery, Naturipe Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Strawberry Market Emerging Trajectories
Breeding priorities, regulatory water allocation frameworks, and channel disintermediation are compressing traditional supply hierarchies while accelerating varietal turnover rates.
Precision irrigation with soil-moisture sensor networks is migrating from high-value permanent crop operations into annual strawberry systems. Large-scale Central Coast producers deploy subsurface drip with real-time telemetry to optimize water application timing. This migration from flood-furrow methods is compressing per-acre water consumption while stabilizing soluble solids concentration through reduced plant stress.
California's Department of Pesticide Regulation residue thresholds are reshaping varietal development pipelines across coastal counties. Breeders now prioritize pest resistance traits alongside flavor and shelf-life metrics in release decisions. Organic program participants face accelerated input substitution timelines as prohibited substance lists expand beyond federal baselines.
Consolidated berry platforms disintermediate traditional wholesale tiers through field-direct subscription fulfillment. Foodservice operators and specialty retailers contract directly with cooperative supply structures, compressing price discovery cycles. This channel restructuring concentrates most visibly in California's Central Coast growing region where microclimate advantages sustain year-round production volumes.
Fresh Strawberry Market Segmentation
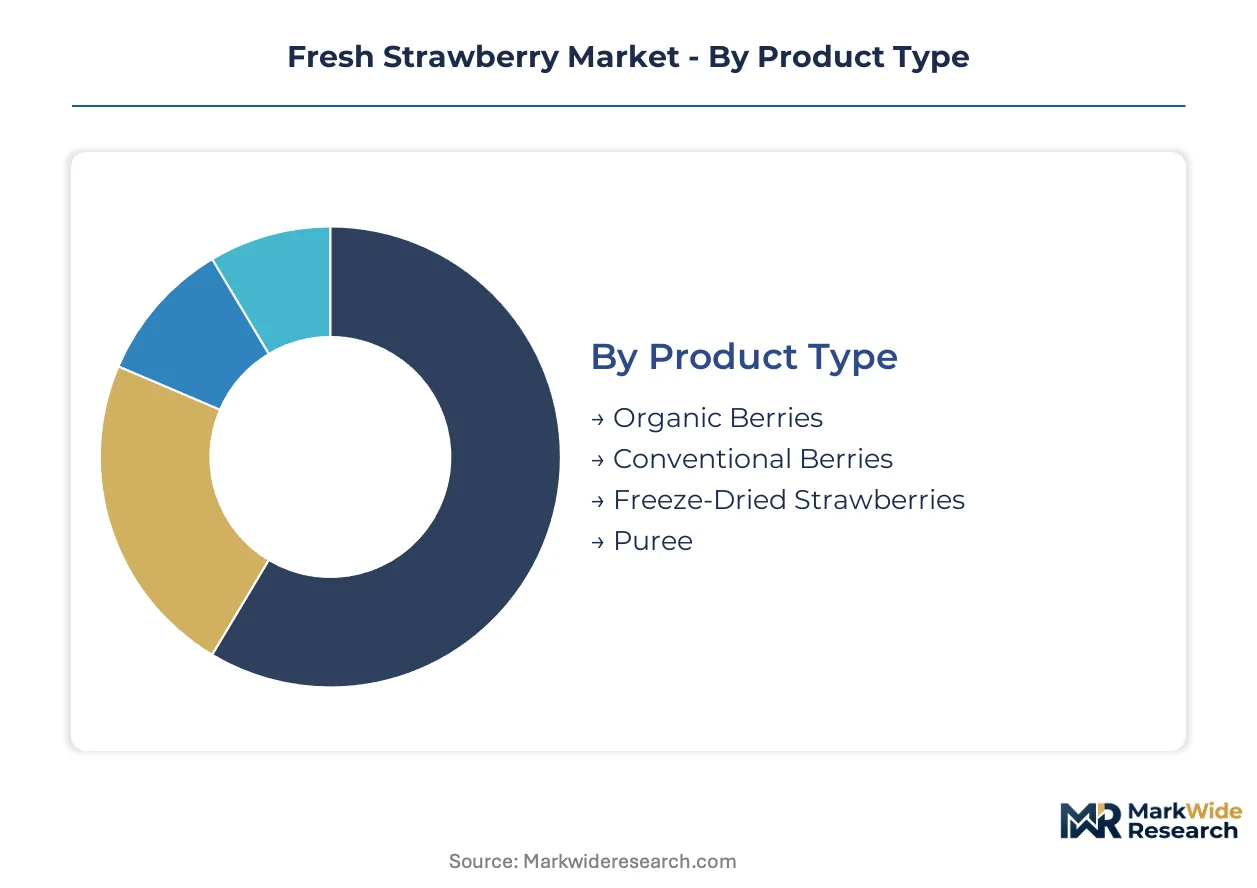
Fresh strawberry segmentation reveals how product form, buyer type, and channel structure create divergent margin profiles and inventory velocity requirements. Each dimension carries distinct cold-chain obligations, certification thresholds, and shelf-life constraints that reshape procurement patterns across coastal California growing zones.
Product Type:
Cycle times vary dramatically across this dimension, with fresh formats turning in days while processed alternatives extend inventory windows to months.
- Conventional Berries:Harvested at peak color development with soluble solids exceeding 6-8°Brix, these berries dominate volume throughput through established spray programs and scale economics. Foodservice operators in California's Central Coast microclimate zones concentrate procurement through direct contracting for premium dessert applications.
- Freeze-Dried Strawberries:Clean-label fruit inclusions with extended ambient stability serve snack manufacturers and cereal formulators seeking reduced perishability. This format climbs the fastest as brands reformulate around supply chain resilience and reduced refrigeration dependency.
- Organic Berries:Labor-intensive weed management and extended field conversion timelines command structural margin premiums above conventional benchmarks.
- Puree:Processed format for beverage and bakery applications requiring standardized brix levels and pasteurized stability.
Conventional berries anchor the volume base while freeze-dried strawberries gain share at the steepest rate.
End User:
Cost tiers separate this category, with premium procurement concentrated in direct-contracting foodservice while wholesale intermediaries absorb price volatility.
- Foodservice:Premium dessert and beverage applications demand exacting size grading and continuous cold-chain compliance below 4°C. California coastal growers secure preferred shelf placement through direct contracting without year-based volume commitments.
- Direct-to-Consumer:Subscription platforms bypass traditional wholesale tiers, capturing margin previously distributed across intermediaries through field-direct fulfillment models.
- Retailers:Supermarket chains impose proprietary packaging specifications and residue threshold requirements that shape varietal breeding priorities.
- Wholesalers:Consolidated berry platforms aggregate output from multiple state-level growing associations for redistribution to smaller retail accounts.
Foodservice commands the highest per-unit margins while direct-to-consumer channels expand most quickly.
Packaging Type:
Application requirements drive selection, with retail-facing formats prioritizing shelf visibility while foodservice emphasizes handling efficiency.
- Clamshell:Standard retail format with ventilation engineering to suppress condensation and gray mold incidence during display.
- Bulk Packaging:Foodservice and processing channels utilize reduced-per-unit packaging costs for high-volume procurement.
- Pouches:Freeze-dried and processed formats employ moisture-barrier films for ambient distribution.
- Cans:Shelf-stable puree applications for industrial bakery and beverage manufacturing.
Clamshell dominates retail shelf placement while bulk packaging captures foodservice procurement volumes.
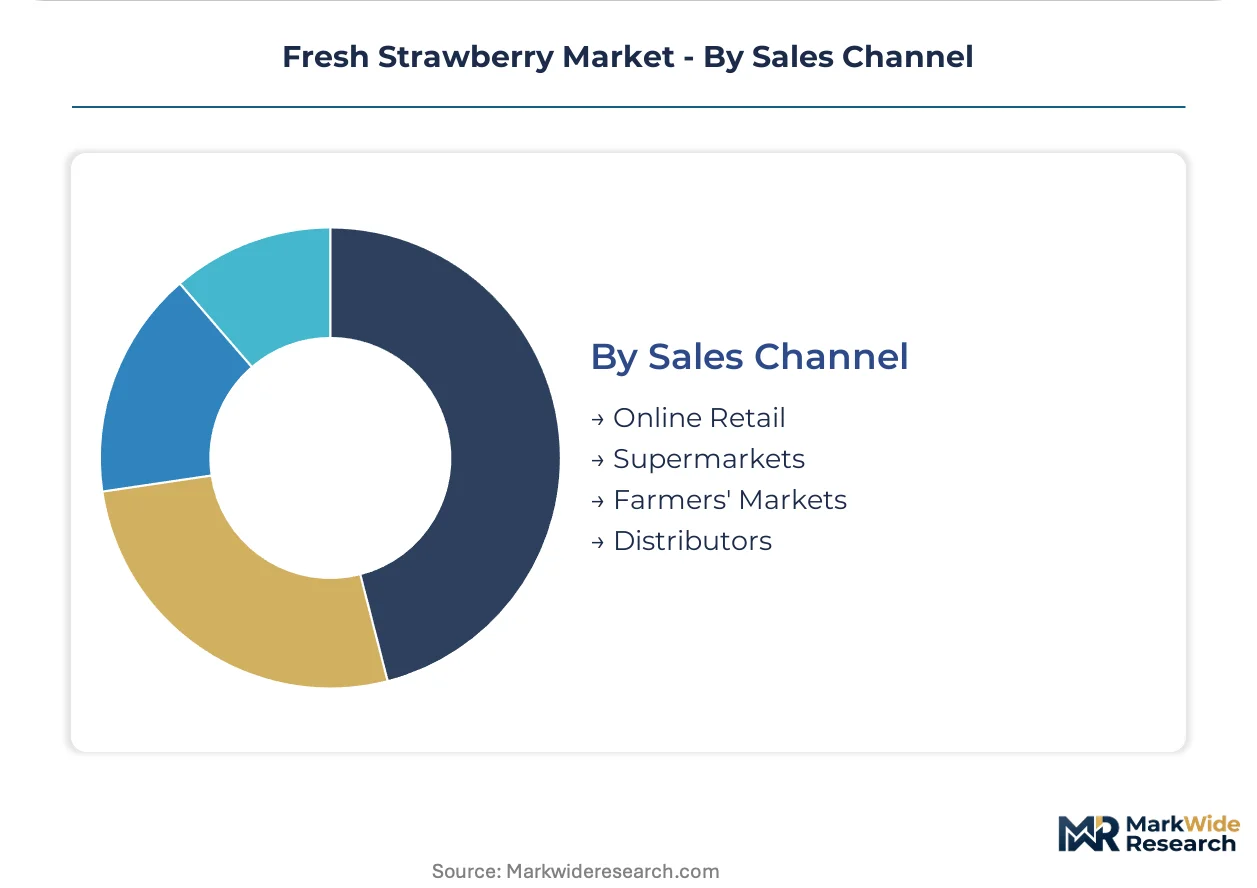
Sales Channel:
Geography concentrates channel performance, with California's Central Coast microclimate advantages sustaining year-round production volumes for premium positioning.
- Supermarkets:Centralized procurement through cooperative supply structures aggregates output across multiple growing associations for consistent shelf stocking.
- Online Retail:Consolidated berry platforms deploy cold-chain logistics investments to extend distribution radius beyond traditional wholesale boundaries.
- Farmers' Markets:Direct producer-to-consumer contact captures premium pricing for same-day harvested product with minimal handling stages.
- Distributors:Traditional wholesale tiers face margin compression as direct contracting and subscription channels disintermediate established relationships.
Supermarkets retain the largest volume share while online retail climbs fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Coast growers capture premium shelf positioning through year-round microclimate production, while Mexican suppliers compete on volume throughput with shorter logistics legs into US distribution centers.
United States
Foodservice operators and direct-to-consumer subscription platforms concentrate procurement in California's Pajaro and Salinas valleys. The USDA organic certification protocol shapes grower compliance timelines across coastal counties. Driscoll's and Wish Farms anchor proprietary genetics and vertical coordination structures in Watsonville and Santa Maria production clusters.
Mexico
Seasonal production windows in Baja California and Michoacán supply US retail chains during domestic off-peak months. Mexico's SENASICA phytosanitary standards govern export eligibility for fresh berry shipments. Field packing operations in Zamora and Irapuato coordinate cold-chain handoffs to Laredo and San Diego border crossings.
Spain
Huelva province growers supply European supermarkets through controlled-environment tunnel production from January through June. Spain's Ministry of Agriculture imposes residue monitoring protocols under EU-wide EFSA safety frameworks. Cooperatives in Lepe and Moguer aggregate output for centralized distribution to German and French retail accounts.
Egypt
Nile Delta winter production captures European import demand during November-March supply gaps. Egypt's Central Administration of Plant Quarantine regulates export certification for EU and Gulf destination markets. Kafr El-Sheikh and Beheira governorships concentrate greenhouse and open-field acreage for Rotterdam and Jeddah shipment routing.
China
Domestic consumption growth in tier-one cities drives protected-culture expansion in Shandong and Liaoning provinces. China's SAMR food safety standards and GB national standards govern pesticide residue limits for fresh produce. Dandong and Qingdao production zones supply Beijing and Shanghai wholesale markets through shortened cold-chain legs.
Fresh Strawberry Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in genetics and propagation. The fresh strawberry market structures around proprietary varietal licensing, cooperative supply aggregation, and direct-to-consumer channel control. Three archetypes dominate: genetics licensors with patent-protected breeding programs, vertically coordinated field-to-shelf operators, and cooperative federations pooling multi-grower output. Competitive moves concentrate on varietal patent expiration windows and cold-chain infrastructure capex to extend distribution radius.
Among North American platform operators, Driscoll's exemplifies the genetics-licensor archetype through proprietary varietal programs, while Wish Farms occupies the vertically coordinated tier with field-packing through retail placement control. Naturipe Farms anchors cooperative supply structures that aggregate output across state-level growing associations. These three represent the dominant competitive configurations without explicit year-based volume commitments.
| Leading Market Players |
|---|
| Driscoll's |
| Ohalo Genetics |
| California Giant Berry Farms |
| Berry Sweet Research |
| California Strawberry Commission |
| Wish Farms |
| Florida Strawberry Growers Association |
| Chris Christian Nursery |
| Naturipe Farms |
| Others |
Supply Flow & Price Mechanics
California's Central Coast growing concentration funnels 80% of domestic fresh strawberry volume through Pajaro and Salinas valley packers, concentrating margin capture with vertically coordinated operators who control field-to-retail shelf placement. This upstream density translates into asymmetric pricing power where cooperative federations and proprietary genetics licensors extract premiums while independent growers absorb input cost volatility.
Pricing Analysis
Organic-conventional spread pricing dominates transactional dynamics, with USDA-certified berries commanding structural premiums reflecting three-year field conversion timelines and labor-intensive hand-weeding protocols. Price differentiation rests on certification tier, varietal patent status, and cold-chain infrastructure depth. Pricing pressure intensifies in conventional tiers as Mexican seasonal imports compress domestic harvest windows. Foodservice operators show lowest price sensitivity due to menu-premium pass-through capability, while mass retailers enforce strict procurement cost ceilings.
Supply Chain Analysis
Supplier-financing arrangements through cooperative packing houses extend payment terms to 45-60 days, easing working capital strain for smallholder participants. Geographic supply concentrates in California, Mexico's Baja California and Michoacán, and Spain's Huelva province. Raw material dependencies center on proprietary nursery stock, methyl bromide alternatives for soil fumigation, and refrigerated container capacity. Single-source vulnerability runs through Driscoll's genetics licensing network. Distribution runs through temperature-controlled LTL networks with continuous 4°C maintenance from field packing through retail shelf placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
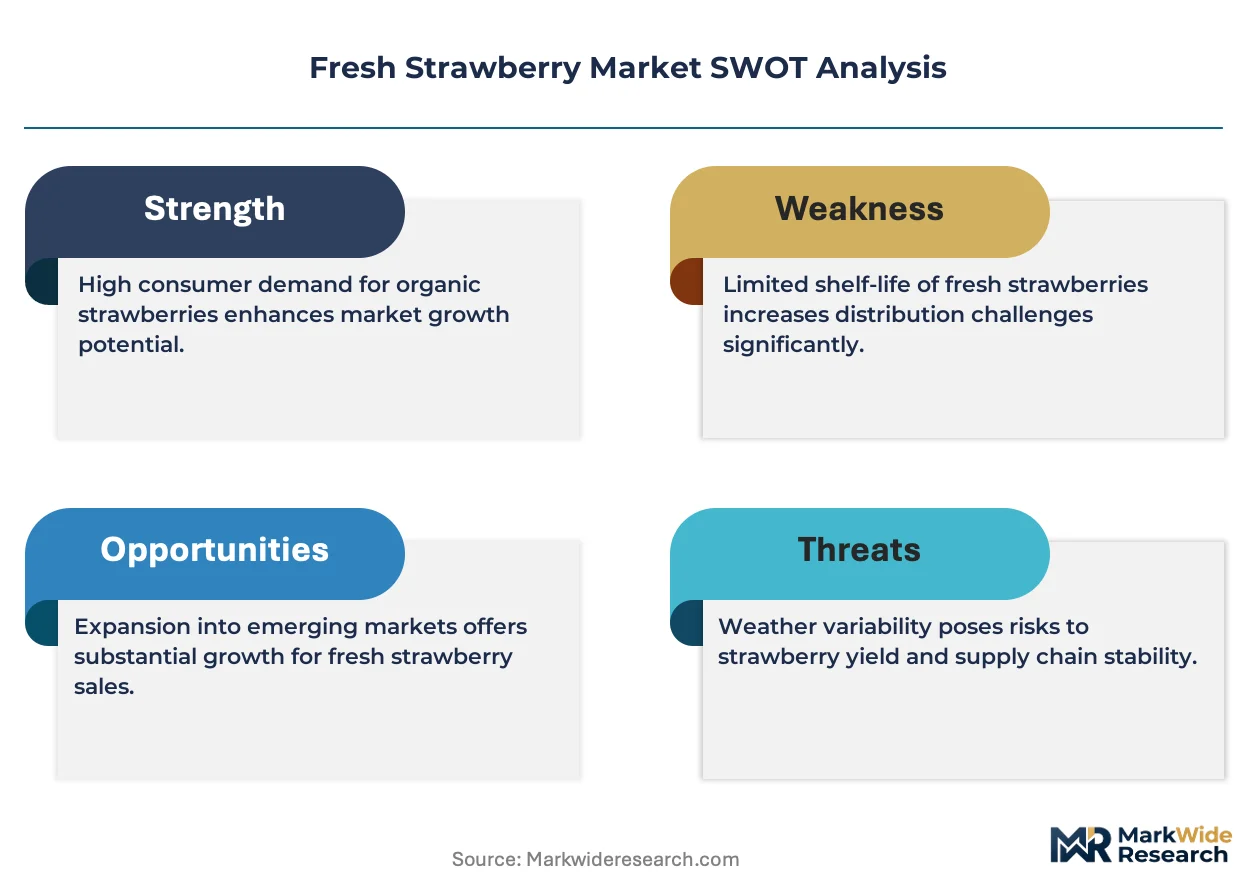
Fresh strawberry market expansion is accelerating through precision irrigation telemetry and direct-to-consumer channel disintermediation, with California's Sustainable Groundwater Management Act forcing structural consolidation among coastal growers.
For Market Incumbents: Harden cold-chain infrastructure through subsurface drip telemetry investments that stabilize soluble solids concentration and reduce per-acre water consumption. Consolidate preferred retail shelf placement through cooperative supply aggregation that pools output across state-level growing associations. Defensive positioning requires preemptive varietal patent licensing before expiration windows open field-level access to adaptive breeding programs.
For New Entrants and Emerging Players: Egypt's Nile Delta winter production gaps present accessible white-space for greenhouse operators targeting European November-March import demand. China's tier-one city protected-culture expansion offers second entry vector through shortened cold-chain legs into Beijing and Shanghai wholesale markets. Go-to-market execution should anchor on direct-to-consumer subscription fulfillment that bypasses traditional wholesale margin extraction.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically coordinated field-to-shelf operators with proprietary genetics access and established retail placement control. Long-term viability over the coming decade hinges on climate adaptation investments and water rights security in groundwater-stressed growing regions. Monitor California State Water Resources Control Board allocation rulings as inflection signal for acreage consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Irrigation Deployment | Soil-moisture sensor networks from permanent crop operations migrate into annual strawberry systems, compressing water consumption. |
| Direct-to-Consumer Channel Launch | Consolidated berry platforms capture margin previously distributed across wholesale intermediaries through field-direct fulfillment. |
| Organic Certification Investment | Three-year field conversion timelines create structural margin premiums that reward early-adopter growers with sustained price positioning. |
| Freeze-Dried Processing Capacity | Clean-label fruit inclusion demand from snack manufacturers extends ambient stability windows for processed strawberry formats. |
| Varietal Patent Licensing | Proprietary genetics programs control field-level access for adaptive breeding programs responding to climate pressure and residue thresholds. |
Methodological Framework
A standing panel of strawberry breeding program directors, cooperative packing house managers, foodservice procurement officers, and retail category buyers provided ongoing calibration across the study period. Primary field interviews with Central Coast growers, Mexican export coordinators, and European supermarket sourcing teams combined with secondary validation from USDA National Agricultural Statistics Service crop reports, California Department of Pesticide Regulation residue monitoring databases, and FDA produce safety rule guidance documents. Bottom-up acreage and yield estimates triangulated against top-down consumption surveys and import-export customs records.
Scenario-bracketing around groundwater allocation rulings and varietal patent expiration windows anchored the analytical framework across the projection horizon. Segmentation modeling incorporated product type, end-user procurement tier, packaging format, and sales channel structure. CAGRs derived from fitted growth curves against historical volume trajectories, with adjustments for climate adaptation investment cycles and cold-chain infrastructure expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Mexican suppliers or Chinese protected-culture operators would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
Raisins Market
Fruits and Vegetables
Middle East and Africa Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Spain Tropical Fruits Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Guanabana Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
Lemon Juice Concentrate Market
Fruits and Vegetables
Brown Shimeji Mushroom Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Fresh Lemons Market
Fruits and Vegetables
Mulberry Market