
 Canada 3PL Market | 2026-2036
Canada 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
Canada 3PL Market Analysis
Ontario is fragmenting as the dominant node for Canadian third-party logistics capacity, with Alberta and British Columbia adding competing distribution infrastructure. DSV leverages its North American network density to anchor transborder freight movements between Toronto and Detroit. Kuehne+Nagel sustains specialized pharmaceutical cold-chain operations through temperature-controlled facilities in Montreal and Vancouver. Metro Supply Chain competes on e-commerce fulfillment velocity, operating same-day delivery hubs in the Greater Toronto Area.
Third-party logistics encompasses outsourced supply chain management functions including transportation brokerage, warehousing operations, inventory management, and value-added distribution services performed under contract rather than captive ownership. Providers typically operate multi-client facilities with rack storage densities exceeding 25,000 pallet positions and cross-dock throughput designed for 24-48 hour inventory turns. The service type dimension shows integrated offerings capturing margin pools as clients consolidate vendor relationships, while warehousing segments face yield pressure from automated facility investments. End-user concentration tilts toward e-commerce and automotive sectors, with retailers demanding omnichannel fulfillment architectures that merge store and direct-to-consumer inventory pools.
Health Canada regulates pharmaceutical distribution through establishment licensing requirements that 3PLs must maintain for healthcare clients. Transport Canada enforces the Electronic Logging Device mandate and hours-of-service rules that constrain driver availability and reshape route planning algorithms. The Canadian Food Inspection Agency imposes traceability standards on food-grade warehousing that filter provider qualification criteria. Stakeholders must monitor how carbon border adjustment mechanisms and provincial clean fuel standards will recalibrate freight mode selection and facility energy sourcing decisions.
Market Dynamics
Ottawa's transportation modernization agenda and cross-border trade protocols are forcing Canadian 3PLs to reconfigure compliance architectures around Electronic Logging Device mandates and carbon border adjustment mechanisms.
Growth Catalysts
- E-commerce fulfillment velocity:Canadian retailers are consolidating vendor relationships around integrated service providers capable of same-day delivery architectures. Metro Supply Chain and competitors are expanding GTA hub capacity to capture this demand.
- Health Canada establishment licensing:Pharmaceutical cold-chain requirements create specialized moats for temperature-controlled facility operators. Kuehne+Nagel leverages Montreal and Vancouver assets to serve healthcare clients.
- Alberta and British Columbia infrastructure buildouts:Distribution gravity is fragmenting beyond Ontario as western provinces add competing logistics corridors. DSV anchors transborder movements through Calgary and Vancouver nodes.
Market Restraints
- Driver availability constraints:Transport Canada hours-of-service rules compress route planning algorithms and inflate labor costs. Fleet operators face scheduling inflexibility during peak seasonal windows.
- Automated facility capex cycles:Warehouse robotics and WMS investments demand capital deployment at scale. Mid-tier providers risk yield compression against technology-leader cost structures.
- Cross-border customs friction:US-Canada protocol complexity adds dwell time at Detroit-Windsor and Blaine-Surrey corridors. DSV and peers absorb compliance overhead in transborder pricing.
Strategic Opportunities
- Quebec pharmaceutical specialization:Montreal's life sciences cluster lacks sufficient cold-chain depth. Providers with Health Canada licenses can expand temperature-controlled square footage.
- Provincial clean fuel standards:British Columbia and Quebec low-carbon fuel rules create fleet electrification incentives. Early adopters secure preferential lane access and municipal contracts.
- AI-driven demand forecasting:Machine learning convergence with warehouse management systems enables dynamic inventory positioning. Retailers in the GTA are piloting predictive replenishment models.
Industry Challenges
- WMS-legacy ERP integration:Automotive and food-grade clients operate decades-old enterprise systems. 3PLs face customization costs and timeline overruns during platform migration.
- CFIA traceability certification timelines:Food-grade warehousing qualification requires extensive documentation. Providers report 6-12 month approval windows for new facility onboarding.
- Specialized technician scarcity:Automated sortation and robotics maintenance demand electro-mechanical skill sets. Technical colleges in Ontario and Alberta lag industry training requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada 3PL Market |
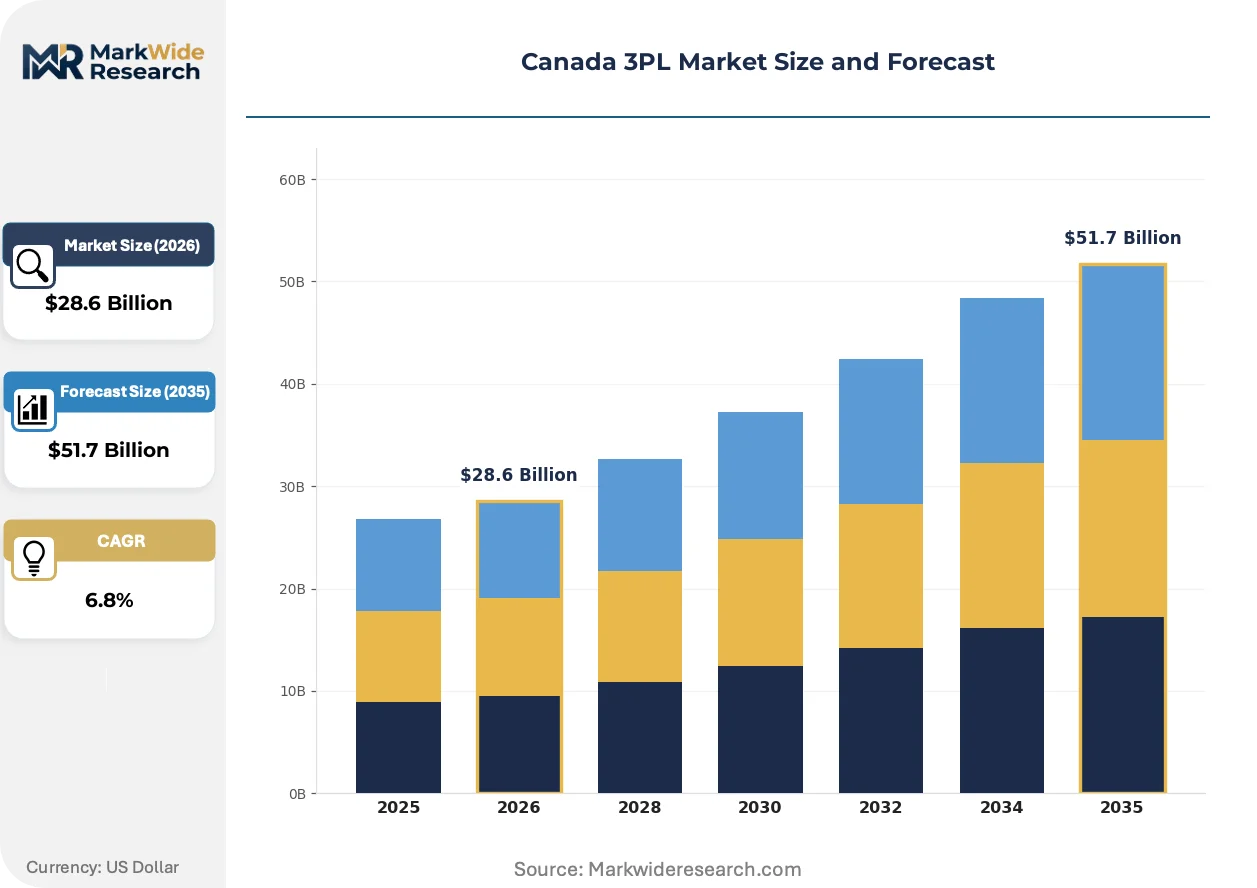
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Integrated End User: Retailers, Manufacturers, E-commerce, Automotive Technology: IoT Solutions, Warehouse Management Systems, Autonomous Vehicles, RFID Delivery Mode: Road, Rail, Air, Sea |
| Companies Covered | DSV, Kuehne+Nagel, Metro Supply Chain, CEVA Logistics, Groupe Robert, Purolator Logistics, DHL Supply Chain, 18 Wheels Logistics, Lineage Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada 3PL Market Emerging Trajectories
Digital twin technology and warehouse automation are compressing inventory turns and redefining competitive positioning in Canadian logistics corridors.
Digital twin platforms are virtualizing facility operations through real-time sensor networks and predictive simulation engines. Retailers in the Greater Toronto Area are deploying these systems to optimize slotting algorithms and labor deployment. The technology is virtualizing traditional warehouse management by enabling scenario testing without physical disruption.
Transport Canada's Electronic Logging Device mandate continues reshaping fleet dispatch and route optimization protocols. Carriers must now integrate telematics data into driver scheduling systems with automated compliance flagging. Long-haul segments serving the Detroit-Torridor face the steepest adaptation costs as cross-border movements compound regulatory complexity.
Omnichannel fulfillment architectures are merging store and direct-to-consumer inventory pools into unified stock positioning models. Canadian retailers are abandoning channel-segregated warehousing in favor of distributed micro-fulfillment nodes. This pattern concentrates investment in the GTA and Vancouver where population density supports same-day delivery radius economics.
Canada 3PL Market Segmentation
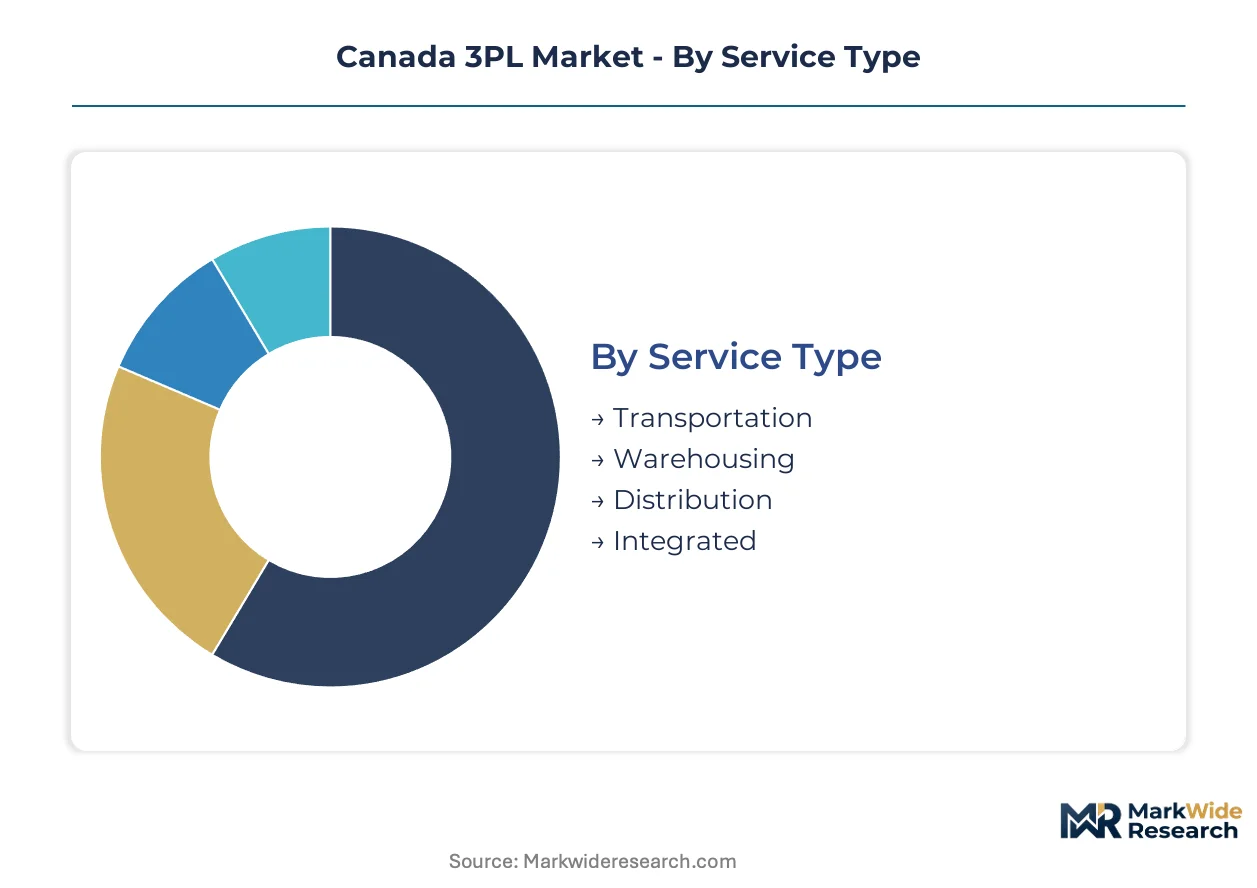
Canadian 3PL providers structure their service portfolios around distinct operational capabilities and client risk profiles. Each segmentation dimension reveals divergent margin structures, capital intensity requirements, and regulatory exposure across the national logistics network.
Service Type:
Cost tier differentiation separates commoditized brokerage functions from integrated relationship-based contracts with embedded technology and compliance services.
- Integrated:Bundled offerings combine transportation brokerage, warehousing operations, and value-added distribution under single-contract governance. Canadian retailers consolidating vendor relationships around Metro Supply Chain and DSV are driving demand concentration here. Health Canada establishment licensing requirements and Transport Canada ELD mandates create compliance moats that justify premium pricing.
- Warehousing:Dedicated and multi-client facilities with rack storage densities exceeding 25,000 pallet positions and cross-dock throughput designed for 24-48 hour inventory turns. Ontario's Greater Toronto Area logistics corridor anchors capacity expansion as e-commerce fulfillment velocity accelerates adoption among Canadian retailers.
- Transportation:Asset-light brokerage and fleet-based carriage connecting origin-destination pairs across provincial boundaries and cross-border corridors.
- Distribution:Last-mile and intermediate-mile delivery orchestration with value-added services including kitting, labeling, and returns processing.
Integrated commands the established base. The steepest expansion runs through Warehousing.
End User:
Application-specific requirements reshape facility specifications, labor models, and technology investments across customer verticals.
- E-commerce:Omnichannel fulfillment architectures merging store and direct-to-consumer inventory pools into unified stock positioning models. Same-day delivery hubs in the Greater Toronto Area and Vancouver micro-fulfillment nodes concentrate investment where population density supports delivery radius economics.
- Automotive:Sequenced parts delivery, just-in-time inventory management, and reverse logistics for manufacturing supply chains serving Ontario and Quebec assembly plants.
- Retailers:Store replenishment, seasonal surge capacity, and promotional event logistics for national and regional chains.
- Manufacturers:Raw materials inbound, finished goods outbound, and vendor-managed inventory programs for industrial production networks.
Automotive anchors the revenue base. E-commerce climbs the fastest as fulfillment velocity rewrites procurement criteria.
Technology:
Maturity gradients separate proven infrastructure from experimental deployments requiring specialized integration expertise and change management.
- Warehouse Management Systems:Core software platforms orchestrating inventory tracking, labor deployment, and slotting optimization across multi-client facilities. Retailers in the GTA are piloting predictive replenishment models through machine learning convergence with legacy WMS architectures.
- IoT Solutions:Sensor networks enabling real-time visibility into temperature, location, and handling conditions for pharmaceutical cold-chain and food-grade cargo regulated by Health Canada and CFIA.
- RFID:Automated identification and tracking infrastructure for high-velocity sortation and inventory reconciliation.
- Autonomous Vehicles:Yard management automation and last-mile delivery pilots subject to Transport Canada regulatory frameworks still in development.
Warehouse Management Systems hold the installed base. IoT Solutions gains share fastest through regulatory compliance mandates.
Delivery Mode:
Geography and cargo characteristics determine modal selection, with carbon border adjustment mechanisms and provincial clean fuel standards recalibrating long-term freight economics.
- Road:Dominant mode for domestic distribution and cross-border movements through Detroit-Windsor and Blaine-Surrey corridors. Transport Canada hours-of-service rules and ELD mandates compress route planning flexibility and inflate labor costs during peak seasonal windows.
- Rail:Bulk commodity and containerized intermodal movements across the Canadian National and Canadian Pacific networks connecting port and inland terminals.
- Air:Time-definite pharmaceutical, electronics, and perishable shipments through Montreal, Toronto, and Vancouver international gateways.
- Sea:International container imports and exports through Vancouver, Prince Rupert, and Halifax port complexes with inland rail and truck connections.
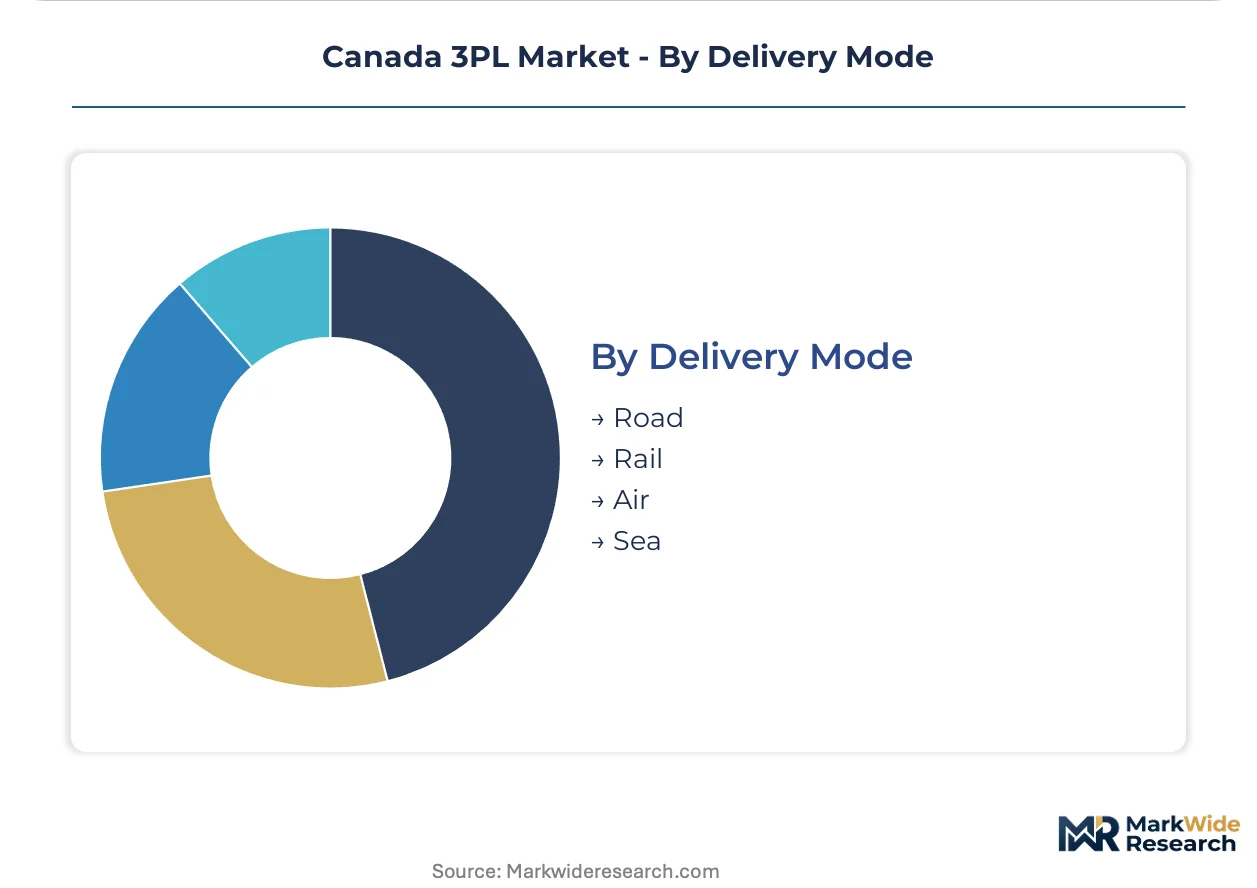
Road dominates volume throughput. Rail captures the steepest capacity expansion as port and inland terminal investments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The CN Rail network and Port of Vancouver container terminals anchor Canada's trans-Pacific trade position, while the Detroit-Windsor corridor processes the densest cross-border freight flows in North America.
Ontario
E-commerce fulfillment velocity and automotive just-in-time sequencing drive demand concentration in the Greater Toronto Area. Transport Canada enforces Electronic Logging Device mandates that compress route planning algorithms for cross-border carriers. The Windsor-Quebec City logistics corridor anchors transborder movements through Detroit-Windsor, where DSV and Metro Supply Chain operate competing distribution infrastructure.
Quebec
Pharmaceutical cold-chain requirements and aerospace parts logistics concentrate specialized 3PL demand around Montreal. Health Canada establishment licensing creates regulatory moats for temperature-controlled facility operators. The Montreal-Quebec City corridor hosts Kuehne+Nagel's healthcare distribution assets, serving life sciences clusters with Health Canada-compliant warehousing.
British Columbia
Asia-Pacific container imports and provincial clean fuel standards reshape freight mode selection around Vancouver and Prince Rupert. The Canadian Food Inspection Agency imposes traceability standards on food-grade warehousing that filter provider qualification criteria. Metro Vancouver's port-rail intermodal terminals anchor competing distribution infrastructure for Pacific Rim trade.
Alberta
Energy sector logistics and agricultural commodity distribution drive specialized warehousing demand in Calgary and Edmonton. Provincial carbon pricing mechanisms recalibrate fleet electrification incentives for regional carriers. The Calgary-Edmonton corridor adds competing distribution infrastructure as western provinces fragment Ontario's historical dominance.
Atlantic Canada
Seafood exports and offshore supply chain logistics concentrate specialized cold-chain demand in Halifax and St. John's. Transport Canada hours-of-service rules constrain driver availability for long-haul movements connecting to central Canada. The Halifax port complex processes international container flows with inland rail connections to Quebec and Ontario manufacturing networks.
Canada 3PL Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in niche regulatory segments. The Canada 3PL market structures around three tiers: global network operators with transborder density, regional specialists with Health Canada or CFIA certifications, and e-commerce velocity players with GTA micro-fulfillment nodes. Strategic moves concentrate on warehouse automation capex cycles and Alberta-British Columbia infrastructure buildouts that fragment Ontario's dominance.
Among global network operators, DSV and Kuehne+Nagel anchor transborder and pharmaceutical cold-chain positioning respectively. DSV leverages North American density for Detroit-Toronto freight movements. Kuehne+Nagel occupies the temperature-controlled healthcare tier through Montreal and Vancouver assets. Metro Supply Chain exemplifies the e-commerce velocity archetype with same-day delivery hub concentration in the Greater Toronto Area.
| Leading Market Players |
|---|
| DSV |
| Kuehne+Nagel |
| Metro Supply Chain |
| CEVA Logistics |
| Groupe Robert |
| Purolator Logistics |
| DHL Supply Chain |
| 18 Wheels Logistics |
| Lineage Logistics |
| Others |
Supply Flow & Price Mechanics
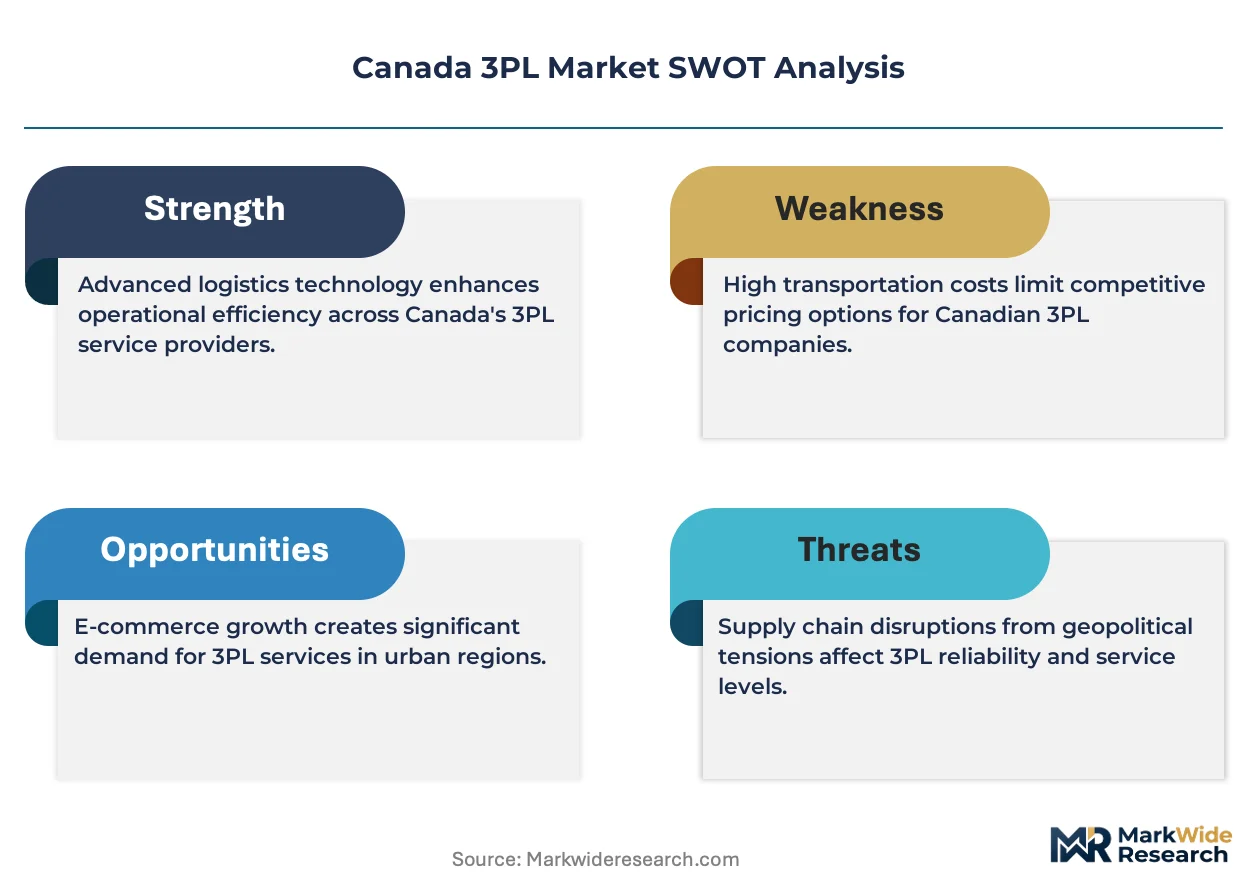
US cross-border trucking capacity concentration around Detroit-Windsor and Blaine-Surrey corridors funnels margin pools toward integrated providers with transborder compliance architectures. Health Canada establishment licensing and Transport Canada ELD mandates create tiered cost structures that downstream buyers absorb through contract premiums or vendor consolidation.
Pricing Analysis
Transport Canada Electronic Logging Device mandates dictate the pricing tier structure across Canadian 3PL service portfolios. Three-tier pricing structure across premium, standard, and economy levels separates Health Canada-licensed pharmaceutical cold-chain operators from multi-client warehousing generalists and asset-light brokerage functions. Cost compression in standard-tier warehousing is intensifying because automated facility investments demand capital deployment at scale. Small and mid-sized retailers exhibit highest price sensitivity, while pharmaceutical manufacturers accept premium positioning for regulatory compliance assurance.
Supply Chain Analysis
Export-control restrictions on warehouse management system software and automated sortation technology limit flows from US and German technology suppliers into Canadian facility upgrades. Equipment sourcing draws from China, Germany, and the United States for robotics, conveyor systems, and temperature-control infrastructure. Single-source vulnerability concentrates in specialized pharmaceutical cold-chain components where Health Canada certification requirements filter qualified suppliers. Distribution runs through Ontario's Greater Toronto Area logistics corridor as the dominant node, with Alberta and British Columbia infrastructure buildouts fragmenting historical concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canadian 3PL penetration remains below optimal saturation as e-commerce fulfillment velocity rewrites retailer procurement criteria and same-day delivery architectures expand adoption. This early-cycle expansion story accelerates through omnichannel inventory unification and micro-fulfillment node deployment.
For Market Incumbents: Pre-empt margin compression by automating warehouse operations in the Greater Toronto Area before yield pressure from technology-leader cost structures intensifies. Secure Health Canada establishment licensing expansions in Montreal's underserved life sciences cluster. Consolidate vendor relationships around integrated service contracts that embed compliance overhead as non-negotiable value.
For New Entrants and Emerging Players: Pursue Quebec pharmaceutical cold-chain specialization where temperature-controlled square footage lags demand from Montreal's life sciences cluster. Target Alberta and British Columbia distribution infrastructure buildouts that fragment Ontario's historical dominance. Lead with provincial clean fuel standards compliance to secure preferential lane access and municipal fleet electrification contracts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across warehouse automation and robotics segments as mid-tier providers face yield compression against technology-leader cost structures. Five-to-ten year viability favors integrated platform operators with transborder density or regulatory-certified specialization over pure-play brokerage functions. Monitor AI-driven demand forecasting pilot outcomes with GTA retailers as inflection indicator for predictive replenishment model adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Licensing Expansion | Montreal's life sciences cluster lacks sufficient cold-chain depth for pharmaceutical distribution compliance. |
| Automated Facility Investment | Warehouse robotics and WMS convergence compress inventory turns against mid-tier provider cost structures. |
| Provincial Clean Fleet Transition | British Columbia and Quebec low-carbon fuel rules create preferential lane access for early electrification adopters. |
| Transborder Compliance Architecture | Detroit-Windsor corridor density anchors premium pricing power for integrated cross-border service providers. |
| AI-Driven Demand Forecasting | Machine learning convergence with legacy WMS enables dynamic inventory positioning for GTA retailers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of Transport Canada regulatory filings, Health Canada establishment licensing databases, Canadian National and Canadian Pacific network capacity disclosures, and provincial clean fuel standard implementation records. Primary interviews engaged logistics operations directors, pharmaceutical supply chain managers, retail procurement leads, fleet compliance officers, and cold-chain facility engineers. Secondary validation drew from Canadian Food Inspection Agency traceability certification timelines, customs and trade corridor data, and warehouse automation vendor deployment records. Bottom-up facility capacity modeling triangulates against top-down national freight volume estimates.
Forecast inputs incorporate service type segmentation across integrated, warehousing, transportation, and distribution functions; end-user concentration within e-commerce, automotive, retail, and manufacturing verticals; technology adoption gradients for WMS, IoT, RFID, and autonomous systems; and delivery mode splits across road, rail, air, and sea. CAGRs derive from elasticity modeling against e-commerce penetration rates, cross-border trade protocol evolution, and automated facility investment cycles across the analysis window. Industry-specific inputs include Health Canada licensing approval timelines and Transport Canada ELD mandate compliance cost curves.
Sensitivities concentrate around carbon border adjustment mechanism implementation timelines and provincial clean fuel standard enforcement intensity. Forecasts reflect documented assumptions regarding e-commerce fulfillment velocity continuation and cross-border customs friction stability. Material shifts in Ottawa's transportation modernization agenda or US-Canada trade protocol complexity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
California Freight and Logistics Market
Logistics and Shipping
North America Automotive Logistics Market
Logistics and Shipping
Canada Cold Chain Logistics Market
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
Canada Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
North America FMCG Logistics Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Russia Third-Party Logistics (3PL) Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market