
 UK Sustainable Home Furniture Market | 2026-2036
UK Sustainable Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
UK Sustainable Home Furniture Market Analytics
Subscription-based furniture refresh services is realigning how UK consumers access sustainable home furnishings. Sebastian Cox leverages traditional coppicing and local hardwood sourcing to anchor its artisan positioning. Timothy Oulton competes through heritage-inspired craftsmanship with controlled retail presence in London and regional hubs. Revive Innovations specializes in post-consumer plastic conversion, occupying a distinct circular-economy niche.
Sustainable home furniture comprises residential fixtures manufactured from certified renewable, recycled, or low-embodied-carbon materials, with FSC timber chain-of-custody documentation and water-based finishes constituting baseline technical parameters; the category serves consumers seeking verified environmental performance without aesthetic compromise. Recycled wood and bamboo materials dominate volume, though organic cotton upholstery commands premium positioning in the sofa category. Household end users represent the established demand base, while hotels are emerging as a faster-growing channel seeking bulk sustainable procurement.
The UK Timber Procurement Advisory Note and FSC certification requirements shape supplier eligibility for public and commercial contracts, while the Environment Agency's waste regulations govern end-of-life recovery obligations. BSI Kitemark standards for furniture safety and durability intersect with emerging carbon disclosure expectations under the UK Sustainability Disclosure Standards. Stakeholders must monitor how extended producer responsibility frameworks and embodied carbon reporting obligations will reshape sourcing economics and competitive differentiation.
Market Dynamics
The UK's Timber Procurement Advisory Note and tightening FSC chain-of-custody documentation are compressing supplier eligibility windows, forcing rapid certification upgrades across domestic and imported material flows while urban millennials in London and Manchester demand traceable provenance as a baseline purchase condition.
Growth Catalysts
- Timber Procurement Policy enforcement:Public sector and commercial contract eligibility now hinges on verified sustainable sourcing, redirecting procurement budgets toward certified UK and EU suppliers.
- Post-consumer plastic conversion technologies:Advanced mechanical recycling processes enable furniture-grade outputs from domestic waste streams, reducing import dependency for synthetic inputs.
- London-Manchester-Bristol demand cluster:Concentrated first-time homeowner populations in these cities prioritize low-carbon furnishings, creating predictable order volumes for regional manufacturers.
Market Restraints
- FSC-certified timber supply concentration:Baltic and Scandinavian suppliers control premium certified hardwood flows, exposing UK manufacturers to Baltic geopolitical disruptions and shipping cost volatility.
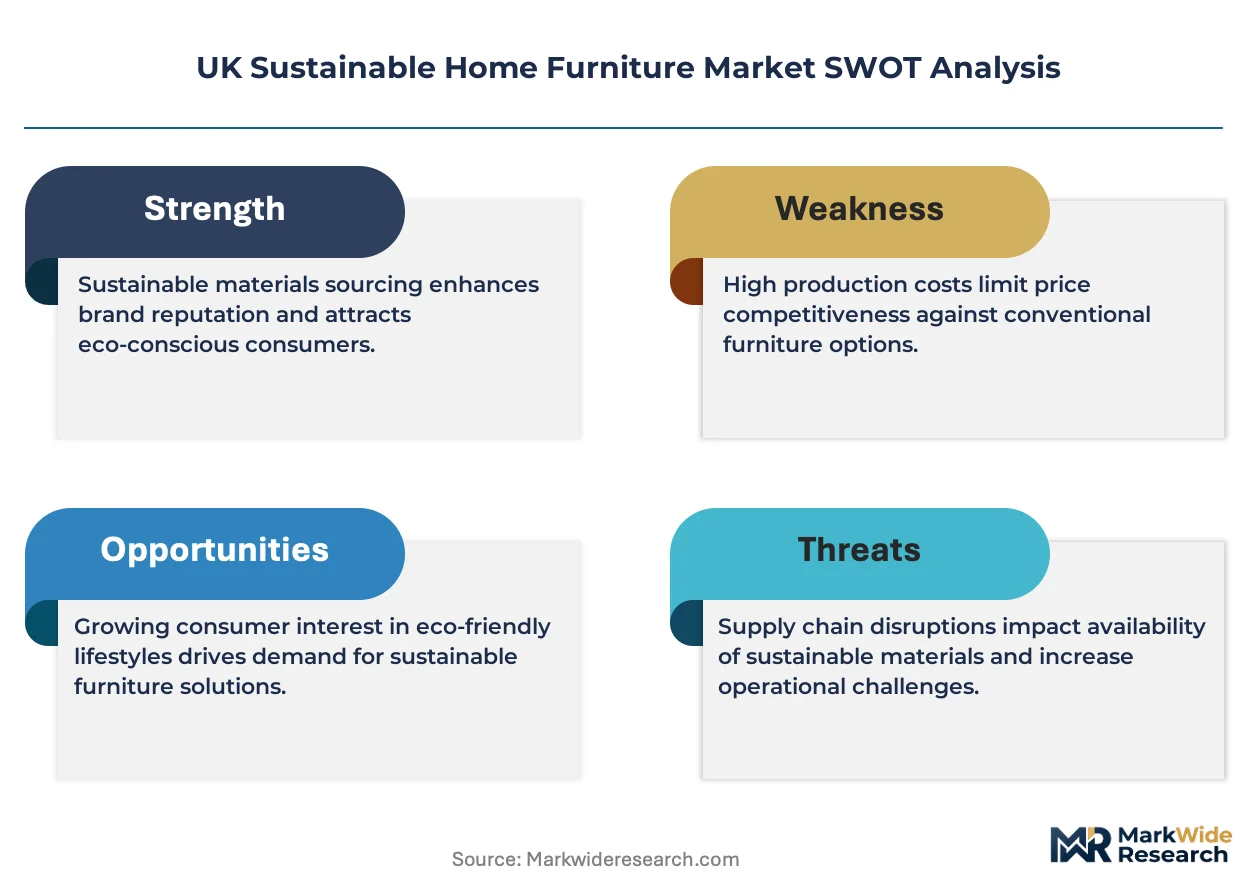
- Organic cotton upholstery cost structure:Certified organic fiber commands 40-60% premiums over conventional alternatives, compressing margin potential in mid-market sofa categories.
- Embodied carbon measurement technical limitation:Absence of standardized UK product-level carbon accounting protocols complicates marketing claims and invites greenwashing scrutiny.
Strategic Opportunities
- Subscription-based furniture refresh services:Circular-economy business models targeting urban millennials in Bristol and Manchester reduce customer acquisition costs while securing predictable residual value recovery.
- Hotel sector bulk procurement mandates:ESG-driven hospitality chains in London and Edinburgh are formalizing sustainable furniture procurement clauses, opening volume contract channels.
- Extended Producer Responsibility frameworks:Anticipated UK waste regulations will mandate end-of-life recovery obligations, rewarding early movers with established take-back infrastructure.
Industry Challenges
- FSC chain-of-custody certification timeline:Small and mid-sized manufacturers face 12-18 month documentation overhauls to meet evolving audit requirements, straining working capital.
- Water-based finish application skill gap:Traditional solvent-based finishing expertise dominates UK craft training programs, creating technician shortages for compliant production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Sustainable Home Furniture Market |
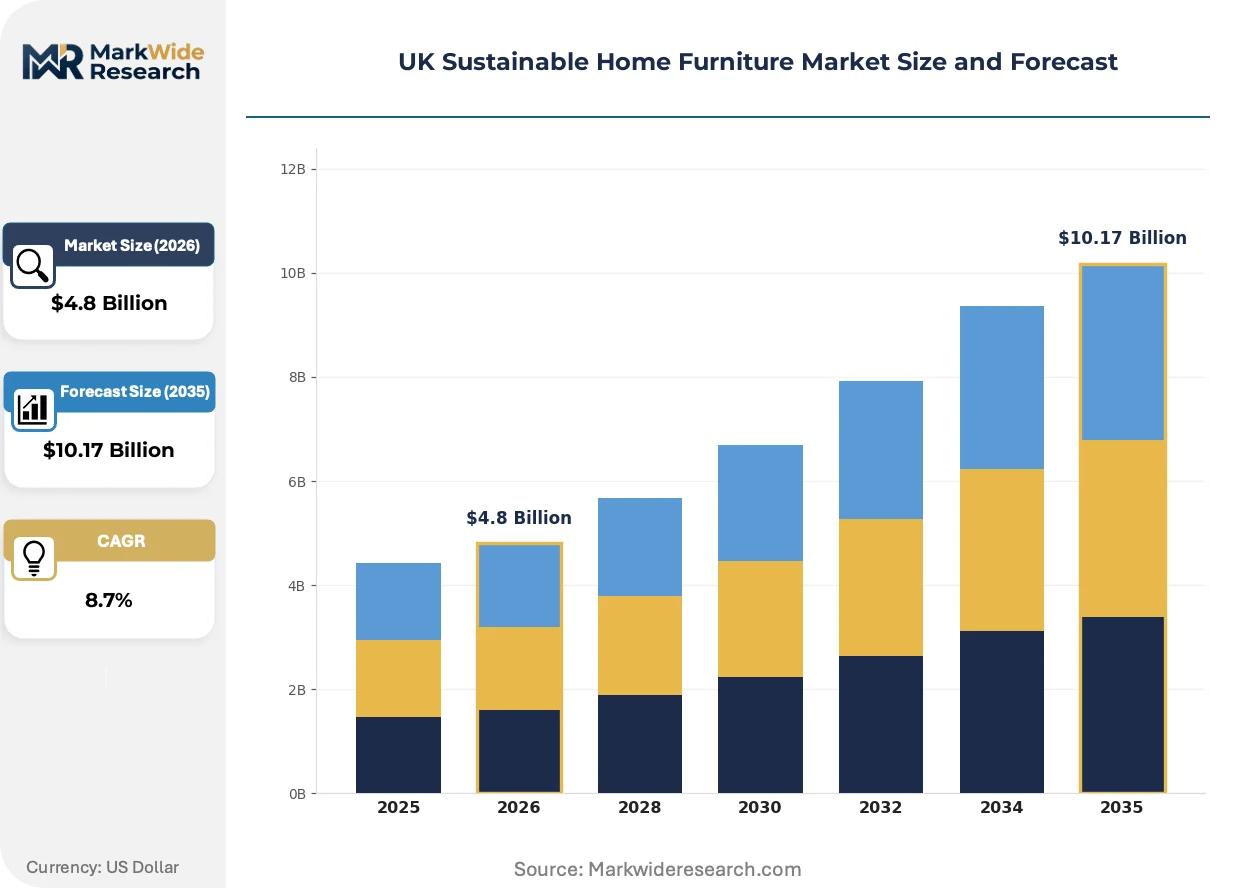
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Bamboo, Recycled Wood, Organic Cotton, Cork Product Type: Chairs, Tables, Storage Solutions, Sofas End User: Households, Offices, Educational Institutions, Hotels Design Style: Minimalistic, Rustic, Modern, Scandinavian |
| Companies Covered | Tomas & Jani, Sebastian Cox, Revive Innovations, Jott Studio, Fuzl, Timothy Oulton, Jan Hendzel, Konk, Graham & Green, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Sustainable Home Furniture Market Evolving Landscape
Digital product passports and blockchain-enabled provenance tracking are collapsing information asymmetries between manufacturers and end buyers, while regulatory pressure on embodied carbon disclosure accelerates material substitution experimentation across the value chain.
Blockchain-based chain-of-custody documentation is unifying previously fragmented supplier audit trails into single-source verification systems. Premium household buyers in London and Manchester now expect QR-accessible provenance data as standard. This compression of trust-building infrastructure is enabling smaller certified producers to compete directly with established heritage brands.
The UK Sustainability Disclosure Standards are mandating granular carbon footprint reporting across corporate value chains. Furniture manufacturers serving commercial and hospitality clients must now document Scope 3 emissions from forest extraction through final delivery. Mid-sized suppliers without in-house lifecycle assessment capability are outsourcing verification to specialized consultancies, adding cost but preserving contract eligibility.
Rental and resale platform integration is fragmenting traditional ownership models among urban millennials. Subscription services and peer-to-peer marketplaces in Bristol and Edinburgh are capturing younger demographics who prioritize access over possession. This behavioral pivot pressures manufacturers to design for durability modularity rather than obsolescence, with warranty and repair service offerings becoming competitive differentiators in direct-to-consumer channels.
UK Sustainable Home Furniture Market Segmentation
Segmentation in UK sustainable home furniture reveals how material certification, product durability, and end-use requirements shape procurement priorities. Understanding these divisions exposes where premium positioning commands price authority versus where standardization drives volume economics.
Material:
Replacement cycles vary dramatically across sustainable materials, with structural applications demanding longer upgrade intervals than surface finishes.
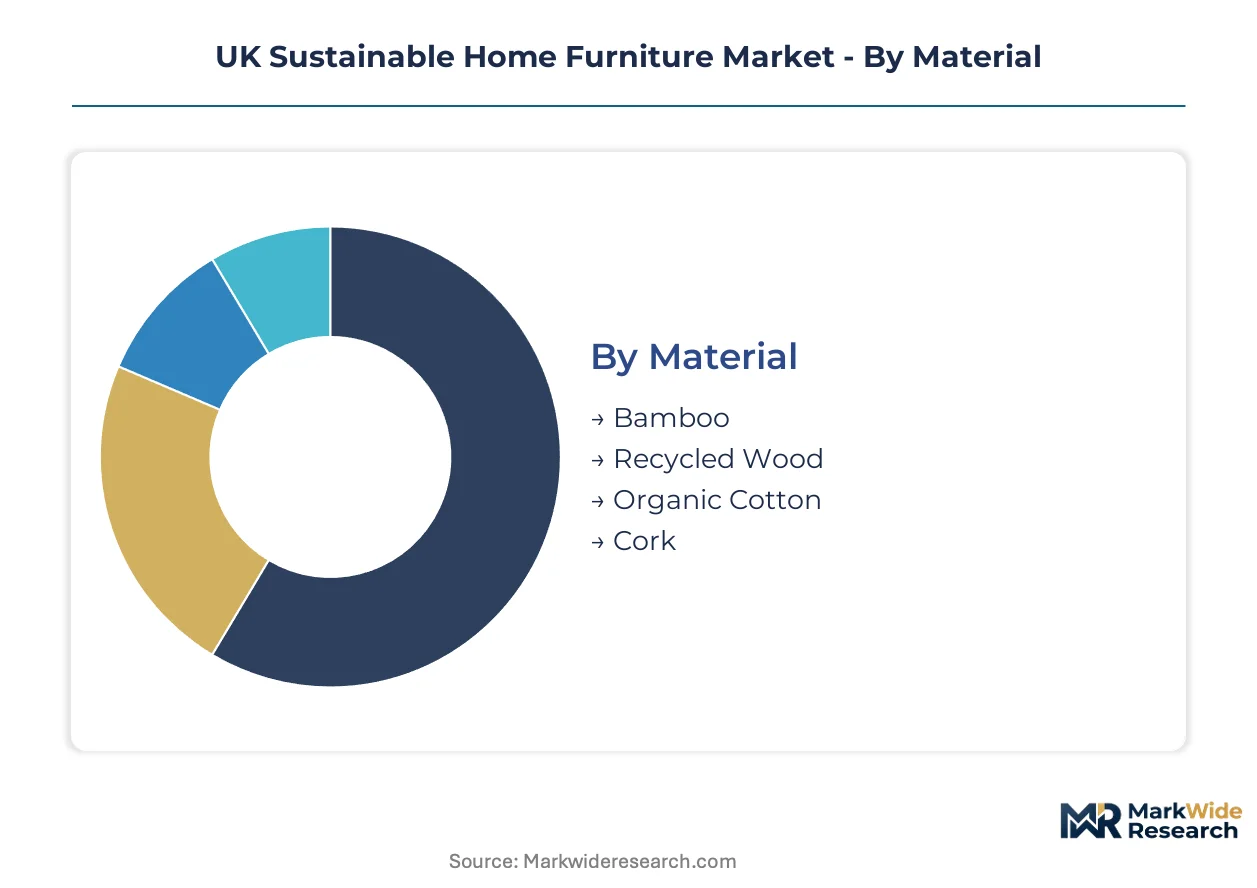
- Recycled Wood:Reclaimed timber with verified FSC chain-of-custody documentation anchors structural furniture production. Demand clusters in Manchester and Bristol among first-time homeowners prioritizing traceable provenance for dining tables and bed frames.
- Bamboo:Rapid-renewal grass species processed into dimensionally stable panels suits high-turnover rental furnishings. London flat-sharers favor bamboo shelving and occasional tables for lightweight modularity during frequent relocations.
- Organic Cotton:GOTS-certified fiber fills upholstery applications where skin contact sensitivity matters.
- Cork:Harvested Mediterranean bark provides acoustic-dampening surface treatments and sustainable flooring underlayment alternatives.
Volume placements concentrate in Recycled Wood; the faster expansion belongs to Bamboo.
Product Type:
Cost tier stratification separates investment-grade anchor pieces from discretionary refresh categories.
- Sofas:Three-seat and sectional configurations with certified timber frames and organic cotton upholstery command the highest per-unit margins. Bristol and Edinburgh households drive replacement demand as rental platforms normalize furniture-as-a-service subscriptions.
- Storage Solutions:Modular shelving and cabinet systems designed for disassembly and reconfiguration address urban space constraints. London millennials prioritize flat-pack certified options compatible with frequent residential moves.
- Tables:Dining and workspace surfaces emphasize reclaimed timber aesthetics for heritage positioning.
- Chairs:Seating spans dining, office, and accent categories with varying durability specifications.
Margin concentration sits with Sofas; Storage Solutions are climbing the fastest as rental mobility reshapes purchase calculus.
End User:
Application-specific durability standards and procurement approval workflows create distinct service requirements.
- Households:Individual purchasers in London, Manchester, and Bristol represent the established demand base, with Scandinavian design loyalty strongest among urban millennials. Certification visibility and QR-accessible provenance now function as baseline expectations rather than differentiators.
- Hotels:ESG-driven hospitality chains in London and Edinburgh are formalizing sustainable furniture procurement clauses with volume contract structures. Bulk replacement cycles align with refurbishment schedules, creating predictable order pipelines for certified manufacturers.
- Offices:Corporate workspace fit-outs increasingly specify low-embodied-carbon furnishings for net-zero building certifications.
- Educational Institutions:Universities and schools face public sector timber procurement compliance requirements with extended tender timelines.
Contract value concentrates in Households; Hotels are gaining share fastest as ESG mandates harden.
Design Style:
Customer type alignment determines whether aesthetic positioning supports premium pricing or mass-market accessibility.
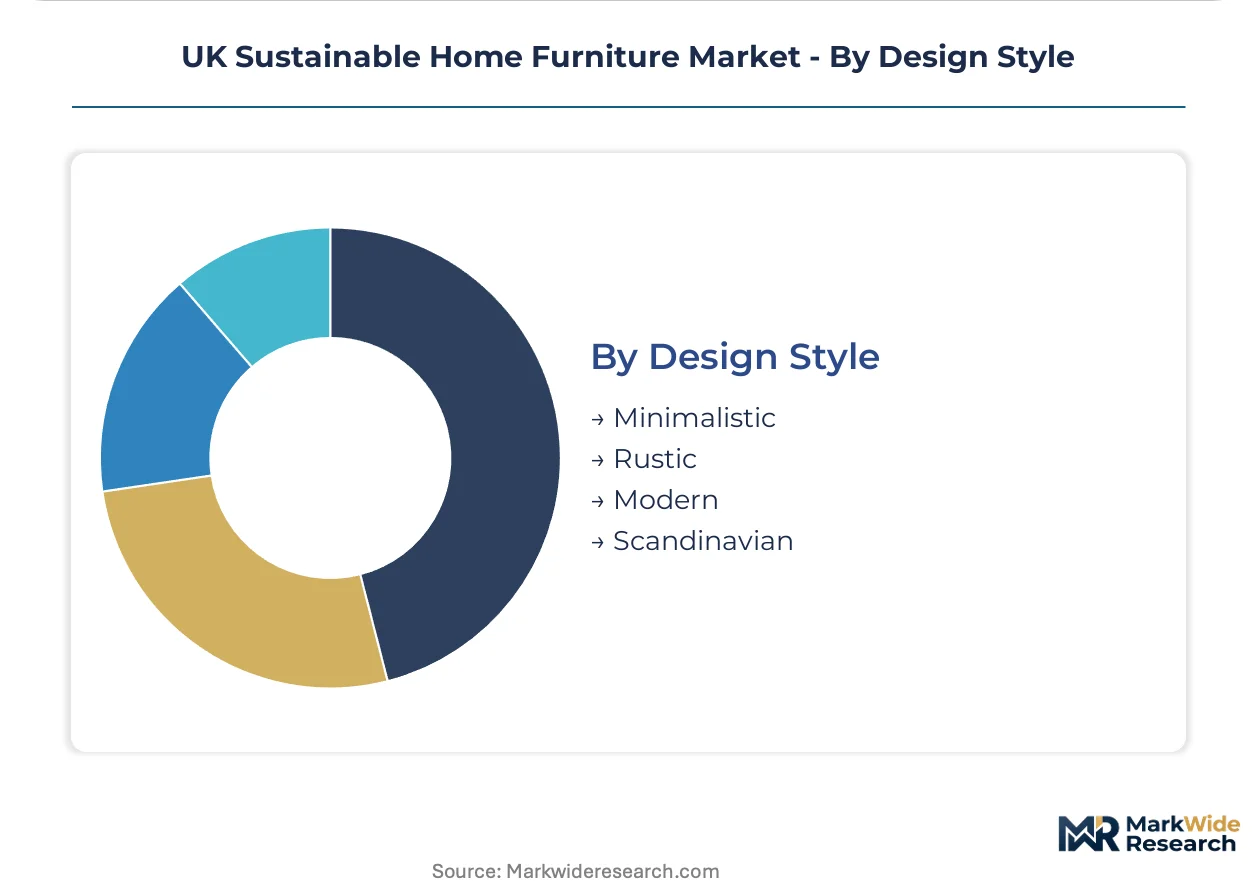
- Scandinavian:Clean lines, light oak tones, and functional minimalism command particular loyalty among London and Manchester first-time homeowners. This segment justifies 20-35% price premiums over comparable standard designs through heritage brand association and longevity signaling.
- Minimalistic:Stripped-back forms emphasizing material honesty and negative space appeal to sustainability-motivated purchasers seeking anti-consumption credibility. Bristol's creative sector workers favor this aesthetic for its alignment with circular economy values.
- Modern:Contemporary interpretations blending sustainable materials with current color palettes and hardware finishes.
- Rustic:Reclaimed timber emphasis with visible joinery and natural distressing targets rural and semi-rural secondary home markets.
Price authority concentrates in Scandinavian; Minimalistic is expanding most quickly among younger demographics rejecting overt consumption signals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UK production capacity concentrates in traditional furniture-making regions while consumption clusters in metropolitan rental markets. This geographic split shapes logistics networks and regional specialization patterns across the value chain.
London and Southeast
First-time homeowners and flat-sharers in Camden, Hackney, and Brixton drive demand for traceable, low-carbon furnishings. The Greater London Authority's procurement standards for sustainable materials influence supplier certification priorities. Shoreditch and Clerkenwell host emerging direct-to-consumer brands leveraging digital product passports for provenance verification.
Midlands
Historic furniture manufacturing centers in Nottinghamshire and Leicestershire retain craft expertise amid certification upgrade pressures. The UK Timber Procurement Advisory Note shapes contract eligibility for manufacturers serving public sector clients. Derby and Loughborough industrial estates concentrate mid-scale producers navigating FSC chain-of-custody documentation overhauls.
North England
Manchester's first-time buyer population prioritizes Scandinavian design aesthetics with verified environmental credentials. Local authority sustainability procurement policies in Greater Manchester redirect municipal budgets toward certified suppliers. Ancoats and Salford Quays regeneration zones attract furniture-as-a-service startups targeting rental mobility.
Scotland
Edinburgh's hospitality sector leads ESG-driven bulk procurement for hotel refurbishment cycles. The Scottish Government's circular economy strategy mandates extended producer responsibility pilot programs. Leith and Granton waterfront developments concentrate sustainable fit-out specialists serving commercial clients.
Southwest
Bristol's creative sector workers favor minimalistic design aligning with anti-consumption values. City council procurement frameworks prioritize local hardwood sourcing and low-embodied-carbon specifications. Stokes Croft and Bedminster neighborhoods support artisan producers leveraging traditional coppicing and reclaimed timber streams.
UK Sustainable Home Furniture Market Competitive Landscape
Top-tier vendors anchor heritage positioning with controlled retail presence, while mid-scale specialists compete through material innovation and circular-economy credentials. The vendor base spans artisan workshops, regional manufacturers, and digital-native direct-to-consumer brands. Three archetypes dominate: heritage craft houses with London flagship stores, post-consumer material converters occupying circular niches, and subscription-platform-integrated producers. Consolidation pressure is accelerating through certification cost barriers, while strategic partnerships with hospitality procurement channels reshape volume allocation.
Among heritage-positioned British fabricators, Sebastian Cox and Timothy Oulton exemplify craft-authentication strategies, while Revive Innovations occupies a distinct circular-economy position through post-consumer plastic conversion. These three represent contrasting competitive vectors—traditional hardwood sourcing, controlled retail heritage positioning, and industrial-scale material recovery—each capturing differentiated margin pools within tightening regulatory frameworks.
| Leading Market Players |
|---|
| Tomas & Jani |
| Sebastian Cox |
| Revive Innovations |
| Jott Studio |
| Fuzl |
| Timothy Oulton |
| Jan Hendzel |
| Konk |
| Graham & Green |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FSC-documented heritage timber and uncertified Baltic imports splits UK sustainable furniture into parallel pricing architectures, with premium Scandinavian-design sofas commanding substantial markups while commodity-grade storage solutions compete on landed cost from regional distribution hubs.
Pricing Analysis
Cost-down pressure on mid-market sofa manufacturers accelerates because organic cotton upholstery premiums compress margins against fixed-frame timber costs. Three-tier pricing structure across heritage-certified, standard-FSC, and economy-import levels differentiates primarily on chain-of-custody documentation depth and finish durability guarantees. Bristol-based rental platforms exhibit highest price sensitivity, demanding volume discounts for subscription-furniture refresh cycles, while London hospitality procurement shows lowest sensitivity, prioritizing ESG-compliant provenance over unit economics.
Supply Chain Analysis
Regional distribution centers in Derby and Loughborough anchor hub-and-spoke fulfillment patterns reaching Manchester and Bristol within 48-hour windows. Raw material flows draw from Baltic States certified hardwood, Mediterranean cork harvests, and domestic coppiced woodland through Sebastian Cox's Kentish supply partnerships. Single-source vulnerability concentrates in FSC-certified Baltic timber channels exposed to geopolitical disruption. Distribution runs through direct-to-consumer digital platforms for urban millennials, with traditional heritage showrooms retaining London-Manchester corridor premium buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled provenance verification is displacing paper-based chain-of-custody documentation as the baseline trust infrastructure, forcing incumbents and entrants alike to retool certification workflows around QR-accessible digital product passports.
For Market Incumbents: Extend FSC chain-of-custody certification depth into tier-two supplier networks before the UK Timber Procurement Advisory Note tightens audit requirements. Anchor heritage positioning through controlled London flagship presence while building captive coppicing partnerships in Kent and Sussex to defend against Baltic supply disruption. Subscription-platform integration represents the critical channel threat from digital-native competitors. For New Entrants and Emerging Players: Edinburgh hospitality procurement managers represent an underserved buyer archetype with formalized ESG mandates and predictable refurbishment cycles. Manchester flat-sharer mobility patterns create white-space for modular bamboo storage solutions designed for frequent relocation. Go-to-market traction demands direct partnerships with furniture-as-a-service platforms rather than traditional retail placement. For Investors and Strategic Acquirers: Re-rating potential sits with post-consumer material converters given anticipated Extended Producer Responsibility mandates and waste regulation enforcement. Mid-scale producers with established take-back infrastructure command scarcity premiums as compliance costs rise. Watch for UK Sustainability Disclosure Standards implementation pace as the inflection signal for carbon-accounting capability valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Product Passport Deployment | Blockchain-enabled provenance tracking satisfies London millennial demand for QR-accessible chain-of-custody verification. |
| Coppicing Partnership Development | Domestic hardwood sourcing through Kentish woodland management reduces Baltic timber dependency exposure. |
| Subscription Platform Integration | Furniture-as-a-service partnerships with Bristol and Manchester rental platforms capture residual value recovery. |
| Hospitality Procurement Certification | ESG-compliant bulk contracts with Edinburgh hotel chains open predictable volume replacement pipelines. |
| Water-Based Finish Capability Buildout | Technician training programs address solvent-to-water transition gaps in UK craft education infrastructure. |
Research Methodology
Independent corroboration across furniture manufacturer executives, FSC certification auditors, hospitality procurement directors, and rental platform operators underwrites the qualitative findings. Secondary validation draws from UK Timber Procurement Advisory Note documentation, Environment Agency waste regulation filings, BSI Kitemark standards archives, and trade flow records through HMRC customs data. Bottom-up production capacity assessments triangulate against top-down consumption estimates from regional household formation statistics.
Comparable-period anchoring to historical certification adoption curves and subscription-service penetration rates shaped the projection horizon. Segmentation modeling incorporates material certification tier, product durability specification, end-use application, and design style loyalty across the analysis window. CAGRs derive from fitted growth curves calibrated to urban millennial household formation in London, Manchester, and Bristol, with cross-reference to hospitality sector ESG procurement clause formalization timelines.
Revisions become necessary when UK Sustainability Disclosure Standards implementation accelerates, Extended Producer Responsibility frameworks harden, or Baltic geopolitical conditions disrupt certified timber flows. Forecasts reflect documented assumptions on certification cost trajectories and water-based finish adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Plastic Furniture Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
United Kingdom Furniture Market
Furniture
Italy Home Furniture Market
Furniture
Europe Wood Decorative Wall Panel Market
Furniture
Fireplace Mantels Market
Furniture
Saudi Arabia Home Furniture Market
Furniture
Rattan Furniture Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
GCC Furniture Market
Furniture
Italy Luxury Furniture Market
Furniture
Chair Hardware Market
Furniture
Bounding Table Market
Furniture
Europe Multifunctional Furniture Market
Furniture
School Furniture Market
Furniture
Children Furniture Market