
 Spain Endpoint Detection and Response Market | 2026-2036
Spain Endpoint Detection and Response Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Endpoint Detection and Response Market Insights
Managed detection revenue is tilting from on-premises appliance sales toward cloud-native subscription models. CrowdStrike leverages its Falcon platform architecture to anchor recurring revenue streams in Iberian banking clients. Palo Alto Networks competes through Cortex XDR integration with broader firewall portfolios, while Telefónica Tech sustains domestic advantage via sovereign cloud certifications and local data residency guarantees.
Endpoint Detection and Response denotes a cybersecurity technology category that continuously monitors endpoint devices—workstations, servers, mobile hardware—for anomalous behavior, employing behavioral analytics and threat intelligence feeds to identify fileless malware and lateral movement patterns missed by signature-based antivirus tools. Cloud-based solutions lead product type adoption as Spanish enterprises exit capital-intensive hardware refresh cycles, while managed services represent the fastest-expanding segment amid acute SOC staffing shortages. The BFSI vertical commands premium pricing due to regulatory audit frequency, though manufacturing is emerging as a volume growth corridor following operational technology convergence risks.
Spain's national cybersecurity strategy aligns with NIS2 transposition requirements enforced by the National Cryptologic Centre and the Spanish Data Protection Agency, mandating incident reporting timelines and supply chain security assessments that directly expand EDR procurement scope. The EU AI Act adds algorithmic transparency obligations for automated threat detection systems, compelling vendors to document decision logic for supervised machine learning models. Stakeholders must weigh sovereign cloud mandates against multi-tenant platform economics when selecting deployment architectures.
Market Dynamics
NIS2 transposition deadlines are compressing procurement cycles across Spanish financial services, forcing institutions to replace legacy antivirus stacks with behavioral monitoring platforms before enforcement begins in late 2024.
Growth Catalysts
- EU AI Act transparency mandates:Automated threat detection systems now require documented decision logic, expanding professional services attach rates for algorithmic auditing and model governance.
- Operational technology convergence:Manufacturing facilities in Catalonia and the Basque Country are deploying unified EDR-OT security platforms as industrial control systems face targeted ransomware campaigns.
- Cloud-native architecture migration:Spanish enterprises are exiting three-year hardware refresh cycles in favor of consumption-based security subscriptions that align spending with actual endpoint counts.
Market Restraints
- Sovereign cloud certification scarcity:Only three domestic providers currently hold National Cryptologic Centre accreditation for classified data processing, creating vendor concentration risk in Madrid and Barcelona.
- Specialized SOC analyst shortage:Spanish universities produce fewer than four hundred cybersecurity graduates annually against demand for over two thousand tier-one incident responders.
- Legacy endpoint agent conflicts:Coexistence of traditional antivirus and modern EDR sensors degrades workstation performance, slowing enterprise rollout timelines.
Strategic Opportunities
- Andalusian agricultural technology sector:Precision farming operations deploying IoT sensor networks remain underserved by endpoint security vendors focused on financial services.
- Managed detection and response bundling:Mid-market manufacturers in Valencia seek turnkey SOC-as-a-service offerings that eliminate internal staffing requirements entirely.
- EU Cyber Solidarity Act funding:Cross-border threat intelligence sharing infrastructure investments will subsidize national security operations center expansion in secondary Spanish cities.
Industry Challenges
- Multi-cloud agent standardization:Enterprises operating across AWS, Azure, and Telefónica sovereign zones struggle to maintain consistent detection policies without vendor-specific console fragmentation.
- Incident response retainer negotiation:Spanish buyers resist prepaying for breach containment services they may never invoke, compressing MDR provider margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Endpoint Detection and Response Market |
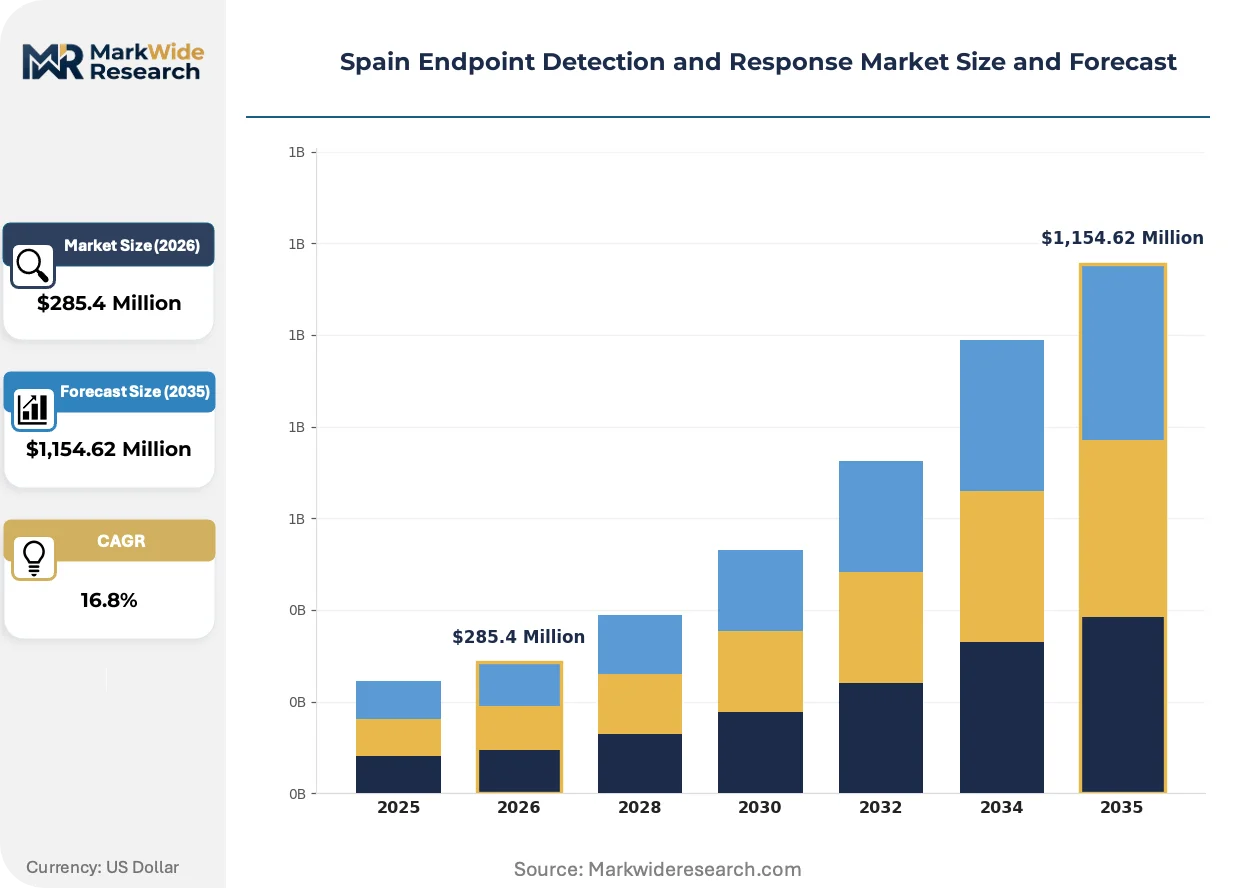
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,154.62 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based Solutions, On-premises Solutions, Hybrid Solutions, Managed Services Industry Vertical: Healthcare, BFSI, Manufacturing, Government Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-premises End User: SMBs, Large Enterprises, Educational Institutions, Cybersecurity Firms |
| Companies Covered | Entelgy Innotec, Cisco, Telefónica Tech, Fortinet, Palo Alto Networks, S21sec Thales, CrowdStrike, Check Point Software, Panda WatchGuard, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Endpoint Detection and Response Market Trends and Innovations
Behavioral analytics engines are displacing signature-dependent detection across Spanish enterprise endpoints, while regulatory pressure accelerates automation in security operations centers.
Extended detection and response platforms are digitizing telemetry correlation across endpoints, networks, and cloud workloads. Iberian banking groups are deploying these architectures fastest, with three of the five largest domestic institutions completing platform migrations during 2024. This convergence is digitizing security vendor competitive dynamics, compressing standalone EDR specialists into broader platform ecosystems.
Spain's National Cryptologic Centre has published binding technical security specifications for critical infrastructure operators, mandating centralized logging and twenty-four-hour incident notification windows. Industrial consequence includes mandatory procurement of managed SOC services for entities below internal staffing thresholds. Energy and transport verticals are responding with accelerated RFP processes, compressing traditional six-month sales cycles to under ninety days.
Subscription fatigue is altering how Spanish CISOs evaluate vendor relationships. Enterprises are consolidating from an average of seven separate security tools toward integrated platforms with unified agent architectures. Channel disruption favors direct vendor relationships over traditional value-added resellers in Madrid and Barcelona, where procurement teams possess sufficient technical depth to negotiate enterprise agreements without intermediary support.
Spain Endpoint Detection and Response Market Segmentation
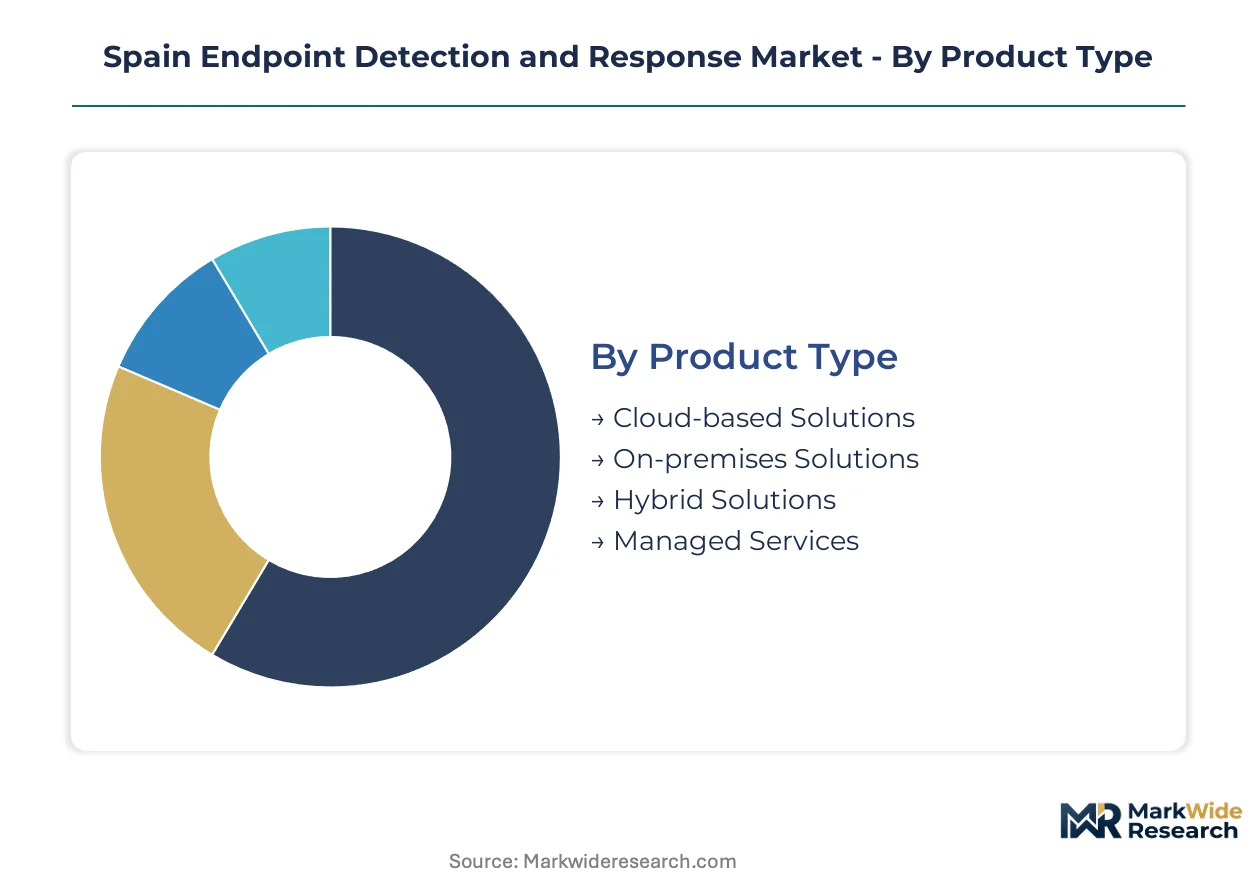
EDR procurement patterns in Spain diverge sharply across organizational scale and regulatory exposure, with cloud-native architectures displacing hardware-dependent deployments among cost-sensitive buyers. Segmentation reveals how NIS2 compliance deadlines and sovereign data mandates reshape vendor selection criteria across Madrid's financial core and peripheral industrial zones.
Product Type:
After-sales service intensity varies dramatically across product categories, with managed services demanding continuous SOC engagement while cloud solutions rely on automated patch cycles.
- Cloud-based Solutions:Multi-tenant platforms deliver behavioral analytics through browser-accessible consoles, eliminating local infrastructure maintenance. Spanish banks in Barcelona and Madrid dominate uptake as these institutions exit three-year hardware refresh obligations.
- Managed Services:Third-party SOC teams monitor endpoint telemetry and execute incident response under contractual SLAs. Acute staffing shortages at Spanish universities—producing fewer than four hundred cybersecurity graduates annually—force mid-market manufacturers toward turnkey detection bundles.
- On-premises Solutions:Appliance-based deployments persist among defense contractors and classified government facilities requiring air-gapped architectures.
- Hybrid Solutions:Split configurations process sensitive data locally while leveraging cloud analytics for non-critical workloads.
By volume, Cloud-based Solutions leads. By growth pace, Managed Services is ahead.
Industry Vertical:
Cost tier stratification separates premium-regulated sectors from price-sensitive operational technology environments.
- BFSI:Financial institutions face compressed procurement cycles as NIS2 enforcement tightens audit frequency and incident reporting windows. The National Cryptologic Centre mandates twenty-four-hour notification timelines that expand EDR scope beyond traditional antivirus perimeters.
- Manufacturing:Catalonian and Basque Country facilities deploy unified EDR-OT platforms as ransomware campaigns target industrial control systems. Operational technology convergence creates novel attack surfaces previously isolated from corporate networks.
- Healthcare:Hospital networks balance patient data sovereignty requirements against cloud scalability needs.
- Government:Central and regional administrations prioritize National Cryptologic Centre accreditation in vendor selection.
By volume, BFSI leads. By growth pace, Manufacturing is expanding most quickly.
Deployment Model:
Customer type determines architecture preference, with classified operators rejecting multi-tenancy while agile enterprises embrace consumption elasticity.
- Public Cloud:Shared infrastructure delivers per-endpoint pricing that aligns spending with actual device counts. Subscription fatigue among Spanish CISOs accelerates consolidation toward these consumption-based models.
- Private Cloud:Single-tenant environments satisfy data residency guarantees required by Telefónica Tech sovereign certifications. Only three domestic providers currently hold National Cryptologic Centre accreditation for classified processing.
- Hybrid Cloud:Workload-sensitive configurations split processing between sovereign and hyperscale zones.
- On-premises:Legacy air-gapped installations persist where network segmentation mandates physical isolation.
By volume, Public Cloud leads. By growth pace, Private Cloud is gaining share fastest.
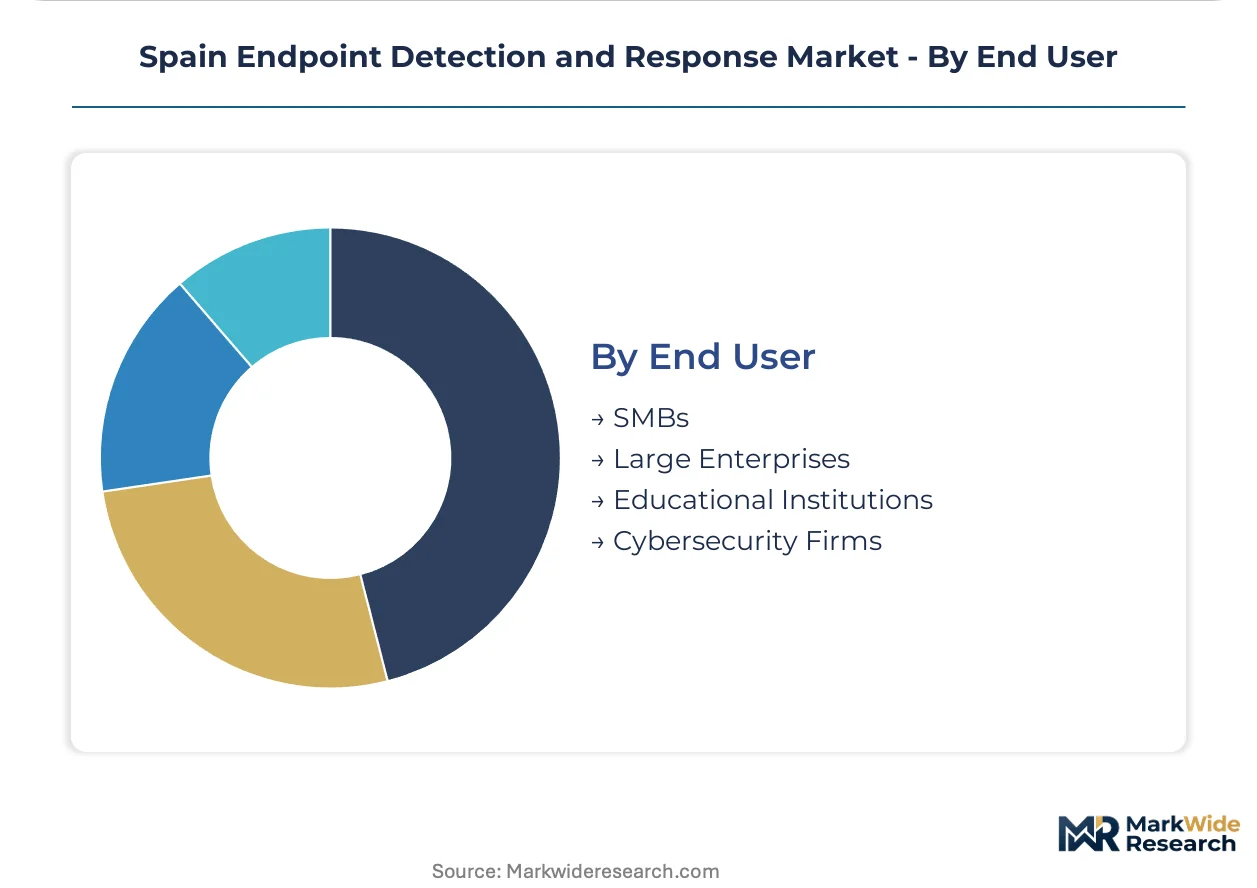
End User:
Organizational maturity shapes procurement sophistication, with enterprise security teams negotiating direct vendor relationships while smaller buyers rely on channel intermediaries.
- Large Enterprises:Internal SOC capabilities support complex multi-cloud agent standardization across AWS, Azure, and Telefónica sovereign zones. Technical depth in Madrid and Barcelona procurement teams enables enterprise agreement negotiation without reseller support.
- SMBs:Resource-constrained organizations in Valencia seek bundled SOC-as-a-service offerings that eliminate internal staffing requirements entirely. These buyers resist prepaying for breach containment services they may never invoke.
- Educational Institutions:University networks face endpoint proliferation from bring-your-own-device policies.
- Cybersecurity Firms:Specialized consultancies deploy EDR platforms as service delivery infrastructure for client engagements.
By volume, Large Enterprises leads. By growth pace, SMBs show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EDR consumption patterns across Spain diverge sharply between financial services hubs demanding sovereign cloud compliance and industrial regions prioritizing operational technology convergence over legacy IT security.
Madrid
Financial institutions and central government agencies concentrate procurement in the capital, driving demand for National Cryptologic Centre-certified private cloud deployments. The National Cryptologic Centre mandates twenty-four-hour incident notification timelines that compress vendor selection cycles. Telefónica Tech operates sovereign security operations centers serving banking clients with data residency guarantees.
Catalonia
Barcelona anchors Spain's second-largest EDR demand cluster, with pharmaceutical and technology firms adopting cloud-native platforms. The region's manufacturing base in surrounding industrial zones accelerates unified EDR-OT deployments as ransomware campaigns target production systems. Local providers compete through managed detection bundles for mid-market exporters.
Basque Country
Advanced manufacturing and energy infrastructure operators in Bilbao and San Sebastián prioritize industrial control system protection. EU NIS2 transposition requirements force critical infrastructure operators toward behavioral monitoring platforms before late 2024 enforcement. Machine-tool and automotive suppliers drive fastest growth in converged IT-OT security spending.
Andalusia
Agricultural technology and precision farming operations remain underserved by endpoint security vendors focused on financial services. Emerging IoT sensor networks across olive groves and greenhouse complexes create novel attack surfaces. Regional technology parks in Málaga and Seville attract cybersecurity startups targeting this vertical gap.
Valencia
Mid-market manufacturers seek turnkey SOC-as-a-service offerings that eliminate internal staffing requirements. The region's ceramics and automotive components sectors resist prepaying for breach containment services they may never invoke. Channel partners dominate distribution, though direct vendor relationships are gaining traction among larger exporters.
Spain Endpoint Detection and Response Market Competitive Landscape
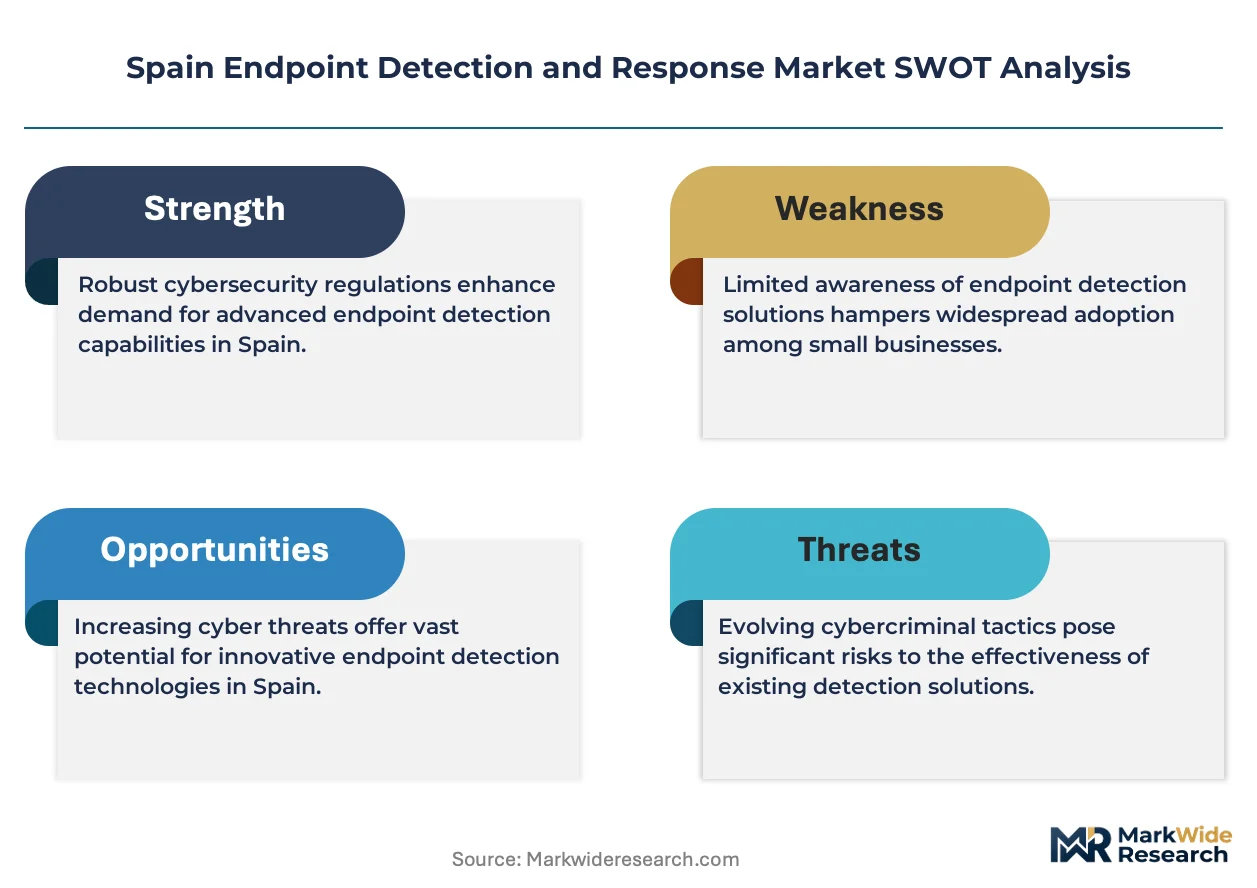
Capability concentration sits with specialized domestic providers holding sovereign certifications; scale advantage sits with international platform vendors deploying multi-tenant cloud architectures. The market structures around three tiers: global cybersecurity platforms with unified agent ecosystems, telecommunications carriers leveraging infrastructure ownership for managed services, and boutique consultancies targeting regulated verticals. Dominant competitive moves include strategic partnerships between cloud hyperscalers and local data residency providers, plus portfolio diversification into extended detection and response platforms.
Within the domestic specialist tier, Telefónica Tech and Entelgy Innotec exemplify providers competing through National Cryptologic Centre accreditation and sovereign cloud guarantees. Among international platform vendors, CrowdStrike occupies a position representing cloud-native architecture adoption in Iberian banking. These anchors illustrate how vendor selection criteria split between compliance-driven public sector procurement and agility-focused private enterprise adoption.
| Leading Market Players |
|---|
| Entelgy Innotec |
| Cisco |
| Telefónica Tech |
| Fortinet |
| Palo Alto Networks |
| S21sec Thales |
| CrowdStrike |
| Check Point Software |
| Panda WatchGuard |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on National Cryptologic Centre-certified sovereign cloud providers determines both pricing tier spreads and supply chain shape in Spain's EDR market. Only three domestic vendors hold this accreditation, compressing procurement options for financial institutions and defense contractors while pushing mid-market buyers toward uncertified alternatives.
Pricing Analysis
Subscription-based SaaS contracts dominate, with annual recurring revenue models displacing perpetual licenses across Spanish enterprises. Price differentiation rests on sovereign certification tier and managed SOC service bundling, with NIS2-compliant deployments commanding premiums over standard cloud offerings. Cost compression in the mid-market intensifies as Valencia manufacturers resist prepaying for breach containment services they rarely invoke. SMBs exhibit highest price sensitivity, while Madrid banking groups accept premium pricing for data residency guarantees.
Supply Chain Analysis
Extended payment terms from Spanish channel partners strain vendor cash conversion cycles, particularly for international platform providers without local balance sheet presence. Software development concentrates in the United States, Israel, and Ireland, with threat intelligence feeds drawing from Israeli military unit alumni networks and US-based research consortiums. Single-source vulnerability runs through hyperscale cloud infrastructure dependencies for multi-tenant platforms. Distribution runs through Madrid-based value-added resellers and direct enterprise agreements in Barcelona.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Madrid financial institutions consolidating vendor relationships from seven separate tools toward unified platforms, compressing margins for standalone specialists.
For Market Incumbents: Insulate recurring revenue streams by deepening integration with Telefónica Tech sovereign cloud infrastructure and accelerating XDR platform migrations ahead of NIS2 enforcement. CrowdStrike's Falcon architecture and Palo Alto Networks' Cortex ecosystem demonstrate how unified agent consolidation displaces point solutions. Certification investment in National Cryptologic Centre accreditation represents the critical defensive lever against unbundling. For New Entrants and Emerging Players: Pursue the Andalusian precision farming vertical where IoT sensor networks remain entirely unserved by endpoint security vendors fixated on financial services. Málaga technology parks offer low-cost development presence adjacent to this agricultural technology gap. A channel partnership with regional agricultural cooperatives provides the most penetrable go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-scale vendors with managed service attach capabilities over standalone EDR specialists. Five-to-ten year viability hinges on XDR convergence and sovereign cloud certification moats. Acquisition targets should demonstrate National Cryptologic Centre accreditation progress or established Telefónica Tech partnership frameworks. The signal to watch is mid-market manufacturer RFP volume for bundled SOC-as-a-service offerings.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | National Cryptologic Centre accreditation unlocks Madrid banking and defense procurement pipelines. |
| XDR Platform Integration | Telemetry correlation across endpoints, networks, and cloud workloads compresses standalone EDR margins. |
| Managed SOC Service Bundling | Turnkey detection offerings eliminate staffing requirements for Valencia mid-market manufacturers. |
| Industrial OT Convergence | Unified EDR-OT platforms address ransomware targeting Basque Country machine-tool and automotive suppliers. |
| Channel Partnership Restructuring | Direct vendor relationships gain share in Madrid and Barcelona as procurement technical depth increases. |
Research Methodology
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings in this study. Primary fieldwork encompassed CISOs at Madrid financial institutions, Barcelona pharmaceutical technology directors, procurement leads at Valencia manufacturing exporters, and channel partners distributing security platforms across Iberian markets. Secondary sources included National Cryptologic Centre technical specifications, Spanish Data Protection Agency enforcement records, EU NIS2 transposition documentation, and hyperscaler cloud infrastructure disclosures. Bottom-up endpoint count modeling and top-down security spending allocation triangulated market sizing.
Calibration against historical deployment trajectories in comparable EU markets refined the analytical framework across the projection horizon. Segmentation dimensions encompassed product architecture, industry vertical regulatory exposure, deployment sovereignty tier, and organizational scale. CAGRs derived from endpoint proliferation rates, compliance deadline compression effects, and substitution elasticities between on-premises and cloud-native solutions. Threat intelligence feed quality and SOC analyst labor market constraints served as industry-specific forecast inputs.
Sensitivities concentrate around NIS2 enforcement timing, National Cryptologic Centre certification queue durations, and hyperscale cloud pricing volatility. Forecasts reflect documented assumptions regarding regulatory compliance behavior and vendor consolidation patterns. Macroeconomic contraction compressing Spanish enterprise IT budgets, accelerated EU AI Act transparency mandates, or sovereign cloud provider insolvency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Password Management Software Market
Security Software
Asia Pacific Anti Money Laundering Solutions Market
Security Software
Asia-Pacific Extended Detection and Response Market
Security Software
North America Video Management System Market
Security Software
Smartphone Security Market
Security Software
Europe IP Video Intercom Device and Equipment Market
Security Software
Global Background Screening Market
Security Software
Global Visitor Management System Market
Security Software
Digital Risk Protection Platform Market
Security Software
Data Masking Technology Market
Security Software
Global Network Security Software Market
Security Software
DNS Protection Software Market
Security Software
SSL Inspection Solution Market
Security Software
DC and PKI Market
Security Software
US Hardware Encryption Market
Security Software
Anomaly Detection Tools Market