
 Global Password Management Software Market | 2026-2036
Global Password Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Password Management Software Market Foresight
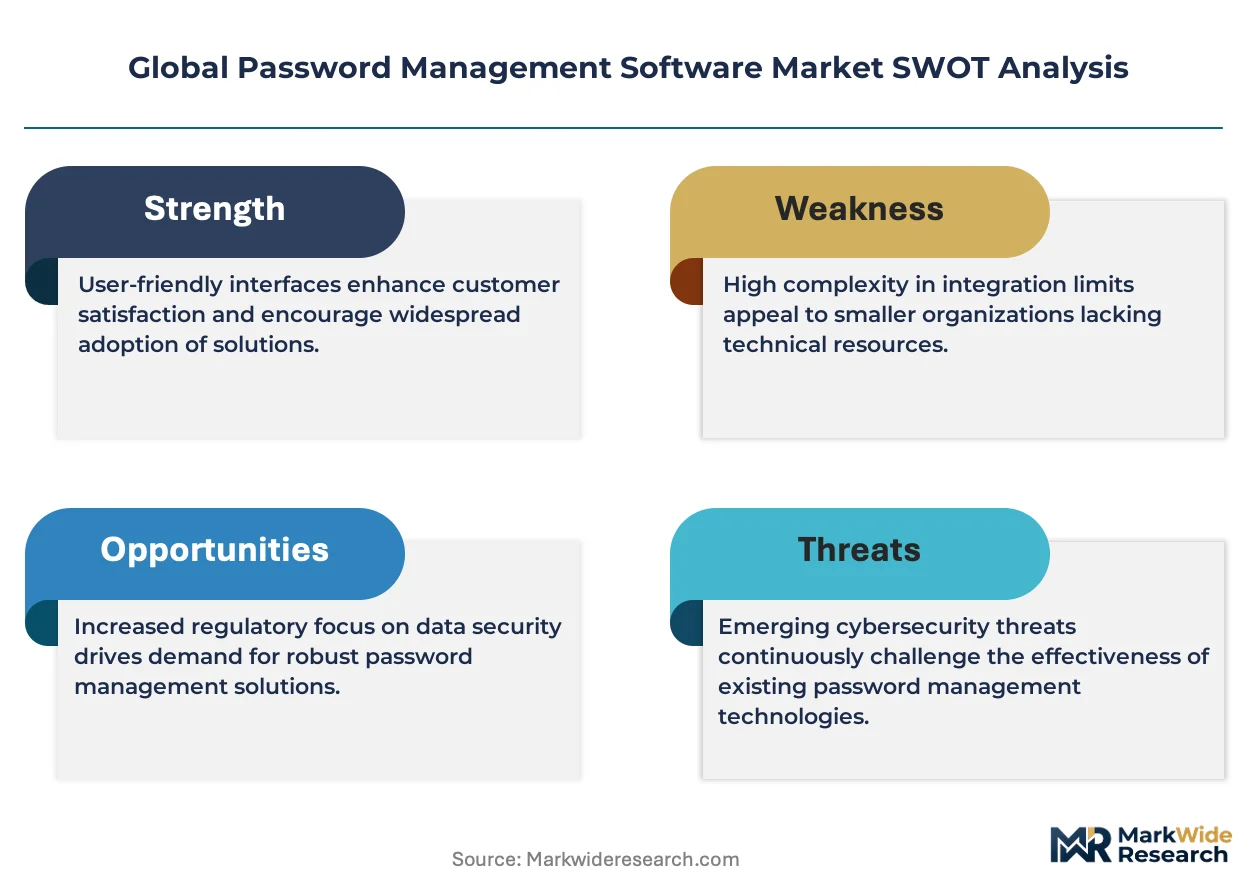
GDPR enforcement is recalibrating the cost-of-entry calculus for password management vendors seeking European market access. CyberArk dominates the privileged access segment with deep enterprise integrations. 1Password leverages consumer-to-business migration pathways. Bitwarden sustains open-source credibility that anchors developer community loyalty.
Password management software comprises credential storage, generation, and authentication orchestration systems that encrypt user secrets using AES-256 or comparable algorithms and automate secure access to enterprise applications and cloud services. The primary commercial purpose is reducing credential-related breach surfaces while enforcing policy compliance across distributed workforces. Cloud-based deployment leads the architecture mix as organizations abandon on-premises identity stacks for SaaS delivery models. Multi-factor authentication integration represents the fastest-expanding feature layer, with biometric methods capturing premium margin pools as hardware security key adoption accelerates among regulated industries.
The US Federal Trade Commission, the European Union's NIS2 framework, and Japan's METI cybersecurity guidelines collectively shape product standards by mandating breach disclosure timelines and encryption baselines. HIPAA in the United States and the EU AI Act's risk classification system further segment compliance requirements for healthcare and AI-adjacent credential systems. Stakeholders must monitor regulatory divergence between jurisdictions as fragmentation in breach notification rules directly impacts vendor certification costs and go-to-market sequencing.
Market Dynamics
Enterprise migration from on-premises identity stacks to SaaS delivery models is compressing deployment cycles and forcing incumbent vendors to rearchitect encryption key custody models around zero-trust principles.
Growth Catalysts
- NIS2 Directive:The EU's expanded cybersecurity framework mandates privileged access controls for critical infrastructure operators, creating compliance-driven procurement pipelines across member states.
- Healthcare digitization:HIPAA-covered entities in the United States face intensified OCR audit scrutiny, accelerating credential vault deployments to satisfy encryption and access logging requirements.
- Biometric hardware keys:FIDO2-compatible security tokens are displacing SMS-based second factors in regulated industries, expanding addressable margins for integrated authentication platforms.
Market Restraints
- Cloud concentration risk:AWS, Azure, and Google Cloud host the majority of password management SaaS infrastructure, creating single-point-of-failure exposure for vendor operations.
- Master password vulnerability:Human-chosen primary credentials remain technically unverifiable for entropy, limiting absolute security guarantees regardless of vault encryption strength.
- GDPR certification friction:Cross-border data transfer mechanisms require EU-based encryption key residency, adding operational overhead for vendors with centralized US infrastructure.
Strategic Opportunities
- India's digital public infrastructure:The country's expanding stack of citizen-facing services lacks mature privileged access tooling, presenting first-mover advantages for localized vault deployments.
- AI Act risk classification:High-risk AI systems under EU regulation require auditable credential chains, creating specialized demand for compliance-integrated password orchestration.
- Passwordless convergence:Passkey standards from FIDO Alliance and device-bound biometrics are merging with traditional vault architectures, enabling hybrid product positioning.
Industry Challenges
- Post-quantum cryptography transition:NIST's finalized encryption standards demand algorithmic retooling across installed bases, straining engineering bandwidth and backward compatibility assurances.
- Legacy directory integration:Active Directory and LDAP environments in established enterprises resist seamless cloud-native identity bridging, extending sales cycles and implementation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Password Management Software Market |
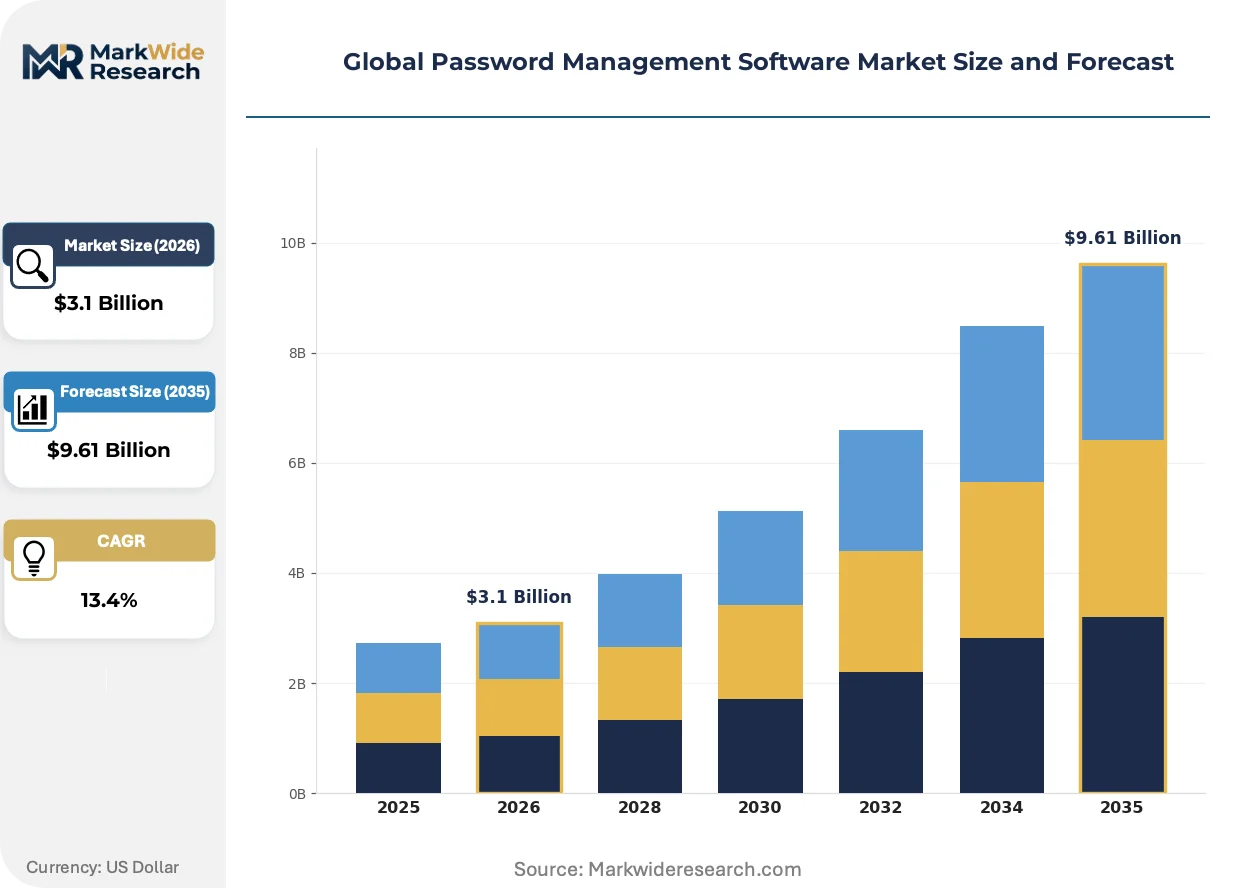
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $9.61 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Small Businesses, Enterprises, Government, Individuals Authentication Type: Single-Factor, Two-Factor, Multi-Factor, Biometric Features: Password Vault, Auto-Fill, Audit Logs, Security Reports |
| Companies Covered | 1Password, LastPass, Bitwarden, Keeper Security, Dashlane, NordPass, Zoho Vault, SailPoint Technologies, CyberArk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Password Management Software Market Shifts & Advancements
Edge-distributed encryption and policy enforcement are displacing centralized vault architectures as organizations confront latency constraints and data sovereignty requirements across multinational footprints.
Passkey credential systems are decentralizing authentication authority from server-side vaults to device-bound cryptographic key pairs. Financial services institutions in Singapore and Germany are piloting enterprise passkey provisioning at scale. This architecture is decentralizing liability models while compressing vendor control over the authentication lifecycle.
The EU AI Act's risk-tiered compliance obligations are forcing credential system vendors to implement auditable access trails for high-risk automated decision-making systems. Healthcare and credit-scoring applications face the strictest documentation requirements. Vendors are responding with specialized compliance modules that pre-map credential events to regulatory reporting formats.
Buyer procurement patterns are fragmenting as departmental shadow IT purchases bypass centralized security procurement. Line-of-business units in technology and professional services sectors now directly subscribe to team-tier password tools. This disintermediation is most pronounced in the United States, where credit-card-at-sign-up friction remains lowest and compliance integration demands are less uniform across state jurisdictions.
Global Password Management Software Market Segmentation
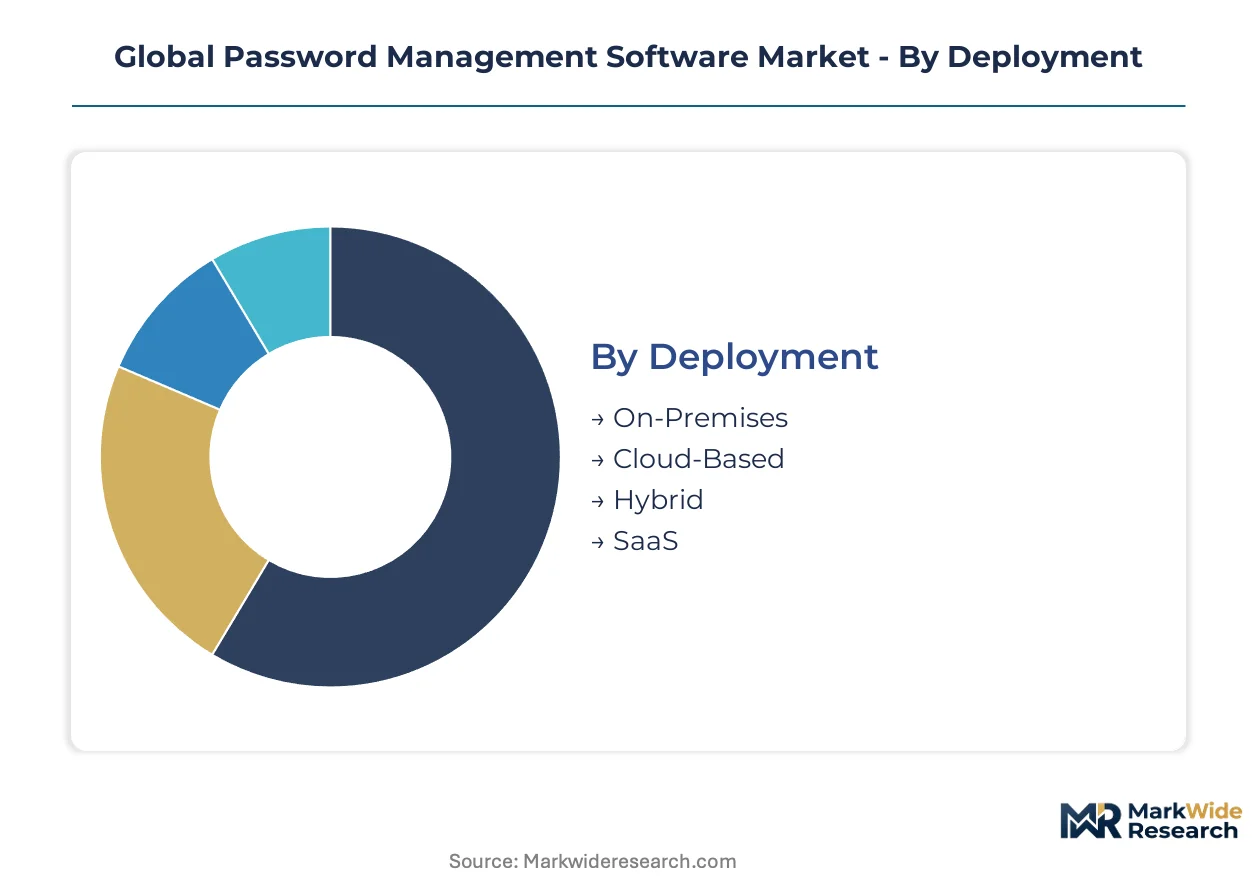
Deployment architecture determines encryption key custody models and compliance boundaries for password management vendors. End-user scale dictates feature complexity and pricing tiers across the market.
Deployment:
Cloud-based and SaaS deployments demand continuous infrastructure investment in multi-region redundancy and encryption key management services.
- Cloud-Based:Vendor-managed infrastructure hosts encrypted credential vaults across distributed data centers. Financial services firms in Singapore and Germany are migrating core identity stacks to cloud-native vaults to satisfy latency requirements for trading platforms and real-time payment systems.
- SaaS:Subscription delivery eliminates local server maintenance while embedding automatic security updates. United States healthcare providers under HIPAA pressure favor SaaS deployments for audit-ready access logging without on-premises hardware refresh cycles.
- On-Premises:Self-hosted vaults retain encryption keys within organizational firewalls for air-gapped environments.
- Hybrid:Split architectures synchronize on-premises legacy directories with cloud-based authentication services.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in SaaS as regulated industries abandon hardware ownership models.
End User:
Enterprise and government segments command premium pricing through mandatory compliance integrations and dedicated support tiers.
- Enterprises:Multi-tenant vault architectures serve thousands of employees with role-based access policies and SIEM integration. German automotive manufacturers and Japanese electronics conglomerates are consolidating fragmented departmental password tools into centralized enterprise platforms to satisfy NIS2 and METI cybersecurity guidelines.
- Government:Classified deployment options with sovereign encryption key residency address national security requirements. Defense contractors in the United States and critical infrastructure operators across EU member states are procuring government-certified vaults with FIPS 140-2 validated modules.
- Small Businesses:Team-tier subscriptions with simplified administration consoles dominate this price-sensitive category.
- Individuals:Freemium personal vaults with cross-device synchronization anchor consumer market entry points.
Enterprises absorb the majority of vendor engineering resources. Government procurement pipelines are expanding most quickly under mandatory critical infrastructure protection laws.
Authentication Type:
Biometric and multi-factor methods require hardware integration investments that differentiate premium product tiers.
- Multi-Factor:Time-based one-time passwords and push notifications layer atop primary credentials for high-risk access scenarios. United States financial institutions and EU payment service providers are mandating multi-factor authentication for customer-facing applications under PSD2 and state-level data protection laws.
- Biometric:Fingerprint and facial recognition templates stored in secure enclaves displace memorized passwords. Healthcare systems in Japan and professional services firms in Germany are deploying biometric vault access to eliminate password fatigue among clinical and consulting workforces.
- Two-Factor:SMS and email backup codes persist as minimum compliance baselines for regulated industries.
- Single-Factor:Master password-only access concentrates in consumer and legacy enterprise segments with limited security budgets.
Multi-factor authentication dominates current implementations. Biometric methods are climbing the fastest as FIDO2 hardware token prices decline and enterprise procurement standards tighten.
Features:
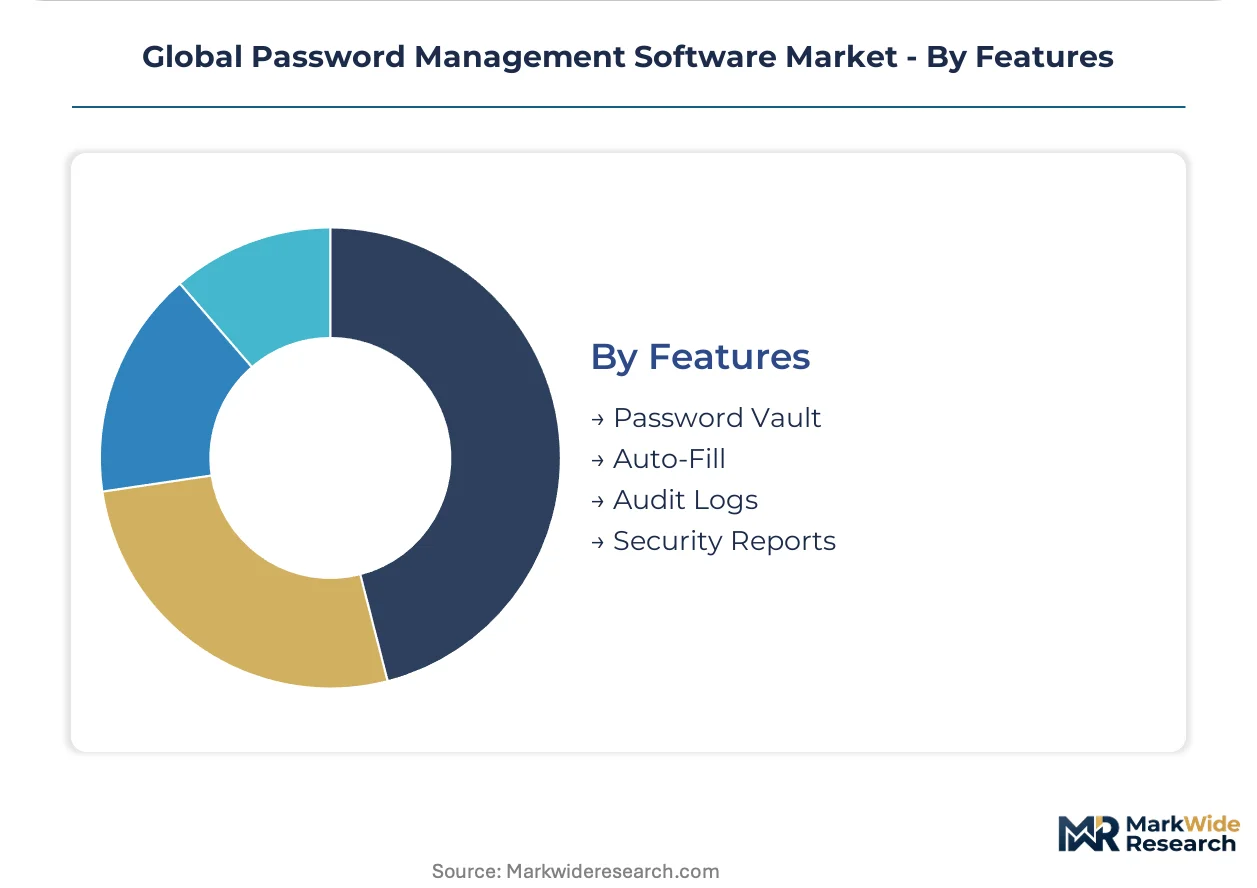
Audit logging and security reporting modules carry the highest development overhead due to regulatory reporting format requirements.
- Audit Logs:Immutable timestamped records of credential access and administrative changes satisfy compliance documentation mandates. HIPAA-covered entities in the United States and AI system operators under EU AI Act risk classification rules require auditable credential chains for automated decision-making oversight.
- Security Reports:Automated vulnerability assessments flag reused, weak, or breached passwords across organizational vaults. Managed security service providers in Germany and internal IT departments in Japan are integrating these reports into quarterly risk committee presentations.
- Password Vault:Core encrypted storage with AES-256 or ChaCha20-Poly1305 algorithms underpins all product tiers.
- Auto-Fill:Browser and mobile application integration reduces credential phishing exposure through domain validation.
Password Vault functionality anchors every deployment. Audit Logs are gaining share fastest as breach disclosure timelines compress under NIS2 and state-level notification laws.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled cybersecurity workforces cluster in metropolitan technology corridors across the United States, Germany, and Japan, anchoring regional demand concentration for privileged access management solutions.
United States
Enterprise IT departments and defense contractors drive procurement volume. HIPAA enforcement by OCR and FTC breach disclosure mandates compress deployment timelines. The Washington DC-Baltimore corridor hosts federal cybersecurity agencies and defense integrators migrating to zero-trust architectures.
Germany
Automotive manufacturers and industrial conglomerates consolidate fragmented password tools. NIS2 Directive implementation by federal cybersecurity authorities mandates privileged access controls for critical infrastructure. Stuttgart and Munich anchor automotive supplier networks deploying centralized vault platforms.
Japan
Electronics conglomerates and healthcare systems expand credential vault deployments. METI cybersecurity guidelines enforce encryption baselines for industrial control systems. Tokyo and Osaka metropolitan areas concentrate enterprise security operations centers upgrading legacy directory integrations.
Singapore
Financial services institutions pilot enterprise passkey provisioning at scale. Monetary Authority of Singapore operational risk frameworks mandate multi-factor authentication for payment infrastructure. The central business district hosts trading platforms migrating core identity stacks to cloud-native vaults.
India
Technology services firms and digital public infrastructure operators lack mature privileged access tooling. RBI cybersecurity guidelines enforce access logging for payment system operators. Bangalore and Hyderabad technology corridors anchor developer communities adopting open-source vault architectures.
Global Password Management Software Market Competitive Landscape
The competitive structure tilts toward specialized cybersecurity vendors with deep enterprise integrations. Market concentration remains moderate as incumbent identity providers compete with pure-play password management specialists. Three archetypes dominate: privileged access specialists with government certifications, consumer-origin platforms executing B2B migration, and open-source-anchored developers sustaining community loyalty. Dominant competitive moves include strategic partnerships with cloud infrastructure providers and portfolio diversification into adjacent identity governance segments.
Within the privileged access specialist tier, CyberArk represents deep enterprise integration capabilities. Among consumer-origin platforms executing B2B expansion, 1Password occupies a position bridging individual and team-tier deployments. Bitwarden exemplifies open-source credibility anchoring developer community loyalty. These three archetypes collectively illustrate the market's strategic segmentation across compliance-heavy enterprise procurement, user-experience-driven team adoption, and transparency-focused technical buyer segments.
| Leading Market Players |
|---|
| 1Password |
| LastPass |
| Bitwarden |
| Keeper Security |
| Dashlane |
| NordPass |
| Zoho Vault |
| SailPoint Technologies |
| CyberArk |
| Others |
Supply & Pricing Matrix
Cloud infrastructure spot pricing indices from AWS, Azure, and Google Cloud cascade through password management vendor cost structures, compressing margins on economy-tier SaaS subscriptions while enabling premium biometric-integrated tiers to sustain wider spreads through hardware security key bundling.
Pricing Analysis
Bundle-unbundle dynamics split sharply between standalone vault subscriptions and authentication-platform suites. Three-tier pricing structure across premium, standard, and economy levels anchors the market, with FIDO2 hardware key certification grade and enterprise SIEM integration depth driving price differentiation. Cost compression in team-tier SaaS is intensifying because hyperscaler infrastructure costs are passed through to price-sensitive small business buyers. Individual freemium users exhibit highest price sensitivity; government-certified deployments with FIPS 140-2 validation show lowest.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Singapore anchor hub-and-spoke delivery patterns for hardware security tokens and biometric sensors. Component sourcing draws from Taiwan for secure enclave chips, South Korea for FIDO2 token manufacturing, and China for packaging materials. Single-source vulnerability concentrates in AWS us-east-1 and eu-west-1 regions hosting primary vault infrastructure. Distribution runs through direct enterprise sales teams for large accounts and self-service web portals for team-tier subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Password management software constitutes a late-cycle quality story as enterprise procurement shifts toward zero-trust architectures demanding premium compliance-integrated vault platforms with auditable credential chains.
For Market Incumbents: Deploy sovereign encryption key residency as the anchor lever. Establish EU-based data centers to satisfy GDPR cross-border transfer requirements and preempt NIS2 audit failures. Acquire specialized biometric authentication startups to close capability gaps against FIDO2-native competitors. Consolidate fragmented departmental shadow IT deployments through centralized enterprise licensing to counter line-of-business disintermediation. For New Entrants and Emerging Players: Managed security service providers represent the most accessible channel partner type for bypassing entrenched procurement relationships. Target India's digital public infrastructure operators lacking mature privileged access tooling. Pursue healthcare AI system operators under EU AI Act high-risk classification requiring auditable credential documentation. Lead with open-source transparency to anchor developer community loyalty before upselling enterprise support tiers. For Investors and Strategic Acquirers: Asymmetric upside sits with consumer-origin platforms executing B2B migration with existing brand recognition and self-serve distribution infrastructure. Five-to-ten-year viability hinges on passkey standard adoption velocity and post-quantum cryptography transition execution. Monitor FIDO Alliance specification releases as the critical inflection signal for authentication architecture displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Migration | NIST algorithmic standards demand engineering retooling across installed vault bases to maintain encryption integrity. |
| Sovereign Key Residency Expansion | EU-based data center deployments satisfy GDPR certification friction and NIS2 compliance mandates for critical infrastructure operators. |
| Passkey Platform Integration | FIDO2 device-bound credentials displace server-side vault architectures in financial services pilots across Singapore and Germany. |
| Healthcare Compliance Module Development | HIPAA audit-ready access logging and EU AI Act risk-tiered reporting formats capture regulated healthcare procurement pipelines. |
| Managed Security Service Partnership | Channel alliances with MSSPs in Germany and Japan extend reach into mid-market enterprises lacking internal security operations centers. |
Research Methodology
Direct dialogue with chief information security officers, identity and access management architects, healthcare compliance officers, and managed security service provider executives grounded qualitative insights. Secondary validation drew from SEC 10-K filings of publicly traded cybersecurity vendors, NIST post-quantum cryptography standard publications, EU NIS2 implementation guidance documents, and hyperscaler infrastructure capex disclosures. Bottom-up deployment modeling across end-user segments triangulated against top-down market sizing from regulatory compliance mandate timelines.
Segmentation outputs across deployment architecture, organization scale, authentication type, and vertical industry classification fed into the projection framework. CAGRs were derived from compliance-driven procurement pipeline analysis and cloud migration velocity indicators specific to privileged access management adoption curves. FIDO2 hardware token price decline trajectories and biometric sensor cost curves informed authentication-type shift assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to post-quantum cryptography standard finalization timelines and passkey protocol fragmentation risks across device manufacturers. Outputs reflect documented assumptions regarding regulatory enforcement intensity and enterprise cloud migration completion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Anti-Spam Software Market
Security Software
Quantum Key Distribution System Market
Security Software
Global Security Orchestration Automation and Response (SOAR) Market
Security Software
Japan Mobile Biometrics Market
Security Software
Software Assurance Market
Security Software
Facial Recognition Market
Security Software
IAM Security Services Market
Security Software
Risk-Based Authentication (RBA) Market
Security Software
US Evidence Management Market
Security Software
Global SMS Firewall Market
Security Software
Stalkerware Market
Security Software
Personal Data Recovery Software Market
Security Software
Keystroke Dynamics Market
Security Software
Battery-Powered Doorbell Camera Market
Security Software
Global Wireless Intrusion Prevention System Market
Security Software
Device Vulnerability Management Market