
 Global Background Screening Market | 2026-2036
Global Background Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Global Background Screening Market Foresight
India is tilting toward cloud-based verification infrastructure as domestic IT services firms build delivery centers. Sterling Check Corp. leverages its proprietary court-access network to sustain turnaround advantages. First Advantage competes through integrated drug-testing and occupational-health workflows. DISA Global Solutions anchors its position in transportation and energy sector compliance screening.
Background screening encompasses the systematic collection and verification of personal, professional, and criminal history data through automated database queries, direct-source verification, and biometric identity confirmation against government records. The process employs API-driven workflows, machine-learning risk scoring, and real-time court-data integration to deliver adjudication-ready reports for hiring, tenancy, and partnership decisions. Criminal record checks occupy the largest service-type share as recurring re-screening mandates expand in regulated industries. Cloud-based deployment leads the infrastructure mix while hybrid architectures capture fastest growth among mid-market buyers seeking data-sovereignty controls. Employee screening dominates application volumes, though vendor and customer due-diligence segments are widening as supply-chain risk management matures.
The U.S. Fair Credit Reporting Act, enforced by the Federal Trade Commission and Consumer Financial Protection Bureau, governs disclosure and adverse-action protocols. The EU AI Act, administered by national market-surveillance authorities, imposes conformity obligations on automated decision systems used in employment screening. India's Digital Personal Data Protection Act, overseen by the Data Protection Board, is creating localization requirements for cross-border background checks. Stakeholders must monitor regulatory divergence between data-localization mandates and the operational need for transnational criminal-record access.
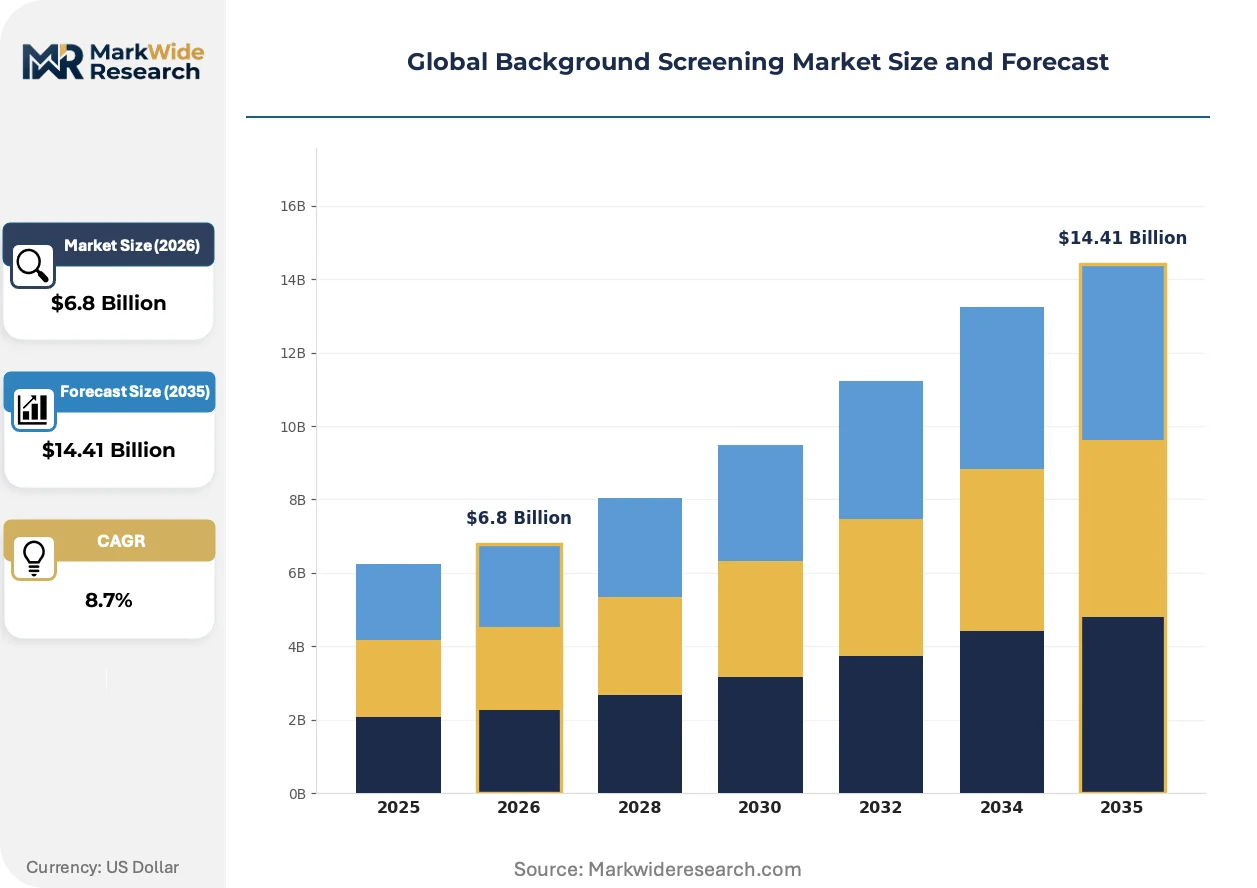
Market Dynamics
Continuous monitoring mandates from financial regulators are compressing screening cycles from annual snapshots to real-time alerts, forcing infrastructure rebuilds across vendor stacks.
Growth Catalysts
- EU AI Act conformity obligations:Automated employment-screening systems face mandatory risk-classification and audit-trail requirements, creating recurring compliance revenue for certified platform providers.
- Transportation sector DOT regulations:Federal Motor Carrier Safety Administration mandates for recurring driver checks expand addressable volumes in trucking, logistics, and last-mile delivery.
- Biometric identity confirmation:Liveness-detection and facial-recognition APIs reduce manual verification bottlenecks, cutting turnaround times from days to minutes for high-volume employers.
Market Restraints
- Cross-border data-localization friction:India's Digital Personal Data Protection Act and similar statutes fragment criminal-record access, raising operational costs for multinational screening programs.
- Court-data integration bottlenecks:County-level record systems in the United States lack API standardization, forcing expensive direct-source verification for jurisdictions without electronic access.
- API rate-limiting and access fees:Government database providers impose throttling and per-query charges that scale unpredictably with volume, compressing margins on high-frequency monitoring contracts.
Strategic Opportunities
- Gig-economy platform onboarding:Ride-sharing, delivery, and freelance marketplaces represent underpenetrated demand for instant, mobile-first identity and credential verification at scale.
- Supply-chain vendor due-diligence:ESG and sanctions-screening requirements are extending background checks from employees to third-party contractors and upstream suppliers.
- Blockchain-verified credential wallets:Self-sovereign identity standards enable candidates to carry portable, tamper-evident employment and education records, reducing duplicate verification costs.
Industry Challenges
- Adverse-action workflow complexity:FCRA-mandated pre-adverse and post-adverse notification sequences require precise timing and documentation, exposing employers to class-action litigation risk.
- Legacy HRIS integration:Enterprise applicant-tracking systems use inconsistent data schemas, forcing custom middleware development for seamless screening orchestration.
- Adjudication standardization gaps:Individual employers apply inconsistent criteria to identical criminal records, complicating automated decision-support tooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Background Screening Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Criminal Record Check, Employment Verification, Education Verification, Identity Authentication, Reference Check Deployment: Cloud-Based, On-Premise, Hybrid, Software-as-a-Service, Managed Services Application: Employee Screening, Tenant Screening, Volunteer Screening, Vendor Screening, Customer Due Diligence End User: Corporate Enterprises, Government Agencies, Educational Institutions, Financial Institutions, Non-Profit Organizations |
| Companies Covered | Sterling Check Corp., DISA Global Solutions, First Advantage, Bchex, Cisive, HireRight, Accurate, KarmaCheck, Checkr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Background Screening Market Shifts & Advancements
Real-time data pipelines and machine-learning risk scoring are displacing batch-processed reports, compressing decision timelines and expanding the addressable market beyond traditional hiring peaks.
Machine-learning risk scoring is migrating from retrospective batch analysis to continuous, event-driven monitoring. Financial institutions and healthcare systems are adopting these platforms fastest, driven by prudential regulator expectations. The shift is compressing vendor differentiation from database breadth to algorithmic accuracy and false-positive reduction.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on high-risk automated employment-screening tools. Vendors must now maintain technical documentation, human-in-the-loop protocols, and post-market monitoring systems. European enterprise buyers are prioritizing providers with notified-body certifications, reshaping competitive positioning for cross-border contracts.
Subscription-based continuous monitoring is displacing transactional, per-check pricing in regulated industries. Large employers in financial services and transportation are consolidating vendor relationships around multi-year platform contracts. This shift is most visible in the United States, where compliance-driven re-screening mandates create predictable recurring revenue streams.
Global Background Screening Market Segmentation
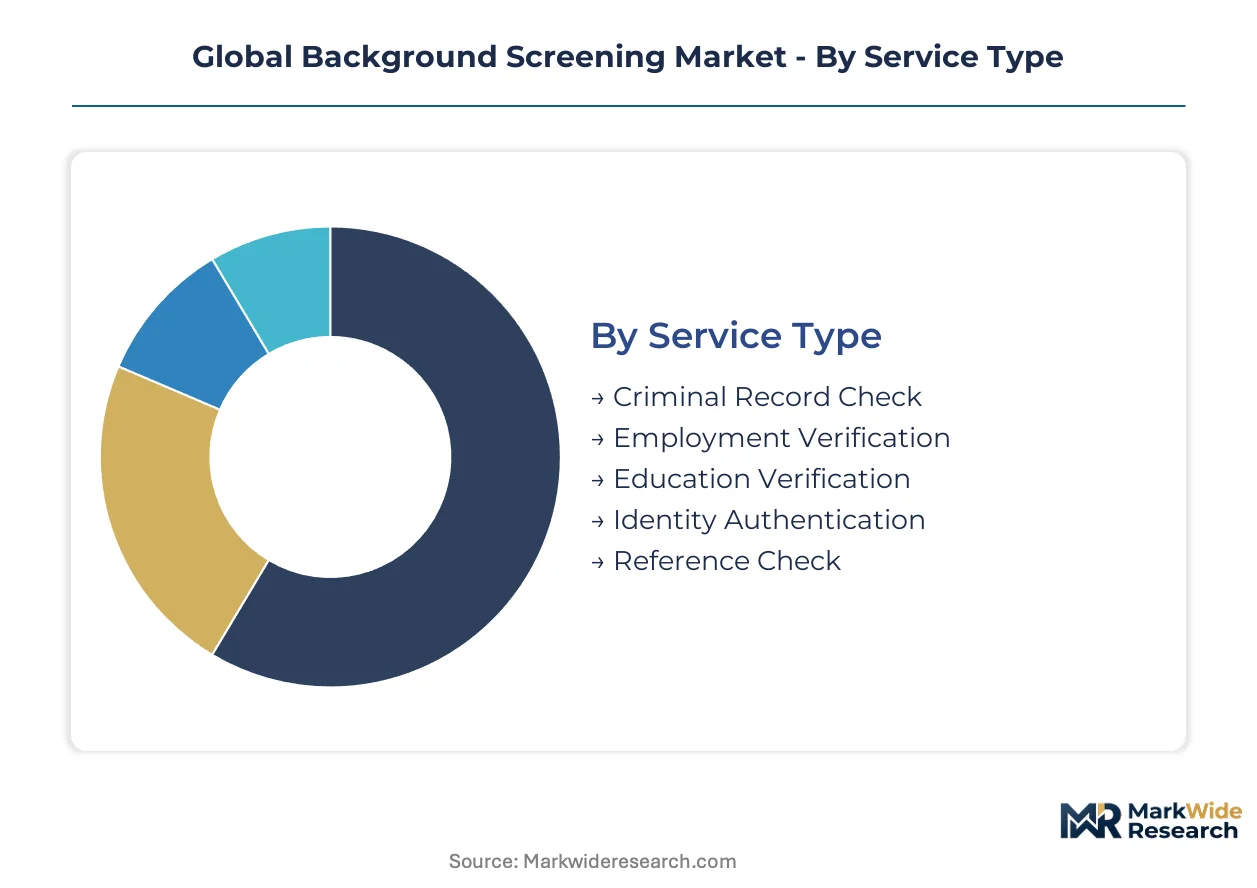
Background screening markets fragment across service delivery models, infrastructure choices, and compliance use cases. Understanding segment velocity helps vendors allocate R&D and sales resources against the highest-turnover verification workflows.
Service Type:
Criminal record checks refresh on continuous cycles in regulated industries, while education verification remains episodic. Employment and identity services occupy intermediate velocity tiers depending on gig-economy platform onboarding intensity.
- Criminal Record Check:Real-time court-data integration and API-driven county-level queries form the technical backbone. Demand concentrates among US financial institutions facing prudential regulator mandates for continuous employee monitoring. The segment absorbs the highest query volumes but faces margin pressure from government database access fees.
- Employment Verification:Direct-source confirmation with past employers via automated HRIS connectors and manual outreach protocols. Corporate enterprises in technology and healthcare sectors drive concentration, seeking to compress hiring timelines while maintaining FCRA disclosure compliance.
- Education Verification:Degree confirmation through registrar direct-source protocols and National Student Clearinghouse database access.
- Identity Authentication:Biometric liveness detection, document verification, and government ID cross-referencing via facial recognition APIs.
- Reference Check:Structured feedback collection from professional contacts through automated survey workflows and telephone interviews.
Criminal Record Check anchors the volume base while Identity Authentication gains share at the steepest rate.
Deployment:
Cost tier stratification separates enterprise buyers with dedicated infrastructure budgets from mid-market purchasers seeking variable-cost scaling. Managed services capture premium pricing for compliance-heavy implementations.
- Cloud-Based:Multi-tenant architectures with API-first delivery and elastic compute scaling for peak hiring seasons. Mid-market employers across US technology clusters favor this model for speed-to-deployment without capital expenditure.
- Hybrid:Split architectures retaining sensitive biometric data on-premise while leveraging cloud analytics. European financial institutions facing GDPR data-sovereignty requirements and India's IT services firms building domestic delivery centers drive adoption.
- On-Premise:Dedicated infrastructure installations for classified government security clearance processing.
- Software-as-a-Service:Subscription pricing with pre-integrated adjudication workflows and HRIS connectors.
- Managed Services:Fully outsourced verification operations with dedicated analyst teams and custom SLA terms.
Cloud-Based deployment holds the installed base majority while Hybrid configurations expand most quickly among compliance-sensitive buyers.
Application:
Customer type differentiation separates high-frequency transactional screening from relationship-driven recurring monitoring. Vendor and customer segments represent greenfield expansion beyond traditional employee verification.
- Employee Screening:Pre-employment and periodic re-screening for criminal, credential, and reference verification. US corporate enterprises in transportation and healthcare dominate volume, driven by DOT medical certification mandates and Joint Commission accreditation requirements.
- Vendor Screening:Due diligence on third-party contractors, suppliers, and service providers for supply chain risk management. Financial institutions extending ESG and sanctions-screening protocols to upstream partners are widening this segment.
- Tenant Screening:Credit history, eviction records, and criminal background verification for residential property leasing.
- Volunteer Screening:Background checks for youth-serving organizations and community programs with statutory clearance requirements.
- Customer Due Diligence:Identity verification and risk scoring for high-value banking and fintech onboarding.
Employee Screening commands the revenue core while Vendor Screening climbs the fastest as procurement teams absorb compliance responsibilities.
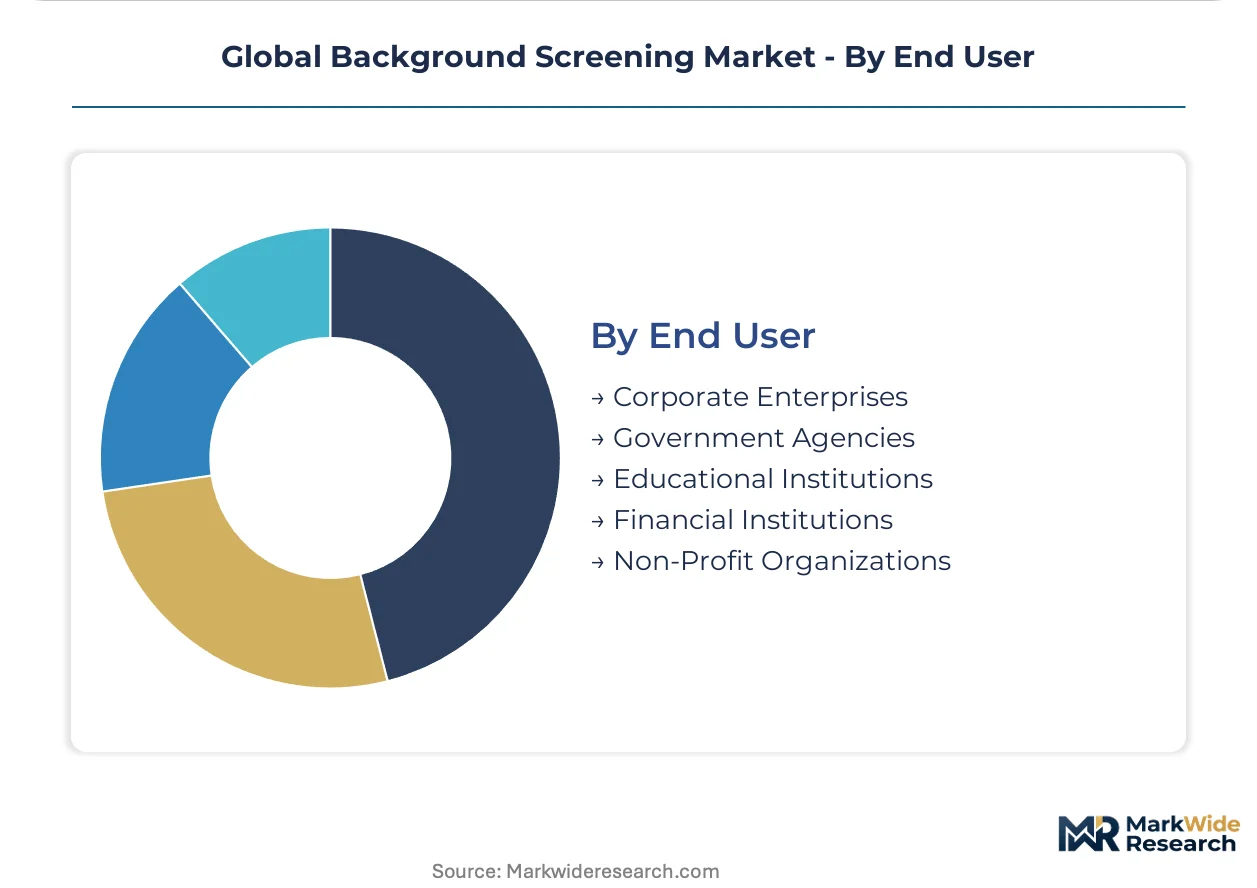
End User:
Institutional maturity tiers separate regulated entities with mandated screening programs from discretionary adopters. Financial and government buyers impose the strictest technical and audit requirements.
- Corporate Enterprises:Multi-divisional employers with centralized HR operations and standardized adjudication matrices. US technology, healthcare, and logistics corporations lead procurement, consolidating vendor relationships around platform contracts.
- Financial Institutions:Banks, insurers, and asset managers facing prudential regulator expectations for continuous monitoring. EU AI Act conformity obligations and SEC examination priorities reshape vendor selection toward certified algorithmic decision systems.
- Government Agencies:Federal, state, and municipal employers with security clearance and statutory background check mandates.
- Educational Institutions:Universities and K-12 districts verifying faculty, staff, and volunteer credentials.
- Non-Profit Organizations:Charities and social services with donor-mandated screening and statutory requirements for vulnerable-population access.
Corporate Enterprises generate the query volume foundation while Financial Institutions drive platform upgrade cycles at the sharpest pace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor infrastructure concentrates in the United States, where enterprise buyers drive platform consolidation. Cloud delivery centers in India and compliance-sensitive hybrid architectures in Germany reshape regional competitive dynamics.
United States
Financial institutions and transportation carriers generate the highest query volumes for continuous monitoring platforms. The FTC and CFPB enforce FCRA disclosure protocols that govern adverse-action workflows. Corporate headquarters clusters in New York, Chicago, and Dallas-Fort Worth anchor procurement decisions for multi-year platform contracts.
India
Domestic IT services firms and global capability centers demand cloud-based verification infrastructure at scale. The Digital Personal Data Protection Act imposes localization requirements for cross-border background checks. Bengaluru and Hyderabad delivery centers are expanding biometric identity confirmation capabilities for multinational employers.
Germany
Automotive manufacturers and industrial conglomerates prioritize GDPR-compliant screening architectures. The EU AI Act imposes conformity assessment obligations on automated employment-screening systems. Frankfurt and Munich financial centers drive demand for certified algorithmic decision tools.
United Kingdom
Financial services and professional services firms seek integrated compliance platforms. GDPR and emerging AI governance frameworks reshape vendor selection criteria. London's concentration of banking headquarters sustains demand for real-time sanctions and adverse media screening.
Canada
Transportation logistics and healthcare systems expand recurring re-screening programs. Health Canada and provincial privacy commissioners enforce data handling standards. Toronto and Vancouver corporate clusters are consolidating vendor relationships around subscription-based monitoring models.
Global Background Screening Market Competitive Landscape
Full-service platform providers and specialized compliance specialists split the market into distinct capability tiers. The vendor base organizes around database breadth, turnaround speed, and regulatory certification depth. Three archetypes dominate: court-data aggregators with proprietary access networks, integrated HRIS platform vendors, and niche sector specialists in transportation or financial services. Competitive moves center on multi-year enterprise platform consolidation and biometric API partnerships that compress verification timelines.
Within the full-service tier, Sterling Check Corp., First Advantage, and DISA Global Solutions exemplify divergent specialization strategies. Sterling Check Corp. anchors the court-data aggregation archetype through direct-source network investments. First Advantage occupies the integrated workflow position, combining screening with adjacent occupational health services. DISA Global Solutions represents sector-specific depth, concentrating on transportation and energy compliance mandates. These three structures illustrate how vendors defend position through infrastructure control, service bundling, or vertical focus rather than undifferentiated scale.
| Leading Market Players |
|---|
| Sterling Check Corp. |
| DISA Global Solutions |
| First Advantage |
| Bchex |
| Cisive |
| HireRight |
| Accurate |
| KarmaCheck |
| Checkr |
| Others |
Supply & Pricing Matrix
County-level court data aggregators in the United States command upstream concentration, anchoring margin pools with enterprise buyers who consolidate around multi-year platform contracts. API access fees from government database providers compress vendor margins while subscription-based continuous monitoring models capture premium pricing from financial institutions facing prudential regulator mandates.
Pricing Analysis
The FCRA and EU AI Act dictate the pricing tier structure across the background screening market. Three-tier pricing structure across premium, standard, and economy levels separates certified algorithmic decision platforms from basic database-query services. Price differentiation hinges on GDPR compliance certification and real-time court-data integration depth. Cost compression in mid-market transactional screening is intensifying because government database providers impose unpredictable per-query charges. Corporate enterprises with centralized HR operations exhibit lowest price sensitivity, while gig-economy platforms with high-volume episodic screening demand aggressive per-unit economics.
Supply Chain Analysis
Cloud infrastructure providers and biometric API developers hold contract-manufacturing concentration for verification platform delivery. Supply concentrates in the United States, India, and Germany for court-data networks, IT delivery centers, and GDPR-compliant hybrid architectures respectively. Raw material dependencies include facial-recognition algorithms, liveness-detection SDKs, and government ID authentication protocols. Single-source vulnerability runs through county-level court systems lacking API standardization, forcing expensive direct-source verification. Distribution runs through API-first platform integrations and managed services with dedicated analyst teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward enterprise procurement teams consolidating vendor relationships around multi-year platform contracts, fragmenting the vendor landscape into full-service providers and specialized compliance specialists.
For Market Incumbents: Insulate platform differentiation through proprietary court-access network investments and EU AI Act conformity certifications. Sterling Check Corp.'s direct-source infrastructure and First Advantage's occupational health bundling illustrate defensive moats against pure-play API entrants. Vertical integration into biometric identity confirmation APIs reduces third-party dependency and compresses turnaround times. For New Entrants and Emerging Players: Build out white-space presence in supply-chain vendor due-diligence and gig-economy platform onboarding, the most penetrable segments beyond traditional employee screening. Blockchain-verified credential wallets represent underexploited technical architecture for portable employment records. Channel partnerships with HRIS platform vendors offer the cleanest go-to-market path against entrenched full-service providers. For Investors and Strategic Acquirers: Capital is best deployed toward court-data aggregators with proprietary access networks and algorithmic risk-scoring specialists with notified-body certifications. Long-term viability favors vendors bridging continuous monitoring infrastructure with regulatory compliance automation. Watch for inflection in DOT regulatory expansion and EU AI Act enforcement intensity as demand signals.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric API Partnership | Facial-recognition integration with liveness detection cuts verification timelines from days to minutes. |
| EU AI Act Certification | Notified-body conformity assessment unlocks European financial institution procurement pipelines. |
| Continuous Monitoring Platform | Real-time alert infrastructure captures recurring revenue from prudential regulator mandates. |
| Court-Data Network Expansion | Proprietary county-level access reduces dependency on fragmented government database providers. |
| HRIS Platform Integration | Pre-built connectors with applicant-tracking systems compress enterprise sales cycles and switching costs. |
Research Methodology
The analysis maps criminal record verification, identity authentication, employment confirmation, and continuous monitoring platforms, each validated through CTOs, HR procurement officers, compliance directors, and biometric API developers. Primary interviews with enterprise buyers, vendor product managers, and regulatory affairs specialists combined with secondary validation against FTC enforcement actions, EU AI Act conformity databases, SEC 10-K disclosures, and county court system API documentation. Bottom-up query volume modeling and top-down market sizing triangulate segment-level outputs.
Assumptions held fixed include regulatory enforcement intensity, government database access fee structures, and hybrid cloud adoption curves across mid-market buyers. Segmentation dimensions modeled span service type, deployment architecture, application use case, and end-user institutional tier. CAGRs derive from regression analysis against query volume trajectories and pricing model shifts. Industry-specific forecast inputs include DOT medical certification mandate expansion rates and EU AI Act implementation timelines across member states.
Stress conditions across API rate-limiting escalation, cross-border data-localization enforcement, and biometric accuracy threshold tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory compliance cost pass-through and enterprise buyer consolidation velocity. Quarterly review of FTC enforcement patterns, EU notified-body certification issuance, and DOT regulatory proposal dockets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Data Loss Prevention Software Market
Security Software
AI Security Platforms Market
Security Software
Asia-Pacific Encryption Software Market
Security Software
Japan Mobile Biometrics Market
Security Software
US Hardware Encryption Market
Security Software
Anomaly Detection Tools Market
Security Software
Asia-Pacific Smart Doorbell Market
Security Software
Quantum Key Distribution System Market
Security Software
Cloud Data Loss Prevention Solution Market
Security Software
Mobile Threat Management Security Software Market
Security Software
Global SMS Firewall Market
Security Software
Global Cloud IAM Market
Security Software
Global Electronic Passports Market
Security Software
Employee Surveillance and Monitoring Software Market
Security Software
Devsecops Market
Security Software
Biometric POS Terminals Market