
 Soy Isoflavones Market | 2026-2036
Soy Isoflavones Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Isoflavones Market Outlook
Buyer concentration across North American nutraceutical formulators is rebalancing as mid-size contract manufacturers gain share from legacy pharmaceutical buyers. ADM leverages its origination infrastructure to secure non-GMO soybean streams for isoflavone extraction. DSM anchors European demand through its position in precision fermentation and botanical extraction. Frutarom Health competes on branded SoyLife ingredient recognition among finished goods marketers.
Soy isoflavones constitute a class of polyphenolic phytoestrogens—primarily genistein, daidzein, and glycitein—typically extracted from defatted soy flakes via ethanol or aqueous processing and standardized to 40-90% total isoflavone content for commercial use. These compounds function as selective estrogen receptor modulators in dietary supplements and functional foods targeting hormonal health applications. Powder formulations occupy the largest volume share due to blending flexibility in bulk nutraceutical production, while liquid extracts represent the fastest-expanding format as beverage fortification accelerates. Menopause relief applications command premium positioning within the application matrix, whereas antioxidant positioning competes on price with broader polyphenol alternatives.
FDA GRAS self-affirmation pathways and EFSA novel food opinions shape ingredient marketability across Atlantic supply chains, with divergent purity thresholds creating formulation complexity for multinational brands. USDA organic certification and Non-GMO Project verification function as de facto market access requirements in premium North American channels. Stakeholders must monitor evolving EPA biotechnology oversight for precision-fermented isoflavone alternatives that could reshape raw material sourcing economics.
Market Dynamics
EFSA novel food evaluation pathways are compressing compliance timelines for European nutraceutical formulators while FDA GRAS self-affirmation maintains parallel but divergent purity thresholds, forcing multinational brands into dual-track formulation strategies.
Growth Catalysts
- Menopause relief positioning:North American functional food channels are expanding shelf space for hormonal health applications, pulling concentrate demand from legacy pharmaceutical buyers toward mid-size contract manufacturers.
- Non-GMO verification:USDA organic certification and Non-GMO Project standards function as de facto market access requirements in premium US channels, locking in origination infrastructure investments.
- Beverage fortification acceleration:Liquid extract formats are capturing share from powder formulations as ready-to-drink functional beverages integrate isoflavones for antioxidant positioning.
Market Restraints
- Input cost volatility:Non-GMO soybean premiums fluctuate with origination tightness in North American growing regions, compressing extraction margins for standard-grade concentrates.
- Regulatory friction:Divergent EFSA and FDA purity thresholds create formulation complexity, requiring separate product lines for Atlantic supply chains.
- Substitution threat:Resveratrol and other polyphenol alternatives compete on price in antioxidant positioning, pressuring commodity-grade isoflavone pricing.
Strategic Opportunities
- Precision fermentation alternatives:EPA biotechnology oversight evolution could enable microbial-derived isoflavones, reshaping raw material sourcing economics away from agricultural extraction.
- German procurement expansion:EFSA compliance pathway clarity is unlocking concentrate demand from German nutraceutical manufacturers previously constrained by novel food uncertainty.
- Direct-to-practitioner channels:Functional medicine clinicians are bypassing retail intermediaries for clinical-grade isoflavone formulations, creating premium pricing pockets.
Industry Challenges
- Dual-track formulation complexity:Multinational brands face SKU proliferation costs maintaining separate EFSA-compliant and FDA-aligned product lines.
- Extraction capacity bottlenecks:Ethanol and aqueous processing infrastructure requires significant capital deployment to scale defatted soy flake throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Isoflavones Market |
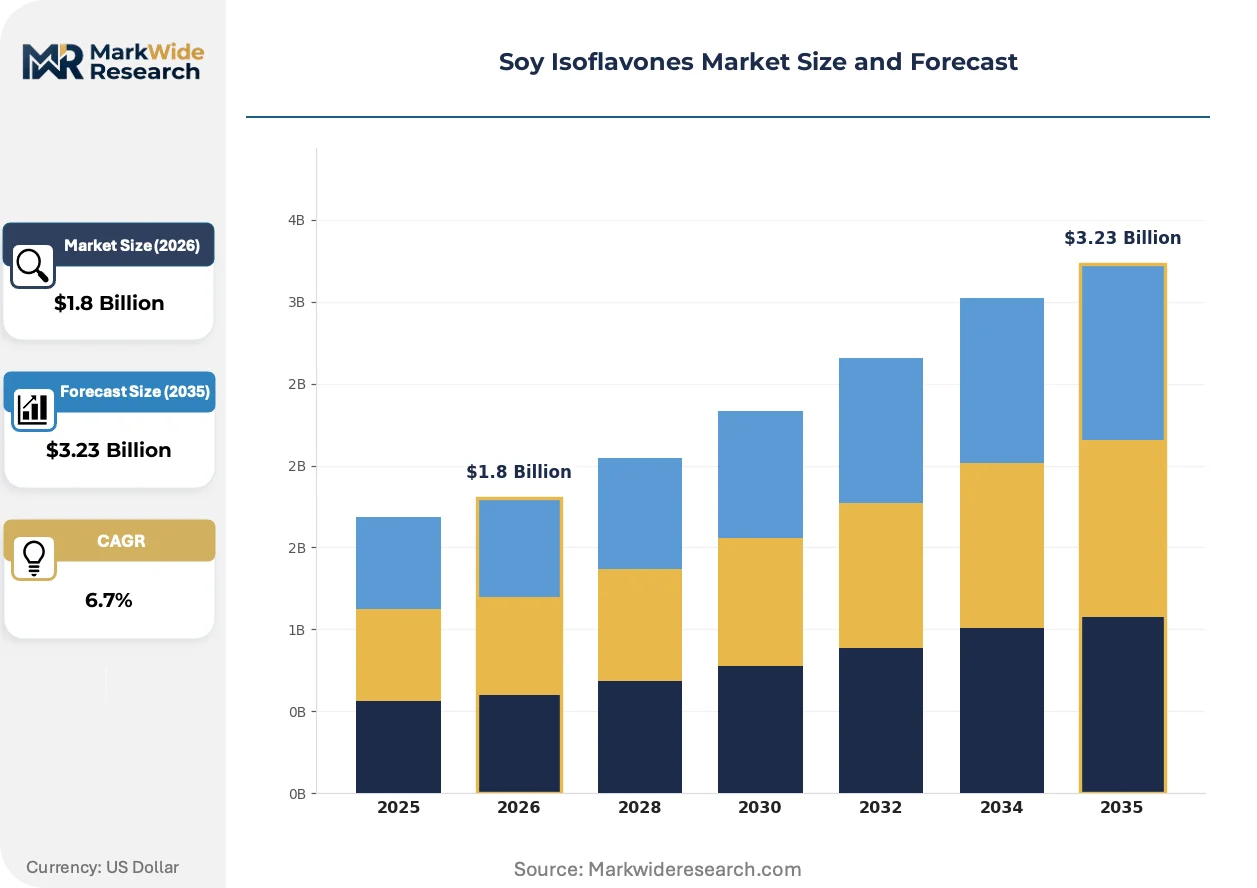
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder, Capsules, Tablets End User: Pharmaceuticals, Food & Beverage, Nutraceuticals, Cosmetics Application: Hormonal Balance, Osteoporosis Prevention, Menopause Relief, Antioxidant Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland Company (ADM), Frutarom Health (SoyLife), Koninklijke DSM N.V. (DSM), Cargill Incorporated, BASF SE, SunOpta Inc., E. I. du Pont de Nemours and Company, International Flavors & Fragrances Inc., Novogen Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Isoflavones Market Strategic Shifts
Processing technology evolution and regulatory pathway divergence are fragmenting competitive advantage sources, with extraction efficiency and compliance velocity replacing scale as primary differentiators.
Continuous aqueous extraction systems are decentralizing production economics for mid-tier concentrate suppliers. Regional processors in France and Germany are adopting modular extraction units to bypass centralized ADM infrastructure. This technology is decentralizing geographic concentration of isoflavone supply away from North American origination hubs.
EFSA novel food opinion finalization is compressing European market entry timelines for standardized extracts. German and French formulators are accelerating procurement commitments as compliance clarity emerges. Menopause relief applications in these markets face accelerated competitive entry as barriers fall.
Practitioner-directed purchasing is displacing retail-driven demand in premium hormonal health segments. Functional medicine clinics and integrative health practitioners are consolidating buying power for clinical-grade formulations. This channel rotation is most visible in US coastal metropolitan markets where direct dispensing regulations permit vertical integration.
Soy Isoflavones Market Segmentation
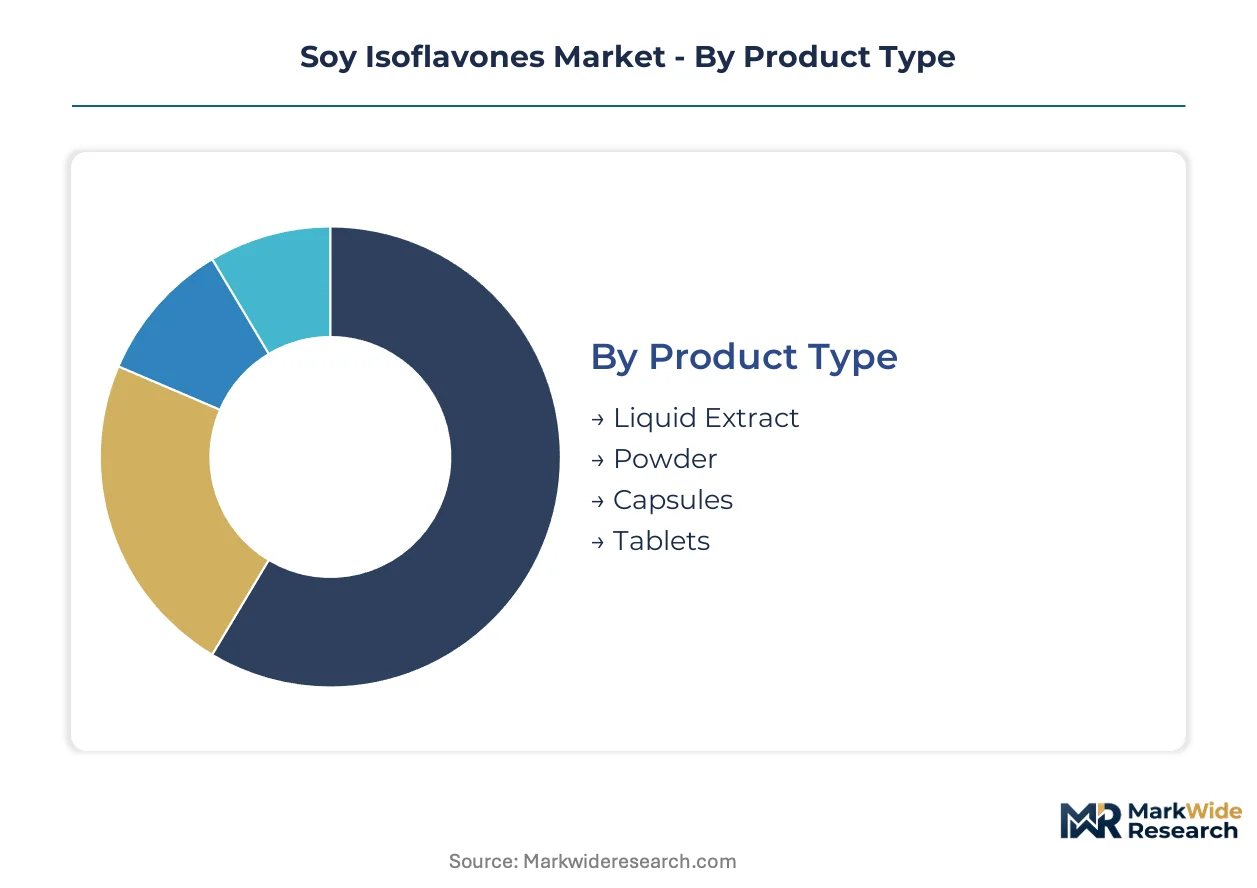
Soy isoflavone formulations diverge sharply across delivery formats and therapeutic positioning, with powder and liquid extracts commanding distinct supply chain investments. End-user concentration in nutraceuticals versus pharmaceutical channels determines margin structures and regulatory compliance burdens.
Product Type:
Replacement cycles in beverage fortification are accelerating demand migration from legacy powder formats toward liquid concentrates that integrate seamlessly into ready-to-drink production lines.
- Powder:Standardized concentrates at 40-90% total isoflavone content serve bulk nutraceutical blending operations. Demand concentrates among North American contract manufacturers seeking formulation flexibility for menopause relief supplements. USDA organic certification functions as a de facto procurement filter in premium channels.
- Liquid Extract:Aqueous and ethanol-derived solutions enable direct incorporation into functional beverages without reconstitution steps. German and French beverage formulators are expanding procurement as EFSA novel food pathways clarify compliance timelines for fortified drink applications.
- Capsules:Pre-measured dosing formats target practitioner-directed channels where clinical-grade specifications command premium positioning.
- Tablets:Compressed formulations compete on convenience in retail supplement aisles, though bioavailability concerns limit penetration in functional medicine segments.
Volume placements concentrate in Powder; the faster expansion belongs to Liquid Extract.
End User:
Cost tier stratification separates pharmaceutical-grade specifications from commodity nutraceutical sourcing, with cosmetics applications emerging as a mid-tier volume opportunity.
- Nutraceuticals:Dietary supplement manufacturers represent the dominant demand channel, with mid-size contract manufacturers gaining procurement share from legacy pharmaceutical buyers. Non-GMO Project verification and USDA organic certification function as de facto market access requirements in premium US channels.
- Pharmaceuticals:Clinical-grade isoflavone formulations target hormone replacement therapy adjuvants and prescription compounding. FDA GRAS self-affirmation pathways and stringent purity thresholds create formulation complexity that favors established suppliers with regulatory affairs infrastructure.
- Food & Beverage:Functional food fortification applications span soy milk, energy bars, and protein supplements. German and French manufacturers are accelerating concentrate procurement as EFSA novel food evaluations clarify compliance pathways.
- Cosmetics:Topical applications leverage isoflavone antioxidant properties in anti-aging formulations. Demand remains fragmented across prestige and mass-market skincare channels.
Revenue concentration sits with Nutraceuticals; Pharmaceuticals retain the steepest expansion trajectory for clinical-grade specifications.
Application:
Margin structures vary dramatically across therapeutic positioning, with hormonal health applications commanding substantial premiums over commodity antioxidant formulations.
- Menopause Relief:Selective estrogen receptor modulation positioning targets perimenopausal and postmenopausal symptom management. North American functional food channels are expanding shelf space for hormonal health applications, pulling concentrate demand toward mid-size contract manufacturers.
- Hormonal Balance:Broader endocrine support applications span menstrual health and fertility support segments. Practitioner-directed purchasing in US coastal metropolitan markets is consolidating buying power for clinical-grade formulations.
- Osteoporosis Prevention:Bone density maintenance claims compete with calcium and vitamin D formulations in aging demographics.
- Antioxidant:General wellness positioning faces price pressure from resveratrol and broader polyphenol alternatives. Commodity-grade isoflavone pricing compresses as substitution threats intensify.
Margin capture concentrates in Menopause Relief; Hormonal Balance is gaining share fastest among functional medicine channels.
Distribution Channel:
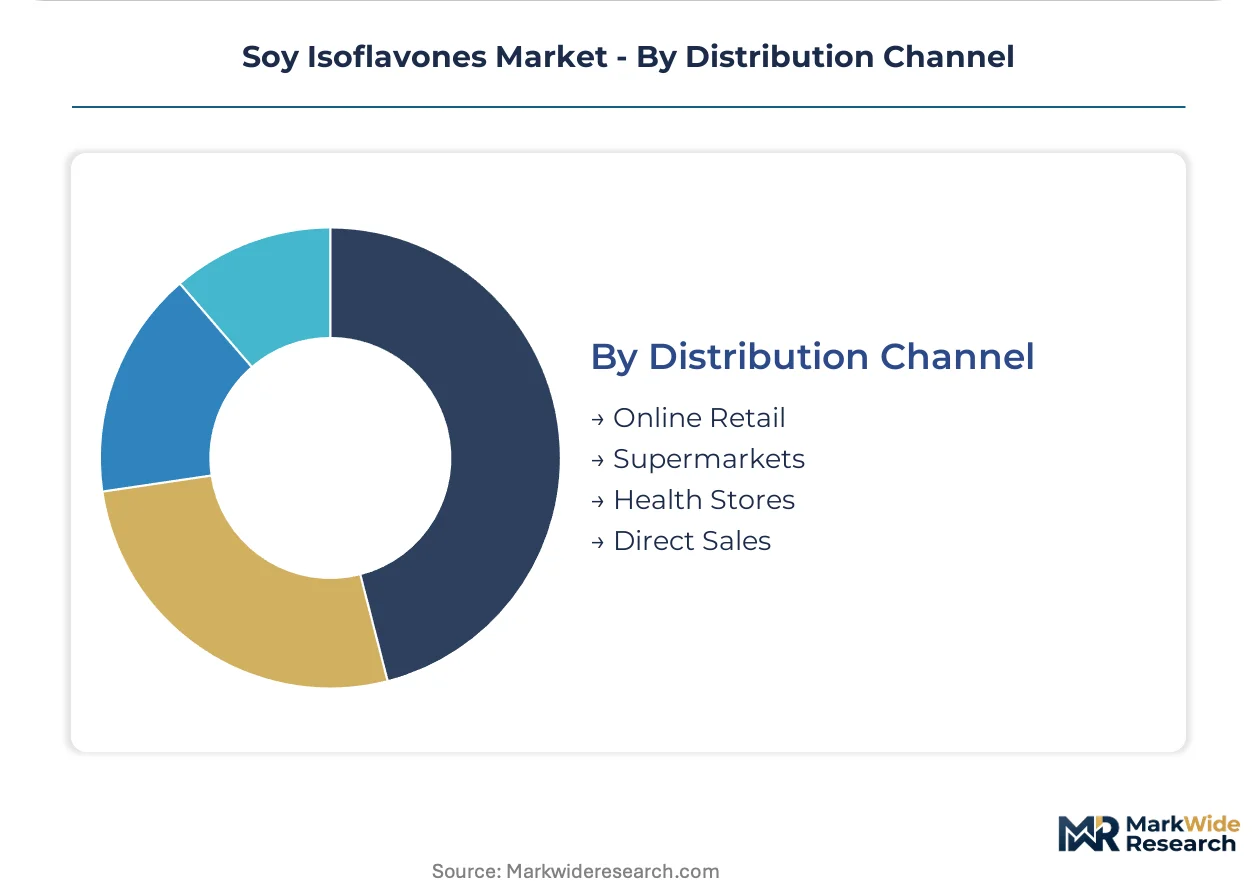
Customer type fragmentation separates retail-driven volume from practitioner-directed premium procurement, with digital channels capturing share from legacy health store networks.
- Health Stores:Specialized retailers remain the primary venue for premium isoflavone supplement discovery. Staff recommendation dynamics favor branded ingredient recognition among finished goods marketers.
- Online Retail:Direct-to-consumer platforms enable subscription models for menopause relief regimens. German and French consumers are migrating toward digital procurement as product education content clarifies EFSA-compliant formulation benefits.
- Supermarkets:Mass-market placement concentrates in antioxidant-positioned products competing on shelf price with alternative polyphenol supplements.
- Direct Sales:Practitioner dispensing regulations in select US states permit vertical integration between functional medicine clinics and clinical-grade formulation suppliers.
Transaction volume concentrates in Health Stores; Online Retail is climbing the fastest among urban professional demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration for soy isoflavones tilts toward the United States and Germany, where nutraceutical formulators and functional food manufacturers command premium concentrate volumes. EFSA novel food evaluations and FDA GRAS pathways create divergent compliance environments across Atlantic supply chains. Regional processing clusters adapt extraction infrastructure to local regulatory thresholds.
United States
Mid-size contract manufacturers in the United States are consolidating procurement share from legacy pharmaceutical buyers for menopause relief applications. FDA GRAS self-affirmation pathways maintain distinct purity thresholds that shape formulation strategies for domestic brands. Chicago and Minneapolis processing clusters anchor North American ethanol and aqueous extraction capacity for defatted soy flake throughput.
Germany
German nutraceutical manufacturers are expanding concentrate procurement as EFSA novel food opinions clarify compliance timelines for standardized extracts. The country's national pharmaceutical regulator aligns with EFSA guidance on botanical ingredient specifications. Frankfurt and Hamburg industrial zones host modular extraction unit deployments that bypass centralized North American infrastructure.
France
French beverage formulators are accelerating liquid extract procurement for ready-to-drink functional food fortification applications. EFSA novel food evaluations provide pathway certainty previously constrained by regulatory uncertainty. Lyon and Paris metropolitan clusters concentrate regional processing capacity for aqueous-derived isoflavone solutions.
China
Chinese extraction facilities supply standard-grade concentrates to international nutraceutical blenders under cost-competitive positioning. The National Medical Products Administration oversees botanical extract specifications for domestic and export markets. Shandong and Jiangsu provinces host defatted soy flake processing infrastructure serving global commodity demand.
Japan
Japanese functional food manufacturers integrate isoflavones into fermented soy product lines with established consumer acceptance. The Pharmaceuticals and Medical Devices Agency evaluates novel food applications for non-traditional delivery formats. Tokyo and Osaka metropolitan areas concentrate precision fermentation research that could reshape raw material sourcing economics.
Soy Isoflavones Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue precision fermentation alternatives and modular extraction technologies. The market structures around three tiers: integrated agribusiness conglomerates with origination infrastructure, specialized botanical extract houses with branded ingredient recognition, and regional processors adopting decentralized aqueous systems. Strategic moves concentrate on backward integration into non-GMO soybean origination and dual-track formulation capacity for EFSA and FDA compliance.
Among integrated agribusiness conglomerates, Archer Daniels Midland Company and Cargill Incorporated exemplify scale-driven archetypes with captive supply chain control over North American soybean streams. Koninklijke DSM N.V. occupies a position within the precision fermentation and botanical extraction tier, anchoring European demand through advanced processing capabilities. Frutarom Health sits within the branded ingredient specialist category, with its SoyLife designation representing recognition-focused positioning among finished goods marketers.
| Leading Market Players |
|---|
| Archer Daniels Midland Company (ADM) |
| Frutarom Health (SoyLife) |
| Koninklijke DSM N.V. (DSM) |
| Cargill Incorporated |
| BASF SE |
| SunOpta Inc. |
| E. I. du Pont de Nemours and Company |
| International Flavors & Fragrances Inc. |
| Novogen Limited |
| Others |
Value Chain & Pricing Dynamics
Mid-size North American contract manufacturers now anchor concentrate procurement for menopause relief applications, shifting pricing power toward volume-tiered contract structures that reward multi-year offtake commitments over spot-market transactions.
Pricing Analysis
Volume placements in standard-grade powder concentrates generate thin margins, while clinical-grade specifications for practitioner-directed channels capture substantial premiums. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified extracts from commodity-grade alternatives and precision-fermented prototypes. Cost compression in standard-grade tiers is intensifying because resveratrol and polyphenol substitutes compete aggressively on price. Pharmaceutical buyers exhibit lowest price sensitivity due to regulatory compliance burdens, whereas mass-market antioxidant positioning faces acute substitution-driven pressure.
Supply Chain Analysis
Dual-sourcing mandates from German and French nutraceutical formulators now require qualification of both North American and European extraction facilities to mitigate EFSA-FDA regulatory divergence risks. Raw material supply draws from non-GMO soybean origination in the United States, organic cultivation in France, and precision fermentation research in Japan. Single-source vulnerability concentrates in ethanol and aqueous processing infrastructure, where capital-intensive defatted soy flake throughput limits rapid capacity scaling. Distribution runs through regional processing clusters in Chicago, Frankfurt, and Lyon before final formulation at contract manufacturing sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance velocity and origination control, with EFSA-FDA dual-track formulation complexity forcing sub-scale extractors toward acquisition or exit.
For Market Incumbents: Extend backward integration into non-GMO soybean origination to lock in supply security against origination tightness in North American growing regions. ADM and DSM should expand modular aqueous extraction capacity in Germany and France to preempt regional processor encroachment. Precision fermentation R&D investment now represents essential defensive positioning against EPA biotechnology oversight evolution that could enable microbial-derived alternatives. For New Entrants and Emerging Players: Functional medicine clinicians in US coastal metropolitan markets represent an underserved buyer archetype with consolidated purchasing power and premium price tolerance for clinical-grade formulations. Direct-to-practitioner dispensing channels bypass retail margin stacking and offer fastest penetration path. White-space exists in EFSA-compliant liquid extracts for German and French beverage fortification applications where compliance clarity has only recently emerged. For Investors and Strategic Acquirers: The window for entry favors specialized botanical extract houses with branded ingredient recognition and established regulatory affairs infrastructure. Long-term viability hinges on dual-track formulation capability spanning Atlantic compliance environments. The signal to watch is EPA guidance finalization on precision-fermented isoflavones, which would trigger raw material sourcing economics disruption and reshape competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Non-GMO Origination | ADM leverages captive soybean streams to secure supply against origination volatility in North American growing regions. |
| Modular Extraction Unit Deployment | Regional processors in Frankfurt and Lyon bypass centralized infrastructure with continuous aqueous systems. |
| Dual-Track Formulation Capacity | Multinational brands maintain separate EFSA-compliant and FDA-aligned product lines to serve Atlantic supply chains. |
| Precision Fermentation R&D Investment | DSM and Japanese researchers advance microbial-derived isoflavones that could reshape agricultural extraction economics. |
| Direct-to-Practitioner Channel Development | Clinical-grade suppliers bypass retail intermediaries through functional medicine dispensing regulations in select US states. |
Study Parameters
Independent corroboration across extraction facility operators, nutraceutical procurement directors, and regulatory affairs specialists underwrites the qualitative findings in this study. Primary fieldwork involved structured interviews with contract manufacturing executives, functional medicine practitioners, and EFSA novel food evaluation consultants. Secondary validation drew from FDA GRAS notifications, EFSA scientific opinions, USDA organic certification databases, and customs trade records for defatted soy flake shipments. Bottom-up volume modeling from segment-level demand and top-down cross-checks against aggregate nutraceutical ingredient spending ensured analytical consistency.
Comparable-period anchoring to historical procurement patterns across powder, liquid extract, and capsule formats established baseline demand trajectories over the projection horizon. The analytical framework modeled delivery format, end-user channel, therapeutic application, and geographic regulatory cluster as core segmentation dimensions. CAGRs were derived from trend extrapolation adjusted for EFSA compliance timeline acceleration and beverage fortification format migration. Forecast inputs incorporated non-GMO soybean premium volatility indices and precision fermentation technology readiness assessments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA biotechnology oversight evolution and EFSA novel food opinion finalization schedules. Deviation in precision fermentation commercialization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
South America Botanical Supplements Market
Nutritional Supplements
Aquatic Feed Supplement Market
Nutritional Supplements
Canada Whey Protein Market
Nutritional Supplements
Nutrition Powder Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
North America Digestive Health Supplements Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
Global Collagen Peptides Market
Nutritional Supplements
Algae Supplements Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Inflammation Supplements Market
Nutritional Supplements
Maternity Vitamins and Supplements Market
Nutritional Supplements
Prenatal Vitamin Supplements Market
Nutritional Supplements
Sleep Gummies Market