
 Maternity Vitamins and Supplements Market | 2026-2036
Maternity Vitamins and Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Maternity Vitamins and Supplements Market Outlook
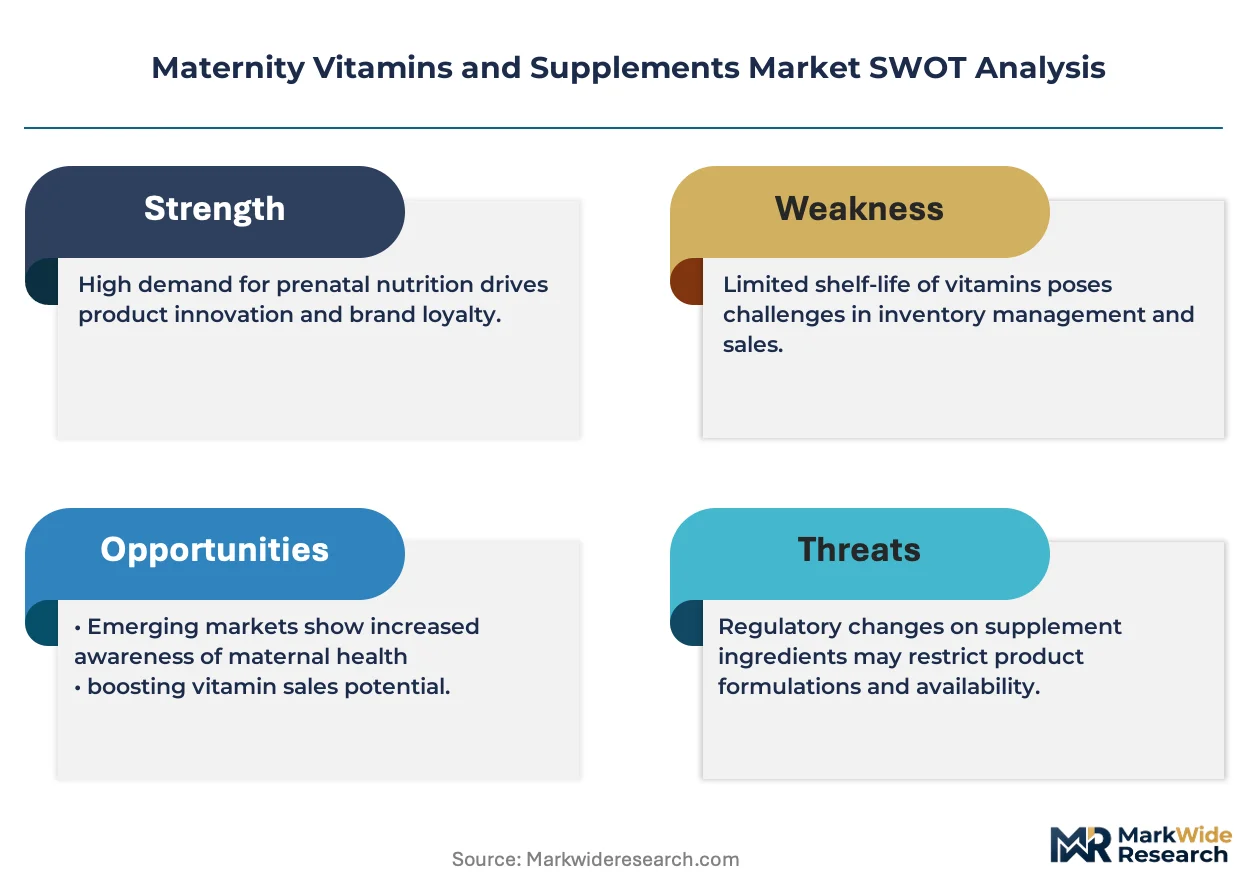
Pharmacy-to-online retail migration is fragmenting traditional maternity supplement distribution. Abbott Laboratories anchors hospital and clinician channels with institutional credibility. Bayer AG leverages its prenatal brand heritage across European and North American pharmacy networks. Garden of Life differentiates through organic certification and whole-food positioning in premium health stores.
Maternity vitamins and supplements comprise formulated nutrient complexes containing folic acid, iron, DHA, and fat-soluble vitamins manufactured via tablet compression, softgel encapsulation, or liquid suspension for gestational and lactational nutritional support. Multivitamins dominate volume as the standard-of-care recommendation from obstetric providers, while omega-3 fatty acids capture expanding margin pools due to premium DHA sourcing and clinical positioning around fetal neurodevelopment. Tablet formulations sustain manufacturing efficiency at scale, though liquid and powder formats are gaining fastest among consumers with swallowing difficulties or preference for mixable delivery.
FDA Current Good Manufacturing Practices and DSHEA labeling requirements govern product quality claims and adverse event reporting in the United States, while the EFSA health claims process shapes permissible marketing language across European jurisdictions. Compliance costs are concentrating formulation investment among established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving micronutrient reference values from WHO and national health agencies, as revised gestational intake thresholds will force portfolio reformulation decisions.
Market Dynamics
Professional recommendation channels—prenatal clinics, obstetric practices, and hospital discharge protocols—are concentrating demand authority among a narrow prescriber base, forcing supplement manufacturers to prioritize institutional formulary acceptance over direct consumer marketing spend.
Growth Catalysts
- FDA Current Good Manufacturing Practice enforcement:Heightened quality standards are filtering out marginal producers and consolidating shelf space for compliant manufacturers in US pharmacy and hospital channels.
- Direct-to-consumer subscription models:Recurring revenue structures are reducing customer acquisition costs and improving lifetime value metrics for digital-native supplement brands.
- Gestational DHA clinical positioning:Fetal neurodevelopment research is expanding omega-3 recommendation rates among US obstetricians and European midwifery networks.
Market Restraints
- Marine-derived DHA supply concentration:Premium omega-3 sourcing depends on Peruvian and North Atlantic fishery outputs vulnerable to El Niño disruption and quota restrictions.
- DSHEA labeling compliance costs:Structure-function claim substantiation and adverse event reporting infrastructure impose fixed cost burdens that disadvantage smaller formulation houses.
- Iron formulation tolerability ceiling:Gastrointestinal side effect profiles limit compliance rates for standard ferrous sulfate preparations, creating adherence gaps.
Strategic Opportunities
- Postpartum lactation support extension:Six-month-plus breastfeeding duration recommendations from WHO are widening the addressable window beyond traditional prenatal-only positioning.
- Vegan algal DHA substitution:Plant-derived omega-3 technologies are capturing dietary-restricted consumer segments previously excluded from marine-sourced products.
- Pharmacy benefit manager integration:Supplement inclusion in US employer-sponsored health spending accounts is reducing out-of-pocket price sensitivity for insured populations.
Industry Challenges
- Regulatory affairs talent scarcity:Dual expertise in FDA DSHEA compliance and EFSA health claims processes commands premium compensation and constrains European market entry timelines.
- Softgel encapsulation equipment lead times:Specialized manufacturing asset availability bottlenecks are extending capacity expansion cycles for DHA-focused product lines.
- Cross-border e-commerce customs complexity:Varying national definitions of food versus pharmaceutical classification for prenatal supplements create fulfillment friction and return risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maternity Vitamins and Supplements Market |
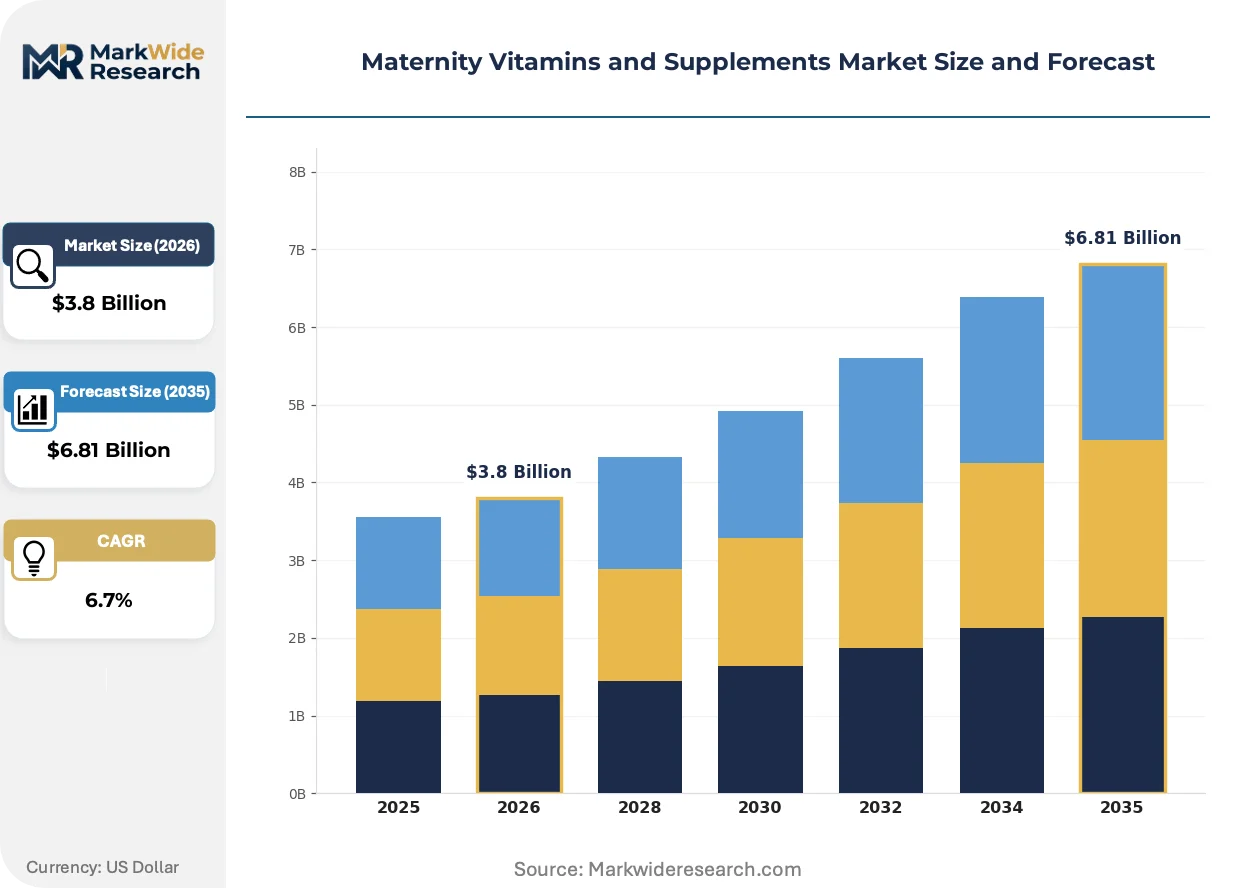
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multivitamins, Iron Supplements, Folic Acid, Omega-3 Fatty Acids Formulation: Tablet, Capsule, Powder, Liquid Distribution Channel: Pharmacies, Online Retail, Health Stores, Hospitals Target User: Pregnant Women, Nursing Mothers, Women Planning Pregnancy, Healthcare Professionals |
| Companies Covered | Nature Made, Bayer AG, Abbott Laboratories, Nestlé Health Science, Garden of Life, Vitabiotics, Church & Dwight Co., Inc., MegaFood, New Chapter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maternity Vitamins and Supplements Market Strategic Shifts
Formulation science and delivery mechanism innovation are compressing the gap between clinical efficacy requirements and consumer experience preferences, reshaping how nutrient bioavailability claims translate into purchase decisions.
Liposomal encapsulation technology is hybridizing traditional vitamin delivery with pharmaceutical absorption enhancement techniques. Premium supplement brands are adopting phospholipid-bound nutrient formats to differentiate bioavailability claims in saturated retail environments. This convergence is compressing margin structures for standard tablet formulations while enabling 40-60% price premiums for enhanced-absorption positioning.
EFSA health claims authorization processes are tightening permissible marketing language for gestational benefit assertions across European jurisdictions. Manufacturers must now navigate pre-substantiation requirements that extend product launch timelines by 18-24 months. The UK and German markets exhibit the strictest enforcement, forcing reformulation of folic acid and DHA promotional materials.
Subscription-based replenishment models are displacing pharmacy counter purchasing as the dominant acquisition channel for millennial and Gen-Z maternal demographics. Direct-to-consumer platforms are capturing prescription-adjacent recommendation flows through telehealth partnerships and influencer obstetrician networks. This channel migration is most pronounced in US coastal metropolitan markets and Australian capital cities.
Maternity Vitamins and Supplements Market Segmentation
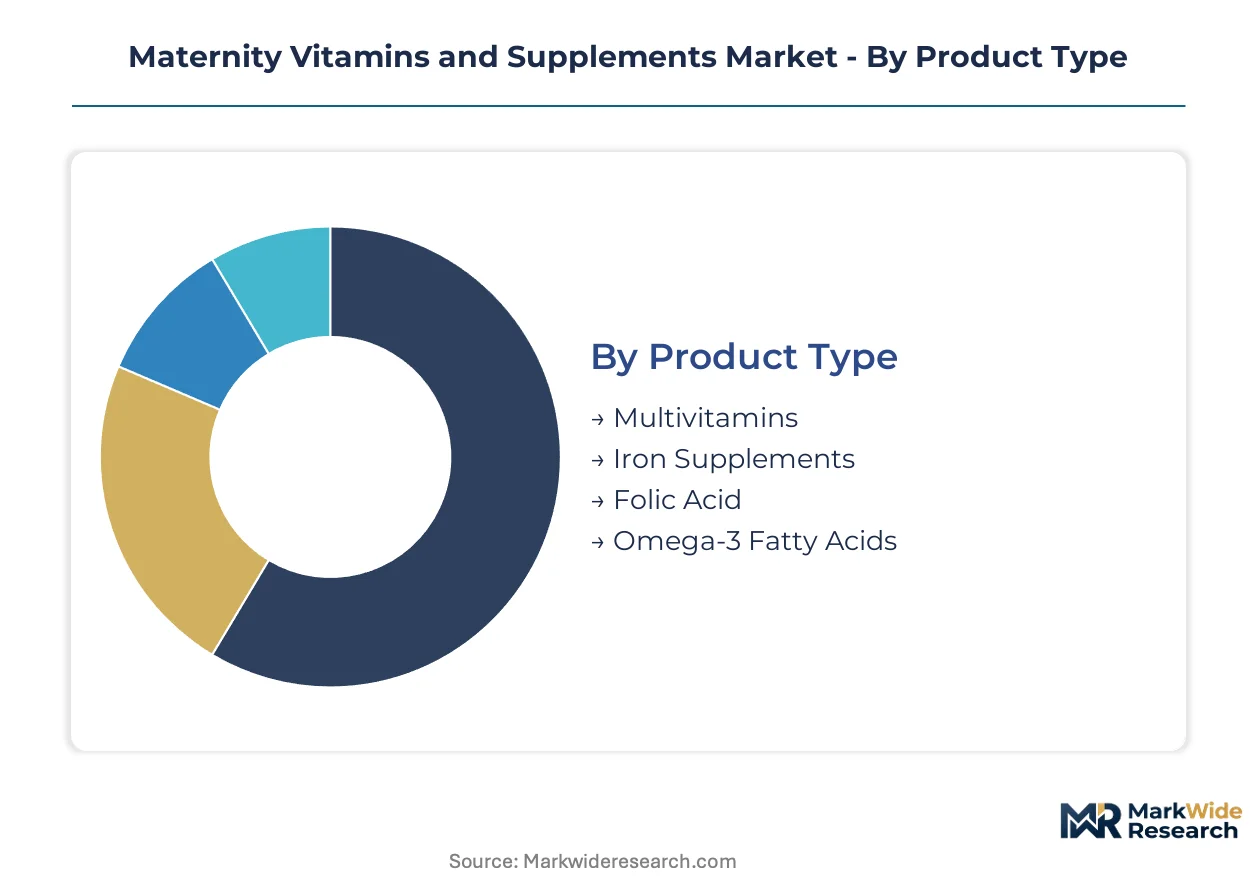
Maternity supplement purchasing cycles vary dramatically across product categories. Multivitamins generate recurring quarterly replenishment, while specialty formulations like omega-3s command longer purchase intervals due to higher per-unit costs and extended supply packaging.
Product Type:
Inventory velocity differs sharply across this category. Standard multivitamins turn over fastest through pharmacy and subscription channels, while premium omega-3 formulations move more slowly due to concentrated dosing schedules and higher price points.
- Multivitamins:Comprehensive nutrient complexes containing folic acid, iron, calcium, and fat-soluble vitamins in fixed-dose combinations. Demand concentrates in prenatal clinic prescription flows across the United States, where obstetric protocol standardization drives formulary inclusion. Insurance reimbursement for prescription prenatal multivitamins reduces out-of-pocket friction in American healthcare systems.
- Omega-3 Fatty Acids:DHA and EPA concentrates sourced from marine fish oil or cultivated microalgae, delivered in triglyceride or ethyl ester forms. European midwifery networks in Germany and the Netherlands are expanding DHA recommendation rates following EFSA neurodevelopment positioning. Algal-derived alternatives are capturing vegan and vegetarian maternal demographics previously excluded from marine sourcing.
- Iron Supplements:Ferrous sulfate, ferrous bisglycinate, and carbonyl iron preparations addressing gestational anemia prevention. Ferrous bisglycinate chelates command premium positioning due to superior gastrointestinal tolerability profiles.
- Folic Acid:Synthetic folate and 5-MTHF (methylfolate) variants supporting neural tube defect prevention. Methylfolate formats penetrate MTHFR polymorphism-aware consumer segments seeking bioactive alternatives.
Multivitamins dominate installed base. Omega-3 fatty acids are where expansion concentrates.
Formulation:
Manufacturing cost structures and consumer compliance patterns segment this dimension. Solid dosage forms achieve lowest per-unit production economics, while liquid and powder formats sacrifice margin for accessibility advantages.
- Tablet:Compressed powder matrices enabling high-volume manufacturing efficiency and extended shelf stability. Tablet production concentrates in FDA-registered facilities across the United States and EMA-compliant plants in Germany and Switzerland.
- Capsule:Hard gelatin or vegetable-derived shells containing powder, granule, or oil-based fills. Softgel encapsulation dominates DHA delivery due to oxygen barrier properties protecting omega-3 oxidation.
- Liquid:Aqueous or oil-based suspensions with flavor masking systems for consumers with dysphagia or pediatric dosing requirements. Liquid formats gain fastest among Australian and UK consumers prioritizing dose flexibility.
- Powder:Free-flowing granules or effervescent compounds for reconstitution in beverages. Powder sachets expand through direct-to-consumer subscription models targeting mix-in convenience.
Tablets dominate installed base. Liquid and powder formats are climbing the fastest.
Distribution Channel:
Channel economics and professional endorsement authority create distinct competitive arenas. Institutional channels leverage clinical credibility, while digital channels optimize lifetime value through recurring revenue structures.
- Pharmacies:Brick-and-mortar retail and hospital outpatient dispensaries with pharmacist consultation access. German and French pharmacy networks maintain strict category gatekeeping through mandatory behind-counter placement.
- Online Retail:Direct-to-consumer platforms, marketplace aggregators, and subscription services. US coastal metropolitan markets exhibit the most pronounced channel migration toward digital acquisition.
- Health Stores:Specialty retailers emphasizing organic, non-GMO, and whole-food positioning. Premium pricing tolerance runs highest in this channel due to self-selected health-conscious demographics.
- Hospitals:Inpatient formulary inclusion and discharge prescription protocols. Abbott Laboratories anchors this channel through institutional contracting relationships.
Pharmacies dominate installed base. Online retail is gaining share fastest.
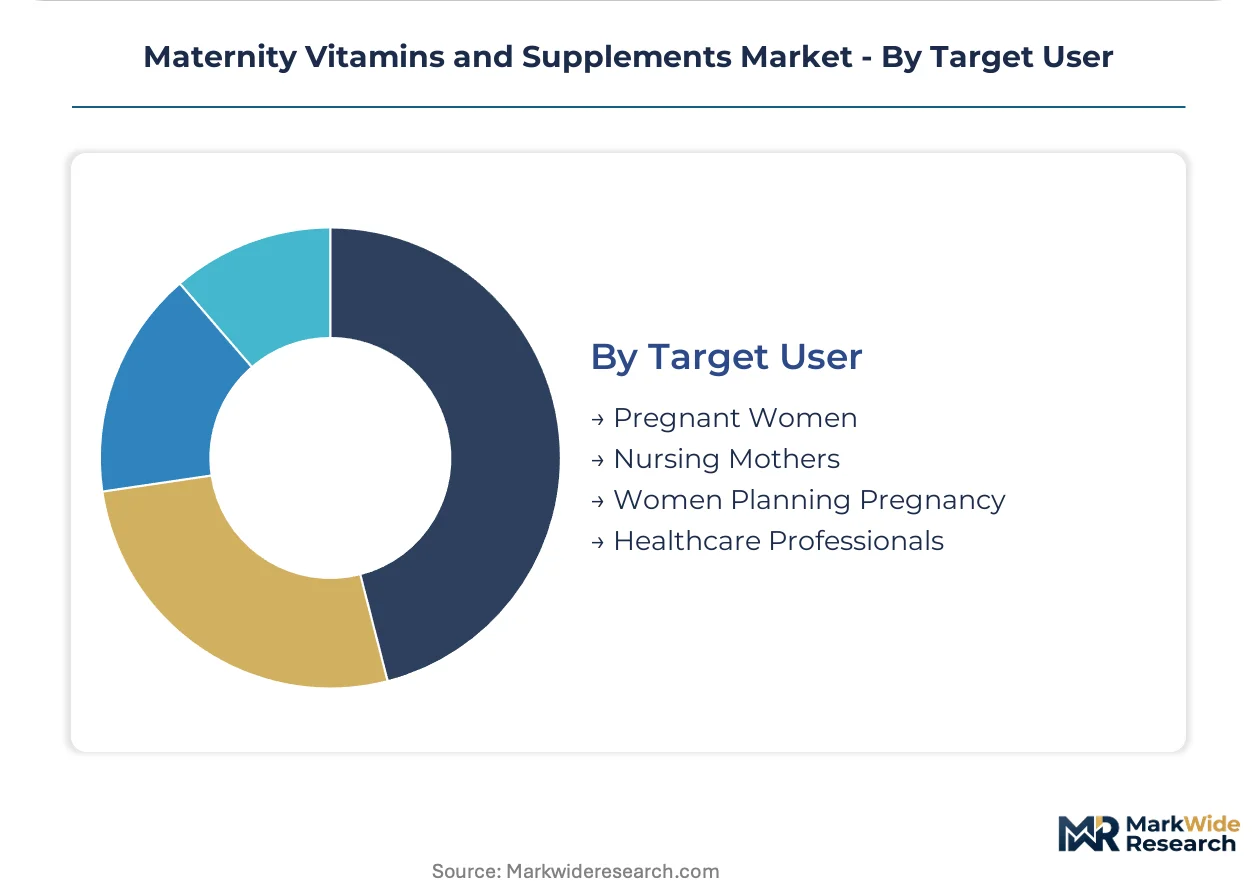
Target User:
Life-stage positioning and recommendation authority differentiate demand profiles. Self-directed purchasing characterizes pre-conception segments, while clinical oversight intensifies through gestation and lactation.
- Pregnant Women:Active gestational consumers following trimester-specific nutrient protocols. First-trimester folic acid emphasis shifts toward iron and DHA prioritization in second and third trimesters.
- Nursing Mothers:Lactational consumers addressing nutrient transfer through breast milk composition. WHO six-month-plus breastfeeding duration recommendations are widening addressable windows.
- Women Planning Pregnancy:Pre-conception consumers initiating folic acid loading three months prior to conception. This segment exhibits highest price sensitivity and brand switching propensity.
- Healthcare Professionals:Prescribing obstetricians, midwives, and nurse practitioners driving formulary decisions. Professional recommendation remains the dominant demand catalyst across all developed markets.
Pregnant women dominate installed base. Nursing mothers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where direct-to-consumer subscription models command premium positioning, while German pharmacy networks enforce strict behind-counter gatekeeping that compresses margins for non-compliant entrants.
United States
Obstetric protocol standardization and prescription prenatal multivitamin reimbursement drive institutional formulary inclusion. FDA Current Good Manufacturing Practice enforcement filters marginal producers from pharmacy and hospital channels. Direct-to-consumer platforms in coastal metropolitan markets capture prescription-adjacent recommendation flows through telehealth partnerships.
Germany
Midwifery network DHA recommendation expansion and mandatory pharmacy placement sustain professional channel dominance. EFSA health claims processes tighten permissible gestational benefit marketing language, extending launch timelines. Berlin and Munich health store clusters prioritize organic certification and whole-food positioning for premium maternal demographics.
United Kingdom
NHS prenatal care pathways and six-month-plus breastfeeding duration recommendations widen lactation support addressable windows. UK-specific EFSA enforcement strictness forces folic acid promotional material reformulation. London subscription-service adoption leads national channel migration toward digital replenishment models.
Australia
Liquid format preference among dysphagia-conscious consumers and capital city direct-to-consumer platform penetration accelerate non-tablet formulation growth. TGA pregnancy supplement classification governs permissible indication claims and adverse event reporting. Sydney and Melbourne telehealth-integrated maternal health startups bridge professional recommendation with digital acquisition.
Netherlands
Midwifery-led prenatal care models and elevated DHA recommendation rates among primary maternity providers sustain omega-3 category expansion. EFSA health claims pre-substantiation requirements constrain new entrant promotional strategies. Randstad region health store networks emphasize algal-derived vegan DHA alternatives for dietary-restricted maternal segments.
Maternity Vitamins and Supplements Market Competitive Environment
Pharmaceutical conglomerates and organic-certified specialists split the market between institutional credibility and premium whole-food positioning. Abbott Laboratories anchors hospital formulary acceptance through discharge protocol integration. Bayer AG leverages prenatal brand heritage across European and North American pharmacy networks. Garden of Life differentiates through organic certification in premium health store channels. Competitive moves concentrate on subscription-model customer acquisition and algal DHA technology licensing for plant-derived alternatives.
Within the pharmaceutical conglomerate tier, Abbott Laboratories and Bayer AG exemplify institutional channel dominance, while Garden of Life occupies a position representing organic-certified whole-food differentiation. These three anchors illustrate the strategic bifurcation between hospital-clinical credibility and premium retail positioning that defines competitive dynamics across developed markets.
| Leading Market Players |
|---|
| Nature Made |
| Bayer AG |
| Abbott Laboratories |
| Nestlé Health Science |
| Garden of Life |
| Vitabiotics |
| Church & Dwight Co., Inc. |
| MegaFood |
| New Chapter |
| Others |
Value Chain & Pricing Dynamics
Marine-derived DHA supply concentration in Peruvian and North Atlantic fisheries determines both the premium-to-economy price spread and the geographic configuration of omega-3 sourcing networks. This single-source dependency forces manufacturers to absorb quota volatility or pass cost spikes through to subscription and pharmacy channels.
Pricing Analysis
The customization-premium spread separates methylfolate and algal DHA formulations from standard ferrous sulfate and synthetic folic acid offerings. Three-tier pricing structure across premium, standard, and economy levels reflects bioavailability enhancement, organic certification, and professional endorsement intensity. Pricing pressure stems from DHA raw material volatility as El Niño disruptions tighten Peruvian anchovy quotas. Price-sensitive pre-conception consumers drive economy tier volume, while insured pregnant populations through pharmacy benefit managers absorb premium positioning with minimal friction.
Supply Chain Analysis
Supplier-financing facilities from Norwegian and Peruvian fishery processors extend payment terms for DHA concentrate offtake agreements. Raw material sourcing draws from marine fisheries in Peru and Norway, algal cultivation facilities in Germany and the Netherlands, and excipient suppliers in India and China. Single-source vulnerability concentrates in Peruvian anchovy quotas governing premium triglyceride DHA availability. Distribution runs through FDA-registered softgel encapsulation contractors in the United States and EMA-compliant facilities in Germany and Switzerland before pharmacy and direct-to-consumer fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as WHO six-month-plus breastfeeding recommendations extend addressable windows beyond traditional prenatal-only positioning. Direct-to-consumer subscription penetration among millennial maternal demographics creates durable recurring revenue pools.
For Market Incumbents: Harden formulary lock-in through hospital discharge protocol integration and pharmacy benefit manager contracting. Deepen backward integration into algal DHA cultivation to offset marine fishery quota volatility. Secure EFSA health claims pre-authorization to extend European promotional runway ahead of competitor launches. For New Entrants and Emerging Players: Establish a beachhead in vegan algal DHA for dietary-restricted maternal segments underserved by marine-sourced incumbents. Target Australian liquid format preference and UK subscription-service adoption as white-space geographies with lower pharmacy channel gatekeeping. Deploy telehealth-integrated influencer obstetrician networks to capture prescription-adjacent recommendation flows without institutional formulary investment. For Investors and Strategic Acquirers: FDA Current Good Manufacturing Practice enforcement reshapes the acquisition landscape by filtering marginal producers and consolidating shelf space for compliant manufacturers. Five-to-ten year viability favors targets with dedicated regulatory affairs infrastructure spanning DSHEA and EFSA processes. Watch EFSA methylfolate and algal DHA health claims authorization timelines as inflection indicators for premium positioning legitimacy.| Strategic Initiative | Industry Significance |
|---|---|
| Algal DHA Technology Licensing | Plant-derived omega-3 sourcing captures vegan maternal demographics previously excluded from marine products. |
| Pharmacy Benefit Manager Integration | Supplement inclusion in employer health spending accounts reduces out-of-pocket price sensitivity for insured US populations. |
| EFSA Health Claims Pre-Authorization | Pre-substantiated gestational benefit language extends European promotional runway and accelerates launch timelines. |
| Direct-to-Consumer Subscription Launch | Recurring revenue structures reduce customer acquisition costs and improve lifetime value metrics in coastal metropolitan markets. |
| Liposomal Encapsulation Adoption | Phospholipid-bound nutrient formats command 40-60% price premiums through bioavailability differentiation in saturated retail environments. |
Study Parameters
Cross-validation between primary interviews with obstetricians, midwives, pharmacy procurement managers, and direct-to-consumer brand executives anchors the qualitative findings against secondary validation from FDA warning letters, EFSA health claims registers, TGA pregnancy supplement classifications, and WHO micronutrient reference value updates. Bottom-up formulation and channel modeling triangulates against top-down maternal health expenditure tracking across national healthcare systems.
Calibration against historical multivitamin and omega-3 adoption curves across the analysis window informs projection elasticity. Segmentation dimensions span product type, formulation technology, distribution channel, and target user life stage. CAGRs derive from fitted adoption curves adjusted for professional recommendation intensity and subscription penetration rates. DHA clinical positioning velocity and methylfolate MTHFR polymorphism awareness serve as category-specific forecast inputs.
Sensitivities concentrate around El Niño fishery disruption, EFSA health claims authorization delays, and pharmacy benefit manager coverage expansion. Forecasts reflect assumptions on professional recommendation rates and subscription retention curves. Macroeconomic contraction in maternal health spending, regulatory reclassification of prenatal supplements as pharmaceuticals, or breakthroughs in food-based nutrient delivery would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Oyster Shell Calcium Market
Nutritional Supplements
Organic Protein Powder Market
Nutritional Supplements
Mood Support Supplements Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Fatty Acid Supplements Market
Nutritional Supplements
North America Protein Market
Nutritional Supplements
Australia Nutraceuticals Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market
Nutritional Supplements
Hair Growth Supplements Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
Personalized Nutrition and Supplements Market
Nutritional Supplements
Chewable Energy Tablet Market
Nutritional Supplements
North and South America Mineral Supplement Tablets Market
Nutritional Supplements
Australia Whey Protein Market
Nutritional Supplements
Ferrous Fumarate Market
Nutritional Supplements
Asia-Pacific Collagen Peptide Products Market