
 Europe Feed Amino Acids Market | 2026-2036
Europe Feed Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Amino Acids Market Foresight
The EU Green Deal is repositioning amino acid procurement standards across European livestock operations. Evonik Industries AG leverages its backward integration into methionine precursors to sustain cost advantages in German and Dutch supply corridors. Adisseo anchors its competitive stance through dedicated European production infrastructure for liquid methionine formulations. DSM differentiates via advanced fermentation platforms that occupy the high-purity lysine tier for precision swine nutrition.
Feed amino acids are nitrogen-containing organic compounds produced through microbial fermentation or chemical synthesis, typically specified at minimum purity thresholds of 98.5 percent for crystalline grades and formulated to precise digestible amino acid coefficients for monogastric species. Their primary commercial purpose is to balance cereal-soybean meal matrices, reducing crude protein levels while maintaining performance benchmarks and lowering nitrogen excretion in intensive livestock systems. Lysine commands the largest volume position across European compound feed production, while methionine captures premium pricing in poultry layer and broiler segments where sulfur amino acid requirements exceed plant-source availability. The aquaculture animal type represents the fastest-expanding application dimension, driven by Atlantic salmon and rainbow trout producers in Norway and Scotland substituting fishmeal with crystalline amino acid packages.
The European Food Safety Authority and REACH frameworks govern feed additive authorization and chemical safety documentation, creating compliance thresholds that filter non-European suppliers from the authorized substance register. The EU F-Gas Regulation and national ammonia emission ceilings under the National Emission Reduction Commitments Directive further shape product specifications by rewarding low-excretion amino acid formulations in intensive livestock regions. Stakeholders must monitor the convergence of CSRD sustainability disclosure rules with feed chain certification requirements, as this intersection will determine which amino acid suppliers retain preferred supplier status with integrated protein companies.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing nitrogen excretion thresholds across intensive livestock zones, forcing compound feed manufacturers to reformulate crude protein matrices with crystalline amino acid precision. This regulatory compression is reshaping procurement specifications and supplier qualification criteria simultaneously.
Growth Catalysts
- REACH Authorization:The EU chemical safety framework mandates rigorous substance documentation that elevates established European amino acid producers above non-registered importers, tightening the authorized supplier pool.
- Aquaculture Substitution:Norwegian and Scottish Atlantic salmon producers are displacing fishmeal with crystalline lysine-methionine packages, opening volume expansion in marine feed formulations.
- Precision Fermentation:Advanced microbial production platforms are enabling higher-purity lysine grades that meet digestible amino acid coefficients for precision swine nutrition protocols.
Market Restraints
- Feedstock Volatility:Corn and molasses input costs fluctuate with biofuel policy arbitrage, compressing fermentation-based amino acid margins unpredictably.
- Production Concentration:German and Dutch chemical corridors host disproportionate methionine precursor capacity, creating geographic supply vulnerability to regional energy price spikes.
- Regulatory Friction:EFSA novel feed additive authorization timelines extend 18-24 months, delaying market entry for innovative amino acid derivatives.
Strategic Opportunities
- Poland Poultry Expansion:Industrialized broiler operations in Greater Poland Voivodeship are underpenetrated for liquid methionine adoption relative to German benchmarks.
- CSRD Disclosure Convergence:Corporate sustainability reporting mandates are creating preferred supplier status for amino acid producers with verified Scope 3 documentation.
- Enzyme-Amino Acid Bundling:Phytase-crystalline lysine co-formulations are emerging as a technical convergence that reduces phosphorus excretion while optimizing digestible protein.
Industry Challenges
- Fermentation Specialist Scarcity:Industrial microbiology and downstream processing expertise pools concentrate at legacy chemical firms, constraining talent mobility for newer market entrants.
- Legacy System Integration:Compound feed mills operate 1990s-era batch control architecture that complicates precision amino acid dosing automation and real-time formulation adjustment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Amino Acids Market |
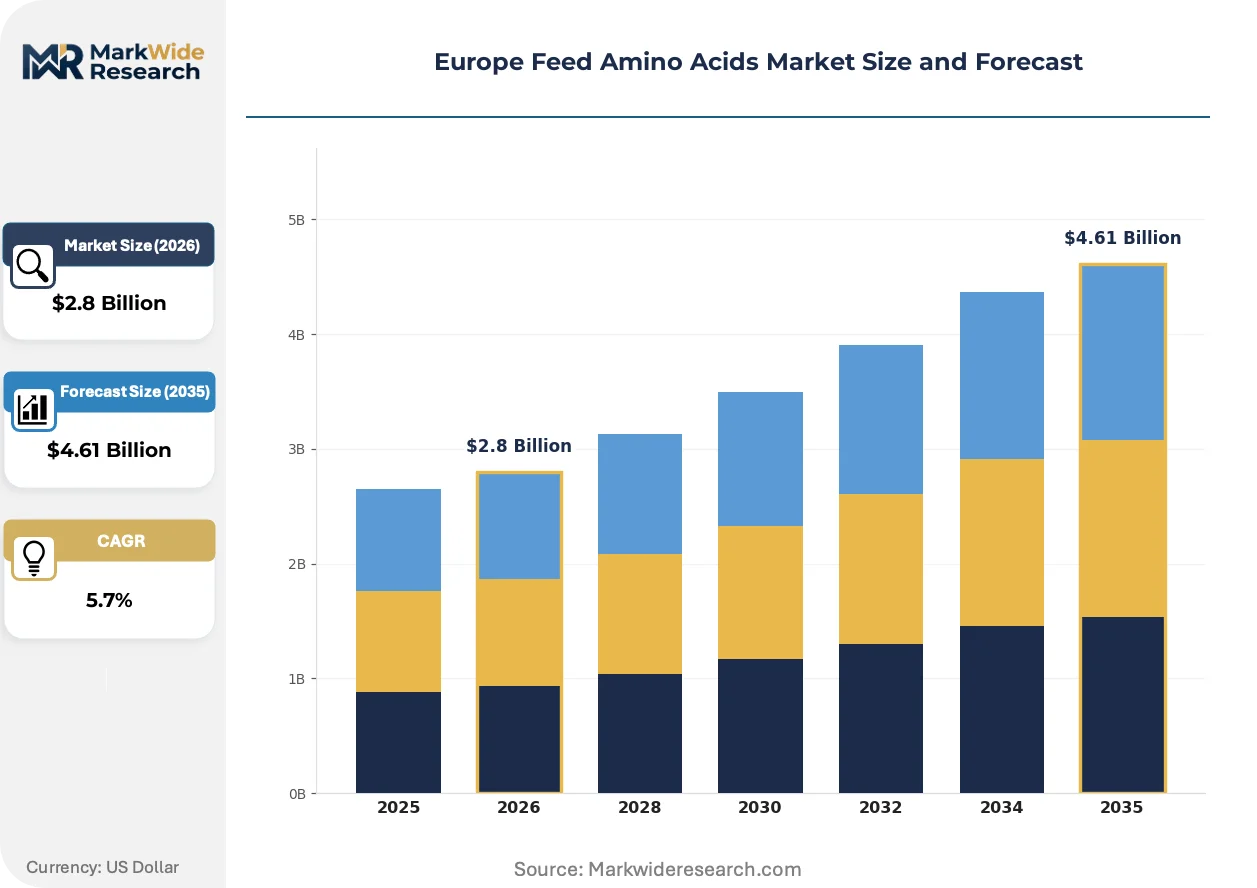
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lysine, Methionine, Threonine, Tryptophan Animal Type: Poultry, Swine, Aquaculture, Ruminants Form: Liquid, Powder, Granular, Tablet Distribution Channel: Online, Offline, Retail, Wholesale |
| Companies Covered | Evonik Industries AG, Adisseo, Archer Daniels Midland, Ajinomoto, DSM, Nutreco, Kyowa Hakko Europe GmbH, Cargill, Kemin Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Amino Acids Market Shifts & Advancements
European feed amino acid production is pivoting toward closed-loop fermentation systems and digital formulation platforms that synchronize real-time crop composition data with precision dosing. These technical shifts are compressing the gap between laboratory-grade purity and field-scale application consistency.
Fermentation-based lysine production is consolidating around single-strain microbial platforms with enhanced carbon yield efficiency. Spanish and German compound feed manufacturers are adopting these high-purity grades for low-protein swine rations at accelerating rates. This technology compression is displacing lower-tier crystalline suppliers who lack backward integration into precursor fermentation capacity.
EFSA's tightened guidance on feed additive environmental claims is reshaping product registration strategies across European amino acid portfolios. The regulatory pressure is forcing suppliers to generate nitrogen excretion reduction data under standardized trial protocols. Poultry layer operations in the Netherlands face the steepest compliance burden, driving accelerated adoption of documented low-excretion methionine formulations.
Compound feed procurement teams are consolidating amino acid purchasing through integrated protein company supply agreements rather than spot market transactions. This channel compression is disintermediating traditional distributor networks in favor of direct manufacturer relationships. German industrialized pork producers are leading this behavioral shift, leveraging volume commitments to secure preferential lysine pricing and technical service bundling.
Europe Feed Amino Acids Market Segmentation
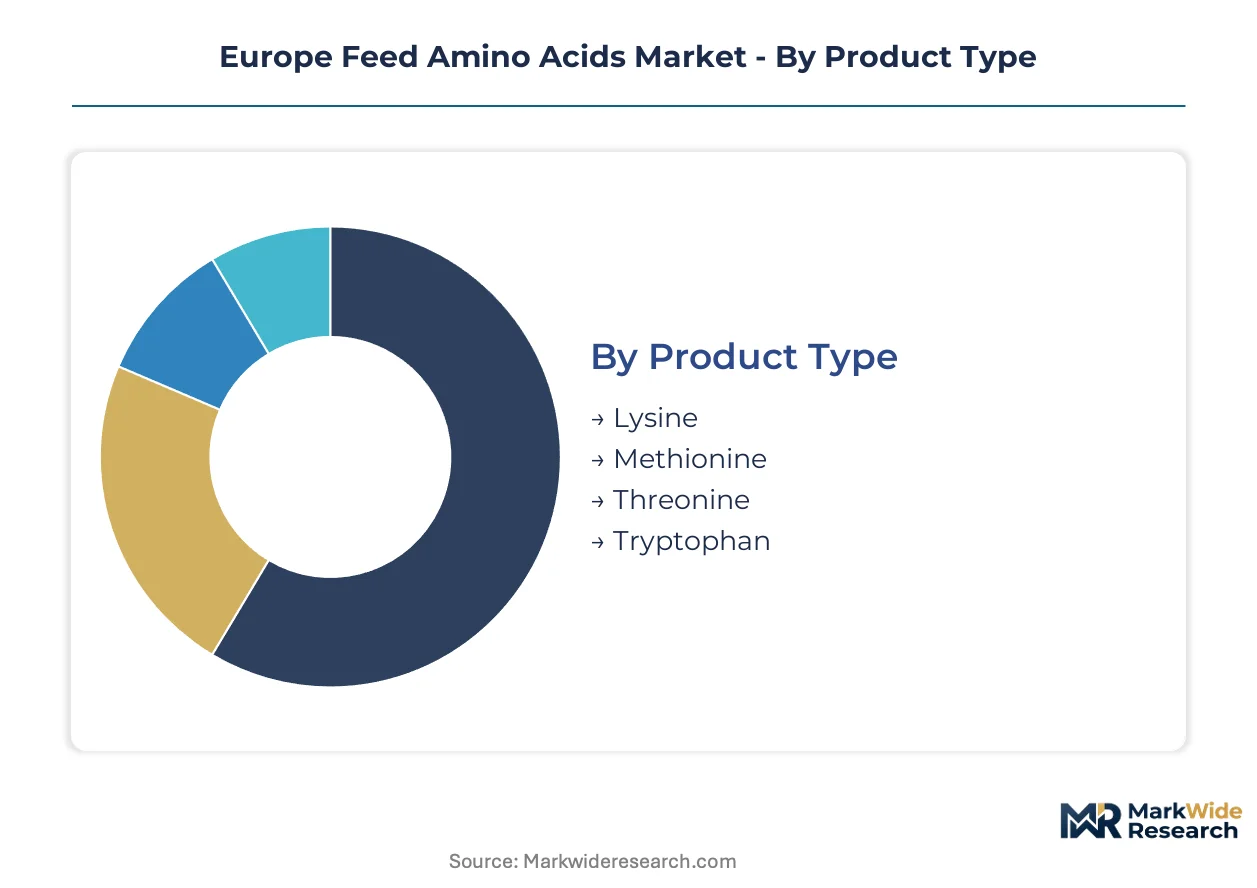
Feed amino acid procurement in Europe fragments across four critical dimensions: product chemistry, target species, physical formulation, and channel architecture. Each axis carries distinct margin profiles and regulatory exposure that shape supplier strategy.
Product Type:
Cost tier differentiation separates commodity-grade amino acids from precision-fermented high-purity grades demanded by premium livestock operations.
- Lysine:Crystalline L-lysine produced via Corynebacterium glutamicum fermentation dominates European compound feed formulations. German and Polish swine producers specify minimum 98.5% purity grades for low-protein ration protocols under EU Green Deal nitrogen caps.
- Methionine:DL-methionine and liquid hydroxy-analogue formulations command premium positioning in poultry layer operations. Dutch and Belgian broiler integrators favor liquid methionine for automated dosing systems in climate-controlled housing.
- Threonine:Second-limiting amino acid for swine and poultry, typically sourced as crystalline feed-grade from Chinese and European fermentation plants.
- Tryptophan:Niche volume position targeting precision-formulated starter diets for weanling piglets and high-performance laying hens.
Lysine leads volumes today; methionine is gaining share fastest through liquid formulation adoption.
Animal Type:
Application-specific digestible amino acid coefficients drive formulation complexity across monogastric and ruminant species.
- Poultry:Broiler and layer operations in Spain, Germany, and Poland consume the majority of European methionine volumes. Sulfur amino acid requirements exceed plant-source availability, forcing crystalline supplementation at 0.15-0.25% inclusion rates.
- Swine:Industrialized pork production across Denmark, Germany, and the Netherlands deploys lysine-threonine blends for crude protein reduction. EFSA-authorized low-excretion formulations qualify for environmental subsidy programs in intensive livestock zones.
- Aquaculture:Norwegian Atlantic salmon and Scottish rainbow trout producers displace fishmeal with crystalline lysine-methionine packages, expanding fastest among all animal types.
- Ruminants:Protected amino acid products for dairy cattle represent limited penetration due to rumen degradation challenges and higher cost thresholds relative to bypass protein sources.
Poultry leads volumes today; aquaculture is climbing the fastest on marine feed substitution.
Form:
Volume scale and automation compatibility separate industrial-grade physical formats from specialty presentations.
- Liquid:Methionine hydroxy analogue and liquid lysine solutions integrate with automated micro-dosing systems at German and Dutch mega-mills. Bulk tank installations reduce handling labor and dust exposure.
- Powder:Standard crystalline grades for batch mixing operations at mid-scale compound feed manufacturers across Poland and Spain.
- Granular:Dust-free handling characteristics preferred by pre-mix specialists and smaller feed mills with limited pneumatic conveying infrastructure.
- Tablet:Niche presentation for on-farm top-dressing applications and specialty mineral-amino acid co-formulations.
Powder leads volumes today; liquid is expanding most quickly through mega-mill automation.
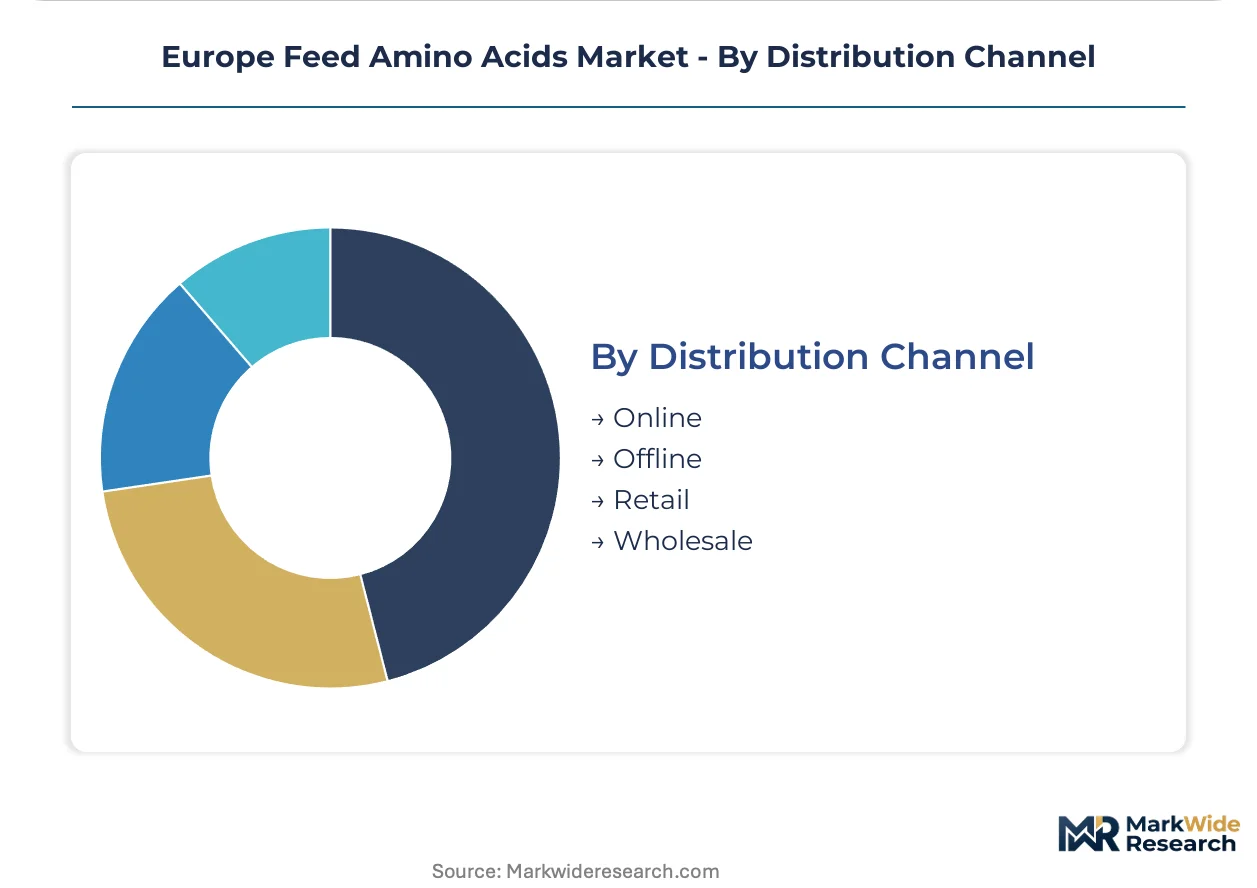
Distribution Channel:
Customer type and procurement sophistication determine channel selection across integrated protein companies and independent feed manufacturers.
- Offline:Direct manufacturer relationships and technical service bundling dominate German industrialized pork and poultry procurement. Volume commitments secure preferential lysine pricing and formulation support.
- Wholesale:Regional distributors serve mid-scale Polish and Spanish compound feed mills with consolidated amino acid and vitamin offerings.
- Online:Emerging platform procurement for smaller livestock operations and specialty pre-mix formulators seeking spot price transparency.
- Retail:Limited penetration through agricultural supply cooperatives serving hobby farmers and smallholder poultry producers.
Offline leads volumes today; online is gaining share fastest among smaller formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed amino acid production in Europe traces its industrial lineage to post-war chemical corridors in Germany and the Netherlands, where petrochemical infrastructure first enabled synthetic methionine synthesis during the 1960s. These Rhine-Ruhr and Rotterdam-Antwerp clusters remain the continent's primary manufacturing nodes today. Regulatory pressure from the EU Green Deal now forces geographic diversification of procurement patterns across the region.
Germany
Industrialized pork and poultry operations in Lower Saxony and North Rhine-Westphalia consume the majority of domestic lysine volumes. The F-Gas Regulation imposes strict ammonia emission ceilings on intensive livestock zones, accelerating adoption of low-excretion amino acid formulations. Chemical production corridors around Marl and Ludwigshafen host backward-integrated methionine precursor capacity that supplies compound feed manufacturers across Central Europe.
Netherlands
Broiler integrators in Gelderland and Noord-Brabant favor liquid methionine hydroxy analogue for automated dosing in climate-controlled housing systems. REACH authorization requirements filter non-registered amino acid importers from the authorized substance register. The Port of Rotterdam serves as the primary import gateway for fermentation-based lysine originating from Asian production facilities.
Spain
Poultry layer operations in Catalonia and Aragón drive methionine consumption as sulfur amino acid requirements exceed local soybean meal availability. EFSA novel feed additive authorization timelines extend market entry delays for innovative amino acid derivatives. Compound feed mills around Lleida and Zaragoza are consolidating procurement through direct manufacturer relationships rather than distributor networks.
Poland
Industrialized broiler production in Greater Poland Voivodeship remains underpenetrated for liquid methionine adoption relative to German technical benchmarks. National ammonia emission commitments under the NECD directive force crude protein reduction in swine rations. Feed manufacturers near Poznań and Wrocław are expanding lysine inclusion rates to meet EU Green Deal nitrogen excretion thresholds.
Norway
Atlantic salmon producers in Vestland and Trøndelag displace fishmeal with crystalline lysine-methionine packages at the fastest rate among all European animal protein sectors. The country's national pharmaceutical regulator enforces strict documentation requirements for feed additive environmental claims. Marine feed compounders around Bergen and Trondheim now specify minimum 98.5% purity grades for precision aquaculture nutrition protocols.
Europe Feed Amino Acids Market Competitive Landscape
Capital-heavy producers compete with asset-light formulators across distinct operational models in the European feed amino acid sector. The market structure concentrates around three to five integrated chemical conglomerates with captive fermentation capacity, while mid-scale distributors and specialty pre-mix formulators occupy fragmented downstream positions. Strategic archetypes separate backward-integrated precursor manufacturers, precision fermentation platform operators, and regional formulation specialists. Capacity expansion and direct procurement relationship-building represent the dominant competitive moves as compound feed mills consolidate purchasing through integrated protein company supply agreements.
Among Germany-based chemical conglomerates, Evonik Industries AG anchors the methionine precursor tier through its Rhine-Ruhr manufacturing footprint. Adisseo occupies a position within the liquid formulation specialist archetype, while DSM exemplifies precision fermentation platform differentiation for high-purity lysine grades. These three entities represent the primary competitive anchors shaping procurement specifications and supplier qualification criteria across European livestock operations.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Adisseo |
| Archer Daniels Midland |
| Ajinomoto |
| DSM |
| Nutreco |
| Kyowa Hakko Europe GmbH |
| Cargill |
| Kemin Industries |
| Others |
Supply & Pricing Matrix
Industrial microbiology and downstream processing expertise pools concentrated in the Rhine-Ruhr and Rotterdam-Antwerp chemical corridors drive labor-cost differentials that widen pricing-tier spreads between precision-fermented high-purity grades and commodity crystalline alternatives. REACH authorization compliance costs and EFSA documentation burdens further stratify procurement economics across European livestock operations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-authorized low-excretion formulations from generic crystalline grades and unregistered imports. Price differentiation rests on certification grade and volume scale, with German industrialized pork producers securing preferential terms through direct manufacturer commitments. Cost compression in the economy tier is intensifying because molasses and corn feedstock arbitrage with biofuel policy erodes fermentation margins. Mid-scale Polish compound feed mills exhibit the highest price sensitivity, while Norwegian Atlantic salmon integrators prioritize purity premiums over unit economics.
Supply Chain Analysis
Bulk liquid methionine hydroxy analogue shipments from Rotterdam and Antwerp face freight cost escalation that compresses margins on long-haul deliveries to Spanish poultry operations. Geographic supply concentration centers on Germany, the Netherlands, and Belgium for methionine precursor capacity, with fermentation-based lysine drawing from Asian production facilities through Rotterdam gateway ports. Raw material dependencies rest on corn and molasses feedstocks, petrochemical-derived precursors, and specialized enzyme catalysts. Single-source vulnerability to regional energy price spikes in the Rhine-Ruhr corridor represents the dominant structural risk. Distribution runs through direct manufacturer relationships with integrated protein companies, disintermediating traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Feed Amino Acids Market functions as a geographic-arbitrage play where Poland's ammonia emission ceilings under the NECD directive impose stricter crude protein reduction mandates than Spanish enforcement patterns, creating divergent lysine demand intensity across otherwise comparable livestock volumes.
For Market Incumbents: Cement backward integration into precursor fermentation capacity to defend margin position against Asian lysine imports and specialty enzyme-amino acid bundling entrants. Prioritize liquid methionine tank infrastructure investments in Greater Poland Voivodeship to capture broiler automation upgrades. EFSA novel feed additive authorization timelines remain the critical regulatory lever for product differentiation. For New Entrants and Emerging Players: Precision fermentation platforms for high-purity threonine grades offer the most penetrable wedge against legacy Corynebacterium glutamicum incumbents. Target Norwegian marine feed compounders seeking documented nitrogen excretion reduction data for environmental claims. A go-to-market angle anchored in CSRD-aligned Scope 3 documentation secures preferred supplier status with sustainability-committed protein integrators. For Investors and Strategic Acquirers: Integrated chemical conglomerates with captive petrochemical infrastructure are the most active acquirer in this space, consolidating methionine precursor capacity and fermentation platforms. Long-term viability across the five-to-ten year horizon depends on backward integration depth and regulatory authorization breadth. Acquisition target archetypes include regional formulation specialists with established EFSA dossiers and underutilized fermentation assets. The signal to monitor is REACH substance evaluation expansion that could delist non-registered amino acid imports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Capacity | Chemical conglomerates in the Rhine-Ruhr corridor secure methionine cost advantages against Asian fermentation imports. |
| Liquid Methionine Tank Infrastructure | Automated dosing systems at Dutch and German mega-mills reduce handling labor and dust exposure liabilities. |
| EFSA Low-Excretion Formulation Registration | Documented nitrogen reduction data qualifies suppliers for environmental subsidy programs in Dutch poultry zones. |
| CSRD-Aligned Scope 3 Documentation | Verified carbon footprint reporting secures preferred supplier status with German industrialized pork integrators. |
| Precision Fermentation Platform Expansion | Single-strain microbial systems with enhanced carbon yield efficiency displace lower-tier crystalline lysine suppliers. |
Research Methodology
Multiple input streams — primary interviews with compound feed procurement directors, fermentation plant managers, and EFSA regulatory affairs specialists; secondary validation through customs trade data, Cefic chemical industry reports, and SEC 10-K filings of listed chemical conglomerates; and bottom-up volume modeling against top-down market sizing — were reconciled to construct segment-level demand estimates across the analysis window.
Cross-referencing historical lysine and methionine price series against panel input from procurement executives at German and Dutch integrated protein companies anchored the forecast framework. Segmentation dimensions modeled include product chemistry tier, target species application, physical formulation type, and channel architecture. CAGRs were derived through exponential smoothing of annual volume trajectories, with feedstock cost indices and regulatory compliance timelines serving as industry-specific forecast inputs.
The model holds under stable REACH authorization enforcement and consistent EU Green Deal nitrogen cap implementation; deviation in biofuel policy arbitrage or regional energy price spikes would shift margin compression patterns across fermentation-based production. Stakeholders should weight assumptions against their own operating context and procurement contract structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Alfalfa Powder Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Copra Meal Market
Agricultural Commodities
Feed Yeast Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Beet Pulp Pellets Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Africa Feed Amino Acids Market
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
Peat Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market