
 Asia-Pacific Crypto Payment Gateway Market | 2026-2036
Asia-Pacific Crypto Payment Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Crypto Payment Gateway Market Insights
Singapore's licensing regime for digital payment token services is reshaping competitive entry across the Asia-Pacific corridor. Binance Pay leverages its exchange-derived liquidity to sustain low-fee merchant settlement in ASEAN markets. Coinbase Commerce anchors compliance-heavy positioning through its adherence to Singapore's Monetary Authority licensing requirements. Alchemy Pay competes on fiat-crypto bridge infrastructure, occupying a distinct niche in Southeast Asian remittance corridors.
A crypto payment gateway is a software layer that validates blockchain transactions, manages wallet address generation, and converts volatile digital assets into merchant-denominated fiat through integrated exchange APIs. The system relies on confirmation-depth thresholds and real-time price oracles to mitigate settlement risk during high-volatility windows. API Integration dominates enterprise deployment, with margin pools concentrating where developers demand customizable webhook architectures for inventory and accounting systems. Micro Transactions show structural momentum across gaming and content platforms, where near-zero base-layer fees on alternative L1 networks undercut traditional card processing economics. Hosted Solutions retain traction among small retail merchants lacking technical infrastructure, though this segment faces compression from no-code plugin alternatives.
Singapore's Monetary Authority enforces strict reserve and anti-money laundering standards for payment token licensees, elevating compliance costs but filtering out unregulated operators. Japan's Payment Services Act and Financial Services Agency oversight mandate segregated cold-wallet custody and third-party security audits, directly shaping product architecture for gateway providers serving Japanese merchants. South Korea's Financial Services Commission imposes real-name verification linkage for all crypto-fiat conversions, creating a bifurcated market between compliant licensed gateways and informal channels. Stakeholders must monitor whether India's pending cryptocurrency legislation introduces a formal central bank digital currency gateway mandate that would displace private settlement infrastructure.
Market Dynamics
Stablecoin settlement rails are compressing cross-border remittance timelines across Southeast Asian merchant corridors, forcing gateway providers to rebuild core infrastructure around dollar-pegged liquidity pools rather than volatile crypto-native assets.
Growth Catalysts
- Japan's Payment Services Act amendments:Segregated cold-wallet custody mandates are filtering out unregulated operators and concentrating licensed gateway deployment among compliant infrastructure providers.
- E-commerce checkout integration:Southeast Asian platforms are embedding digital-asset payment options to capture unbanked consumer segments excluded from card networks.
- Real-time settlement infrastructure:South Korea's existing instant payment rails are enabling sub-second crypto-fiat conversion that merchant acquirers leverage for working capital efficiency.
Market Restraints
- Reserve backing requirements:Singapore's Monetary Authority mandates 100% liquid asset coverage for payment token licensees, elevating working capital intensity beyond unregulated competitors.
- Real-name verification linkage:South Korea's Financial Services Commission requires bank-account tethering for all conversions, creating onboarding friction that informal channels exploit.
- Base-layer fee volatility:Ethereum mainnet gas spikes during network congestion periodically erode merchant margin economics versus fixed-fee card processing.
Strategic Opportunities
- India's pending CBDC gateway mandate:Draft legislation may displace private settlement infrastructure with central bank digital currency rails, creating first-mover positioning for licensed bridge providers.
- Micro-transaction gaming corridors:Alternative L1 networks with near-zero fees are unlocking content-platform monetization models previously uneconomical under card minimums.
- Remittance corridor specialization:Philippines-to-Singapore worker payment flows remain underpenetrated by compliant gateways, offering volume concentration for fiat-crypto bridge operators.
Industry Challenges
- Webhook architecture talent scarcity:Enterprise merchants demand customizable API integrations for inventory and accounting systems, but qualified blockchain developers command premium compensation in Singapore and Tokyo labor markets.
- Multi-jurisdiction compliance synchronization:Gateway providers serving Japanese and South Korean merchants simultaneously face divergent audit timelines, security standards, and reporting cadences that strain operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Crypto Payment Gateway Market |
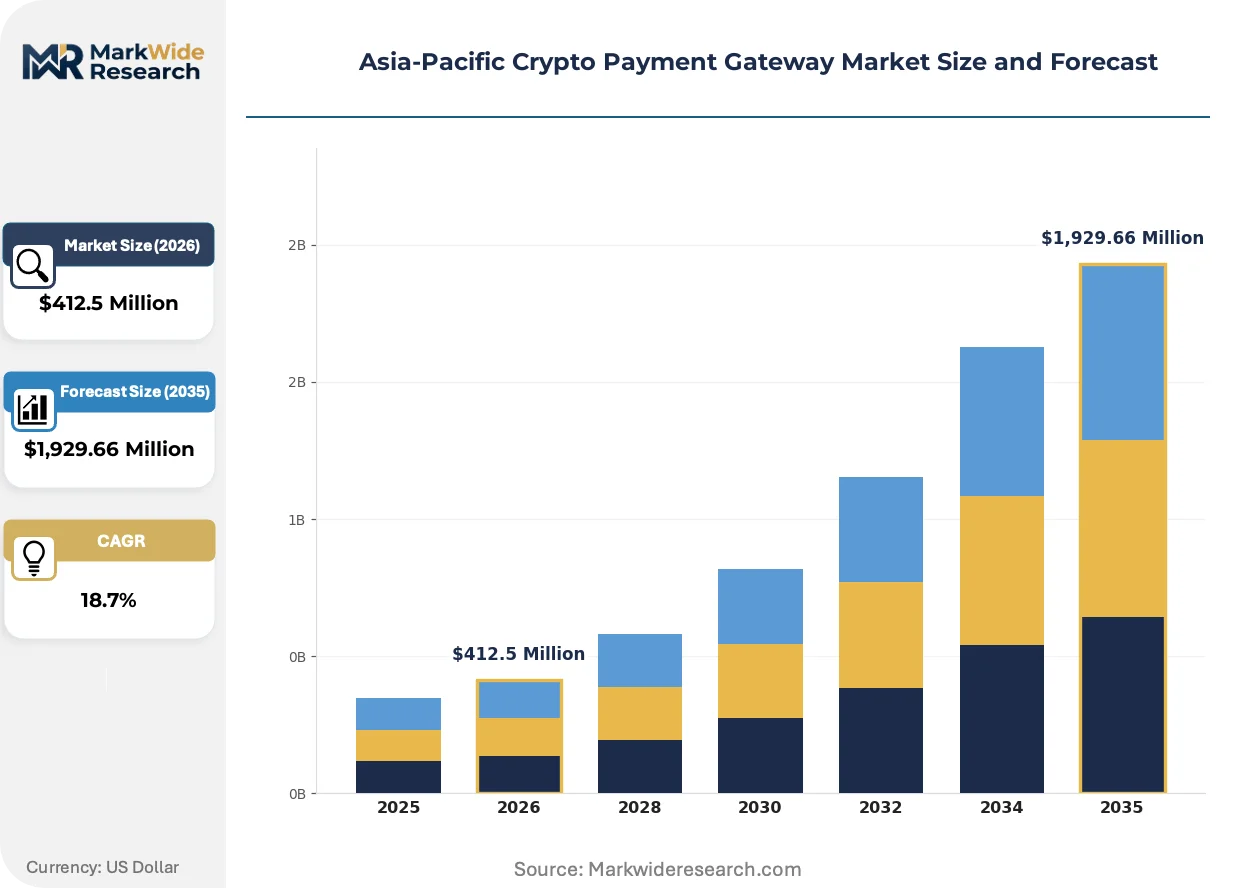
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Bitcoin, Ethereum, Litecoin, Ripple Transaction Size: Micro Transactions, Small Transactions, Medium Transactions, Large Transactions End User: Retail Merchants, Online Services, E-commerce Platforms, Non-profits Integration Type: API Integration, Plugin Solutions, Hosted Solutions, Custom Solutions |
| Companies Covered | BitPay, CoinGate, Coinbase Commerce, Binance Pay, TripleA, Crypto.com Pay, CoinPayments, Alchemy Pay, NOWPayments, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Crypto Payment Gateway Market Trends and Innovations
Payment infrastructure across Asia-Pacific is bifurcating between compliance-heavy licensed channels and experimental Layer-2 settlement rails, with merchant adoption patterns diverging sharply by jurisdiction and transaction size.
Layer-2 rollup architectures are hybridizing Ethereum mainnet security with sub-cent transaction economics. Gaming platforms and content micro-monetization services in Vietnam and the Philippines are migrating settlement volumes to these networks, compressing effective processing costs below traditional card interchange floors and enabling transaction sizes previously uneconomical for merchant acceptance.
Singapore's Monetary Authority licensing framework for digital payment token services is mandating segregated custody, reserve transparency, and real-time audit access. Licensed gateway providers are rebuilding product architecture around cold-wallet multi-signature schemes and third-party security attestations, while unregulated operators face systematic exclusion from banking partnerships and merchant acquiring relationships.
Merchant procurement of payment infrastructure is fragmenting by transaction archetype. Large e-commerce platforms in Indonesia and Thailand are demanding API-native customization for complex inventory reconciliation, while small retail merchants in Malaysia are migrating toward no-code plugin solutions that eliminate technical deployment costs. This bifurcation is compressing hosted solution margins while elevating developer-tooling valuations.
Asia-Pacific Crypto Payment Gateway Market Segmentation
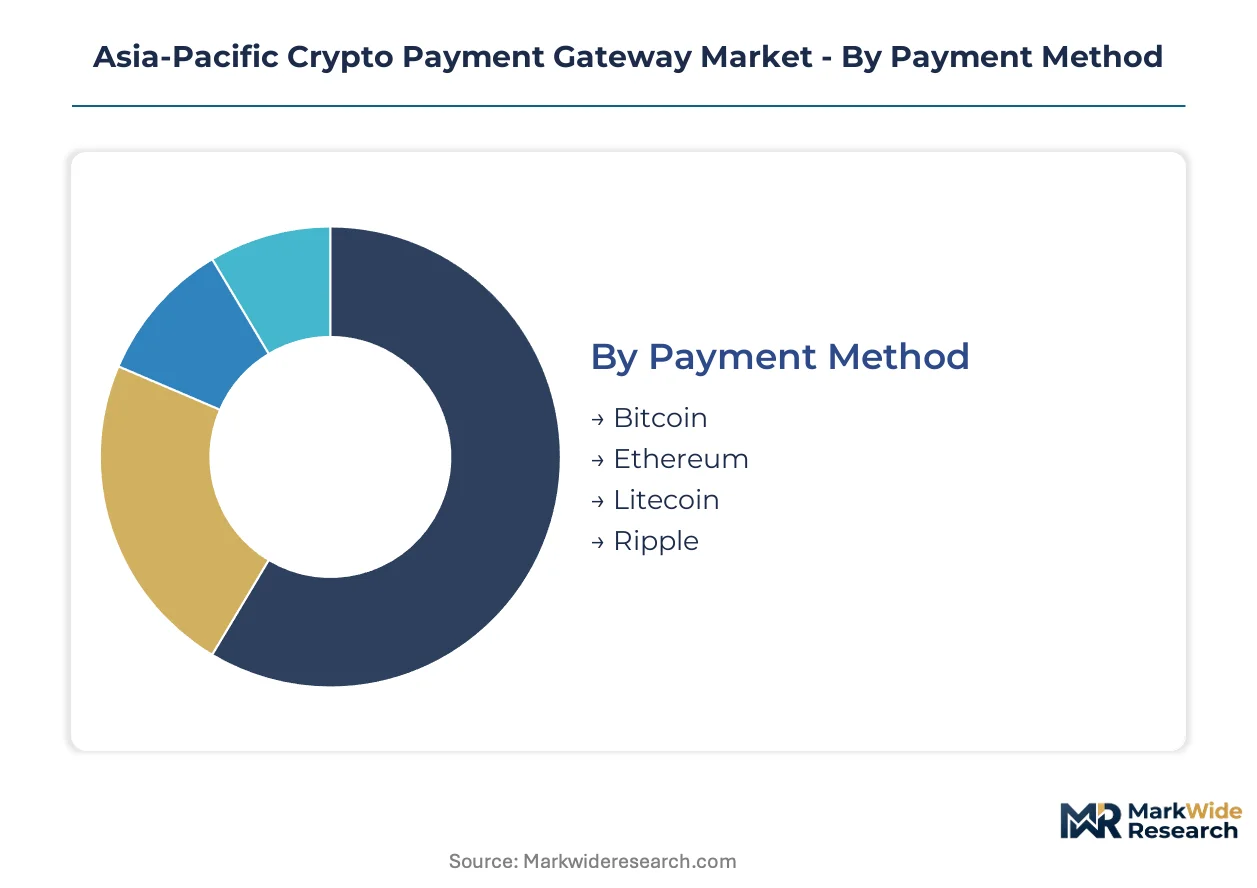
Asia-Pacific gateway providers architect product tiers around settlement velocity, compliance exposure, and technical integration depth. Merchant procurement patterns diverge sharply across these dimensions, with e-commerce platforms in Indonesia and Thailand demanding API-native customization while Malaysian small retailers favor no-code deployment.
Payment Method:
Cost tier determines infrastructure requirements, with base-layer fee volatility and confirmation latency shaping merchant acceptance economics.
- Bitcoin:Proof-of-work finality demands six-confirmation thresholds that extend settlement windows to 60 minutes during network congestion. Japanese merchants under FSA custody mandates absorb this latency through segregated cold-wallet architectures, though working capital intensity rises.
- Ethereum:Smart-contract programmability enables automated fiat conversion through integrated DEX liquidity pools. Singaporean licensed gateways leverage this for real-time merchant settlement, though mainnet gas spikes during congestion periodically erode margin economics versus fixed-fee alternatives.
- Litecoin:Faster block times compress confirmation cycles to 2.5 minutes, reducing working capital drag for high-frequency retail corridors in South Korea.
- Ripple:Consensus ledger architecture eliminates mining delays, delivering 3-5 second finality suited to Philippines-Singapore remittance corridors where speed commands premium pricing.
Bitcoin commands the established base. The steepest expansion runs through Ethereum.
Transaction Size:
Volume thresholds dictate risk management architecture, with confirmation-depth requirements and price-oracle refresh rates scaling nonlinearly with exposure.
- Micro Transactions:Sub-dollar settlements on alternative L1 networks undercut card minimums, unlocking gaming and content monetization in Vietnam and the Philippines where near-zero base fees enable previously uneconomical transaction sizes.
- Small Transactions:Daily purchase volumes under $100 dominate South Korean retail penetration, where real-name verification linkage creates compliant onboarding pathways distinct from informal channels.
- Medium Transactions:B2B procurement settlements between $1,000-$10,000 concentrate in Singapore's licensed gateway ecosystem, where 100% reserve backing requirements filter out undercapitalized operators.
- Large Transactions:Institutional treasury conversions above $50,000 demand multi-signature cold custody and third-party security audits mandated by Japan's Payment Services Act amendments.
Micro Transactions are gaining share fastest. Large Transactions anchor fee revenue concentration.
End User:
Customer type determines compliance burden and technical integration depth, with procurement patterns fragmenting between developer-heavy and no-code deployment paths.
- Retail Merchants:Physical point-of-sale acceptance in Malaysia and Thailand favors hosted solutions with minimal technical deployment, though margins compress as no-code plugins displace traditional gateway relationships.
- Online Services:Subscription and SaaS platforms across Southeast Asia demand webhook architectures for automated billing reconciliation, creating talent scarcity premiums in Singapore and Tokyo labor markets.
- E-commerce Platforms:Marketplace operators in Indonesia embed digital-asset checkout to capture unbanked consumer segments excluded from card networks, with API integration dominating enterprise deployment.
- Non-profits:Cross-border donation corridors leverage stablecoin rails to bypass correspondent banking delays, with Philippines-based organizations pioneering compliant gateway adoption for diaspora fundraising.
E-commerce Platforms command the established base. The steepest expansion runs through Online Services.
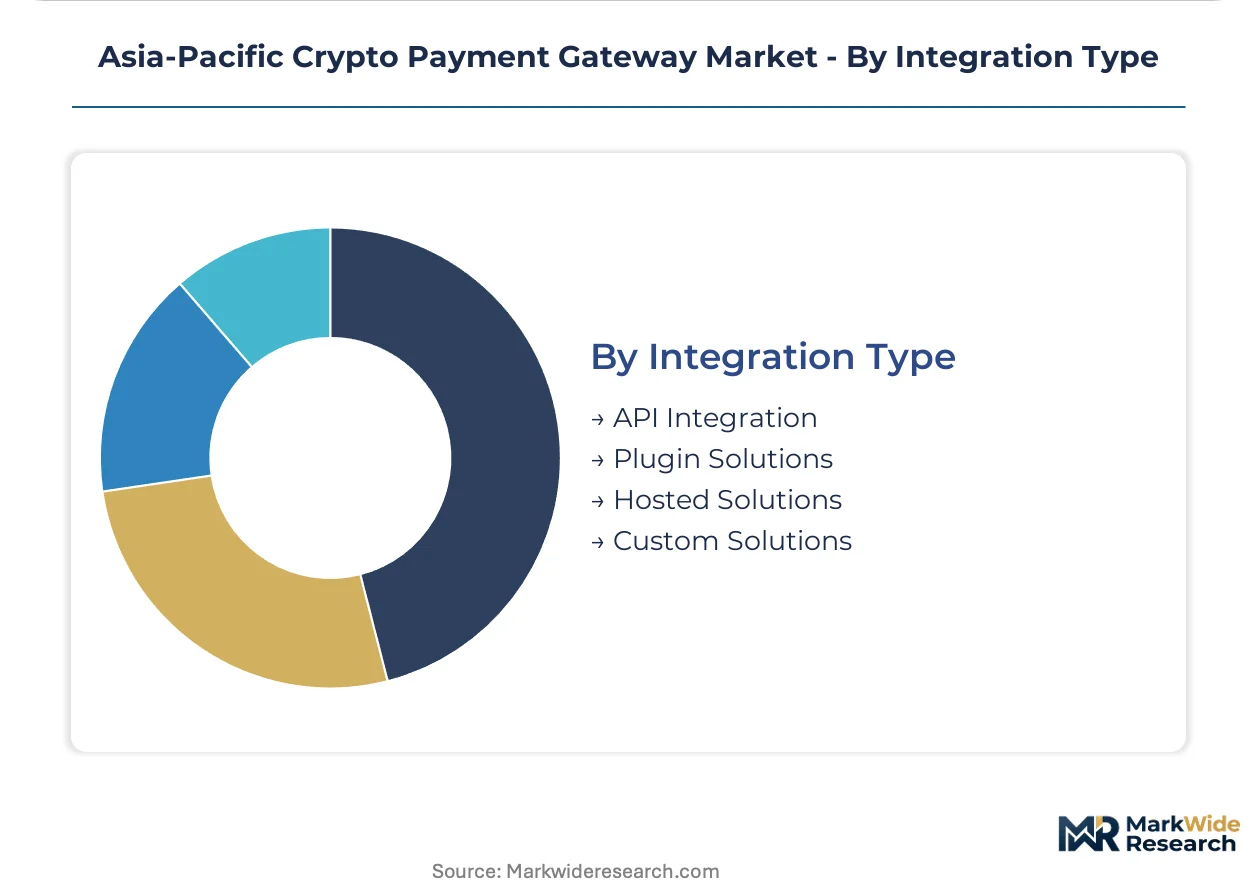
Integration Type:
Technical maturity separates merchant segments, with customization requirements and in-house development capacity determining procurement economics.
- API Integration:Native webhook architectures enable real-time inventory and accounting system synchronization. Large Indonesian platforms demand this tier, though qualified blockchain developers command premium compensation.
- Plugin Solutions:No-code deployment eliminates technical barriers for Malaysian small retailers, compressing hosted solution margins while accelerating merchant onboarding velocity.
- Hosted Solutions:Third-party custody and settlement management retains traction among risk-averse merchants lacking compliance infrastructure, particularly in Japan's FSA-regulated environment.
- Custom Solutions:White-label deployments for regional banks and payment aggregators require multi-jurisdiction compliance synchronization across Japanese and South Korean audit timelines.
API Integration commands the established base. Plugin Solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gateway infrastructure concentrates where regulatory clarity intersects with dense e-commerce penetration. Licensed operators cluster in financial hubs with established digital asset frameworks, while unregulated channels persist in markets with enforcement gaps.
Singapore
Merchant demand concentrates in cross-border B2B settlements and remittance corridors. The Monetary Authority's payment token licensing regime mandates 100% liquid asset coverage and real-time audit access, filtering out undercapitalized competitors. The Raffles Place financial district hosts concentrated gateway development activity as licensed providers build compliance-first infrastructure.
Japan
Retail merchant adoption drives volume in physical point-of-sale and e-commerce checkout integration. The Financial Services Agency enforces segregated cold-wallet custody and third-party security audits through Payment Services Act amendments. Tokyo's Shibuya and Shinjuku commercial districts exhibit dense merchant onboarding as compliant gateways deploy FSA-approved infrastructure.
South Korea
Real-time settlement infrastructure enables sub-second crypto-fiat conversion for high-frequency retail corridors. The Financial Services Commission requires bank-account tethering for all conversions, creating compliant onboarding pathways distinct from informal channels. Seoul's Gangnam and Hongdae districts demonstrate concentrated merchant uptake where licensed gateways leverage existing instant payment rails.
Indonesia
E-commerce platforms embed digital-asset checkout to capture unbanked consumer segments excluded from card networks. The national financial services authority maintains evolving oversight frameworks without formal licensing mandates comparable to Singapore. Jakarta's fintech corridor and Surabaya's logistics hubs attract gateway providers targeting marketplace integration and cross-border trade settlement.
Philippines
Overseas worker remittance flows create demand for stablecoin-based settlement bypassing correspondent banking delays. The central bank maintains progressive digital asset guidelines without restrictive licensing comparable to regional financial hubs. Metro Manila's business process outsourcing clusters and Cebu City's remittance corridors drive merchant adoption for diaspora-facing payment infrastructure.
Asia-Pacific Crypto Payment Gateway Market Competitive Landscape
Exchange-originated platforms and fiat-crypto bridge specialists split the market between liquidity-heavy settlement and compliance-first positioning. Concentration remains moderate as licensing requirements in Singapore and Japan filter participants while informal channels persist in less regulated corridors. Three archetypes dominate: exchange-integrated gateways leveraging proprietary liquidity pools, standalone licensed operators building multi-jurisdiction compliance stacks, and remittance-focused bridge providers targeting specific fiat corridors. Competitive dynamics center on banking partnership acquisition and developer tooling sophistication rather than price competition alone.
Within the exchange-integrated tier, Binance Pay and Coinbase Commerce exemplify divergent geographic strategies. Binance Pay anchors ASEAN market penetration through exchange-derived liquidity advantages. Coinbase Commerce occupies compliance-intensive positioning through Monetary Authority licensing adherence in Singapore. Alchemy Pay represents the fiat-bridge archetype, targeting Southeast Asian remittance corridors where traditional correspondent banking creates settlement friction.
| Leading Market Players |
|---|
| BitPay |
| CoinGate |
| Coinbase Commerce |
| Binance Pay |
| TripleA |
| Crypto.com Pay |
| CoinPayments |
| Alchemy Pay |
| NOWPayments |
| Others |
Pricing and Supply Chain Analysis
Exchange-originated liquidity pools in Singapore and Japan concentrate upstream settlement capacity, directing margin capture toward compliant gateway operators with direct banking partnerships rather than unregulated bridge providers. This concentration elevates working capital requirements for reserve-backed licensing while compressing transactional spreads available to informal channel competitors.
Pricing Analysis
Singapore's Monetary Authority payment token licensing dictates the pricing tier structure across the Asia-Pacific corridor. Three-tier pricing structure across premium, standard, and economy levels separates FSA-compliant Japanese operators with segregated cold-wallet custody from ASEAN no-code plugin providers and unregulated remittance bridges. Price differentiation hinges on certification level (MAS license tier) and customization depth for enterprise webhook architectures. Cost compression in the standard tier is intensifying because no-code alternatives displace traditional hosted solutions. Small retail merchants in Malaysia exhibit highest price sensitivity, while Singaporean B2B platforms prioritize compliance assurance over rate minimization.
Supply Chain Analysis
Upstream fiat-crypto bridge infrastructure draws from banking partnerships concentrated in Singapore, Japan, and South Korea. Core inputs include real-time price oracle feeds, segregated custody hardware security modules, and API middleware for inventory system synchronization. Single-source vulnerability runs through correspondent banking relationships that licensed gateways rely upon for merchant settlement rails. Distribution runs through direct enterprise sales teams for large Indonesian e-commerce platforms, with channel partners handling Malaysian small merchant onboarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
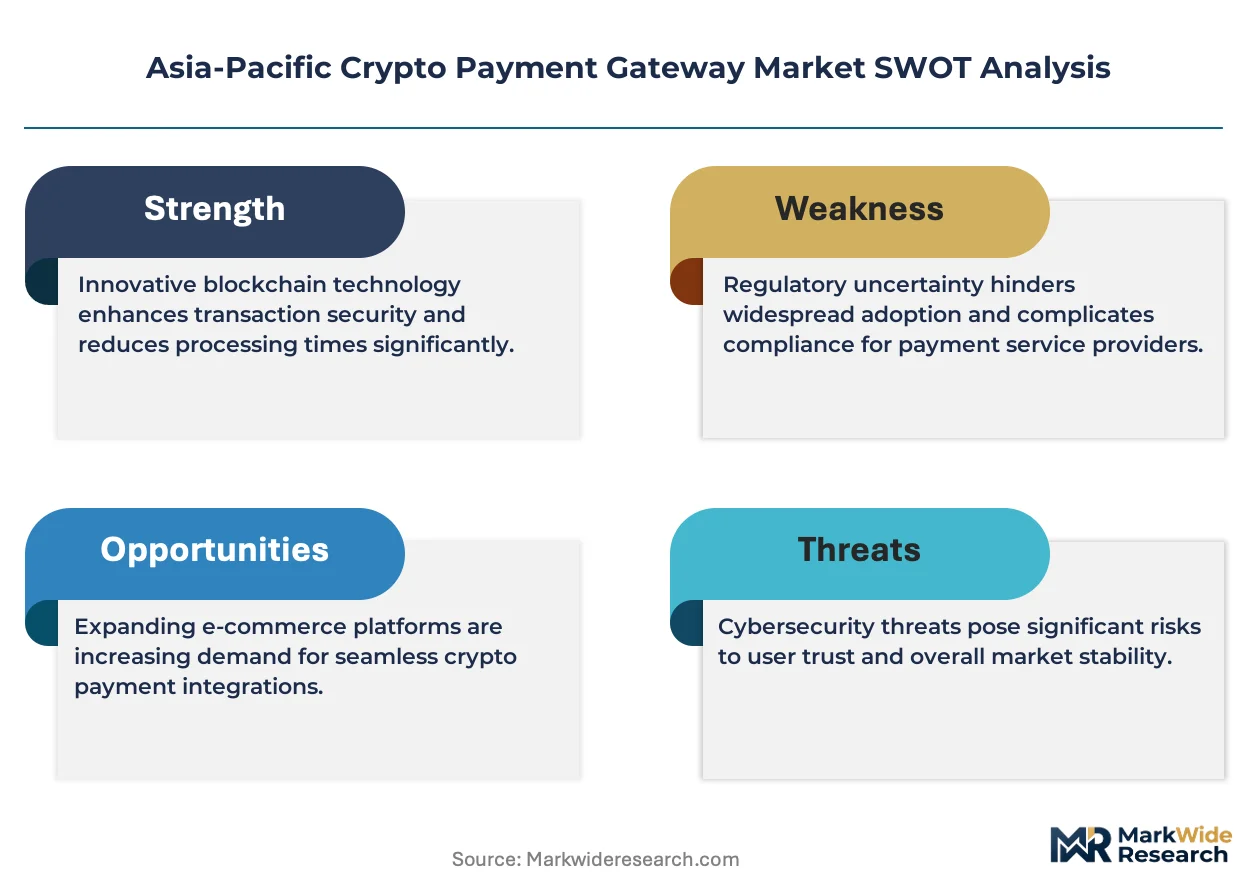
Central bank digital currency rails in India pose a direct substitution threat to private settlement infrastructure, forcing incumbents to defend positioning through compliance deepening and corridor specialization.
For Market Incumbents: Insulate merchant relationships by deepening MAS and FSA license adherence beyond baseline requirements, while building captive stablecoin liquidity pools that informal channels cannot replicate. Vertical integration into cold-wallet custody infrastructure in Tokyo and Singapore reduces third-party security audit dependency. Channel control through exclusive banking partnerships in Seoul's Gangnam commercial district reinforces switching costs against unregulated competitors.
For New Entrants and Emerging Players: Pursue Philippines-to-Singapore remittance corridors where compliant gateway penetration remains underdeveloped and correspondent banking friction sustains premium pricing opportunities. Target white-label deployments for regional Indonesian banks seeking digital-asset checkout integration without in-house compliance infrastructure. A developer-tooling-first go-to-market angle captures webhook architecture demand from Vietnamese gaming platforms.
For Investors and Strategic Acquirers: Capital is best deployed toward fiat-crypto bridge specialists with established ASEAN banking partnerships and multi-jurisdiction compliance synchronization capabilities. Long-term viability rests on whether India's CBDC mandate displaces private infrastructure or creates regulated bridge demand. The signal to watch is Monetary Authority licensing queue velocity as a proxy for competitive filtration intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Compliance Synchronization | Enables simultaneous Japanese FSA and Singapore MAS licensing without redundant audit cycles. |
| Stablecoin Liquidity Pool Expansion | Reduces cross-border settlement friction in Philippines-Singapore remittance corridors. |
| API-First Developer Tooling Investment | Captures webhook architecture demand from Indonesian e-commerce platform engineering teams. |
| No-Code Plugin Distribution Partnership | Accelerates Malaysian small merchant onboarding velocity without direct sales overhead. |
| Cold-Wallet Custody Infrastructure Buildout | Satisfies Japan's Payment Services Act segregated custody mandates while reducing third-party dependency. |
Research Methodology
A standing panel of gateway product managers, merchant acquiring executives, regulatory compliance officers, and blockchain infrastructure engineers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against Monetary Authority licensing disclosures, Financial Services Act amendment filings, and South Korean Financial Services Commission regulatory bulletins. Bottom-up merchant adoption modeling and top-down payment volume triangulation anchored the analytical framework.
Scenario-bracketing framed the projection methodology across the analysis window. Segmentation dimensions modeled include payment method architecture, transaction size tier, end-user merchant category, and integration technical depth. CAGRs were derived from merchant onboarding velocity trajectories and stablecoin settlement rail adoption curves. Forecast inputs incorporated real-name verification linkage compliance rates and Layer-2 network fee compression timelines.
Macroeconomic conditions sit as an overlay; deviation in regional interest rate environments, cryptocurrency market capitalization cycles, or central bank digital currency launch timing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory filtration intensity and banking partnership accessibility. Cross-checking against Monetary Authority licensee public registers and Financial Services Agency registered provider disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Germany Mobile Payments Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
Bulgaria POS Terminals Market
Payments
Clearing Houses and Settlements Market
Payments
Cloud Billing Market
Payments
Southeast Asia POS Terminal Market
Payments
Canada Real Time Payments Market
Payments
GCC Payment Gateway Market
Payments
India RTP Market
Payments
In-Vehicle Payment Services Market
Payments
Europe Digital Transaction Management (DTM) Market
Payments
UAE Card Payments Market
Payments
India Real Time Payments Market
Payments
Payment Orchestration Platform Market
Payments
Russia Payments Market
Payments
Online Charging System (OCS) Market