
 Canada Payment Gateway Market | 2026-2036
Canada Payment Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Payment Gateway Market Insights
Merchant sourcing of payment infrastructure is decoupling from bundled banking relationships toward standalone gateway contracts. Moneris Solutions anchors its position through deep integration with Canadian chartered banks and legacy retail POS networks. Stripe competes by extending developer-first API tooling that reduces merchant onboarding friction. Square sustains brand strength among small-business owners through hardware-software convergence at the point of sale.
A payment gateway is a technology layer that encrypts, routes, and authorizes transaction data between merchant systems and acquiring banks, typically processing card-not-present payments through HTTPS-secured API endpoints or hosted redirect pages. Its commercial purpose is to reduce fraud exposure, accelerate settlement cycles, and enable multi-currency acceptance for digital commerce. Hosted payment services occupy the largest volume share among service types because they minimize PCI-DSS compliance burdens for mid-market merchants. API integration offerings represent the fastest-expanding category, driven by direct checkout embedding demands from subscription services and SaaS platforms. Tokenization technology leads the technology dimension by displacing raw card storage across cloud-based deployments.
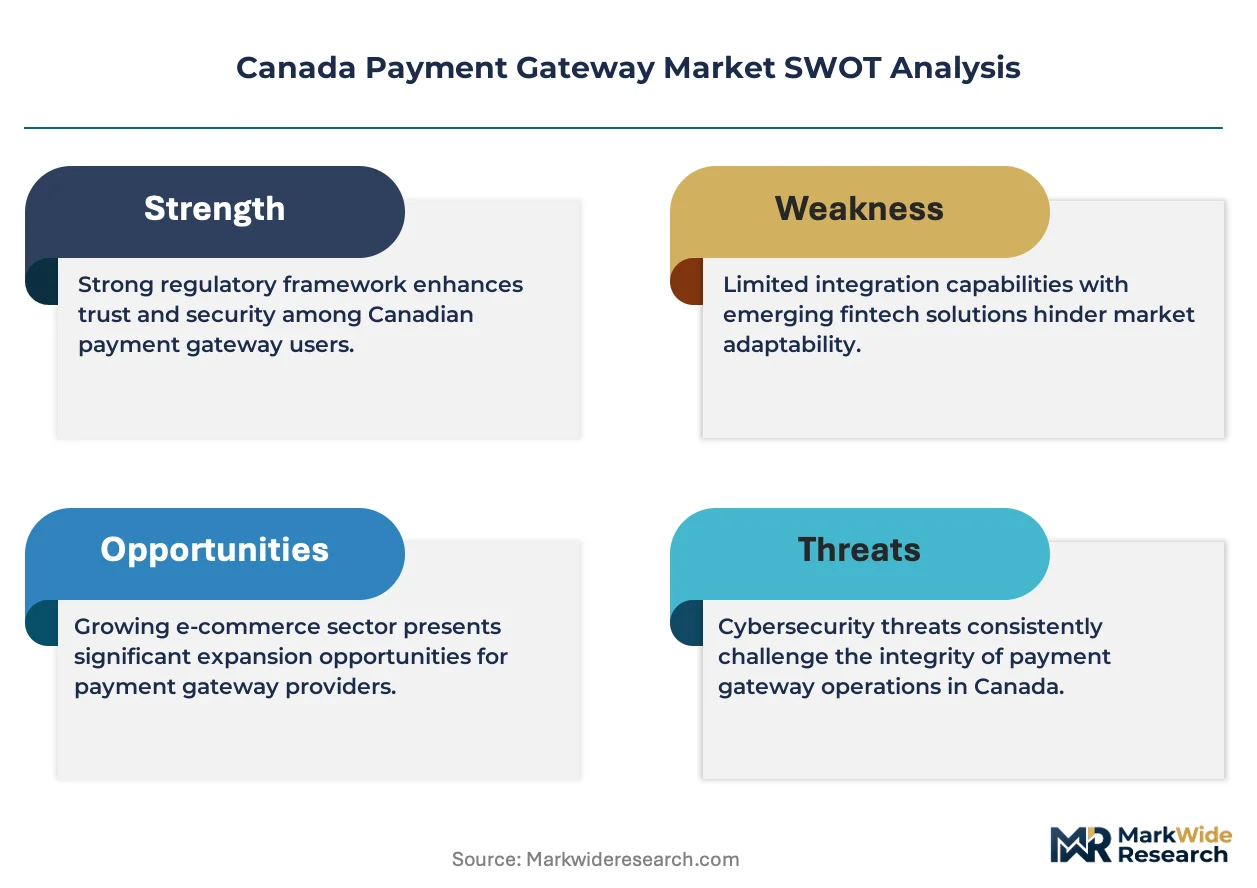
The Bank of Canada supervises systemic payment clearing under the Retail Payment Activities Act, while FINTRAC mandates anti-money-laundering reporting thresholds that shape gateway data-retention architectures. Provincial consumer protection statutes in Ontario, Quebec, and British Columbia impose refund and chargeback disclosure rules that influence merchant contract terms. Stakeholders must monitor whether OSFI extends prudential standards to non-bank payment facilitators, as this would reshape capital requirements and competitive entry costs.
Market Dynamics
Merchant procurement of payment infrastructure is decoupling from bundled banking relationships toward standalone gateway contracts, forcing incumbent processors to unbundle legacy POS-integrated stacks and compete on API velocity rather than branch presence.
Growth Catalysts
- Retail Payment Activities Act:The Bank of Canada's supervision mandate creates compliance-driven upgrade cycles among mid-market payment service providers, accelerating modernization of routing architectures.
- Subscription commerce:SaaS platforms and membership-based retailers in Vancouver's technology corridor demand tokenization-native checkout flows that minimize PCI-DSS scope.
- API-first architectures:Direct checkout embedding is displacing hosted redirect pages among Ontario-based e-commerce merchants seeking conversion rate optimization.
Market Restraints
- Chartered bank concentration:Deep integration between incumbent processors and Canada's Big Five banks creates switching friction for merchants locked into legacy settlement relationships.
- PCI-DSS compliance costs:Small and mid-sized merchants face disproportionate audit and remediation expenses relative to transaction volumes.
- Interchange fee regulation:The Competition Bureau's scrutiny of card network pricing compresses gateway margin structures and limits pricing flexibility.
Strategic Opportunities
- Quebec's underpenetrated fintech corridor:Montreal's emerging SaaS cluster presents first-mover potential for French-language localized checkout experiences.
- Real-time rail integration:Payments Canada's modernization of clearing infrastructure enables instant settlement products that bypass traditional card rails.
- Open banking convergence:The Department of Finance's consumer-directed finance framework creates data-sharing protocols that could embed account-to-account payments within gateway stacks.
Industry Challenges
- Legacy POS integration complexity:Merchants operating hybrid online-offline environments face fragmented reconciliation across incompatible terminal and e-commerce stacks.
- Fraud modeling talent scarcity:Machine learning engineers with payment-specific risk expertise command premium compensation in Toronto's competitive labor market.
- Cross-border data residency:FINTRAC's transaction record retention rules complicate cloud infrastructure strategies for gateways serving multi-national merchants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Payment Gateway Market |
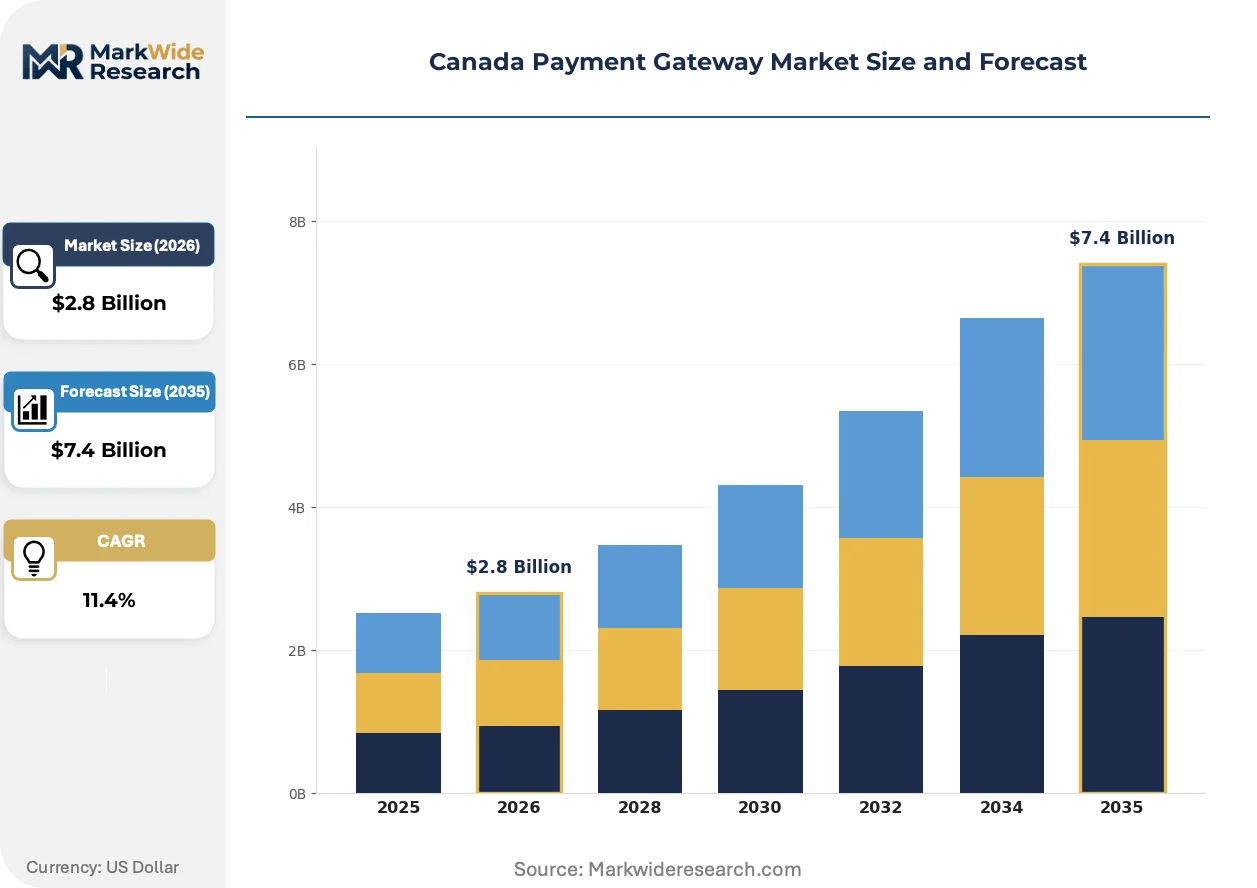
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hosted Payment, API Integration, Payment Processing, Transaction Management Technology: Tokenization, Cryptography, Biometric Verification, Mobile Wallets End User: E-commerce Platforms, Retail Stores, Subscription Services, Nonprofits Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Moneris Solutions, PayPal Holdings, Inc., Stripe, Square, Interac Corporation, Block, Inc., Paramount Commerce, Chase Paymentech, Shopify Payments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Payment Gateway Market Trends and Innovations
Payment gateway architectures are converging around developer-centric tooling and embedded finance primitives, compressing merchant onboarding cycles and expanding addressable markets beyond traditional retail.
Tokenization technology is absorbing raw card storage responsibilities across cloud-based deployments, eliminating merchant exposure to primary account number breaches. Subscription services and SaaS platforms in British Columbia are adopting vaulting strategies at accelerated pace. This shift is absorbing liability concentration away from merchant environments and centralizing it within certified gateway infrastructure.
The Retail Payment Activities Act is mandating systemic risk disclosures and operational resilience standards for payment service providers. The Bank of Canada's supervision framework is forcing gateway operators to maintain segregated safeguarding accounts and incident response protocols. Mid-market providers are responding by restructuring corporate entities and enhancing internal audit functions to meet prudential expectations.
Merchant technical teams are embedding payment functionality directly within product workflows rather than outsourcing to hosted pages. Direct API integration is displacing redirect-based checkout among Ontario e-commerce merchants prioritizing conversion optimization. This pattern is most visible in Toronto's direct-to-consumer retail vertical, where checkout abandonment metrics drive vendor selection criteria.
Canada Payment Gateway Market Segmentation
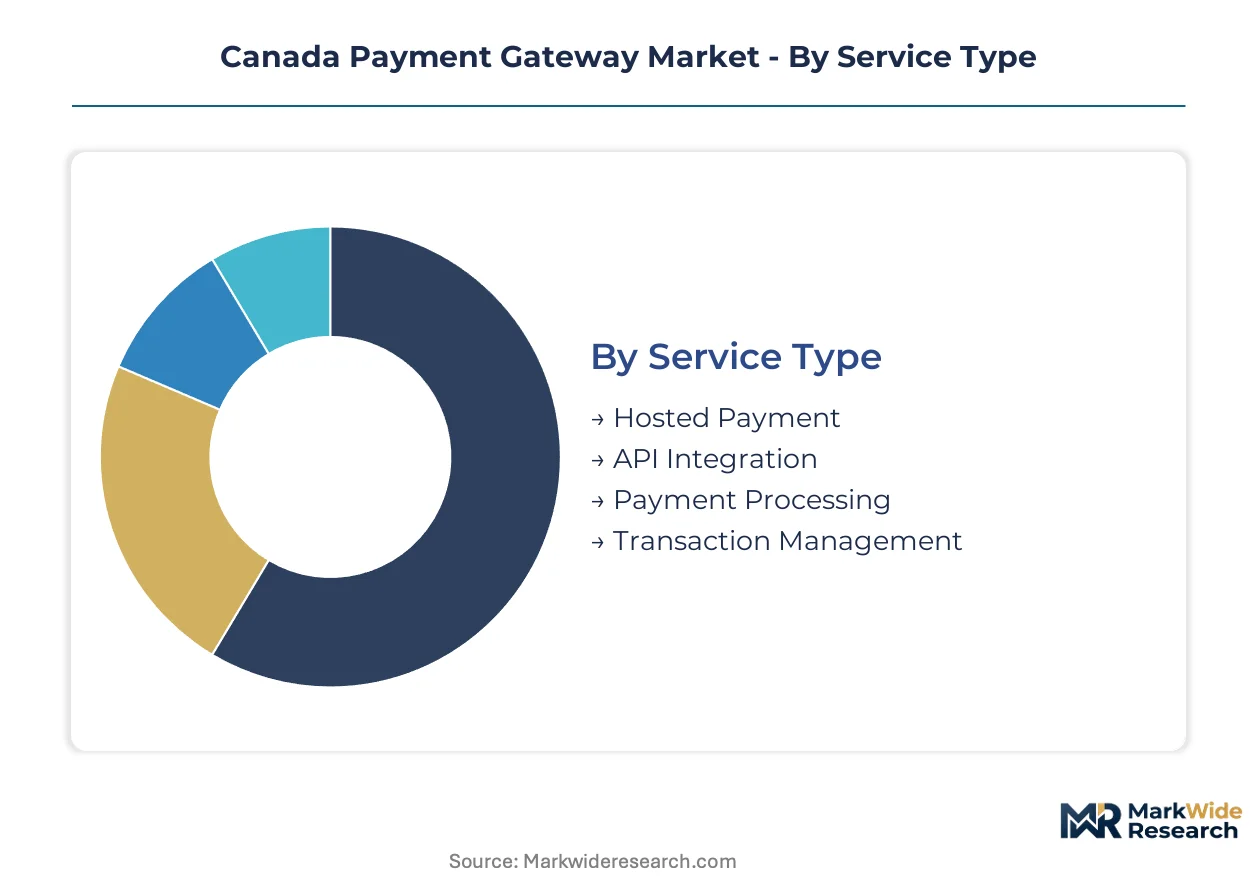
Payment gateway segmentation in Canada reflects divergent technical capabilities and compliance tolerances across merchant types. Service architecture choices directly determine PCI-DSS scope, settlement speed, and integration complexity for businesses operating under the Retail Payment Activities Act.
Service Type:
Merchants select service models based on internal engineering capacity and regulatory risk appetite.
- Hosted Payment:Third-party checkout pages handle card data collection entirely outside merchant infrastructure. Toronto's mid-market retailers favor this model to minimize audit scope under Bank of Canada supervision mandates.
- API Integration:Direct embedding of payment fields within merchant-controlled interfaces. Vancouver SaaS platforms and subscription services in Ontario's fintech corridor prioritize this architecture for conversion rate optimization and seamless user experiences.
- Payment Processing:End-to-end transaction routing and settlement orchestration. Charitable organizations and smaller nonprofits leverage this bundled approach to reduce vendor management overhead.
- Transaction Management:Specialized tools for reconciliation, reporting, and dispute handling. Hybrid online-offline merchants operating across British Columbia and Quebec deploy these solutions to unify fragmented sales channel data.
Hosted Payment leads volumes today; API Integration is gaining share fastest.
Technology:
Security architecture choices are concentrating liability and determining infrastructure investment priorities across Canadian gateway deployments.
- Tokenization:Vault-based replacement of primary account numbers with non-sensitive equivalents. British Columbia subscription platforms and Ontario e-commerce merchants adopt this technology to eliminate raw card storage and compress PCI-DSS compliance burdens.
- Cryptography:End-to-end encryption protocols securing data in transit and at rest. High-volume merchants in Toronto's financial district require advanced cryptographic implementations to satisfy FINTRAC data retention and incident response standards.
- Biometric Verification:Fingerprint and facial recognition authentication layers. Mobile-first retailers in Vancouver test these capabilities for card-not-present fraud reduction.
- Mobile Wallets:Apple Pay, Google Pay, and Samsung Pay integration protocols. Small business owners across Canadian urban centers favor this technology for hardware-software convergence at physical point-of-sale locations.
Tokenization dominates current deployment; Mobile Wallets show steepest expansion trajectory.
End User:
Vertical-specific transaction patterns and regulatory exposure shape gateway procurement criteria across Canadian merchant categories.
- E-commerce Platforms:Pure-play digital merchants requiring multi-currency acceptance and rapid settlement. Ontario-based direct-to-consumer brands and Vancouver technology retailers drive demand for low-latency API architectures.
- Retail Stores:Brick-and-mortar operations with hybrid online-offline footprints. Merchants in Toronto and Montreal seek unified reconciliation across legacy POS terminals and modern e-commerce stacks.
- Subscription Services:Recurring billing models demanding vaulting and automated retry logic. SaaS platforms in British Columbia's technology corridor prioritize tokenization-native checkout flows.
- Nonprofits:Donation-dependent organizations with sporadic transaction volumes and limited technical staff. Charitable entities across Canada favor hosted solutions to minimize compliance costs relative to processing scale.
E-commerce Platforms anchor current revenue; Subscription Services are climbing the fastest.
Deployment:
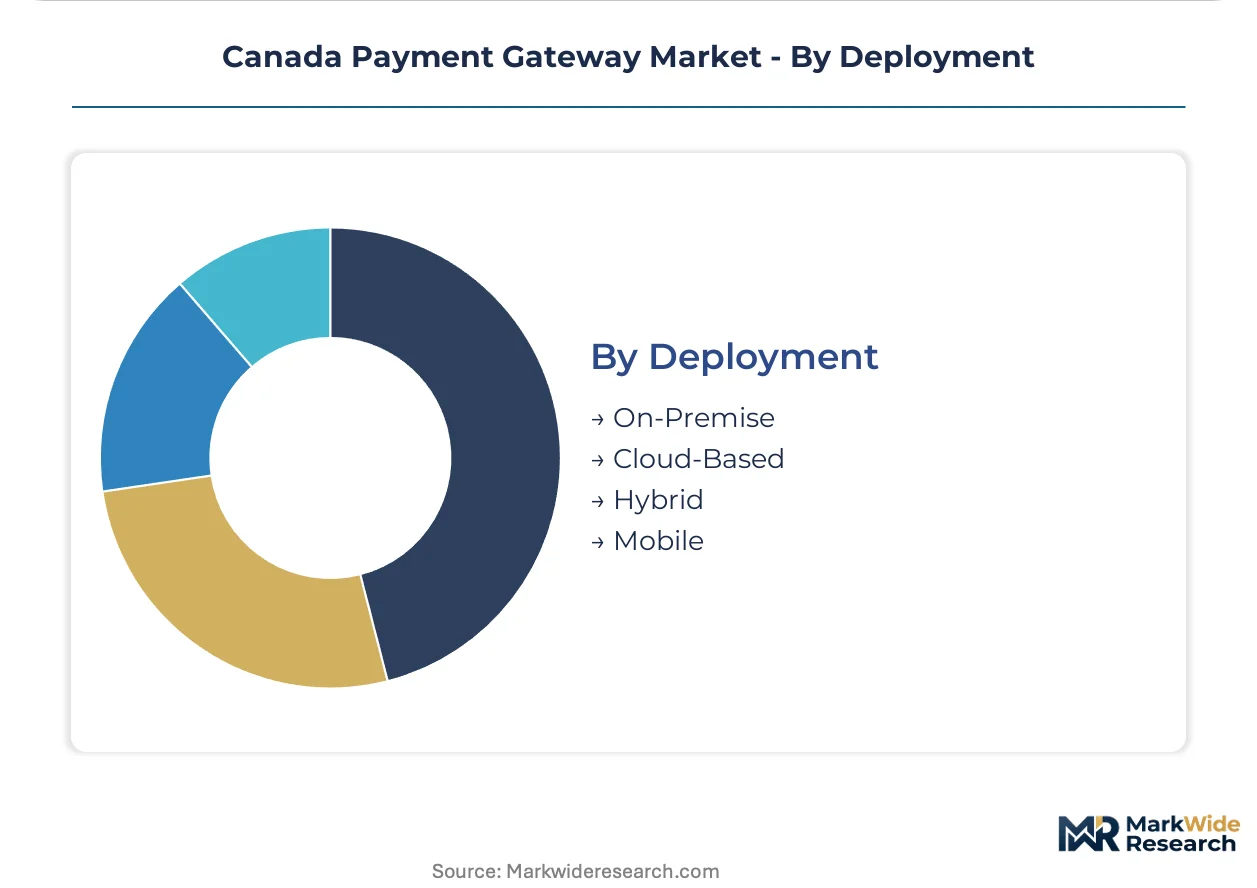
Infrastructure location decisions reflect data residency requirements, latency sensitivity, and legacy system constraints.
- On-Premise:Self-managed hardware within merchant-controlled facilities. Large retailers in Quebec and established Ontario chains maintain these deployments for direct control over transaction data and customization flexibility.
- Cloud-Based:Third-party hosted infrastructure with elastic scaling capabilities. Growth-stage SaaS companies in Vancouver and Toronto fintech startups favor this model for rapid geographic expansion and reduced capital expenditure.
- Hybrid:Split architectures combining on-premise transaction processing with cloud-based analytics and reporting. Mid-market merchants across Canadian provinces adopt this approach to balance control with operational agility.
- Mobile:Smartphone and tablet-native payment acceptance without dedicated terminal hardware. Pop-up retailers, food trucks, and service professionals in urban Canadian markets leverage this deployment for location-independent commerce.
Cloud-Based deployments lead adoption today; Hybrid configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toronto's fintech corridor anchors payment gateway demand through dense clusters of SaaS platforms and direct-to-consumer retailers migrating toward API-first architectures.
Ontario
E-commerce merchants in Toronto and Ottawa prioritize embedded checkout flows to reduce abandonment rates. The Retail Payment Activities Act, enforced by the Bank of Canada, mandates operational resilience standards that accelerate infrastructure upgrades among mid-market providers. Waterloo Region's technology cluster hosts subscription billing startups adopting tokenization-native vaulting strategies.
British Columbia
Vancouver's SaaS ecosystem drives demand for low-latency API integrations and automated retry logic for recurring revenue models. FINTRAC's anti-money-laundering reporting thresholds shape data-retention architectures for cloud-based gateway deployments. Victoria's emerging fintech community experiments with real-time rail integration for account-to-account settlement products.
Quebec
Montreal's underpenetrated fintech corridor presents first-mover opportunities for French-language localized checkout experiences. Provincial consumer protection statutes impose refund and chargeback disclosure rules that influence merchant contract terms. Laval's payment service providers restructure corporate entities to meet prudential expectations under Bank of Canada supervision.
Alberta
Calgary's energy sector payment processors seek hybrid online-offline reconciliation across legacy terminal and e-commerce stacks. The Competition Bureau's scrutiny of card network pricing compresses gateway margin structures for small-business merchants. Edmonton's retail technology startups favor mobile wallet integration for hardware-software convergence at physical point-of-sale locations.
Atlantic Canada
Halifax's nonprofit and charitable organizations leverage hosted payment solutions to minimize PCI-DSS compliance costs relative to processing scale. Provincial data residency requirements complicate cloud infrastructure strategies for gateways serving multi-national merchants. St. John's merchant acquirers face switching friction from deep integration between incumbent processors and regional credit union networks.
Canada Payment Gateway Market Competitive Landscape
Global majors compete with regional champions across developer tooling and bank-integrated legacy stacks. The vendor base concentrates around three strategic tiers: chartered bank-aligned processors with deep POS network penetration, API-native platforms reducing merchant onboarding friction, and hardware-software convergent providers targeting small-business owners. Dominant competitive moves include unbundling legacy integrated stacks to compete on API velocity and restructuring corporate entities to meet prudential supervision standards.
Within the bank-integrated tier, Moneris Solutions occupies a position exemplifying deep chartered bank relationships and legacy retail network coverage. Among API-native platforms, Stripe and Shopify Payments represent archetypes of developer-first tooling and embedded commerce infrastructure respectively.
| Leading Market Players |
|---|
| Moneris Solutions |
| PayPal Holdings, Inc. |
| Stripe |
| Square |
| Interac Corporation |
| Block, Inc. |
| Paramount Commerce |
| Chase Paymentech |
| Shopify Payments |
| Others |
Pricing and Supply Chain Analysis
Mid-market SaaS merchants concentrated in Vancouver and Toronto drive pricing power toward usage-based transactional models with tiered API call thresholds. Their procurement preferences for low-friction onboarding compress margin structures for gateway providers competing against developer-centric platforms.
Pricing Analysis
Interchange fees and network assessment costs pass through to merchant pricing with limited absorption capacity among smaller processors. Three-tier pricing structure across premium, standard, and economy levels segments by transaction volume scale and PCI-DSS certification tier. Pricing pressure stems from the Competition Bureau's scrutiny of card network pricing compressing gateway margins. Small nonprofits and charitable organizations exhibit highest price sensitivity, while enterprise SaaS platforms prioritize API reliability over per-transaction cost.
Supply Chain Analysis
Regional data center distribution across Toronto, Montreal, and Vancouver establishes hub-and-spoke patterns for latency-sensitive transaction routing. Cloud infrastructure draws from hyperscaler facilities in the United States and domestic Canadian facilities to satisfy FINTRAC data residency requirements. Supply chain risk centers on single-source vulnerability for specialized fraud detection hardware and cryptographic modules. Distribution runs through direct API provisioning for SaaS merchants and value-added reseller networks for legacy POS-integrated retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as merchant procurement shifts toward tokenization-native architectures with embedded compliance automation. Premium specifications now dominate vendor selection criteria among British Columbia subscription platforms.
For Market Incumbents: Cement dominance through deep vertical integration into tokenization vaulting infrastructure and real-time rail settlement capabilities. Moneris Solutions and bank-aligned processors face displacement risk from API-native entrants; priority lever rests on accelerating developer tooling parity while maintaining chartered bank settlement relationships.
For New Entrants and Emerging Players: The mid-market price-point gap between Stripe's premium developer tier and Square's small-business economy tier creates white-space opportunity. Quebec's French-language SaaS corridor and Atlantic Canada nonprofit segments present lowest competitive density. Go-to-market angle should emphasize hosted-to-API migration paths with PCI-DSS compliance bundling.
For Investors and Strategic Acquirers: Payment infrastructure specialists are the most active acquirer in this space, targeting API-native gateway assets with recurring revenue concentration. Long-term viability favors platforms with real-time rail integration and open banking data protocols. Signal to watch: OSFI prudential standard extension to non-bank facilitators as inflection indicator for capital requirement reshaping.
| Strategic Initiative | Industry Significance |
|---|---|
| Tokenization Vault Expansion | British Columbia SaaS platforms absorb liability away from merchant environments into certified infrastructure. |
| Real-Time Rail Integration | Victoria fintech experiments bypass traditional card rails through Payments Canada modernization protocols. |
| API-First Architecture Migration | Toronto direct-to-consumer brands reduce checkout abandonment through embedded payment field embedding. |
| Compliance Automation Layer | Mid-market providers restructure entities to meet Bank of Canada operational resilience standards. |
| French-Language Localization | Montreal SaaS cluster demands localized checkout experiences with Quebec consumer protection disclosure rules. |
Research Methodology
Direct dialogue with payment gateway CTOs, merchant acquiring executives, FINTRAC compliance officers, and SaaS platform engineers grounded qualitative findings. Secondary validation drew from Bank of Canada supervisory reports, Payments Canada clearing infrastructure disclosures, FINTRAC guidance documents, and Retail Payment Activities Act regulatory filings. Bottom-up merchant adoption modeling and top-down market sizing triangulated volume estimates.
Segmented outputs across the projection horizon reflect service architecture, security technology, end-user vertical, and deployment model dimensions. CAGRs were derived from merchant onboarding velocity analysis and API integration adoption curves. Industry-specific inputs included real-time rail implementation timelines and open banking framework progression.
Caveats apply where OSFI prudential extension, interchange fee regulatory shifts, or cross-border data residency rulings could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Retail Point of Sale (POS) Market
Payments
Fingerprint Payment Market
Payments
Europe Clearing Houses and Settlements Market
Payments
Thailand Mobile Payments Market
Payments
United Kingdom Mobile Payments Market
Payments
Bus Card Reader Market
Payments
In-Vehicle Payment Services Market
Payments
Norway POS Terminals Market
Payments
North America Payments Market
Payments
Sweden POS Terminals Market
Payments
Japan Virtual Cards Market
Payments
Europe Prepaid Card Market
Payments
Germany Real Time Payments Market
Payments
Slovakia POS Terminal Market
Payments
E-Wallet Market
Payments
Egypt Mobile Payments Market