
 Biometric Payment Market | 2026-2036
Biometric Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric Payment Market Analysis
GDPR's Article 9 prohibition on processing biometric data is broadening the cost-of-entry calculus for payment technology vendors entering European markets. Samsung leverages its Knox security architecture to anchor trust in mobile wallet deployments across regulated jurisdictions. Apple differentiates through on-device neural engine processing that keeps biometric templates off cloud servers. IDEMIA controls large-scale government identity contracts that extend into payment credentialing pipelines.
Biometric payment denotes transaction authentication using unique physiological or behavioral characteristics, typically requiring liveness detection thresholds below one percent false acceptance rate and sub-second matching latency against encrypted template stores. The primary commercial purpose is eliminating credential replay fraud while reducing checkout friction in high-throughput retail environments. Fingerprint recognition dominates POS terminal deployments due to mature sensor economics and consumer familiarity, while facial recognition captures the fastest growth in e-commerce checkout flows where camera ubiquity removes hardware barriers. Deployment through mobile devices concentrates the largest addressable user base, though wearable devices represent an emerging margin pool as tokenized biometric credentials migrate to smartwatch secure elements.
The US Federal Trade Commission enforces Section 5 unfairness standards against biometric data retention practices, while India's RBI mandates multi-factor authentication for transactions above specified thresholds and the BIS certification regime governs biometric device accuracy standards for financial applications. These overlapping compliance requirements fragment vendor certification pathways and inflate go-to-market timelines for cross-border solution providers. Stakeholders must monitor regulatory divergence between data localization mandates and interoperability standards to determine whether regional product variants or unified global platforms yield superior capital efficiency.
Market Dynamics
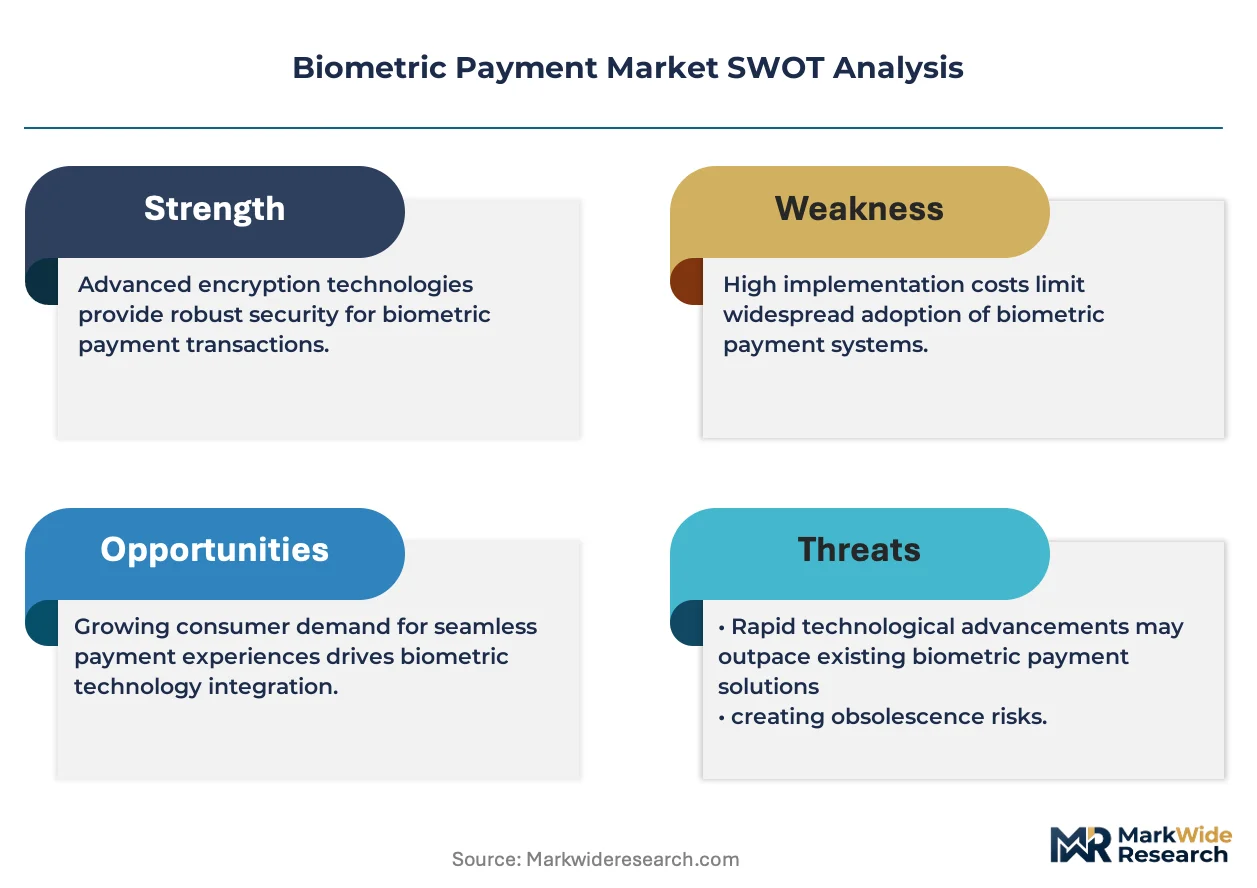
The EU AI Act's risk-tier classification for biometric systems is forcing vendors to re-engineer algorithmic transparency and audit trail architectures, compressing product development cycles while elevating compliance costs for European market entry.
Growth Catalysts
- India's UPI-Aadhaar convergence:The Unified Payments Interface linked to national identity infrastructure creates instant addressable scale for voice and vein recognition deployments across tier-2 and tier-3 merchant networks.
- Contactless hygiene protocols:Post-pandemic retail environments favor facial and palm recognition over fingerprint sensors at high-traffic checkout terminals.
- RBI's biometric authentication mandate:India's central bank requires multi-factor verification for transactions above specified thresholds, institutionalizing biometric hardware procurement across the banking sector.
Market Restraints
- GDPR Article 9 friction:Europe's prohibition on biometric data processing forces vendors to maintain parallel product architectures, inflating certification timelines by 12-18 months.
- Sensor supply concentration:Fingerprint module production clusters in East Asian manufacturing hubs, exposing procurement to geopolitical disruption and input cost volatility.
- Template storage liability:Centralized biometric database architectures face escalating cyber insurance premiums and breach remediation costs.
Strategic Opportunities
- Wearable secure element migration:Smartwatch tokenization of biometric credentials opens margin pools beyond smartphone-dependent deployments.
- EU AI Act compliance services:Algorithmic audit and documentation tooling represents adjacent revenue streams for biometric software vendors.
- Vein recognition in cold-chain retail:Gloved-worker environments in pharmaceutical and frozen food distribution favor contactless vascular pattern authentication.
Industry Challenges
- Liveness detection R&D talent scarcity:Sub-one-percent false acceptance rate engineering requires specialized computer vision expertise concentrated in limited geographic pools.
- Cross-border certification fragmentation:BIS accuracy standards in India, RBI authentication protocols, and FTC Section 5 enforcement in the US create non-harmonized testing requirements.
- Legacy POS integration complexity:Decade-old terminal estates lack secure element capacity for modern biometric template matching, forcing expensive hardware refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric Payment Market |
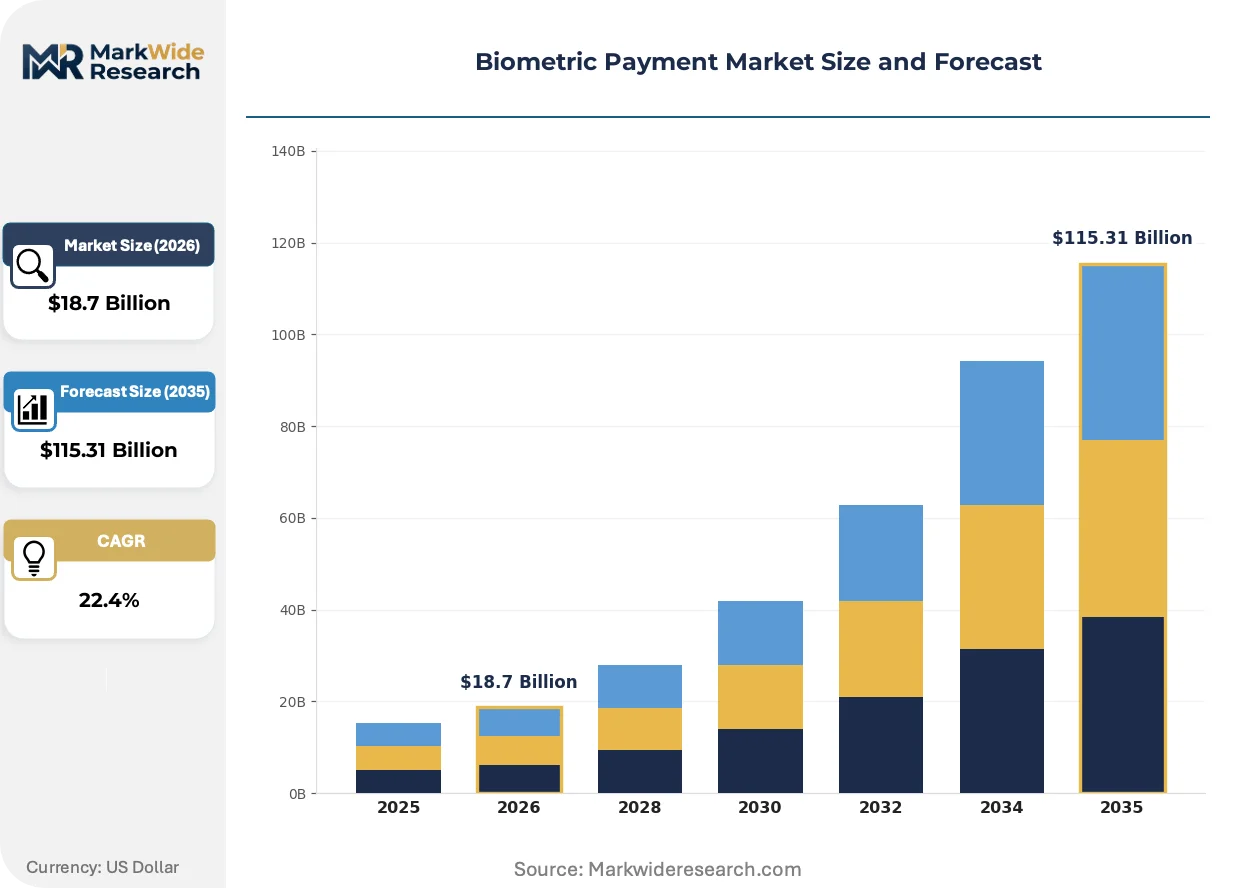
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Vein Recognition Application: Retail, E-Commerce, Banking, Transportation End User: Consumers, Enterprises, Financial Institutions, Government Deployment: Mobile Devices, ATMs, POS Terminals, Wearable Devices |
| Companies Covered | Samsung, Fujitsu, Apple, Fingerprint Cards, Mastercard, NEC, Zwipe, Dermalog, IDEMIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric Payment Market Emerging Trajectories
Algorithmic processing architectures and regulatory compliance frameworks are simultaneously reshaping competitive positioning, with on-device inference and risk-classification mandates determining which vendor configurations capture merchant procurement preference.
Edge-based neural engine deployment is automating biometric template matching directly on smartphone and terminal hardware, eliminating cloud transmission latency and reducing breach exposure. Large retail chains in North America and Western Europe are prioritizing these architectures for sub-second checkout authentication. This shift is automating the displacement of centralized biometric service providers that previously monetized API-based verification calls.
The EU AI Act's high-risk system classification for real-time biometric identification imposes conformity assessment obligations and post-market monitoring requirements on payment terminal vendors. European merchants now demand algorithmic impact documentation and human oversight protocols as procurement preconditions. France, Germany, and the Netherlands are seeing accelerated vendor consolidation around those with pre-established notified body relationships.
Merchant procurement patterns are compressing authentication friction tolerance thresholds, with quick-service restaurants and grocery chains rejecting solutions exceeding 800-millisecond matching latency. Cloud-based biometric APIs are losing share to on-premise edge deployments in high-throughput environments. India and Brazil display the most aggressive procurement specifications, with national payment networks mandating performance benchmarks that disqualify legacy architectures.
Biometric Payment Market Segmentation
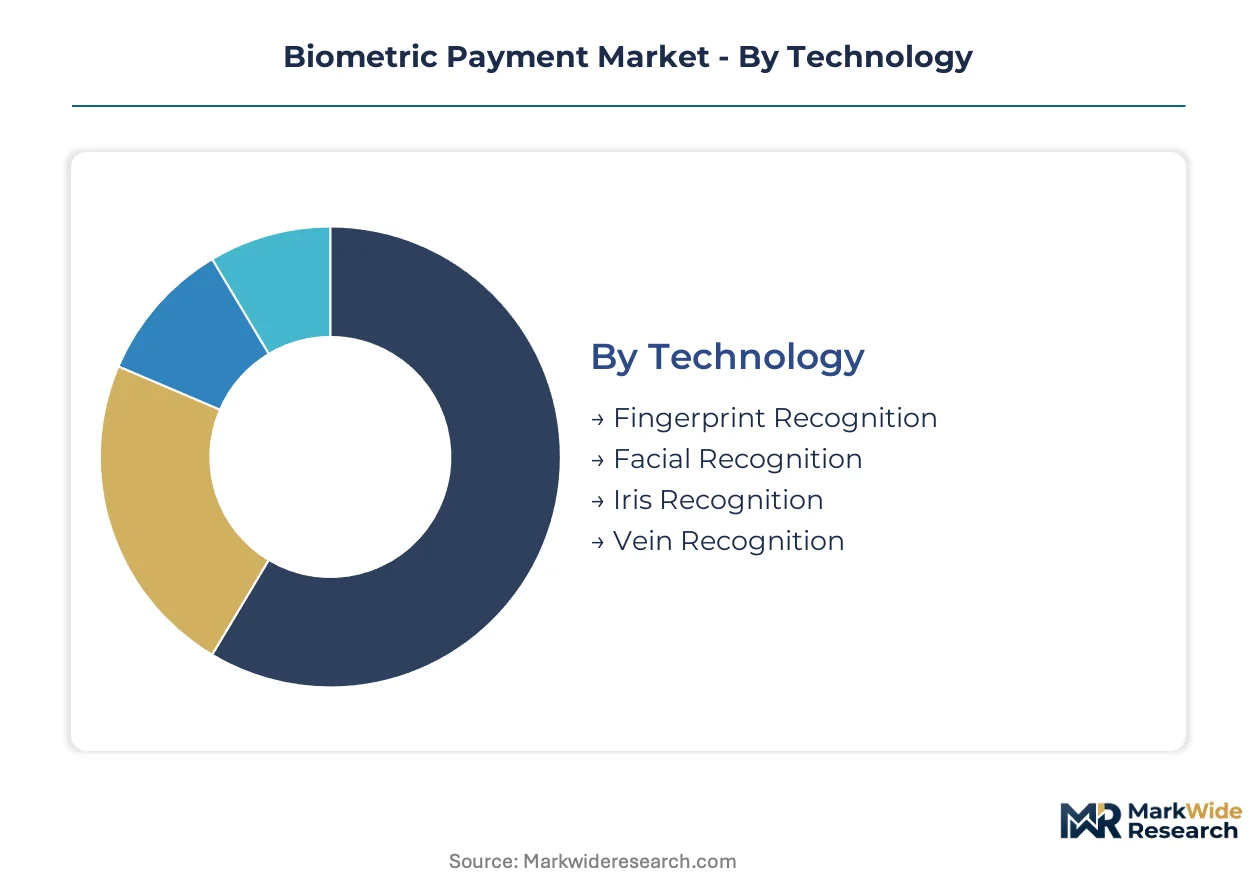
Segmentation in biometric payments reveals how authentication modalities, transaction environments, and hardware form factors allocate capital and compliance burden across vendor portfolios. Each dimension carries distinct engineering requirements and regulatory exposure that shape competitive positioning.
Technology:
Fingerprint and facial systems capture volume economics, while iris and vein modalities command premium positioning in specialized deployments.
- Fingerprint Recognition:Capacitive and ultrasonic sensors embedded in POS terminals and smartphones match encrypted minutiae templates against secure element storage. Retail checkout networks in India and Brazil standardize on this modality for sub-second authentication latency. Mature deployment sits with Fingerprint Recognition. Newer deployment is concentrated in Facial Recognition.
- Facial Recognition:Neural engine inference on device cameras enables liveness detection through depth mapping and infrared dot projection. E-commerce merchants deploy this for camera-native checkout flows where hardware elimination reduces merchant acquisition cost. This segment captures the steepest expansion trajectory as liveness detection accuracy improves.
- Iris Recognition:Near-infrared imaging of unique stromal patterns delivers false acceptance rates below one in one million for high-security financial applications.
- Vein Recognition:Near-infrared transillumination of subcutaneous vascular structures enables contactless authentication in gloved-worker environments such as pharmaceutical distribution.
Volume manufacturing advantages concentrate in fingerprint sensors. Algorithmic sophistication differentiates facial recognition vendors.
Application:
Retail throughput demands drive hardware-intensive deployment, while banking and transportation impose divergent compliance architectures.
- Retail:High-frequency checkout environments prioritize sub-800-millisecond matching latency and liveness detection below one percent false acceptance. Quick-service restaurant chains and grocery networks in North America procure edge-based terminals that eliminate cloud transmission. Deployment concentrates in tier-1 metropolitan markets with refreshed POS estates.
- E-Commerce:Camera-native authentication on smartphones removes hardware procurement barriers for online merchants. The modality shifts fraud liability from merchants to issuers under network tokenization schemes. This application is expanding most quickly as merchant checkout abandonment rates drive friction reduction investment.
- Banking:Multi-factor authentication mandates from India's RBI and similar regulators institutionalize biometric hardware procurement across ATM networks and branch counter systems.
- Transportation:Transit authority procurement favors contactless facial and palm recognition for fare gate throughput in high-density urban corridors.
Established infrastructure dominates retail. Regulatory mandates are accelerating banking deployment.
End User:
Consumer-facing authentication scales through mobile wallet integration, while enterprise and government procurement carries longer sales cycles and certification requirements.
- Consumers:Smartphone-native biometric enrollment through Apple Wallet and Samsung Pay creates addressable scale without dedicated hardware distribution. Liveness detection performance determines wallet provider selection for in-app and in-store transactions.
- Enterprises:Corporate campus and facility access systems extend into payment credentialing for cafeteria and procurement card programs. Integration complexity with legacy identity management platforms constrains vendor selection.
- Financial Institutions:Issuer investment in biometric card programs and ATM network upgrades follows regulatory authentication mandates in India and similar markets.
- Government:National identity infrastructure such as India's Aadhaar creates payment authentication pipelines through linked financial inclusion programs.
Consumer mobile deployment leads volume. Government-linked systems create anchored demand in emerging markets.
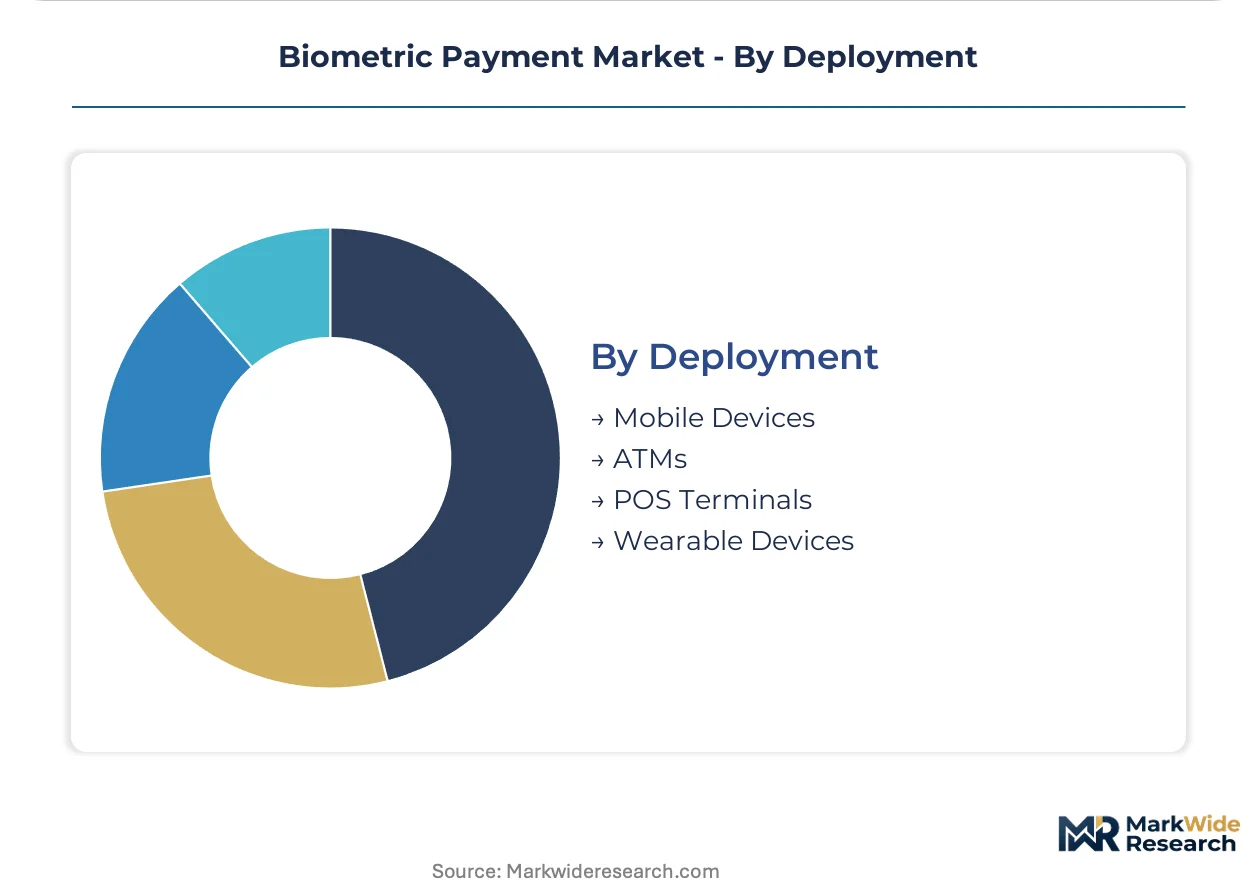
Deployment:
Mobile device concentration defines the largest addressable base, while wearable and ATM deployments represent emerging margin pools with distinct hardware requirements.
- Mobile Devices:Secure element and neural engine integration on smartphones enables on-device template matching without cloud exposure. Tokenized credential migration to smartwatches extends this architecture to wearable form factors.
- POS Terminals:Merchant hardware refresh cycles in North America and Western Europe prioritize edge-based inference and EU AI Act compliance documentation. Legacy terminal estates lacking secure element capacity force expensive replacement timelines.
- ATMs:Banking network upgrades incorporate fingerprint and facial modules for cardless cash withdrawal authentication.
- Wearable Devices:Smartwatch secure elements host tokenized biometric credentials for transit and retail tap-to-pay scenarios.
Smartphone deployment holds installed base dominance. Wearable tokenization is gaining share fastest among emerging hardware categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the most aggressive near-term demand expansion through its UPI-Aadhaar payment infrastructure convergence, while regulatory fragmentation across the United States, European Union, and East Asian manufacturing hubs shapes divergent vendor compliance pathways and certification timelines.
United States
Merchant procurement of edge-based POS terminals accelerates through quick-service restaurant and grocery chain networks seeking sub-second checkout authentication. The FTC enforces Section 5 unfairness standards against biometric data retention practices, elevating cyber insurance and breach remediation costs for centralized database architectures. Silicon Valley technology clusters and Atlanta-based payment processors anchor domestic vendor development and merchant acquisition channels.
India
UPI transaction volumes linked to Aadhaar authentication create instant scale for voice and vein recognition deployments across tier-2 and tier-3 merchant networks. The RBI mandates multi-factor biometric verification for transactions above specified thresholds, institutionalizing hardware procurement across banking and ATM networks. Mumbai and Bangalore concentrate fintech development while Delhi-NCR anchors government identity infrastructure integration with payment systems.
Germany
Industrial machinery and automotive payment credentialing programs drive enterprise campus deployment of fingerprint and facial authentication systems. The EU AI Act's high-risk classification for biometric identification imposes conformity assessment obligations and post-market monitoring requirements on terminal vendors. Bavaria and Baden-Württemberg host manufacturing clusters where automotive suppliers integrate biometric access into procurement card programs.
China
Mobile wallet penetration through smartphone-native facial recognition enables camera-based checkout flows at scale across e-commerce and retail environments. The national standards regime and MIIT certification requirements govern biometric device accuracy for financial applications, fragmenting testing protocols from Western jurisdictions. Shenzhen and Beijing concentrate sensor module manufacturing and algorithm development for domestic and export markets.
Brazil
National payment network mandates for performance benchmarks accelerate merchant hardware refresh cycles, disqualifying legacy architectures that exceed latency thresholds. The central bank's authentication protocols and ANVISA-equivalent device certification requirements create parallel compliance pathways for cross-border solution providers. São Paulo anchors financial technology development while Rio de Janeiro concentrates retail network procurement for biometric terminal deployment.
Biometric Payment Market Vendor Landscape
East Asian producers anchor sensor manufacturing and mobile device integration; European specialists hold algorithmic audit and government identity contract positions. The vendor structure concentrates around technology conglomerates with secure element architectures, component specialists with mature sensor economics, and identity vendors with large-scale credentialing pipelines. Strategic moves center on edge-based neural engine deployment and EU AI Act compliance documentation capabilities.
Within the technology conglomerate tier, Samsung and Apple exemplify divergent trust architectures—Samsung through Knox security frameworks across regulated jurisdictions, Apple through on-device neural engine processing that eliminates cloud template exposure. IDEMIA occupies a position bridging government identity infrastructure into payment credentialing pipelines. Component specialists such as Fingerprint Cards and Zwipe represent the sensor economics tier supplying modules for POS terminal and card-embedded deployments.
| Leading Market Players |
|---|
| Samsung |
| Fujitsu |
| Apple |
| Fingerprint Cards |
| Mastercard |
| NEC |
| Zwipe |
| Dermalog |
| IDEMIA |
| Others |
Supply Flow & Price Mechanics
Computer vision engineering talent concentrated in Shenzhen, Bangalore, and Silicon Valley creates labor-cost differentials that widen pricing spreads between premium edge-based systems and commodity fingerprint modules. Vendors with captive liveness detection R&D teams command three-tier pricing structures across premium, standard, and economy levels, while module assemblers without algorithmic capabilities compete on sensor unit economics alone.
Pricing Analysis
Volume-vs-margin splits sharply between commodity fingerprint sensor suppliers and premium facial recognition platform vendors. Three-tier pricing structure across premium, standard, and economy levels stratifies by liveness detection accuracy certification and secure element integration depth. Cost compression in economy-tier capacitive sensors intensifies because East Asian manufacturing overcapacity feeds merchant procurement auctions. Quick-service restaurant chains exhibit highest price sensitivity, demanding sub-dollar per-transaction authentication costs, while banking networks prioritize certification tier over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for smartphone-integrated facial recognition modules, while distributor networks serve tier-2 POS terminal manufacturers in India and Brazil. Supply concentrates in China for near-infrared camera modules, South Korea for secure element chipsets, and Taiwan for neural engine fabrication. Raw material dependencies include indium gallium arsenide photodetectors, cryptographic coprocessors, and specialized optical glass substrates. Single-source vulnerability in EU AI Act compliance documentation tooling creates procurement bottlenecks for European market entry. Distribution runs through authorized component distributors with BIS and MIIT certification relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EU AI Act compliance costs and liveness detection R&D scale requirements force weaker algorithmic vendors toward exit or acquisition. Margin pressure on centralized biometric API providers accelerates displacement by edge-based architectures.
For Market Incumbents: Extend algorithmic audit service capabilities to capture adjacent revenue from EU AI Act conformity assessment demand. Deepen backward integration into secure element chip design to reduce dependency on Samsung and Apple captive supply. Defensive patent clustering around sub-800-millisecond matching latency architectures blocks emerging entrant differentiation.
For New Entrants and Emerging Players: Launch via vein recognition specialization targeting pharmaceutical cold-chain distribution networks where gloved-worker environments disqualify fingerprint alternatives. Target tier-3 Indian merchant networks underserved by incumbent POS terminal refresh cycles. White-space capture in wearable secure element tokenization for transit authority procurement offers fastest path to revenue.
For Investors and Strategic Acquirers: Re-rating potential sits with government identity contract holders given Aadhaar-linked payment authentication pipeline expansion. Long-term viability over the coming decade favors vendors with pre-established notified body relationships for EU high-risk system classification. Acquisition target archetype: mid-scale liveness detection engineering teams with BIS certification track records. Signal to watch: RBI threshold adjustments for mandatory biometric verification coverage expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Documentation Investment | Notified body relationships accelerate merchant procurement preference in France and Germany. |
| On-Device Neural Engine Architecture Migration | Edge-based inference eliminates cloud transmission latency for sub-second retail checkout authentication. |
| Vein Recognition Module Development | Near-infrared transillumination captures pharmaceutical distribution procurement in gloved environments. |
| Wearable Secure Element Tokenization | Smartwatch credential migration opens transit authority fare gate deployment opportunities. |
| Backward Integration into Sensor Manufacturing | Captive capacitive module production insulates margin from East Asian input cost volatility. |
Methodological Framework
SEC filings from biometric technology vendors, RBI circulars on authentication mandates, and EU AI Act implementation guidance formed the secondary backbone. Primary interviews with POS terminal procurement managers, liveness detection engineering leads, and banking network infrastructure heads combined with secondary validation. Bottom-up triangulation across sensor shipment data and top-down reconciliation against payment transaction volumes anchored market sizing.
Historical trendline analysis of fingerprint and facial recognition deployment trajectories informed projection frameworks across the analysis window. Segmentation dimensions modeled include authentication modality, deployment form factor, and regulatory compliance tier. CAGR derivation rested on merchant hardware refresh cycle timing and national payment network mandate implementation schedules. Industry-specific inputs encompassed BIS device certification timelines and FTC Section 5 enforcement pattern analysis.
The model assumes a particular technology adoption path; alternative pathways for voice recognition in rural Indian merchant networks would alter the outlook. Forecasts reflect assumptions regarding EU AI Act enforcement consistency and RBI threshold stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Digital Wallets Market
Payments
Telecom Cloud Billing Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
EMV Card Market
Payments
US Buy Now Pay Later Services Market
Payments
Crypto Payment Gateway Market
Payments
Canada Payment Gateway Market
Payments
Wireless POS Terminals Market
Payments
Payment Instruments Market
Payments
QR Codes Payment Market
Payments
United States Mobile Payment Market
Payments
Cross-Border Payment Platform Market
Payments
LAMEA Payment Gateway Market
Payments
M Commerce Payment Market
Payments
China Payments Market
Payments
France Virtual Cards Market