
 South Korea Telecom Market | 2026-2036
South Korea Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Telecom Market Analytics
The gap between premium 5G standalone services and legacy 4G commodity offerings is realigning how carriers structure capital deployment and customer retention. SK Telecom leverages its nationwide 5G infrastructure to anchor high-margin enterprise contracts. KT competes through specialized fiber-to-the-home deployments in dense urban corridors. LG Uplus differentiates via aggressive content bundling and media partnerships.
South Korea telecom encompasses wireless and wireline communication services, network infrastructure operation, and digital service delivery through technologies operating across sub-6 GHz and millimeter-wave spectrum bands with fiber backhaul integration. The primary commercial purpose is enabling voice, data, and video transmission for consumer and enterprise endpoints. Mobile Services commands the largest revenue pool as 5G penetration deepens, while Internet Services captures expanding margin from symmetric gigabit fiber. Fiber Optic technology leads infrastructure replacement cycles, and 5G segments show the fastest structural growth as standalone core networks mature.
MFDS equipment certification, KCC radio spectrum licensing, and MSIT 5G rollout mandates shape device approval timelines, bandwidth allocation, and infrastructure buildout obligations respectively. These frameworks tighten compliance costs while securing quality benchmarks for network equipment deployment. Stakeholders must monitor spectrum reallocation proceedings and open-RAN interoperability requirements to anticipate vendor selection and partnership decisions.
Market Dynamics
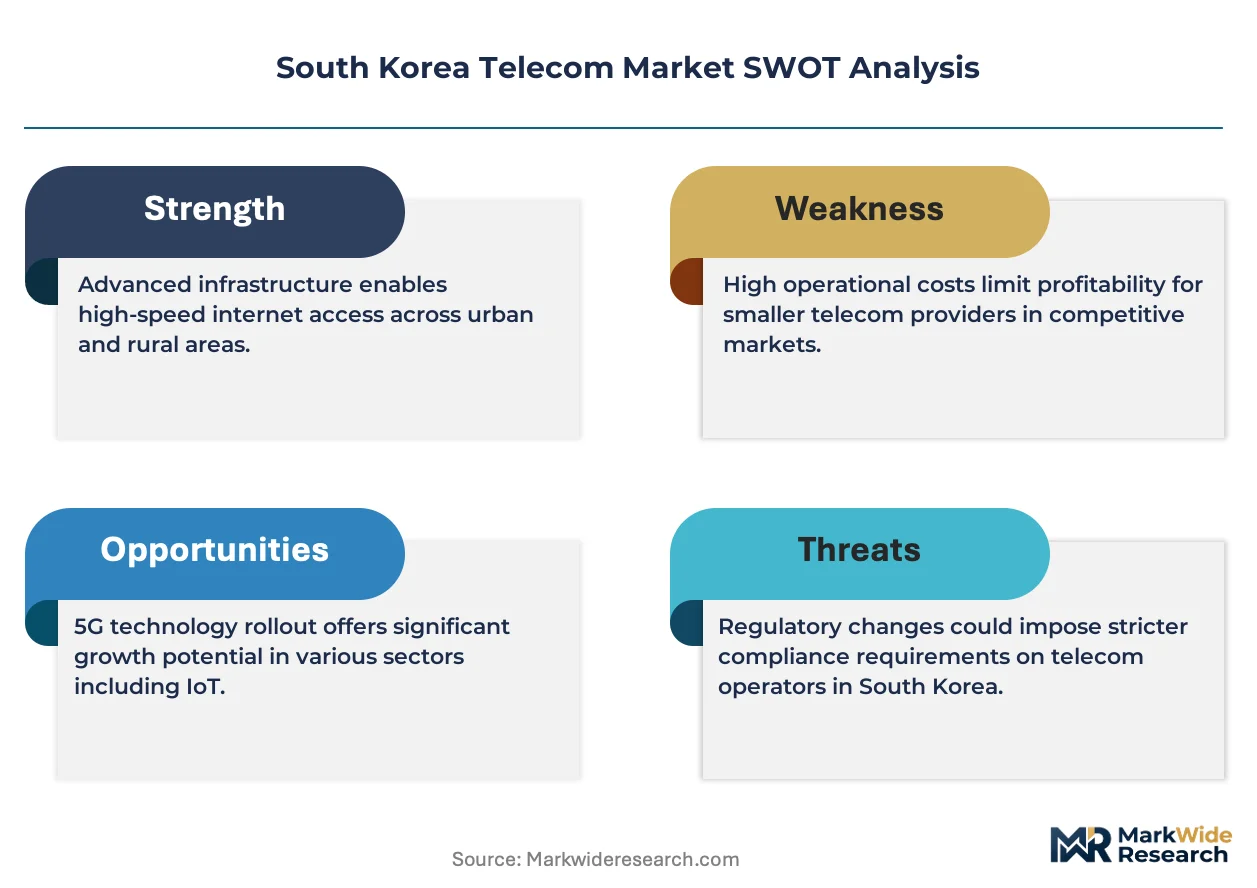
The transition from non-standalone 5G to standalone core networks is compressing carrier investment timelines while forcing simultaneous fiber densification and edge compute deployment across metropolitan corridors.
Growth Catalysts
- MSIT 5G rollout mandates:Infrastructure buildout obligations accelerate base station deployment in Seoul's metropolitan corridor and Pangyo Techno Valley cluster.
- Smart manufacturing:Industrial enterprises adopt private 5G networks for latency-critical automation, pulling fiber backhaul investment into factory zones.
- Symmetric gigabit fiber:Consumer and SME demand for upload parity drives replacement cycles in legacy copper infrastructure.
Market Restraints
- Millimeter-wave propagation limits:Dense urban deployment requires three to four times more small cells than sub-6 GHz, elevating site acquisition costs.
- KCC spectrum licensing fees:Auction structures compress carrier margins while amortization periods extend beyond typical technology refresh cycles.
- Optical component supply concentration:Dependence on specialized fiber amplifier and transceiver suppliers creates input cost volatility during capacity expansions.
Strategic Opportunities
- Gwangju-Daejeon corridor:Secondary metropolitan zones outside Seoul show underpenetrated 5G standalone coverage with industrial anchor tenants.
- Open RAN interoperability:MSIT guidelines create vendor diversification pathways for disaggregated baseband and radio unit procurement.
- Media-content convergence:Bundled streaming and cloud gaming packages attract subscriber stickiness in saturated mobile markets.
Industry Challenges
- Legacy 4G core integration:Carriers maintain parallel signaling paths during standalone transition, doubling operational complexity.
- MFDS equipment certification timelines:New radio and core network hardware face extended approval queues, delaying commercial launch windows.
- Baseband software talent scarcity:Open RAN architectures require skills spanning both telecom protocols and cloud-native development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Telecom Market |
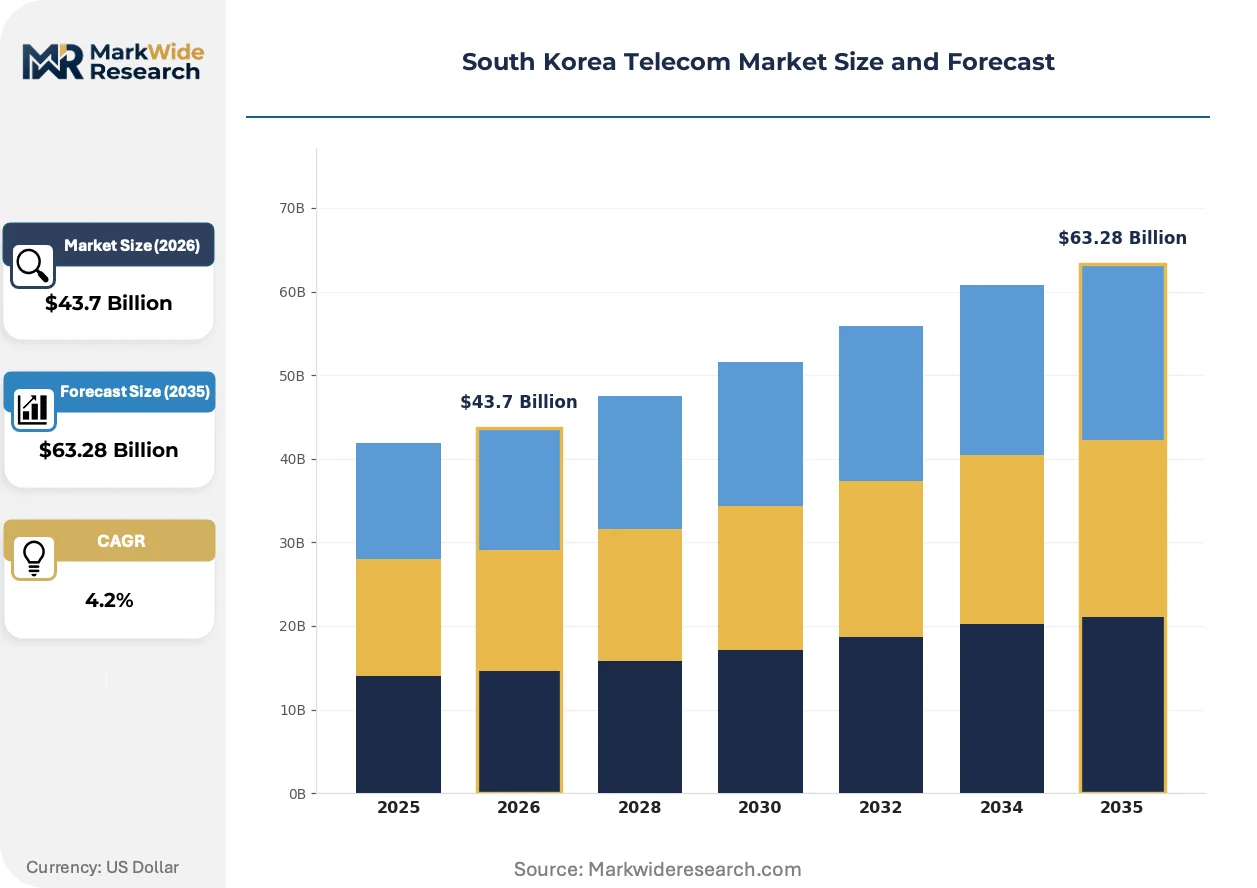
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $63.28 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed-Line Services, Internet Services, VoIP Customer Segment: Residential, Small Business, Large Enterprise, Government Technology: 4G LTE, 5G, Fiber Optic, DSL Pricing Model: Pay-As-You-Go, Subscription, Tiered Plans, Bundled Services |
| Companies Covered | SK Telecom, KT, LG Uplus, SK Broadband, SK Telink, SEJONG Telecom, Dreamline, IDIS Powertel, Samsung SDS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Telecom Market Evolving Landscape
Network function virtualization and cloud-native core architectures are dissolving traditional hardware-software boundaries, enabling carriers to deploy software updates at infrastructure scale rather than box-by-box replacement cycles.
Open RAN disaggregation is absorbing capital that previously consolidated in integrated vendor stacks. Tier-two carriers and enterprise private networks adopt multi-vendor radio and baseband combinations to escape single-source pricing power. This technology is absorbing margin from incumbent equipment suppliers while redistributing value toward software integrators and cloud infrastructure providers.
KCC spectrum reallocation proceedings are tightening device approval timelines for millimeter-wave equipment. The industrial consequence is compressed vendor qualification cycles that favor pre-certified module suppliers over custom hardware development. Mobile broadband infrastructure projects face the most acute timeline pressure, with carriers prioritizing sub-6 GHz deployment to avoid certification bottlenecks.
Enterprise procurement of network services now separates connectivity from platform functionality. Manufacturing and logistics verticals contract directly with cloud providers for edge compute while sourcing raw bandwidth from carriers. This pattern is most visible in Busan's port automation cluster and Incheon's logistics hubs, where terminal operators specify latency SLAs independent of underlying transport ownership.
South Korea Telecom Market Segmentation
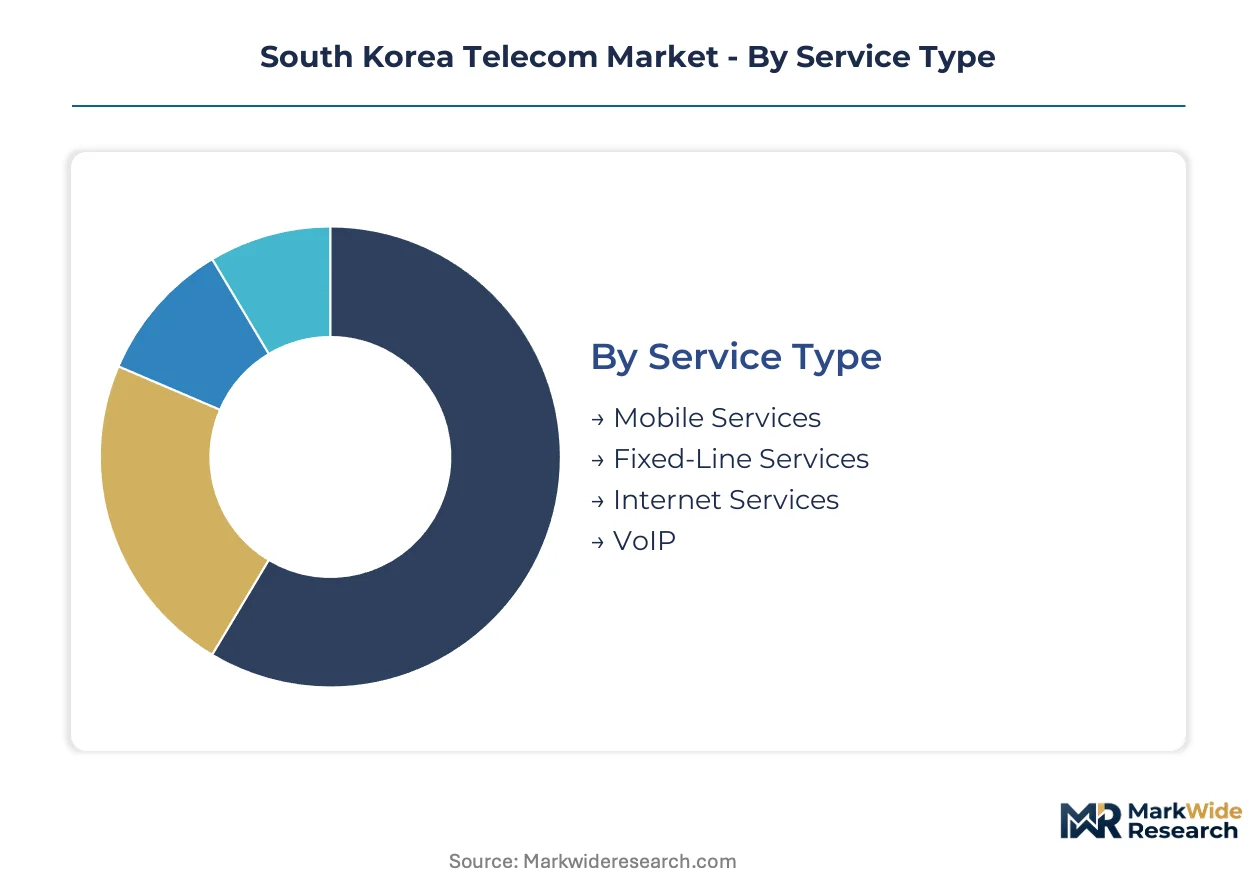
Carrier investment cycles and regulatory mandates create distinct upgrade pathways across service layers in South Korea. Understanding where replacement demand concentrates versus where new infrastructure builds out reveals how spectrum policy and enterprise automation reshape revenue pools.
Service Type:
Replacement cycles diverge sharply between wireless infrastructure undergoing 5G standalone migration and wireline assets reaching fiber end-of-life.
- Mobile Services:5G standalone core networks now handle signaling independently of 4G anchors, enabling network slicing for enterprise latency guarantees. Seoul's metropolitan corridor and Pangyo Techno Valley cluster absorb the densest base station deployments as MSIT buildout obligations compress timelines.
- Internet Services:Symmetric gigabit fiber replaces legacy copper for consumer upload parity and SME cloud workloads. KT's specialized fiber-to-the-home deployments in dense urban corridors capture expanding margin from this replacement wave.
- Fixed-Line Services:Legacy PSTN infrastructure sustains voice-only subscribers in aging demographics.
- VoIP:Session border controllers integrate with enterprise unified communications platforms.
Volume placements concentrate in Mobile Services; the faster expansion belongs to Internet Services.
Customer Segment:
Procurement sophistication separates price-sensitive residential subscriptions from enterprise contracts specifying SLA-backed latency tiers.
- Large Enterprise:Manufacturing and logistics verticals contract directly for private 5G networks with fiber backhaul into factory zones. Smart manufacturing adoption in Busan's port automation cluster and Incheon's logistics hubs pulls dedicated infrastructure investment.
- Residential:Streaming and cloud gaming bundles drive subscriber stickiness in saturated mobile markets. LG Uplus leverages aggressive content partnerships to defend ARPU in this segment.
- Small Business:Symmetric fiber demand concentrates in Seoul's commercial districts for cloud workload parity.
- Government:Public safety networks and municipal broadband projects specify open-RAN interoperability.
Margin capture concentrates in Large Enterprise; the steepest expansion trajectory belongs to Small Business fiber upgrades.
Technology:
Spectrum allocation policy under the Ministry of Science and ICT forces parallel investment across multiple radio generations.
- 5G:Sub-6 GHz deployment dominates metropolitan corridors while millimeter-wave fills dense urban hotspots. KCC spectrum licensing fees compress carrier margins during this buildout phase.
- Fiber Optic:Dense wavelength division multiplexing and coherent optics enable terabit-scale backhaul. Optical component supply concentration in specialized amplifier and transceiver suppliers creates input cost volatility during capacity expansions.
- 4G LTE:Non-standalone signaling paths persist during core network transition, doubling operational complexity.
- DSL:Copper retirement accelerates in fiber-complete districts.
Capital deployment concentrates in 5G; the fastest structural growth belongs to Fiber Optic infrastructure replacement.
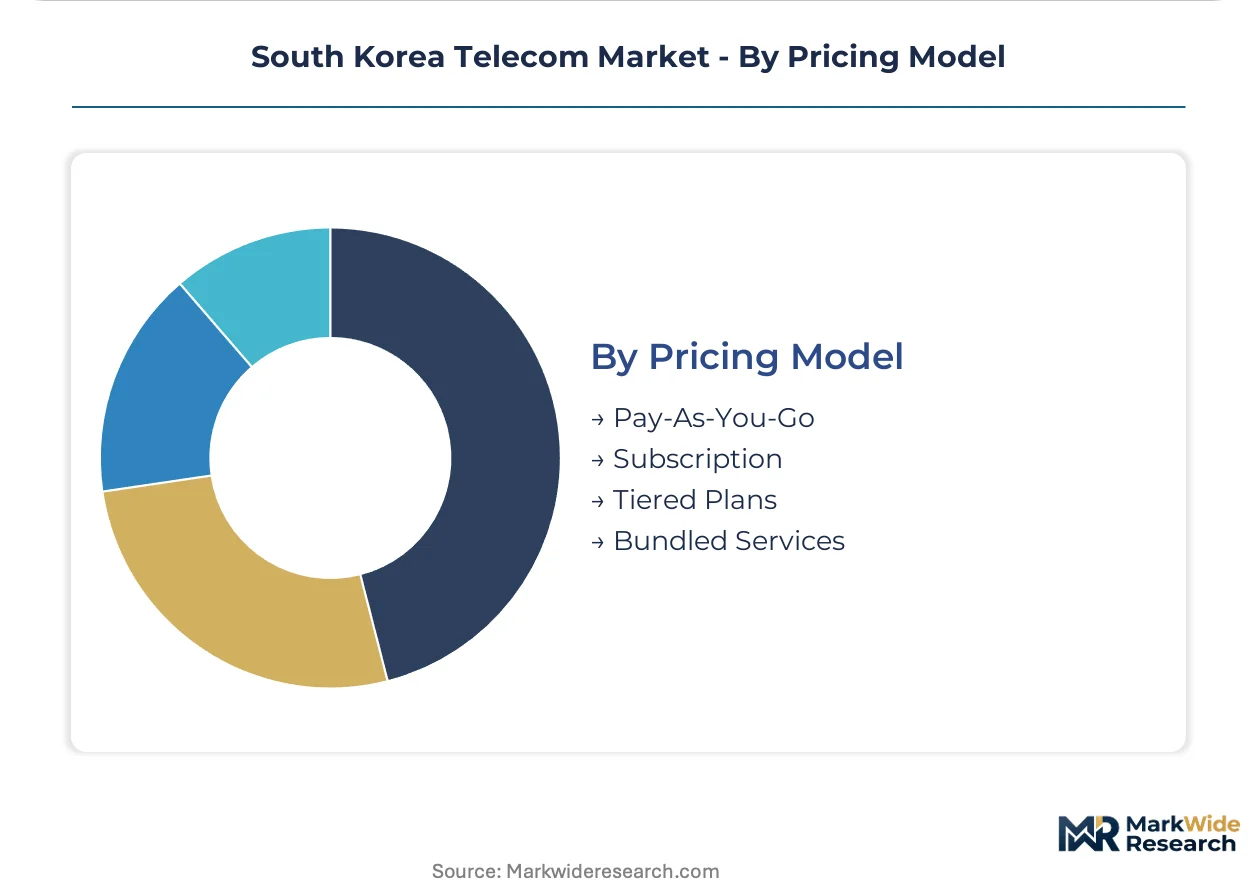
Pricing Model:
Enterprise procurement now separates connectivity from platform functionality, collapsing traditional bundled pricing power.
- Subscription:Recurring revenue anchors carrier cash flow models across consumer and enterprise tiers. SK Telecom leverages nationwide 5G infrastructure to anchor high-margin enterprise contracts on this basis.
- Bundled Services:Media-content convergence packages attract subscriber stickiness through streaming and cloud gaming partnerships. This model absorbs margin pressure in saturated mobile markets.
- Tiered Plans:Data caps and speed tiers segment price sensitivity across demographic cohorts.
- Pay-As-You-Go:Prepaid models retain relevance in transient populations and credit-constrained segments.
Revenue stability concentrates in Subscription; the most rapid model evolution belongs to Bundled Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's metropolitan corridor absorbs the densest telecom infrastructure investment in South Korea, with Pangyo Techno Valley anchoring enterprise 5G deployment and fiber densification across the capital region.
Seoul Capital Area
Symmetric gigabit fiber replacement and 5G standalone core migration dominate carrier spending. MSIT buildout obligations compress base station deployment timelines. Pangyo Techno Valley and Gangnam commercial districts concentrate private network contracts for financial services and media verticals.
Busan-Ulsan
Port automation and shipyard digitization pull dedicated fiber backhaul into industrial zones. Smart manufacturing adoption among heavy industry enterprises accelerates latency-critical network slicing. Busan Port Authority contracts specify edge compute SLAs independent of underlying transport ownership.
Daegu-Gyeongbuk
Secondary metropolitan infrastructure shows underpenetrated 5G standalone coverage relative to Seoul. KCC spectrum licensing structures compress rural deployment margins. Daegu's medical device cluster and Gumi electronics manufacturing zone anchor industrial anchor tenants for private network expansion.
Daejeon-Sejong
Government research complexes and administrative city development drive public sector connectivity procurement. Open-RAN interoperability requirements shape municipal broadband specifications. Korea Advanced Institute of Science and Technology campus networks pilot disaggregated radio architectures.
Gwangju-Honam
Optical component manufacturing concentration creates supply-side interdependence with national fiber buildouts. MFDS equipment certification timelines affect regional vendor qualification cycles. Gwangju's photonics research institutes anchor specialized amplifier and transceiver development.
South Korea Telecom Market Competitive Landscape
Capital-heavy infrastructure operators compete with asset-light platform developers for enterprise wallet share. The market structure consolidates around three integrated carriers with nationwide spectrum holdings, while tier-two fixed-line specialists and enterprise solution providers fragment the remaining addressable space. Strategic archetypes separate spectrum-integrated mobile carriers, fiber-dominant wireline operators, and cloud-native platform integrators. Dominant competitive moves include fiber-to-the-home densification in urban corridors and content bundling partnerships for subscriber retention.
Within the integrated carrier tier, SK Telecom, KT, and LG Uplus occupy positions defined by infrastructure scale and spectrum depth. SK Telecom exemplifies the nationwide 5G infrastructure archetype anchoring enterprise contracts. KT represents specialized fiber-to-the-home deployment concentration in dense metropolitan corridors. LG Uplus sits within the content-convergence segment, with media and streaming partnerships differentiating subscriber propositions in saturated mobile markets.
| Leading Market Players |
|---|
| SK Telecom |
| KT |
| LG Uplus |
| SK Broadband |
| SK Telink |
| SEJONG Telecom |
| Dreamline |
| IDIS Powertel |
| Samsung SDS |
| Others |
Value Network & Pricing Analysis
Sovereign-backed spectrum allocation through the Ministry of Science and ICT shapes both infrastructure investment discipline and carrier pricing power, compressing margins during 5G buildout while concentrating procurement leverage among three integrated operators.
Pricing Analysis
Network-slicing guarantees tied to latency SLAs anchor value-based pricing for enterprise private 5G contracts. Subscription models dominate consumer and SME tiers, while bundled content packages differentiate saturated mobile markets. Price differentiation rests on spectrum depth and fiber density rather than brand premium alone. Pricing pressure stems from KCC auction structures extending amortization beyond technology refresh cycles. Residential subscribers show highest price sensitivity; large enterprises with automation mandates demonstrate lowest.
Supply Chain Analysis
Workforce availability constraints in South Korea's Gwangju photonics cluster and China's specialized amplifier manufacturing zones tighten optical component procurement timelines. Supply concentrates in South Korea, China, and Japan for fiber amplifiers, coherent transceivers, and baseband silicon. Raw material dependencies span rare-earth dopants for fiber amplification, high-purity silicon for radio units, and lithium niobate for optical modulation. Single-source vulnerability in millimeter-wave transceiver modules elevates qualification risk. Distribution runs through carrier-direct procurement and systems integrator channels serving enterprise private networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over edge compute infrastructure and fiber backhaul determines enterprise contract capture.
For Market Incumbents: To counter margin compression from KCC spectrum fees, deepen fiber densification in Seoul's metropolitan corridor and Pangyo Techno Valley cluster. Anchor high-margin enterprise contracts through network-slicing SLAs that bundle connectivity with edge compute platforms. Prioritize open-RAN interoperability certification to diversify vendor options and escape single-source pricing power. For New Entrants and Emerging Players: MSIT open-RAN guidelines in South Korea open a window for disaggregated baseband and radio unit procurement. Target secondary metropolitan zones in the Gwangju-Daejeon corridor where 5G standalone coverage remains underpenetrated. Contract directly with industrial anchor tenants for private network deployment, bypassing carrier wholesale channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor optical component specialists with millimeter-wave certification pipelines in South Korea's Gwangju-Honam region. Long-term viability hinges on positioning ahead of standalone core network maturation and enterprise edge compute separation from transport ownership. Monitor KCC spectrum reallocation proceedings as the signal for infrastructure replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Densification Buildout | KT's urban corridor deployments capture symmetric gigabit replacement demand in Seoul commercial districts. |
| Private 5G Network Deployment | SK Telecom anchors manufacturing contracts through latency-guaranteed network slicing in Busan port automation. |
| Open-RAN Interoperability Certification | Vendor diversification pathways under MSIT guidelines reduce single-source dependence for baseband procurement. |
| Content Bundling Partnership | LG Uplus defends consumer ARPU through streaming and cloud gaming packages in saturated mobile markets. |
| Edge Compute Platform Integration | Enterprise procurement separation of connectivity from cloud functionality reshapes carrier value capture in Incheon logistics hubs. |
Research Methodology
Document review covered MSIT policy filings, KCC spectrum auction records, and MFDS equipment certification databases, complemented by interviews with carrier network planning executives, optical component procurement managers, and enterprise IT infrastructure leads. Secondary validation drew from Ministry of Science and ICT infrastructure deployment reports, hyperscaler edge compute capex disclosures, and industrial automation vendor specifications. Bottom-up service revenue estimates triangulated against top-down spectrum allocation and fiber deployment metrics.
Cross-referencing historical buildout patterns with panel input from infrastructure vendors established the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, customer segment, technology generation, and pricing model, with additional granularity on metropolitan zone density tiers. CAGRs derived from carrier capital expenditure trajectories, replacement cycle timing for legacy copper infrastructure, and enterprise private network adoption curves.
The model assumes a particular technology adoption path; alternative pathways for standalone 5G core maturation would alter the outlook. Forecasts reflect assumptions regarding MSIT buildout obligation compliance, KCC spectrum reallocation timing, and optical component supply normalization. Material deviation in industrial automation deployment velocity or open-RAN interoperability standardization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Poland Telecom Market
Telecommunications
Indonesia B2B Telecom Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Machine to Machine (M2M) Services Market
Telecommunications
Egypt ICT Market
Telecommunications
A2P SMS Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
5G Remote Radio Head Market
Telecommunications
LTE Emergency Networks Market
Telecommunications
Rich Communication Services (RCS) Messaging Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Prepaid Communication Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
Cellular Modem Market
Telecommunications
Vietnam ICT Market
Telecommunications
France Telecom Market